Latest from BCA Research

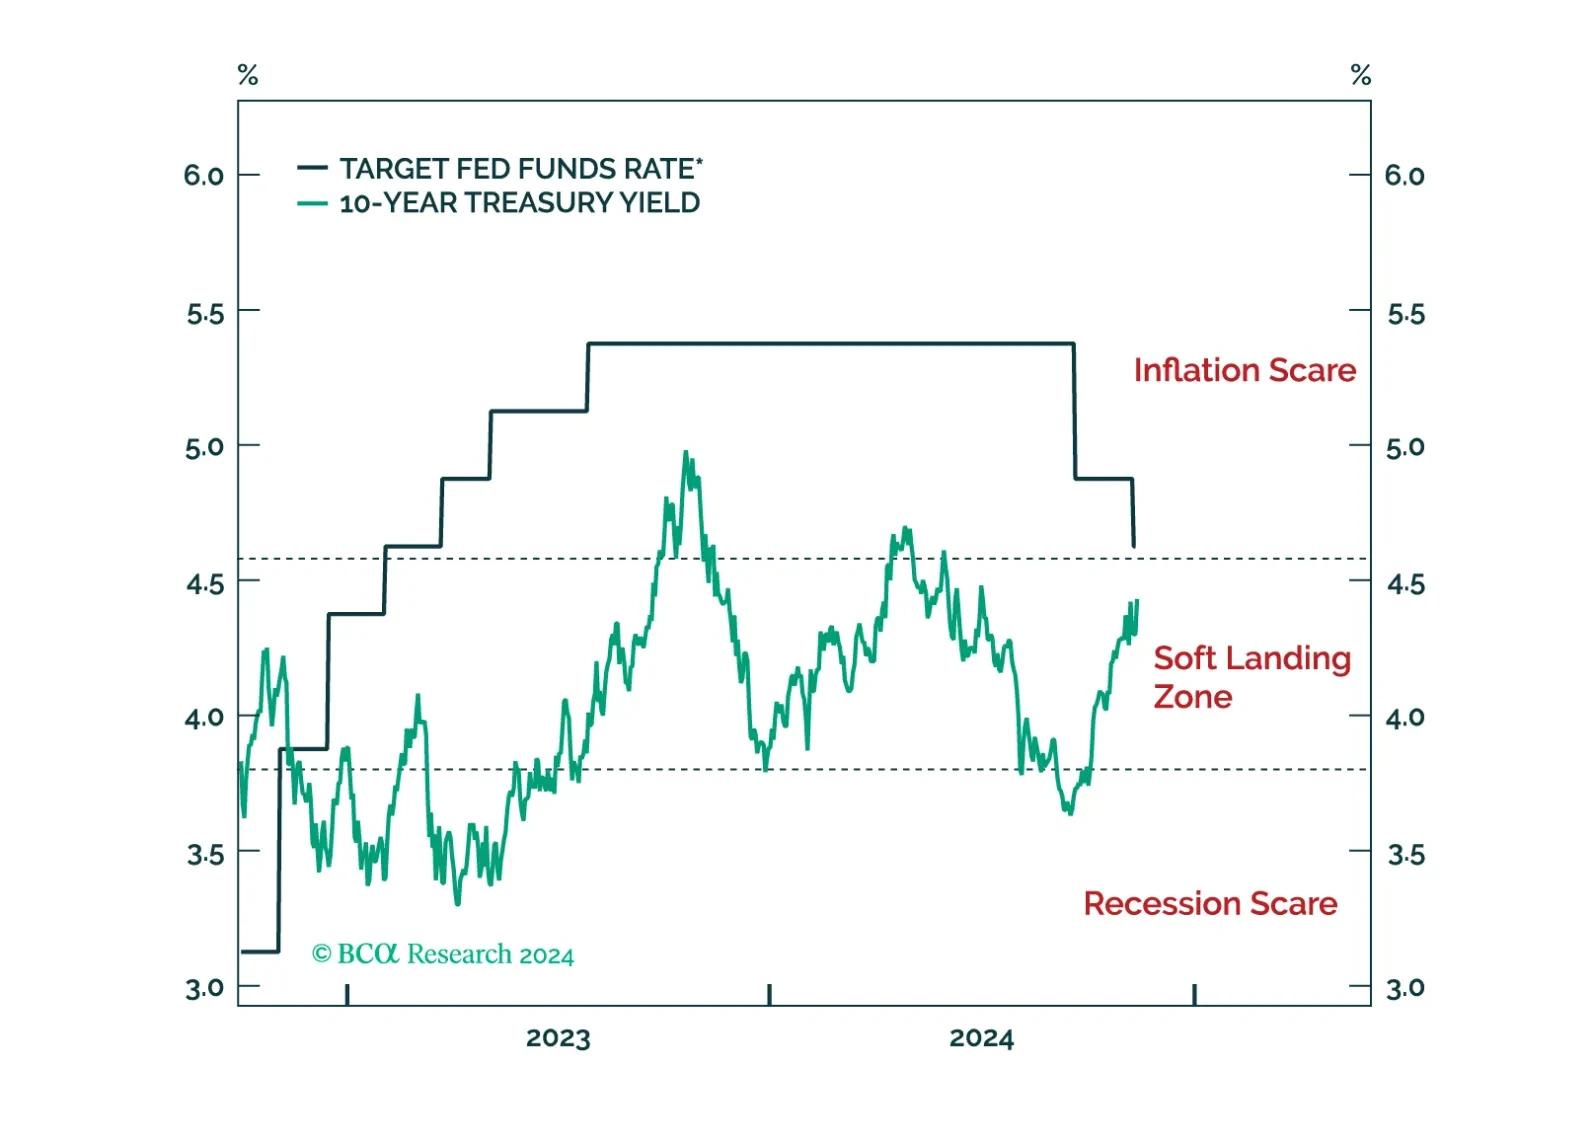
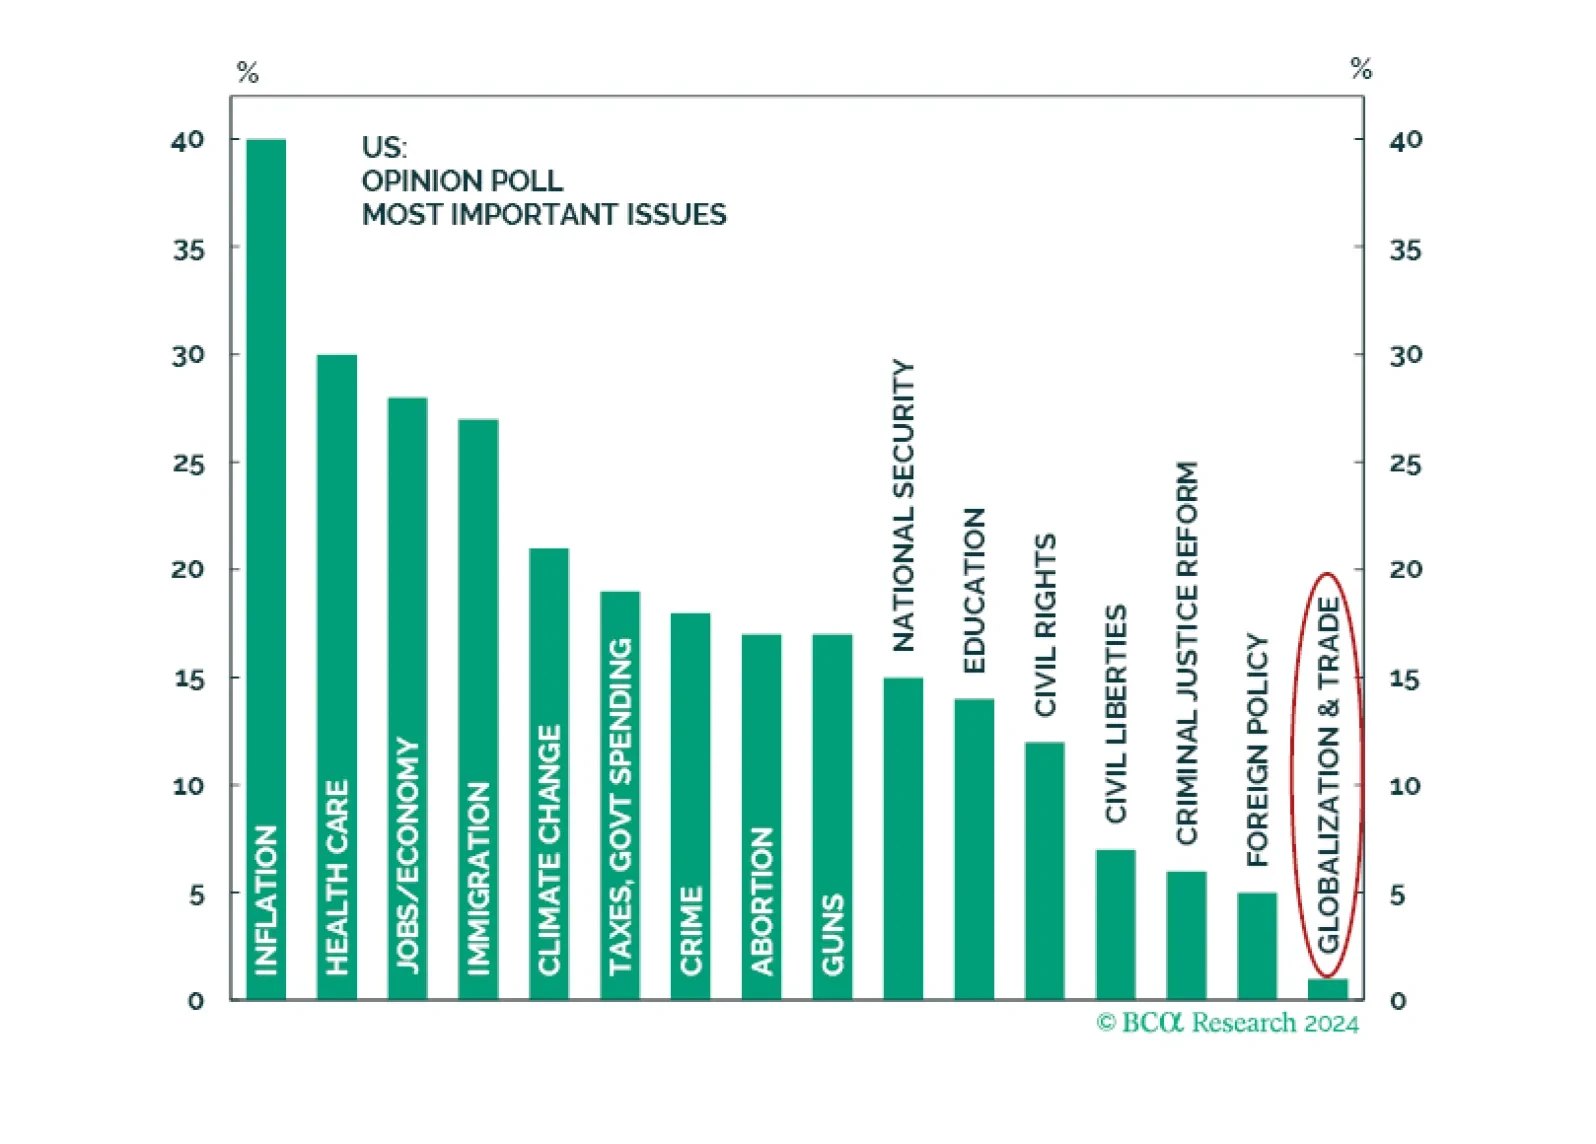
After the election, investors have begun to price in a repeat of the first Trump presidency. The market is expecting Trump to enact a flurry of policies that will unleash a year of growth like 2017. But we believe the consensus is wrong. Investors are playing the man and not the macro. The economic outlook and the political situation today are the polar opposite to late 2016. We are fading the small cap rally and recommending above-benchmark duration. We also recommend a defensive stance.
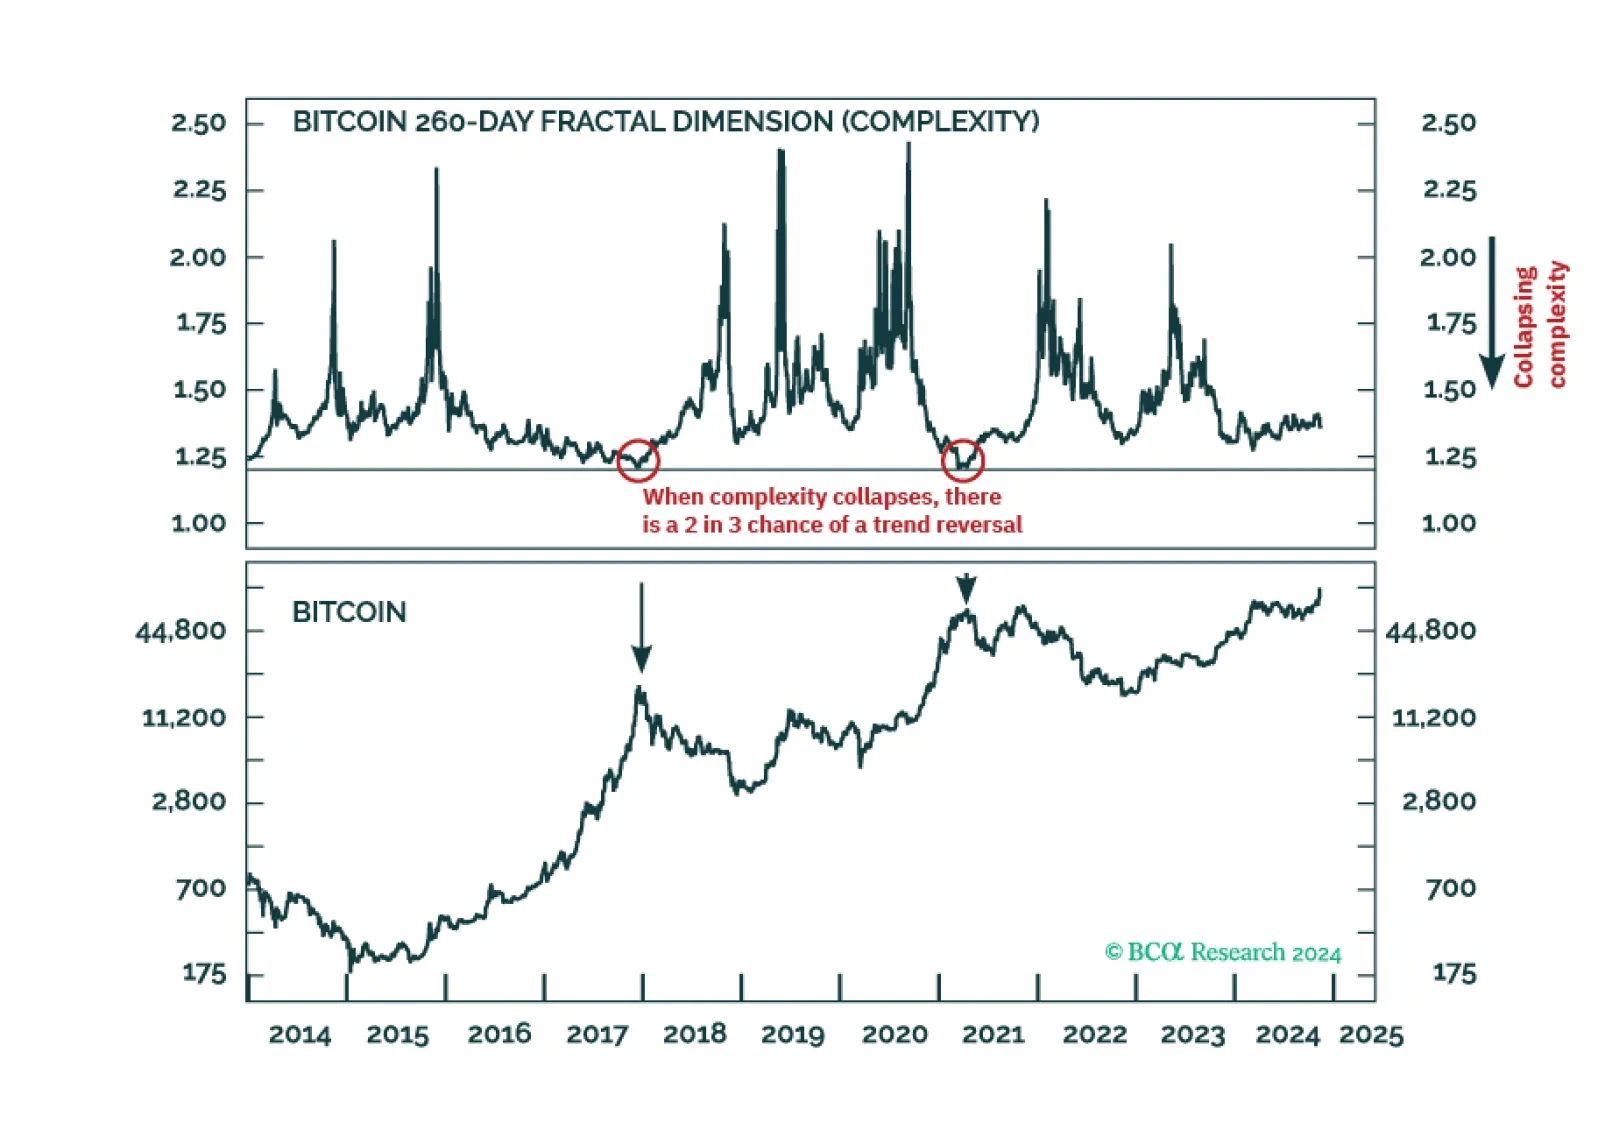
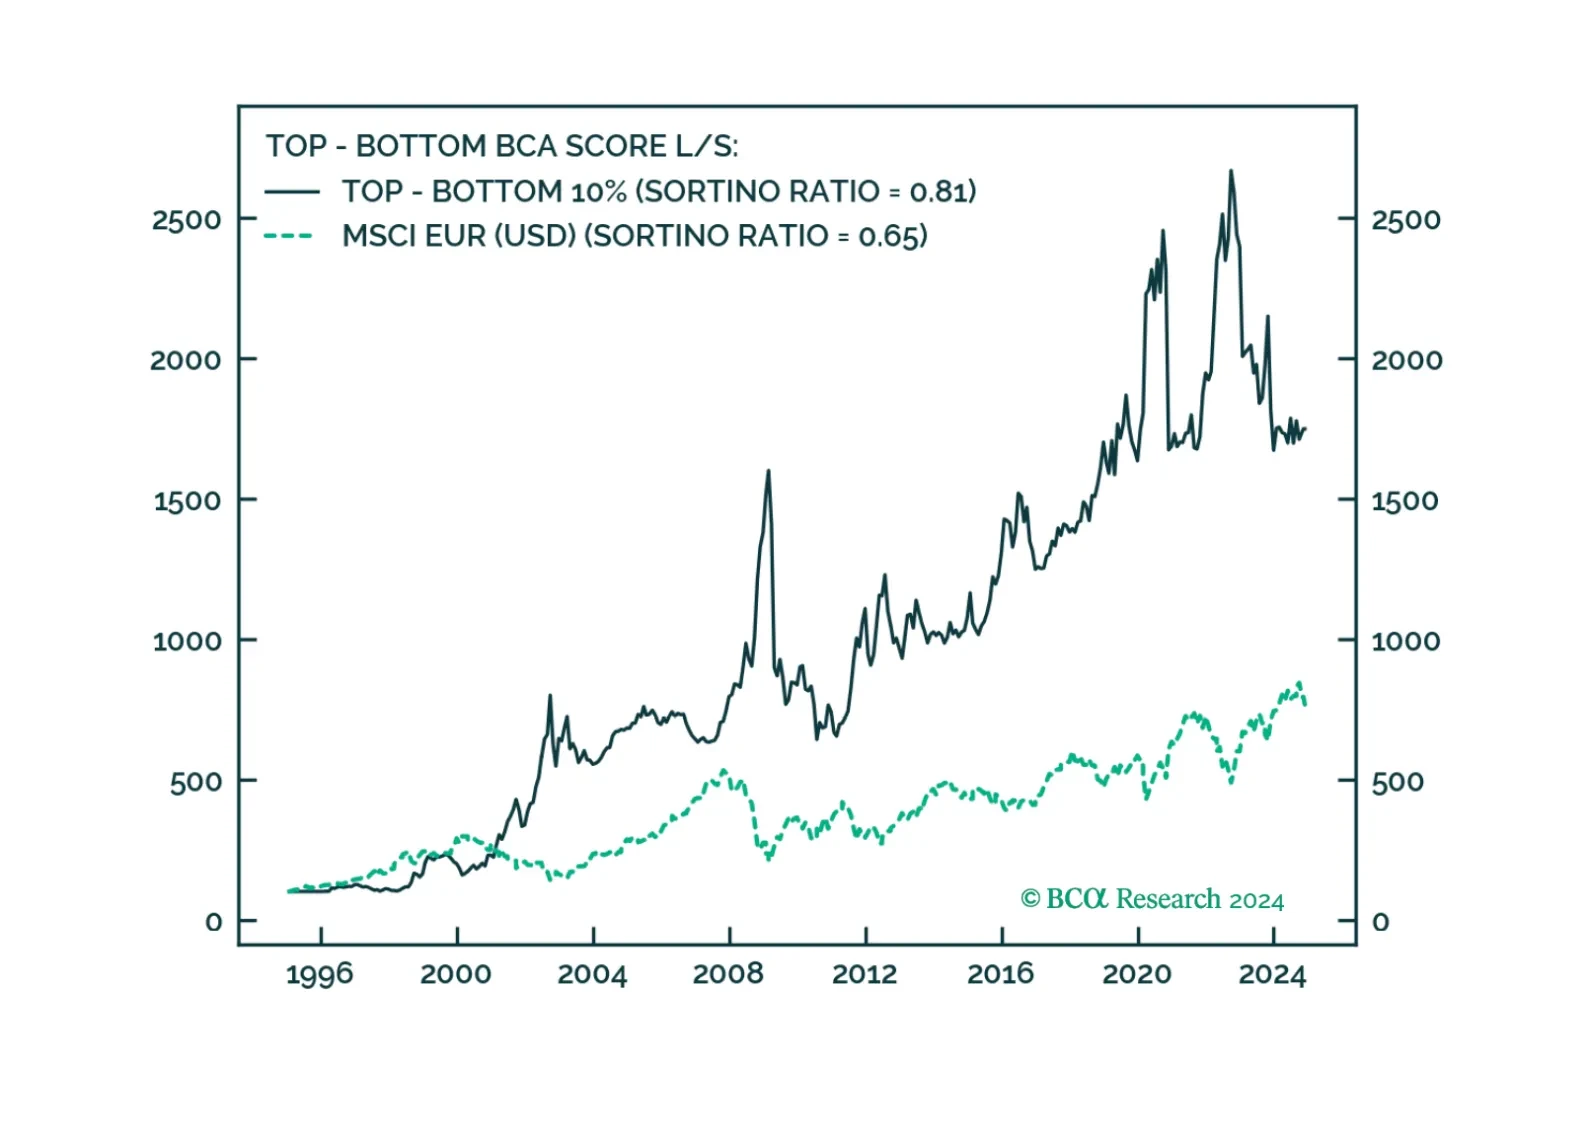
The value of both gold and bitcoin comes from the collective belief that they are the non-confiscatable assets to own in a fiat monetary system, as an insurance against hyperinflation, banking system failure, or state expropriation. As global wealth rises, the value of both gold and bitcoin will also rise. But as bitcoin takes market share from gold, bitcoin has considerably more upside than gold, with an ultimate destination of $200,000+. Plus: 10-year T-bonds and Portuguese stocks are tactically oversold.
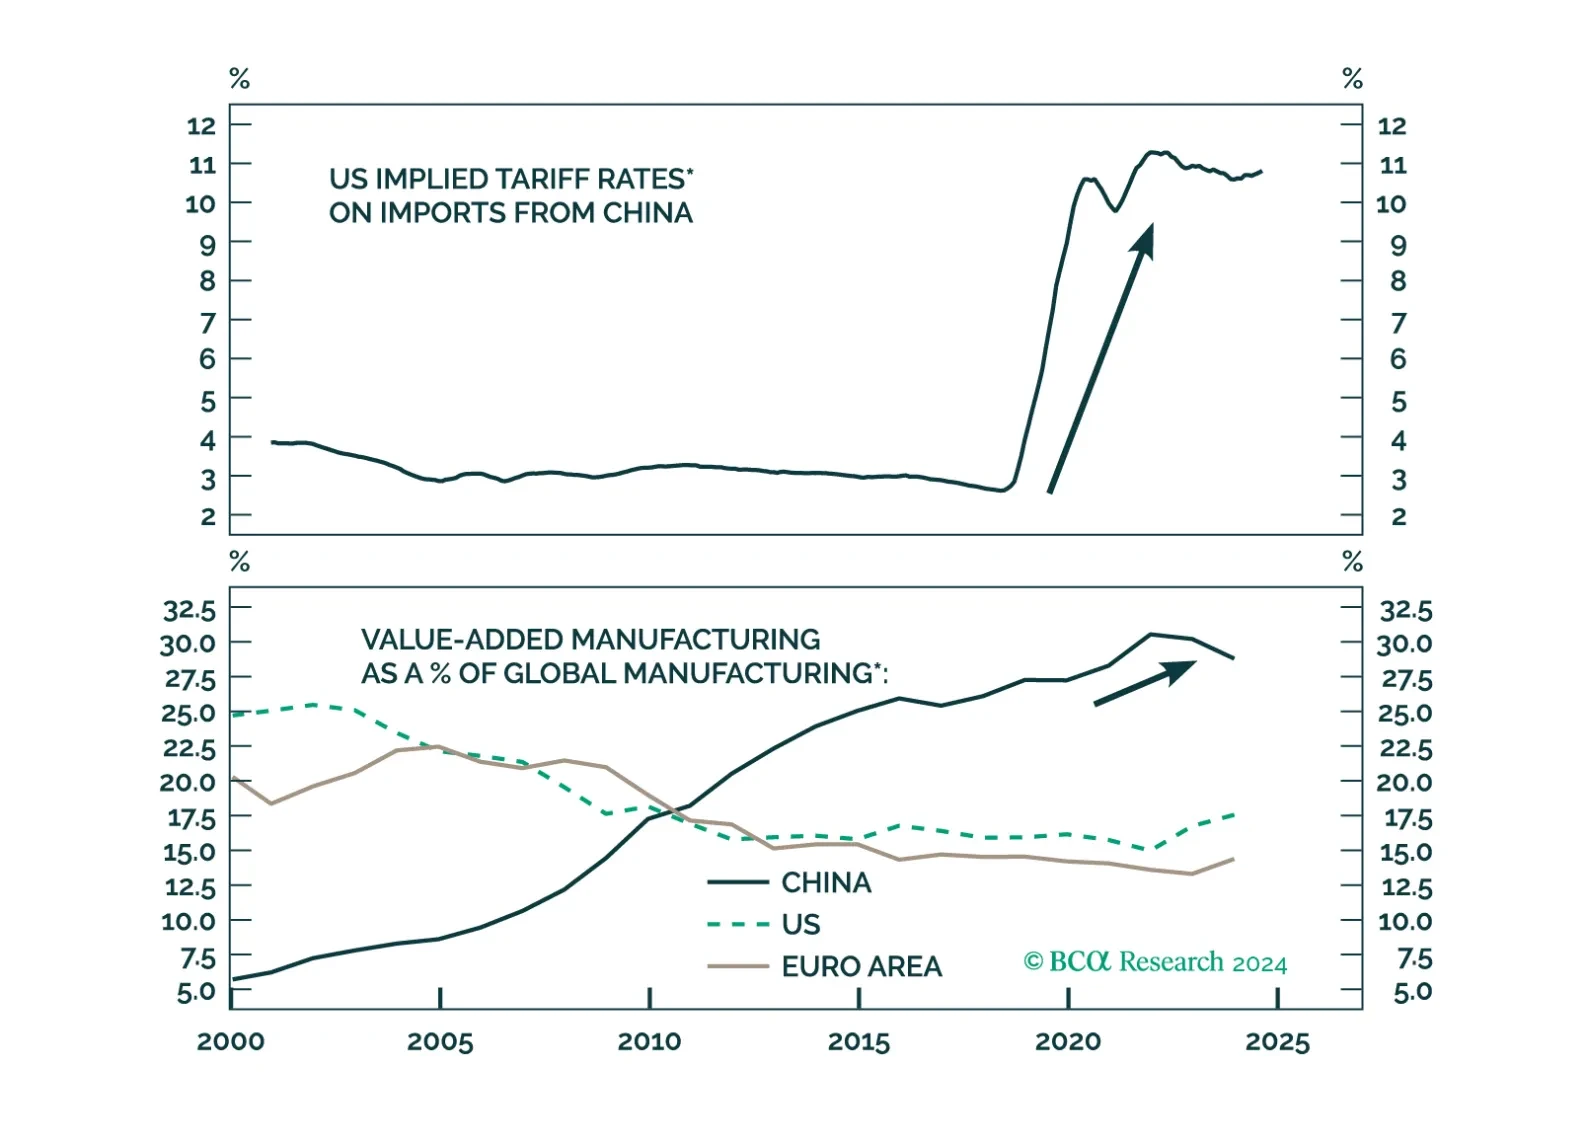
Trump's presidential re-election makes US tariff rate hikes on Chinese exports an imminent threat. Beijing has made extensive efforts to derisk the domestic economy and diversify trade away from the US. However, China is no better positioned today than it was in 2018 to withstand the impact of a renewed trade war.

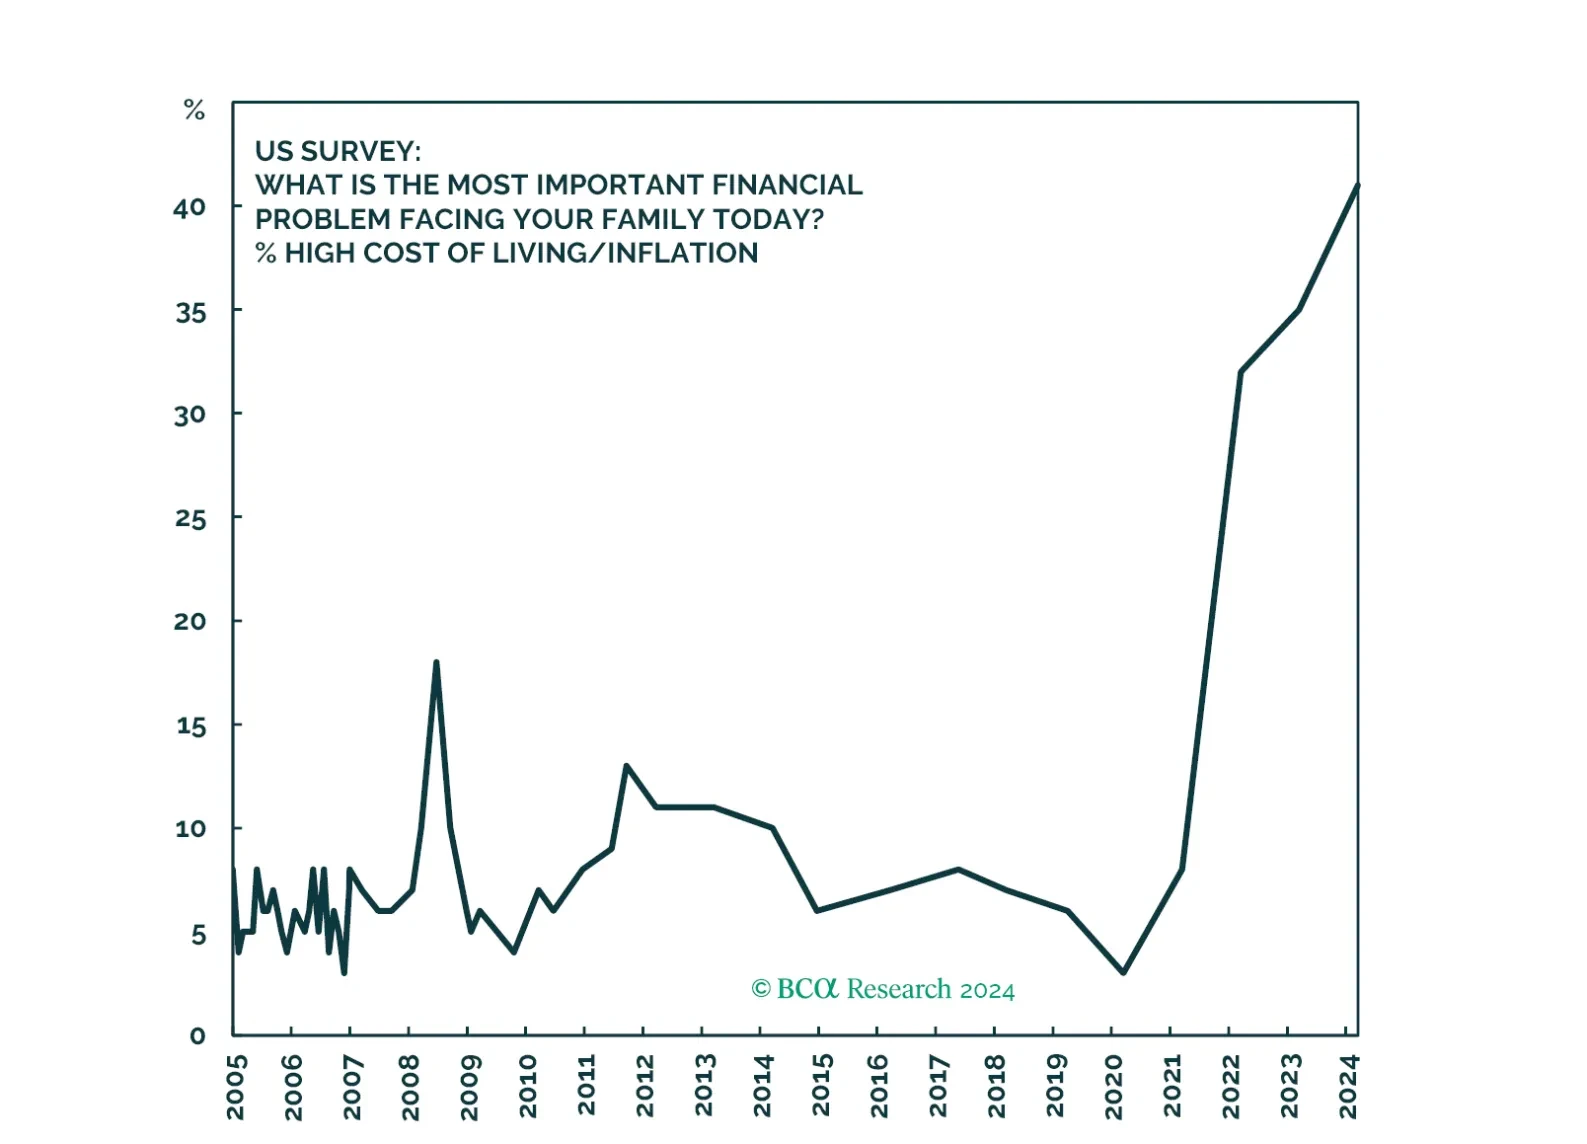
We update our inflation forecast following this morning’s CPI release, concluding that TIPS breakeven inflation rates have room to fall.
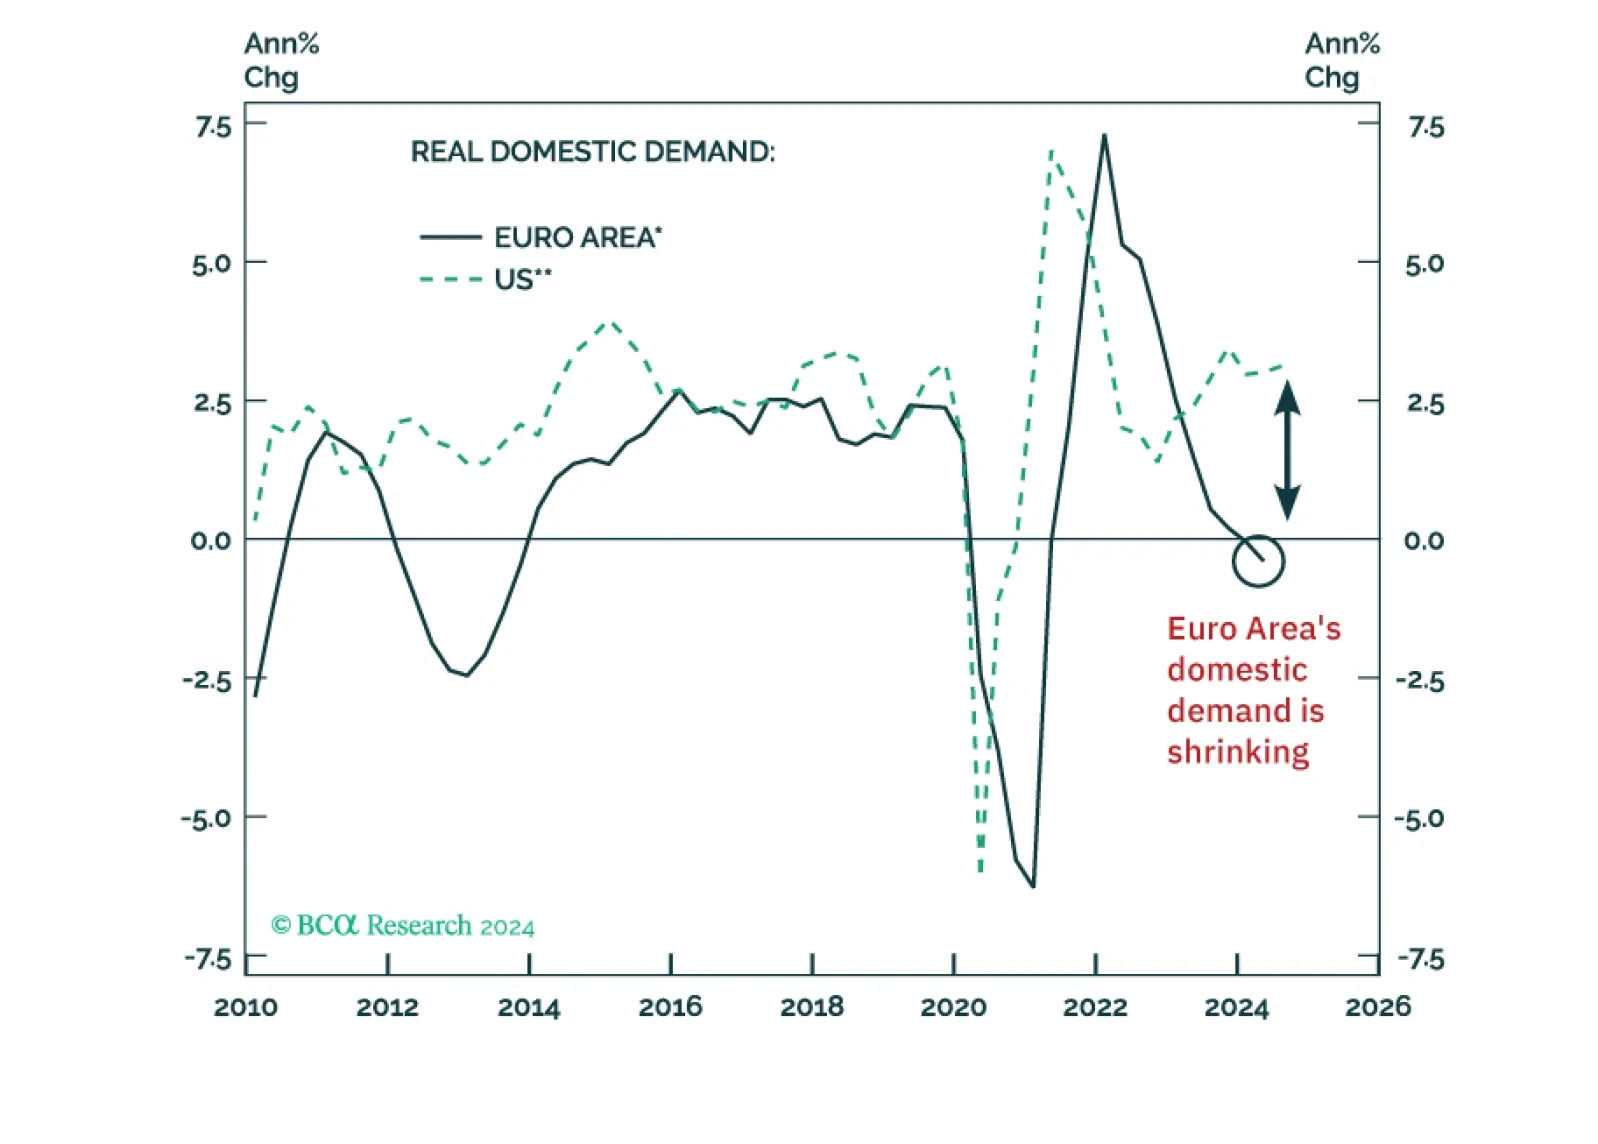
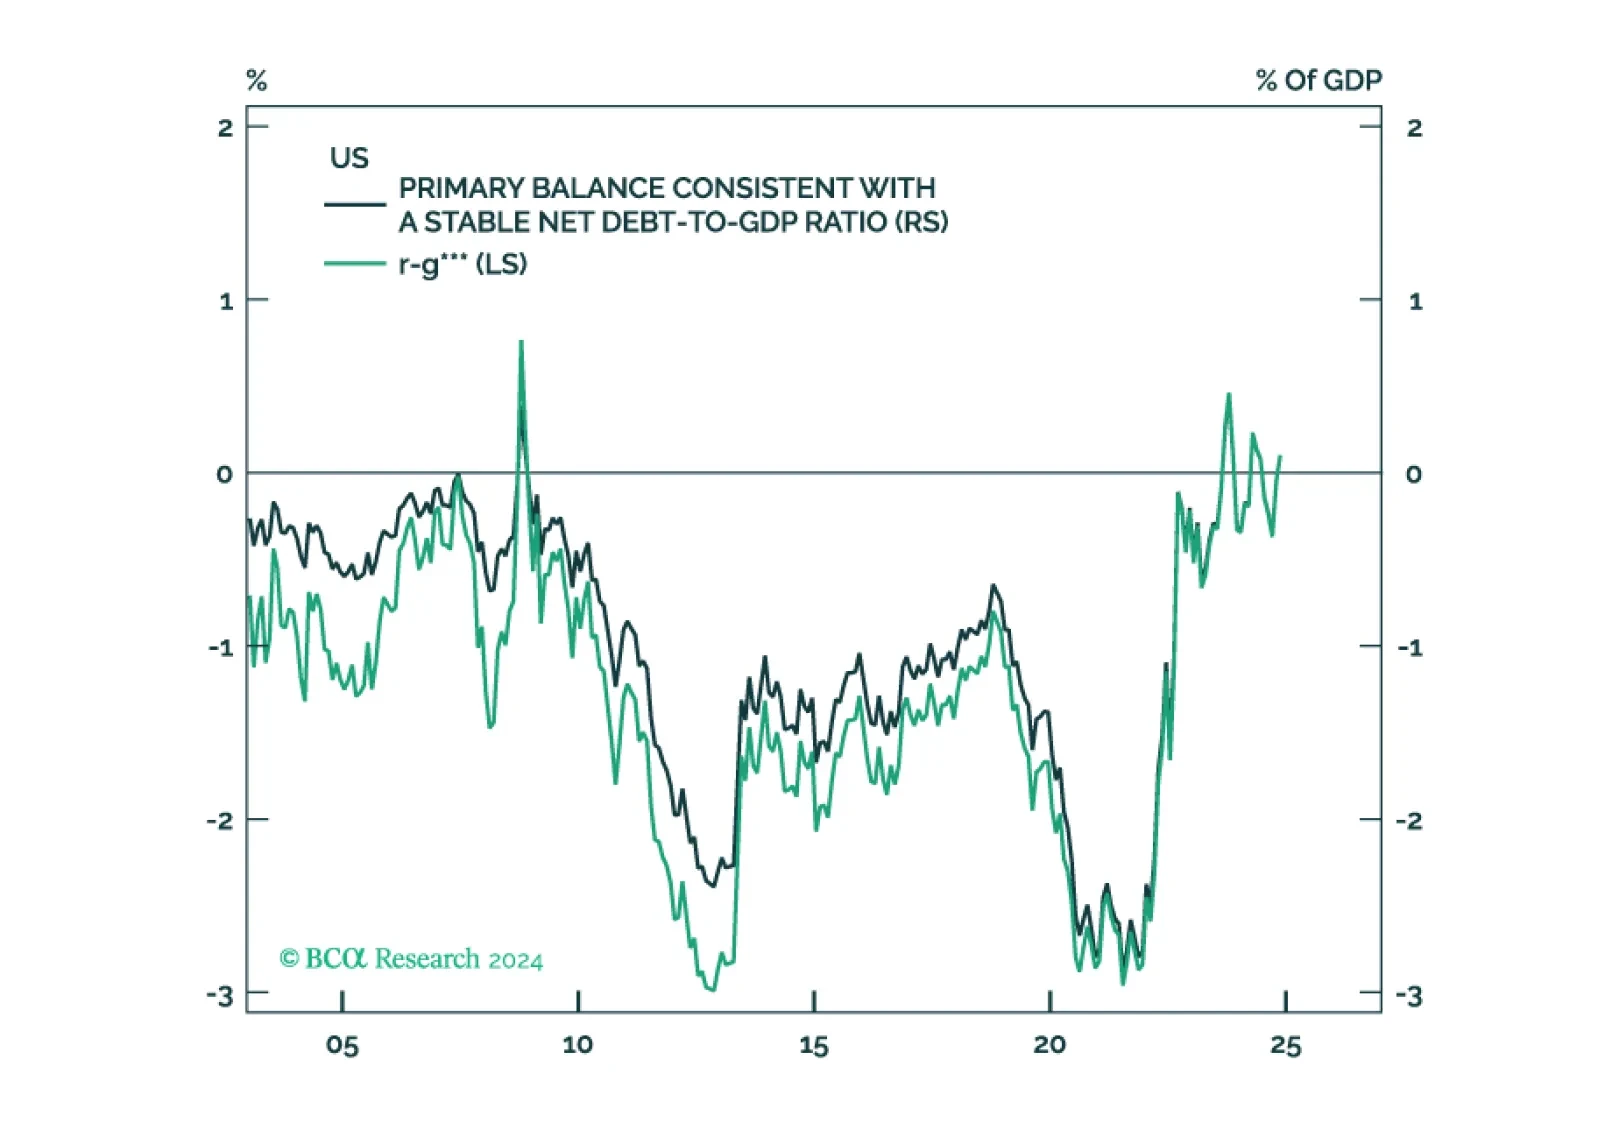
The threat of import tariffs and US growth outperformance versus the rest of the world will continue supporting the US dollar rally over the near term. Nevertheless, the Trump administration’s medium- to long-term goal will be a US dollar devaluation to boost the country’s manufacturing competitiveness. We will recommend upgrading EM stocks and bonds when we downgrade our US dollar view.