Latest from BCA Research

We are upgrading Europe Private Equity, predominantly driven by Buyouts, from underweight to neutral. Our outlook towards Global Buyouts is improving, with Europe benefiting from enhanced credit availability and an earlier recession. Non-domestic investors may also be advantaged by an appreciation in the EUR and GBP over the next market cycle.
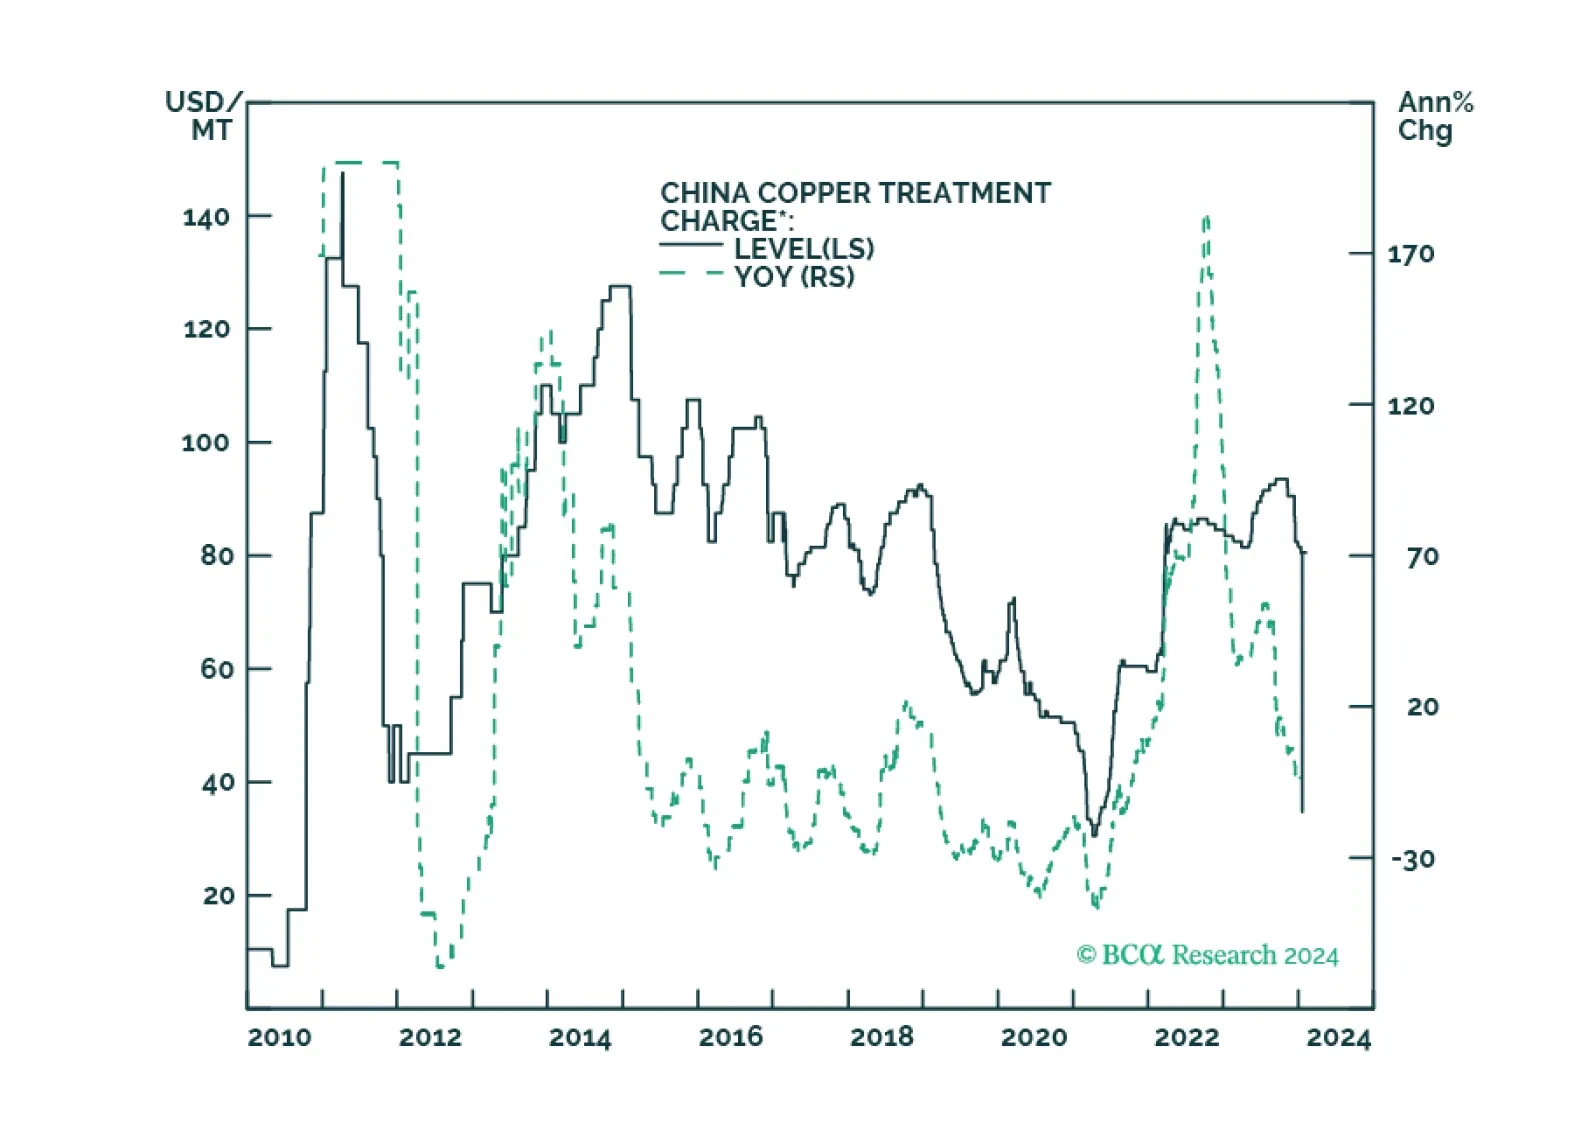
Supply and demand shocks in markets critical to the renewable-energy and defense industries will continue to play havoc with prices, which will negatively impact capex. In the short run, this benefits China given its already-dominant position in these markets. Longer term, investors already are providing capital for long-term projects needed for the energy transition. We remain long the XME ETF, given its low exposure to lithium and nickel holdings.
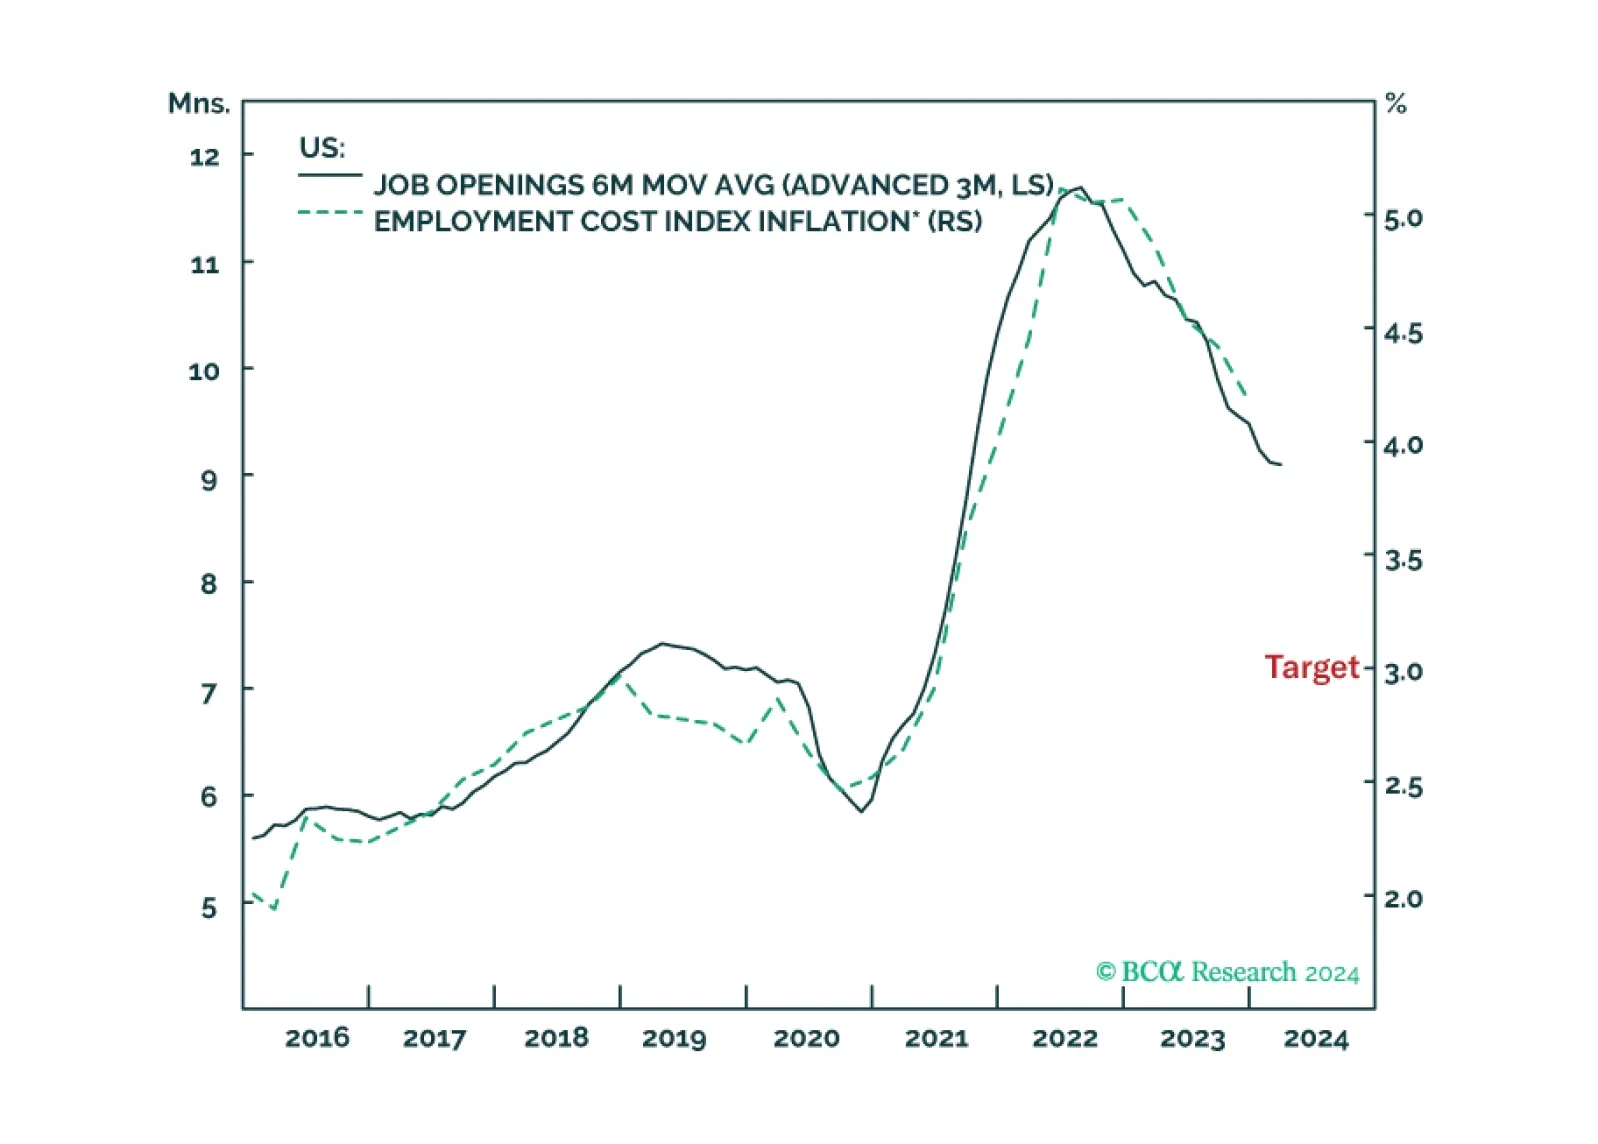
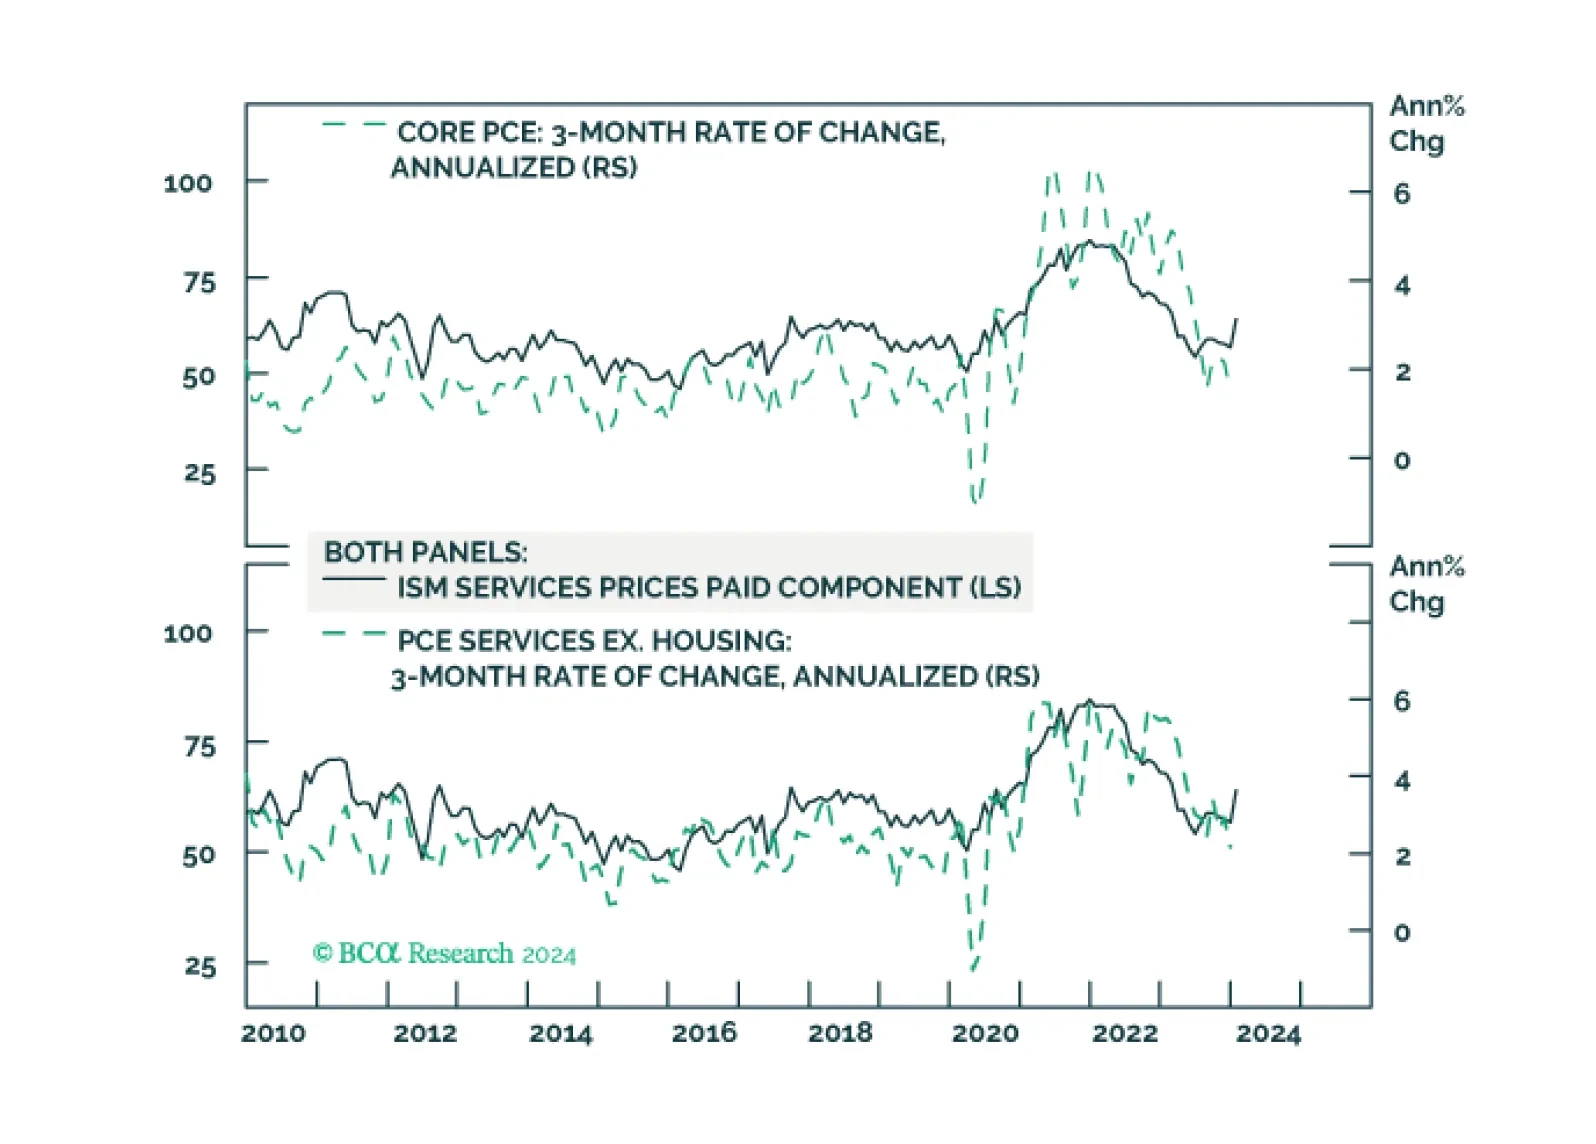
The disinflation to date has been benign because it has come almost entirely from improving supply. But the supply-side tailwind has exhausted, so the last mile of the journey to 2 percent inflation will be the hardest, especially in the US and the UK. We discuss the investment implications. Plus, we highlight an interesting sector pair-trade.
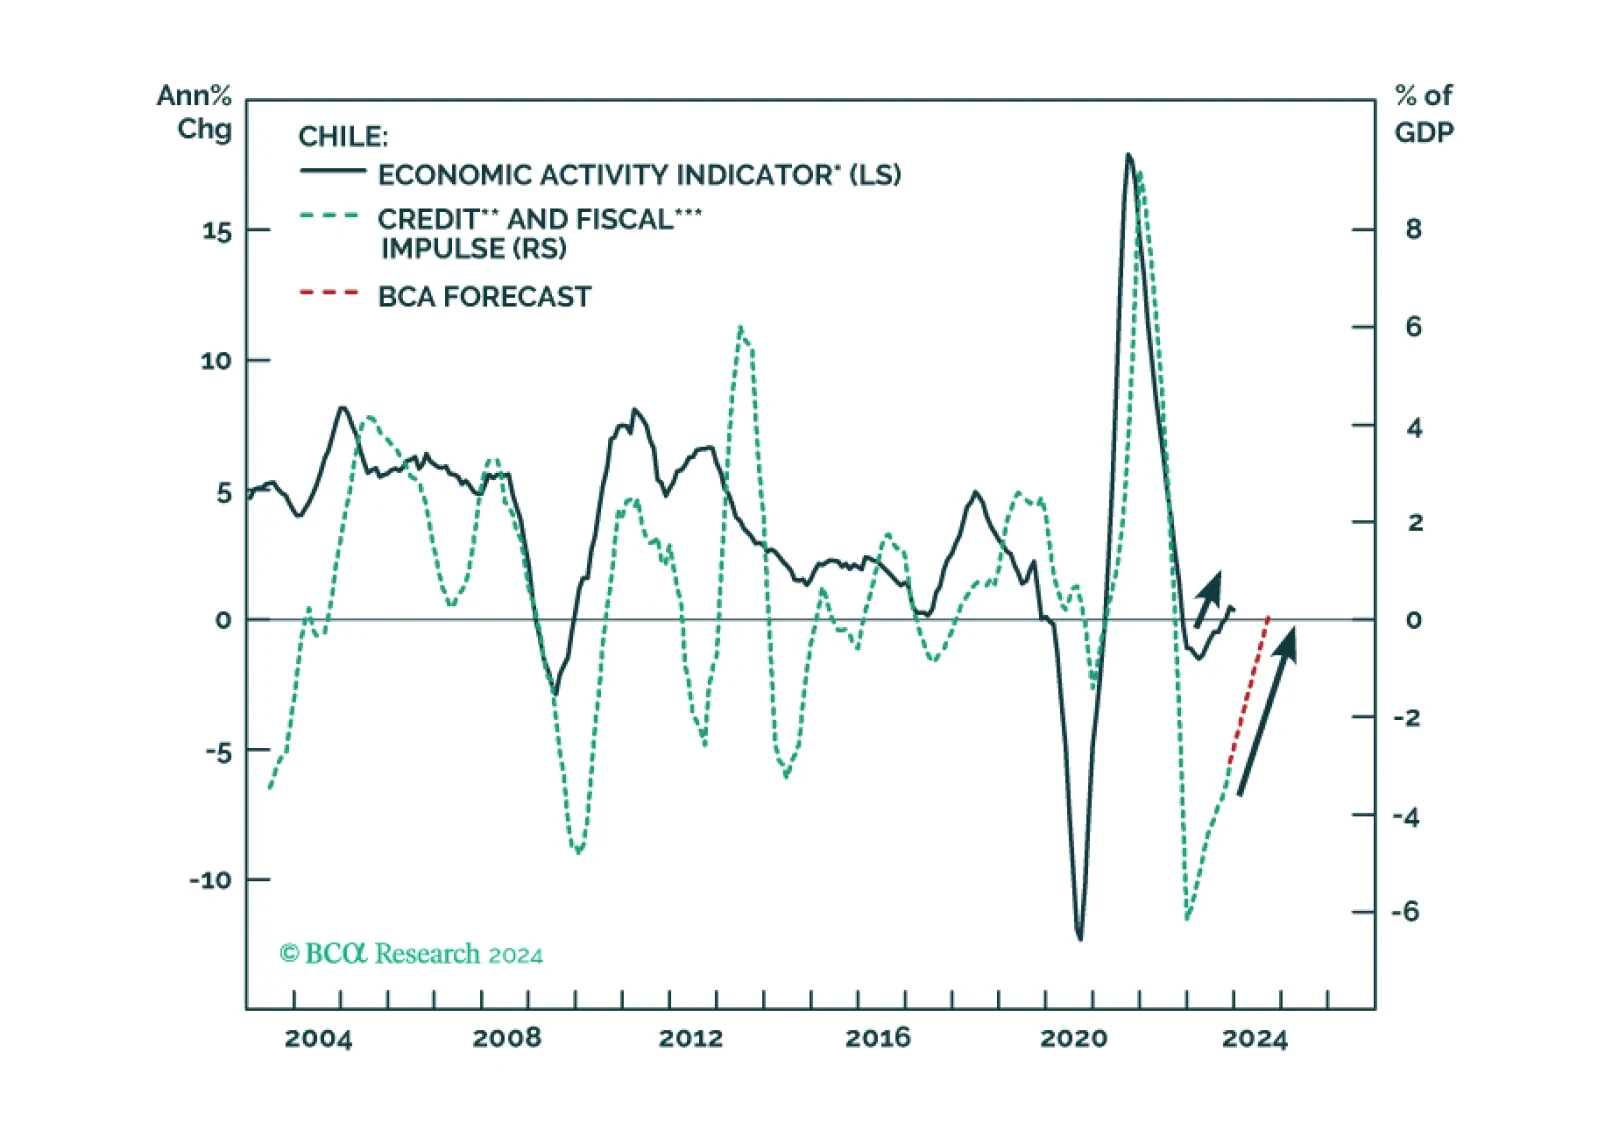
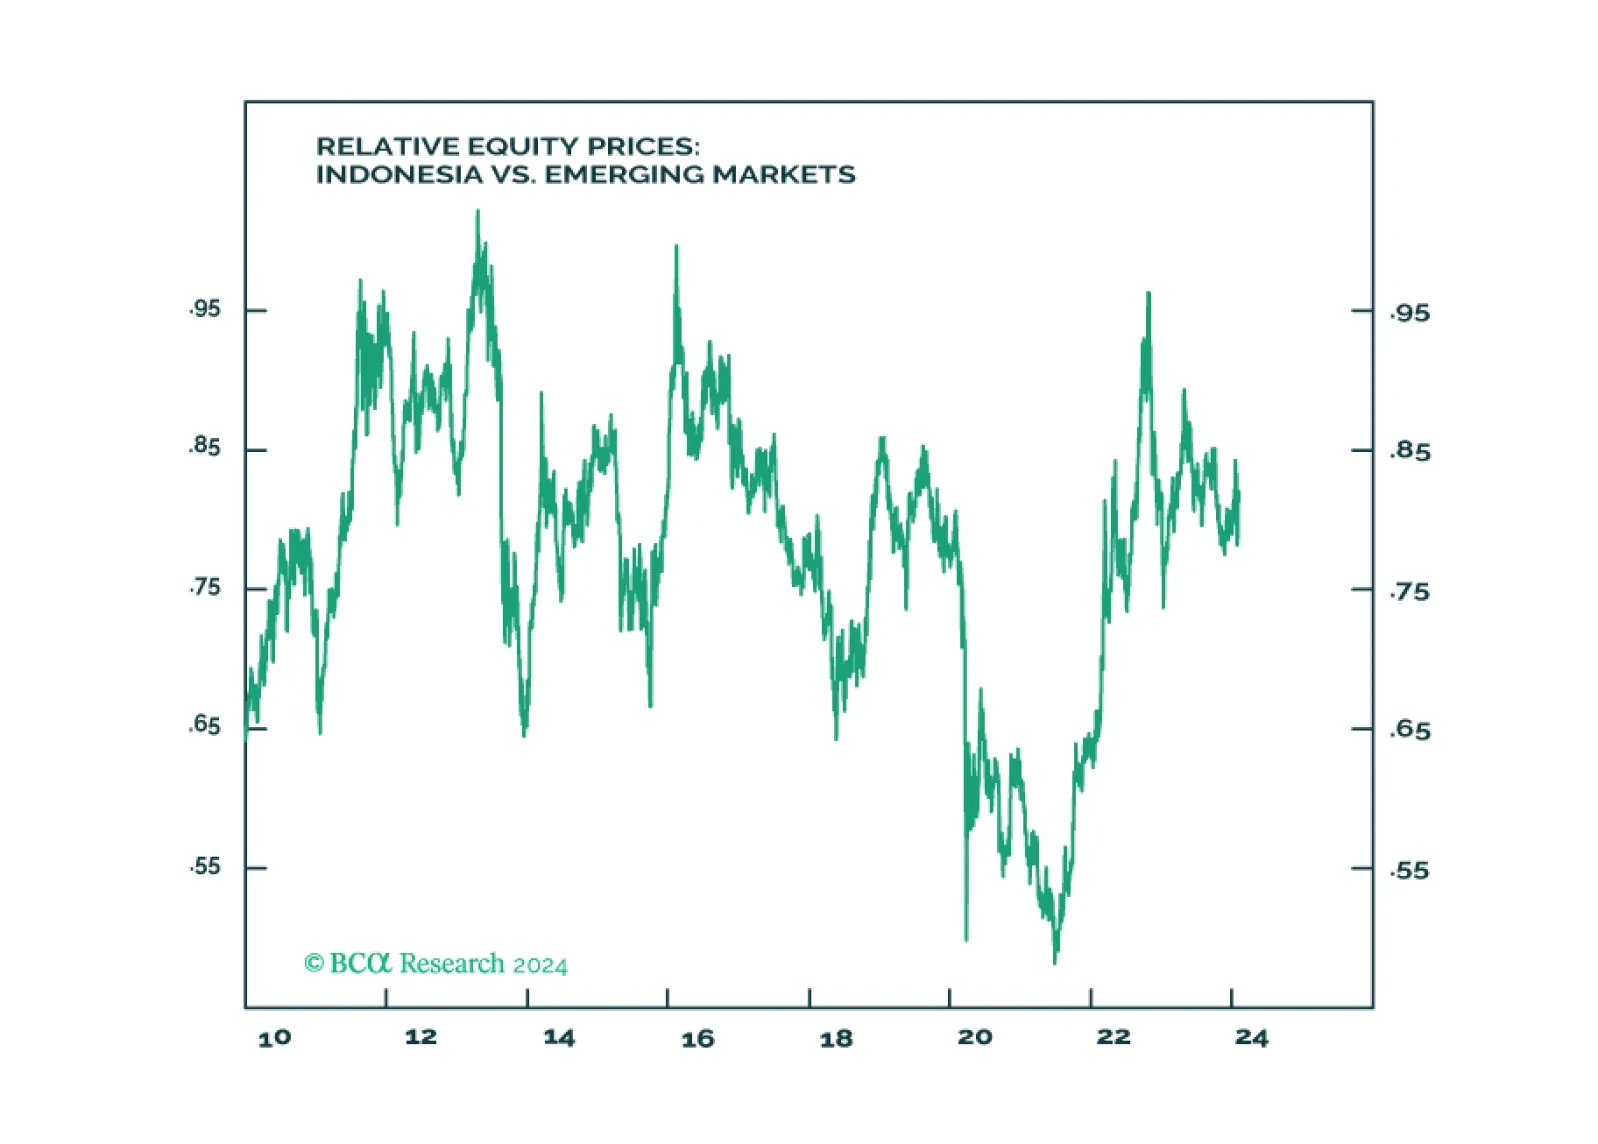
The stars have aligned for a major outperformance of Chilean stocks versus the EM equity benchmark. Plummeting inflation in Chile will push monetary authorities to continue their aggressive rate cuts, engineering a quick economic recovery this year. We maintain our overweight stance on Chilean stocks and fixed income, and recommend investors go long Chilean banks / short the overall EM index, buy 10-year government bonds, and go long CLP / short COP.

The USHQ Large Cap portfolio outperformed its benchmark by 2.5% and the USHQ SMID 2.4%. The BCA Score L/S started the year off strong with positive contributions from Safety, Technicals, and Quality for January.
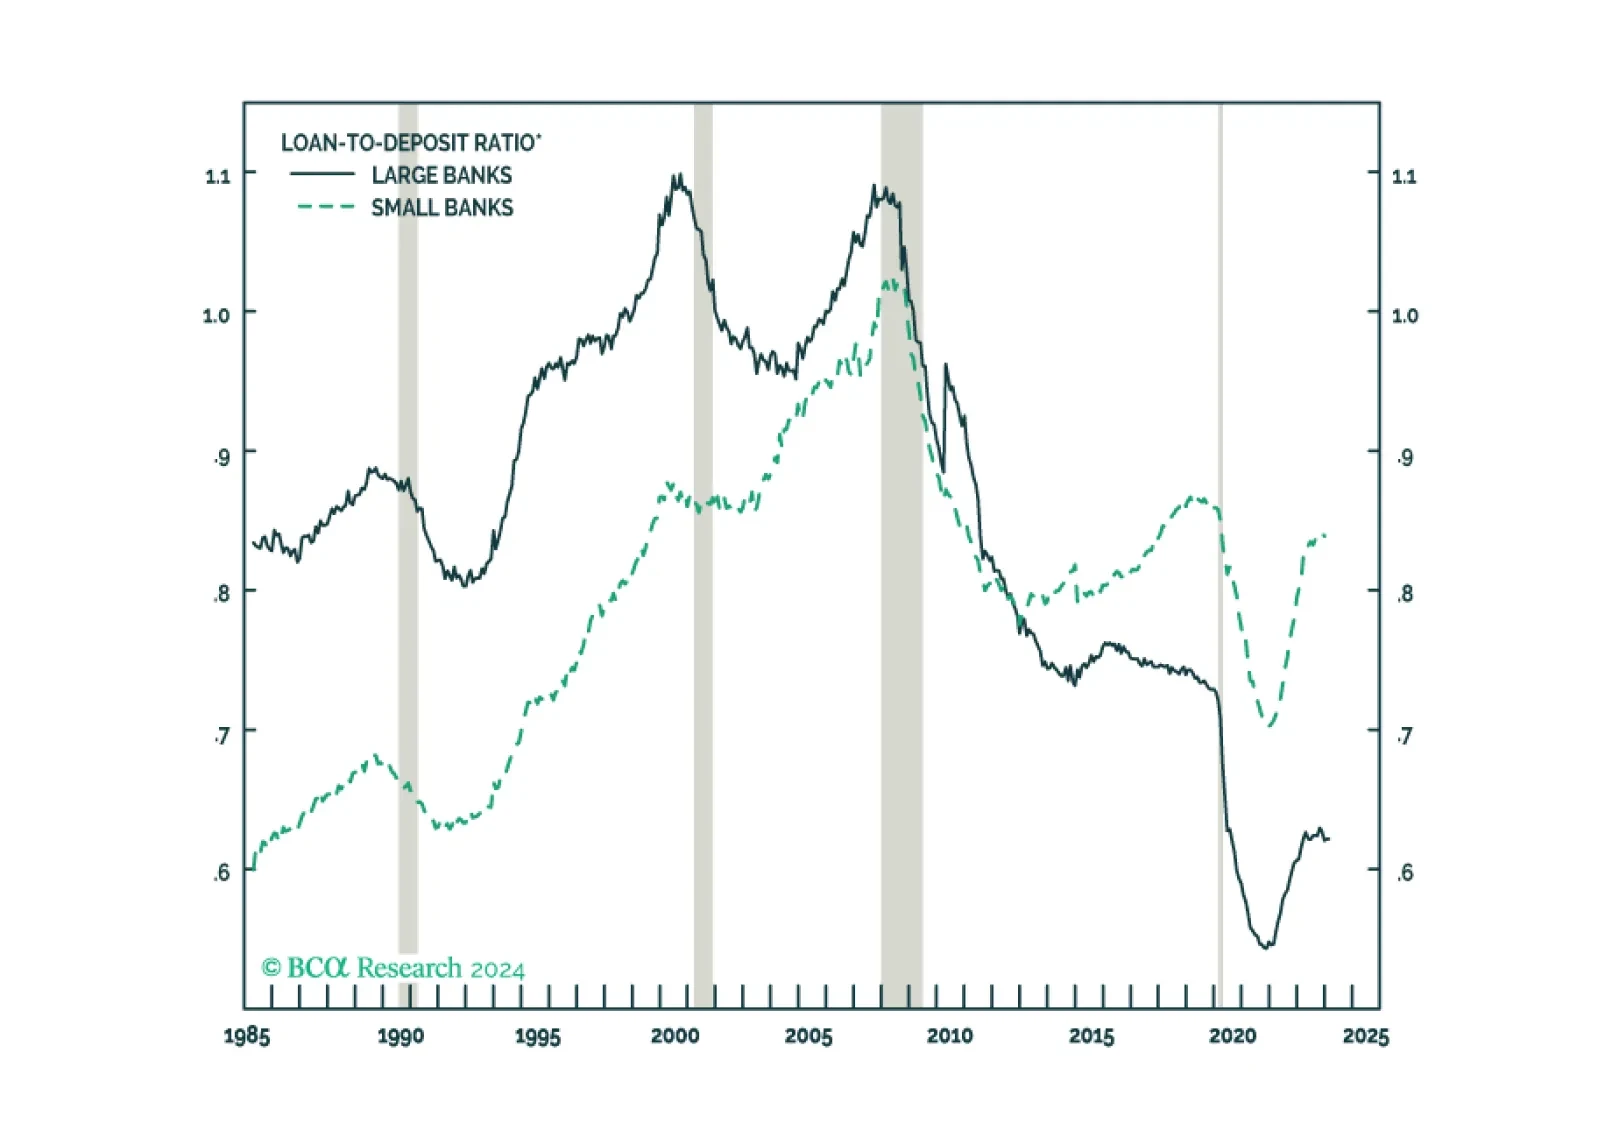
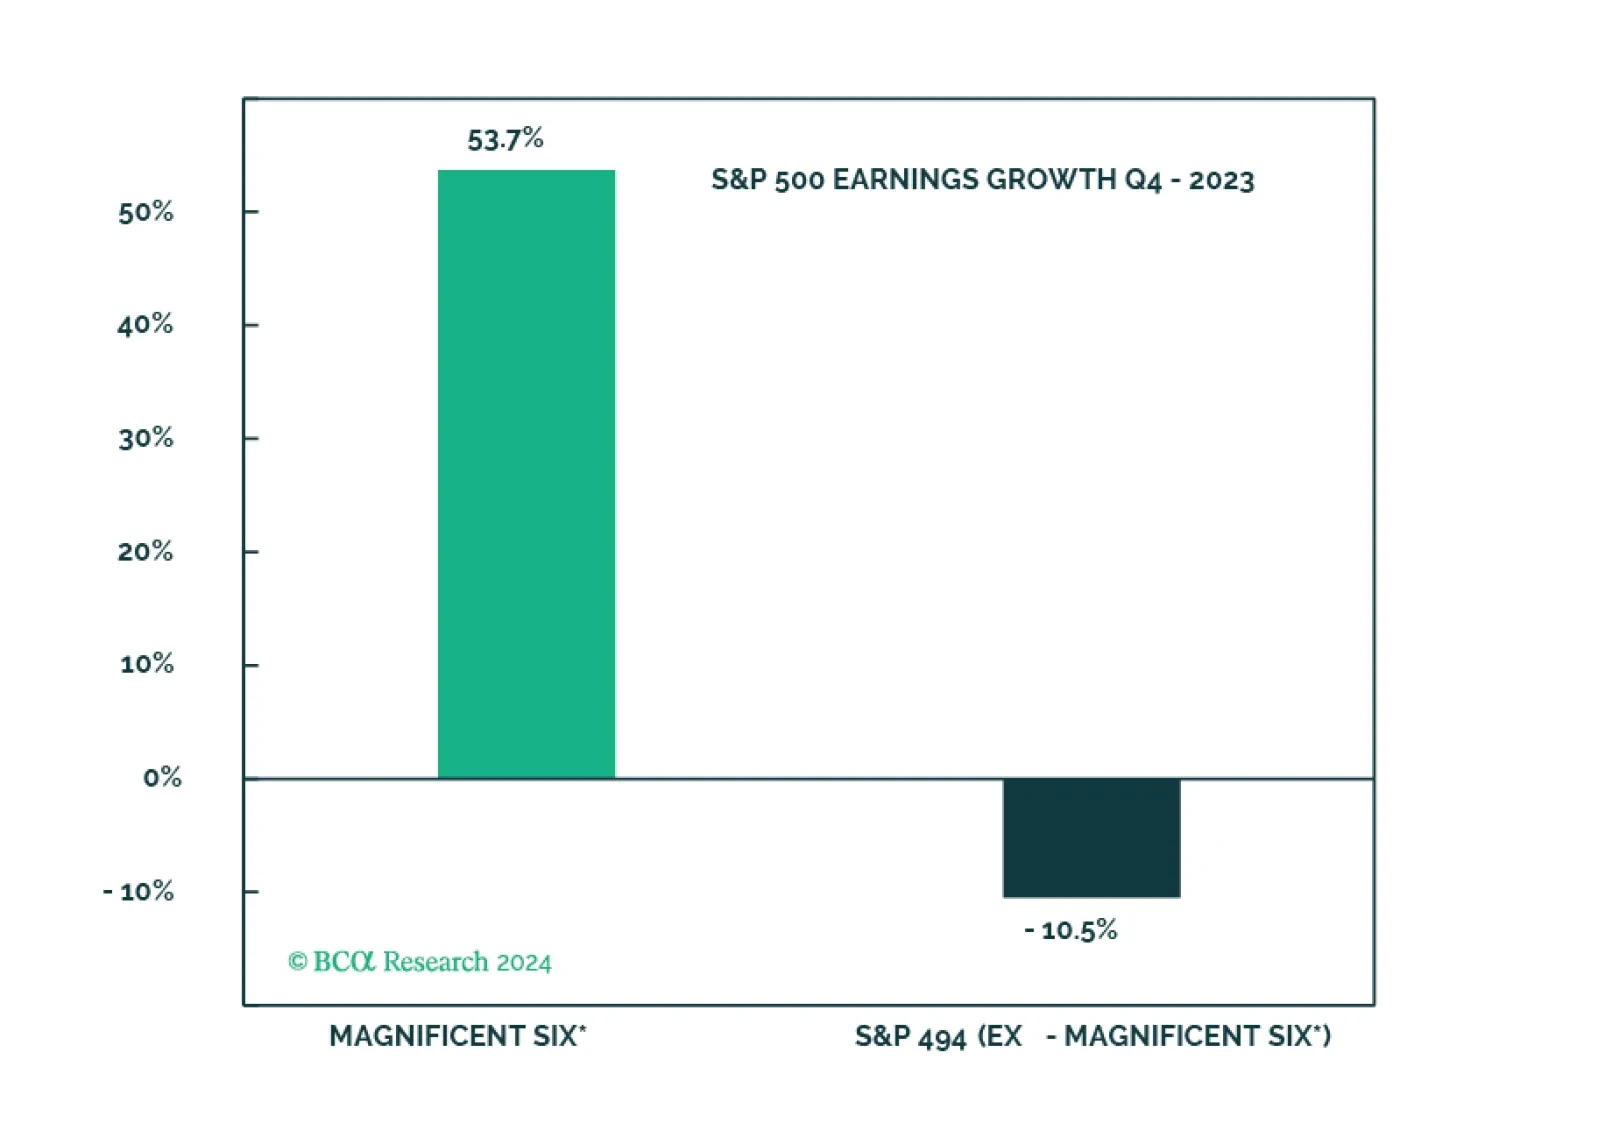
The soft landing and rate cuts narrative is being priced out, and the S&P 500 is overvalued and getting overbought. The Magnificent Seven are about to get a new moniker on the back of performance dispersion. However, without the cohort, S&P 500 earnings would have been even deeper in the red.

The Global Equity Score turned bearish this month, resulting in an increased exposure to the Consumer Staples and Health Care. The Style Score continues to favor Large-Cap Value over Small-Cap Growth.