Skip to main content

Latest from BCA Research
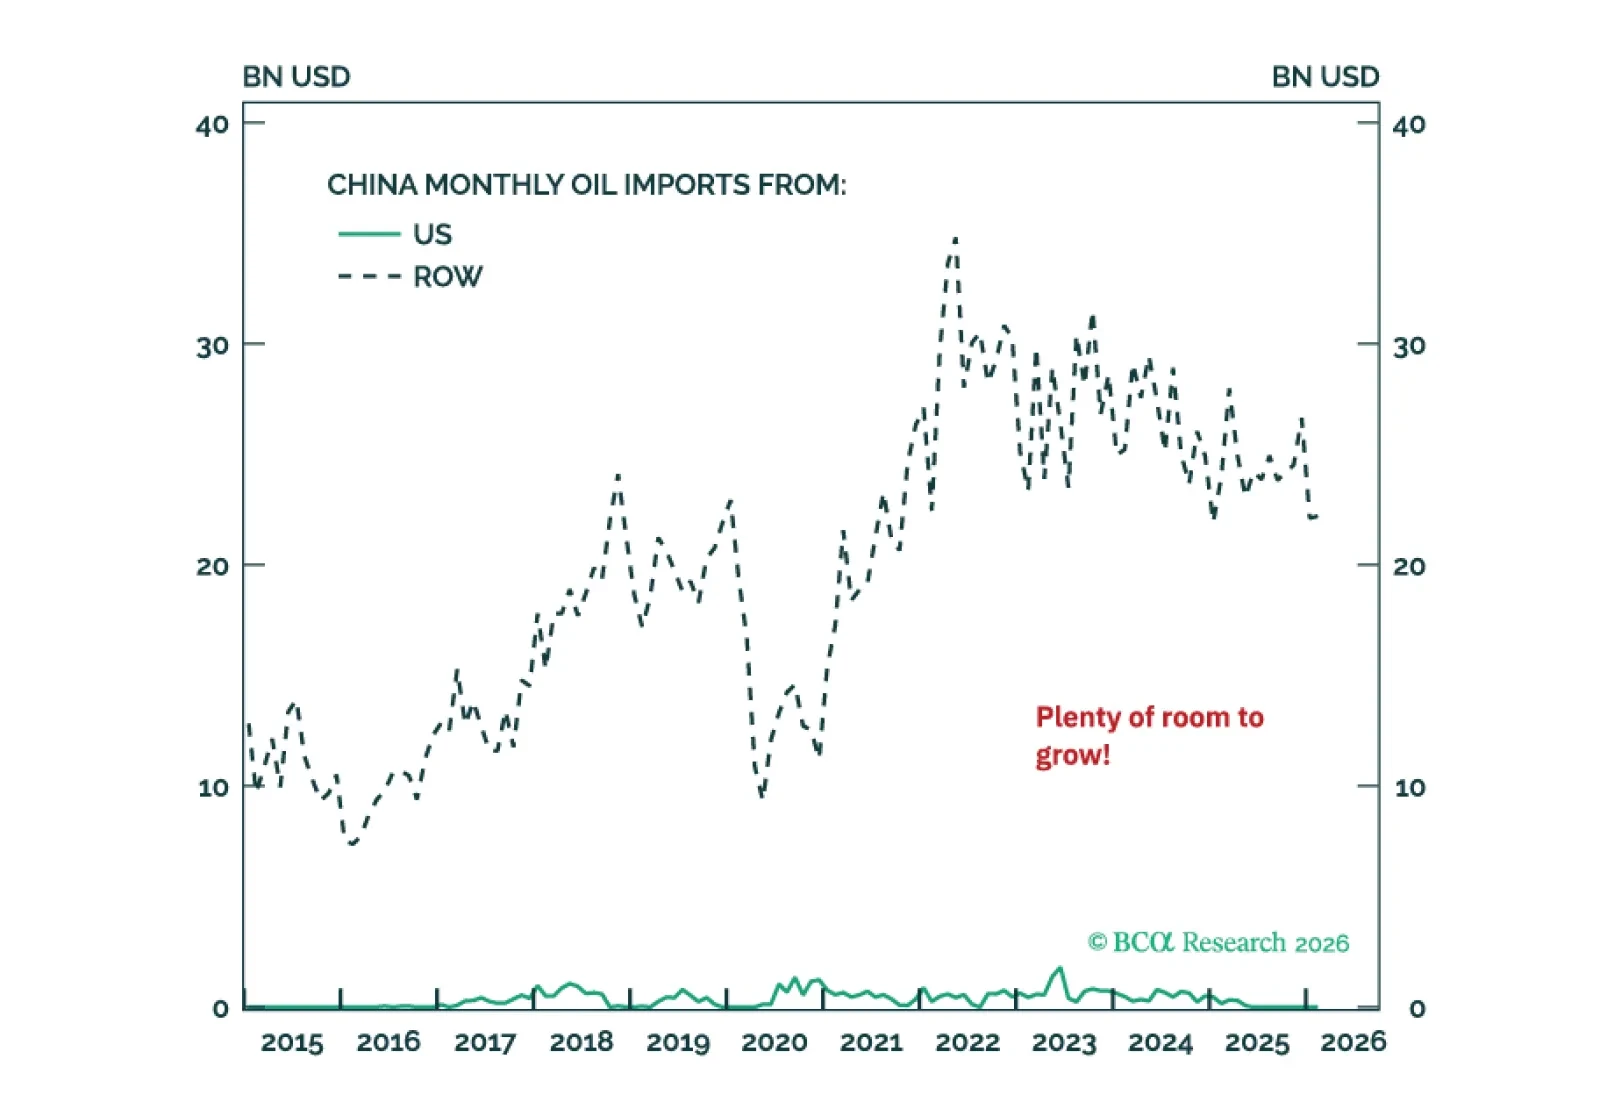
Special Report The US-China trade truce is getting bigger and better, but a grand strategic bargain on Iran and Taiwan is not happening.
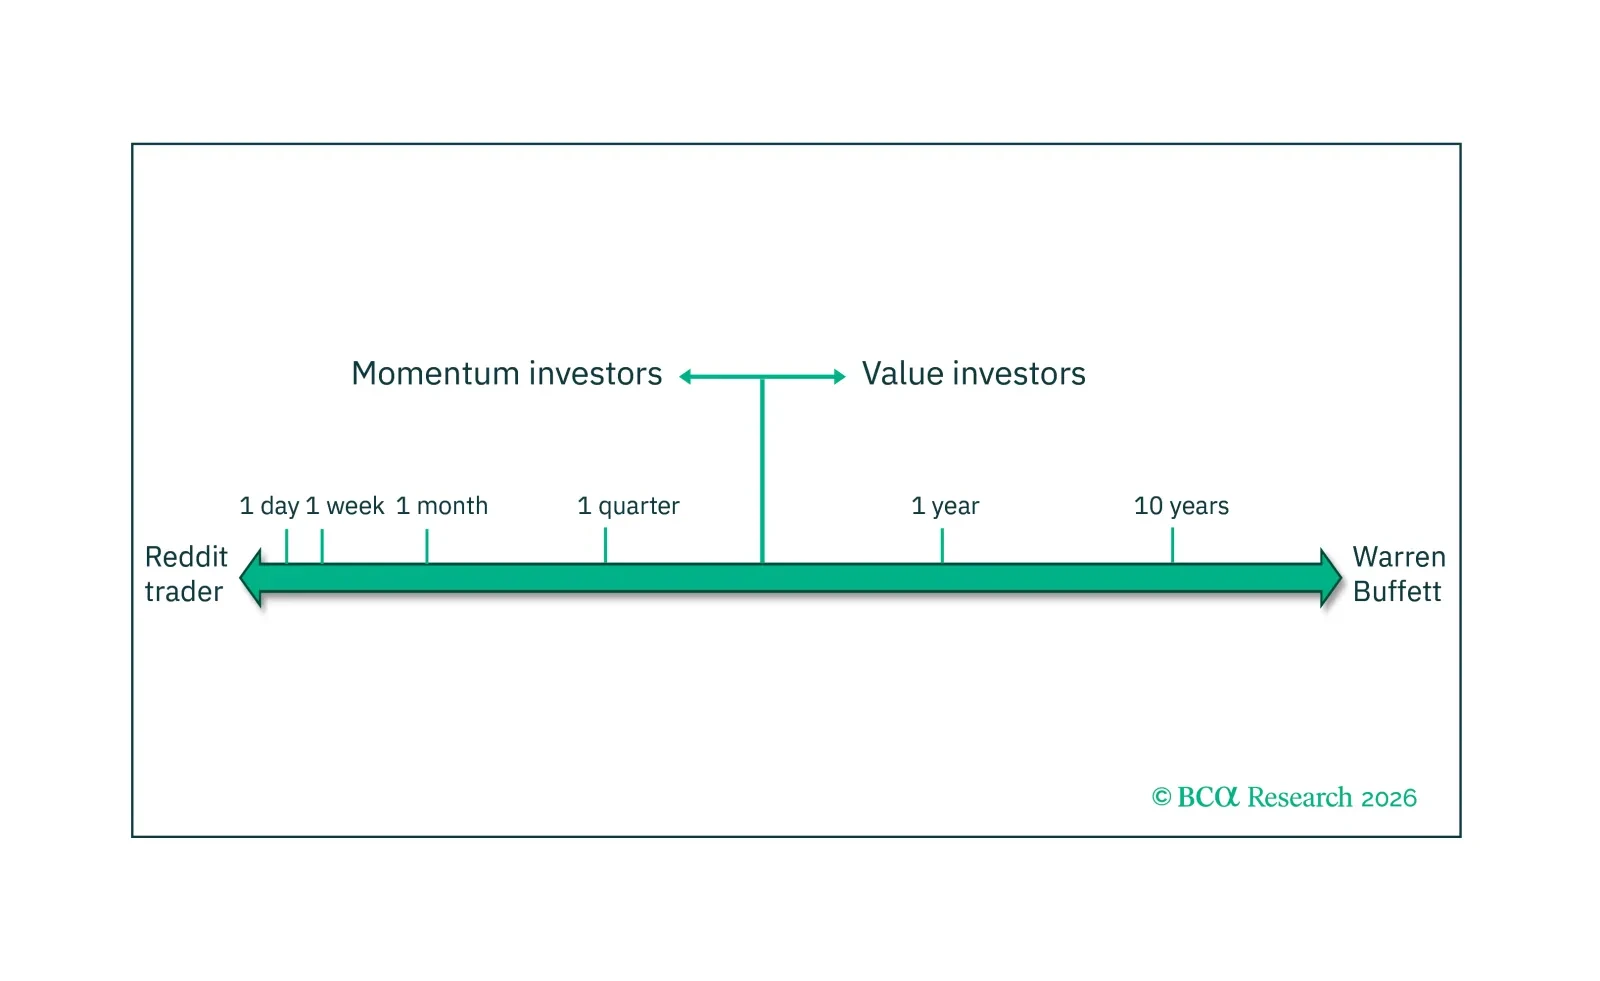
Special Report A market becomes inefficient, illiquid, and vulnerable to a phase transition when the ‘wisdom of crowds’ switches to the ‘madness of crowds.’ This switch from market wisdom to market madness may be the most significant recurring behavioural opportunity in active fund management and can be exploited in real-time by measuring the market’s complexity.
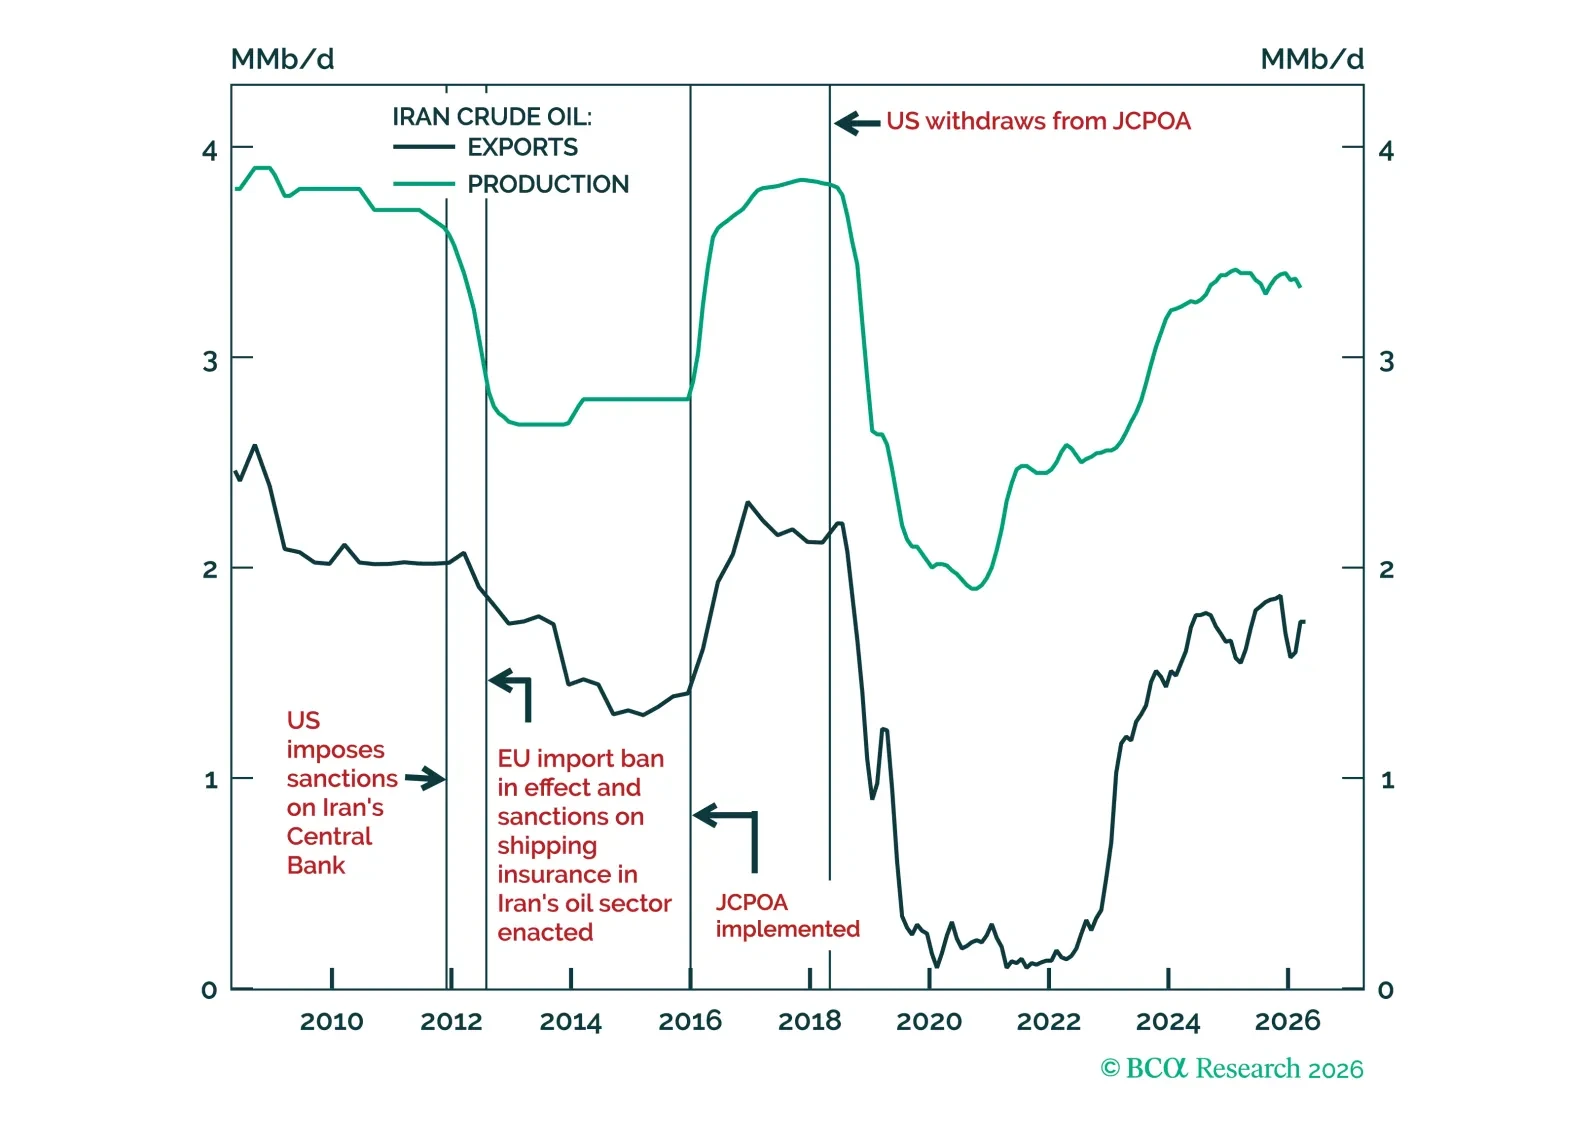
Hopes for an imminent Middle East de-escalation have capped oil prices in recent weeks, but that restraint may soon fade.
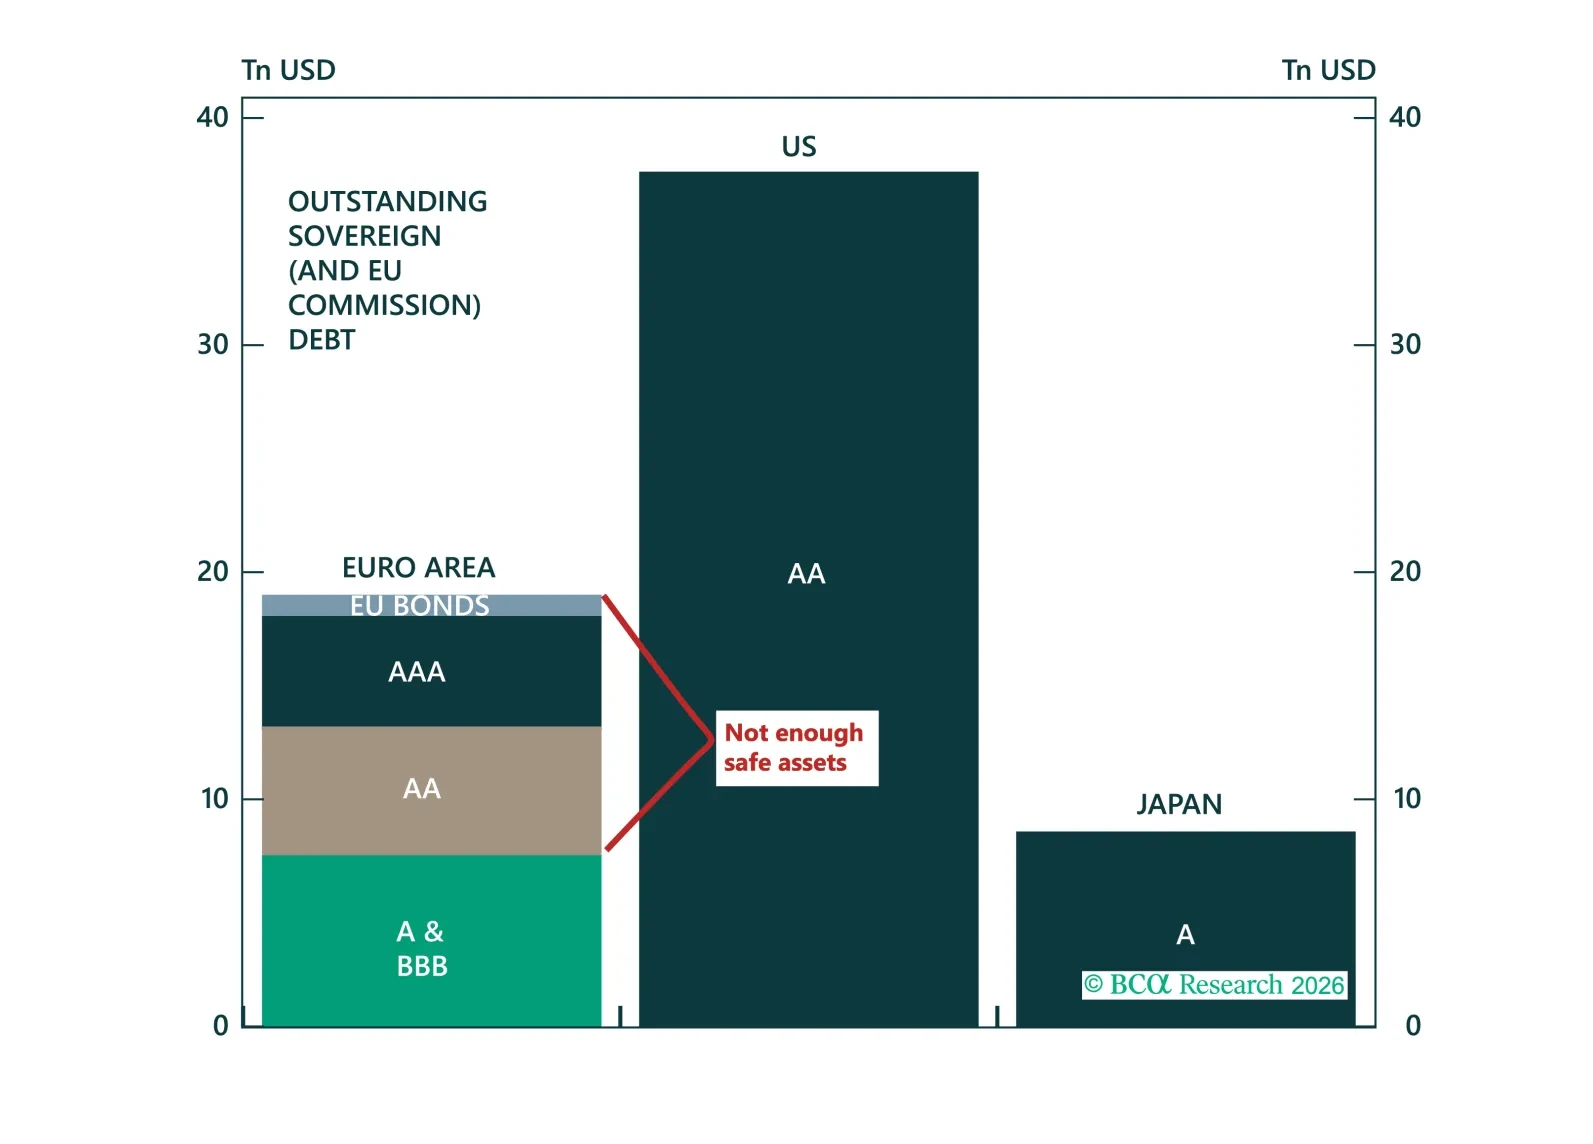
Special Report The dollar's retreat is creating the most compelling window for euro internationalisation since Maastricht, but Europe is missing the one instrument that would make it real. In this report, we make the case for the Eurobond, assess which model is most likely to prevail, and explain why the trade is long euro on dips and overweight Central and Eastern European sovereign spreads.
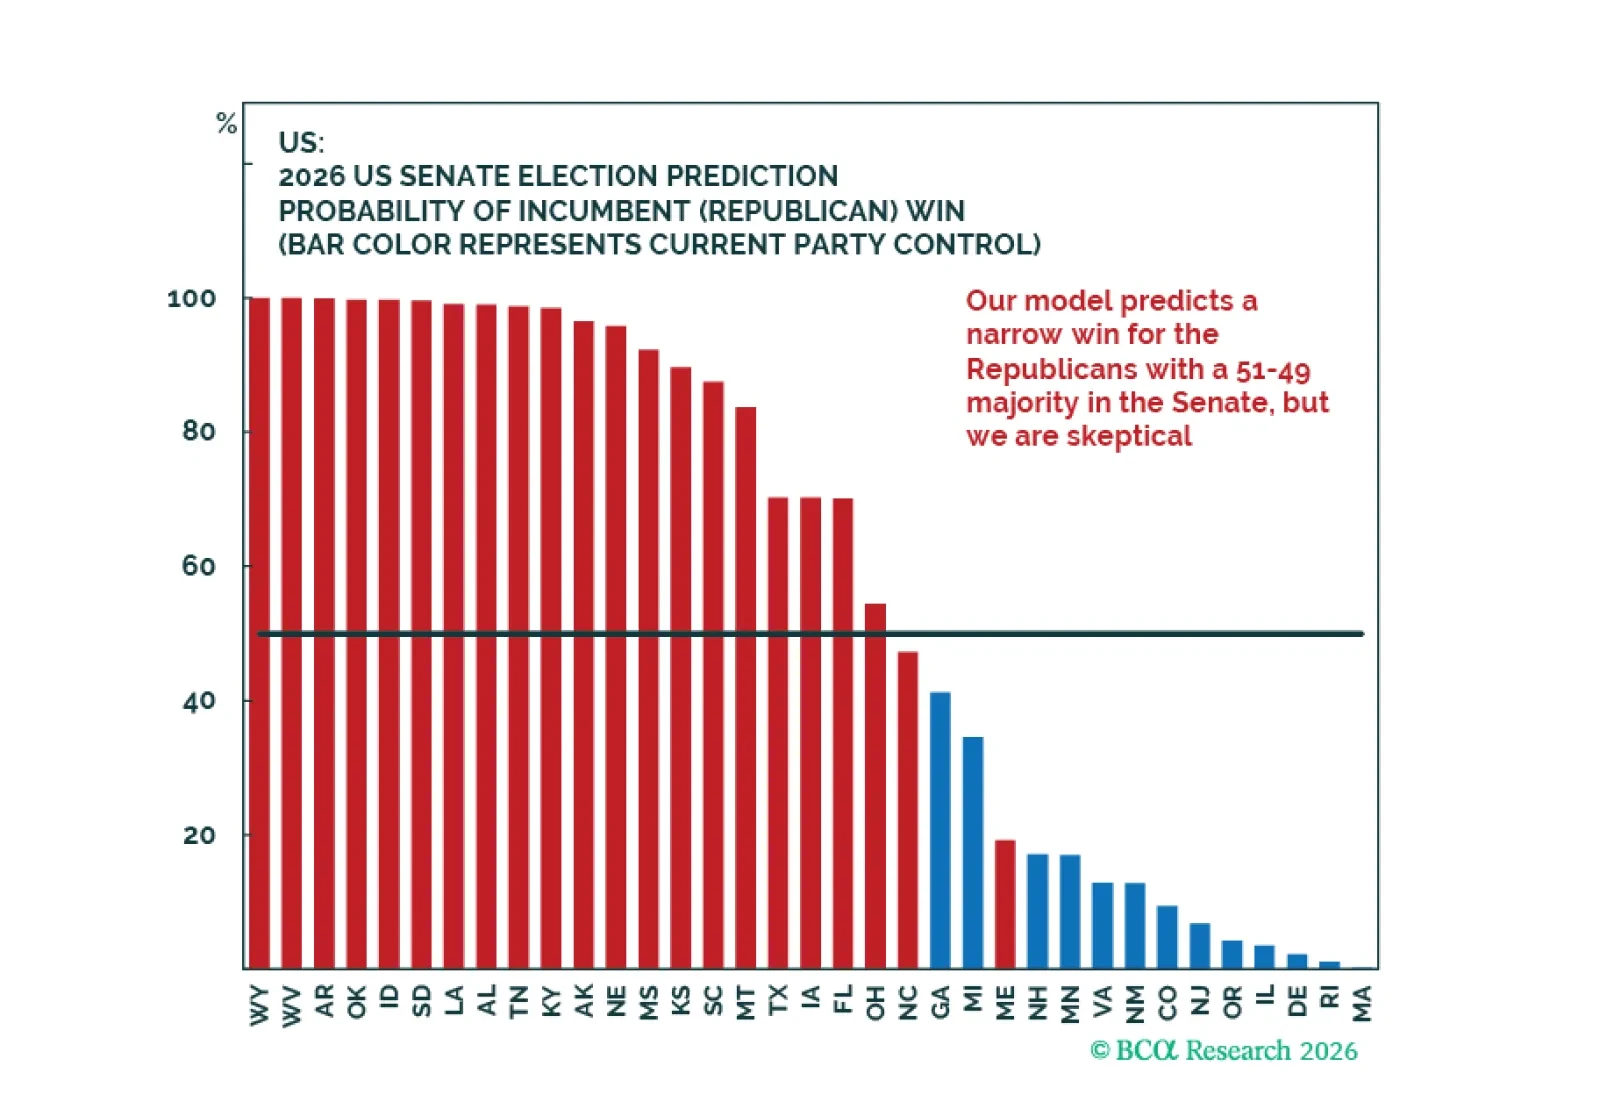
Special Report Democrats are likely to win big in this year's midterm elections. Our new quant model still slightly favors Republicans for the Senate, but we expect the oil shock to deliver surprise Democratic victories.
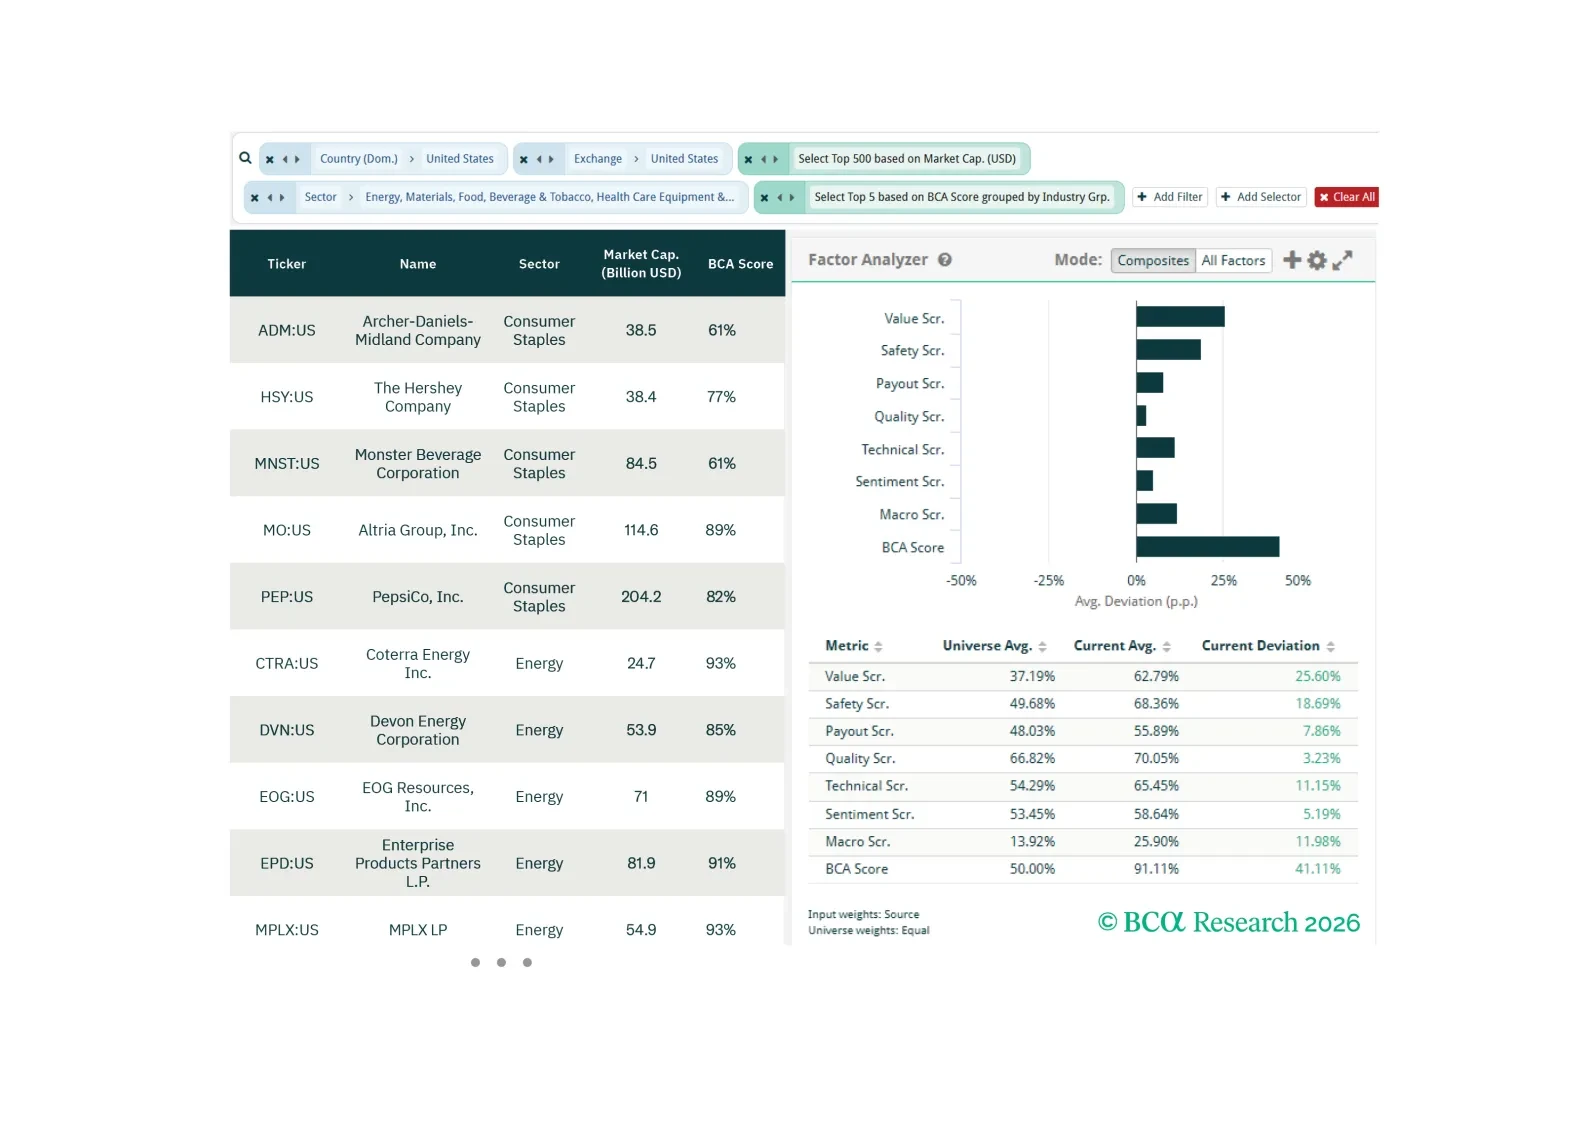
In this screener report, we explore opportunities in Inflation risk, supply-constrained Information Technology stocks, and old-economy cyclicals.
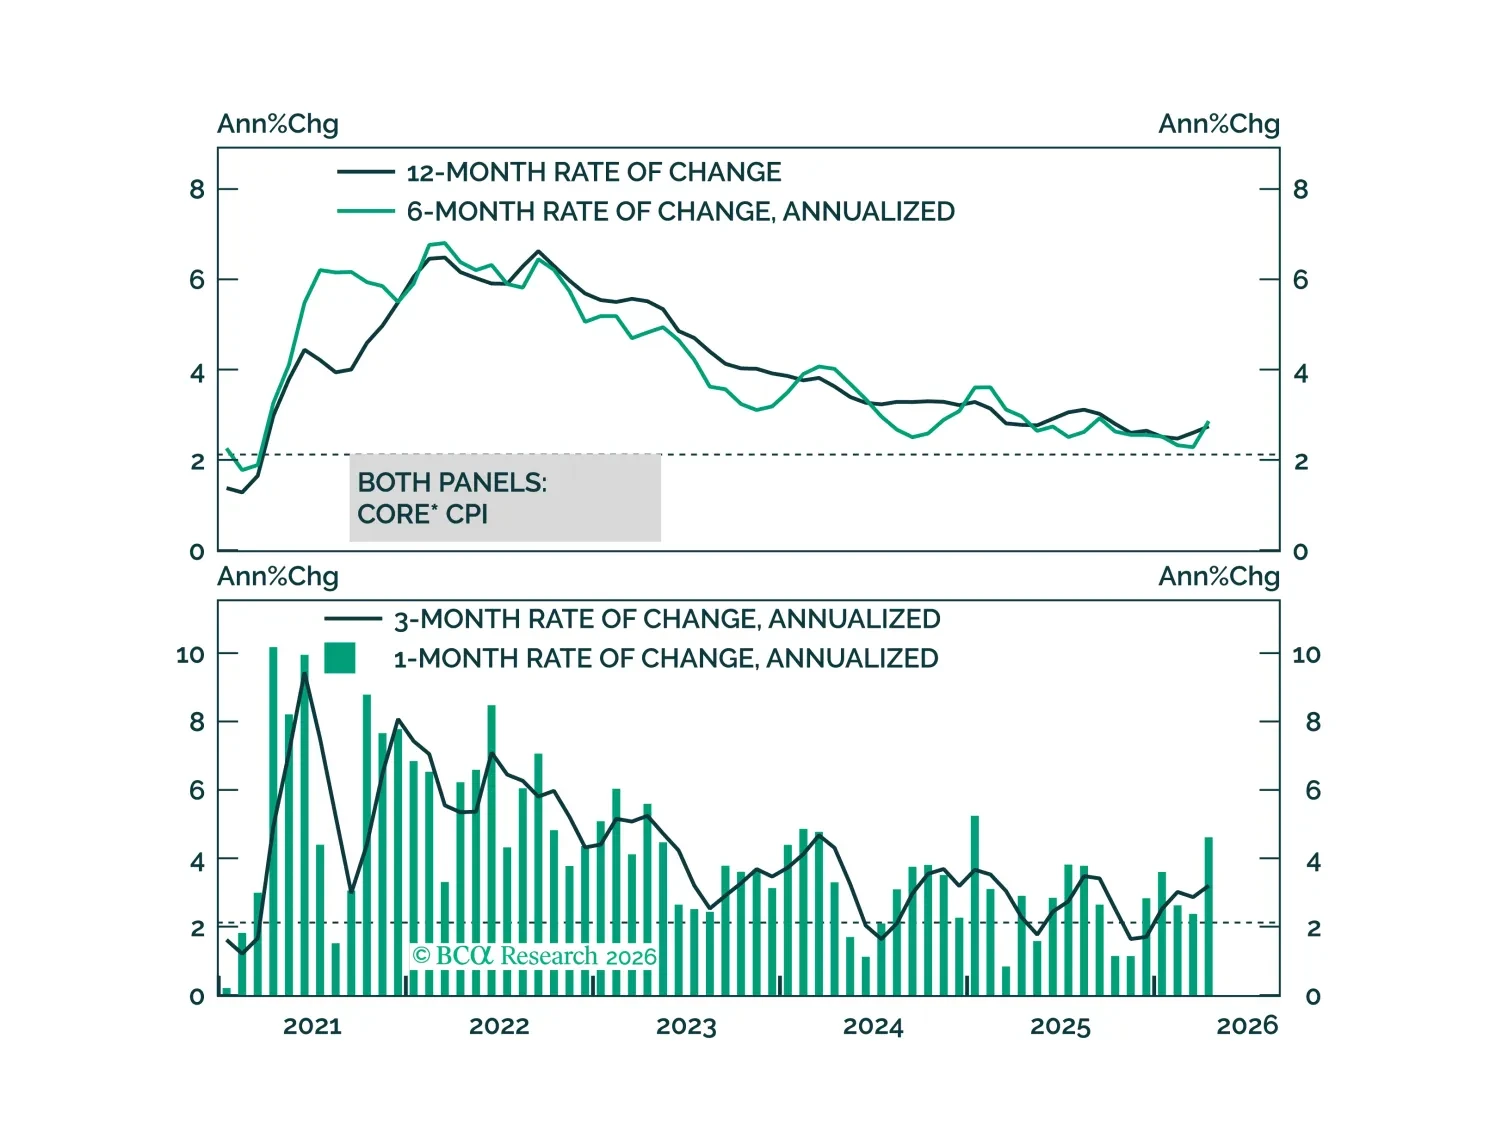
The April CPI report showed clear evidence of the direct effect of higher oil prices on inflation but, so far, limited evidence of passthrough to core.
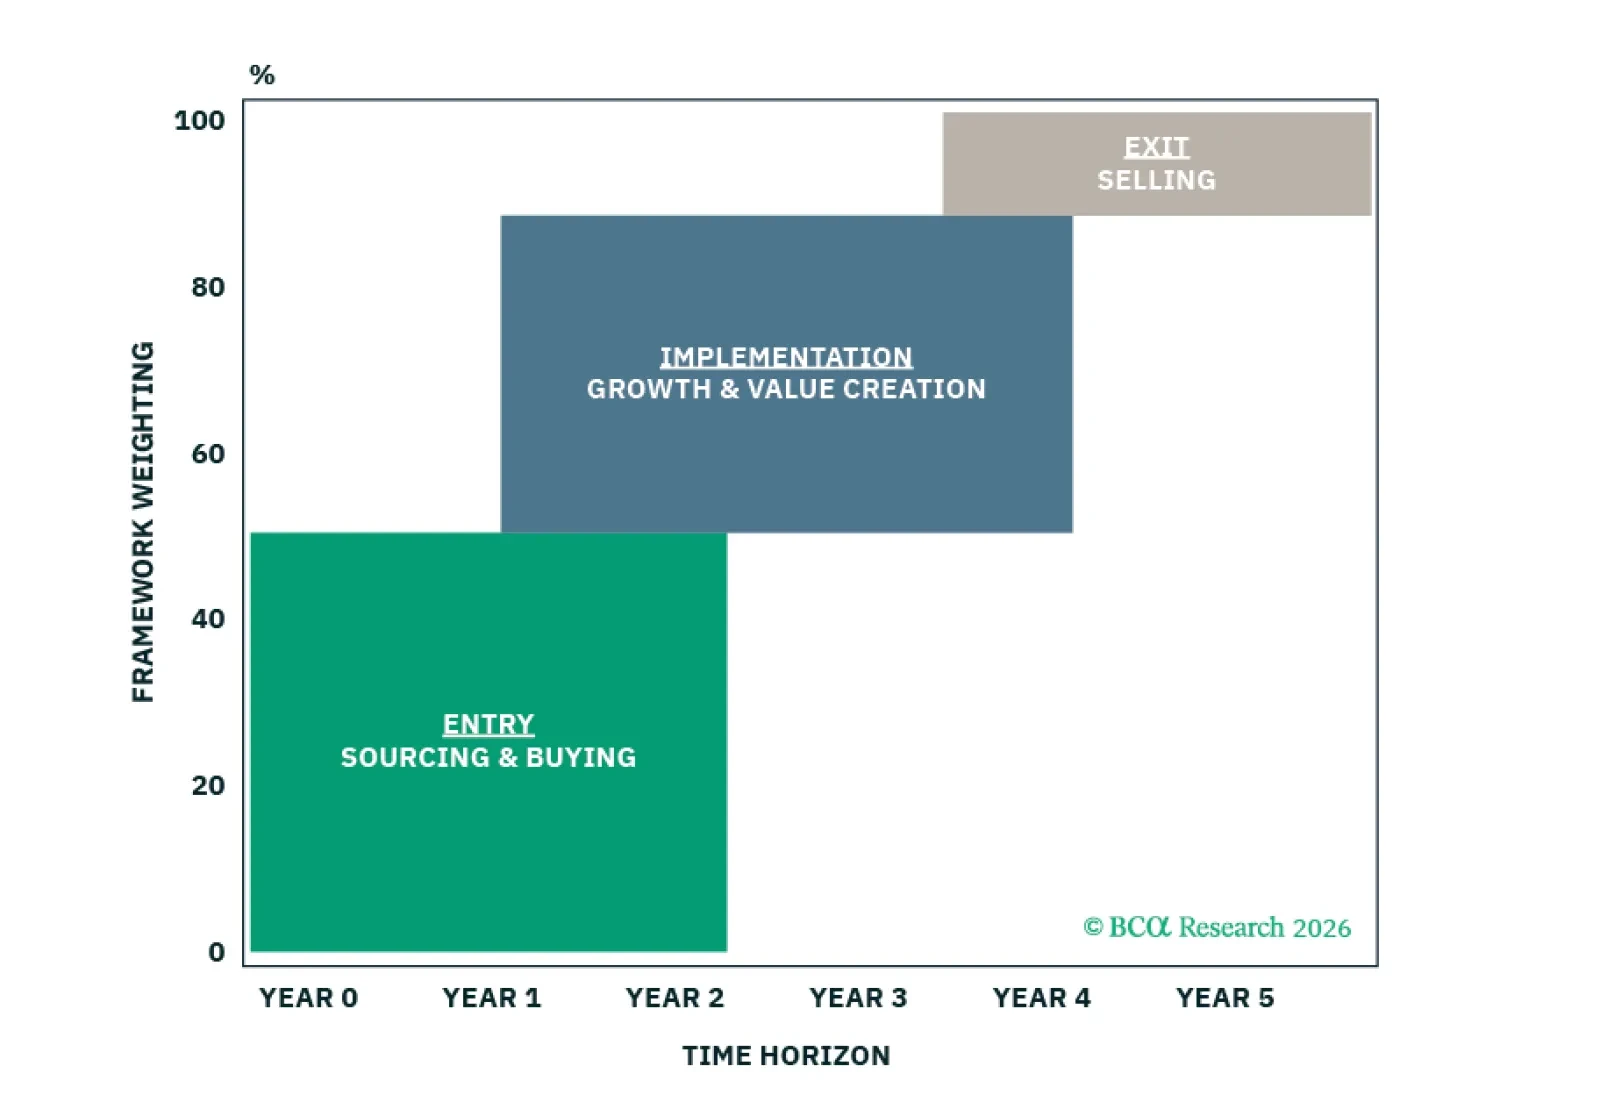
Special Report Private Equity fund vehicles may extend beyond 10 years, but the underlying assets that drive performance typically do not. We provide the framework for investors to capitalize on this reality.
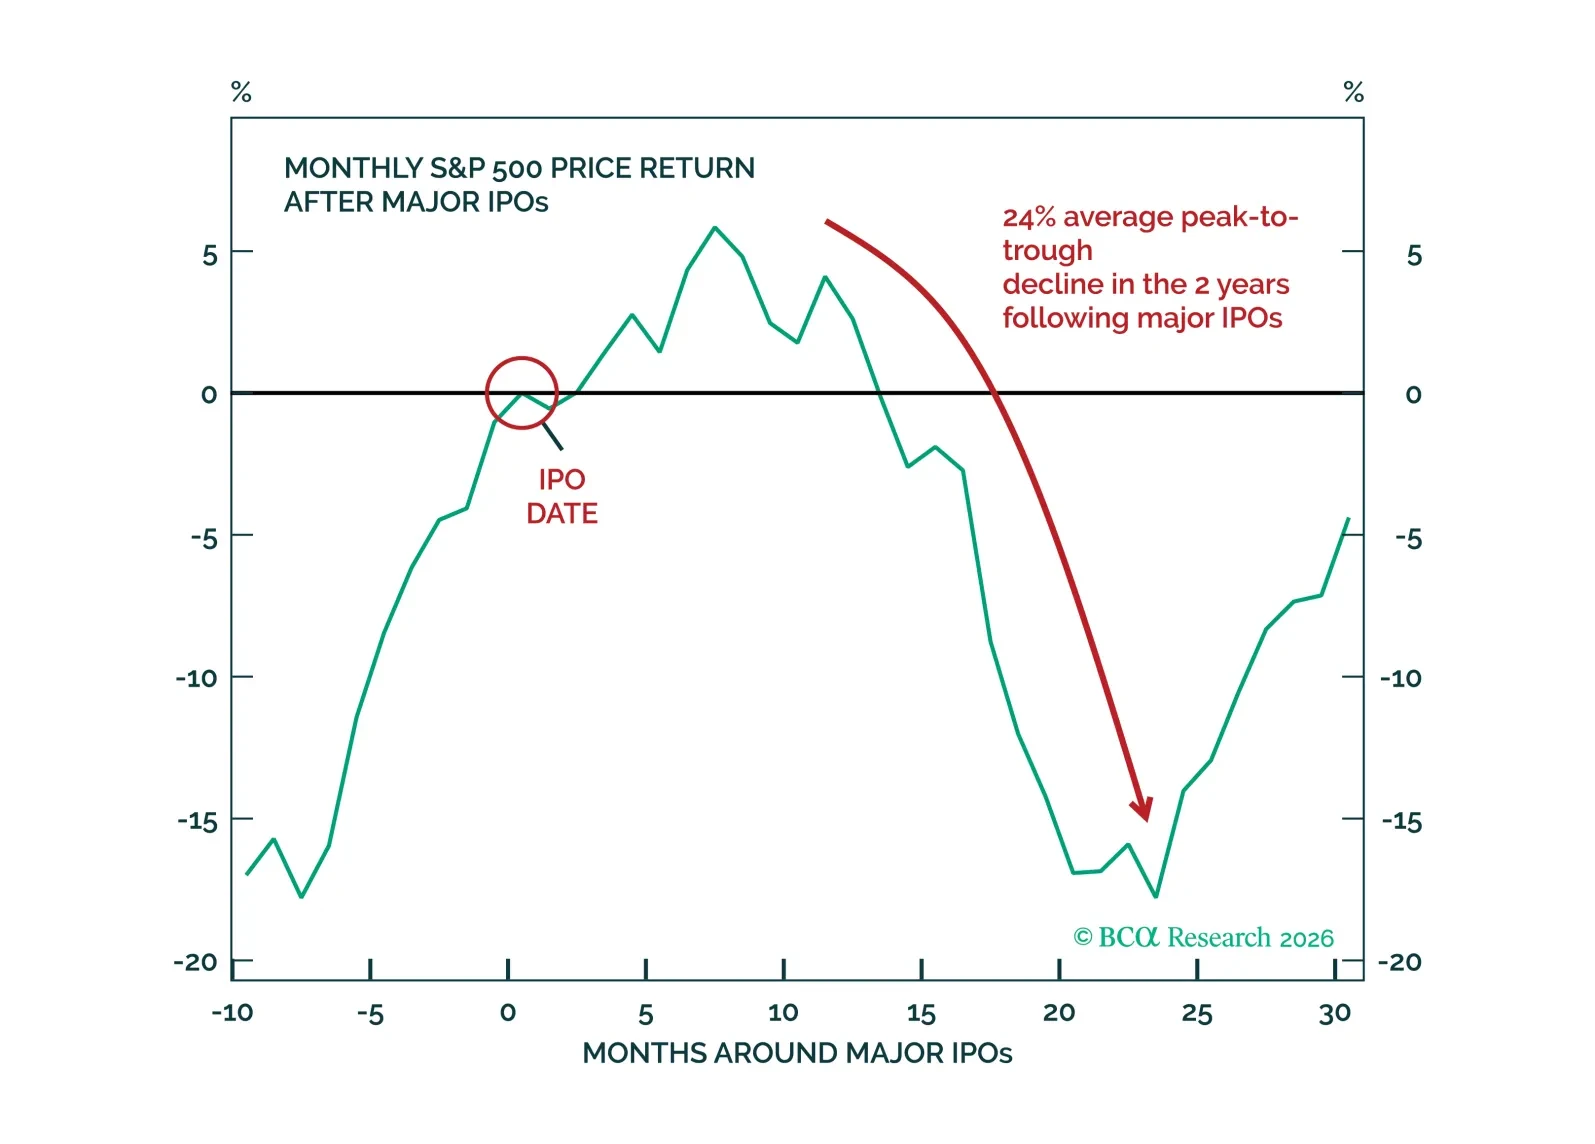
Equities have thrown caution to the wind for much of April and early May. We do not disagree with the sanguine mood, but caution that the Hormuz saga is far from over. Still, the AI capex mania continues and the labor market is firming in the US, suggesting that there is more upside to equities.
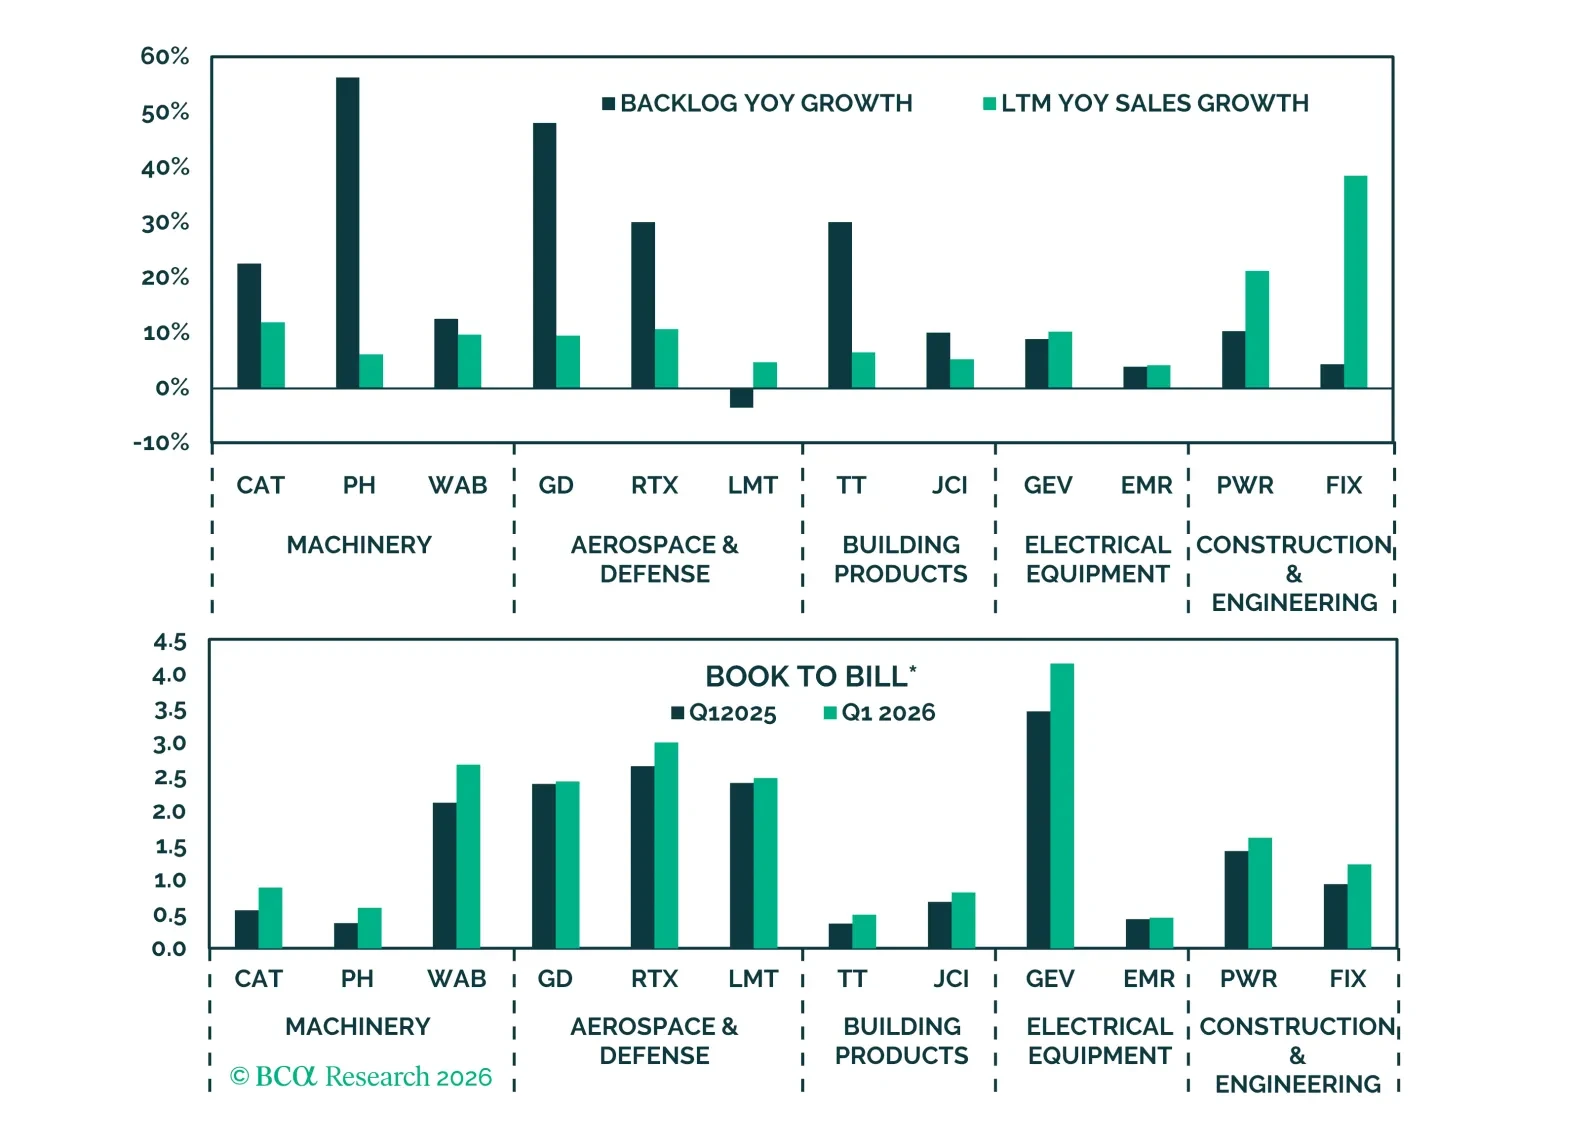
The investment cycle remains firmly intact, driving equity prices and fundamentals, as confirmed by both Q1 data and corporate commentary. Upside surprises, expanding margins, and rising capex expectations point to resilient demand. Companies confirm that AI-related demand is broad and visible, while geopolitical and credit risks remain contained and not yet systemic.