Latest from BCA Research
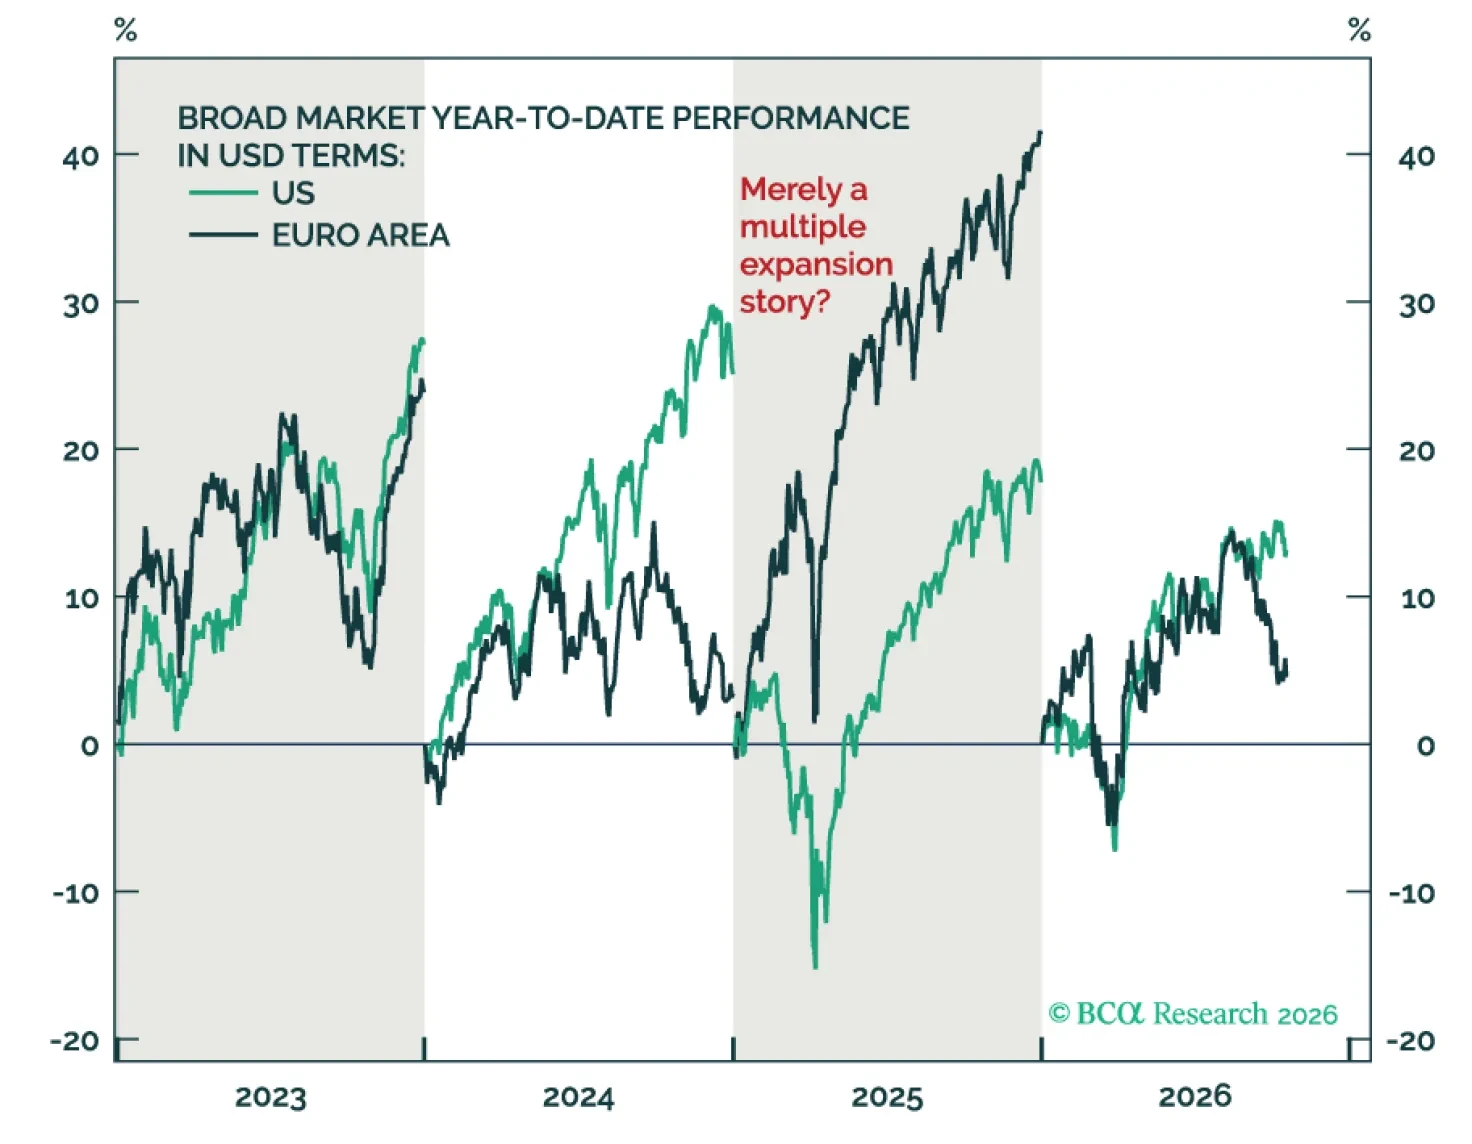
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.
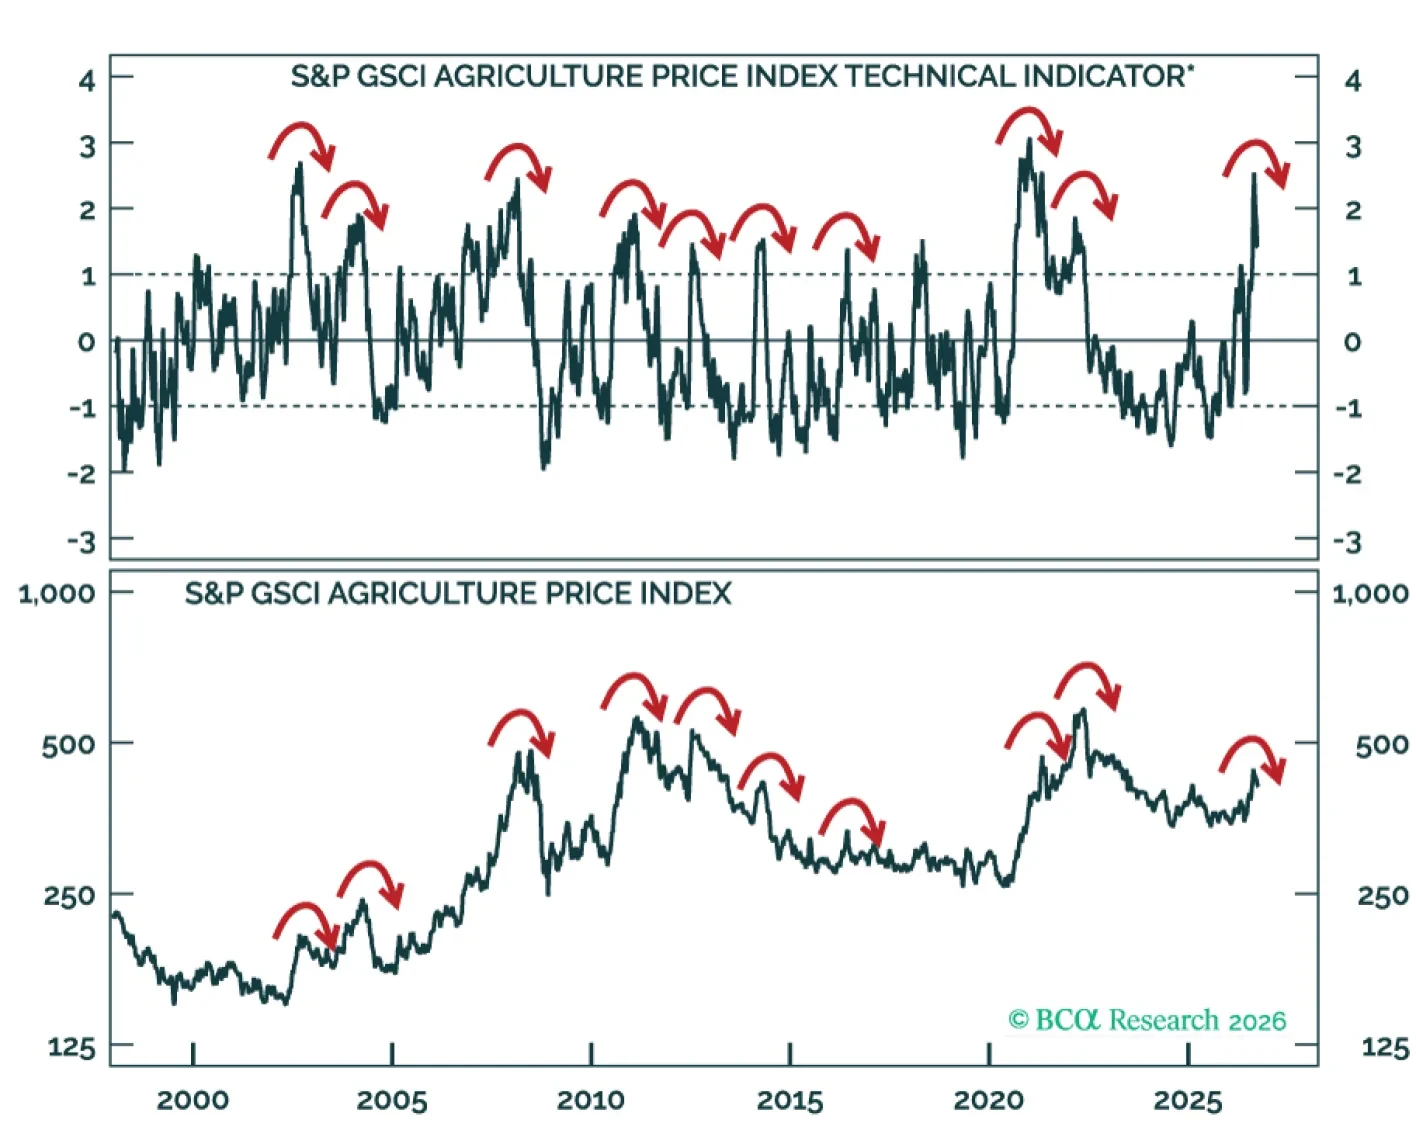
Ags have tumbled from overbought highs, and further near-term weakness is likely. But a “super” El Niño and an ongoing energy shock are setting the stage for the next rally.
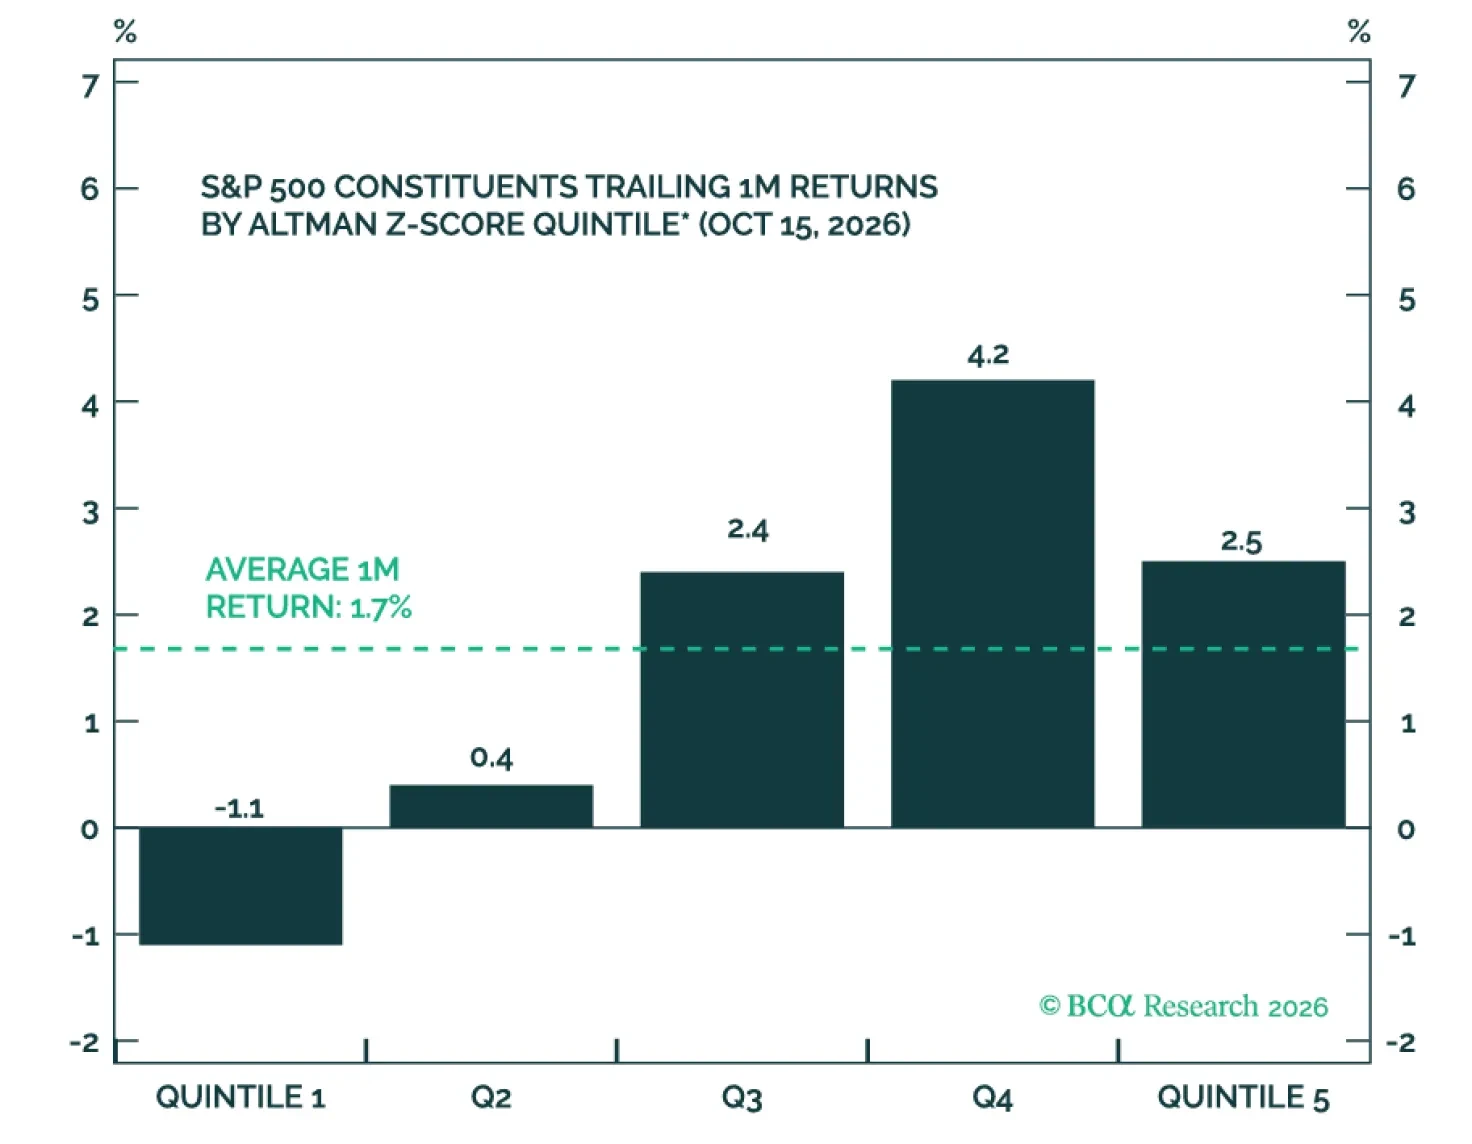
Credit spreads have widened as bond risks intensified, pressuring weak-balance-sheet companies. But the stress is narrow and valuations have already compressed, so equity risks look manageable. Rather than de-risk, we would lean into quality: large over small caps, quality capex, and defensible Tech margins, and look to Q3 earnings for confirmation.

We highlight several potential inflections in well-established structural factors, pointing out ways that markets might respond differently this time to economic data and policy actions.

EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.
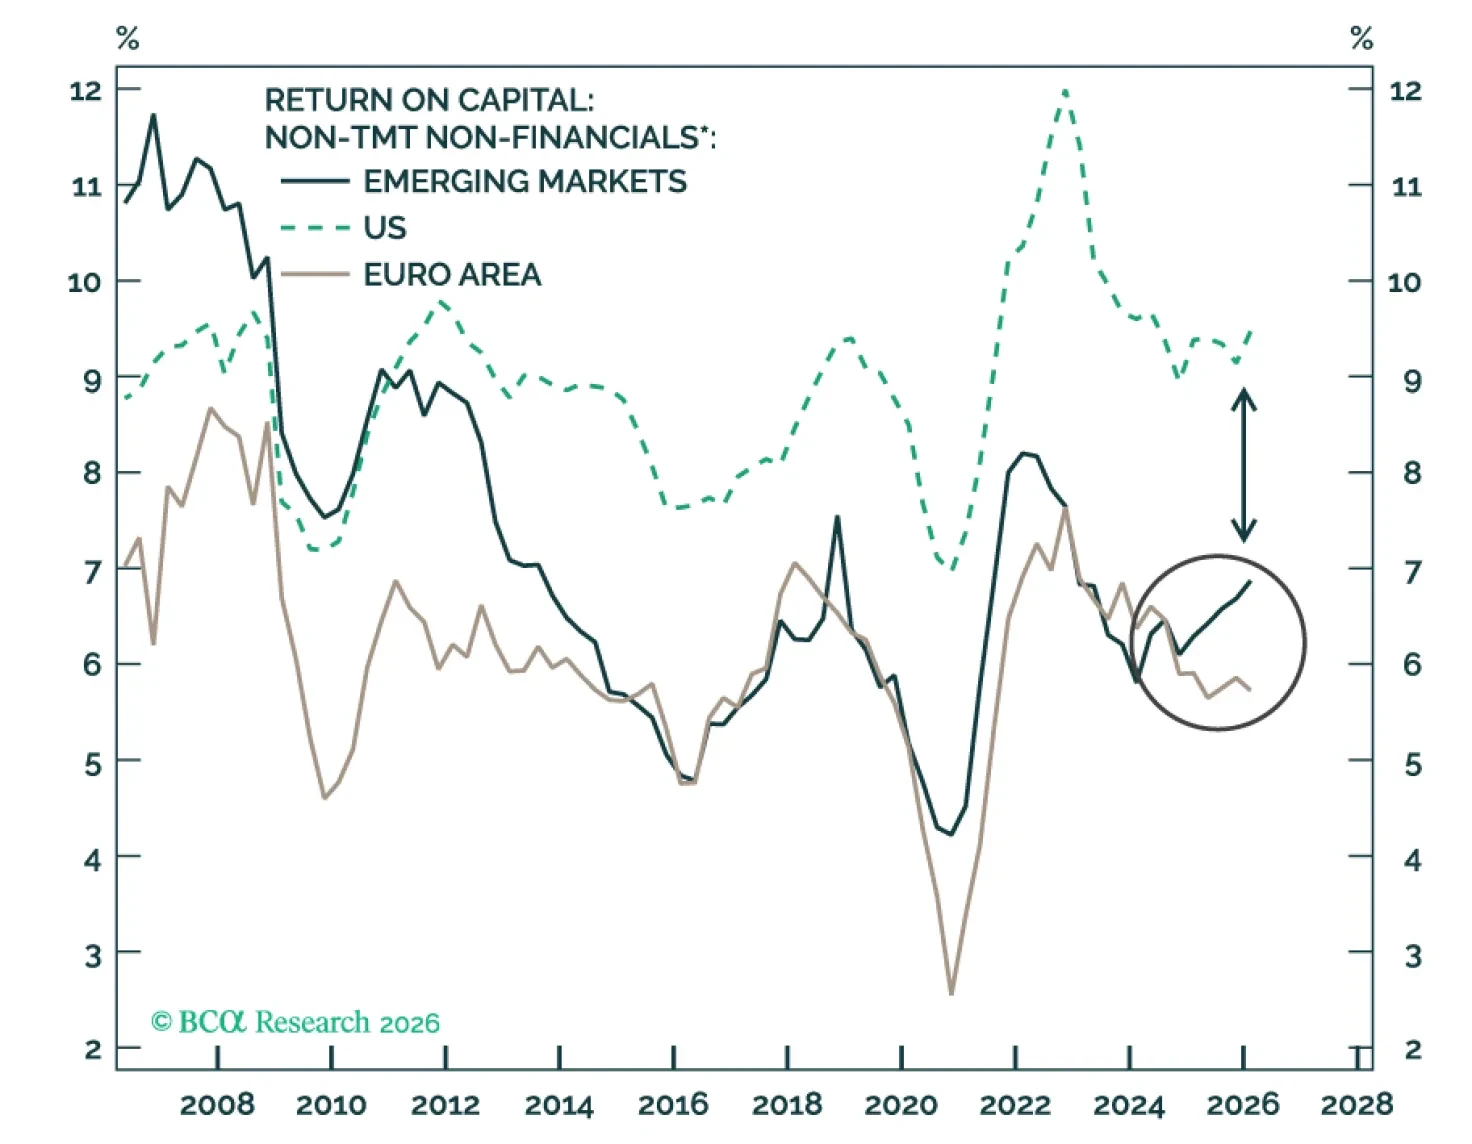

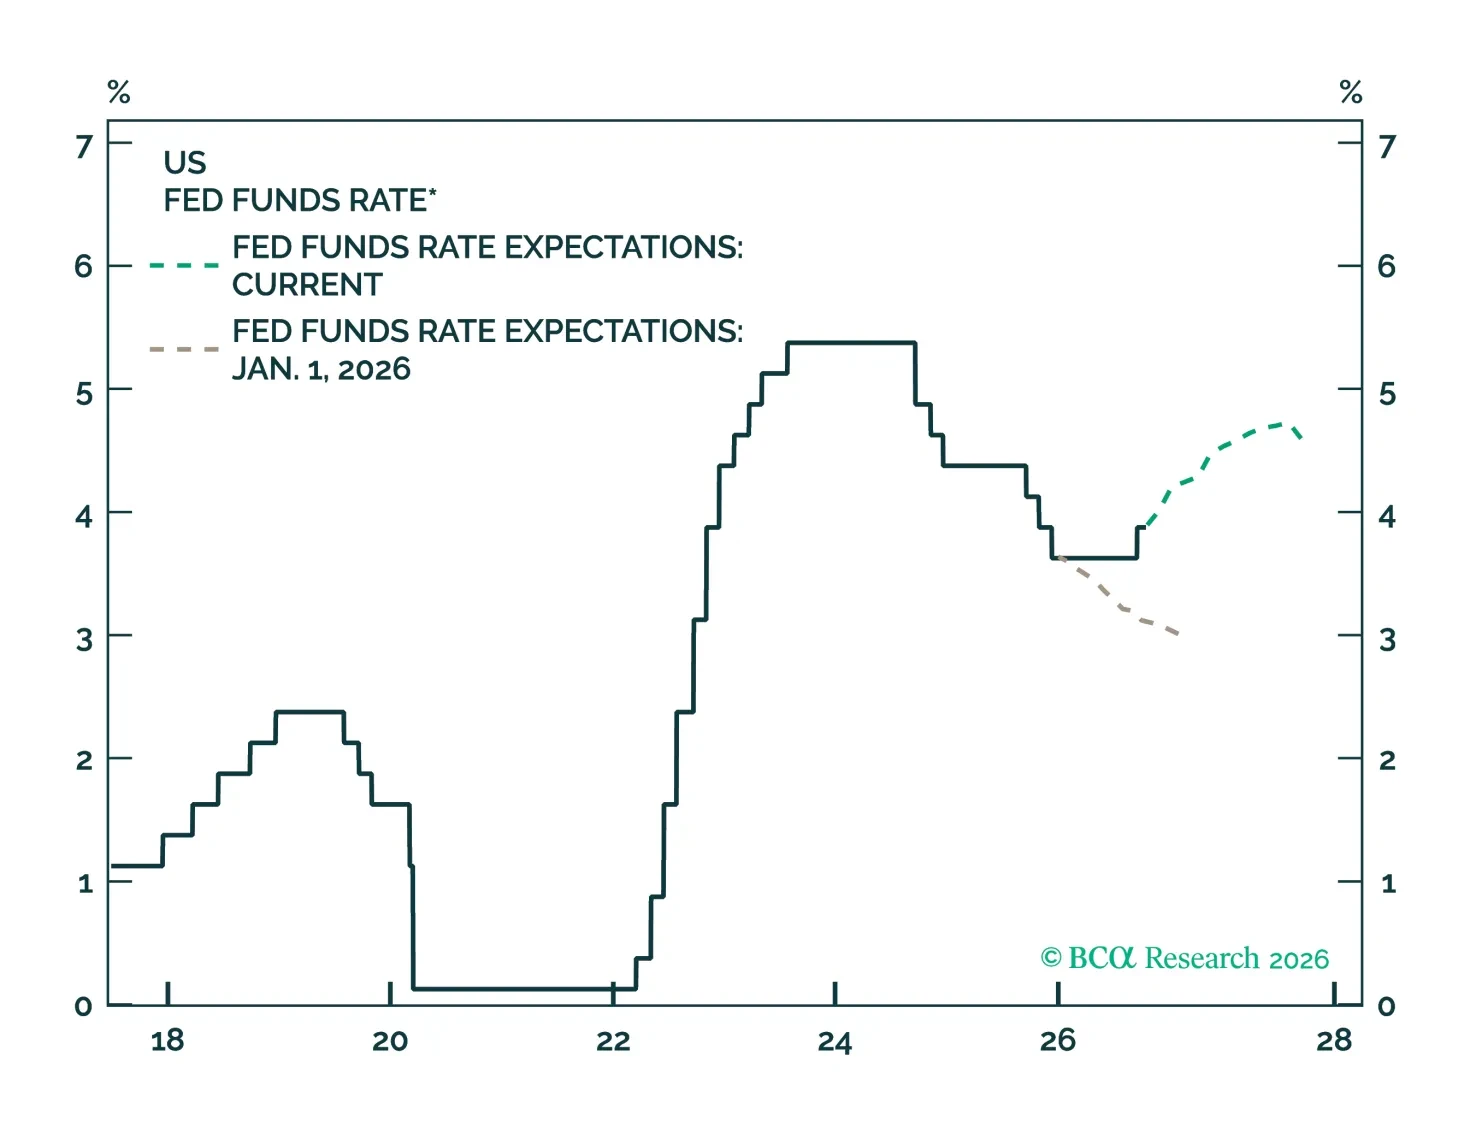
AI capex is supporting the global economy but also generating collateral damage for rate-sensitive sectors such as housing, as well as highly indebted governments. Maintain a benchmark allocation to equities for now and look to get more defensive next year.
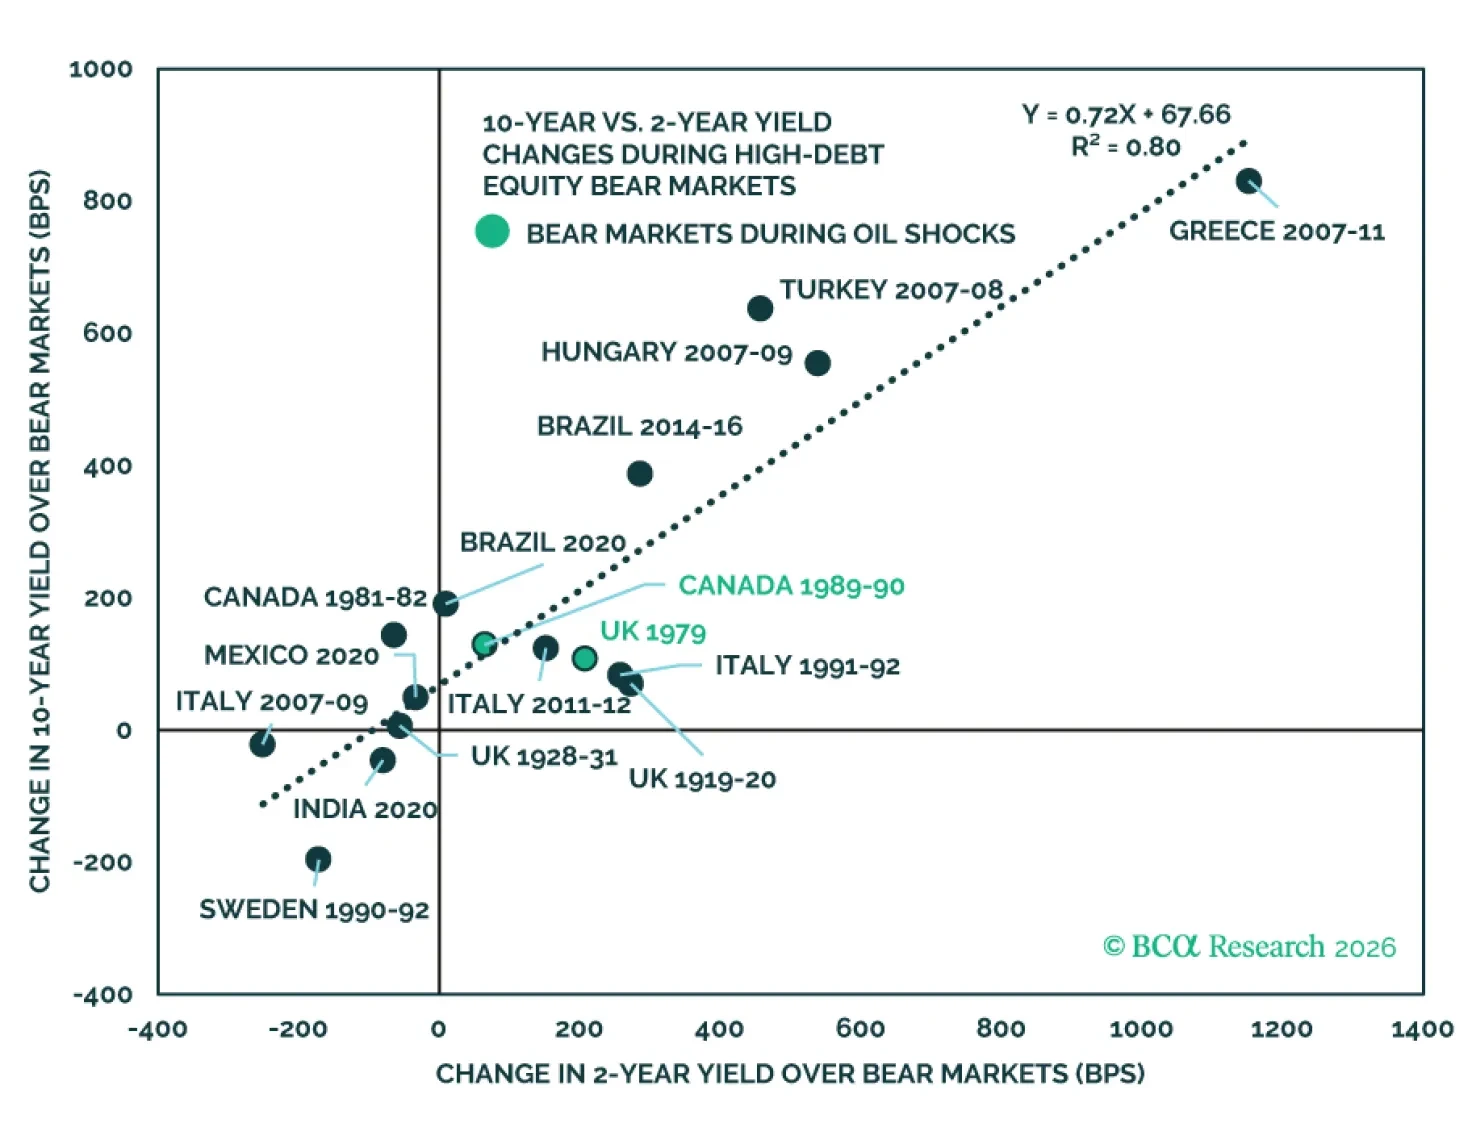
History suggests central bank policy determines how bonds behave in recessions, even for high-debt countries. The Fed should be able to cut into a slowdown, making Treasurys an effective equity hedge… for USD-based investors. Foreign investors will see currency depreciation erase their gains.
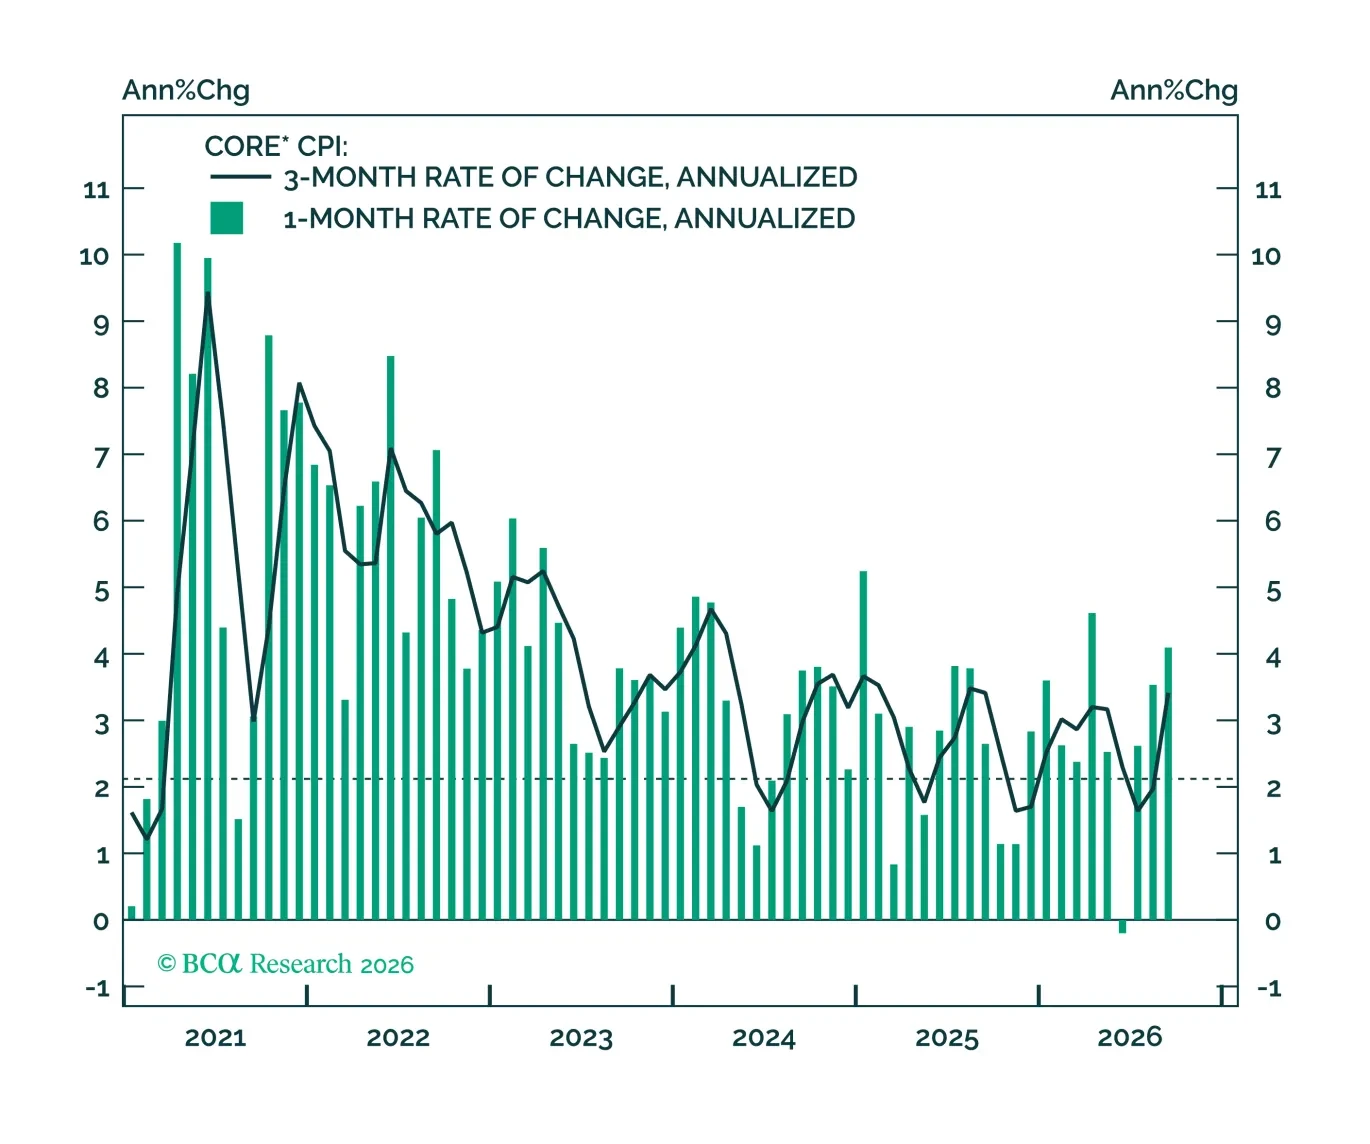
US inflation came in hot for the second consecutive month in September, though probably not hot enough for the Fed to move its next rate hike up to the October meeting.