Latest from BCA Research
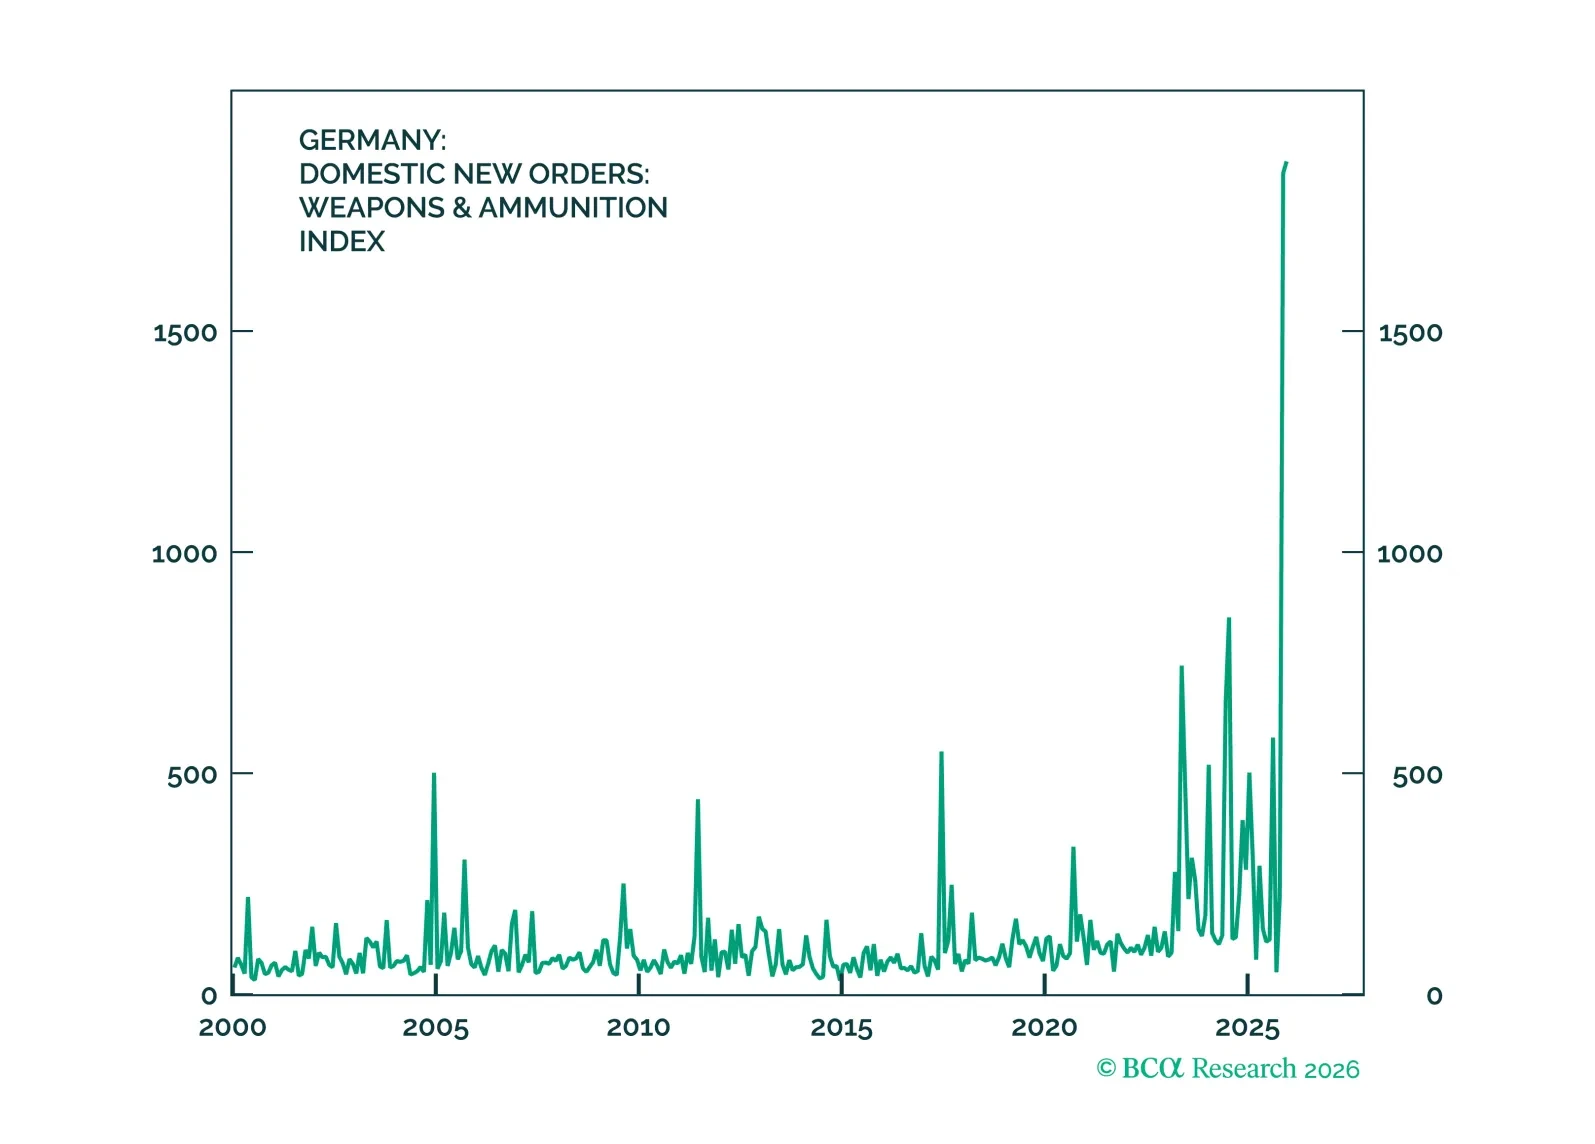
Beyond the imminent SCOTUS ruling, we revisit our bullish Europe thesis – with the Chart of the Month suggesting that Germany is so back – as well as our bearish USD view. Also, a few charts on oil and geopolitics.
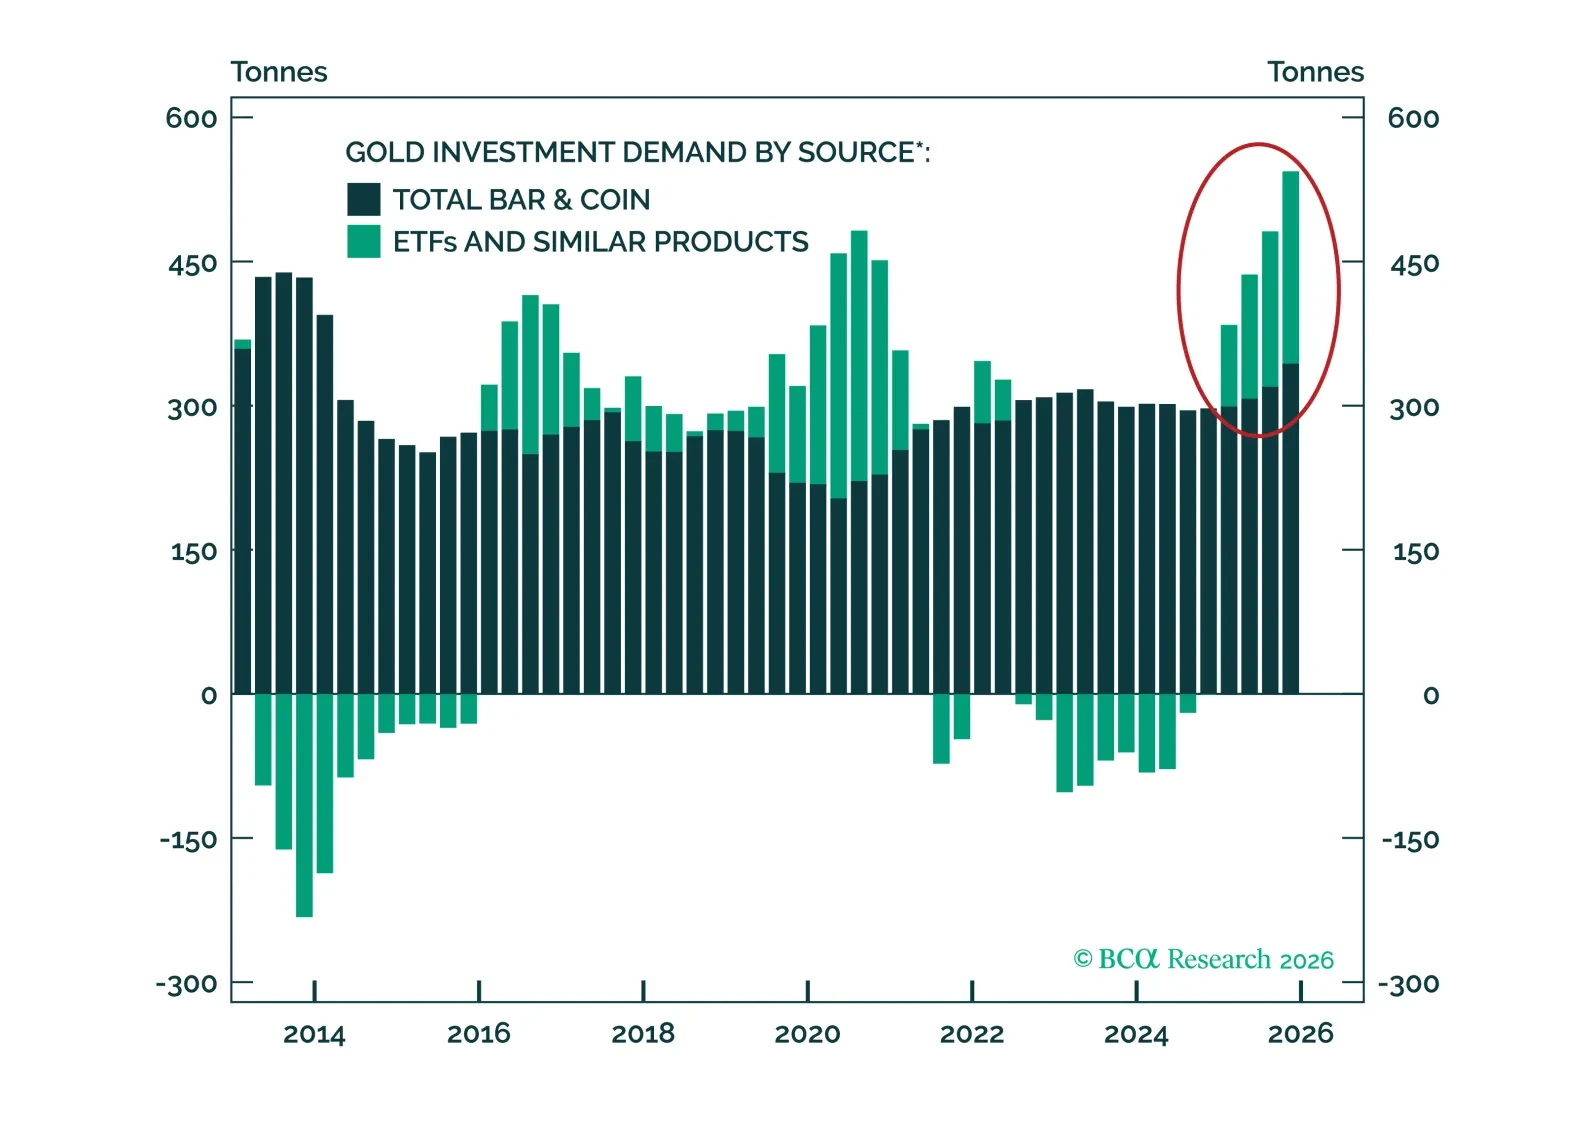
This report flags near-term risks for gold. Yet we remain optimistic about the prospects for its long-term bull market.
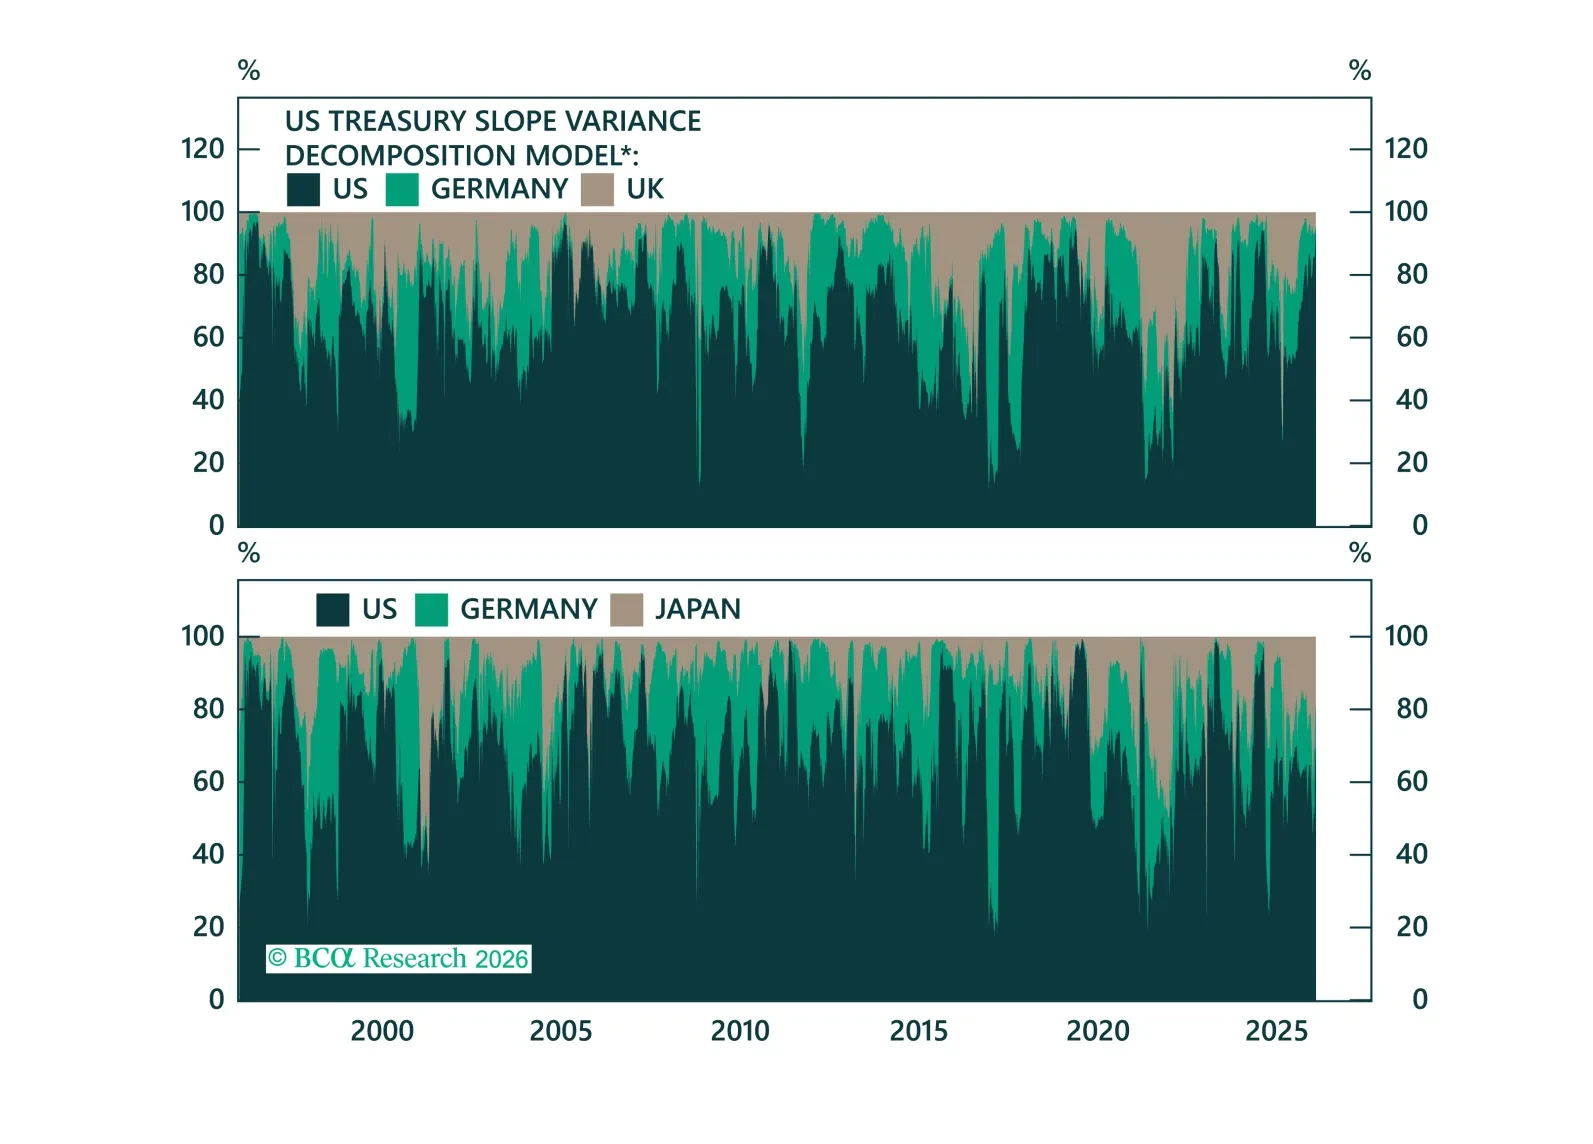
What’s driving government bond yields, and how do different bond markets impact each other? In today's Strategy Insight, we decompose yield moves into global drivers and idiosyncratic local drivers.
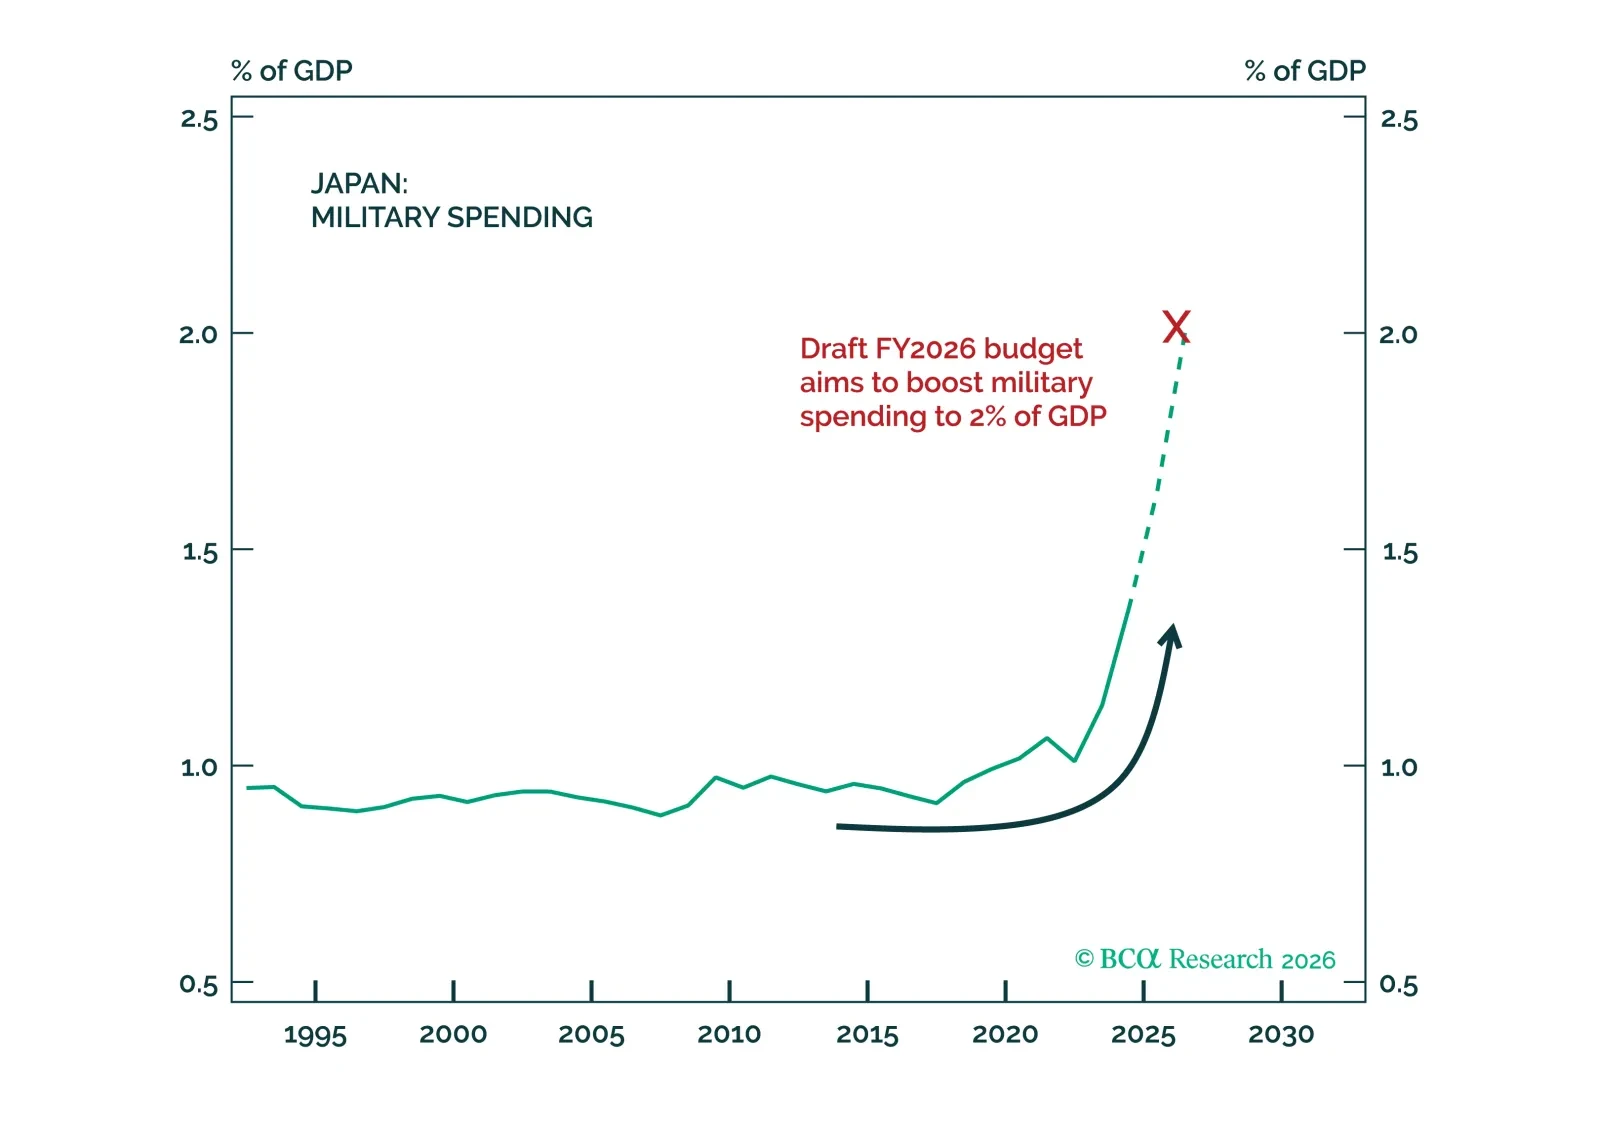
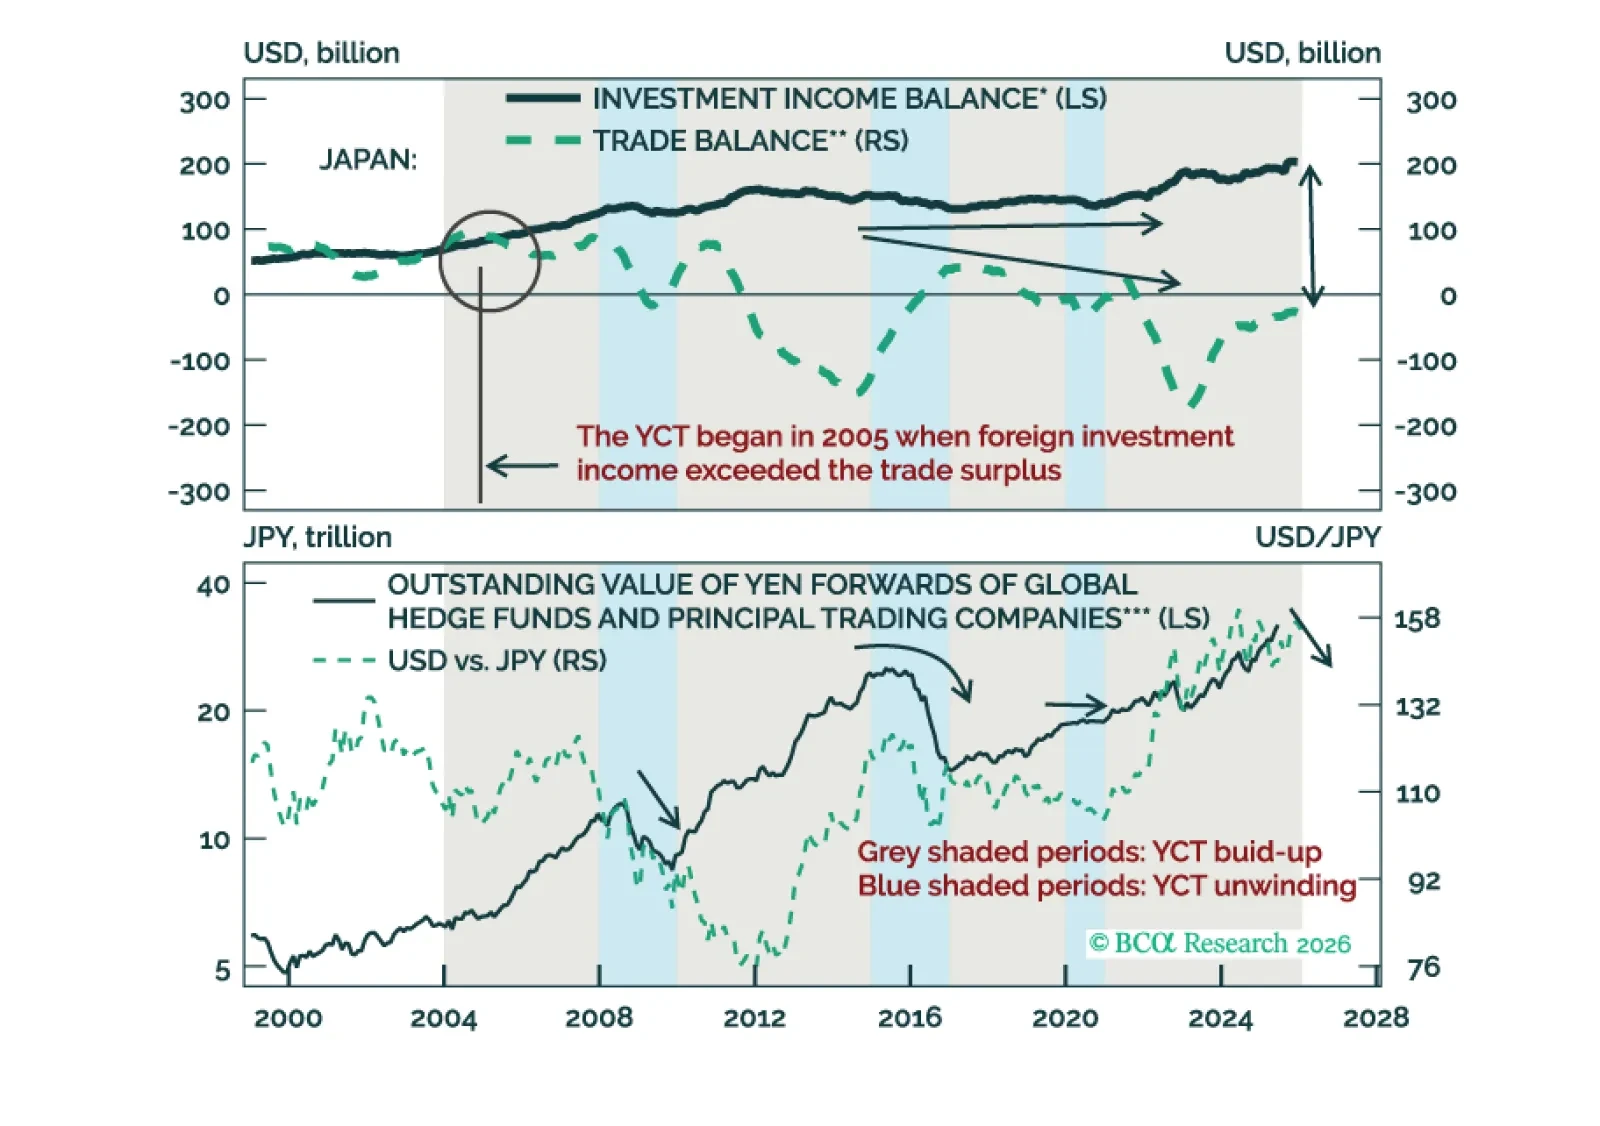
Ignore Japan's constitutional debate. Rearmament will accelerate anyway. Tech, defense stocks, and industrials will benefit. The threat to JGBs is real but will probably be contained.
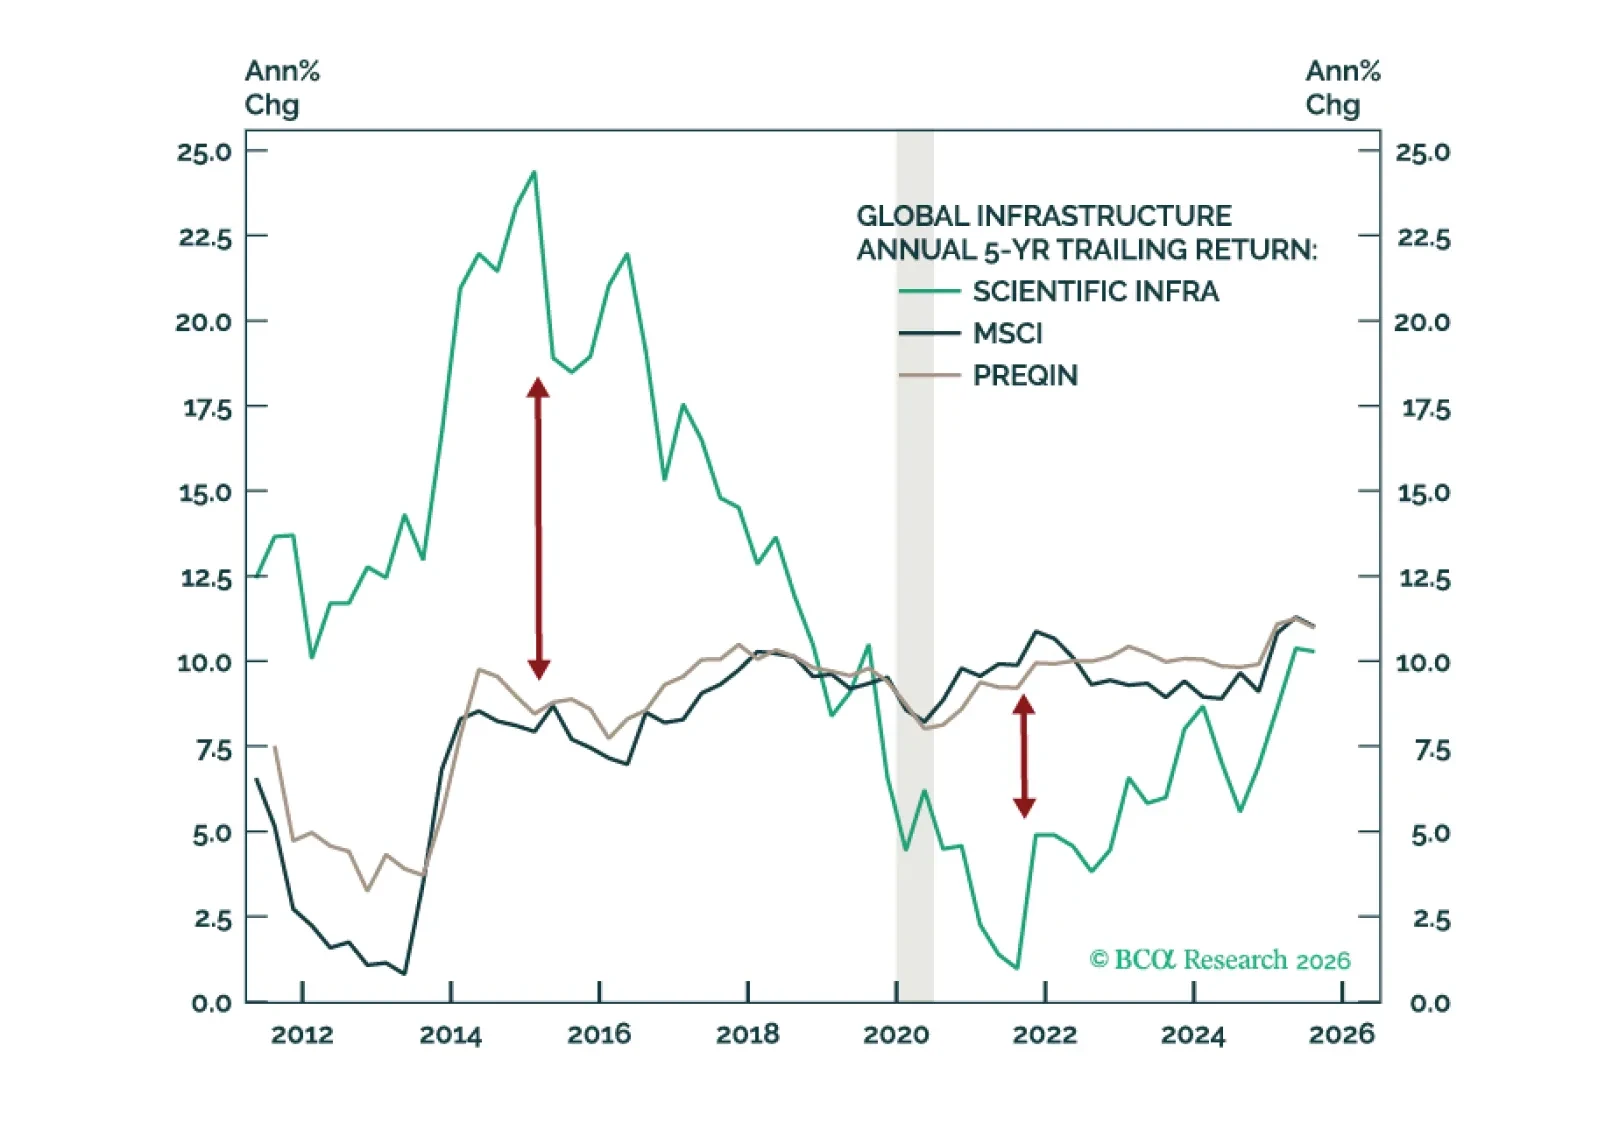
Private Infrastructure is the fastest growing alternative asset class. While metrics vary across data providers, differences largely reflect sector and regional mix. Core Infrastructure inflows have been strong, reversing declines seen in preceding years. Recent returns have been robust, and despite valuation dispersion, levels do not appear stretched.
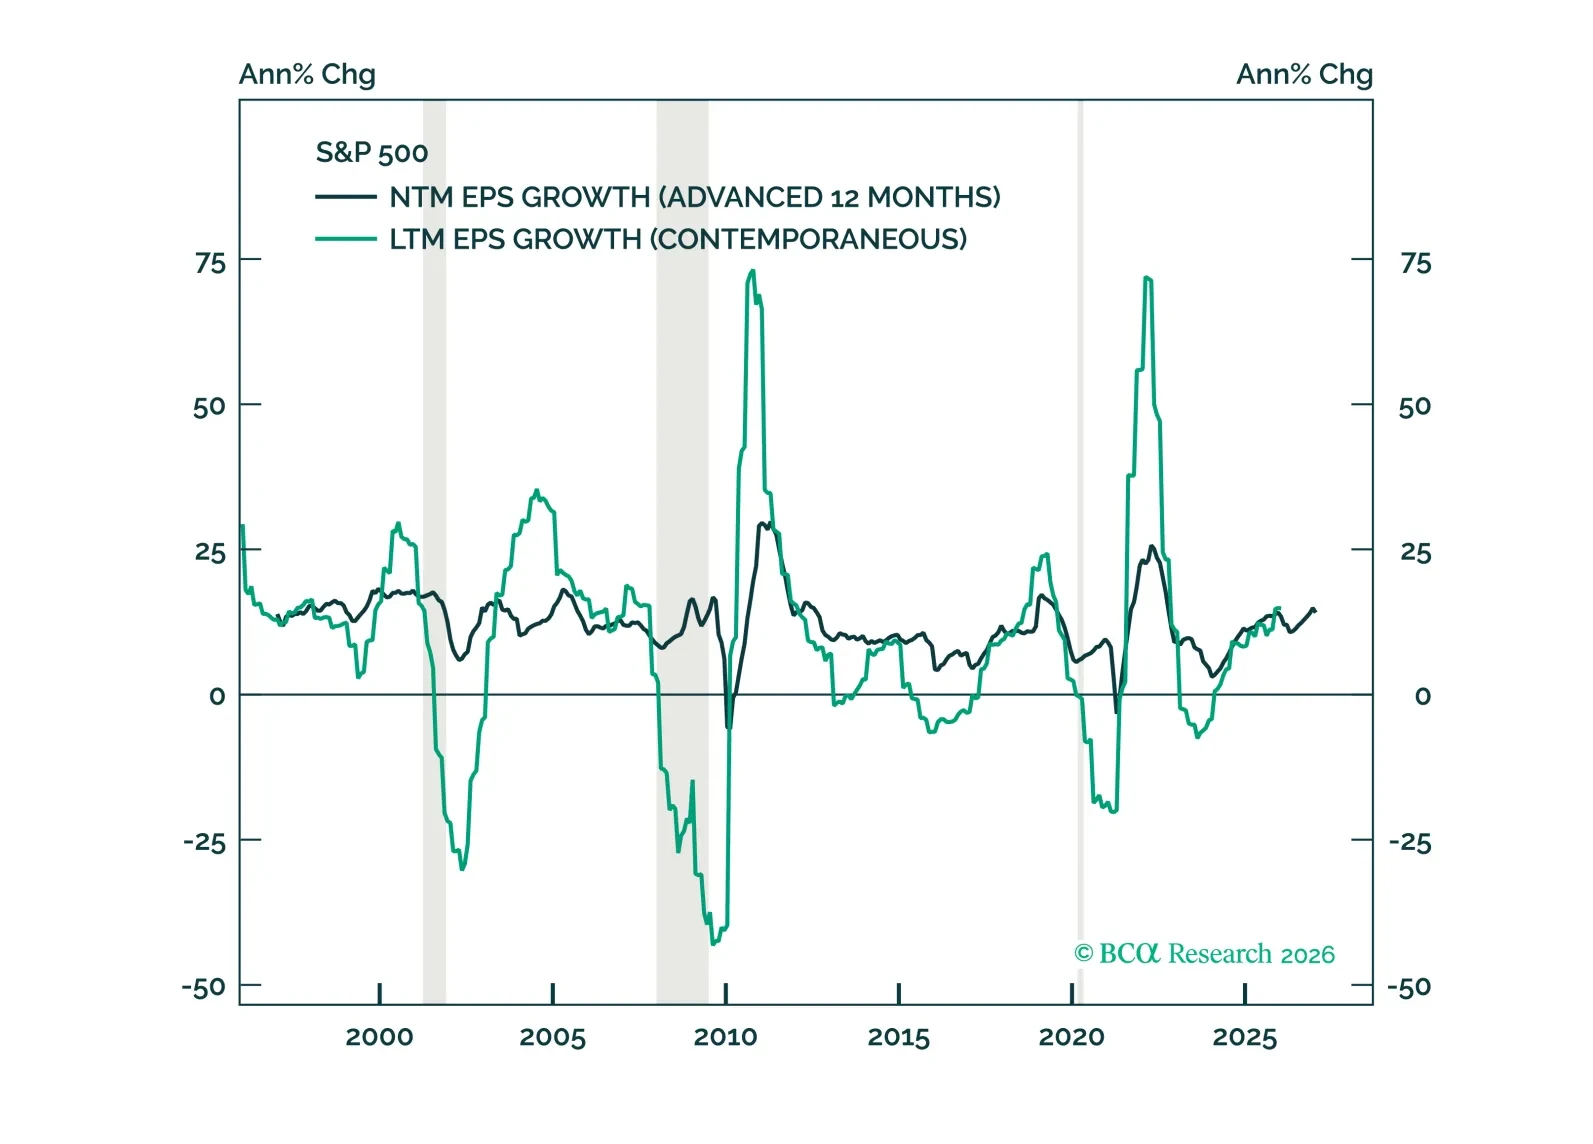
Earnings strength, durability, and breadth are all improving. As the market transitions from multiple-driven to earnings-driven returns, this backdrop supports continued gains in 2026—but with less concentration and greater scope for laggards to catch up rather than leaders to roll over.
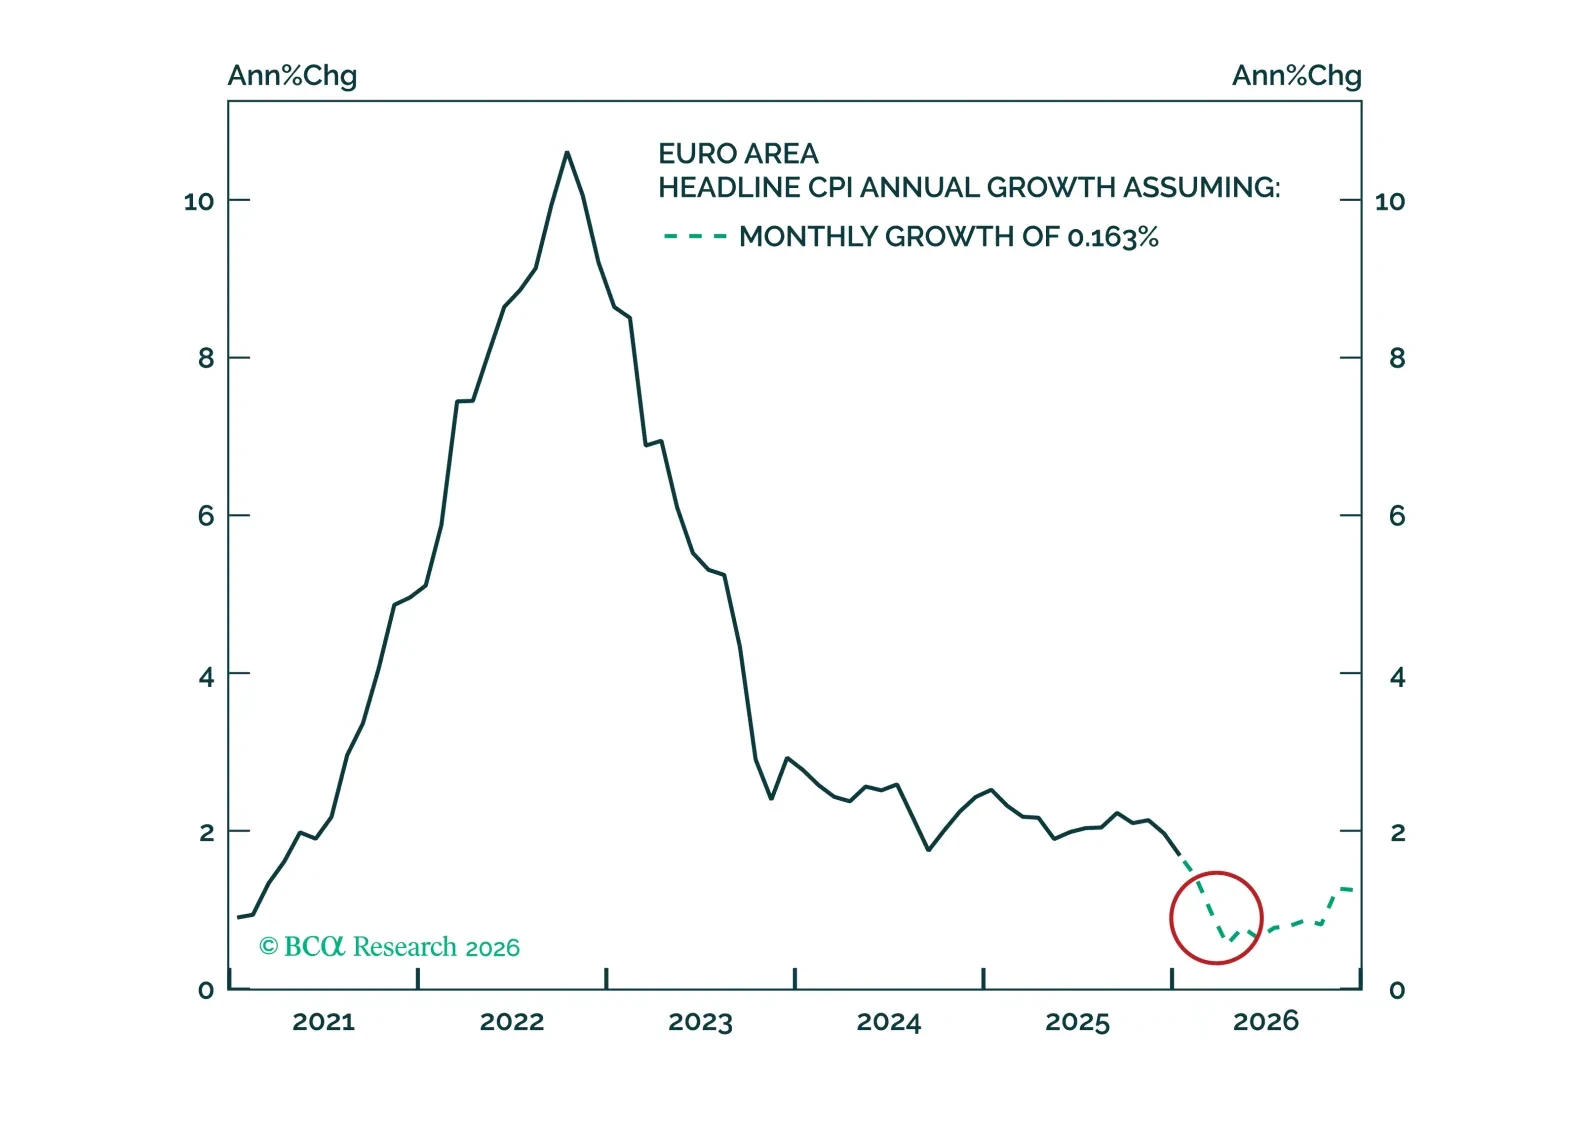
The ECB is about to make its first policy mistake in the current cycle by being complacent about the downside risks to inflation. The confluence of base effects, a stronger euro, food and energy deflation, and rapid services disinflation will push headline inflation closer to 1% in the first half of the year. This significant undershoot will force the ECB to deliver reflationary cuts. Go long the September 2026 3-month Euribor futures and tactically reduce exposure to inflation-linked bonds in the Eurozone.
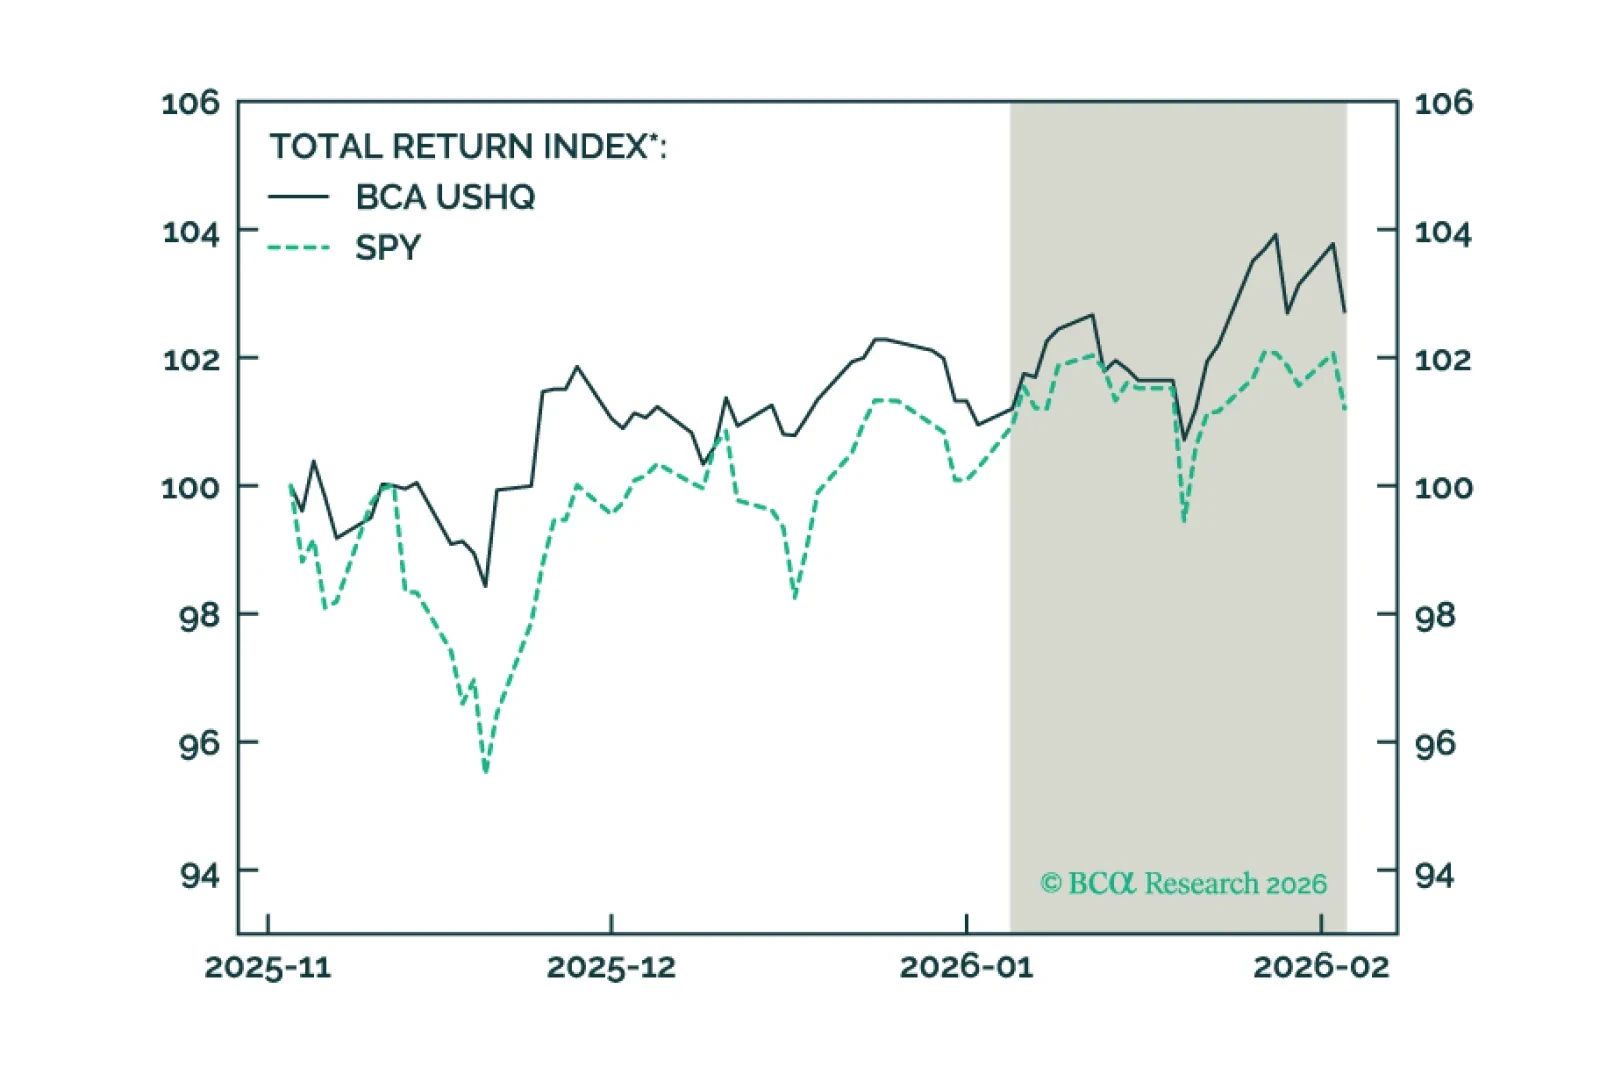
The US High Quality portfolio outperformed its benchmark through January, returning 1.50%, while its SPY benchmark returned 0.26%. On a trailing three-month basis, the USHQ portfolio’s performance was stronger than the benchmark as well, with USHQ outperforming by approx. 152bps.
