Latest from BCA Research
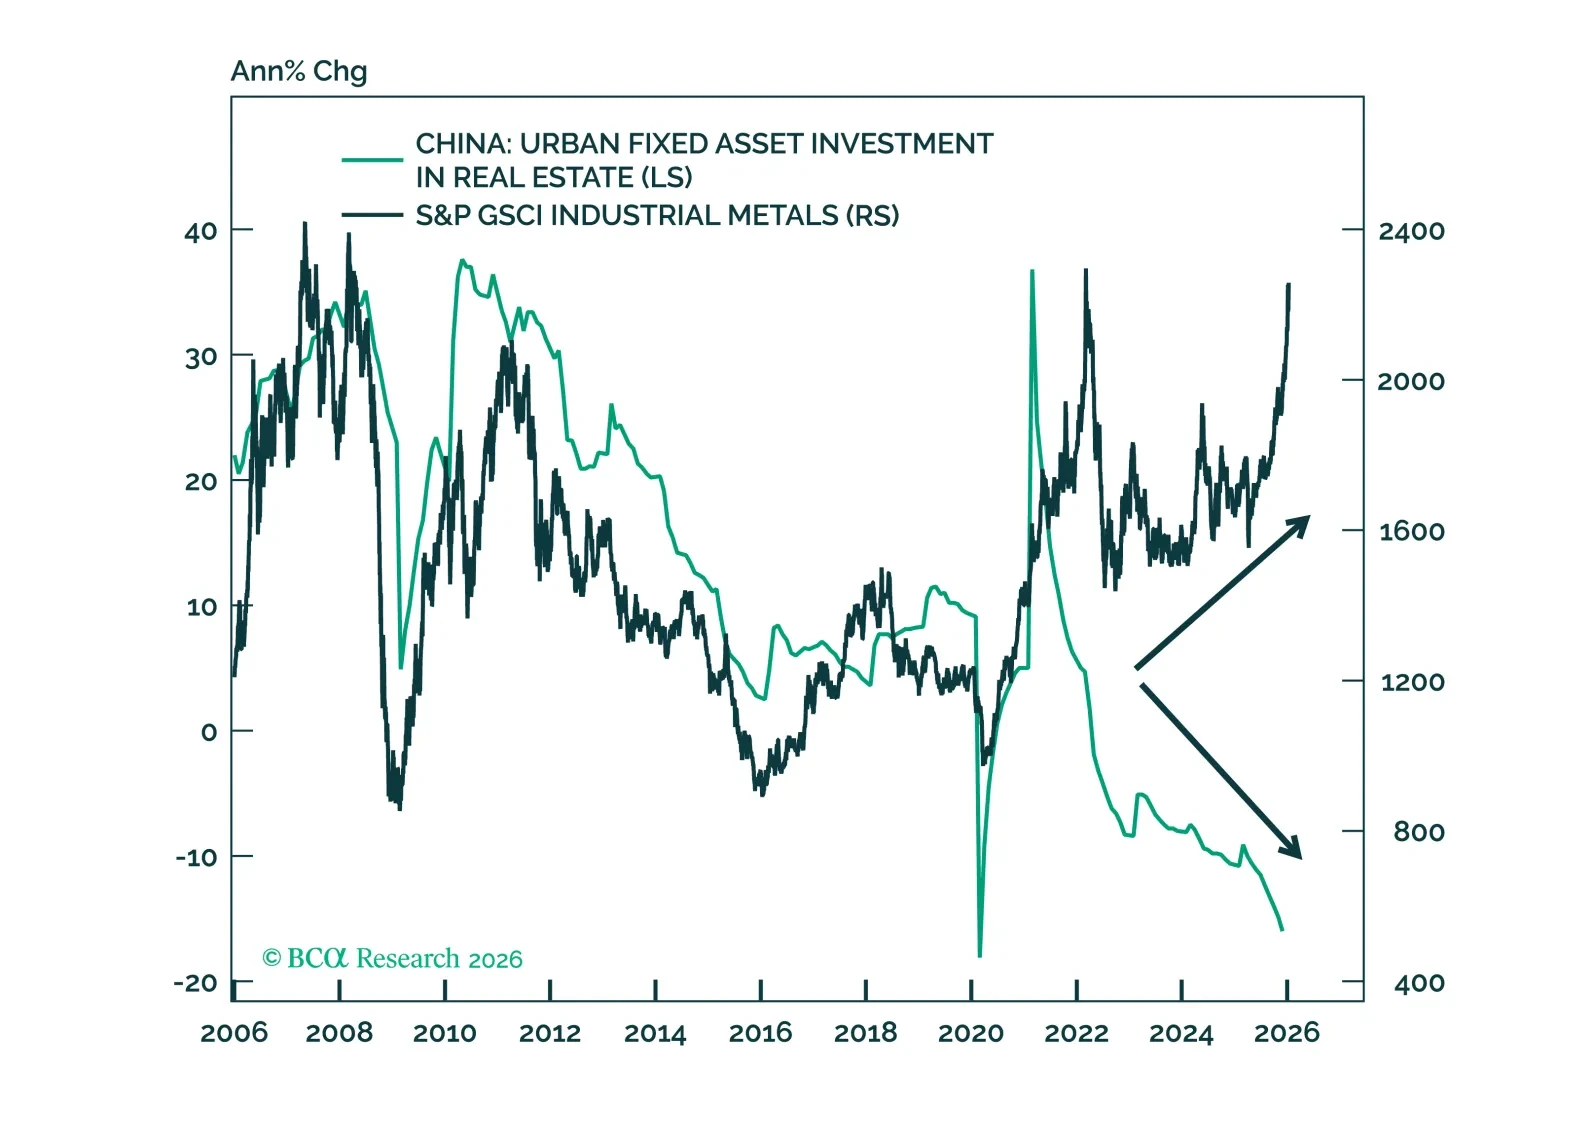
The year 2026 has started off well, with not even the threat to central bank independence denting the market's enthusiasm. Perhaps our tactical caution is misplaced.
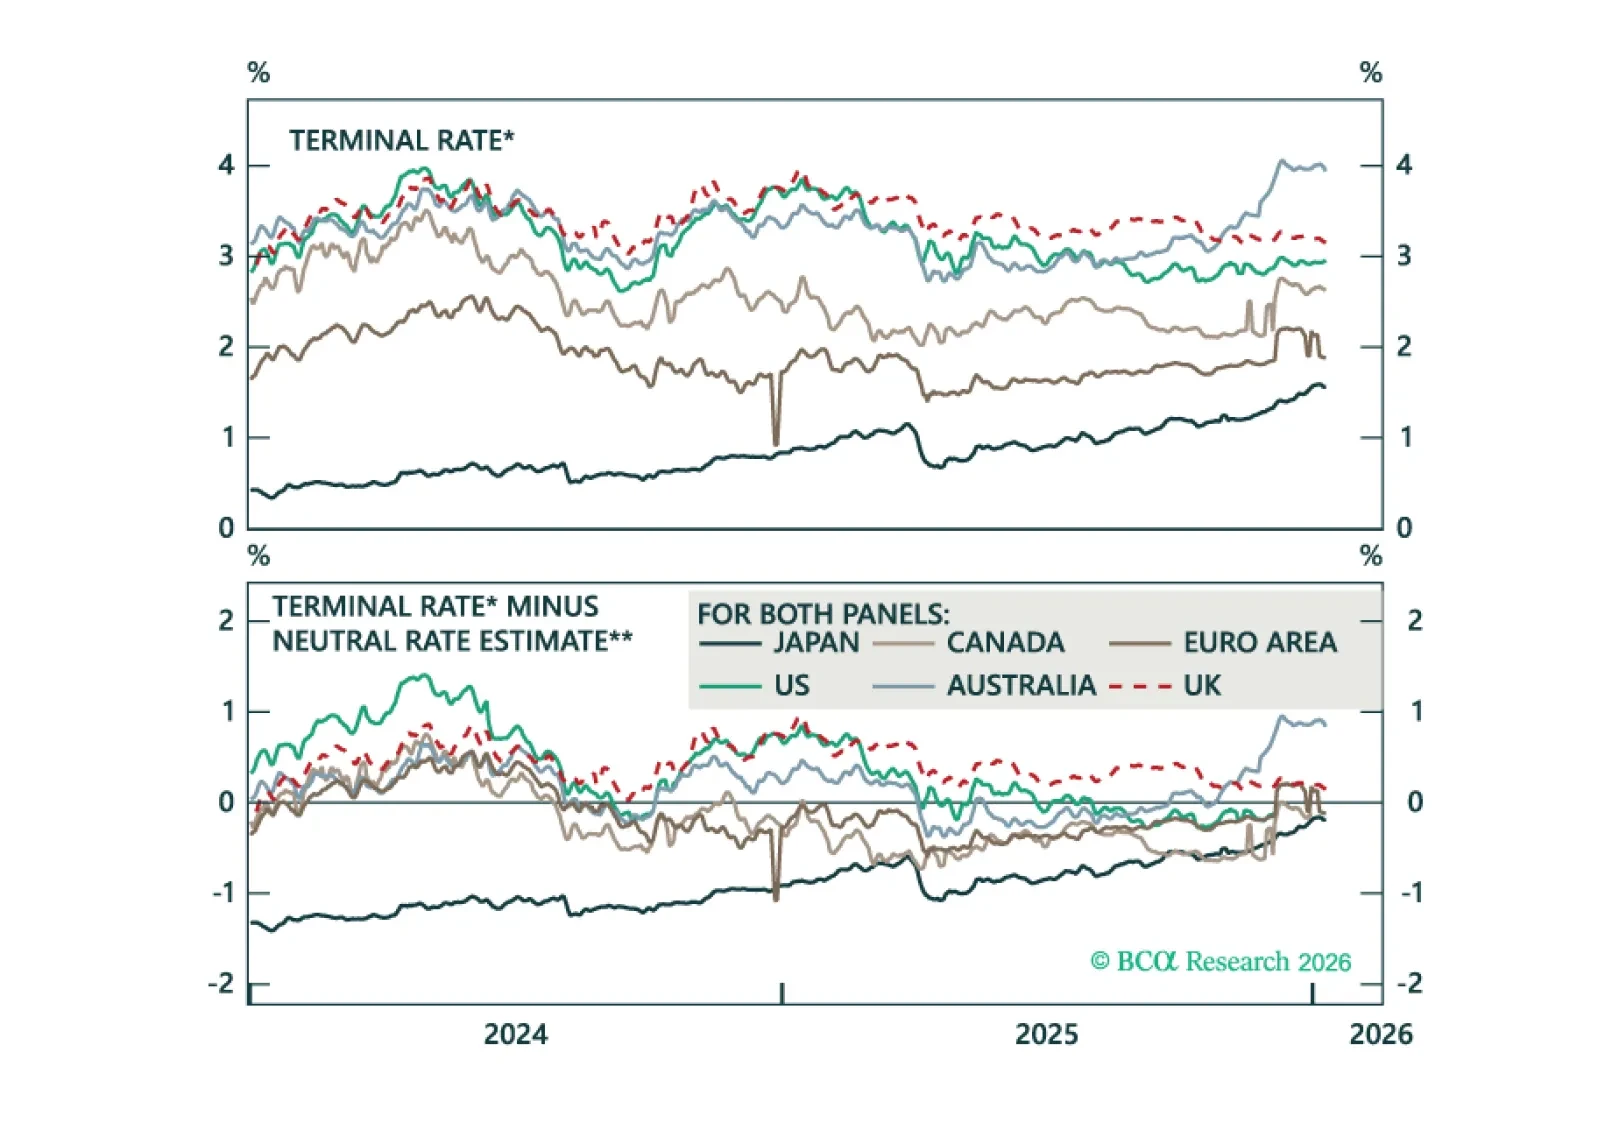
Our Q1 outlook maps global growth, curve dynamics, and policy surprises, which we then translate to our recommended global fixed income portfolio allocations and trades.
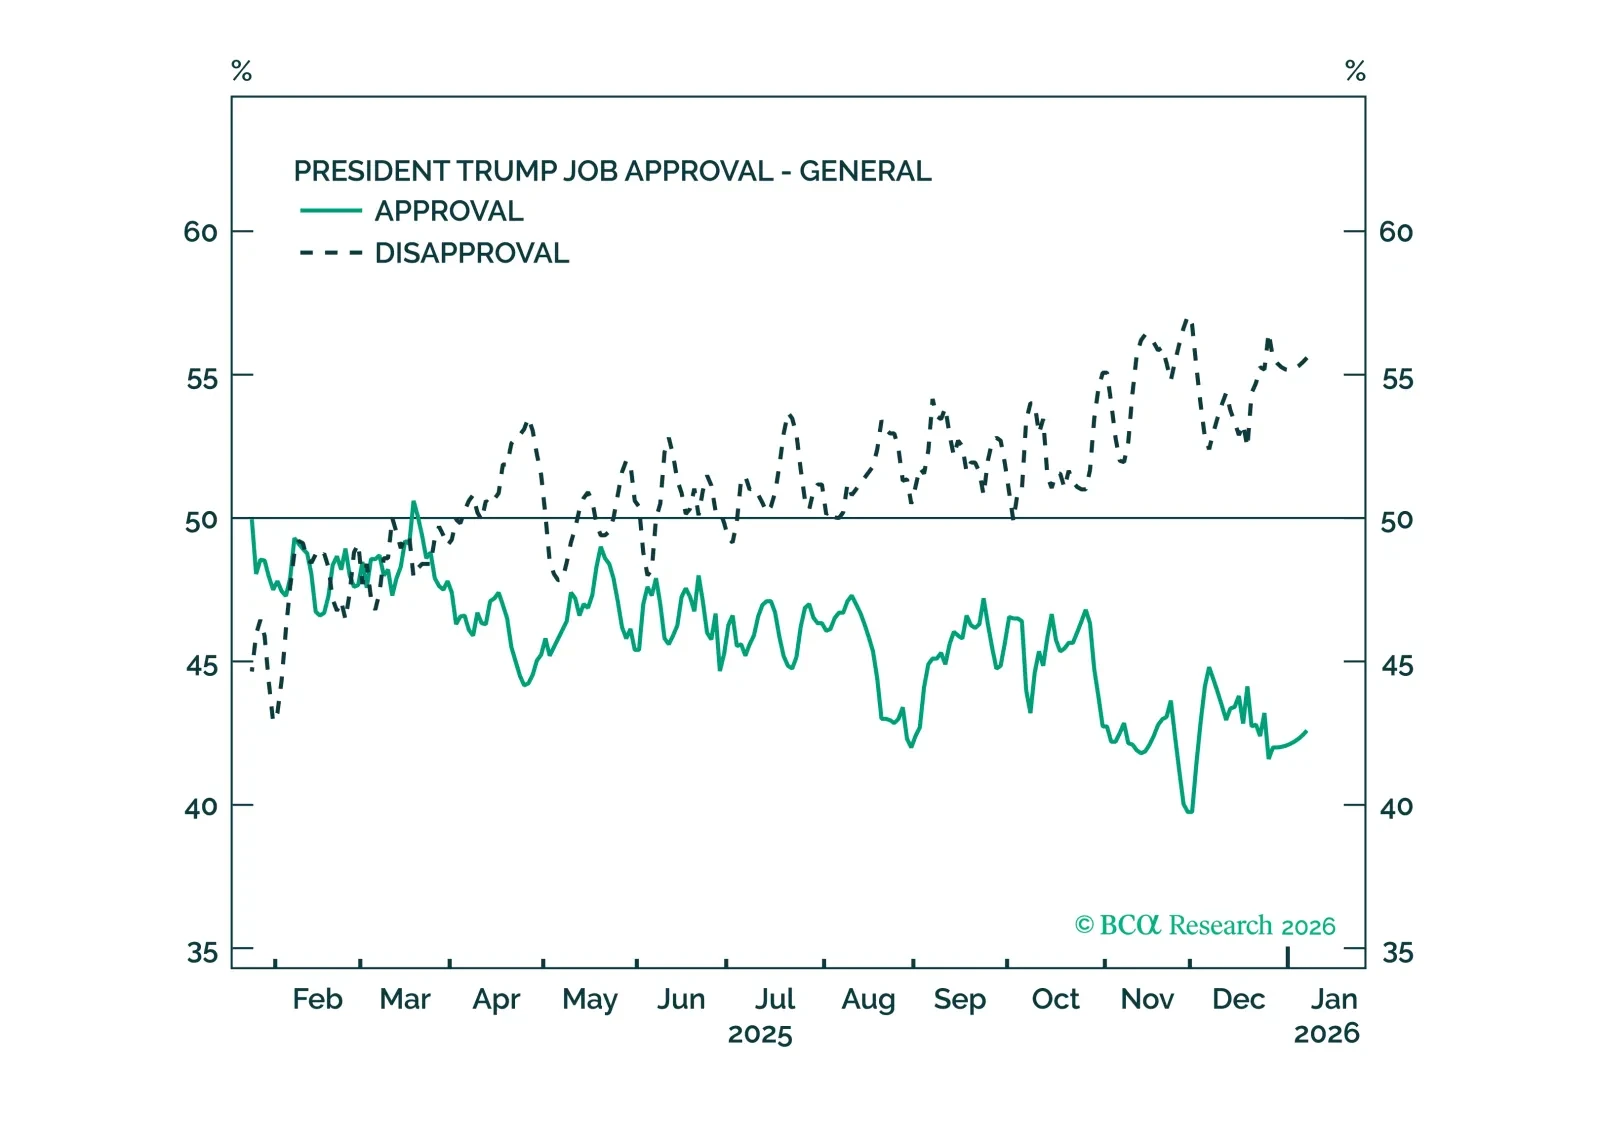
Congress will ultimately limit Trump from acting on his worst impulses, but his efforts to bypass those limits will cause market volatility.
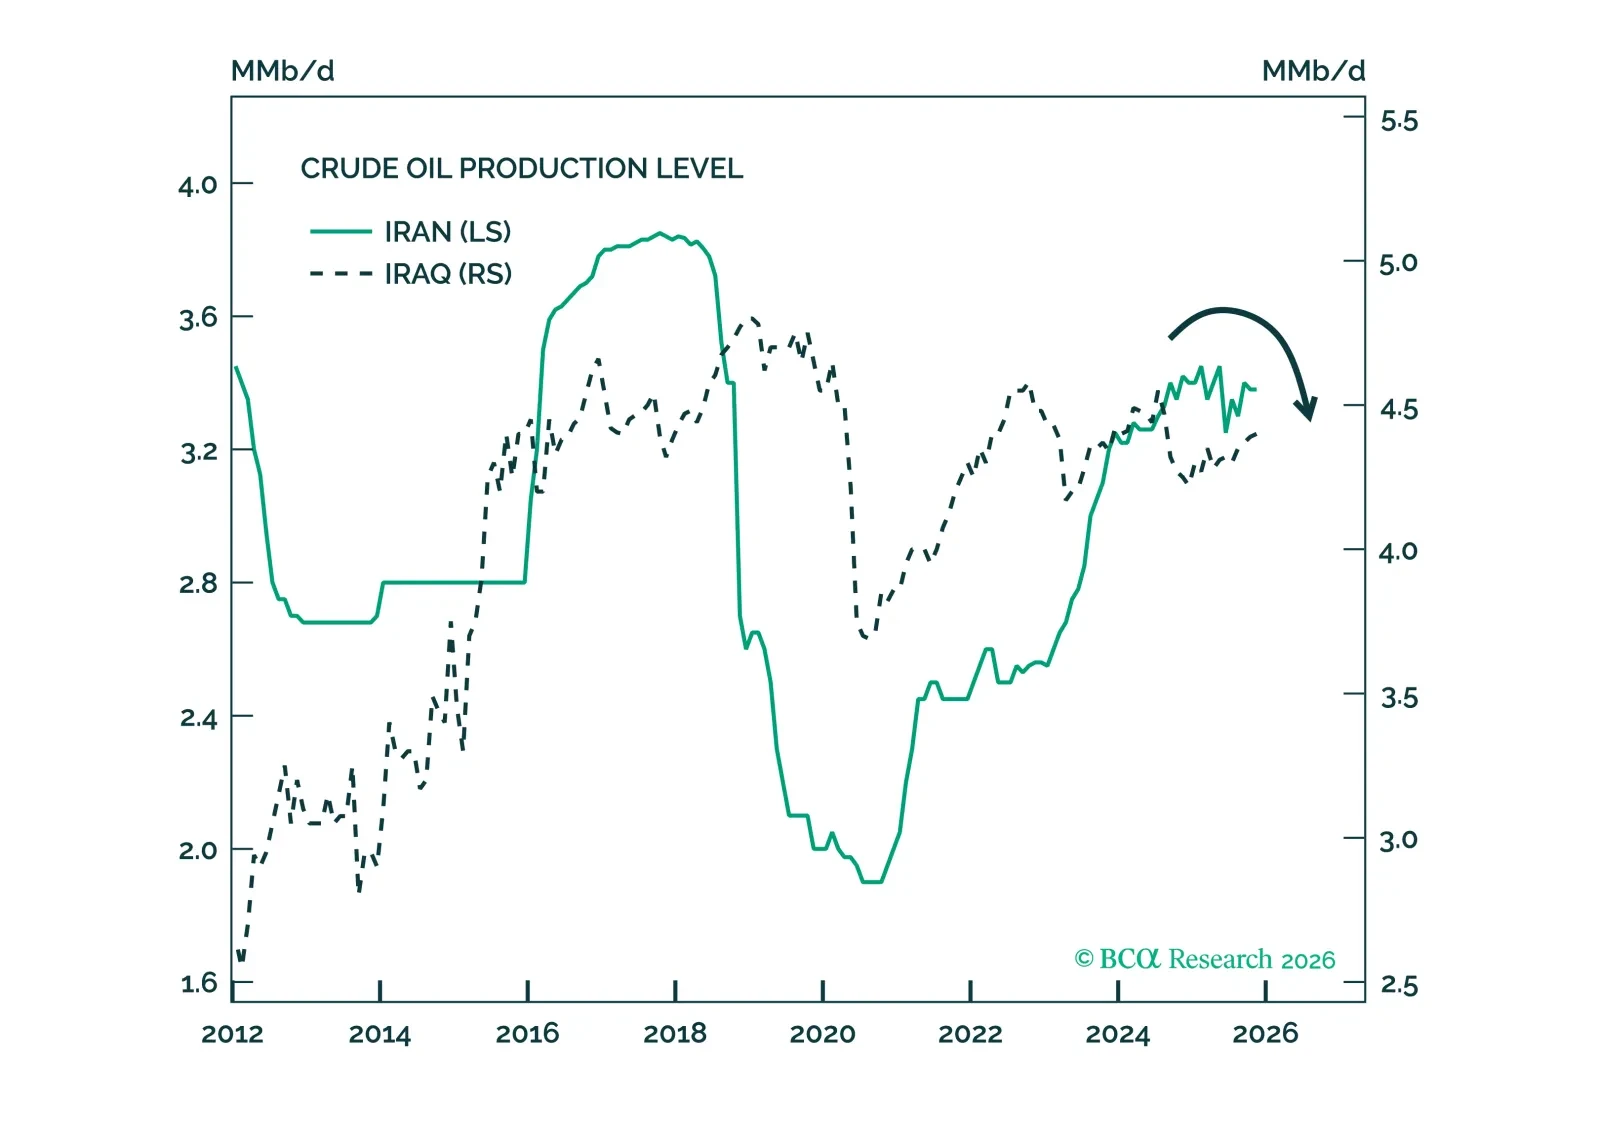
The risk to Iran's regime survival raises the probability of a massive global oil supply shock back to around 40%, where we put it last year.

Measures of labor market utilization improved in December, ruling out a January cut and significantly reducing the odds of a March cut.
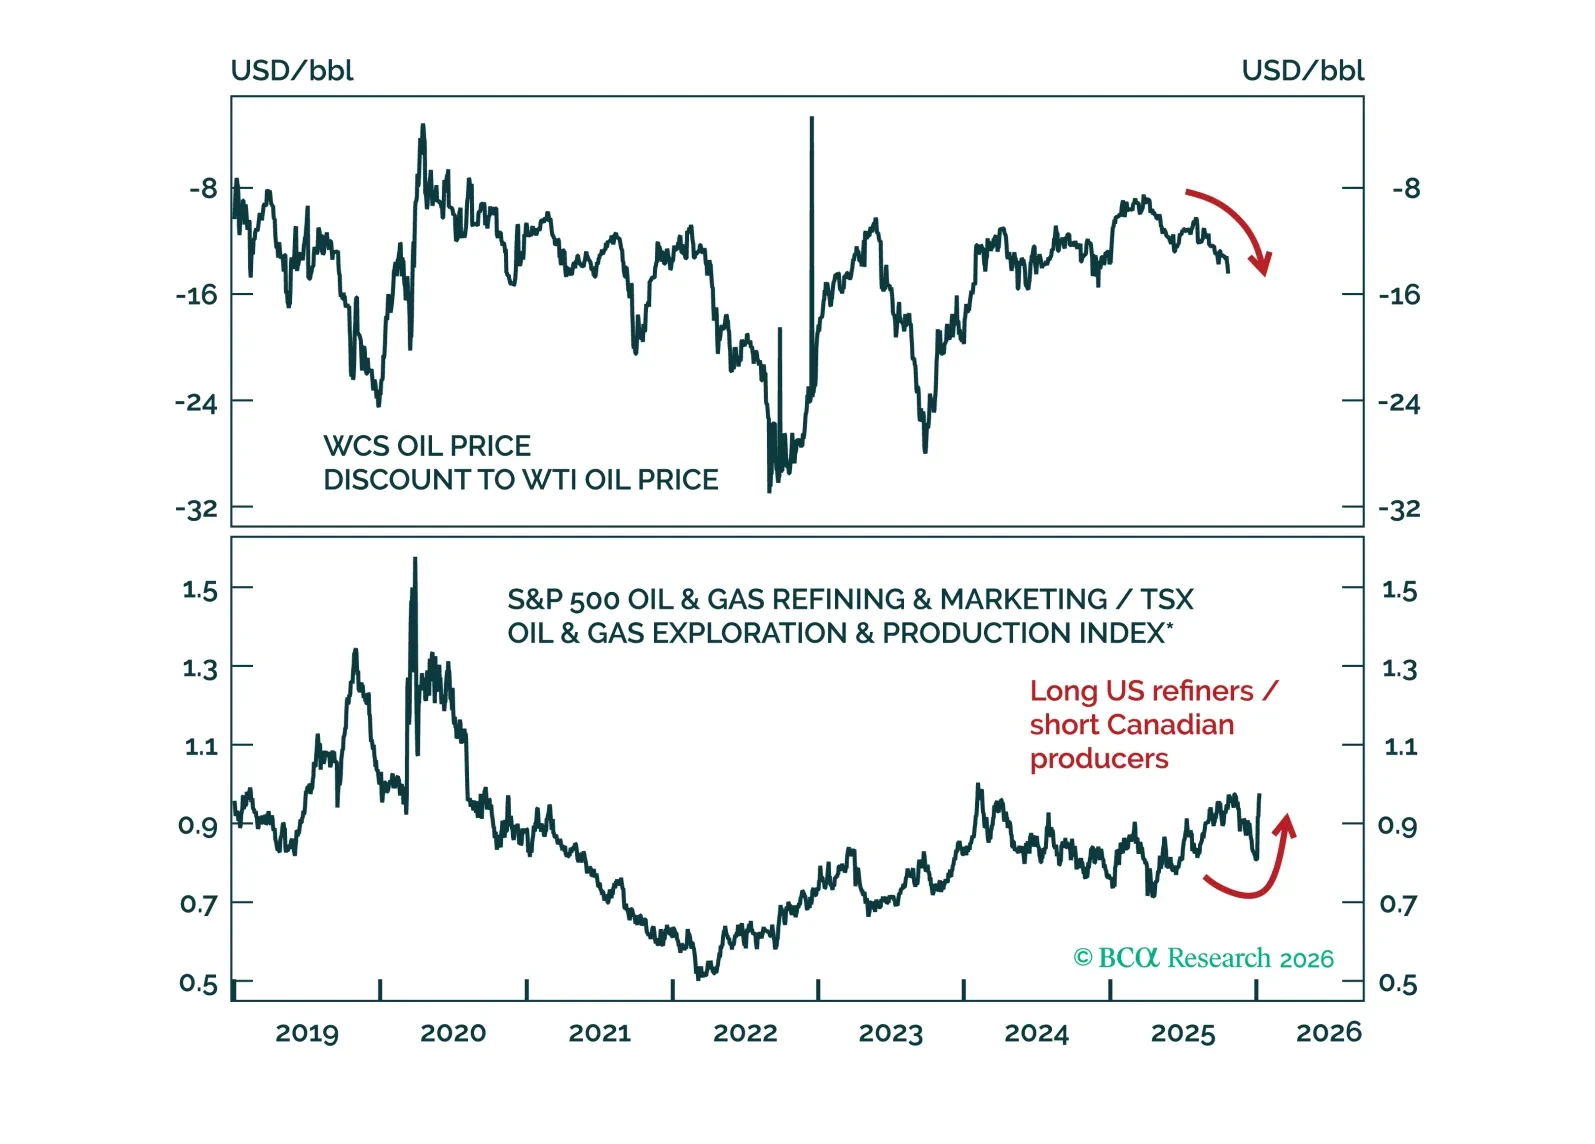
Venezuelan crude output is unlikely to alter the global oil market outlook for this year. However, US control of Venezuelan crude is a risk to Canadian oil sands producers and Canadian oil prices. Go long US oil refiners/short Canadian oil producers.
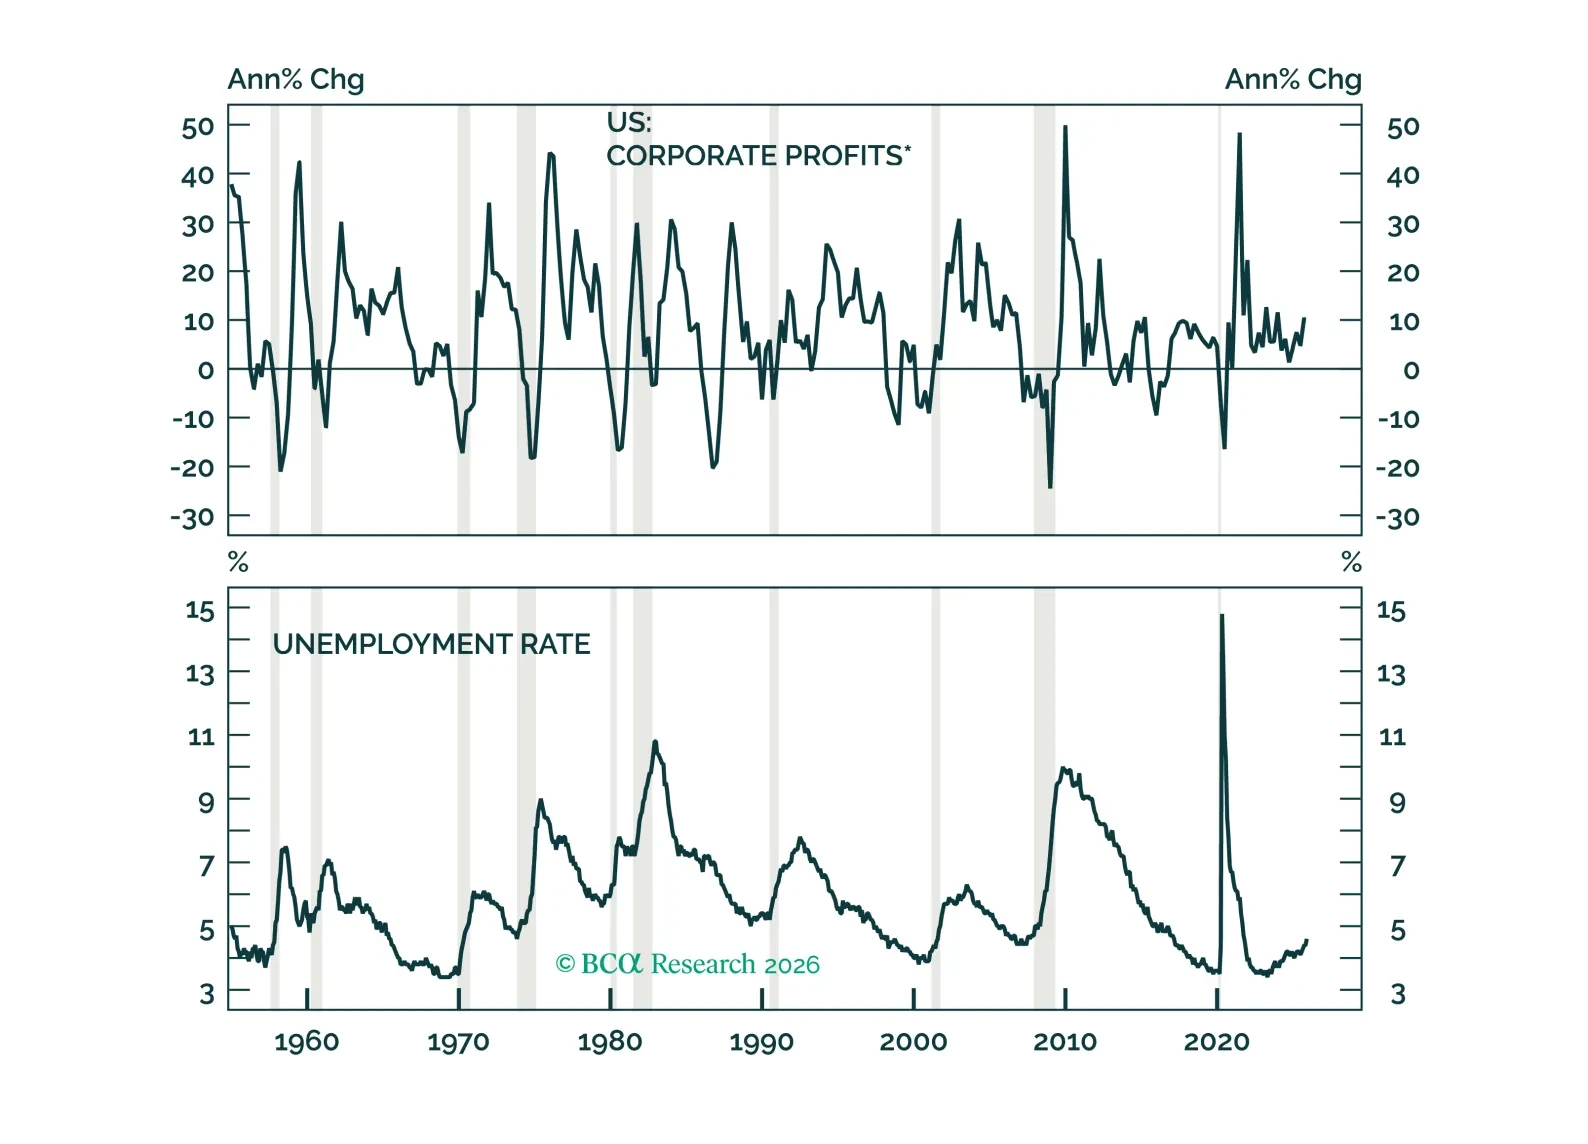
To start 2026, we answer what we believe are the most important questions facing investors surrounding the labor market, monetary and fiscal policy, and AI stocks. Overall, we reiterate our overweight views on risk assets and highlight the risks surrounding the upcoming tariff decision.
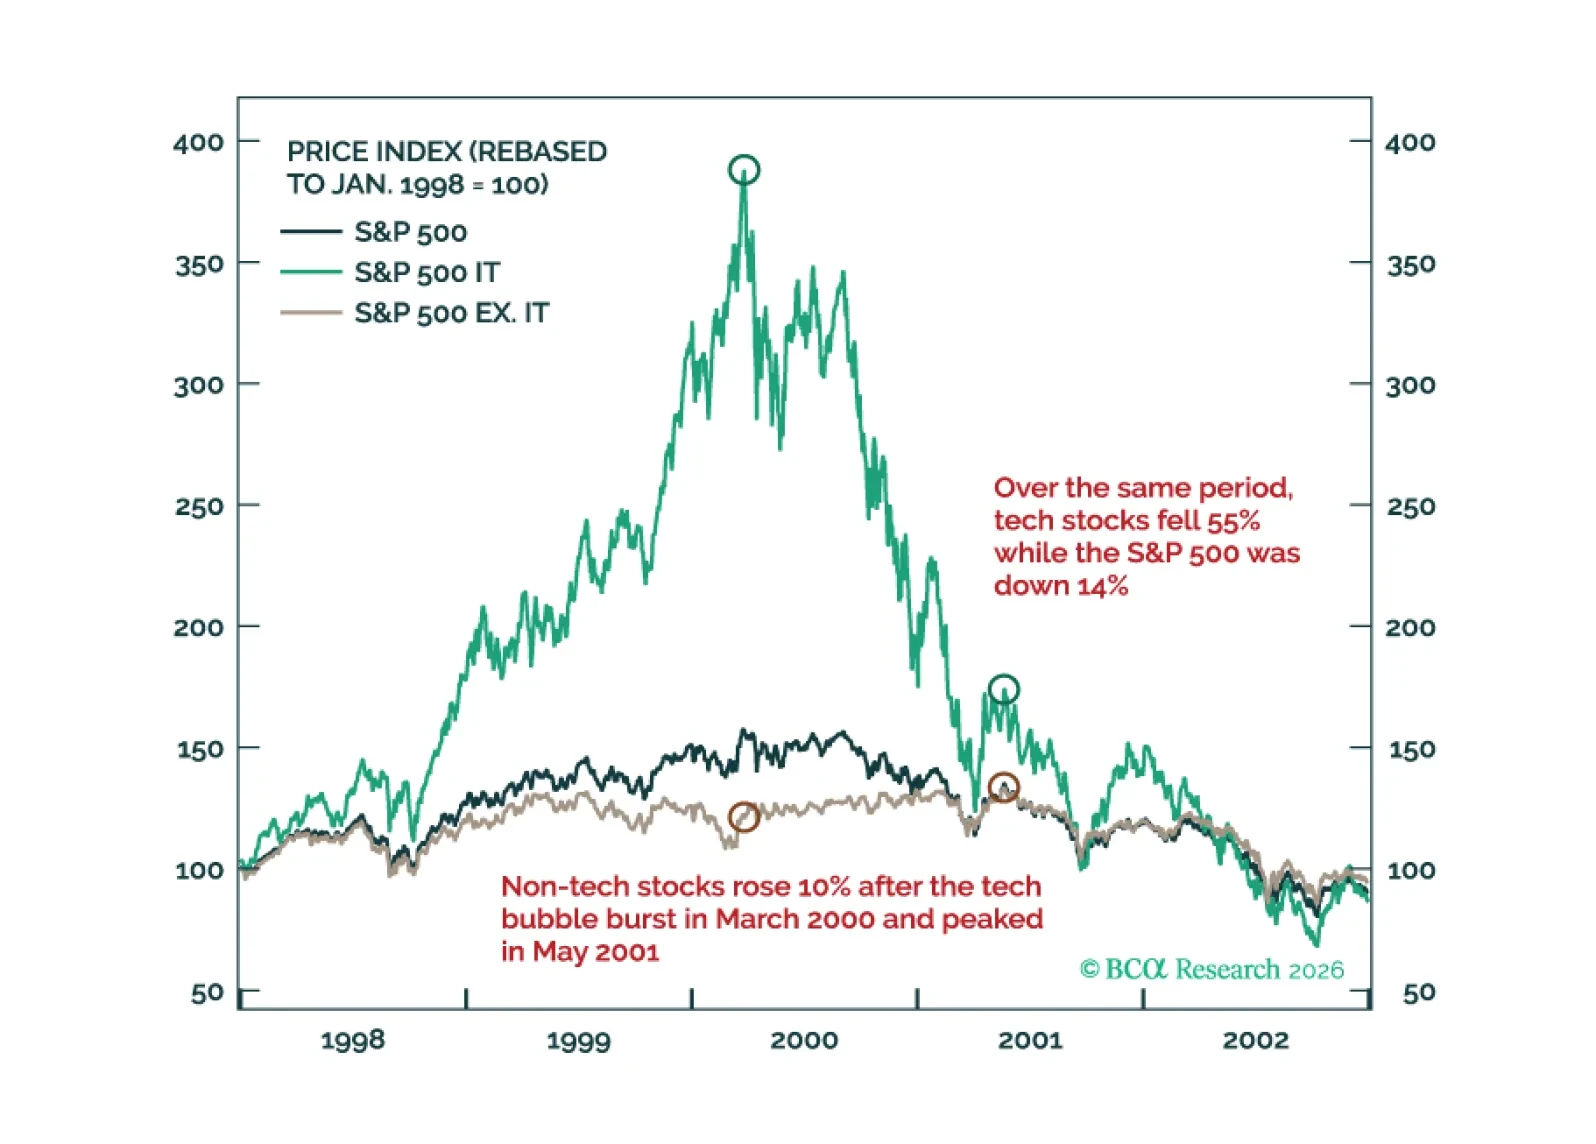
Much like the 2000 episode, we expect this year to unfold in two stages: A “Great Rotation” from tech stocks to non-tech names in the first half of 2026 followed by a broad-based selloff in stocks in the second half on the back of a weakening US economy.
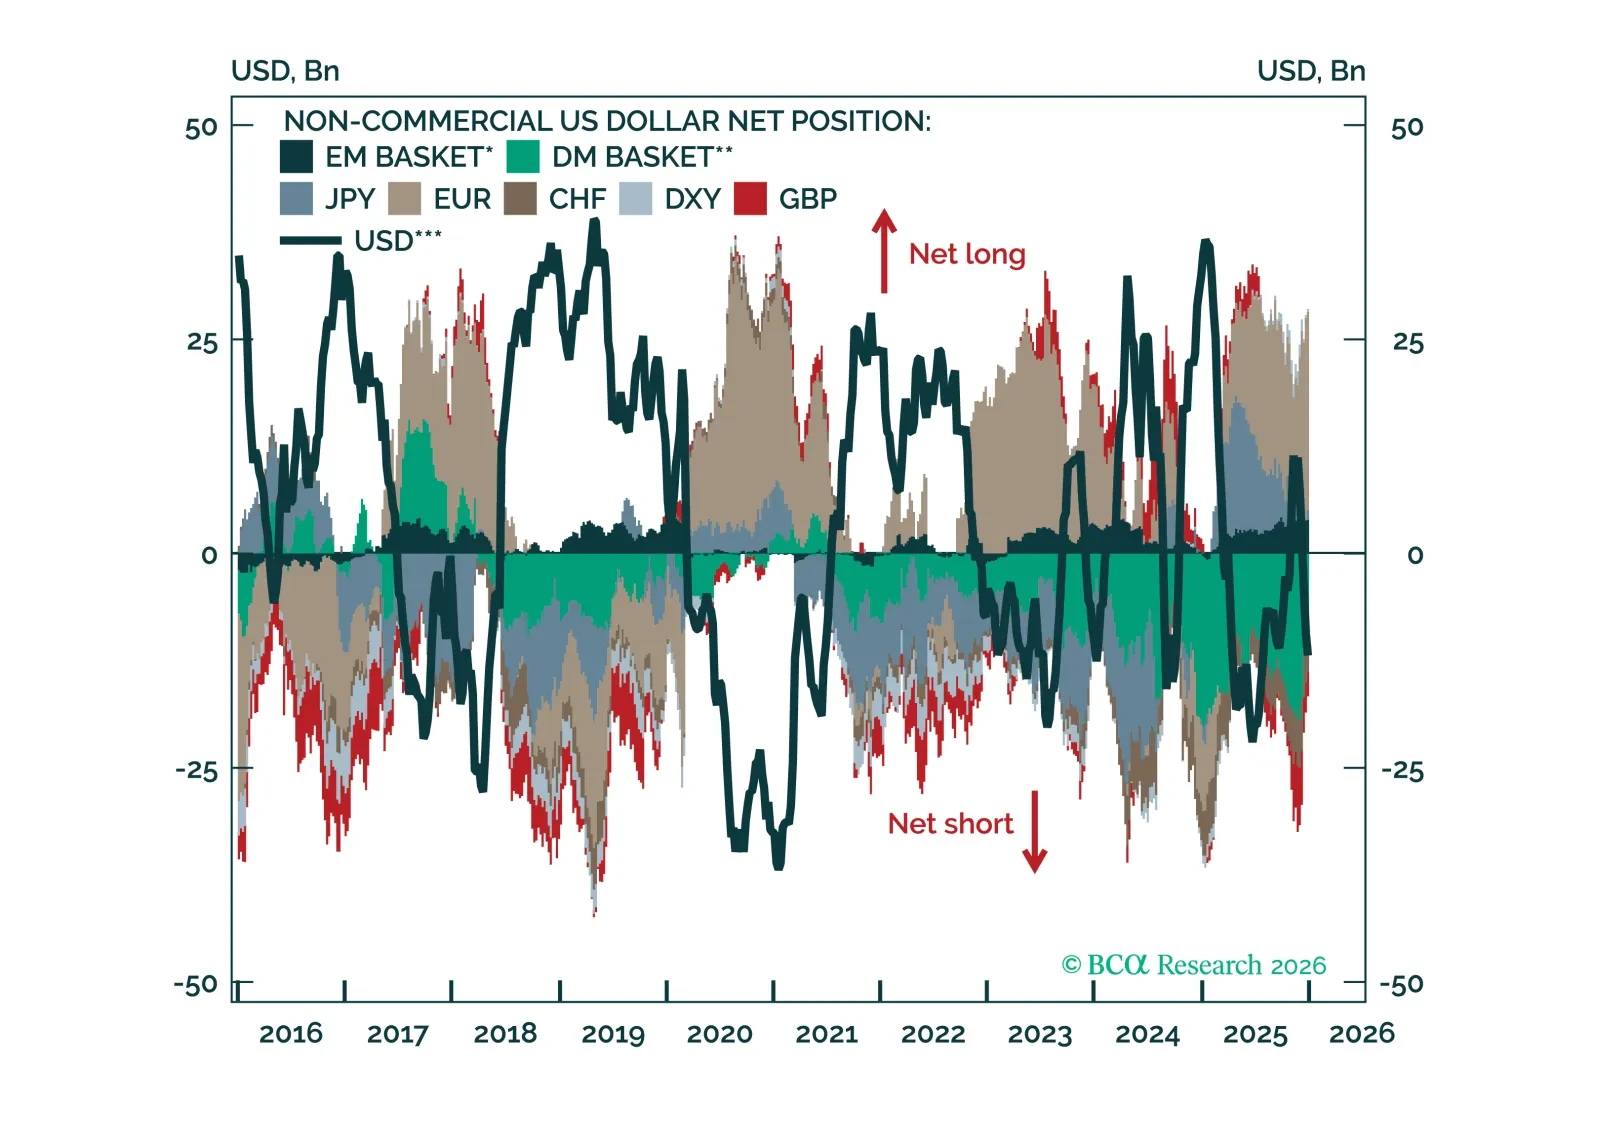
With FX volatility near cycle lows, this Insight examines where positioning has become most stretched across G10, EM FX, and precious metals – and what that implies for near-term moves and reversal risks.
