
Skip to main content

Economy

According to BCA Research’s US Bond Strategy service, Treasury curve steepeners will pay off handsomely once the next recession hits. However, curve flatteners (aka barbelled Treasury portfolios) offer better value for the near term. A barbelled Treasury…
China’s CPI and PPI releases delivered a negative signal about the domestic economy. The rate of contraction in the CPI index accelerated to -0.5% y/y in November, the sharpest rate of decline in 3 years and disappointing expectations it would remain at -0.2%…
Results of the New York Fed’s November Survey of Consumer Expectations corroborate the signal from the University of Michigan’s preliminary results that inflation expectations are receding. The 0.2 percentage point drop in one-year ahead inflation…
Multiple major DM central banks are scheduled to decide on monetary policy this week. The US Fed will meet on Wednesday, followed by the ECB, BoE, and Norges Bank on Thursday. It comes after the BoC and RBA both opted to keep rates unchanged last week. With…
The gold/silver ratio (GSR) confirmed the improvement in global risk sentiment in November. It declined on the back of a 9.2% rally in silver, which outpaced the 1.9% rise in gold. Since then, the GSR has soared amid a more pronounced drop in the price of…
According to BCA Research’s European Investment Strategy service, European equities near cycle highs are vulnerable to weaker earnings. The team’s earnings model for Eurozone equities continues to point to a double-digit profit contraction over the next nine…
Special Report

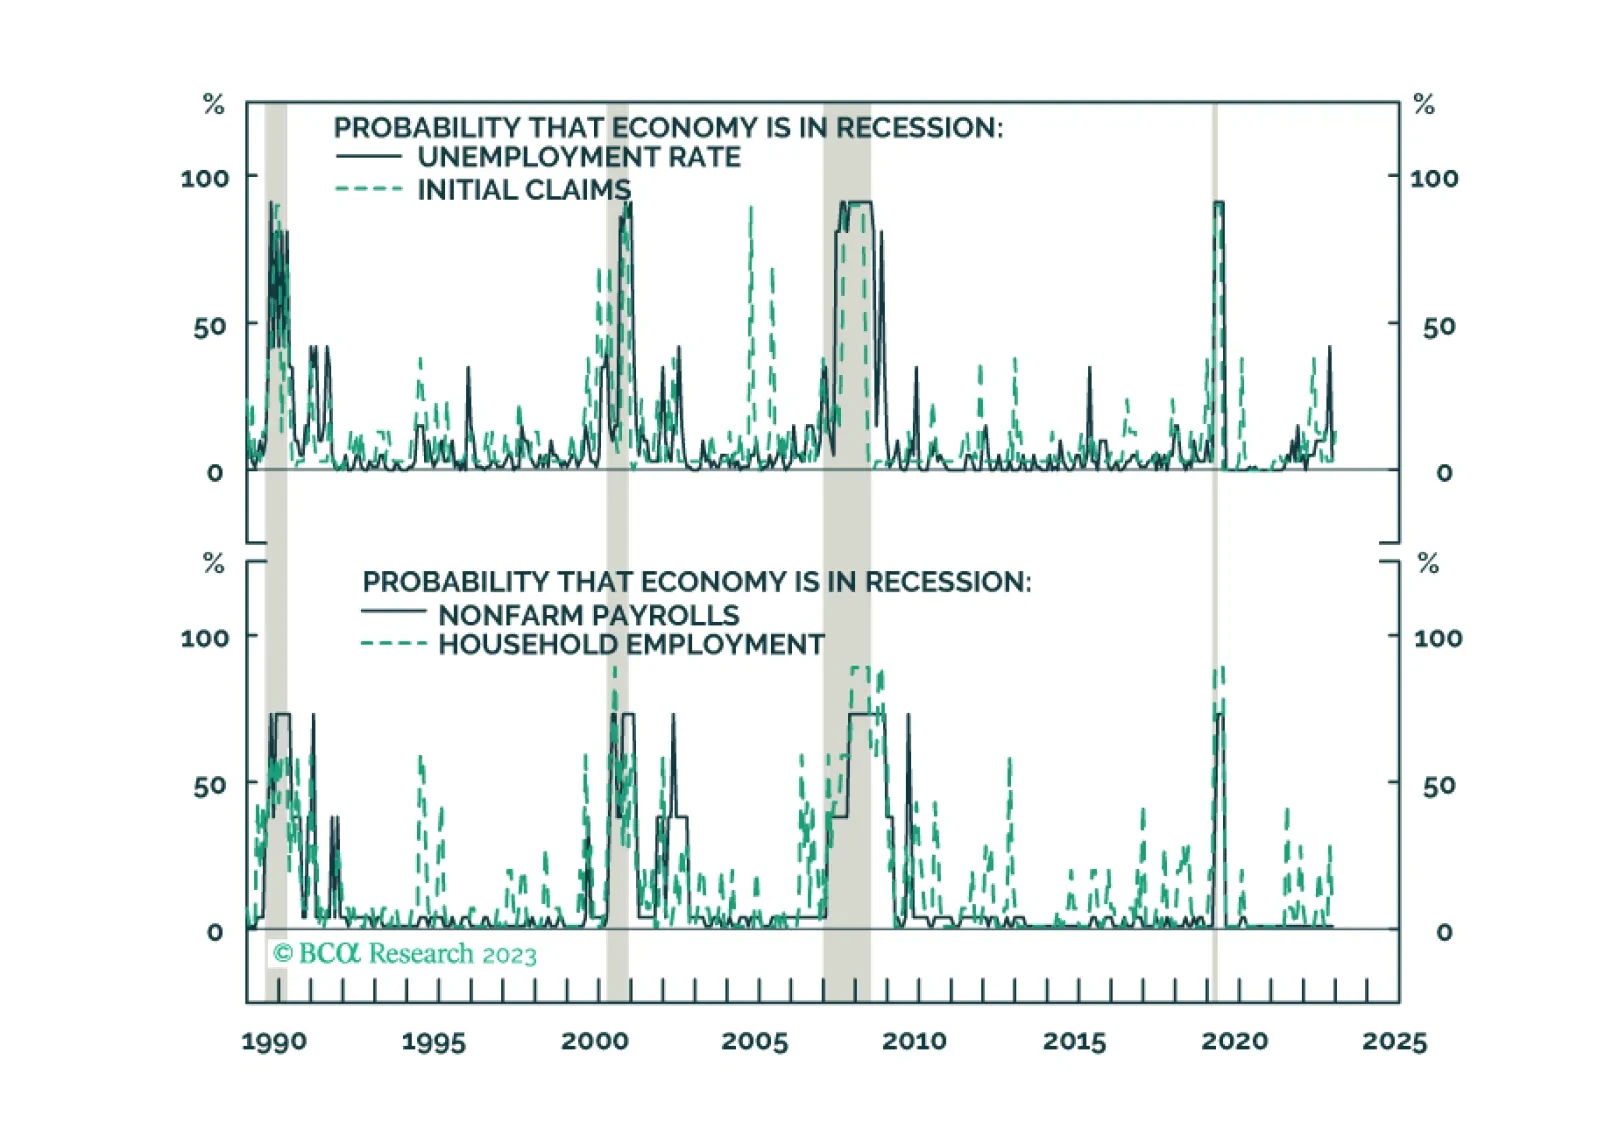
Our US fixed income team’s key investment views for 2024.
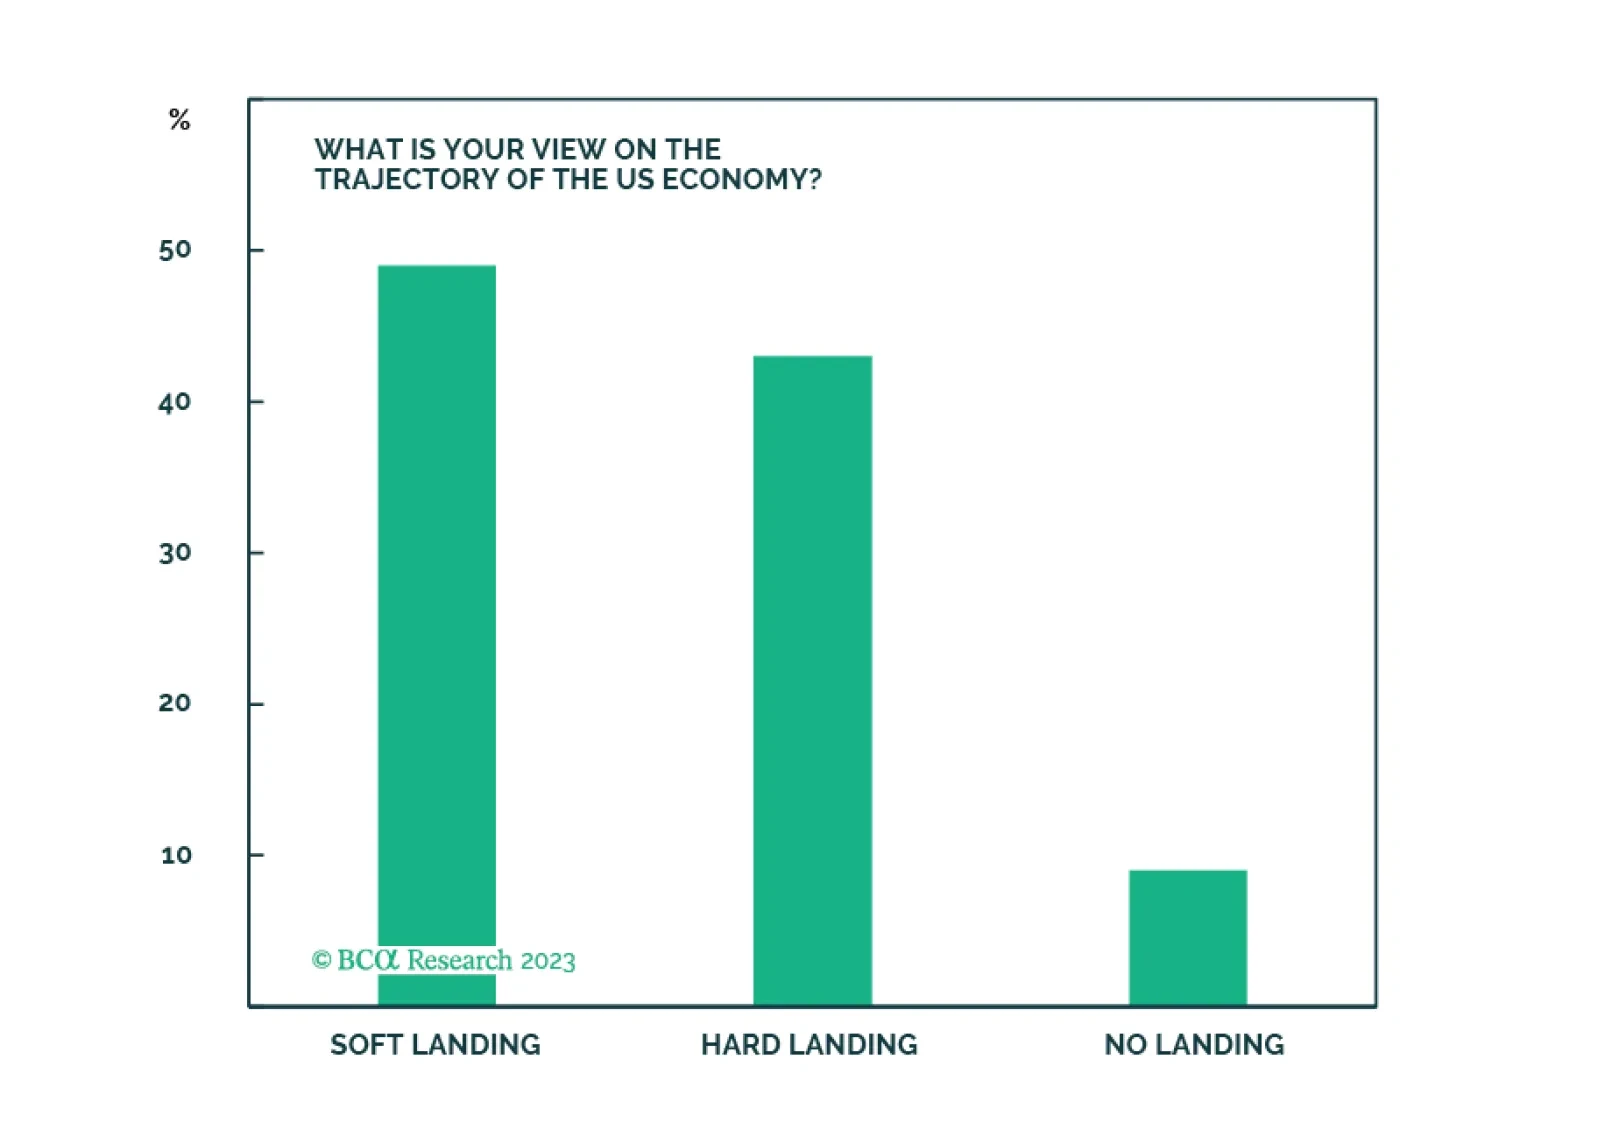
The Santa Claus rally is a repricing of the "soft landing" scenario as a likely economic outcome. Yet, many investors remain cautious, and harbor significant cash balances. Next year, repricing of various scenarios will continue, and volatility will be elevated. We remain in a "hard landing" camp and recommend defensive stance on a strategic investment horizon.
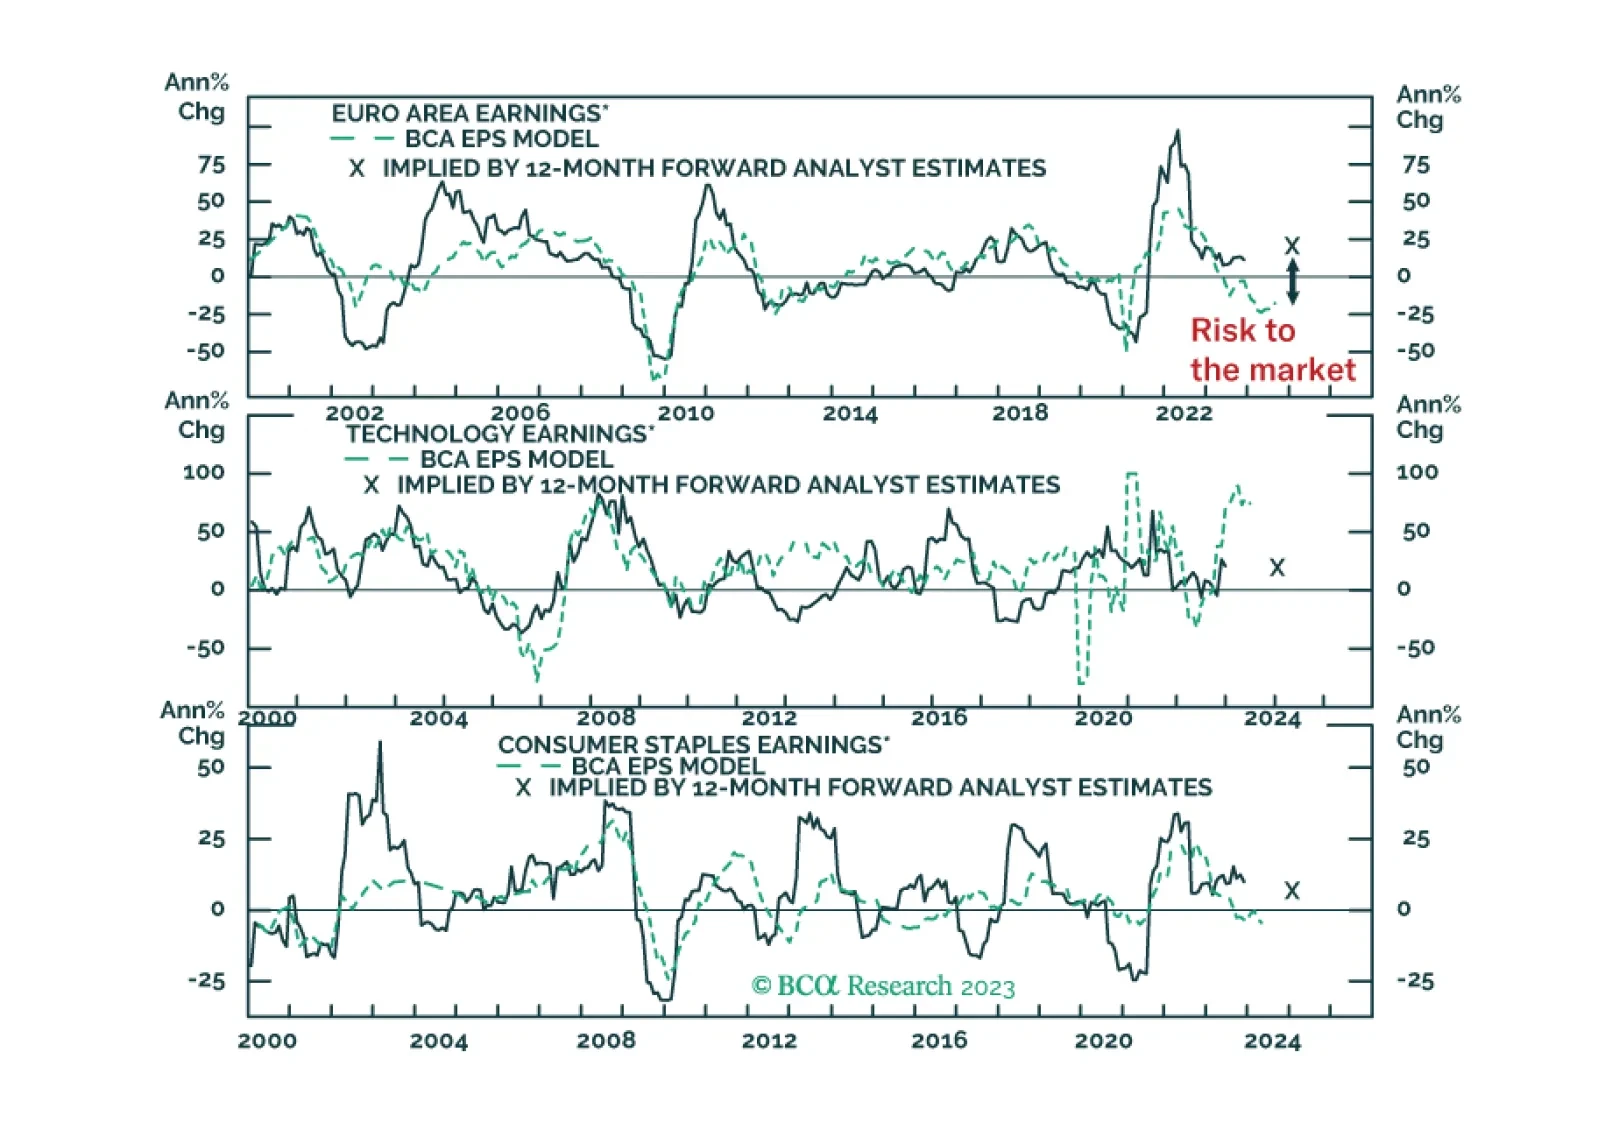
The recent decline in yields has powered European equities higher, however, this rally cannot last if earnings decline meaningfully. With this in mind, are our earnings models flagging risks for stocks next year?
Special Report

Our recommendations for blogs and X’s (on the economy, financial markets, asset allocation, bonds, quants, energy, real estate, geopolitics, and specific countries and regions) to try over the holidays.