Latest from BCA Research
The Fed held rates steady this afternoon, and the timing of its next move will be dictated by whether the tariff shock to inflation is transitory or more long lasting.

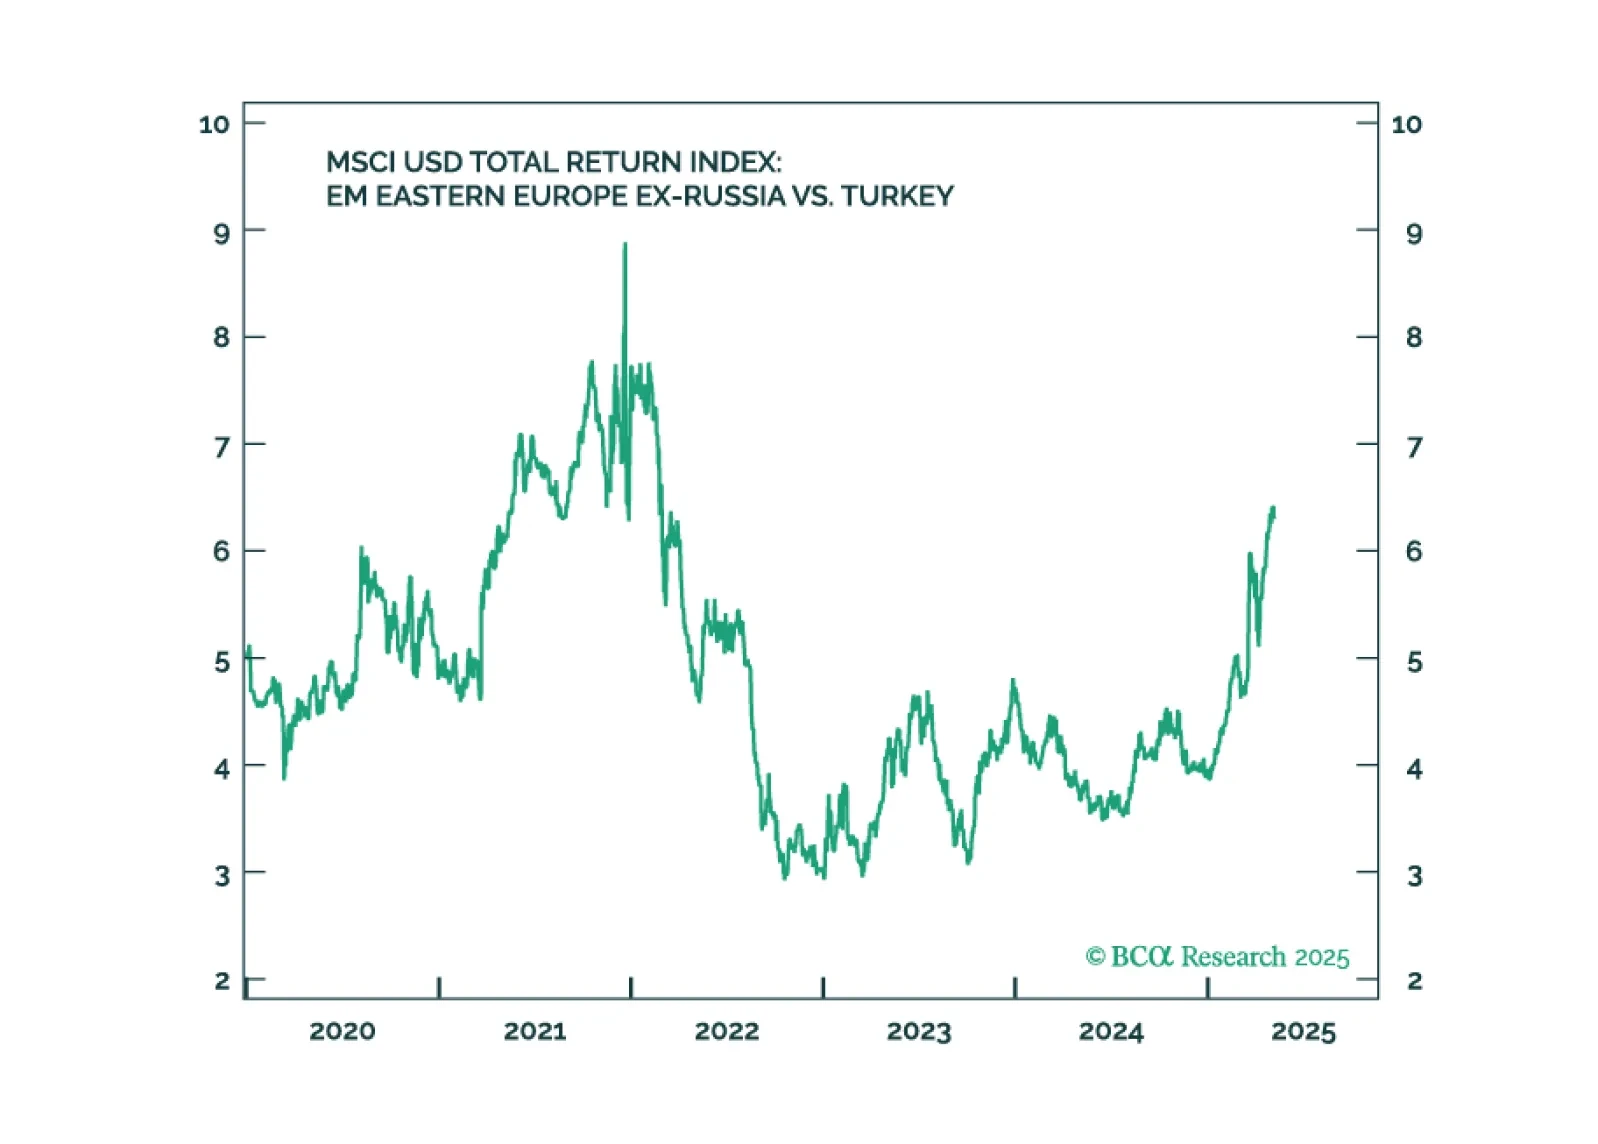
In our Beta report, we do something different. We focus on what factors create a macro context that is conducive to FDI inflows. Market size, trade openness, and infrastructure quality drive appeal, but secondary factors like governance and overall business climate play a meaningful role as well. As FDI reshuffles around geopolitics and new supply chains, competition will heat up among both destinations and investors.
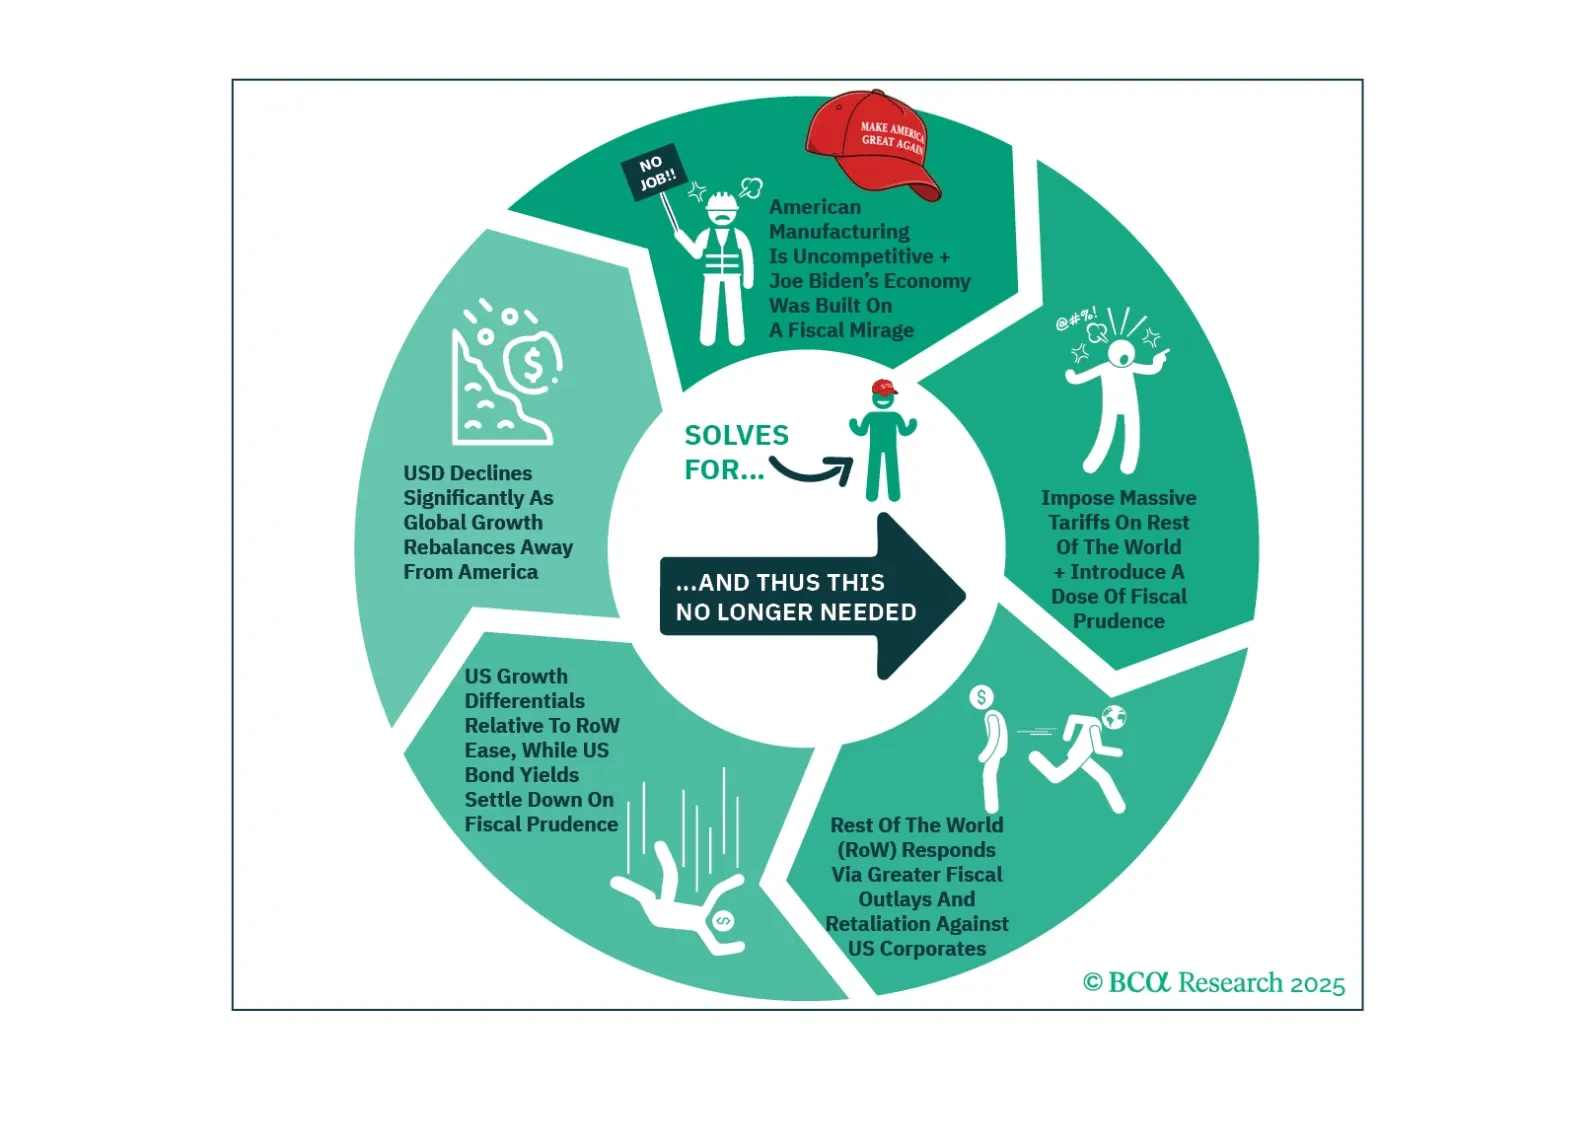
Negotiations on trade, Iran, and Ukraine will prove critical this month. Markets will remain volatile because positive data surprises enable the White House to press its hawkish tariff hikes, while negative surprises force the White House to backpedal.
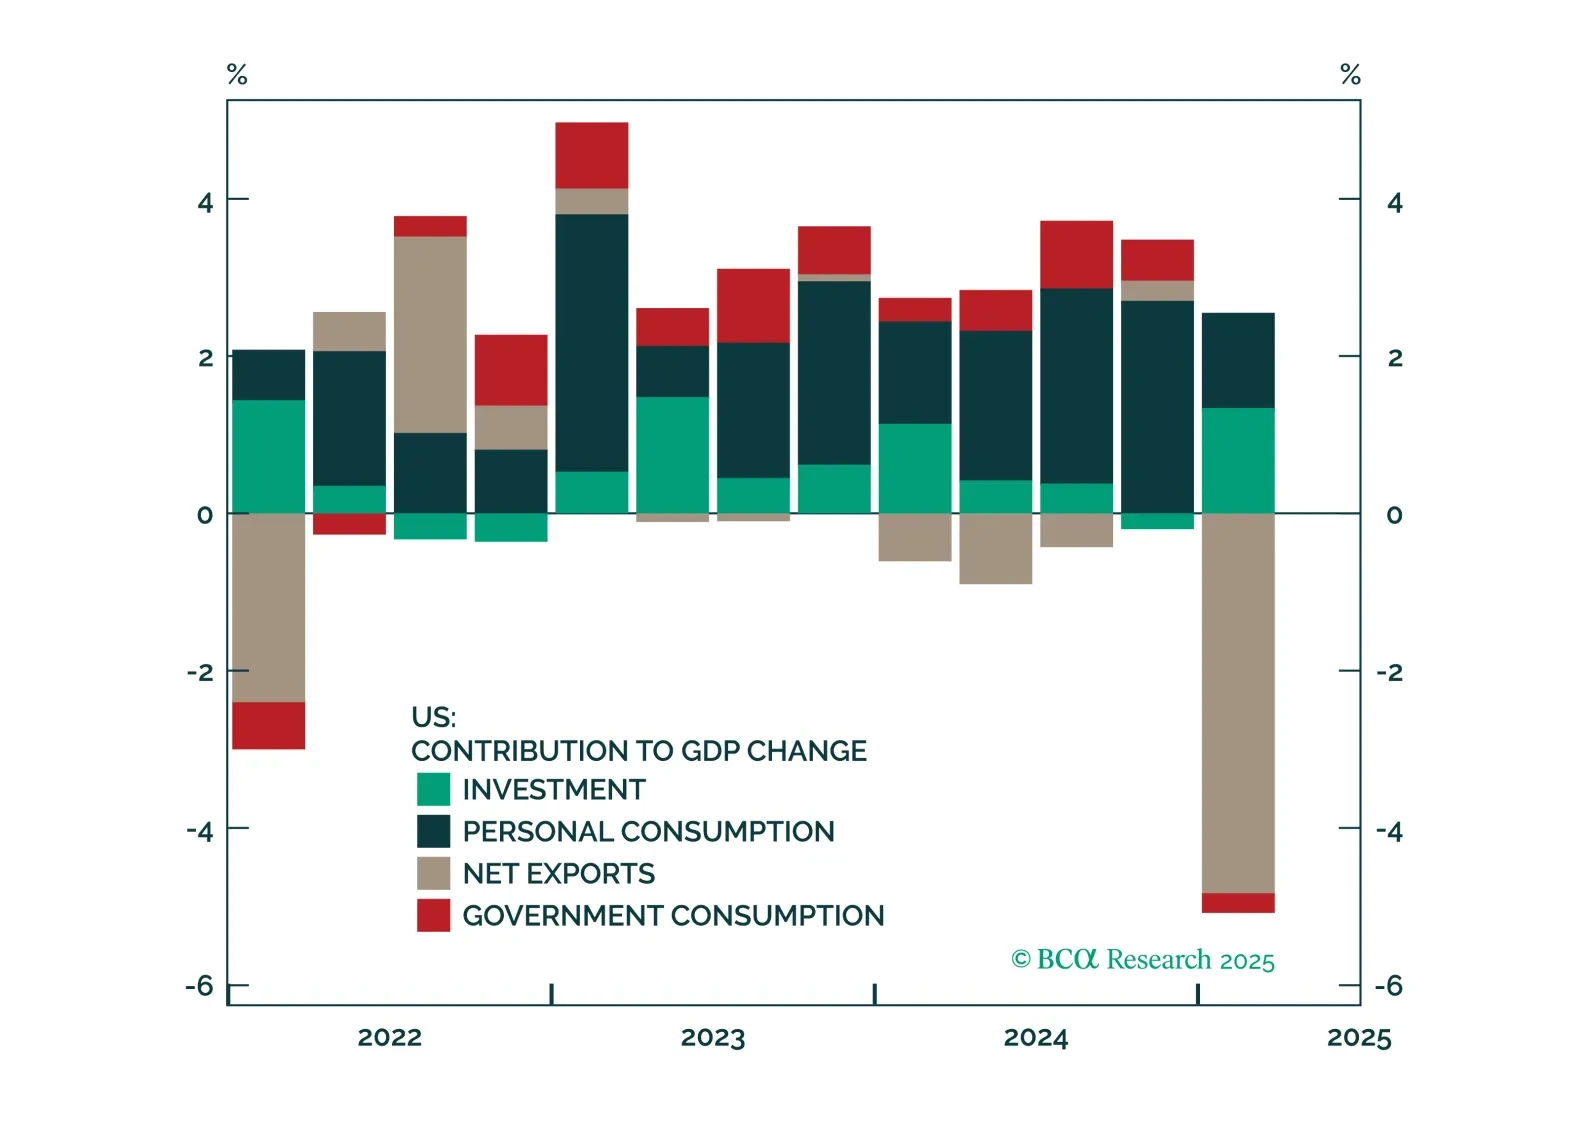
In our Alpha report, we explain how to trade the trade war and then conduct a scenario analysis for global asset allocation. The short version is that a policy induced recession has to be traded based on policy, not hard macroeconomic data.
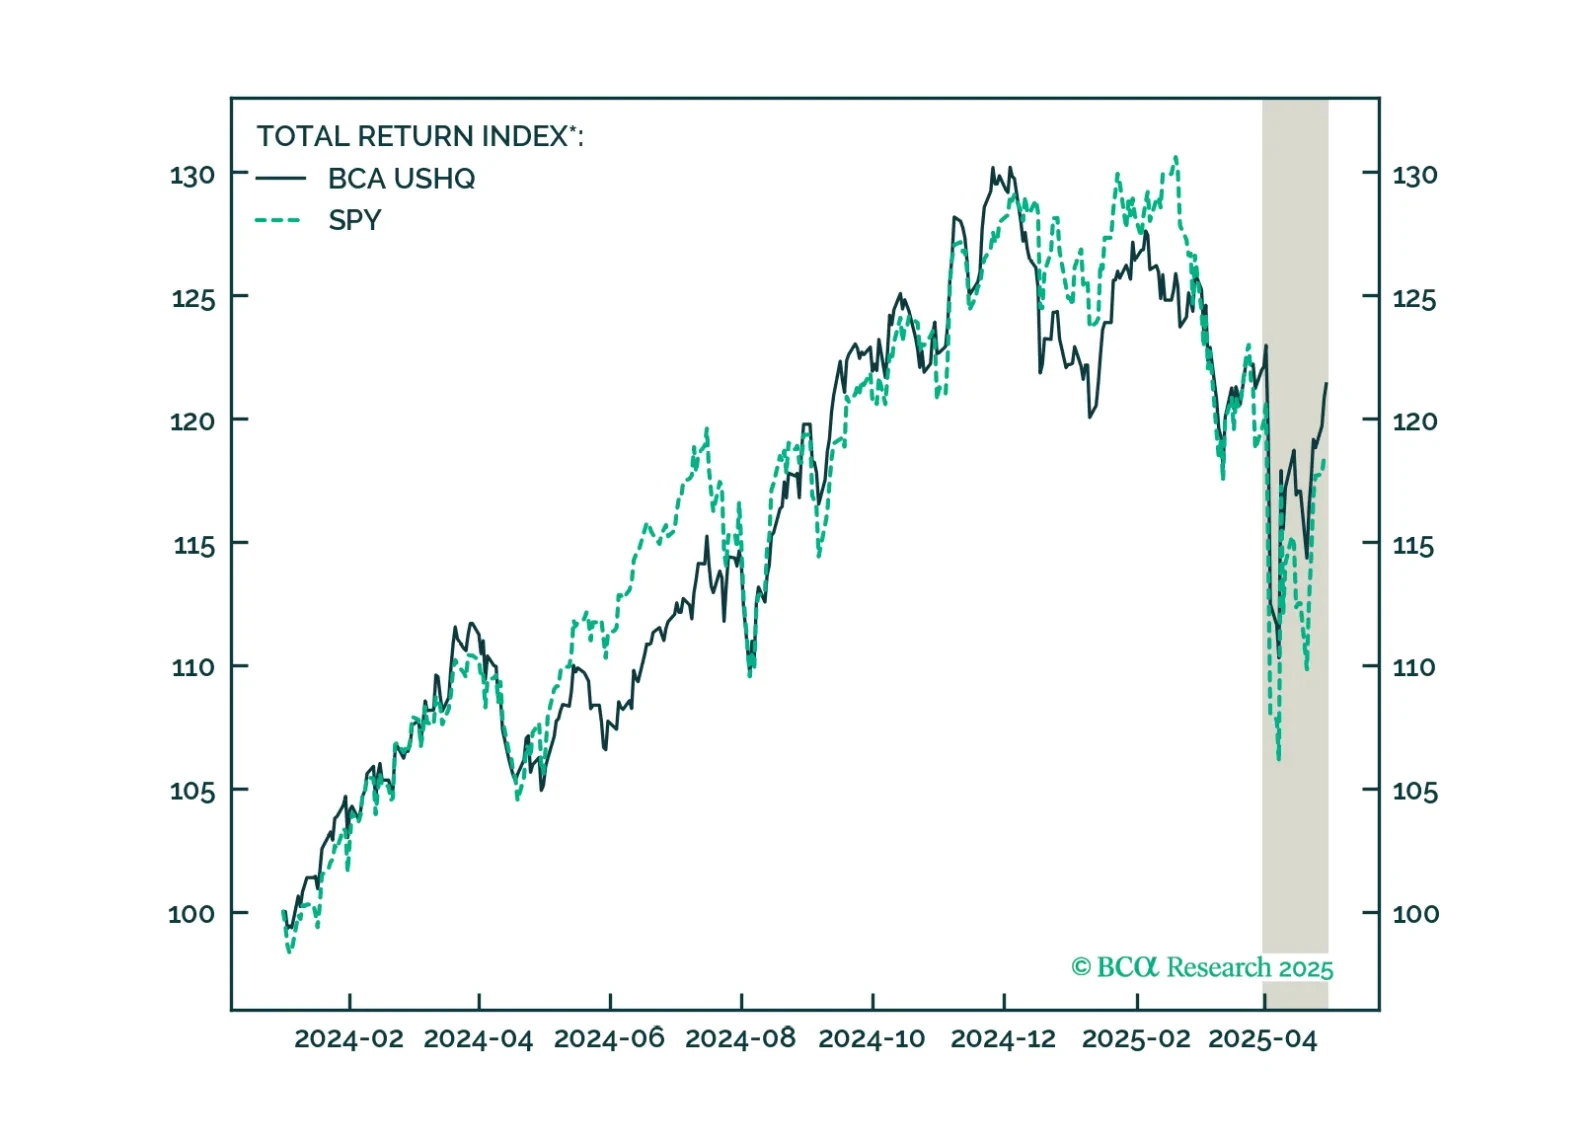
The US High Quality (USHQ) portfolio outperformed on the margin through April, returning -0.6%, whilst its SPY benchmark returned -1.2%. On a trailing three-month basis, performance remains robust vs. benchmark, with USHQ generating +230bps of excess return. Volatility and drawdown are lower too.
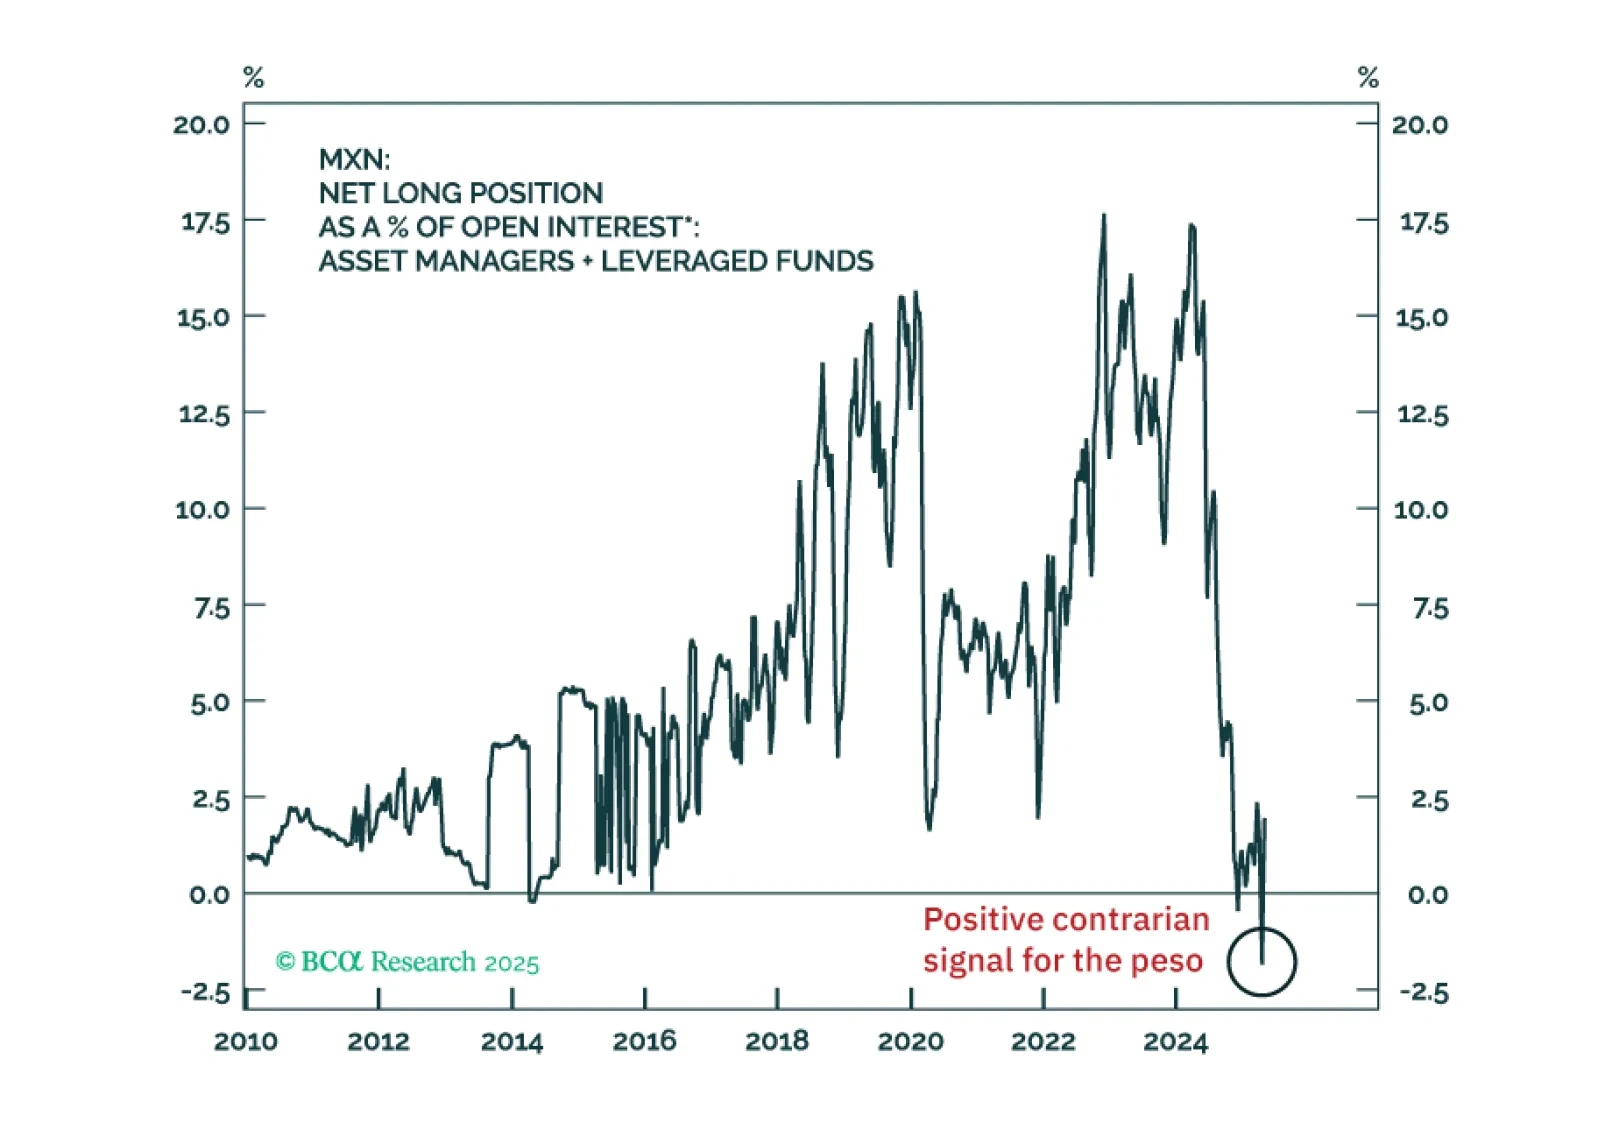
In the long run, Mexico will emerge as one of the biggest winners of US tariffs as the US diversifies supply chains away from China. In the medium term, however, a US growth slowdown and tariffs will push Mexico into recession. In EM portfolios, we remain overweight Mexican equities, domestic bonds, and sovereign credit. We are reiterating a buy on 10-year domestic bonds. Go long MXN versus CNH.
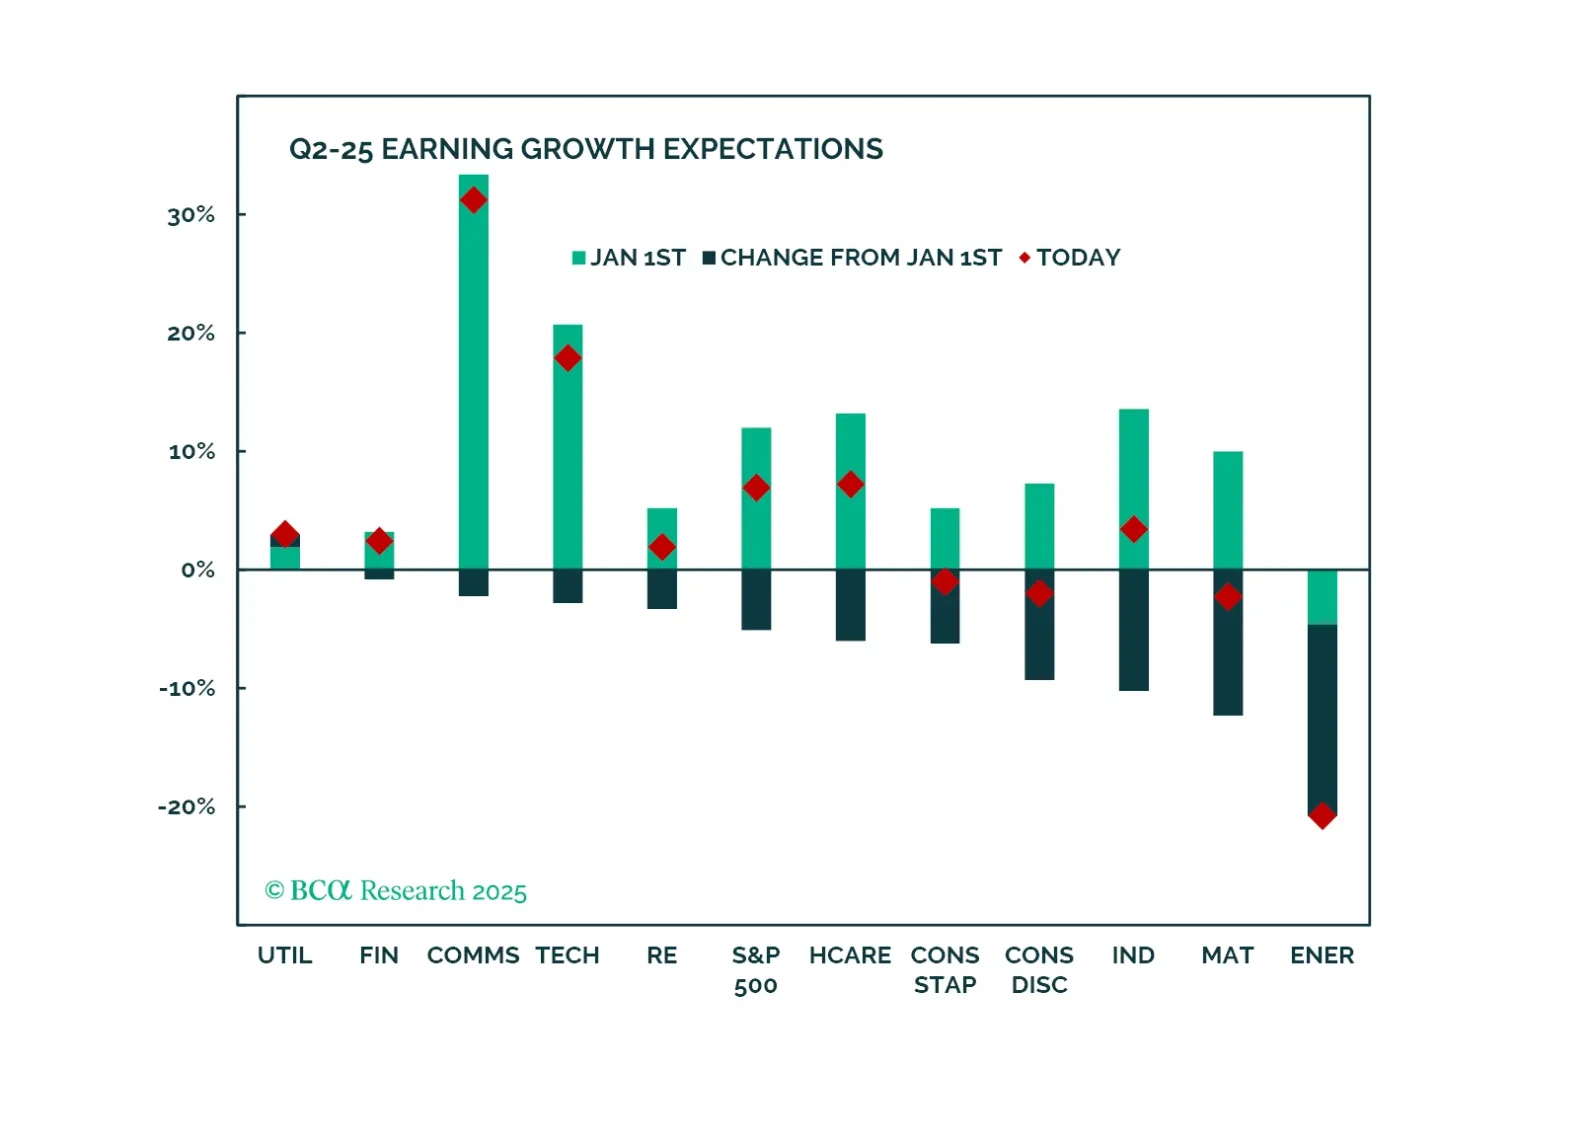
In the front section of the chart pack, we review April and YTD market performance, provide an update on the Q1 earnings season, examine the outlook for the Magnificent Seven, and adjust portfolio positioning.
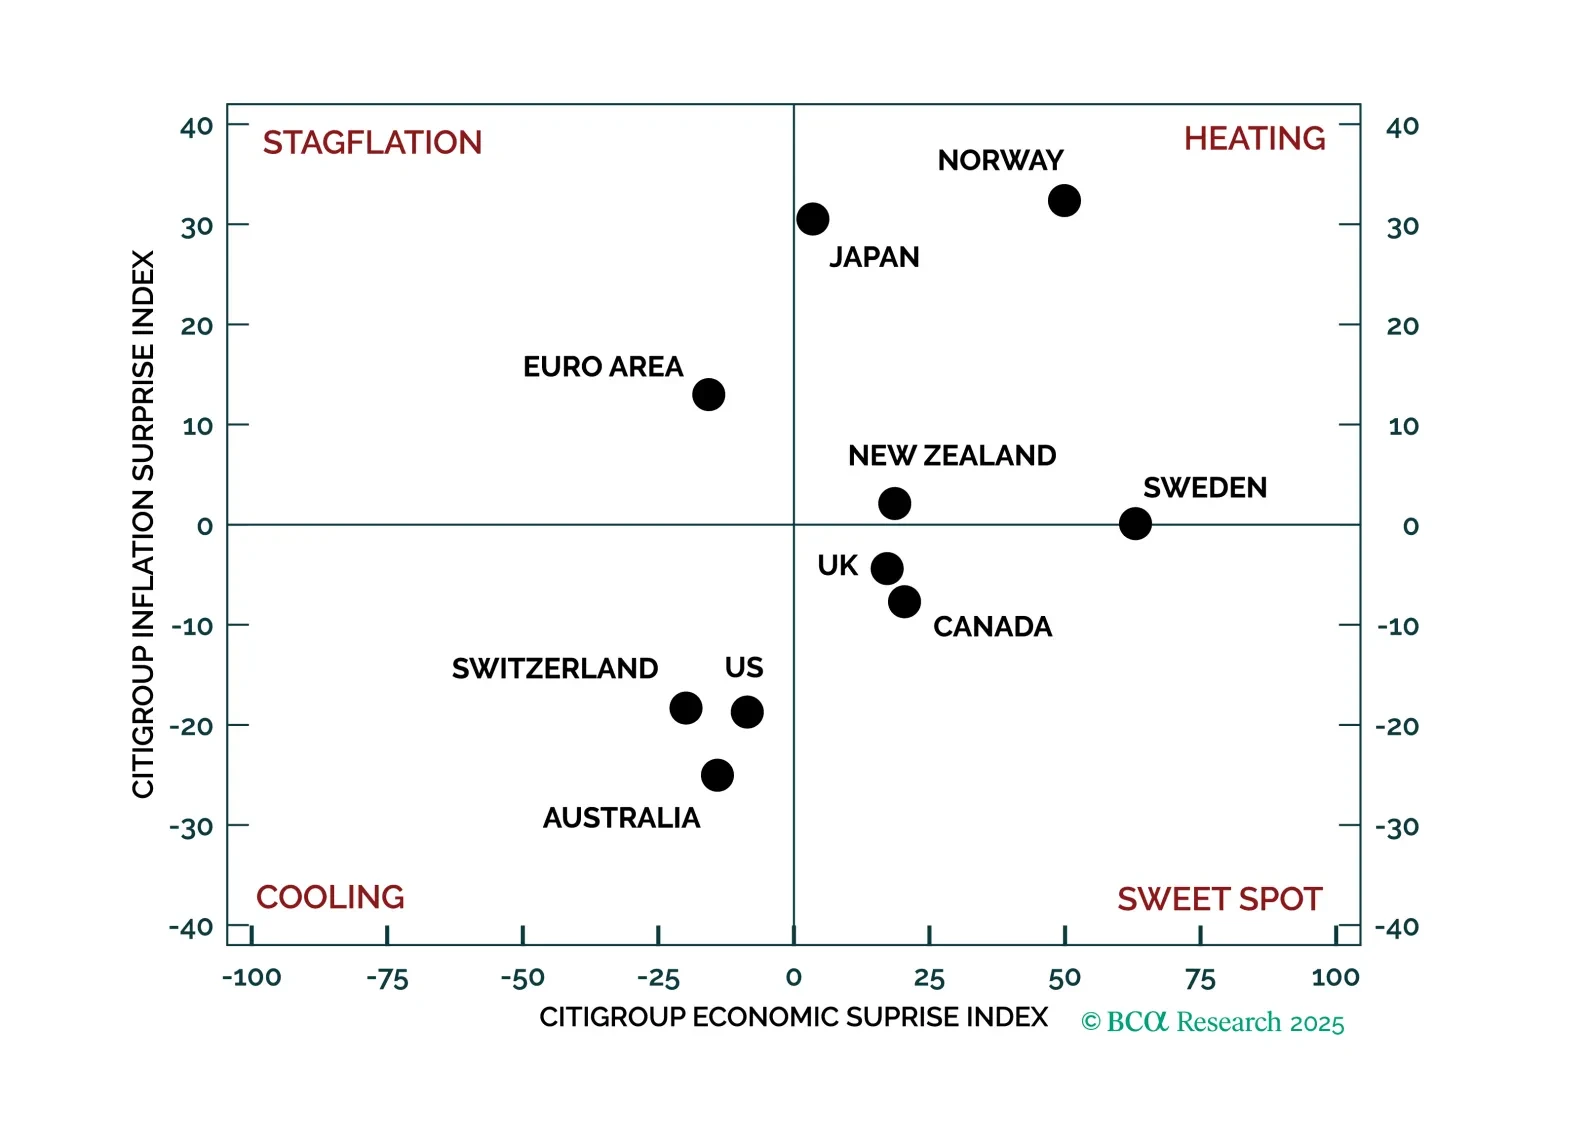
We apply our systematic approach to investing based on economic, inflation, and monetary policy surprises to the major global bond markets. The economic regimes defined by the current macro-surprises setup confirm our existing fixed-income portfolio tactical recommendations.
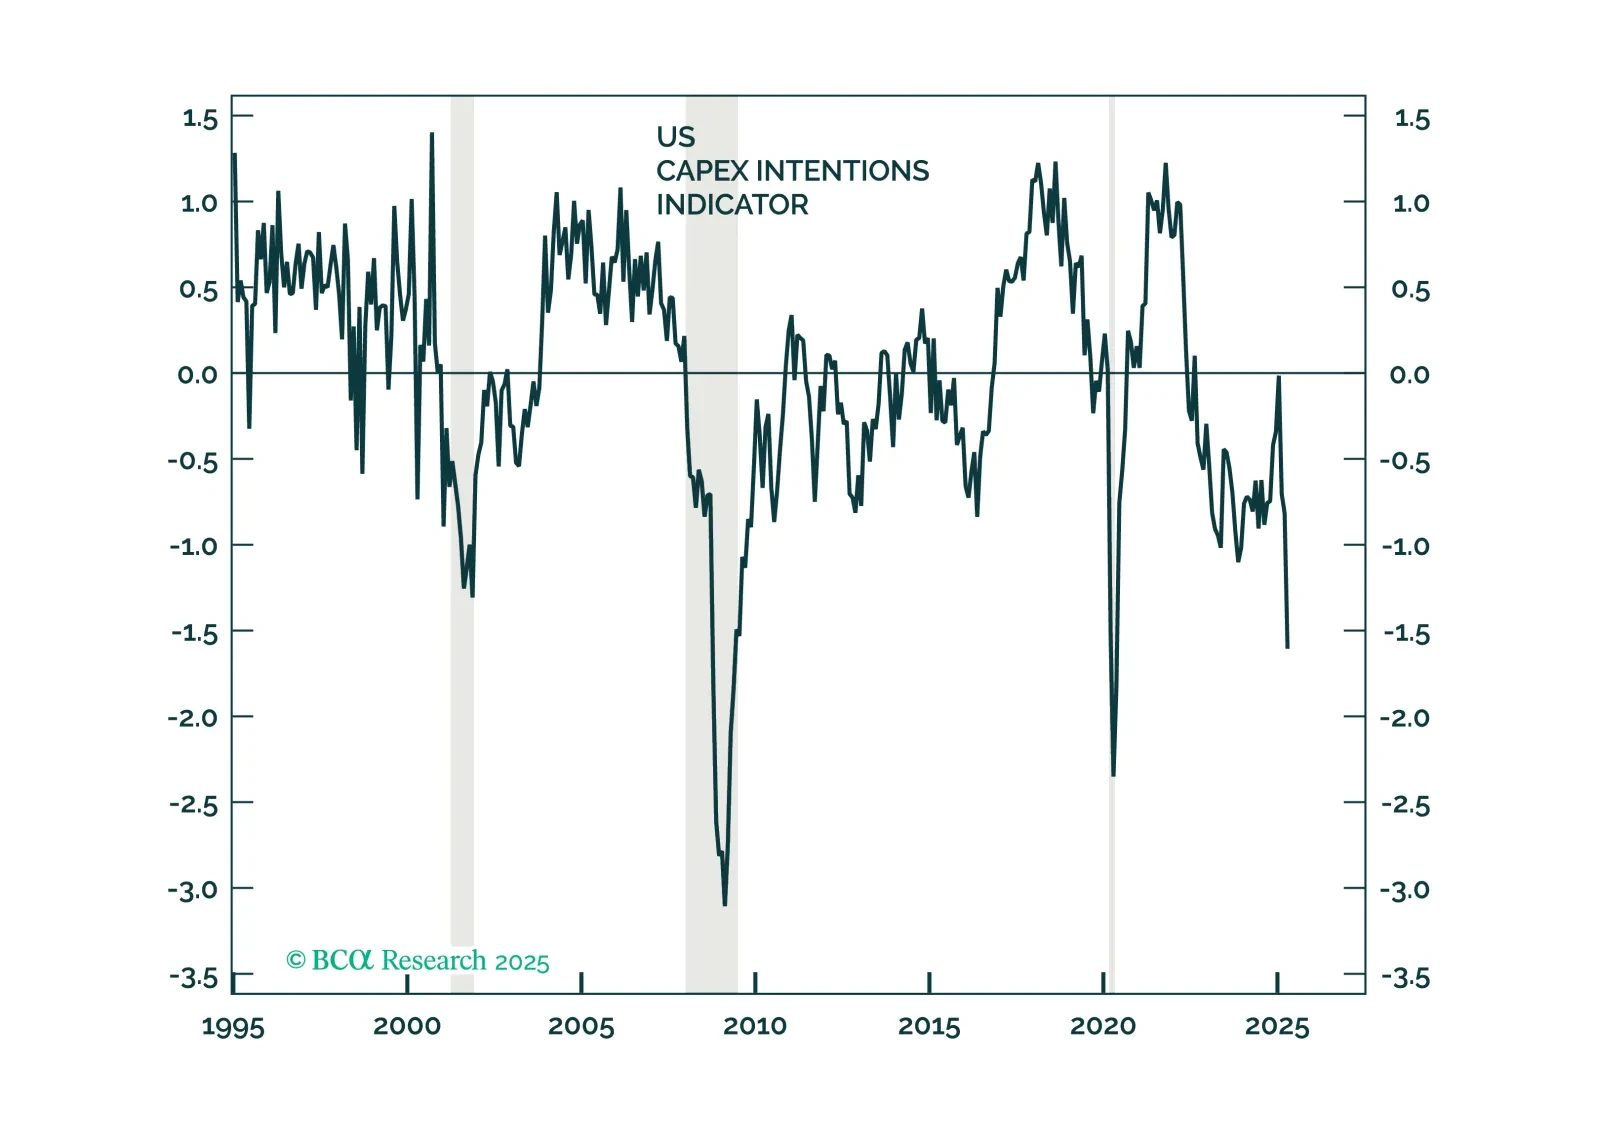
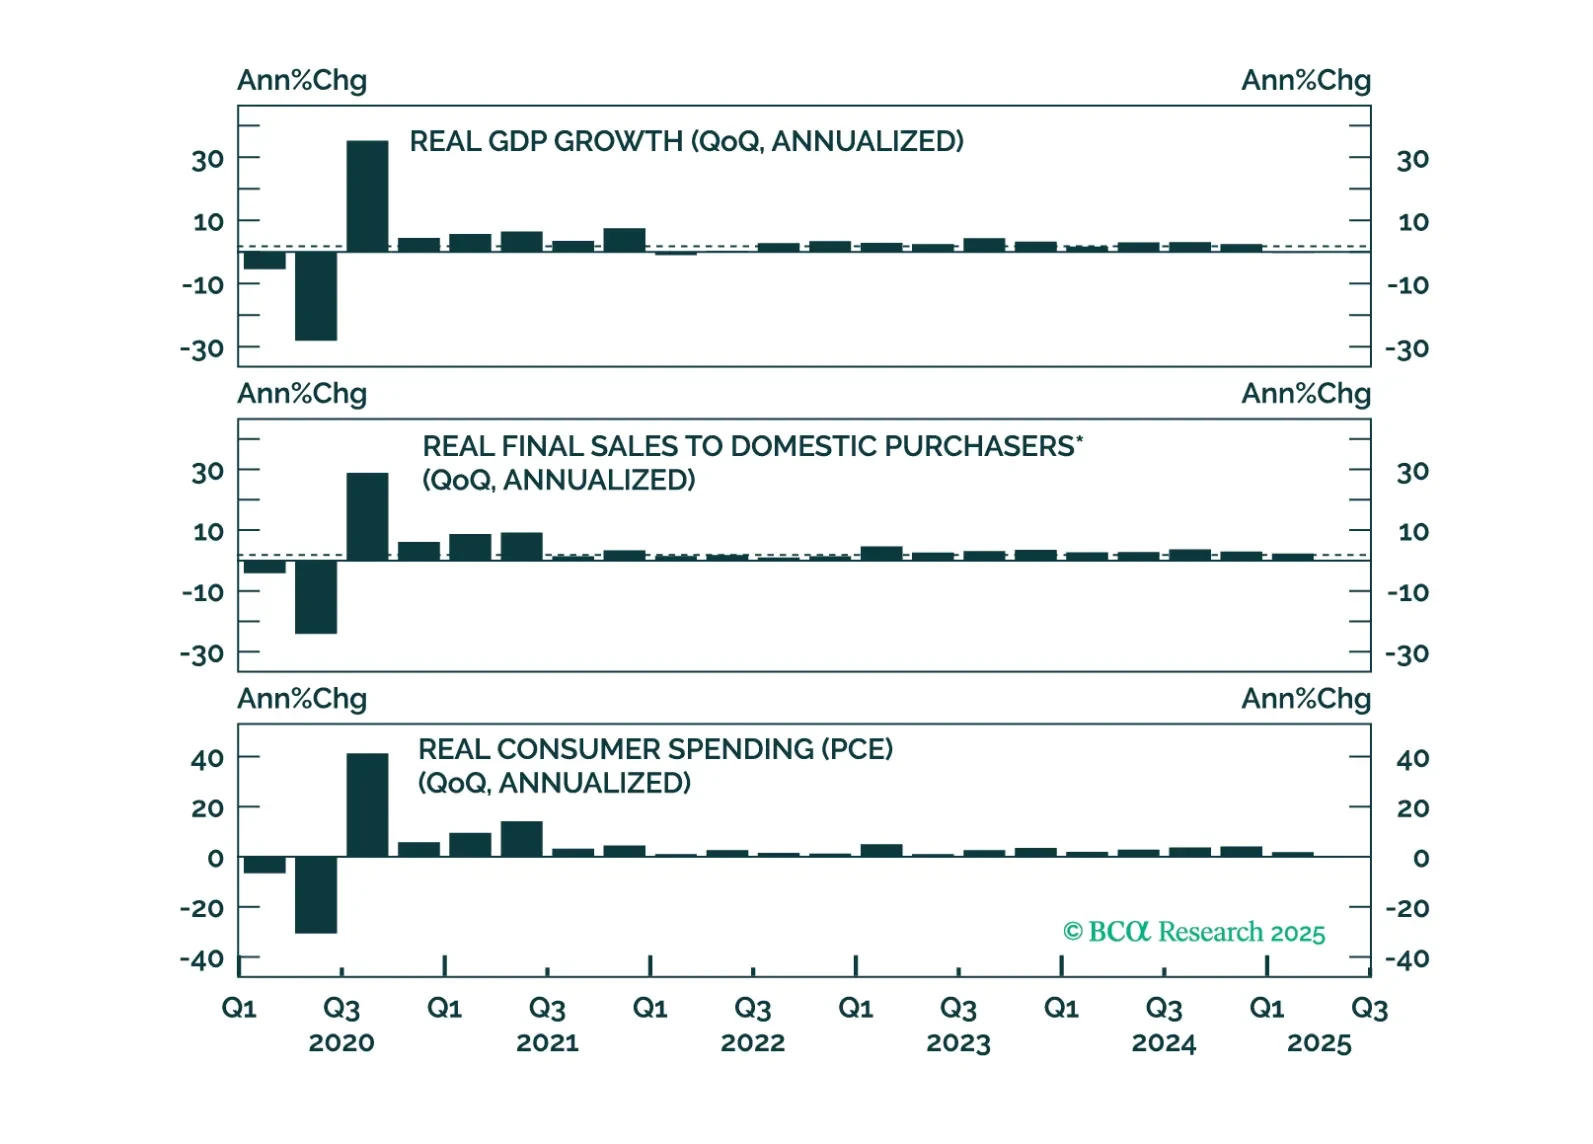
Hard aggregate macro data series remain solid, but surveys of businesses and consumers continue to worsen and the list of consumer-facing companies lowering earnings estimates gets longer by the week. We believe surging equities are ignoring the adverse effects of tariffs and reiterate our defensive asset allocation recommendations.