Latest from BCA Research
Fed Chair Jay Powell’s remarks yesterday were in-line with our base case expectation that the Fed will not cut rates proactively in the face of rising tariff-driven inflation.

The textbook impact of the world’s largest goods importer, the US, imposing an ultra-high tariff on the world’s largest goods exporter, China, is for global goods prices to FALL. Thereby, while Trump’s tariffs will be inflationary for the US they will be DEFLATIONARY for Europe. We go through the implications for rates, bonds, stocks, and FX. Plus: tactically underweight global utilities (JXI); and tactically buy TGT.
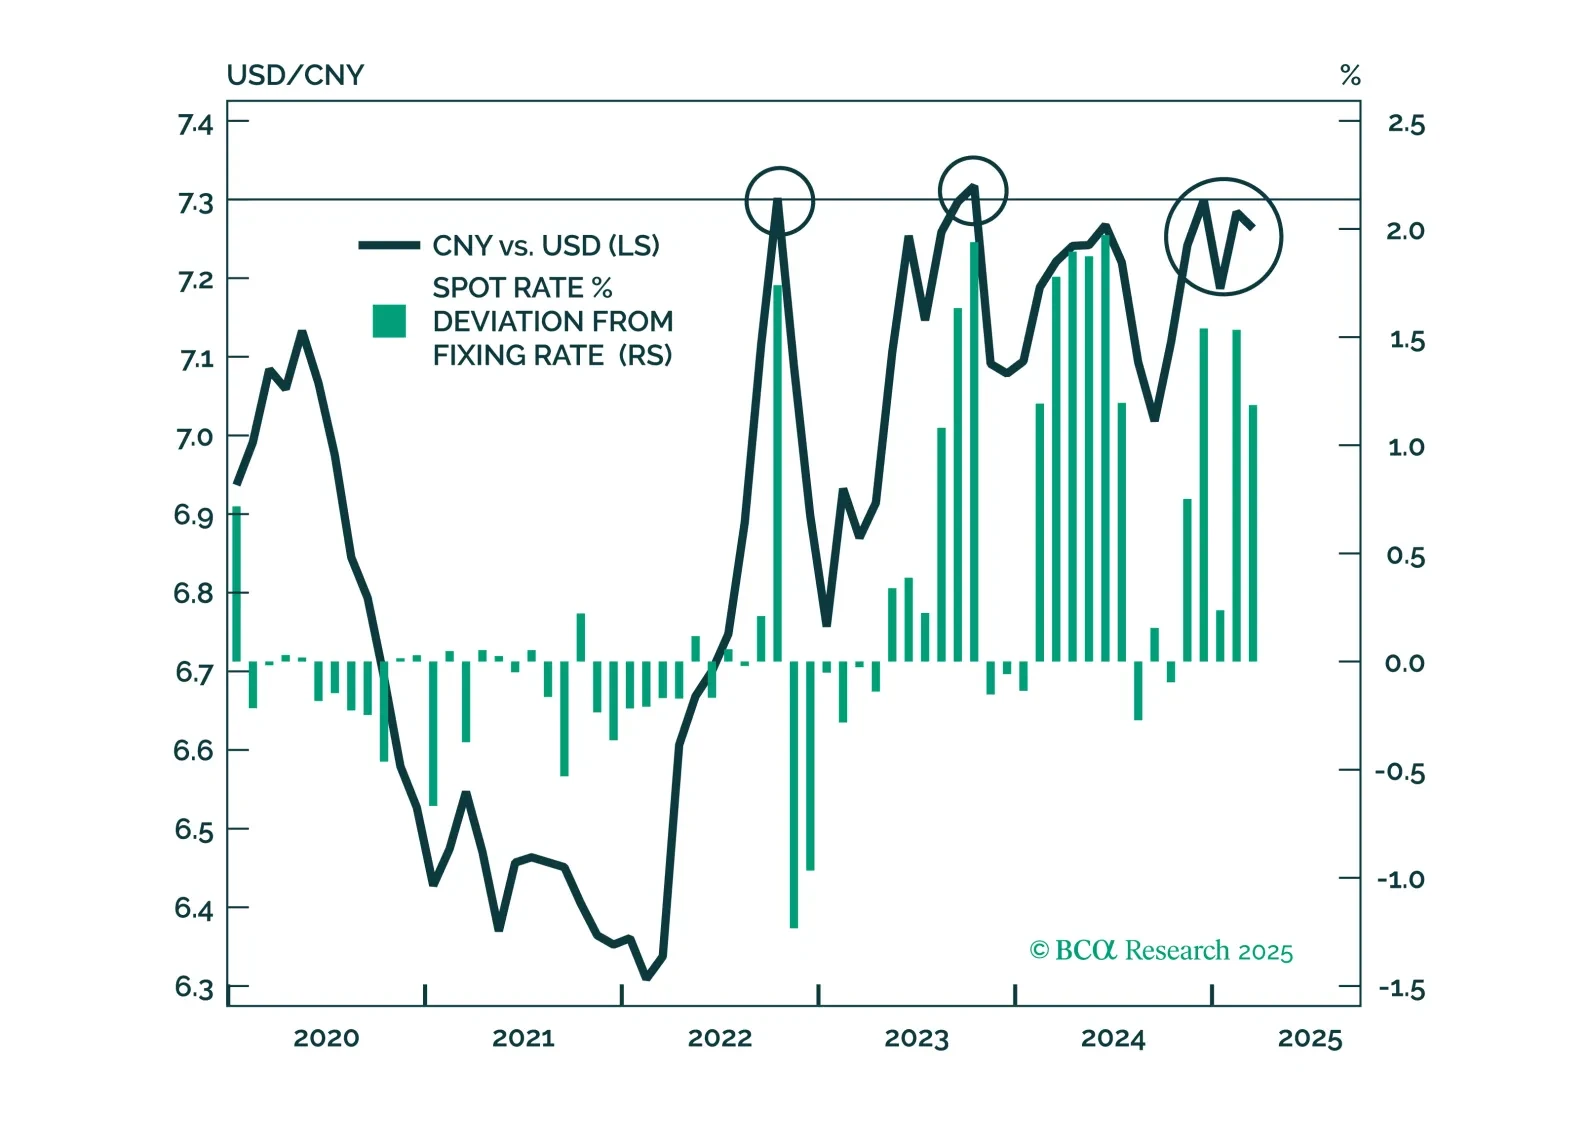
While the United States and China may aim for full decoupling, all they can afford now is some form of trade skirmishes. Increasing economic pressure will eventually force both Washington and Beijing to pursue more proactive negotiations. Until then, internal economic and financial strains are likely necessary to break the stalemate and resume dialogue between the two nations.
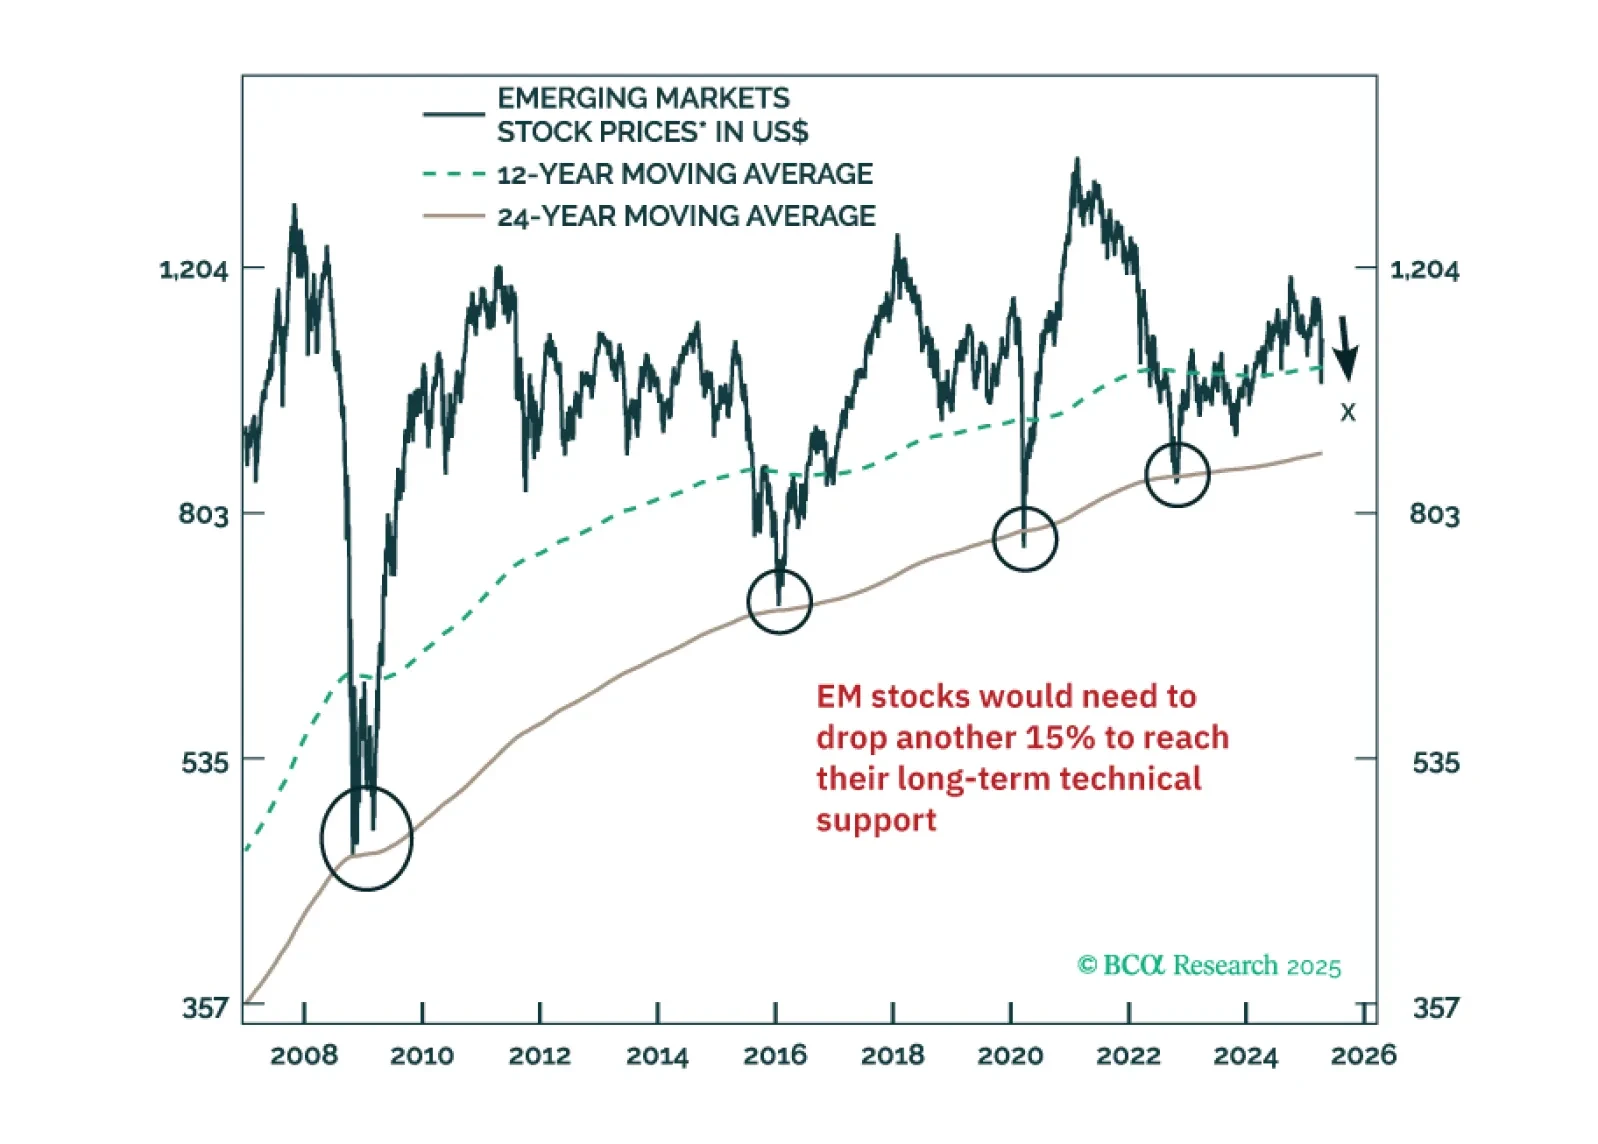
Even after policymakers retract their prejudicial actions, financial markets might continue selling off. We compare the current tariff shock with two past episodes when policy reversals did not produce market turnarounds: (1) the RMB devaluation in August 2015, and (2) the US Congress's initial rejection of the TARP bank bailout program in 2008. In addition, we show numerous technical indicators illustrating at which levels the potential bottom in various equity markets could be.
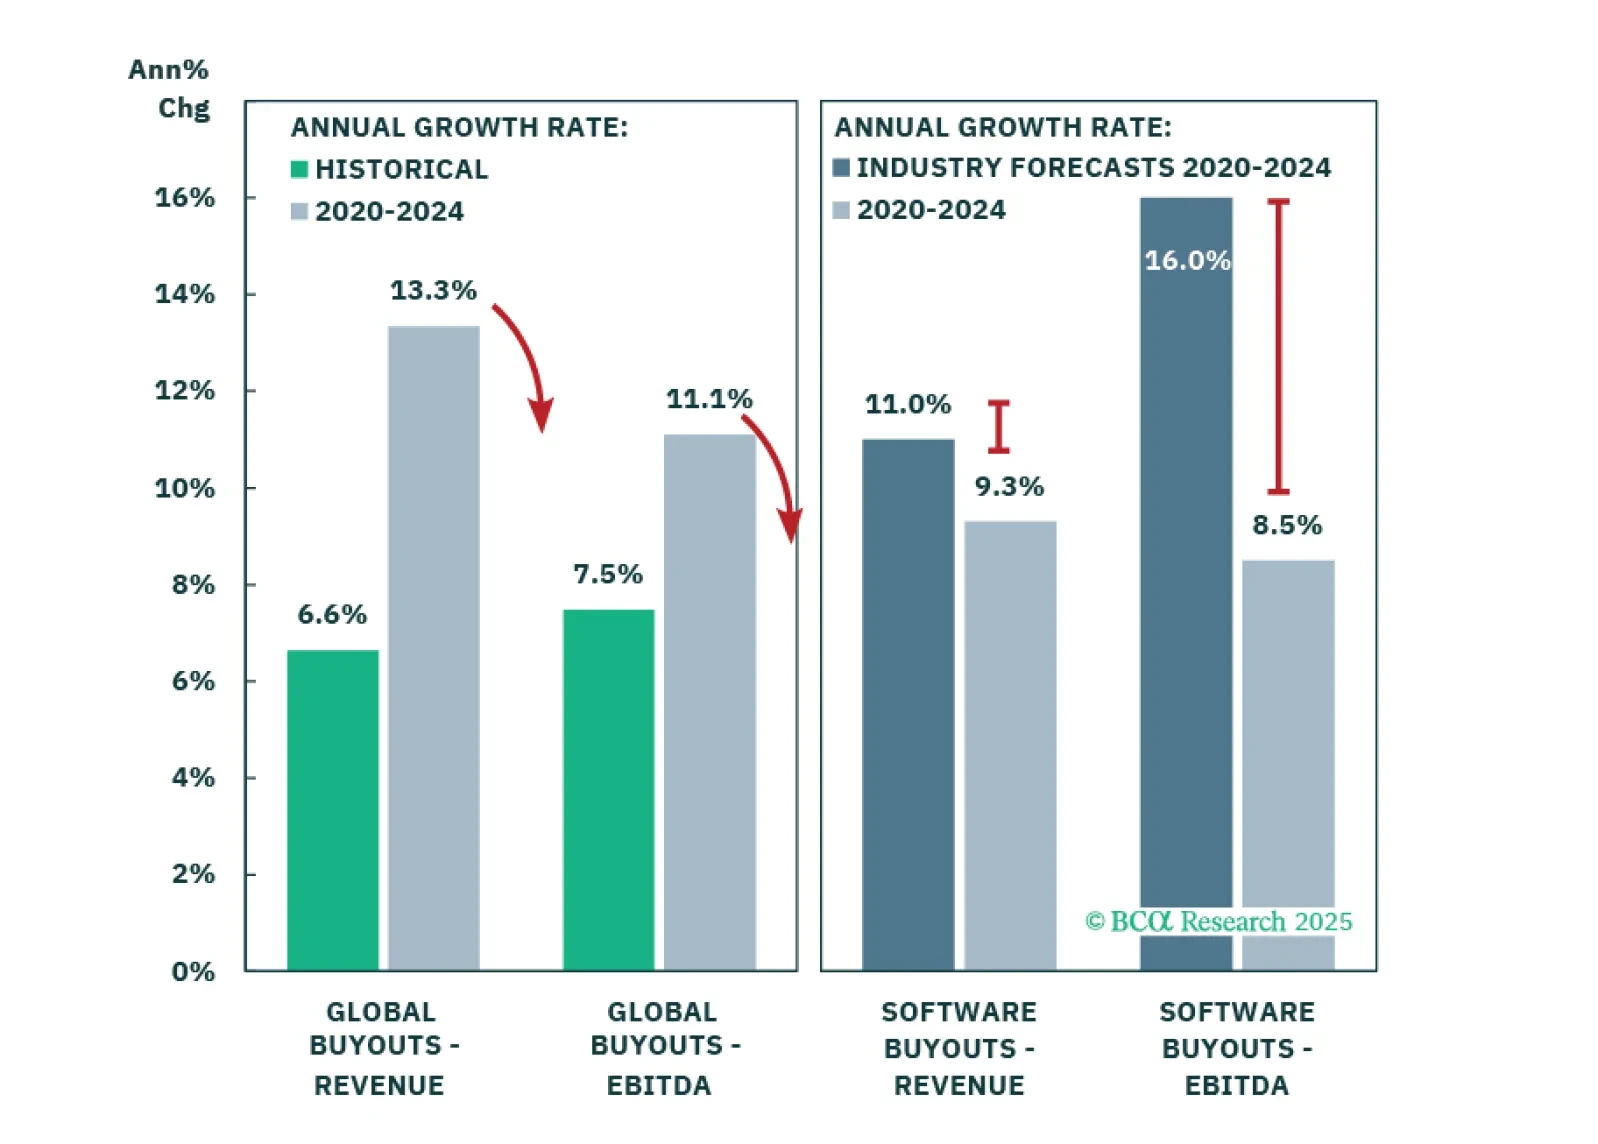
Tariffs may trigger the recession, but the economy was already vulnerable from unsustainable growth and inflated expectations. Private Equity is most exposed, though this situation neither emerged suddenly nor will it unfold overnight. Our recommendations remain largely unchanged as market conditions increasingly align with our outlook.
President Trump keeps walking back his tariffs, aligning with our Seven Steps of Maximum Pressure. Investors should expect a lot of back and forth over the next few weeks, including the dreaded Step 5 (“Leave the Bride at the Altar”). Already, Commerce Secretary Howard Lutnick has suggested that the tariff exemptions for electronics – which surged global risk assets today – would not last long. We hesitate to just declare the “all clear” and go outright long but are shifting our posture on global risk assets to neutral.
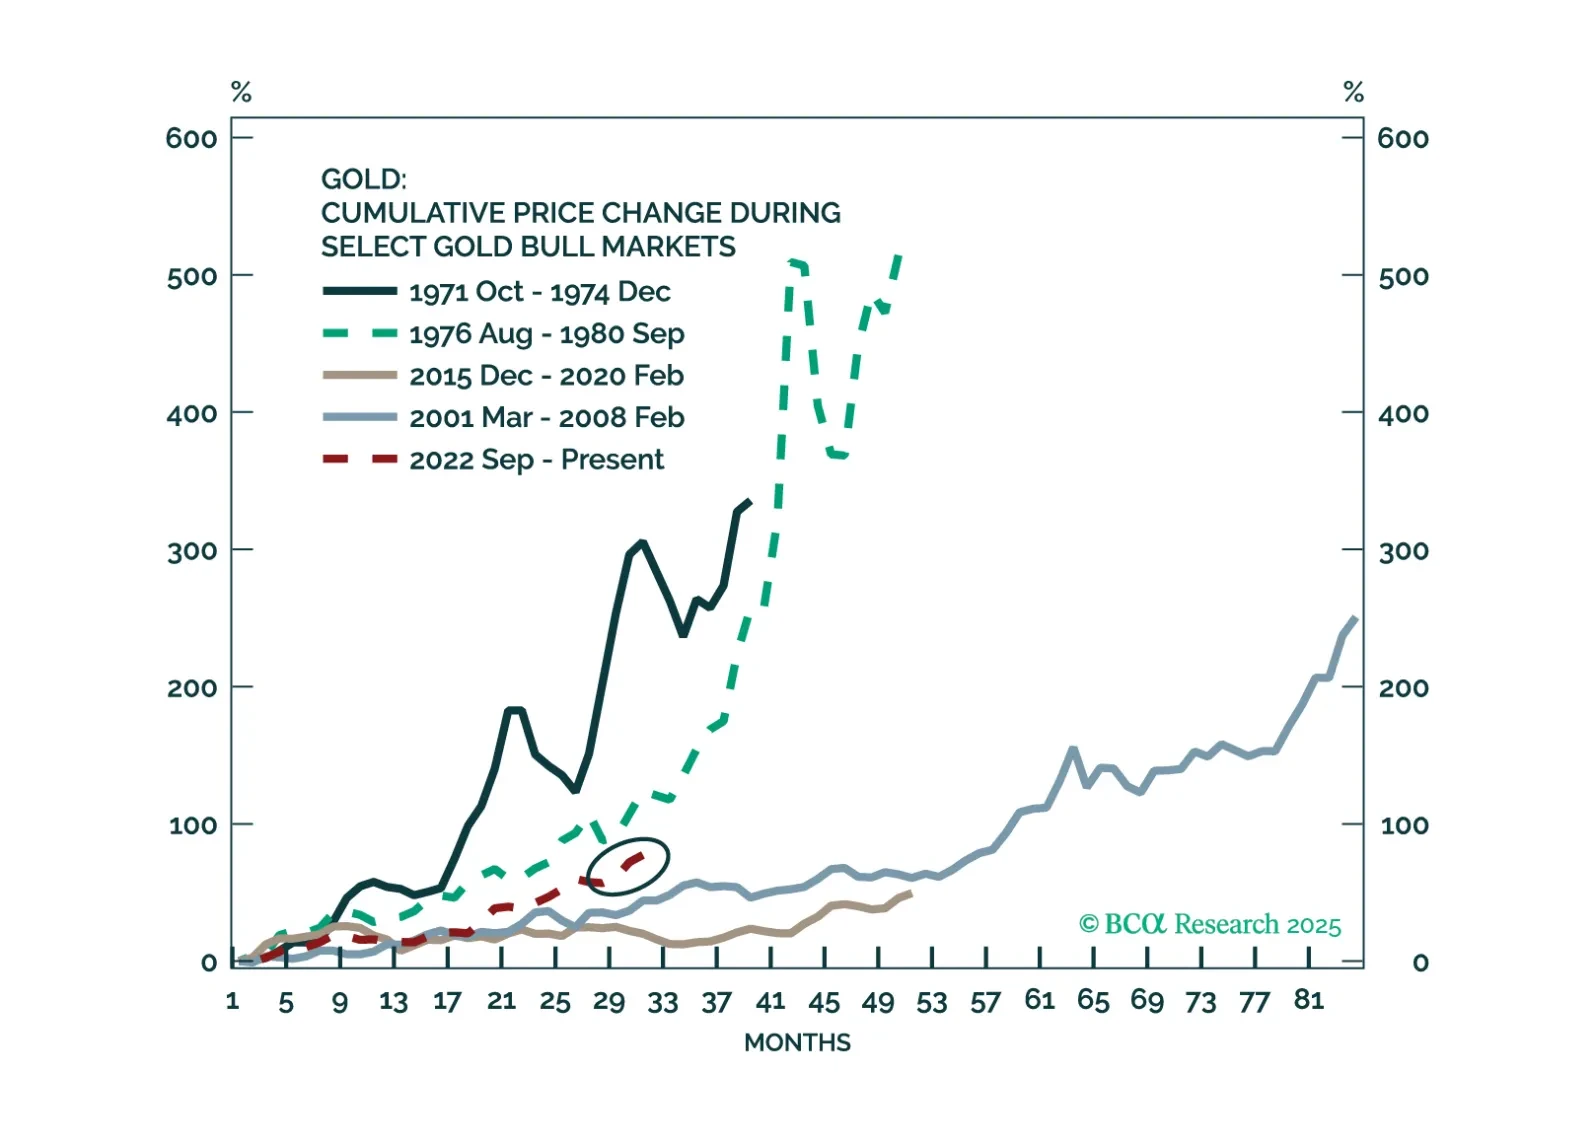
Commodities have not been spared the wrath of the post-"Liberation Day" selloff. However, in the sea of red, gold continues to shine bright, climbing to a fresh record high. How much further does the recent price action have left to run? We explore technical indicators to gauge the likely price outlook for gold, oil, and copper over the coming months.

This week, our three screeners cover equity plays in: Gold mining stocks, Japanese Staples, and Implicit Dividend Yield.