Latest from BCA Research
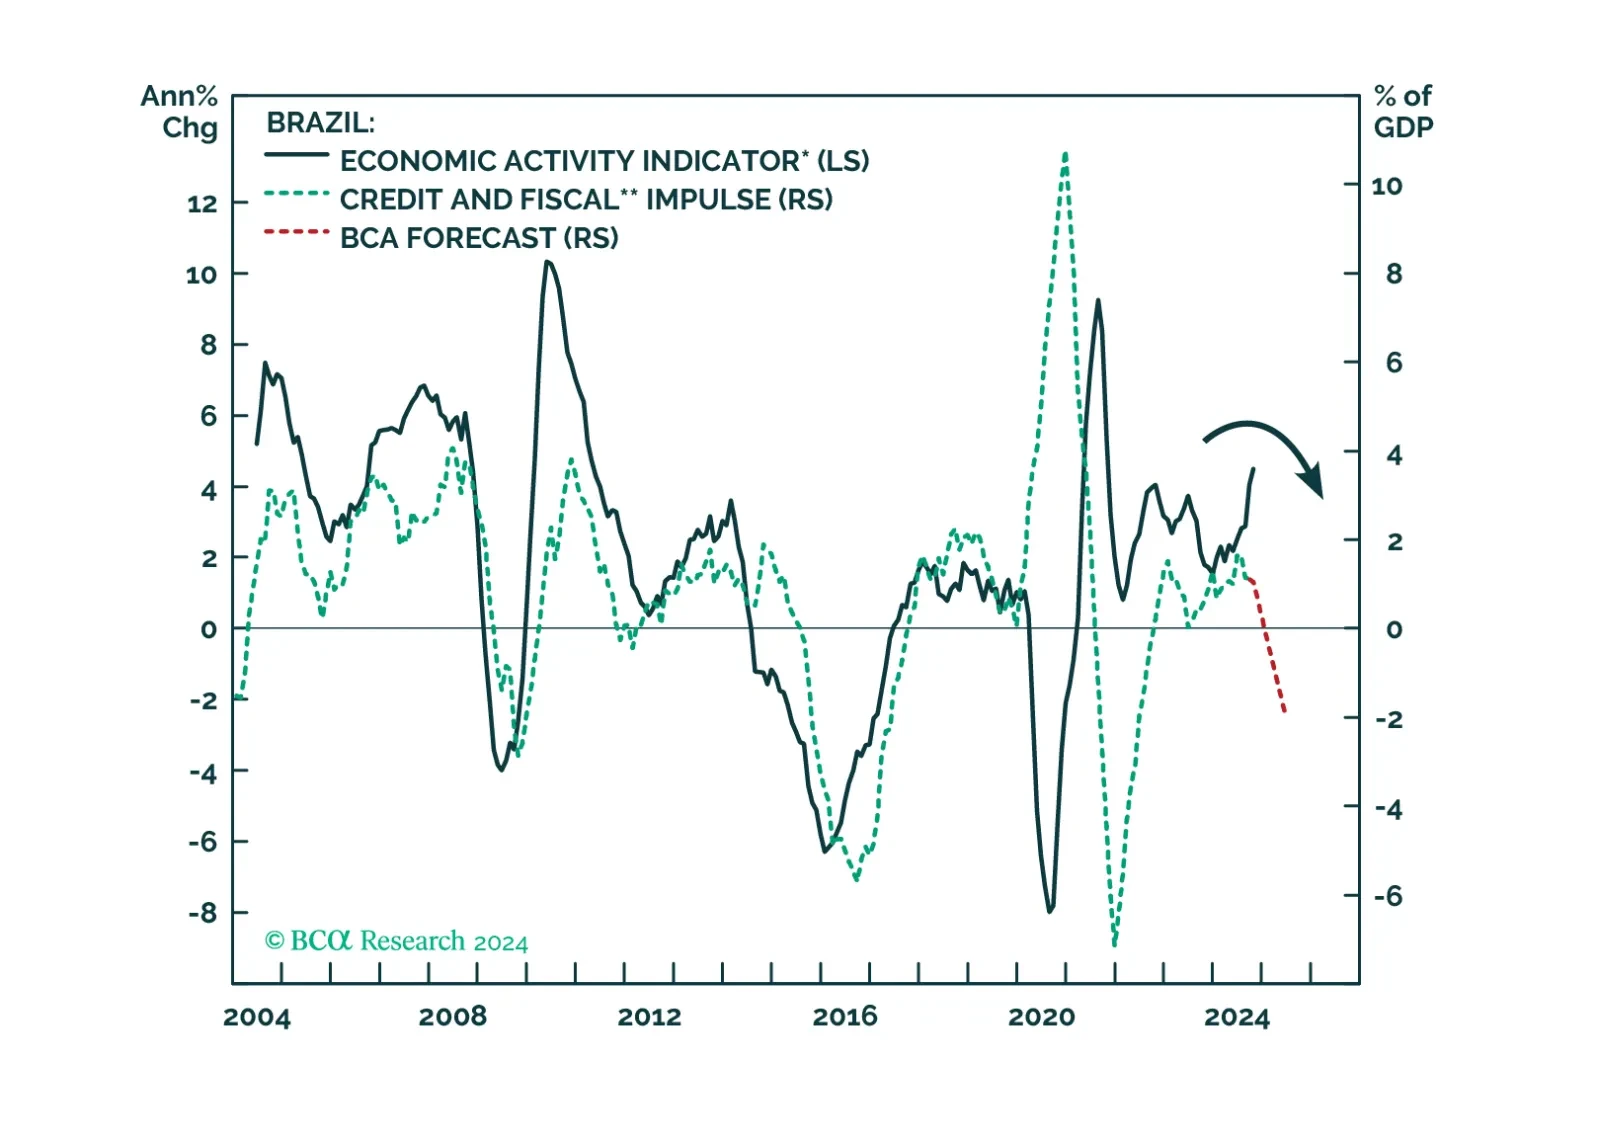
Any additional fiscal tightening and further rate hikes might serve as a band-aid, but not a cure, to Brazilian markets. The country’s risk assets and the currency will continue to face headwinds from an impending recession, a strengthening USD, weak commodity prices, and worsening public debt dynamics. Investors should fade out any relief rallies in Brazilian markets for now.
As the US faces renewed government shutdown risk, I thought it was prudent to highlight two developments to GeoMacro clients.

Understanding the risks across Private Credit will enable investors to be offensive, not just with sizing but across their total portfolio. Senior Direct Lending is not risk-free, Private Credit is not systemic, and a liquidity crisis will not be born in this asset class.

A confluence of both supply and demand factors contributed to the natural gas rally over the past few months. This trend could continue for a while longer. However, cyclical and structural factors ultimately argue against a sustained increase in prices.
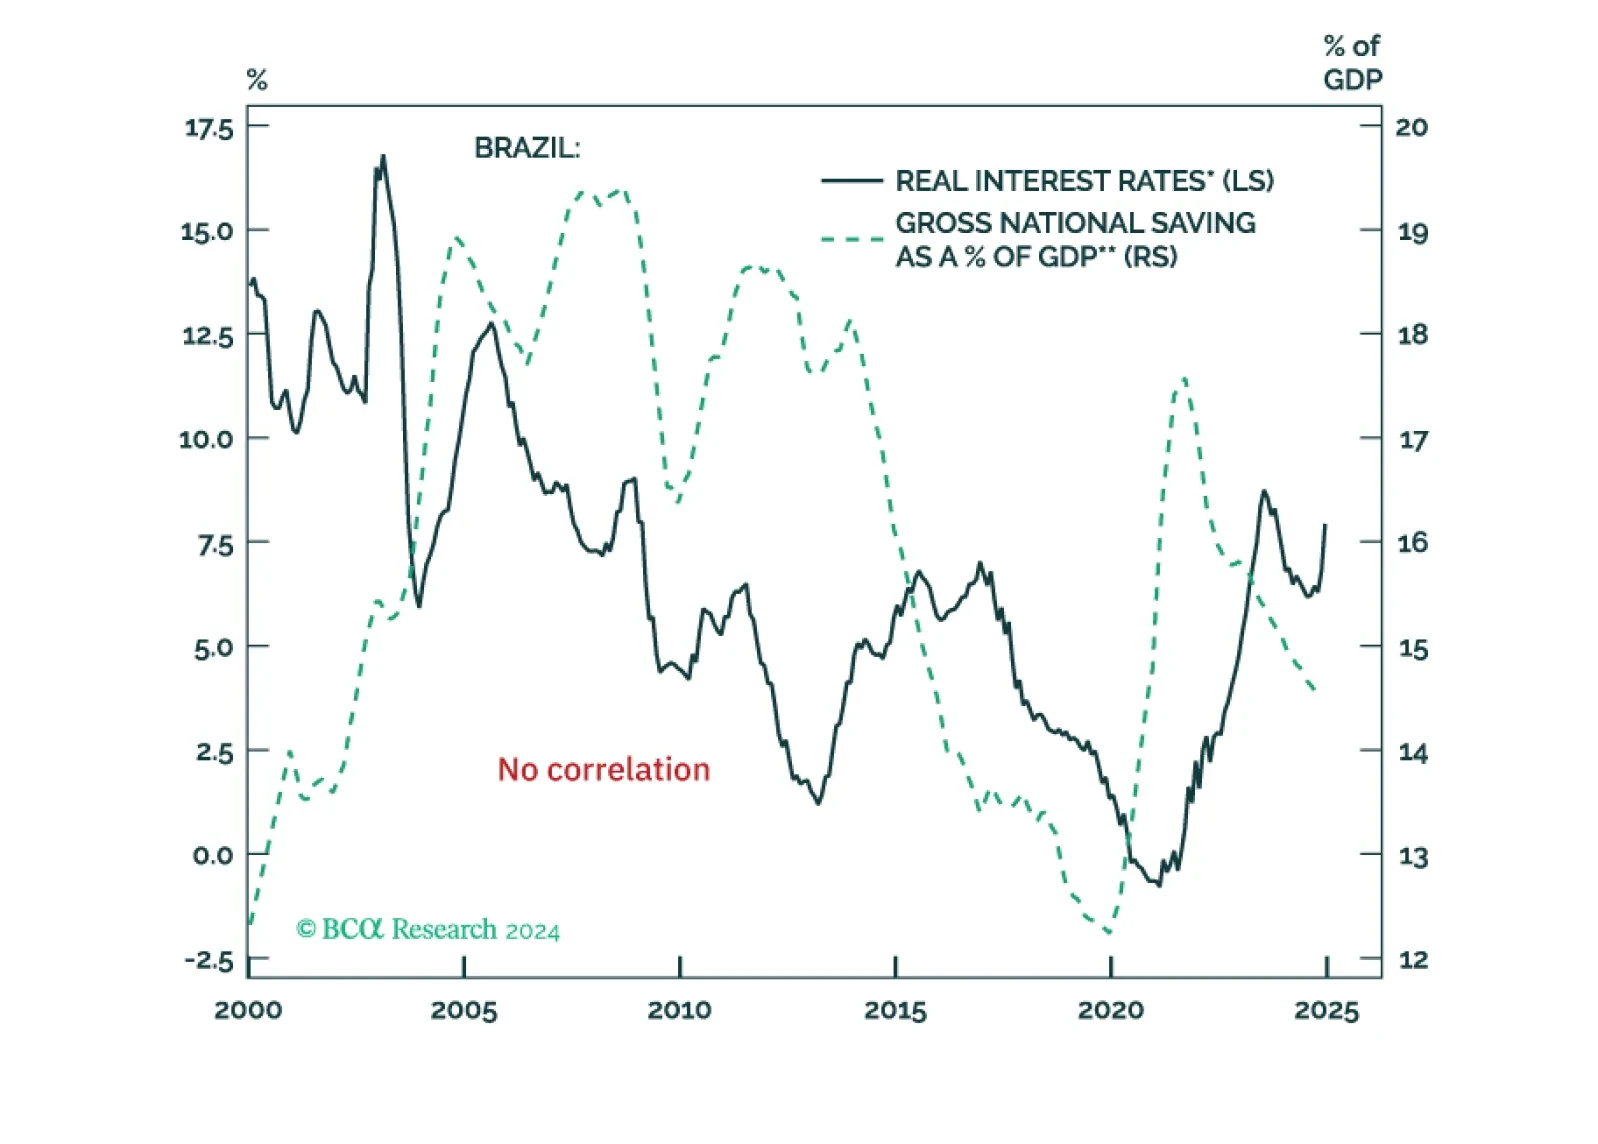
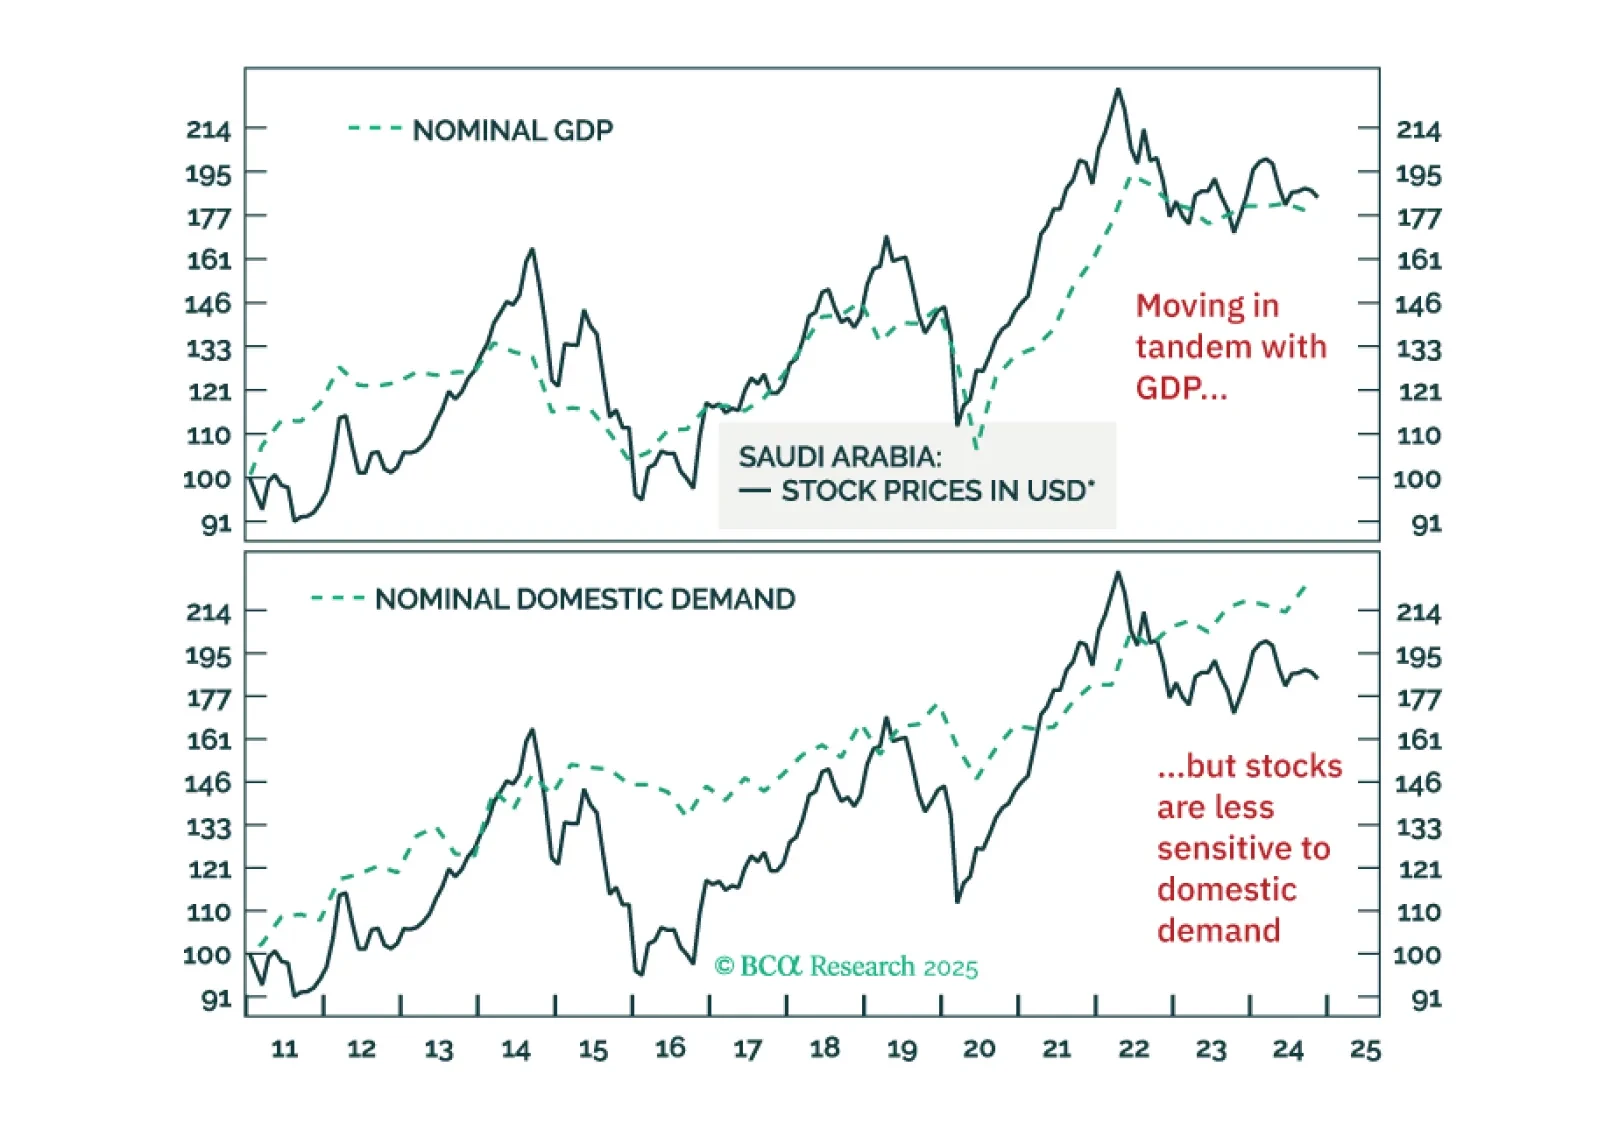
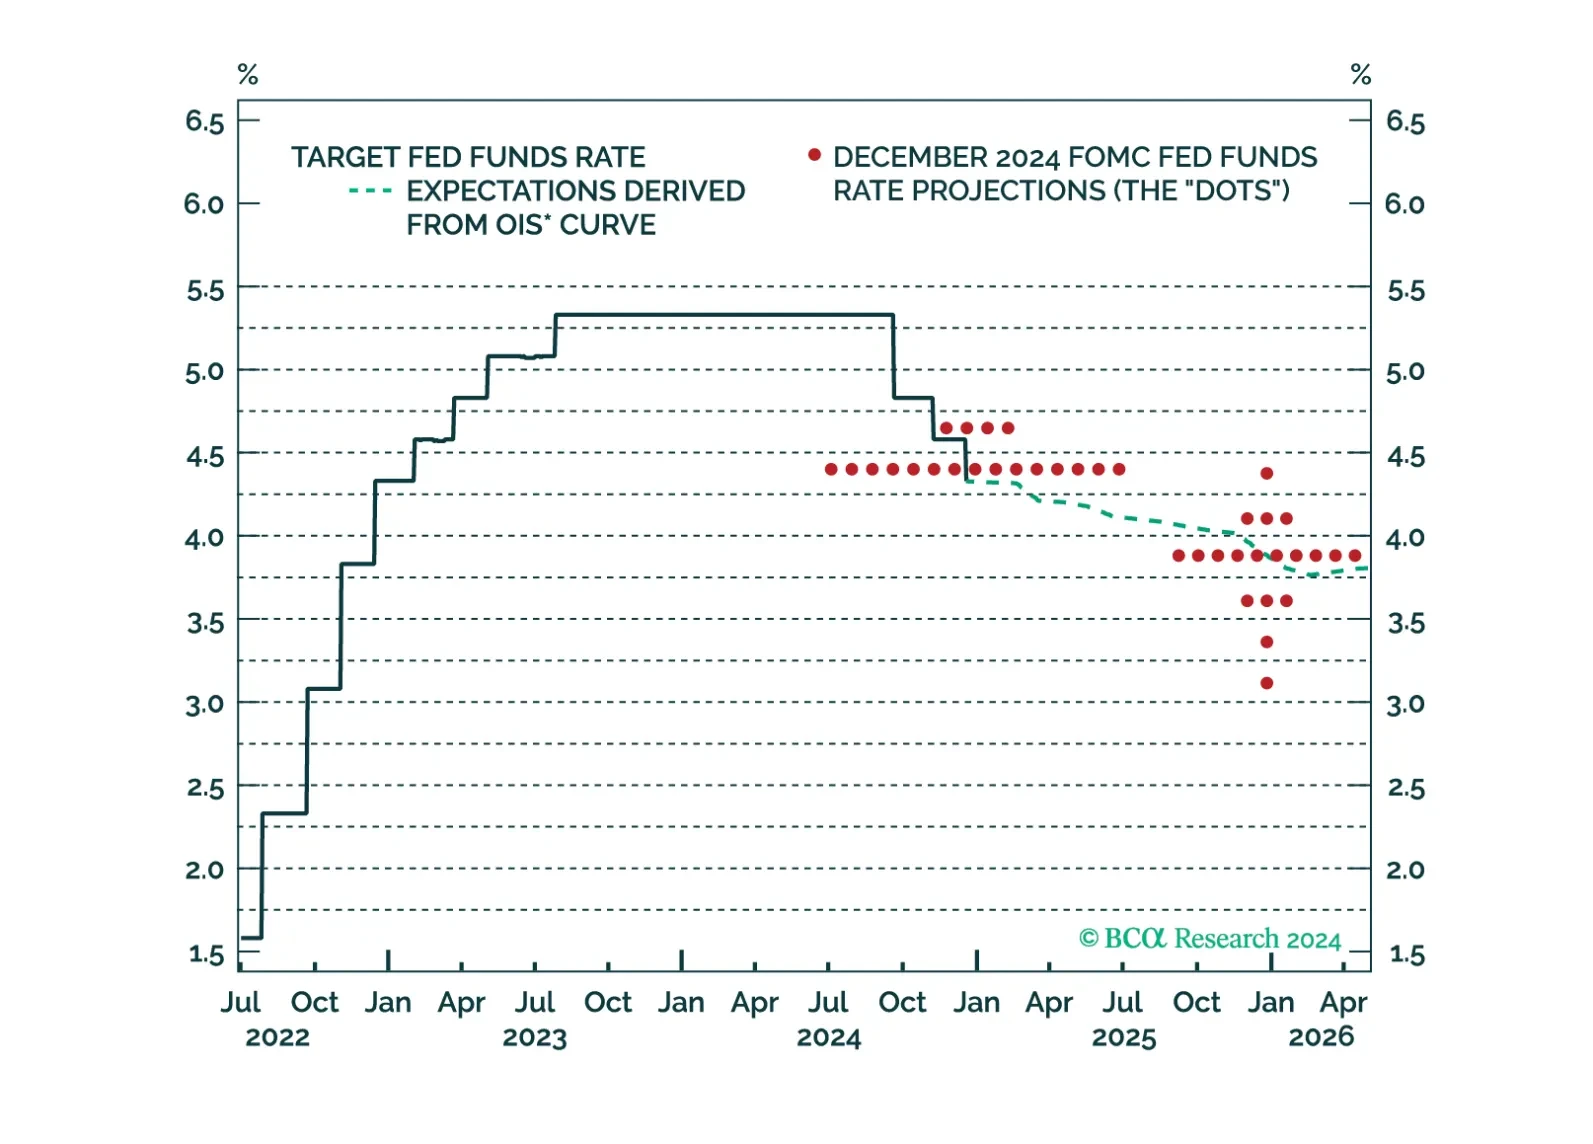
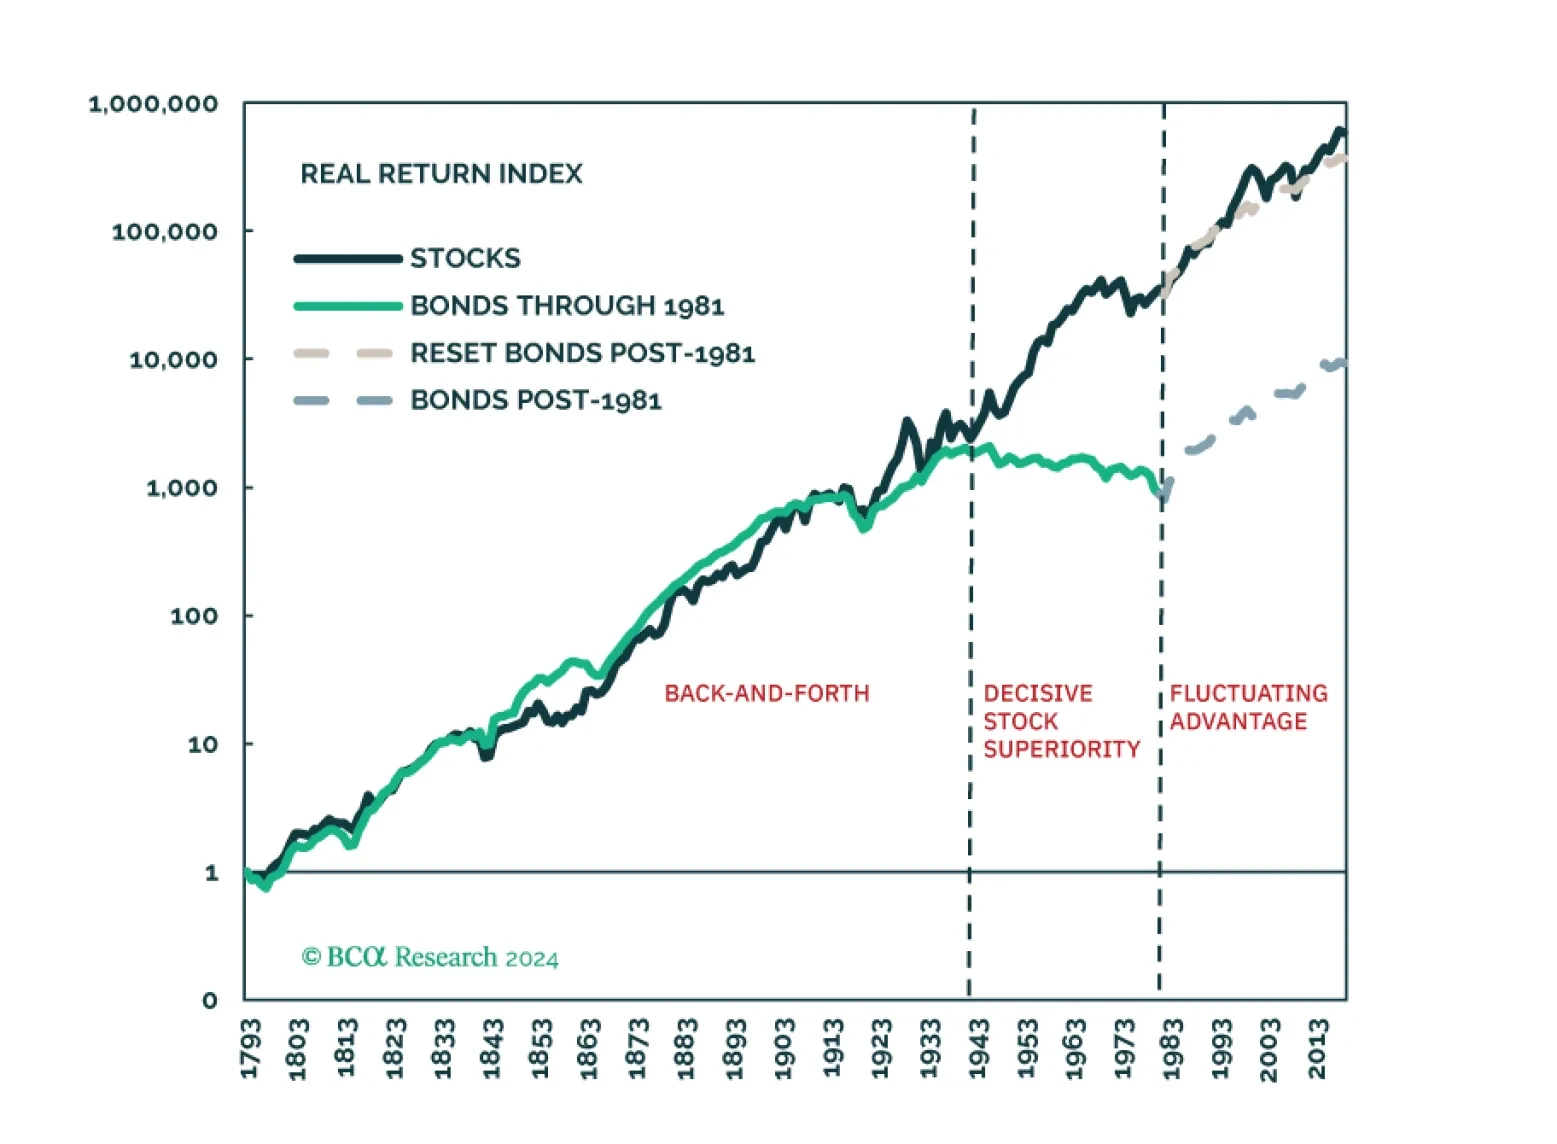
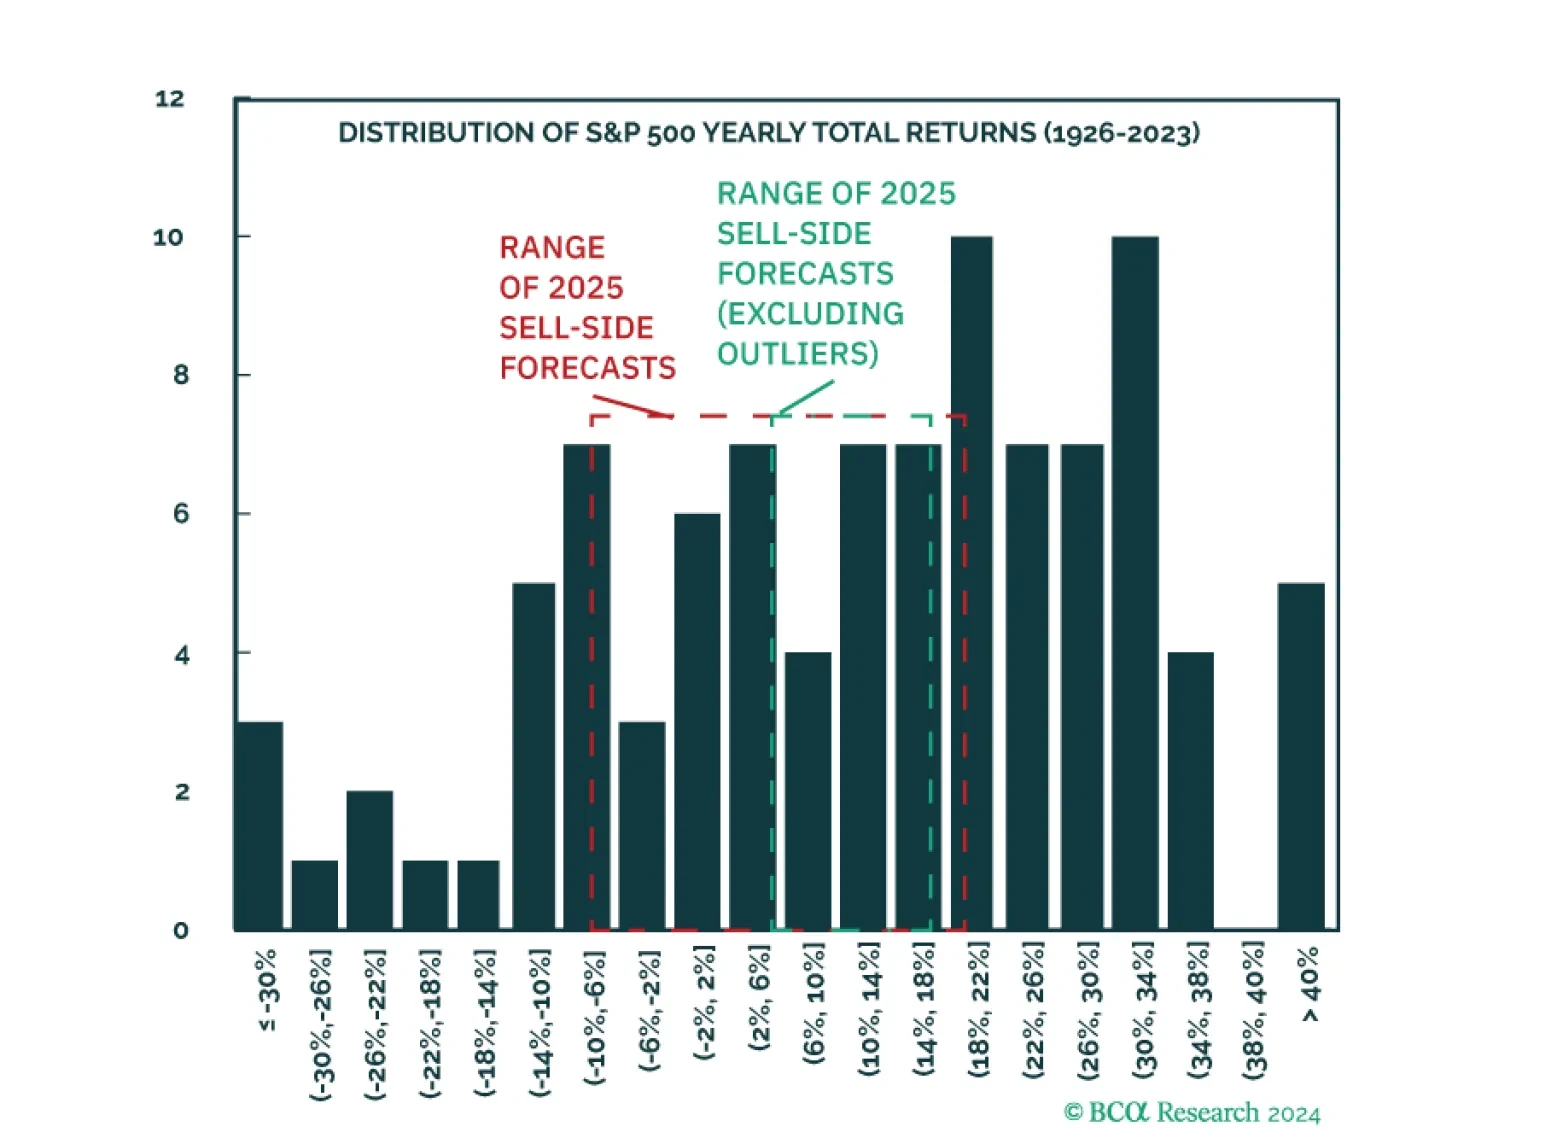
The range of forecast for the S&P 500 is too narrow. While most strategists are predicting an average year for the S&P 500, average returns do not happen often. The S&P is more likely to fall to below 5500 or rise above 7100, than to stay within the range of forecast. As a result, our negative view will either be spectacularly right or spectacularly wrong.
