Latest from BCA Research
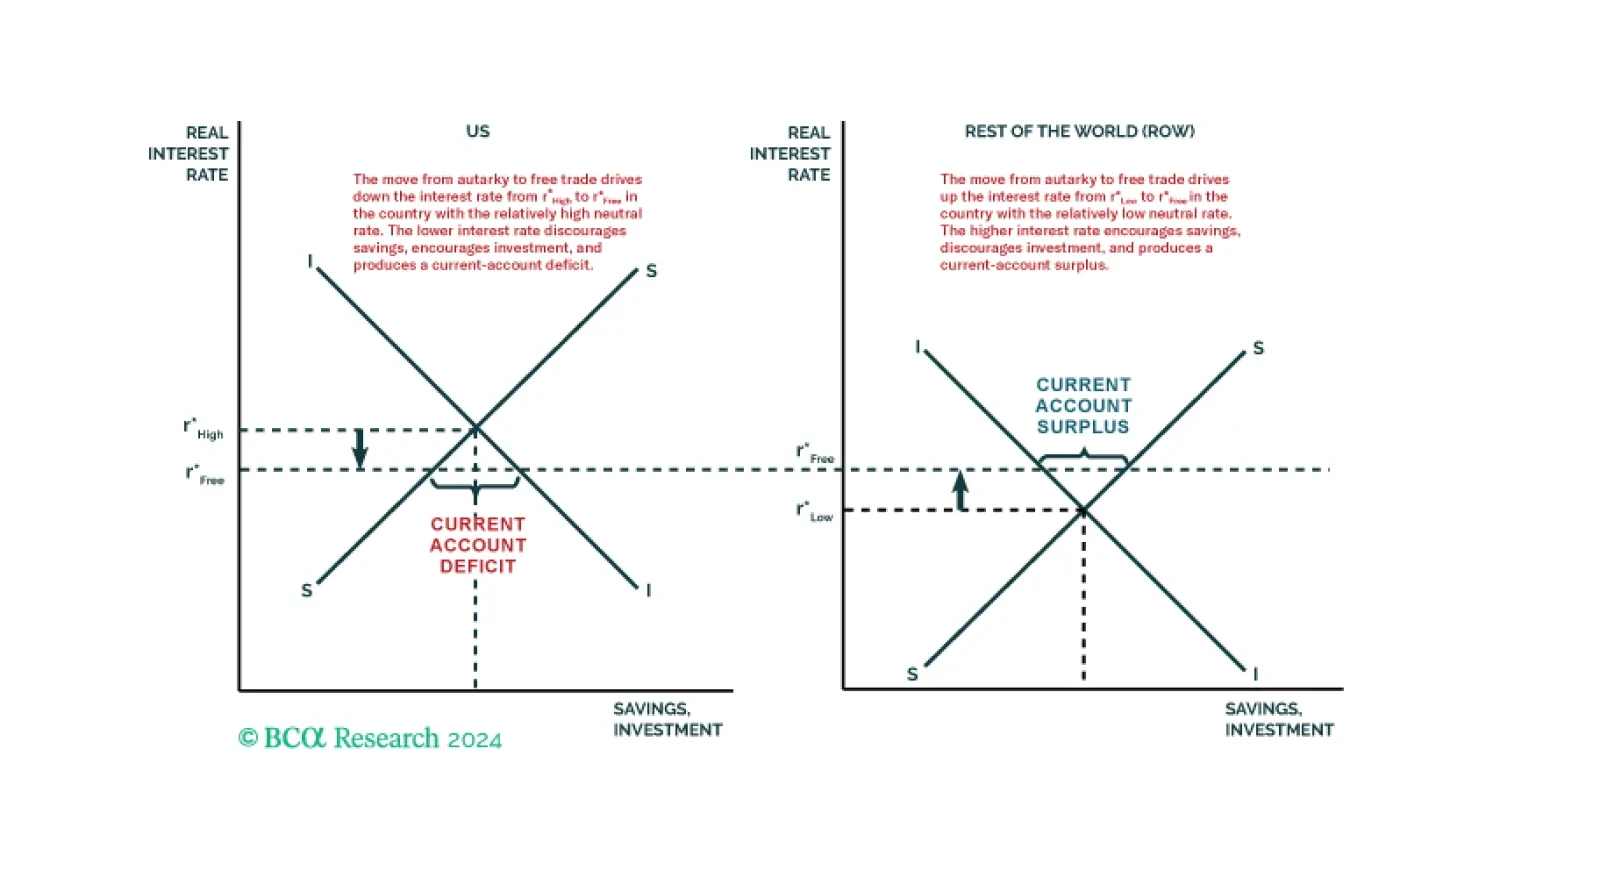

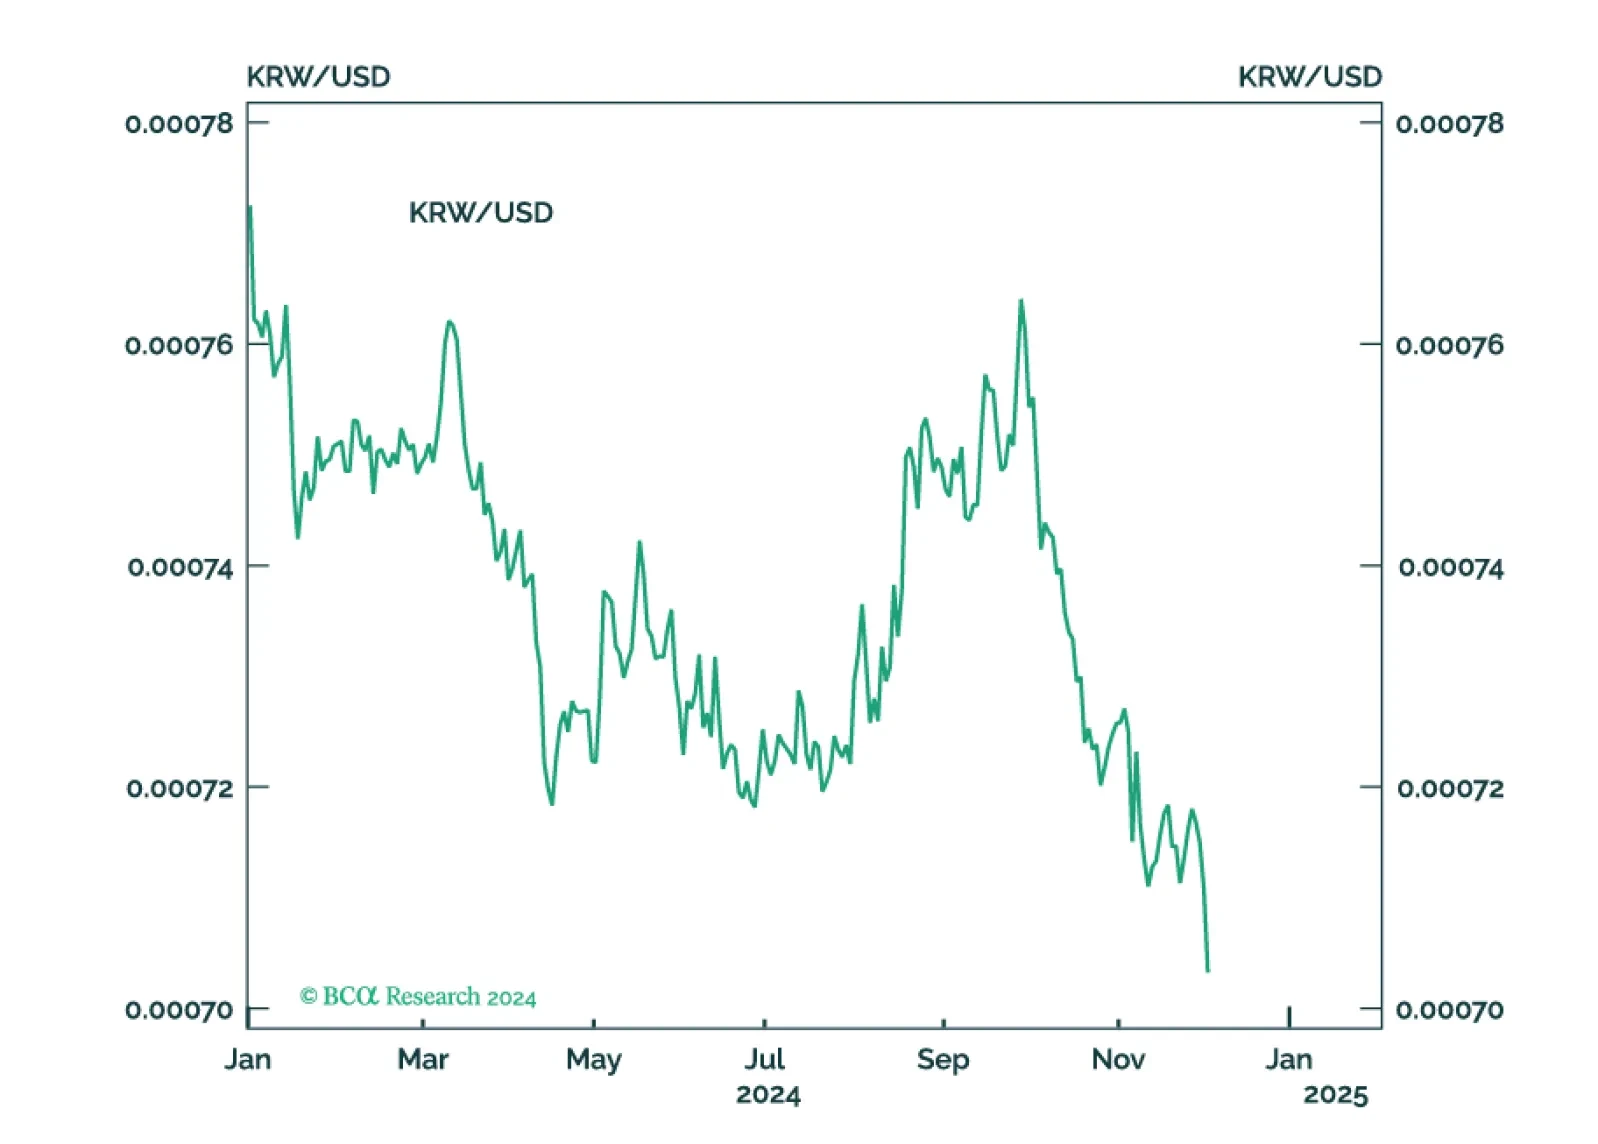
The flurry of global political instability that we expected after the US election is coming to pass. Investors should de-risk in the near term as stocks are flying high but face the turmoil of Biden's last months and then Trump tariffs.
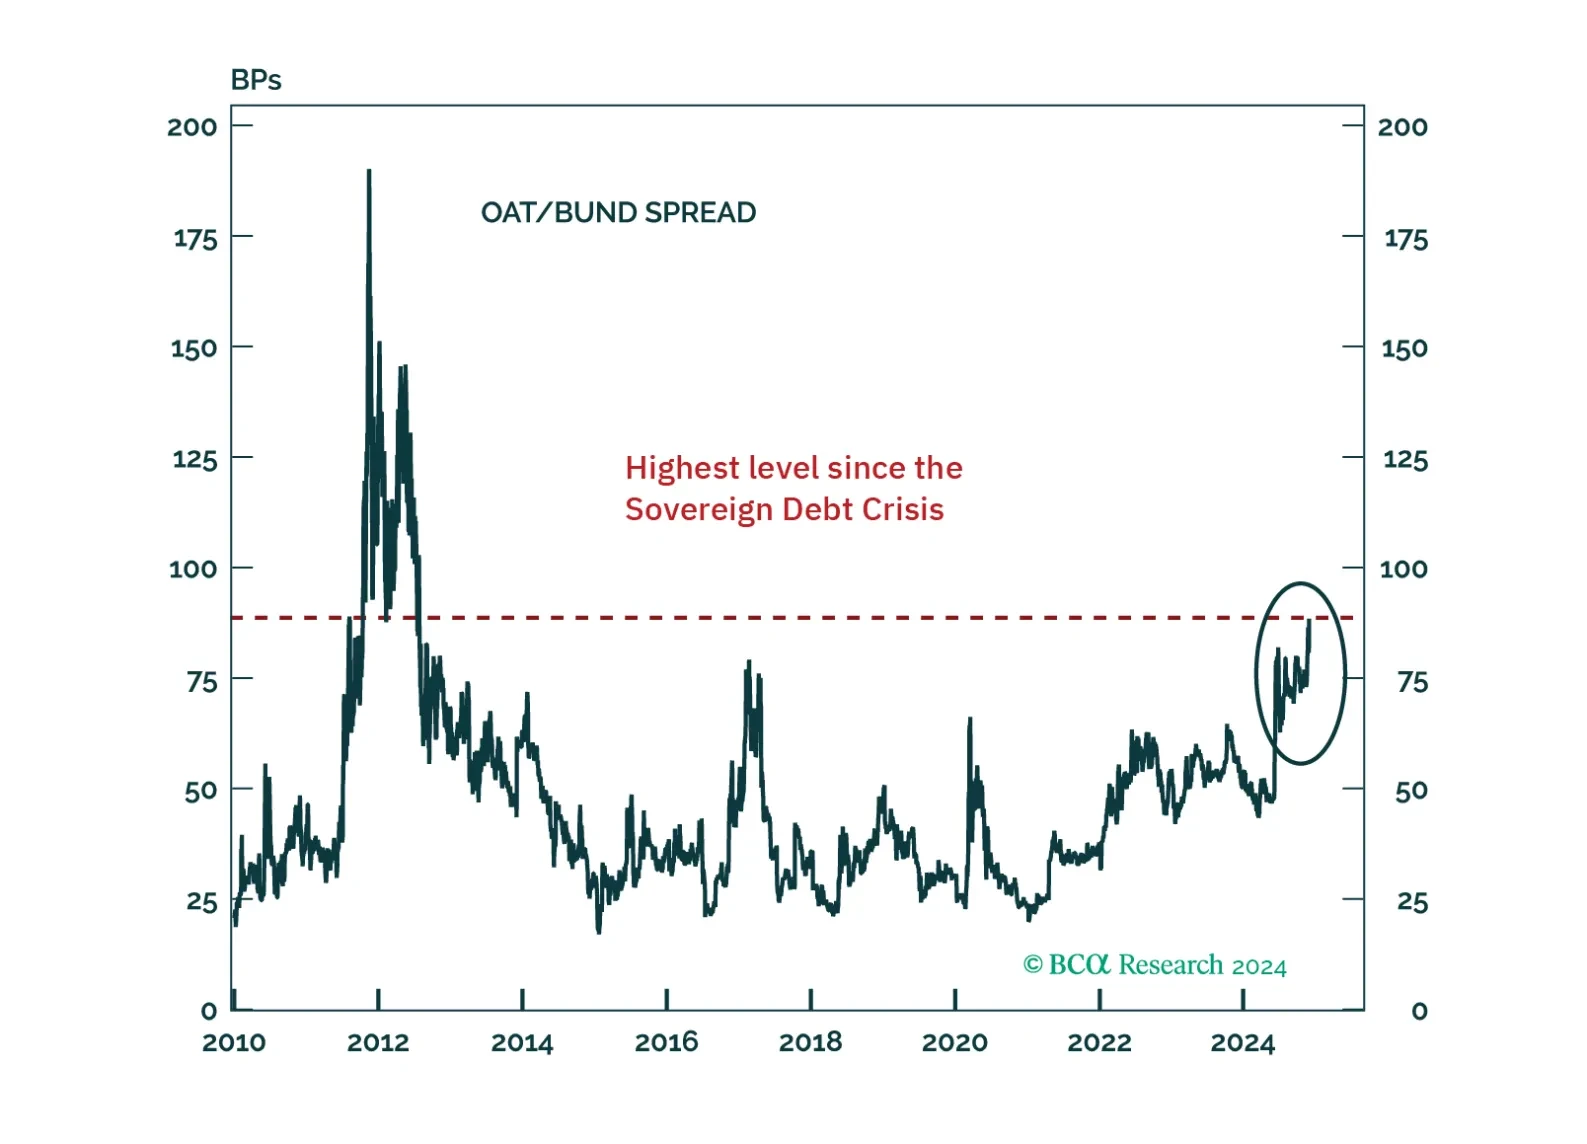
France finds itself in a unique, thorny situation. Can it heave itself out of it? And what does it mean for investors?
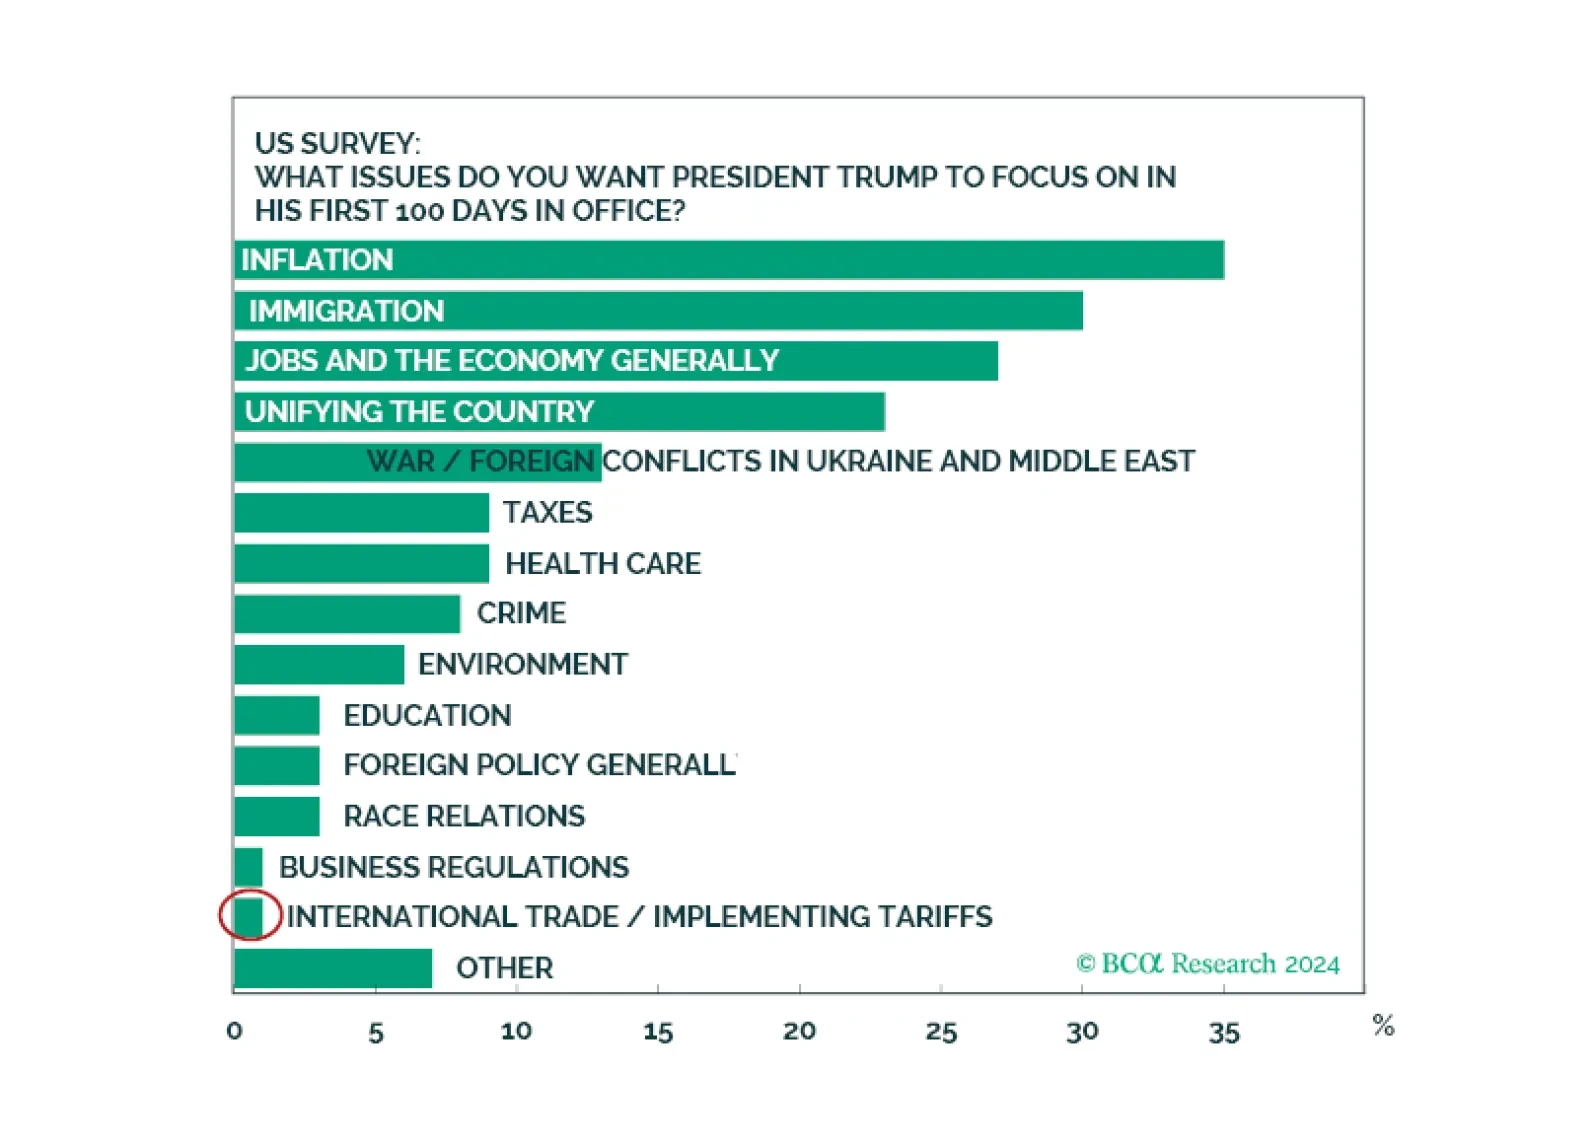
In our Alpha report, we deliver our Annual Forecast. The current macro narrative is that the US will continue to outperform the rest of the world, in large part because President Trump will again deliver fiscally led growth and global tariff carnage. In our view, 2025 will be the year of “Peaks.” Peak fiscal profligacy, peak de-globalization hysteria, and peak geopolitical risks. All three will reverse US Exceptionalism. But getting ahead of that trade is folly. For the time being, we concede that it is “America First” on all fronts. Particularly with the Greenback being a momentum currency.

Investors have given up on European assets, which now suffer exceptional discounts to US ones. However, tighter US fiscal policy, the end of Europe’s austerity and deleveraging, the LNG Tsunami about to hit European shores, and the global capex fueled by the Impossible Geopolitical Trinity mean that Europe’s time to shine will soon come back.
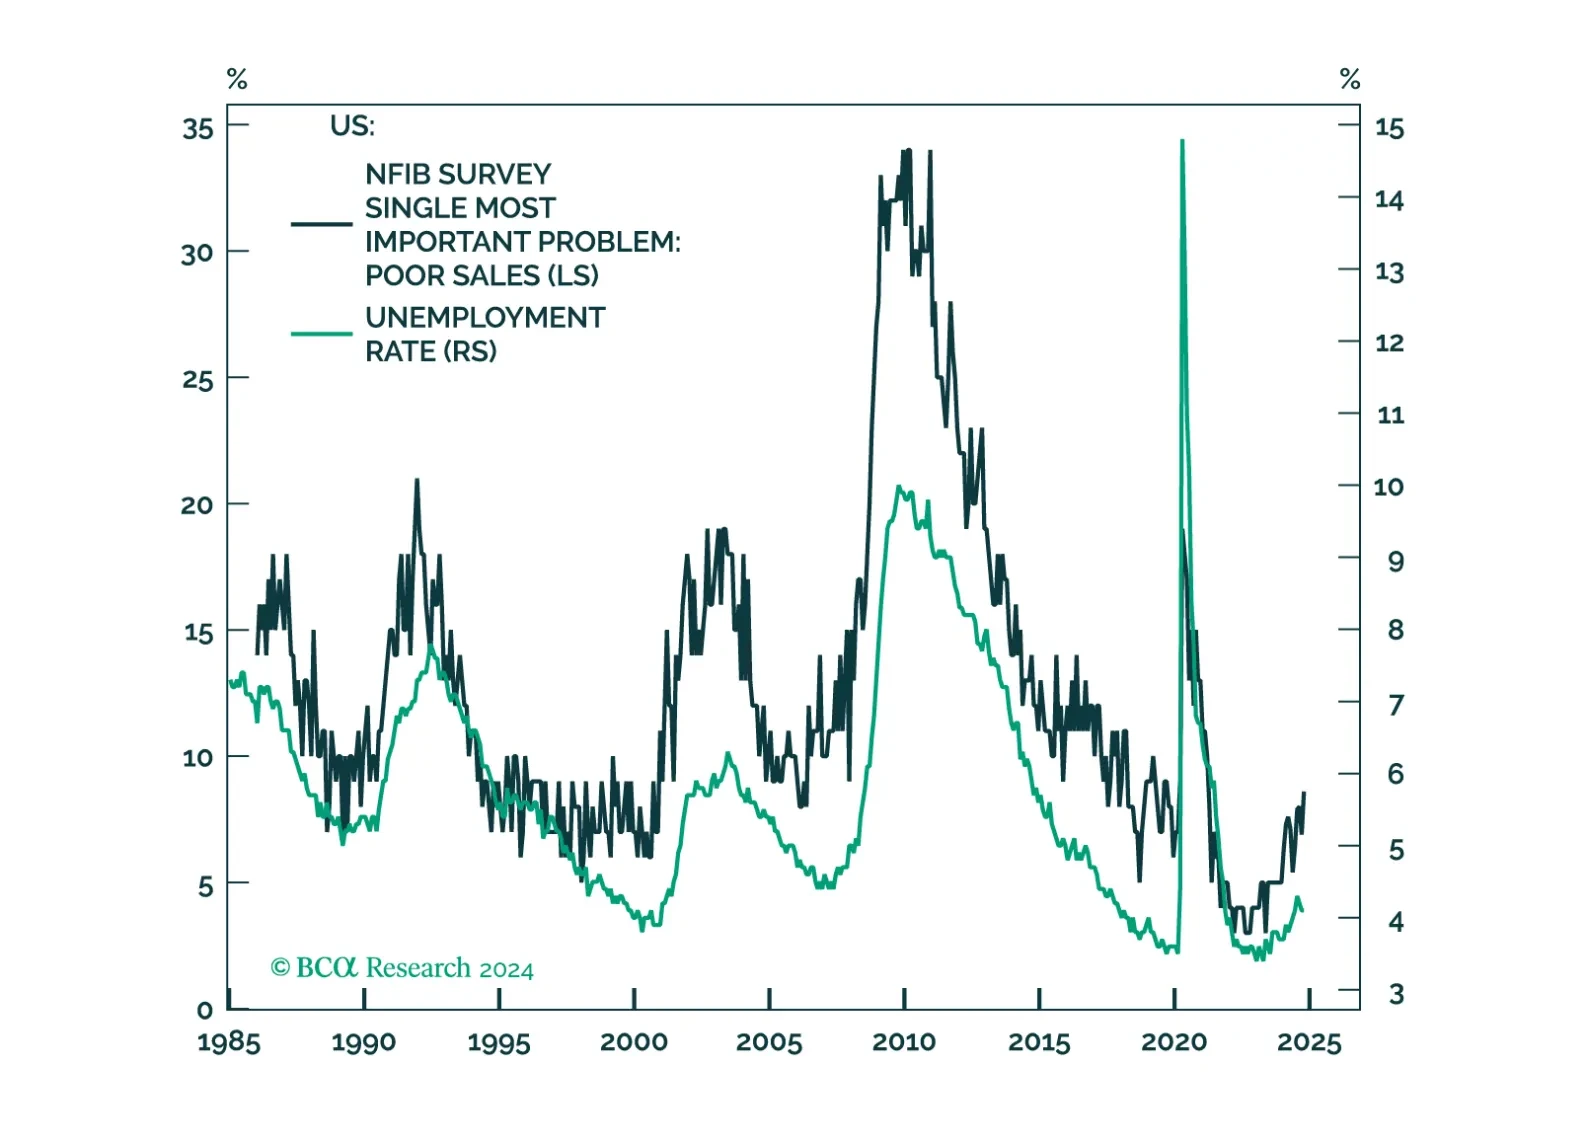
The post-COVID recovery has been one of excesses. Government deficits have ballooned, tight labor markets have led to a windfall of consumer spending, and equity valuations have soared on the back of lofty growth expectations. But these excesses will no longer be sustainable in 2025. Our theme for next year is Thin Is Back In. Government budgets, economic growth, and equity valuations will be leaner than investors expect. We discuss this the reasoning behind this macro view and the asset allocation implications that follow from it.
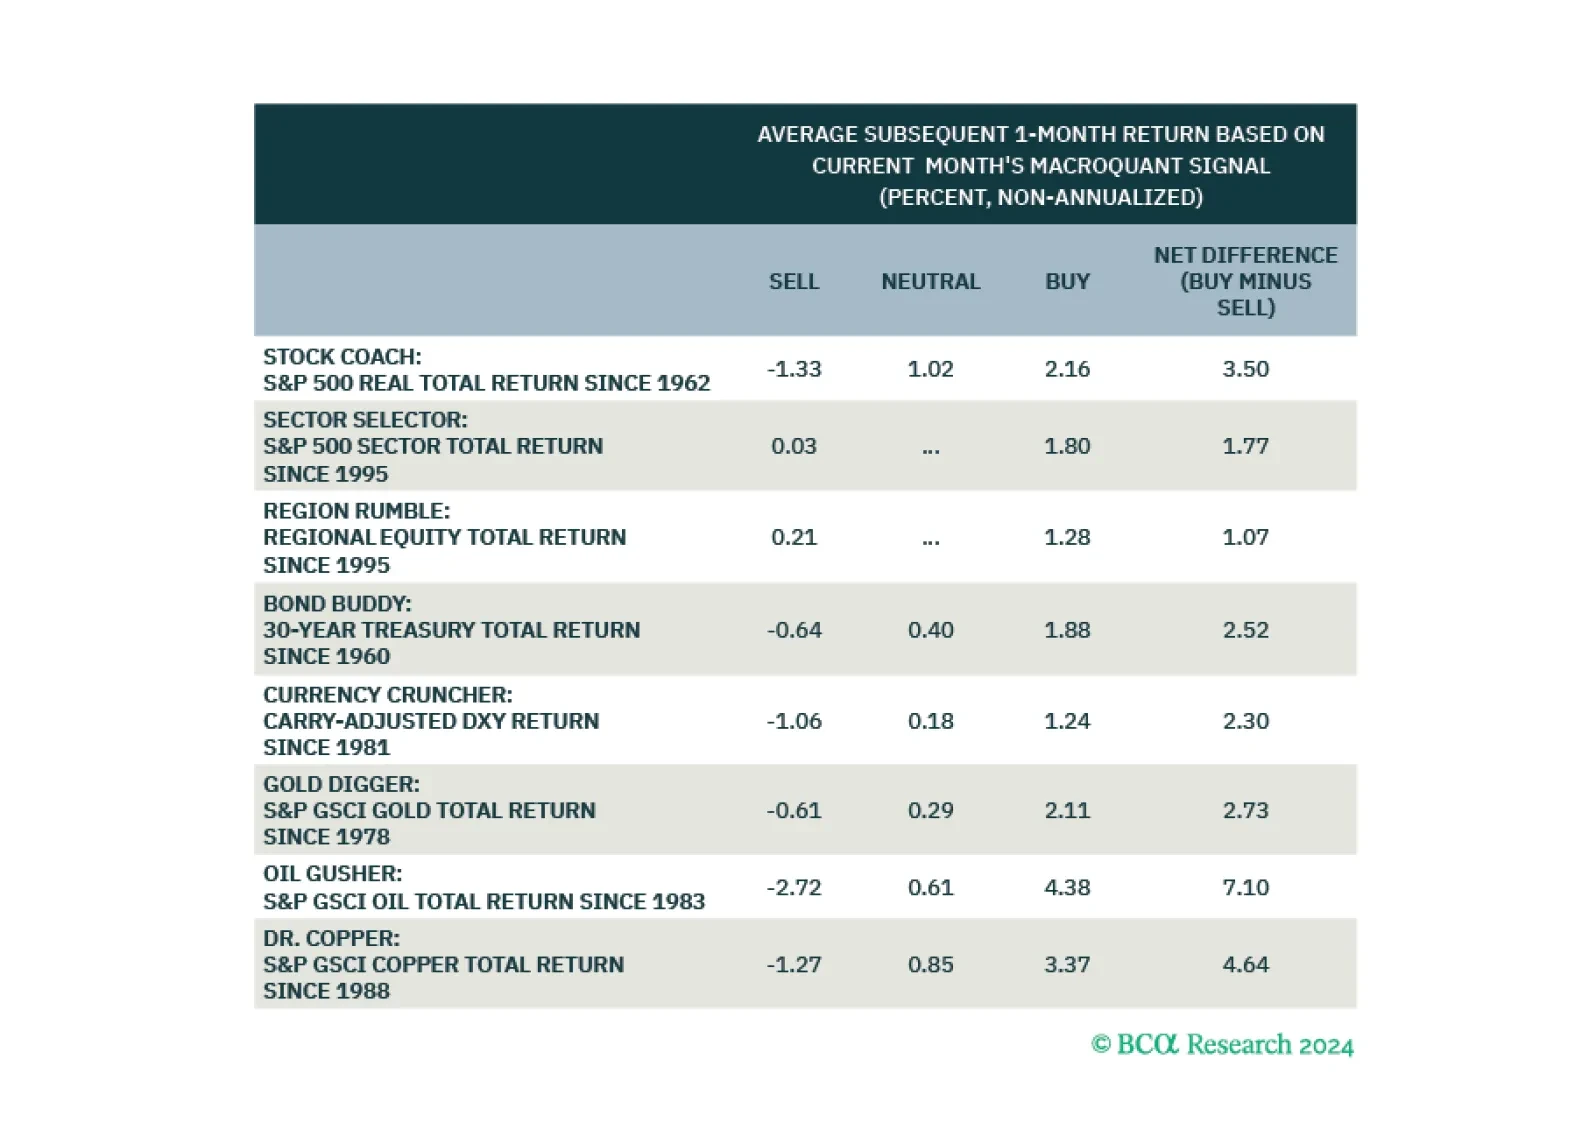
Today, we are unveiling an update to our MacroQuant model. The latest version of the MacroQuant model sees downside risk to stocks going into December and recommends increasing duration exposure in global fixed-income portfolios.

Today, we are unveiling an update to our MacroQuant model. The latest version of the MacroQuant model sees downside risk to stocks going into December and recommends increasing duration exposure in global fixed-income portfolios.