Latest from BCA Research
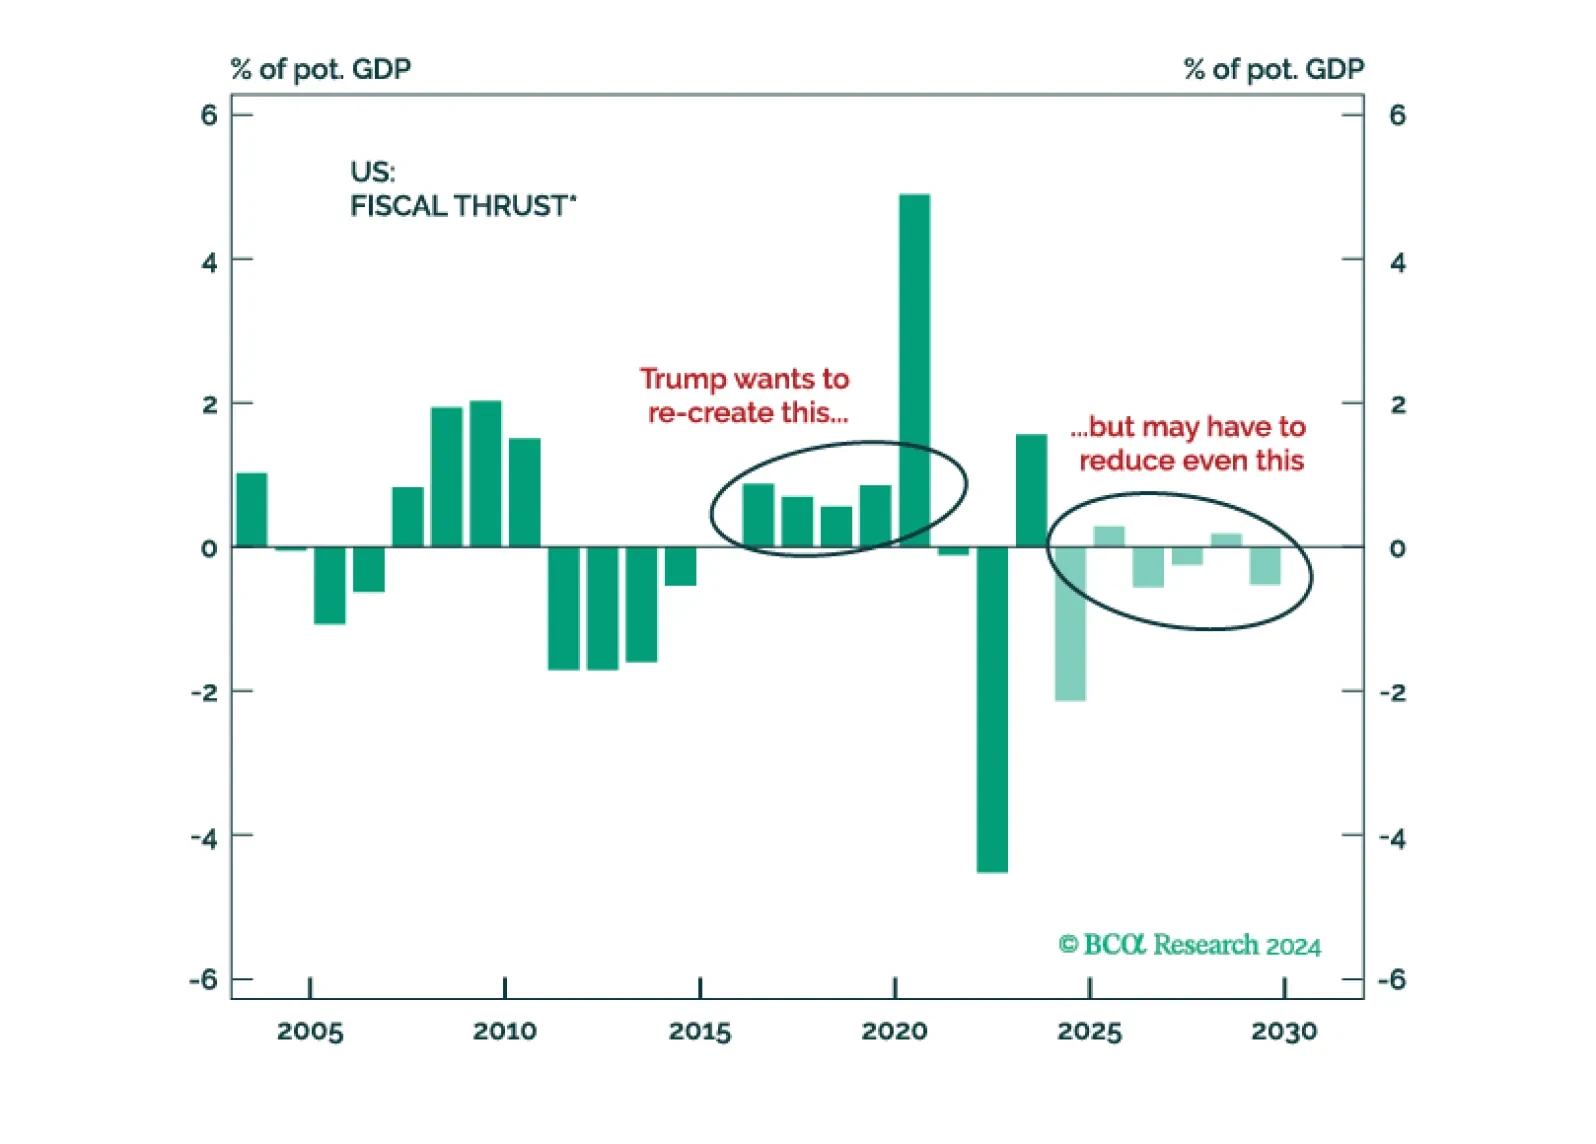
The month of November has brought us S&P 6,000! President Trump has won a “Red Sweep” (as we expected all year) and has ushered in a regime change in America. For now, we are open to chasing momentum. However, the biggest risk to the market are bond yields, which should rise as investors start to price President Trump’s policies and their impact on deficits.
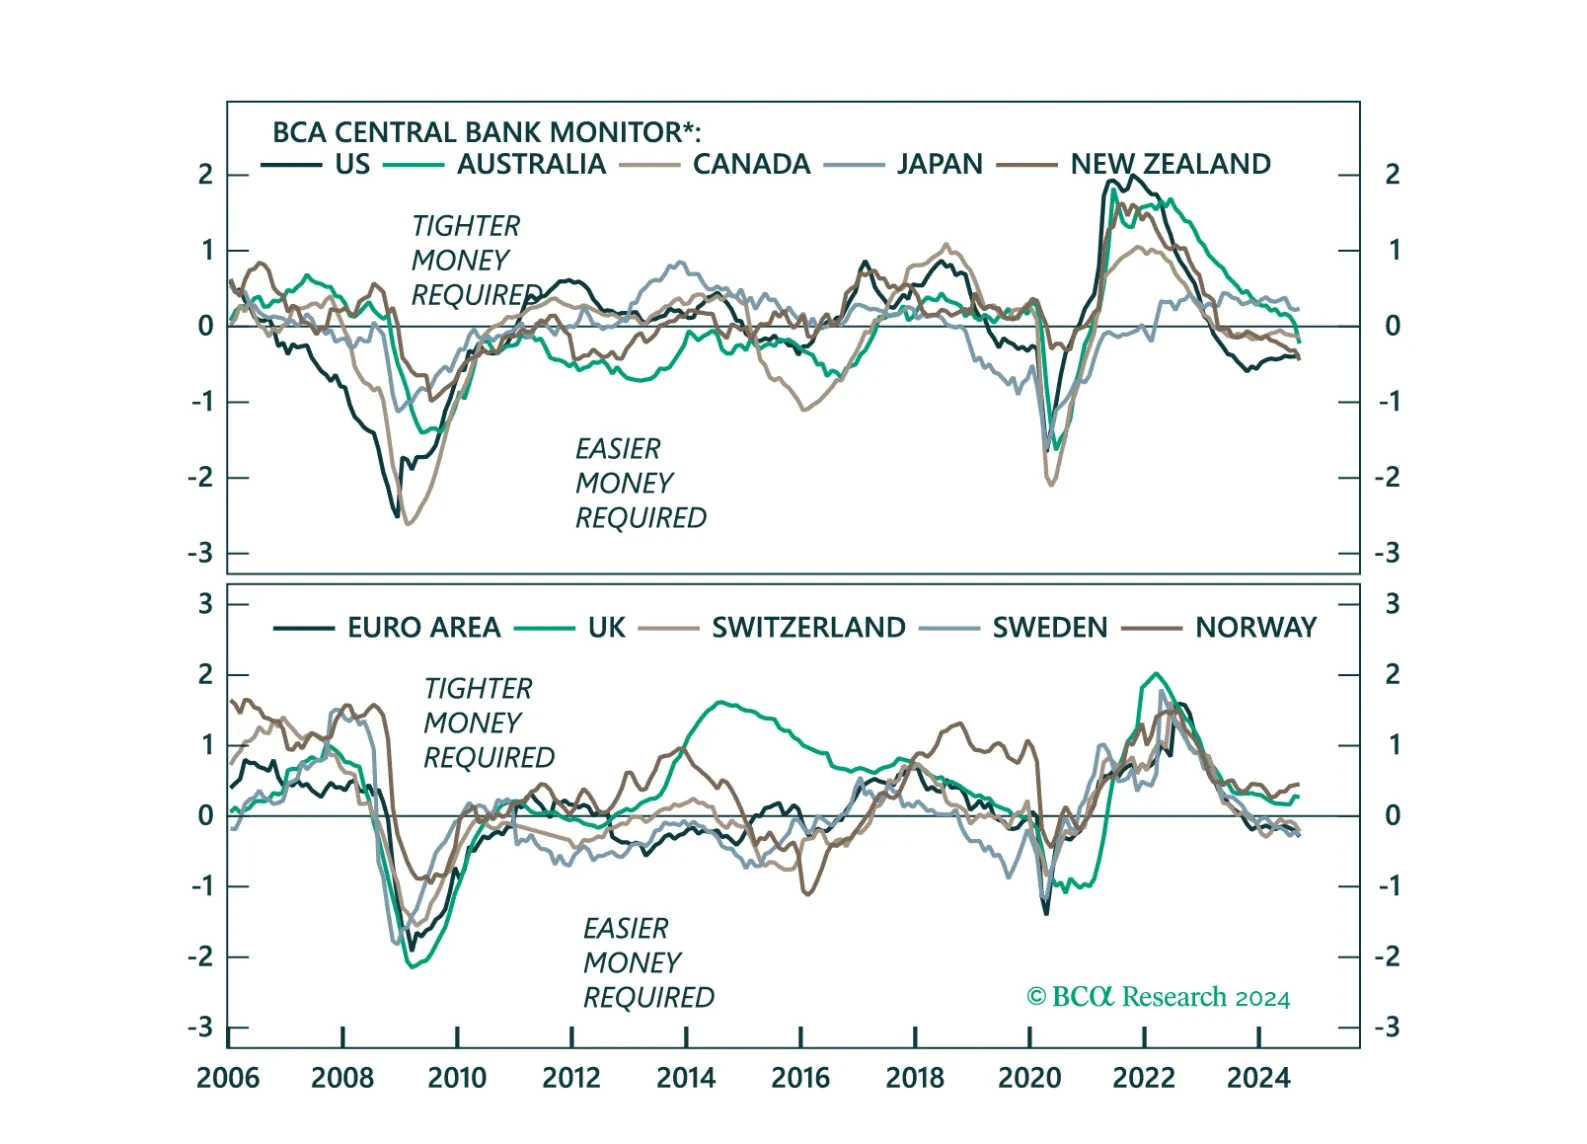
This week, we update our Central Bank Monitors (CBMs), that help us calibrate how monetary policy should be adjusted in developed-market economies. Our conclusion is that while overall, easier monetary settings are required, there a few trade ideas that arise from the divergences in signals amongst G10 countries.
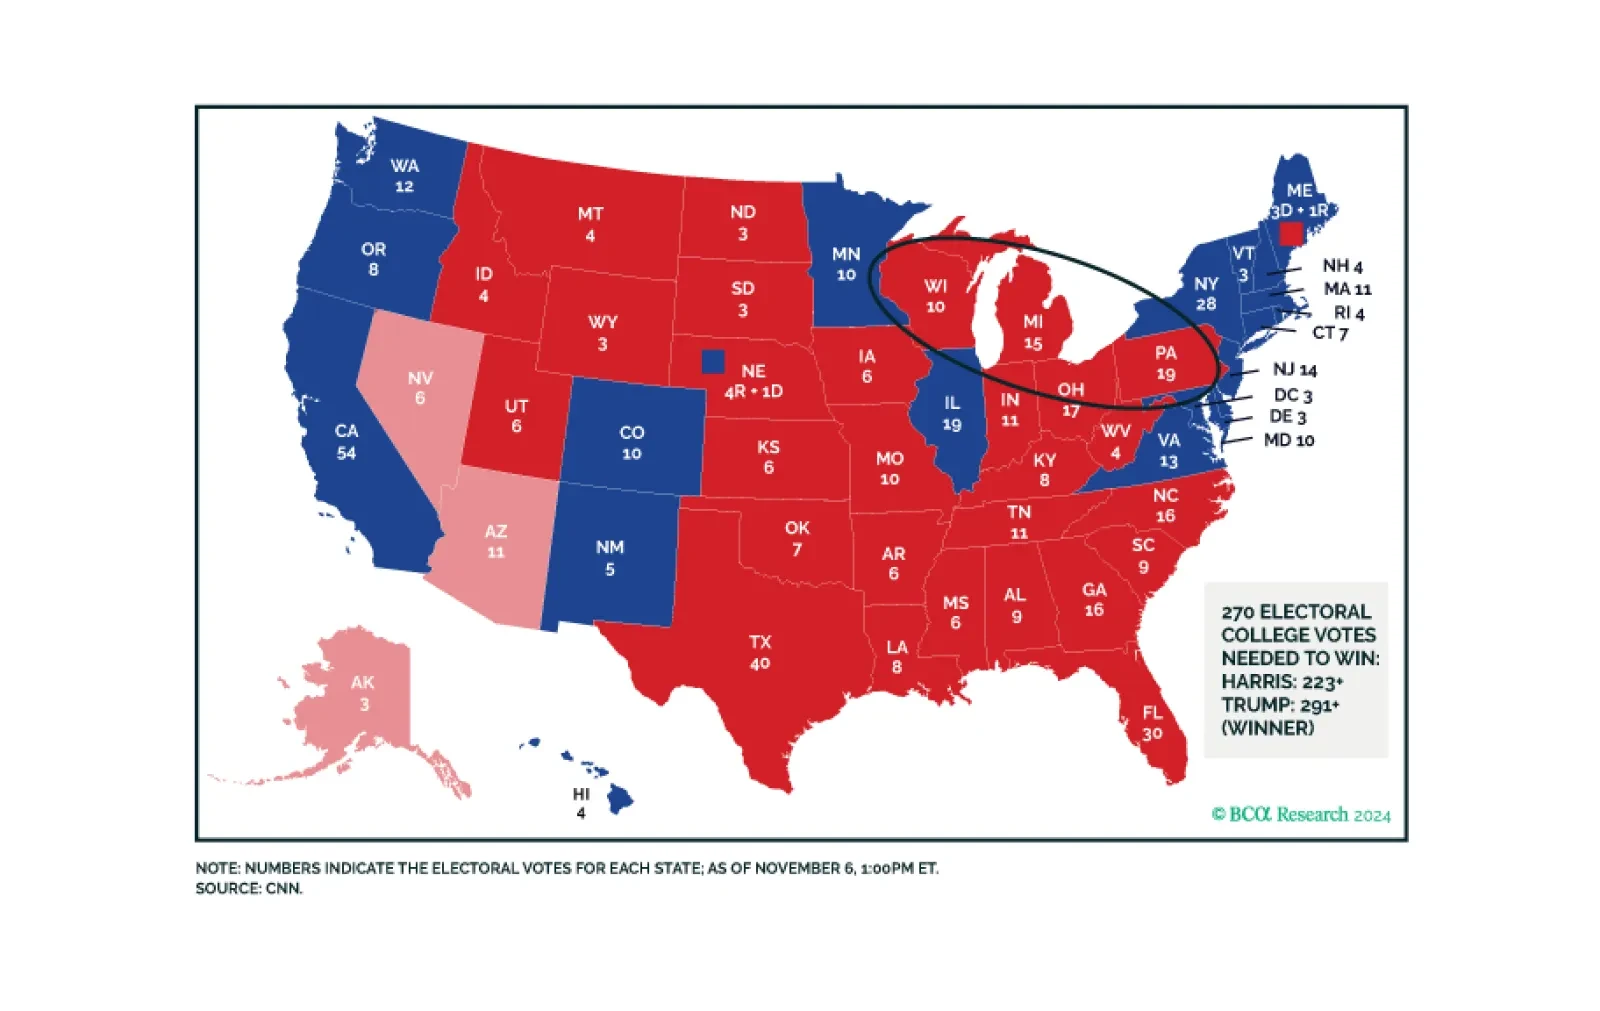
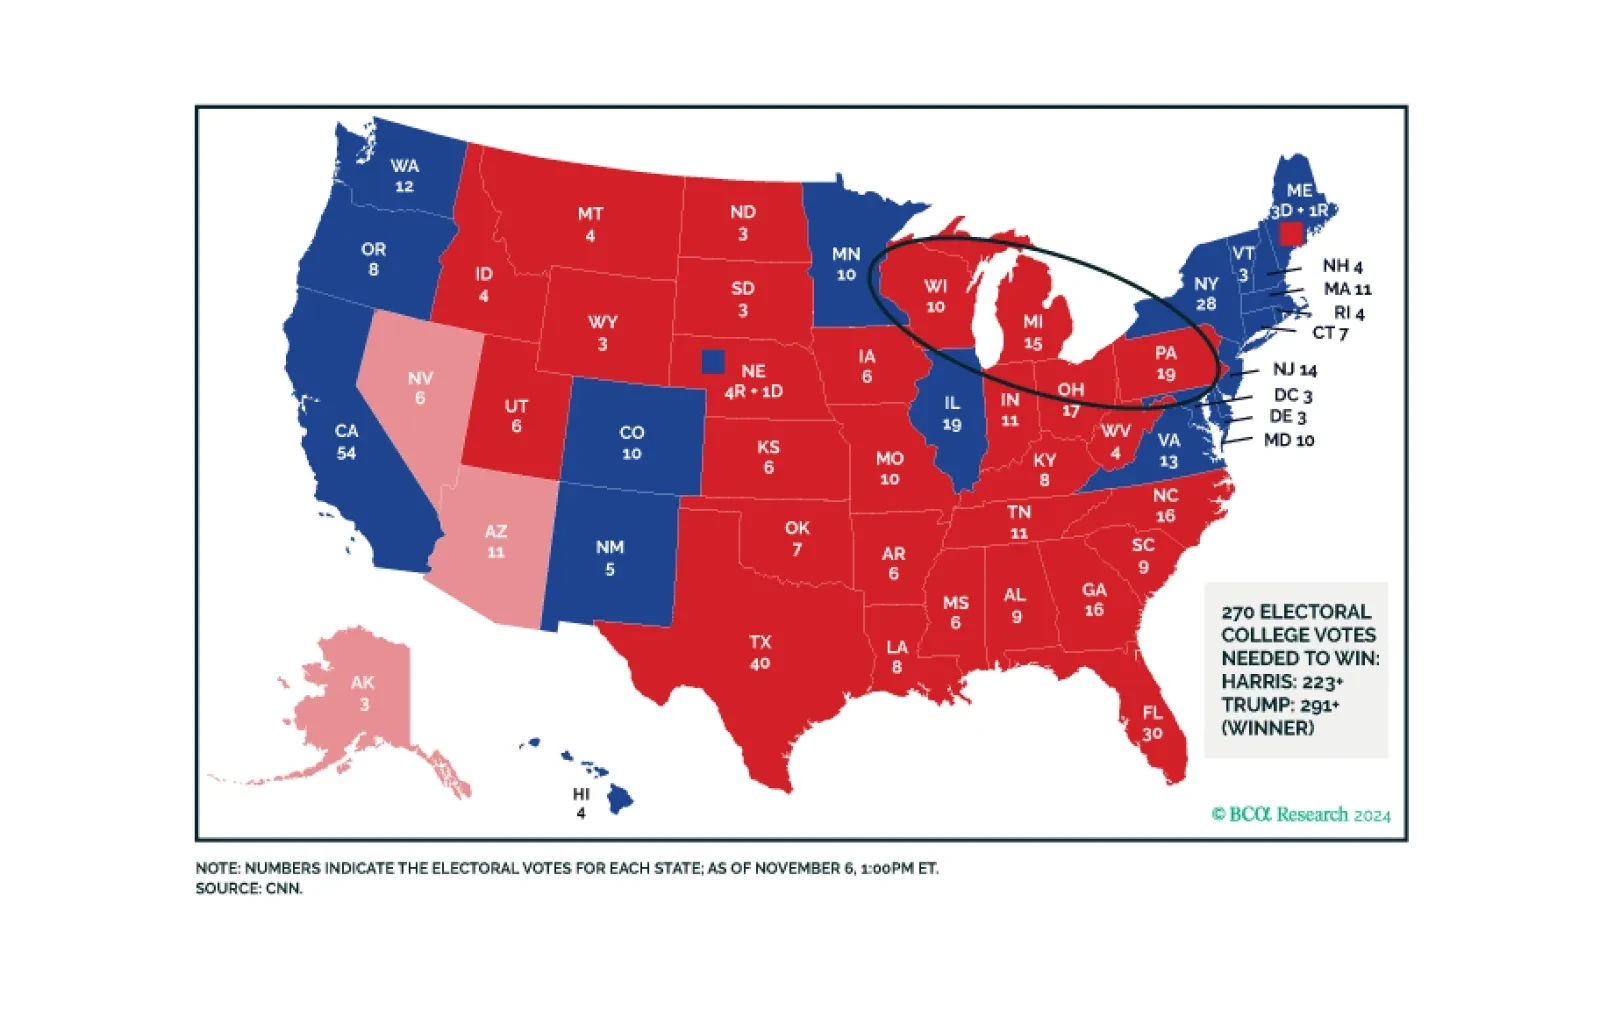

The market is celebrating the prospect of deregulation, lower taxes, and Fed rate cuts, for now ignoring the dangers of wider budget deficits, inflationary pressures, and trade wars. The rally can continue into the year-end and reduced uncertainty, seasonality, and positive momentum will benefit recent laggards such as Small, Value, and Cyclicals. We downgrade Energy from overweight to underweight. We downgrade Telecoms and Consumer Staples to underweight. We upgrade Insurance from underweight to overweight. We upgrade Utilities to overweight.
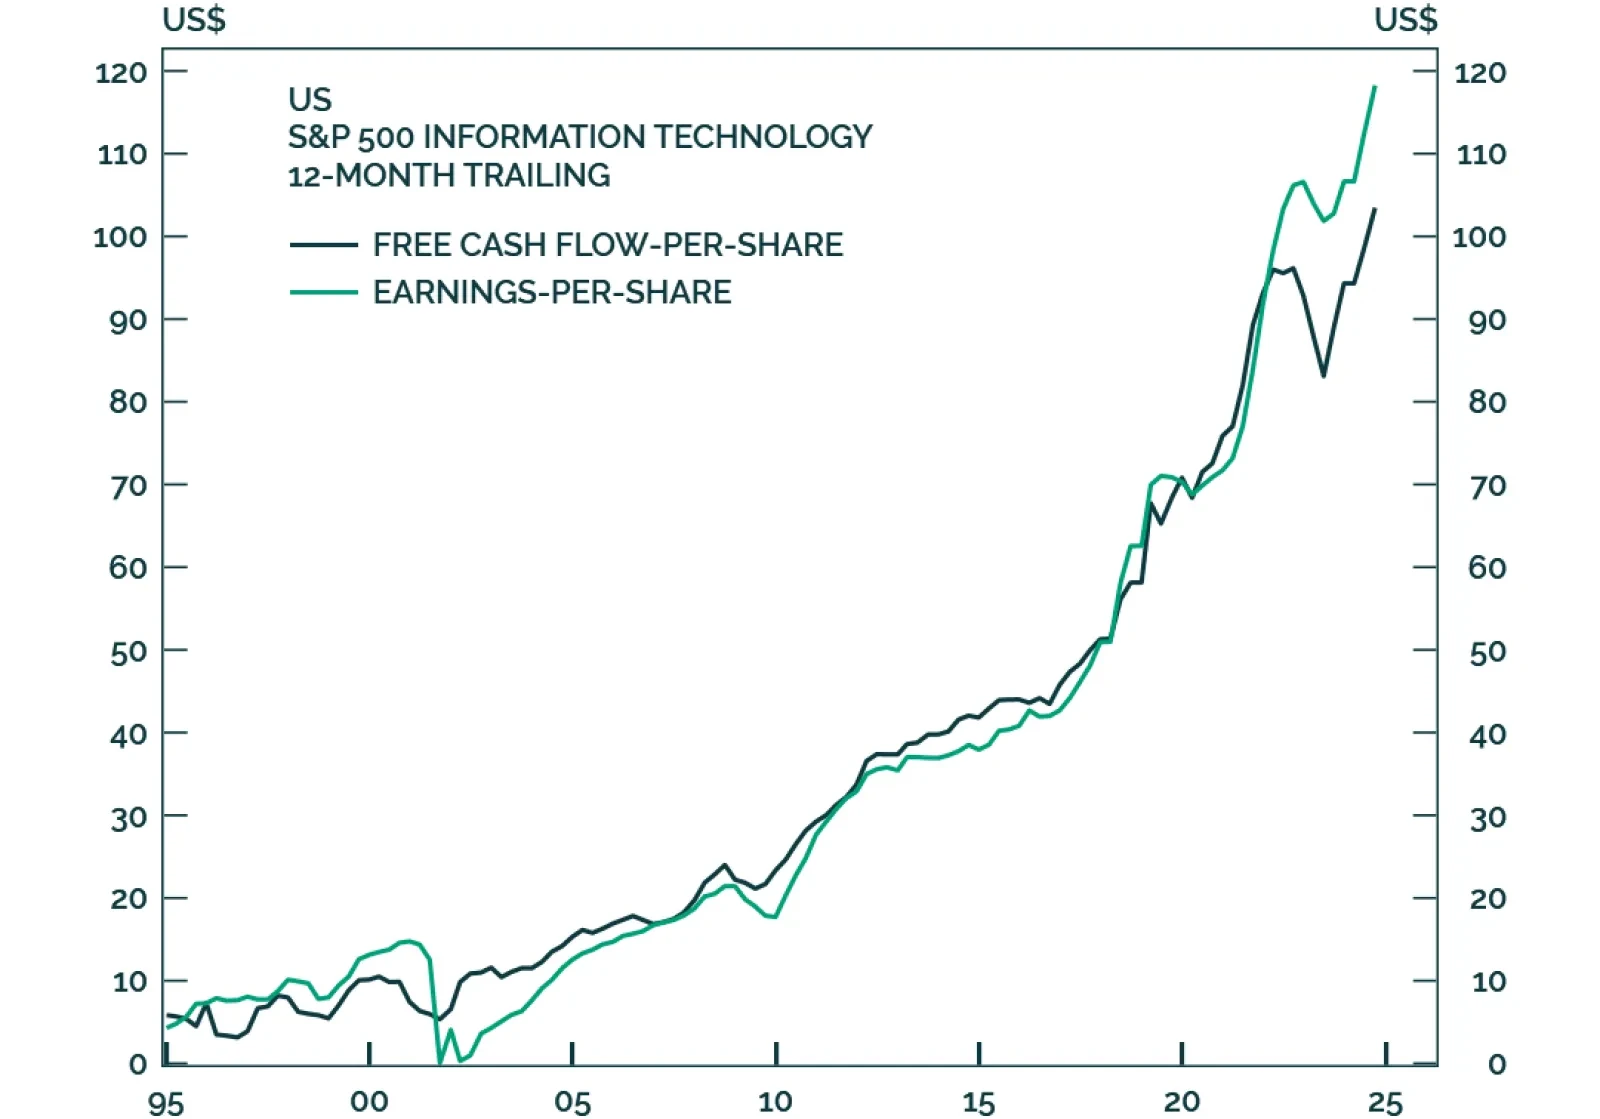
Since the end of 2021, EPS for the S&P 500 Information Technology sector has grown by 29%. In contrast, free cash flow-per-share has grown by only 11%.
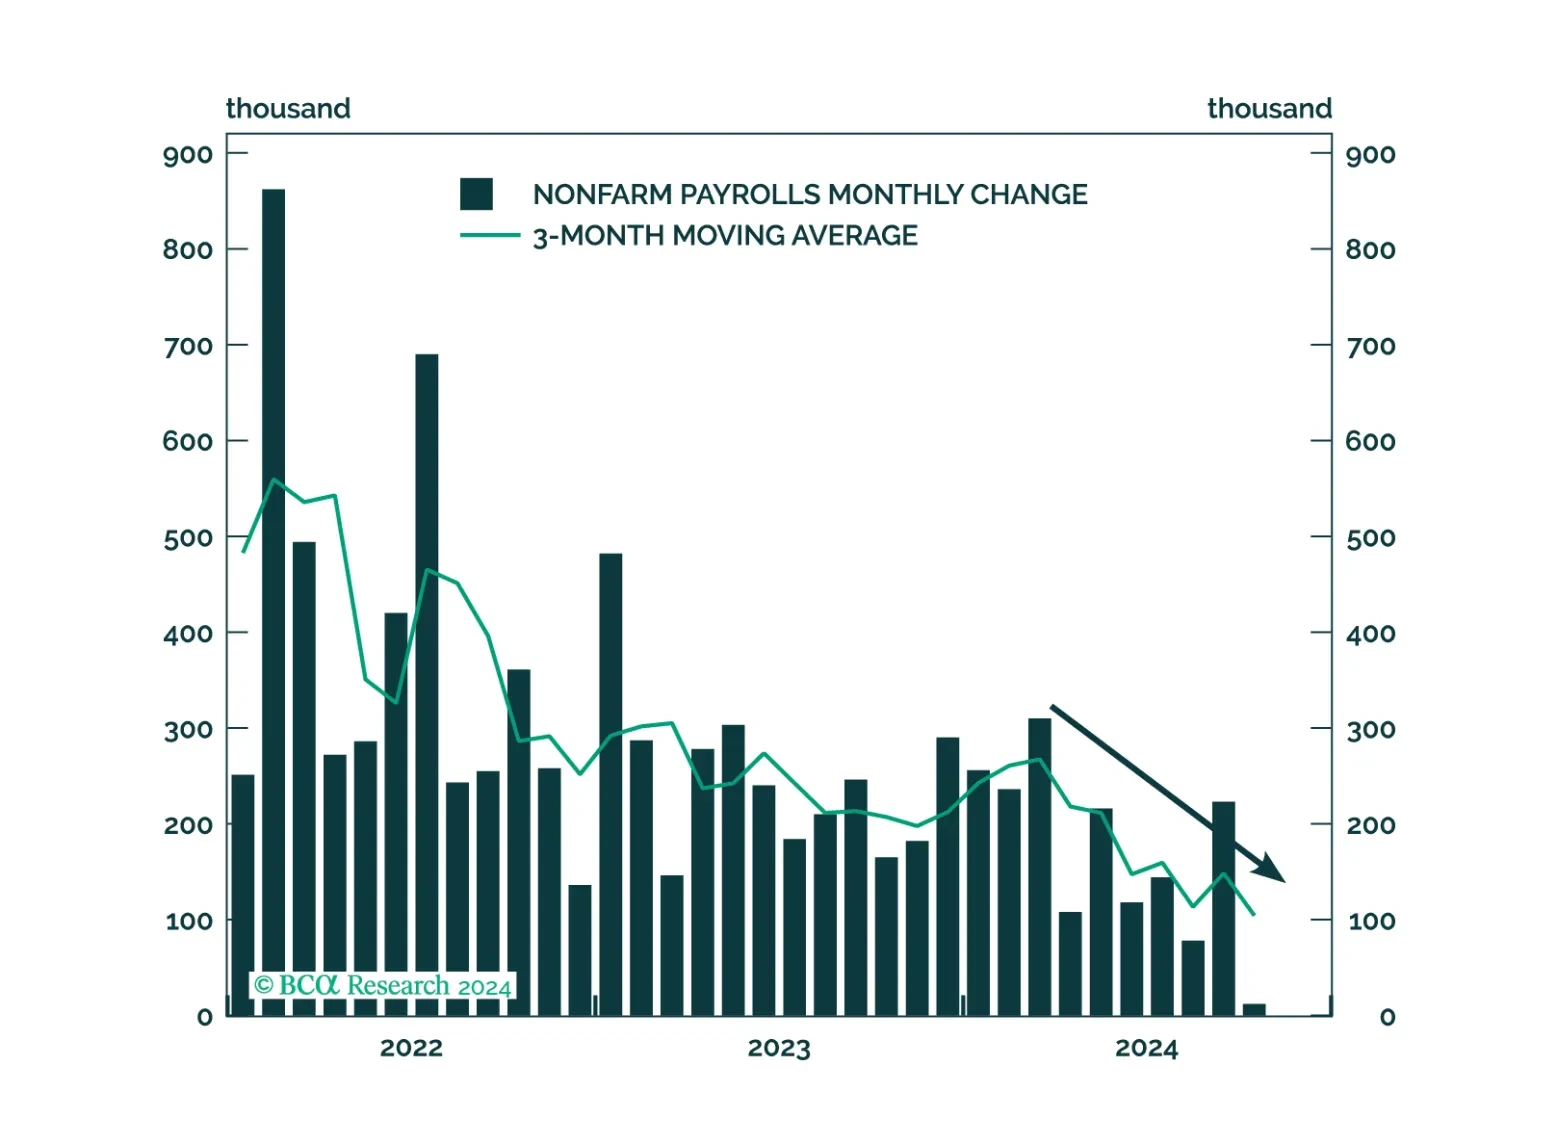
The force of the post-election momentum leads us to believe we could be stopped out of our defensive positioning before the week is out, but we still believe in our recession call. If we are eventually stopped out, we will seek a more opportune entry point to bet against risk assets once the election fever runs its course.
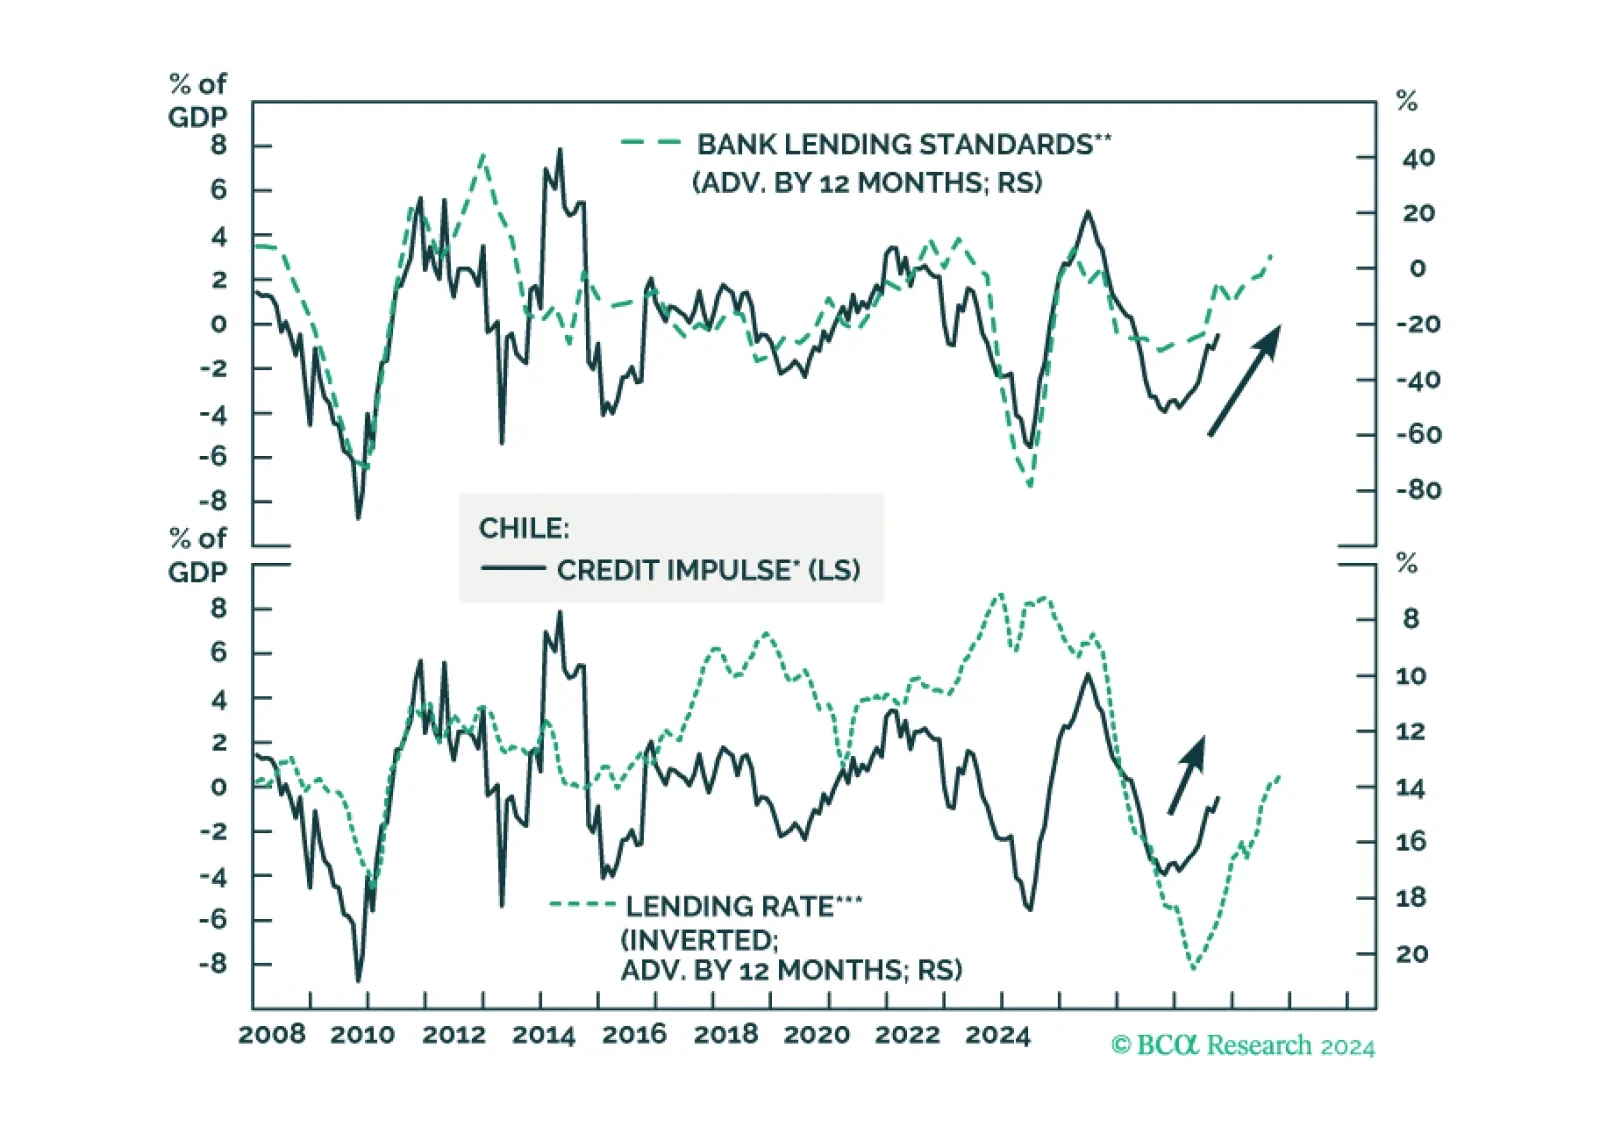
In absolute terms, Chilean markets and the currency will fall given a strengthening trend in the US dollar and weak global trade. However, Chile’s economy can withstand the global trade slump relatively well due to substantial monetary easing at home, which will help Chilean markets outperform EM peers. Moreover, a favorable and improving political backdrop and attractive valuations will benefit Chilean equities and the peso versus their EM counterparts.
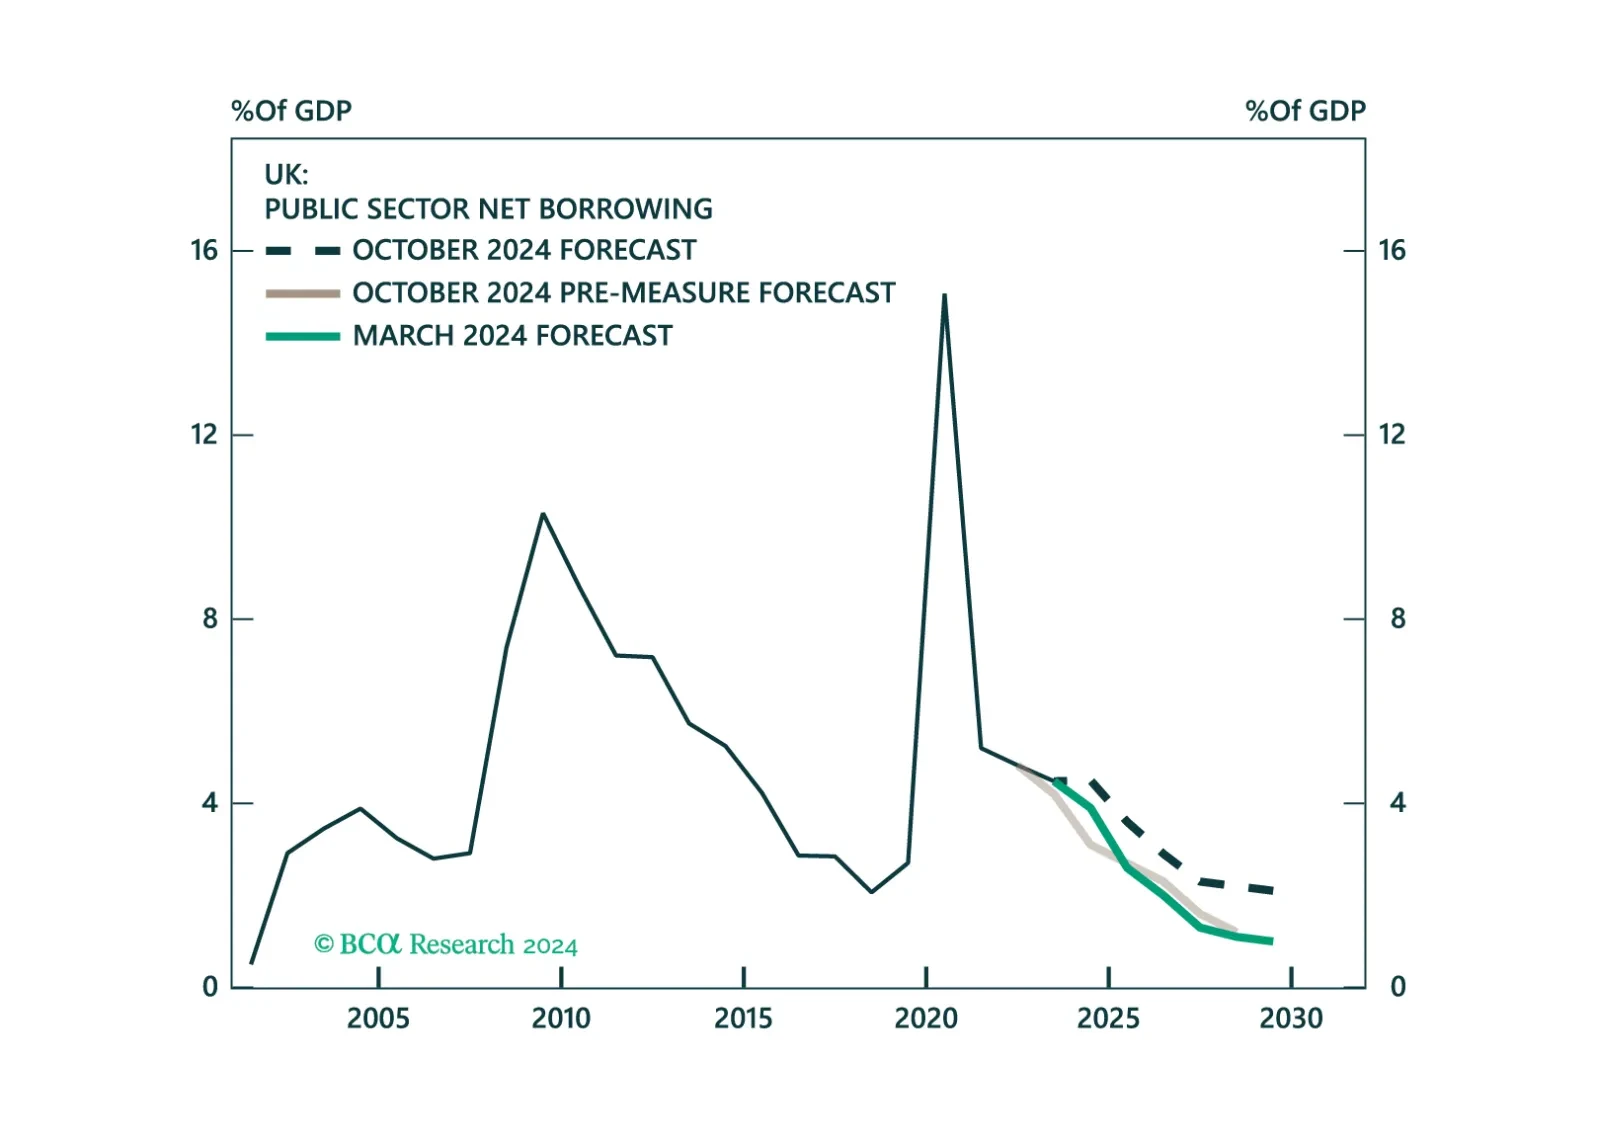
This Strategy Insight presents our view on today’s rate cut by the Bank of England as well as the budget announced by the UK government last week.