Latest from BCA Research
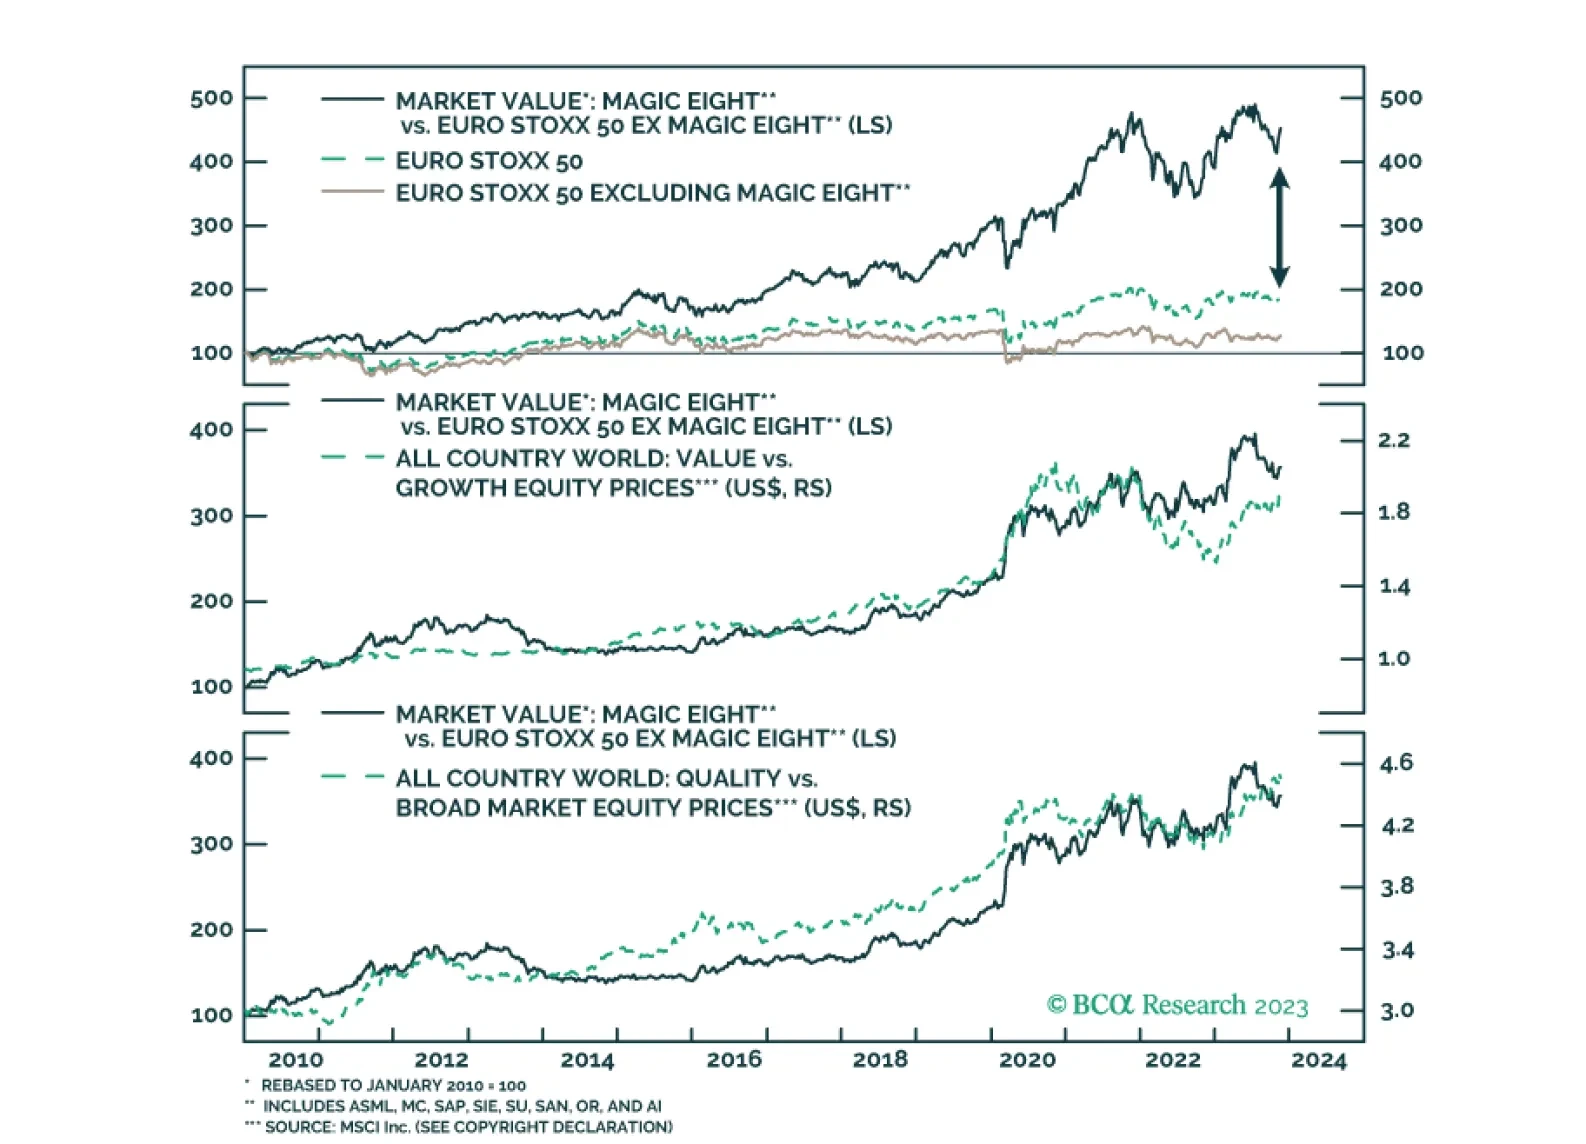
The US has the Magnificent Seven, Europe has the Magic Eight. What drives the performance of those eight stocks crucial to the European market?
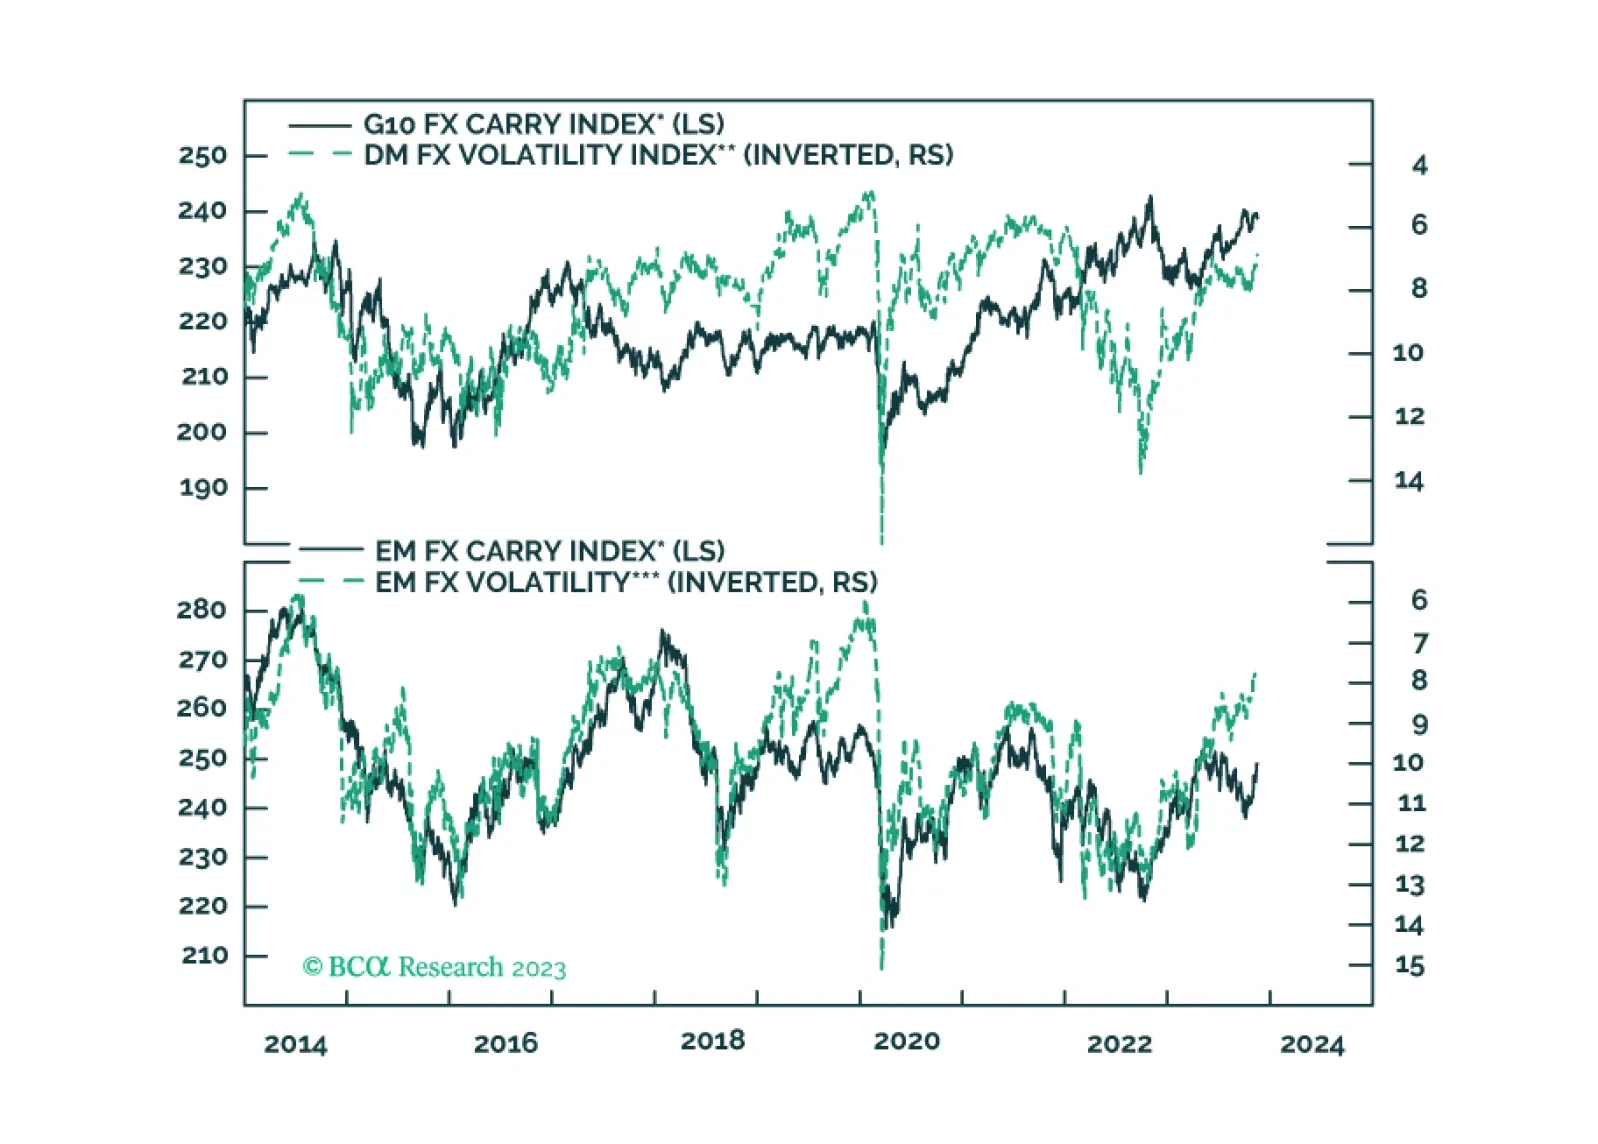
In this report, we evaluate the risk to carry trades in the coming months.

After a prolonged slump, there are early signs that demand for chips has bottomed and is showing signs of life. Meanwhile, corporate demand for future GAI chips is still a significant industry tailwind. In line with our call for an overweight of the Magnificent Seven, upgrade Semis to equal weight from underweight on a tactical basis. Longer-term outlook is neutral to negative as we expect the economy to slow in 2024, while growth expectations may be too high.

US and Chinese oil-demand strength will offset EU weakness next year. Incremental supply growth from non-OPEC 2.0 producers, coupled with a lower risk of the US enforcing its sanctions on Iranian oil exports, reduces our 2024 Brent price forecast by $6/bbl, and takes it to $112/bbl.

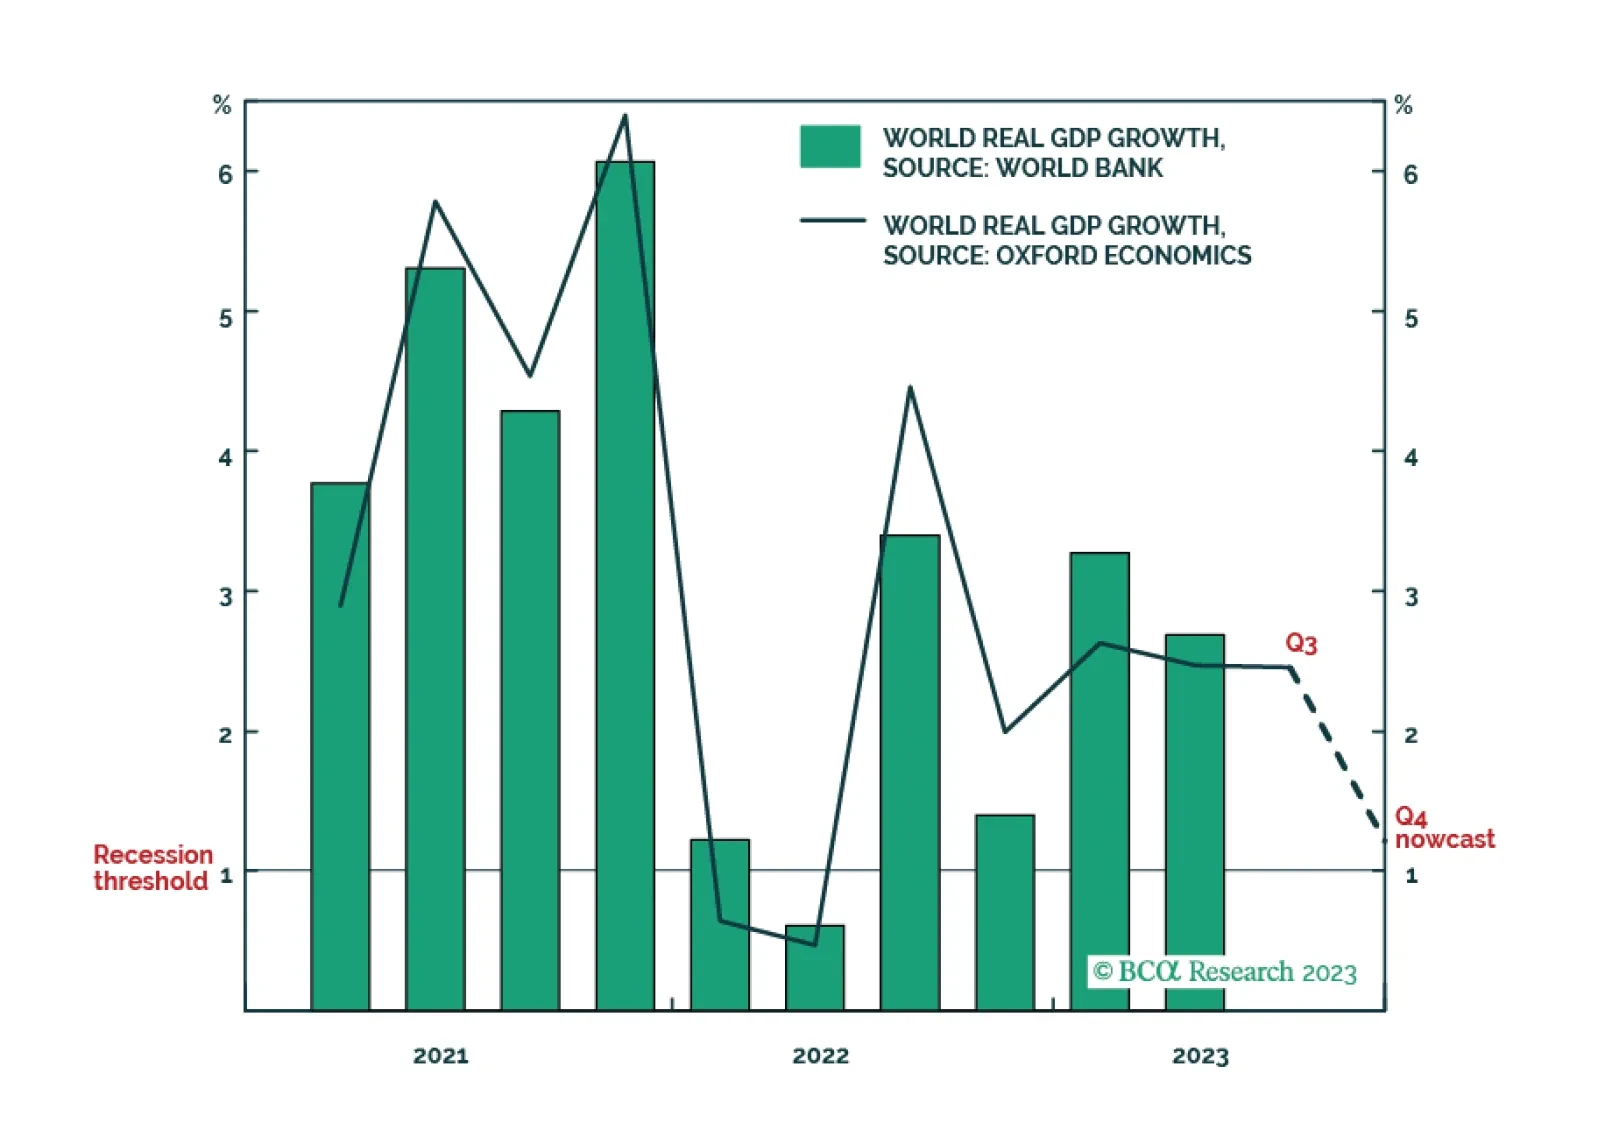
The latest ‘nowcast’ for world economic growth in the fourth quarter has plunged to just 1.2 percent, marking the cusp of another world recession. One important implication is that expectations for oil demand growth and industrial metal demand growth are way too optimistic.
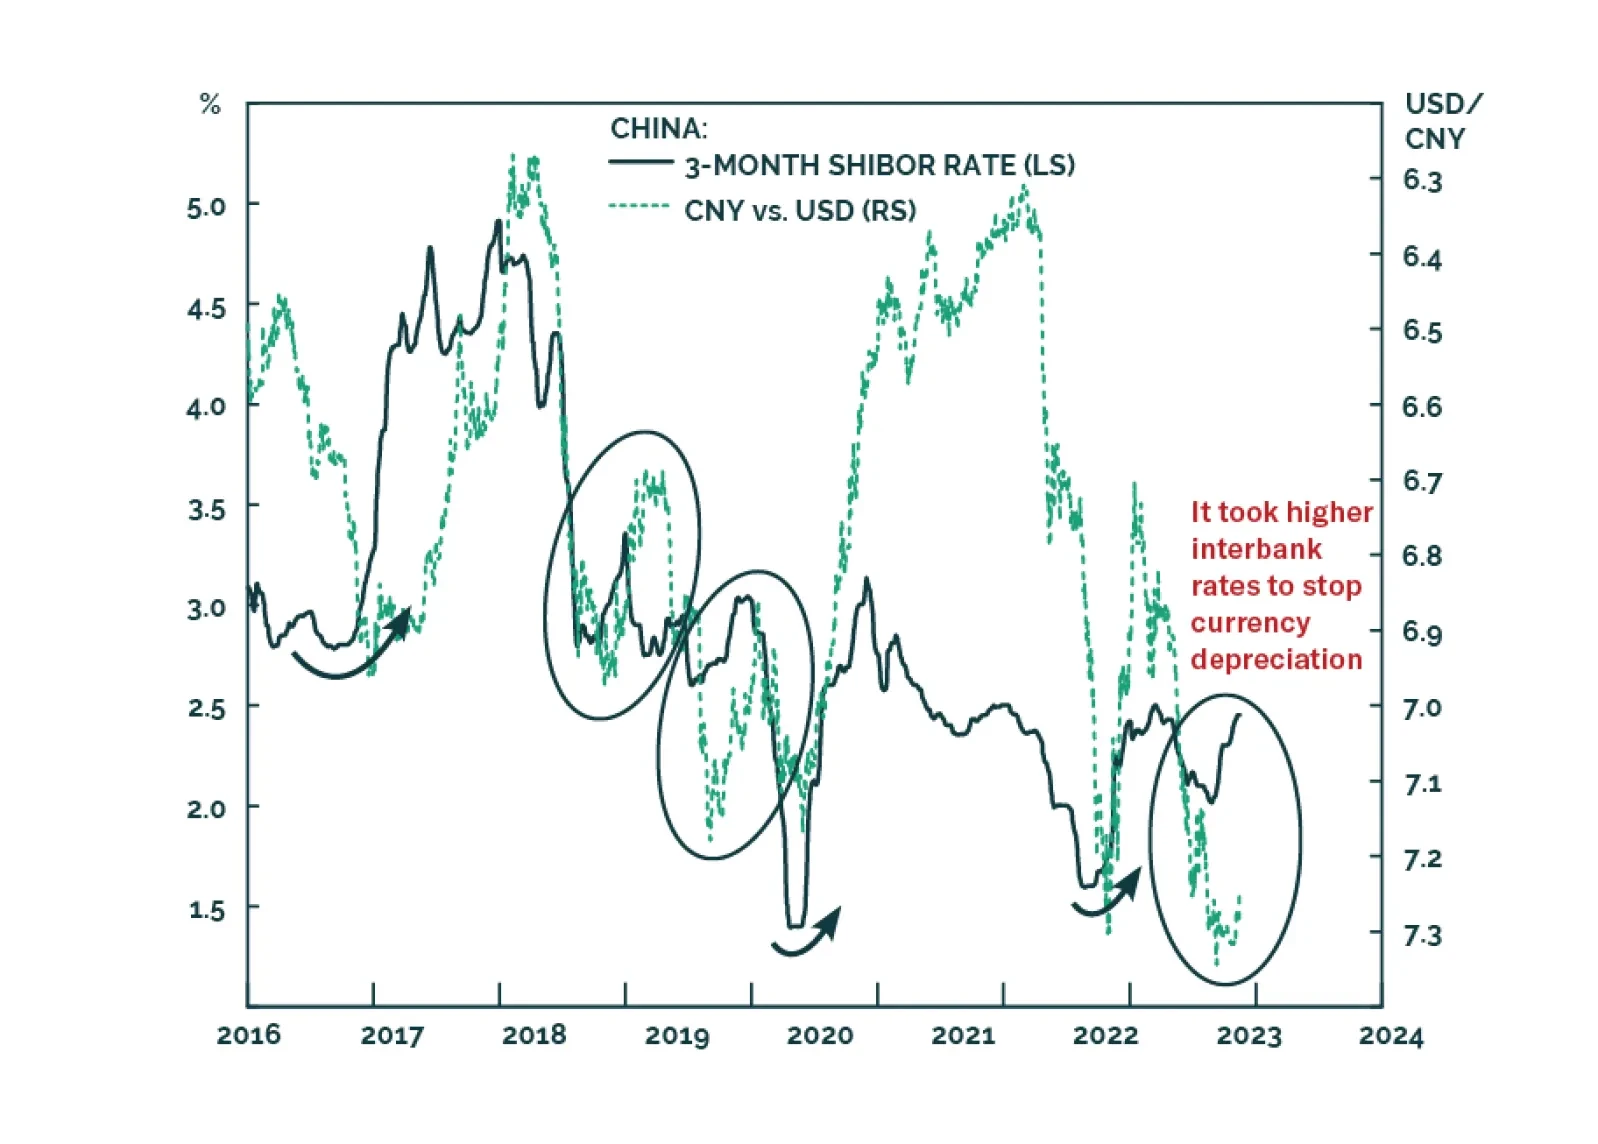
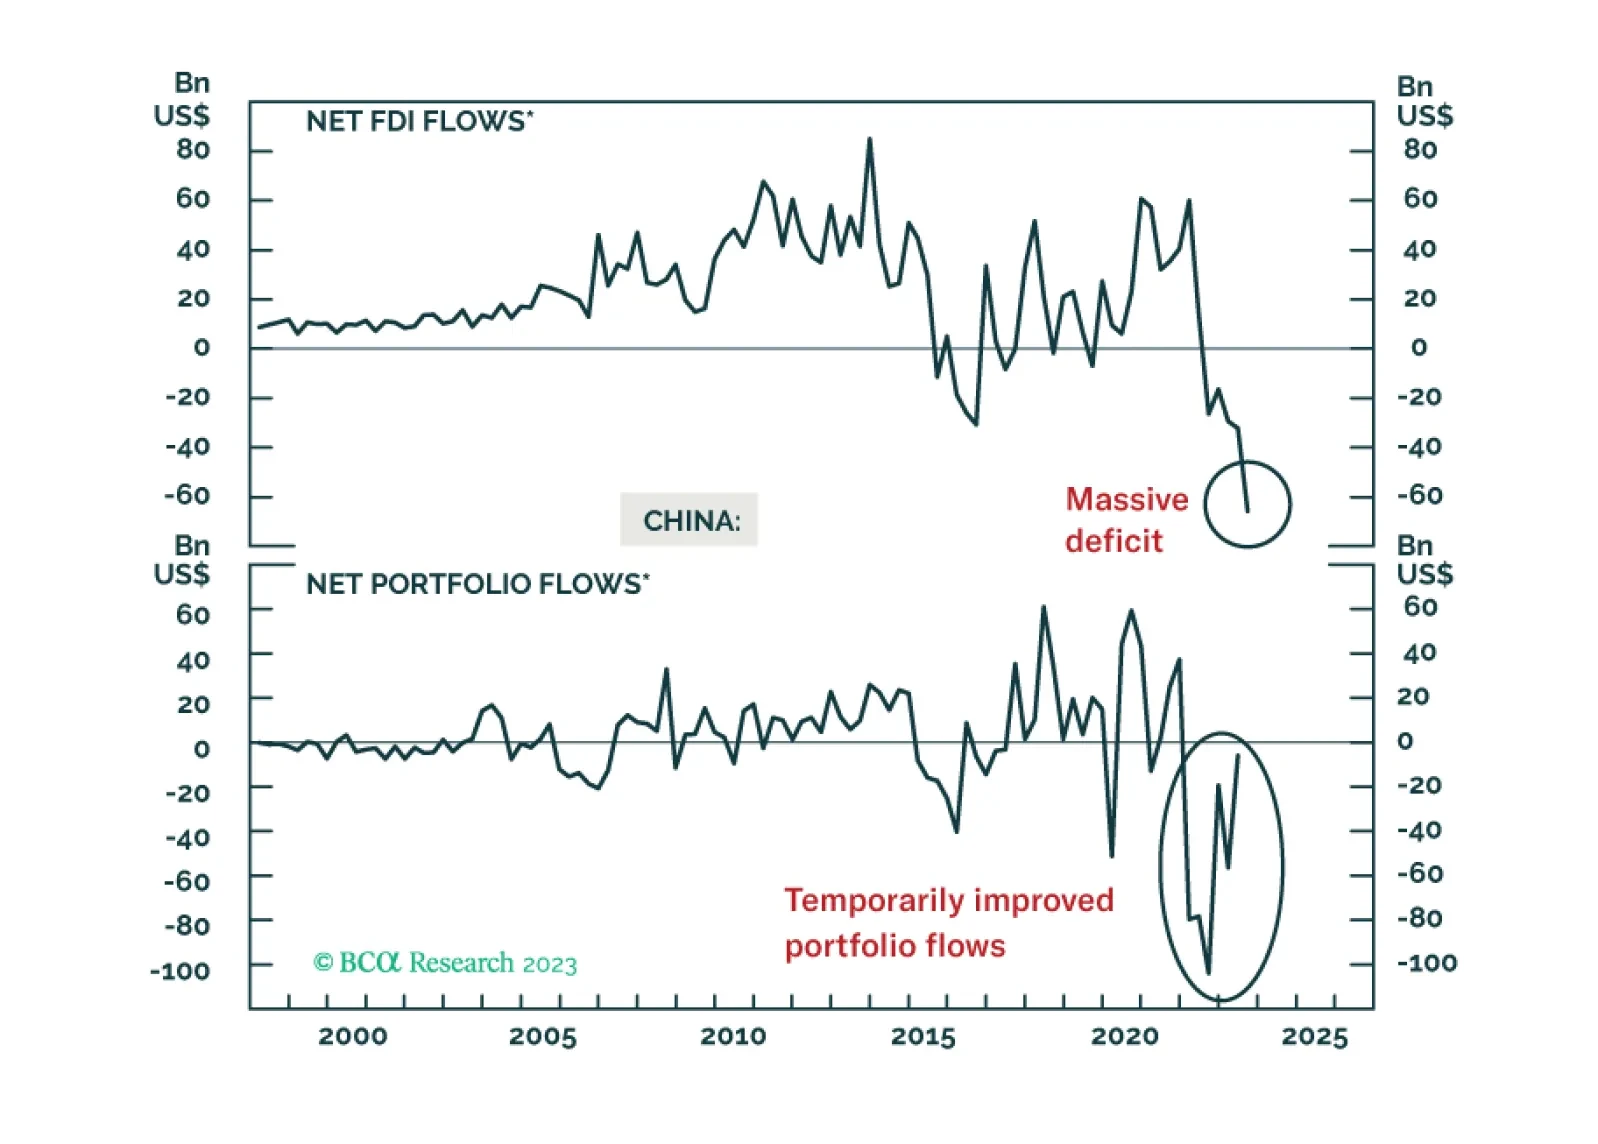
Many commentators have attributed the latest increase in Chinese interest rates to an improving economy, the large issuance of government bonds, the tax payments season, and other technical factors. Yet, these explanations are missing the key point: the PBoC has steered interbank rates higher to defend the currency. Higher borrowing costs are the last thing the mainland economy now needs.
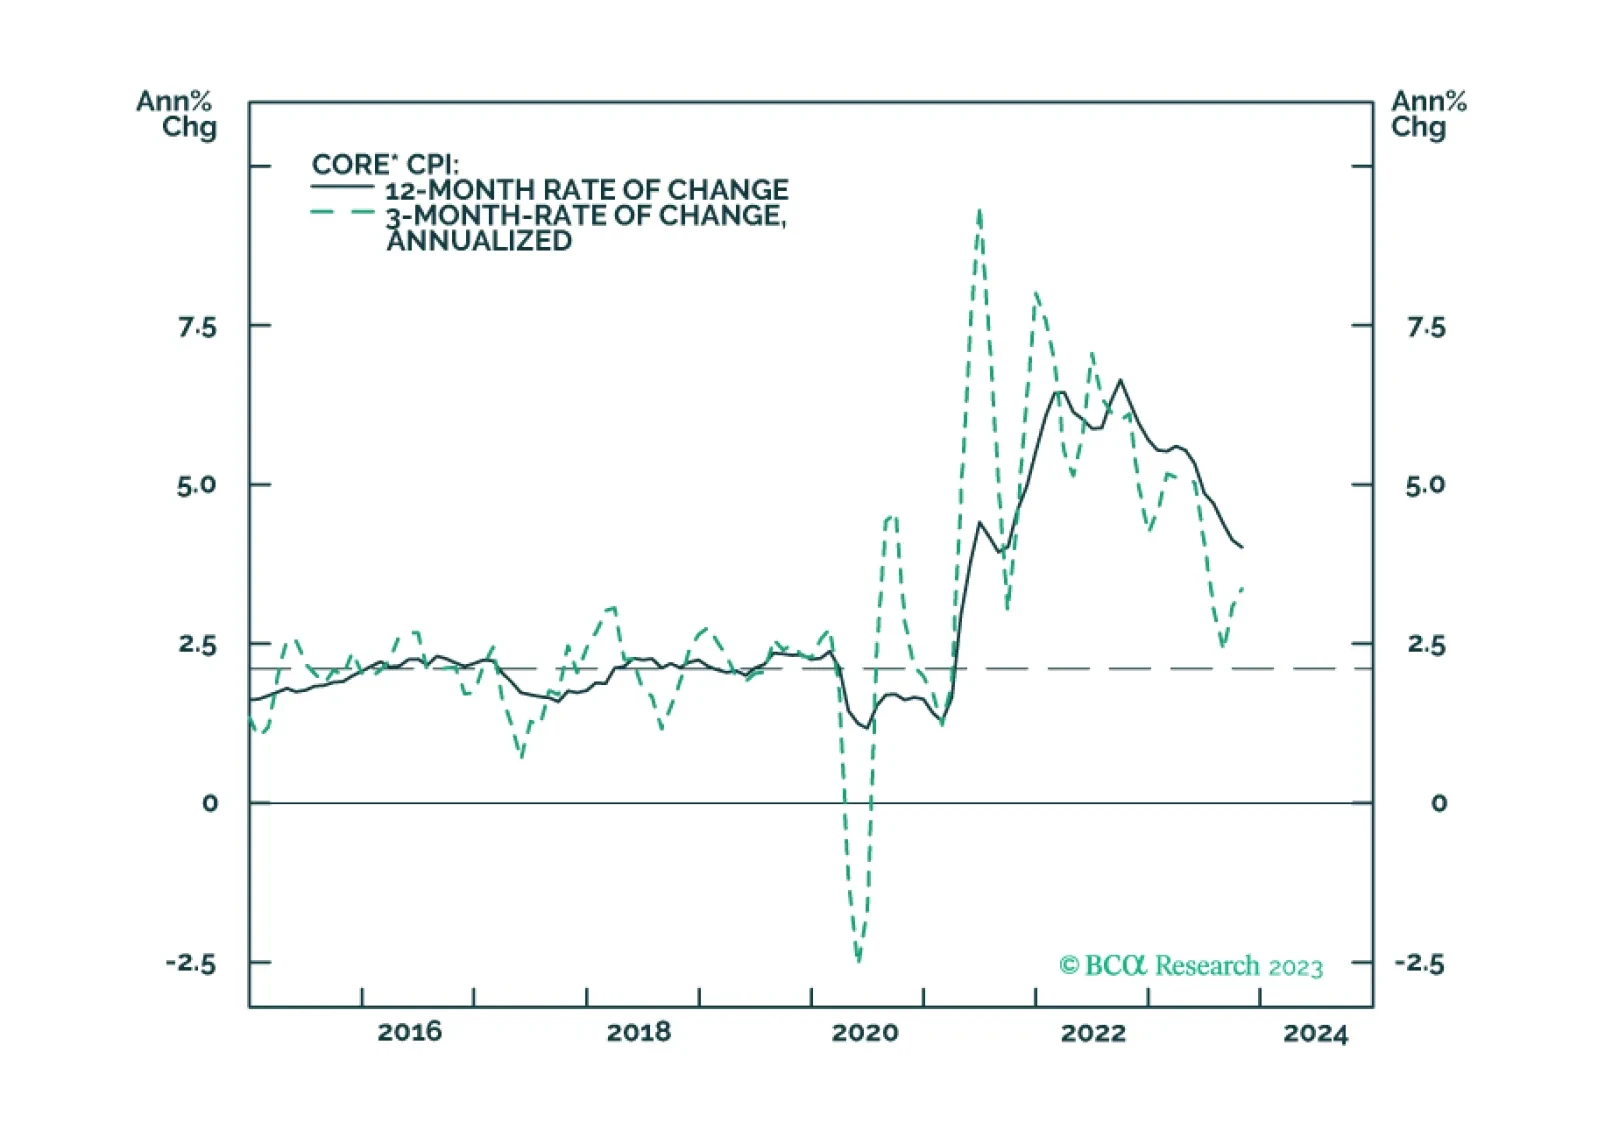
Our thoughts on this morning’s CPI print and the bond market’s reaction.
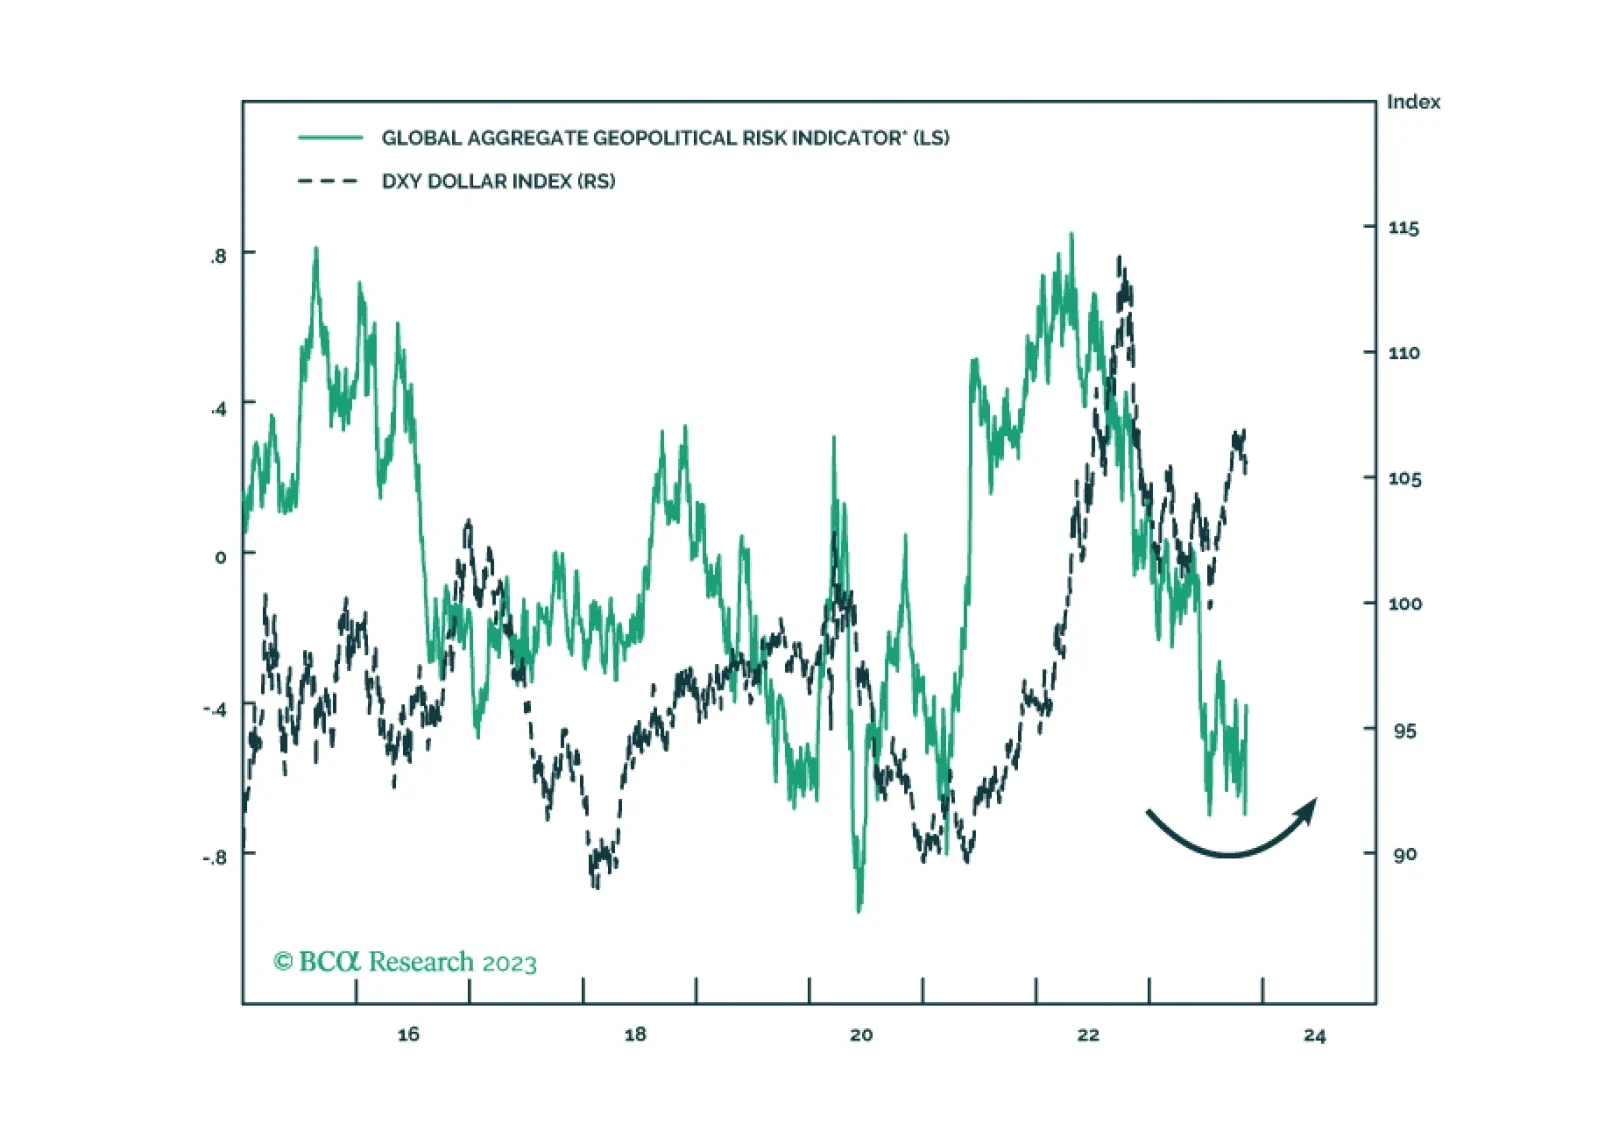
Amid a range of geopolitical narratives, what matters is that the US strategy of economic engagement with its rivals is failing, giving rise to a new strategy of containment that will reinforce the secular rise in geopolitical risk. Our market-based quantitative indicators of geopolitical risk are set to rise in the coming year.