Latest from BCA Research
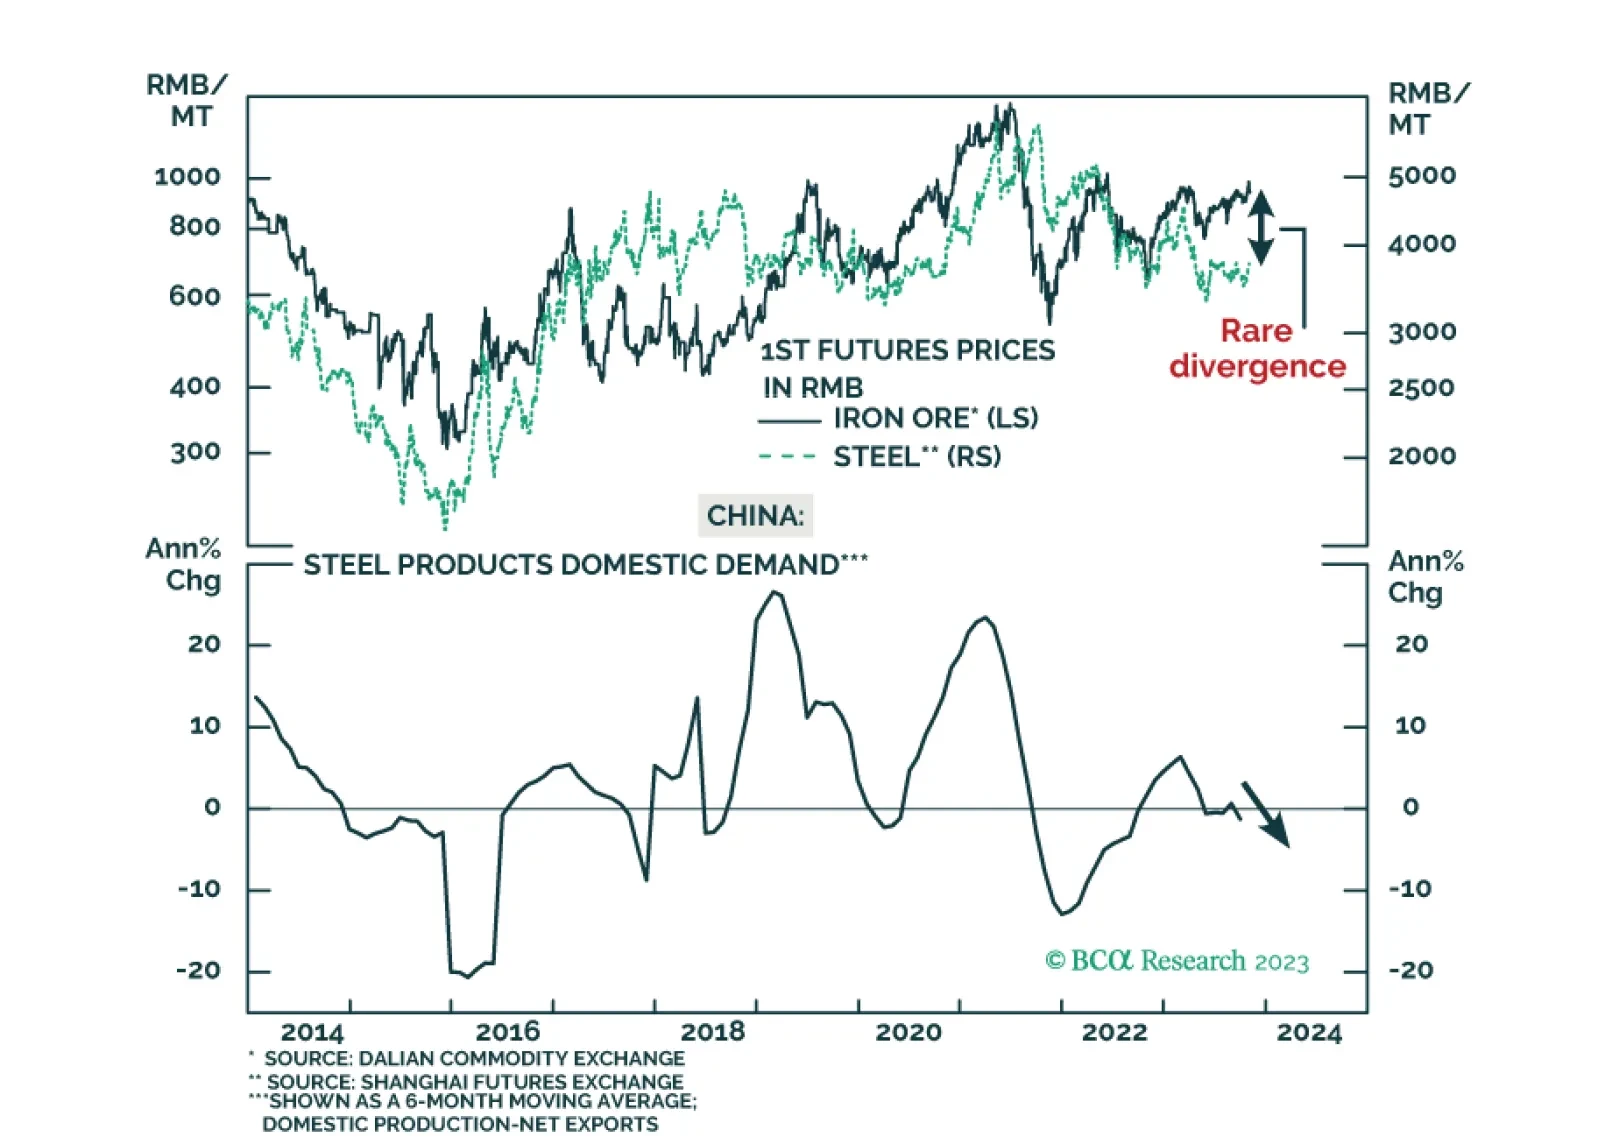

Despite very low inflation, Bank Indonesia raised its policy rates last month to support the currency. The strategy did not work before and will not work now. Stay short the rupiah.
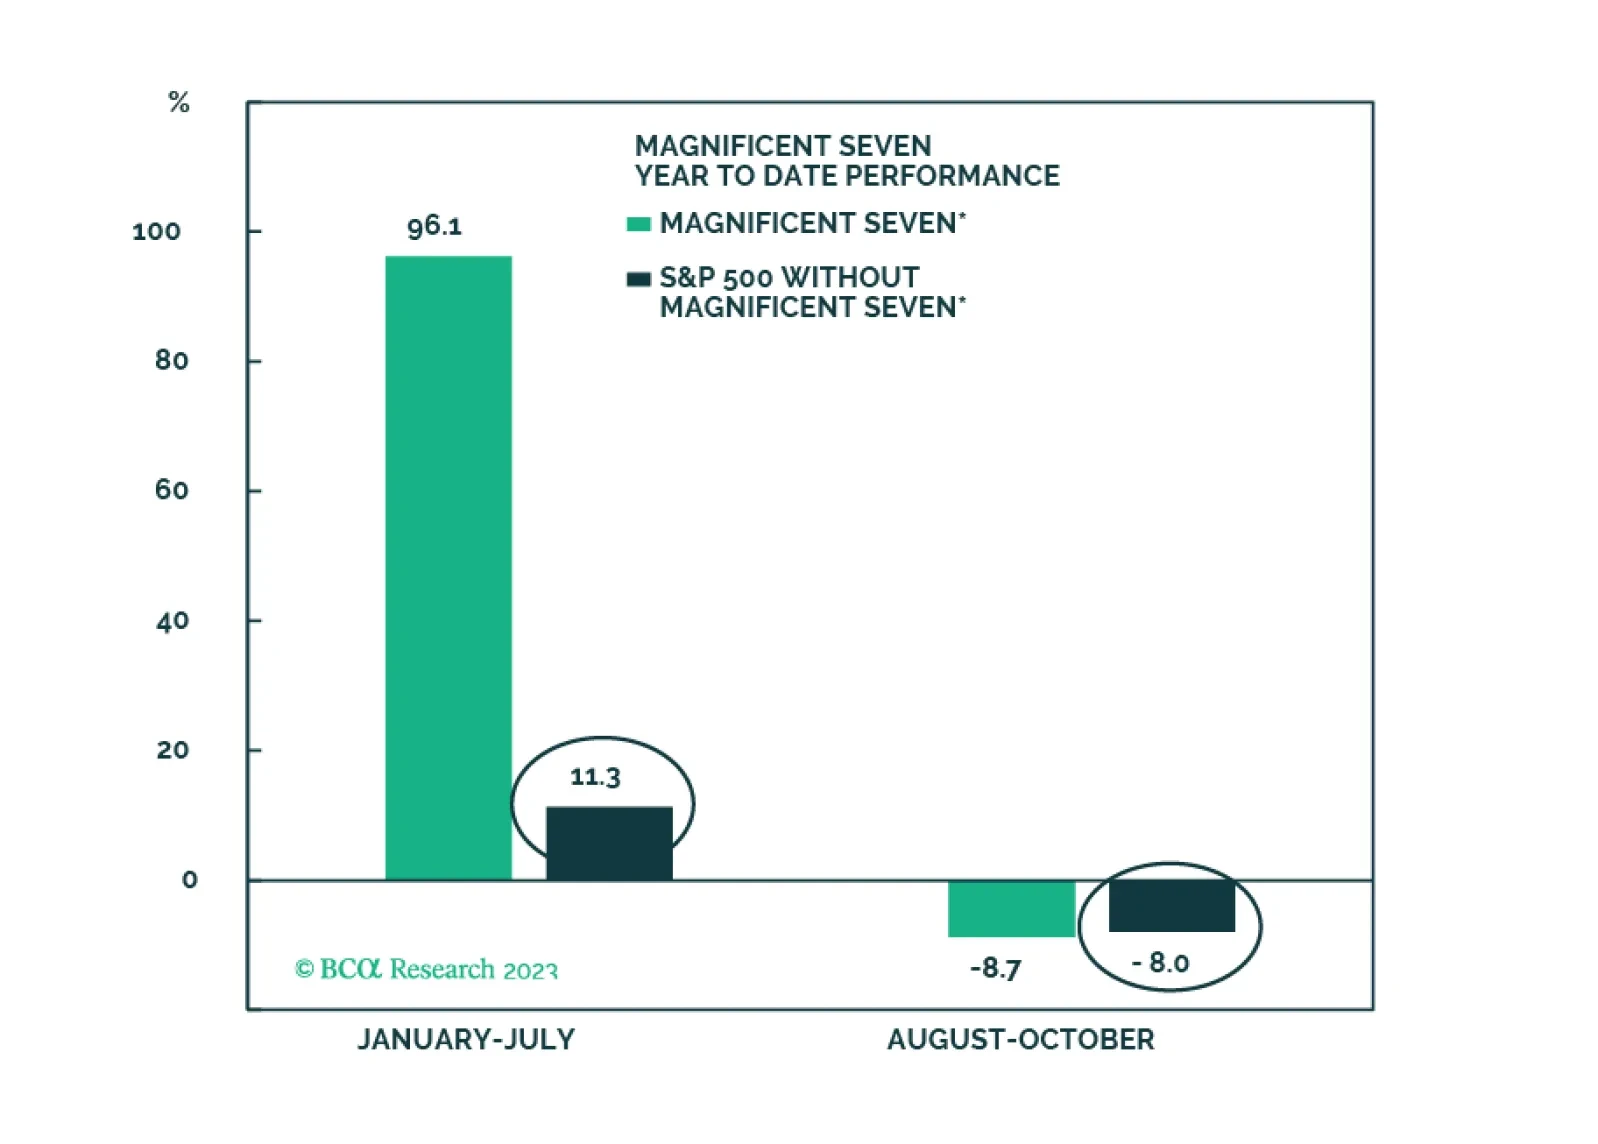
The Vicious Troika remains a long-term threat, but over the short term, rates will likely have another leg down on growth concerns, offering support to equities, which are now fairly valued and are no longer overbought. Longer-term outlook remains negative. The Magnificent Seven will likely lead a tactical rebound. Overweight Growth vs Value and FSemis.
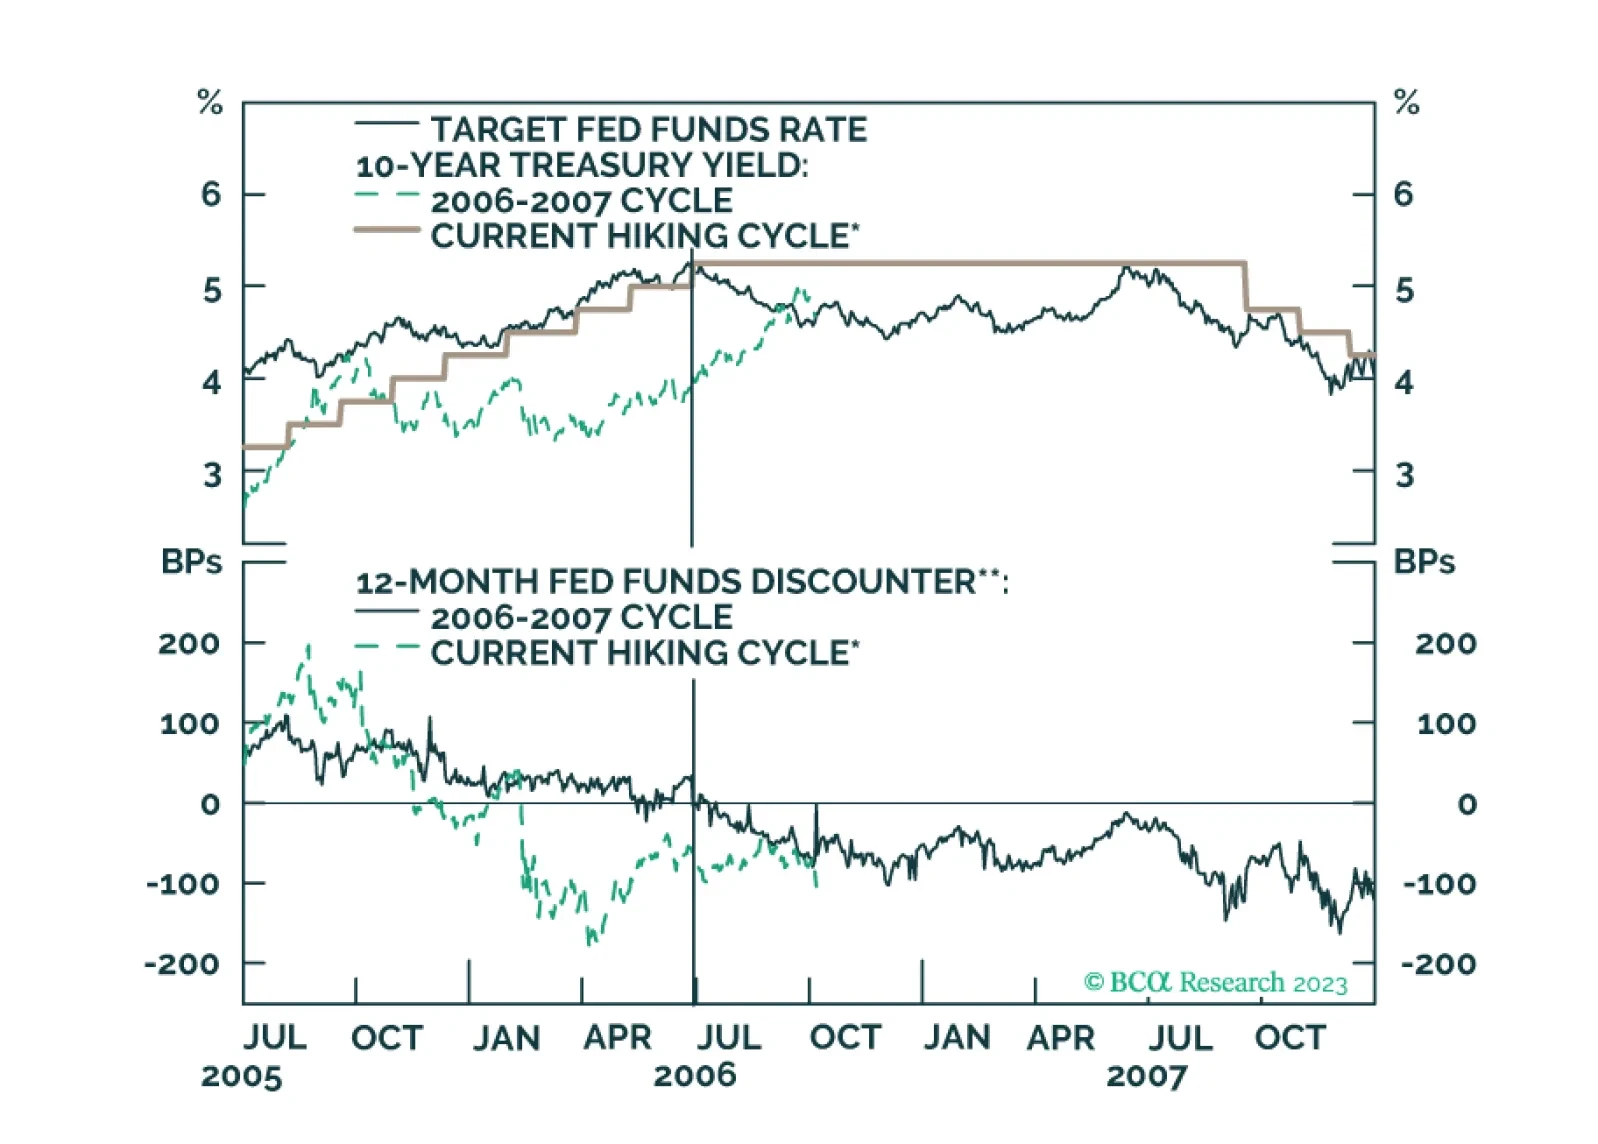
Our Portfolio Allocation Summary for November 2023.

Both USHQ portfolios outperformed inline with their benchmarks and the BCA Score L/S had another strong month. Increased market volatility continues to benefit the BCA Score.
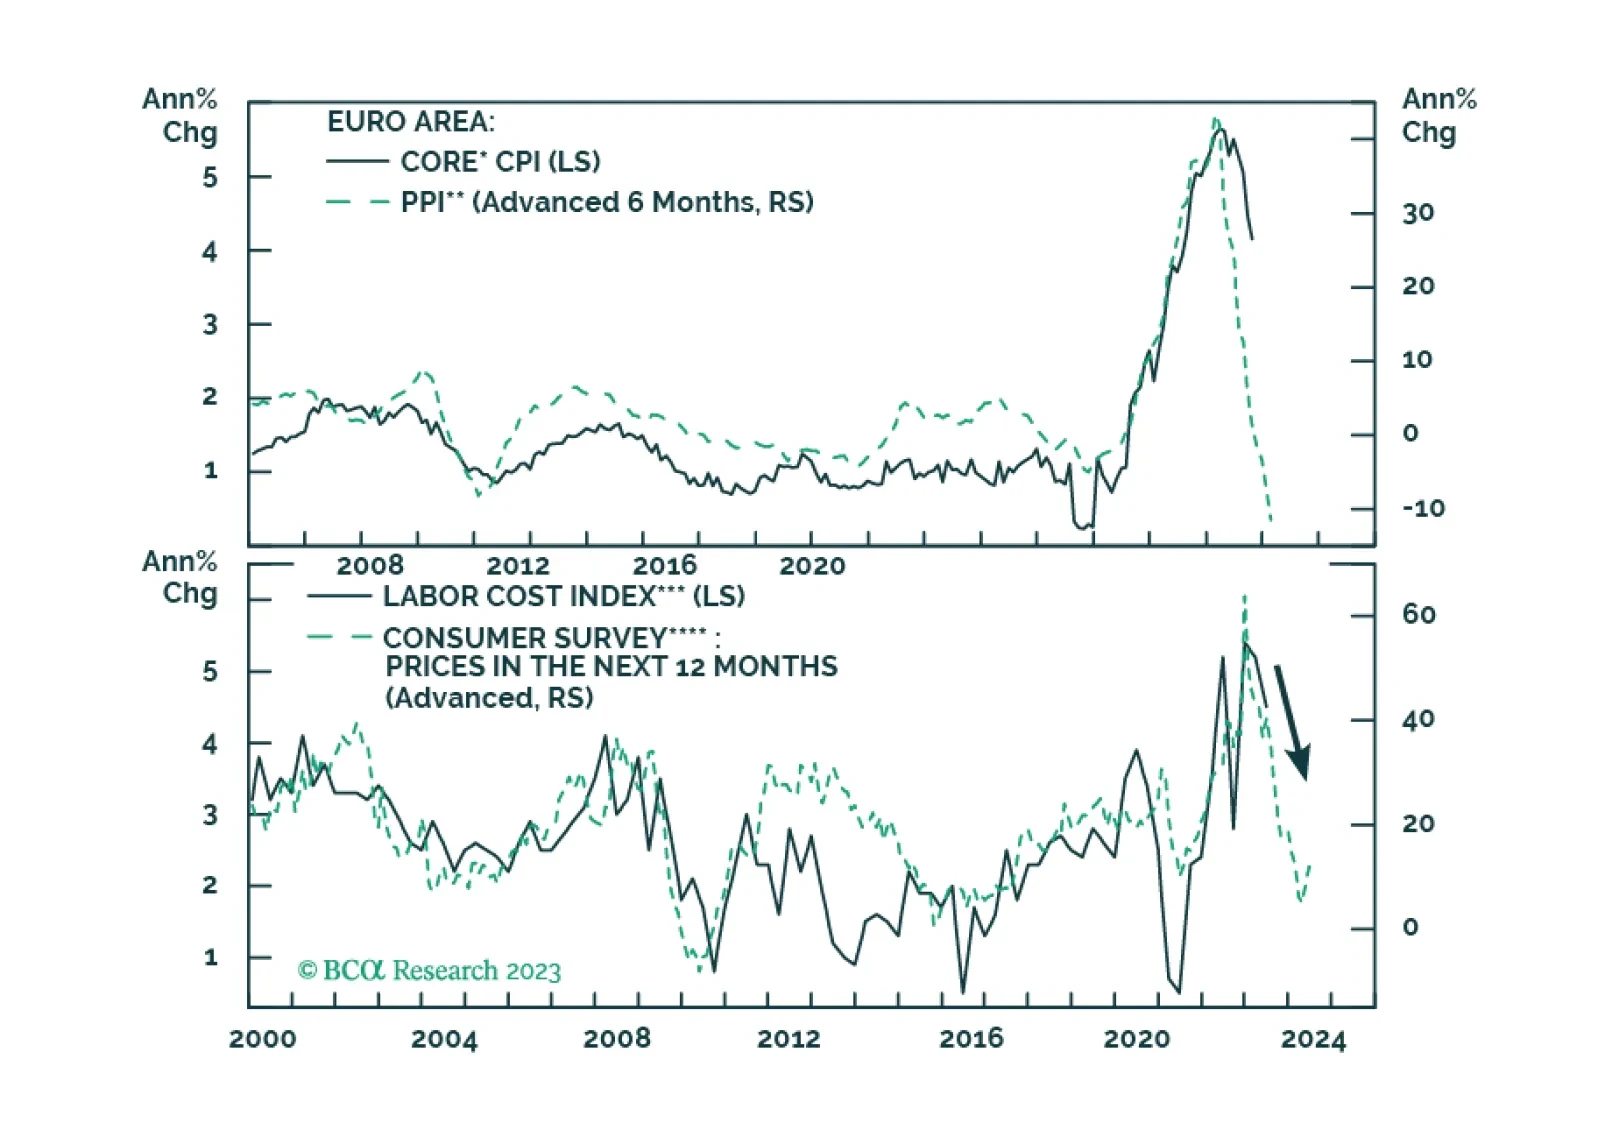
The Eurozone’s inflation will continue to slow over the coming months. While this trend will help Bund prices, will it boost the appeal of European equities?

We consider several uncertainties in this week’s report, from the interest rate outlook to the source of the mountain of cash households have amassed since the pandemic began. We have not adjusted our tactical asset-allocation recommendations but will do so soon to align with the defensive cast of our cyclical recommendations.

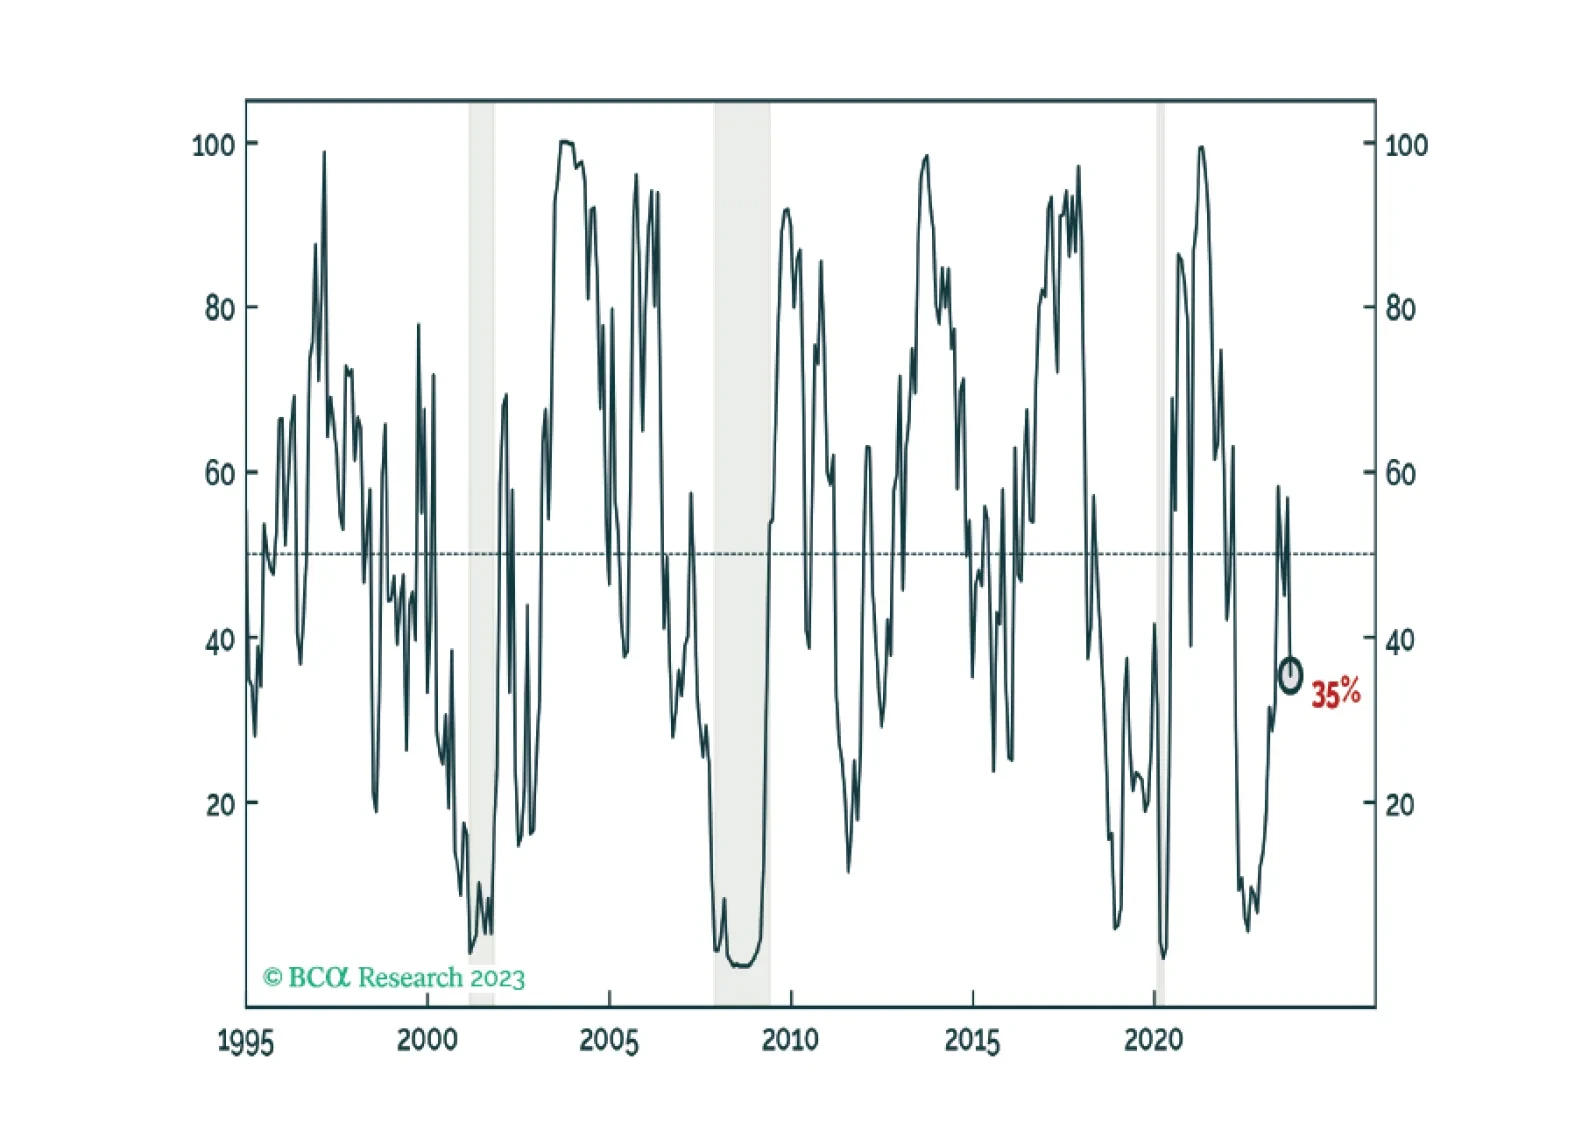
This month the Global Equity Score turned bearish after hovering in neutral territory for a few months. As a result, the sector model upgraded Consumer Staples to bullish. We also explore the remarkable year-to-date performance of the Composite Value Composite Score and propose a screen.

We are approaching another phase transition from boom to bust. Stocks should rally into year-end, but investors should look to reduce equity exposure early next year while increasing bond exposure.