Latest from BCA Research
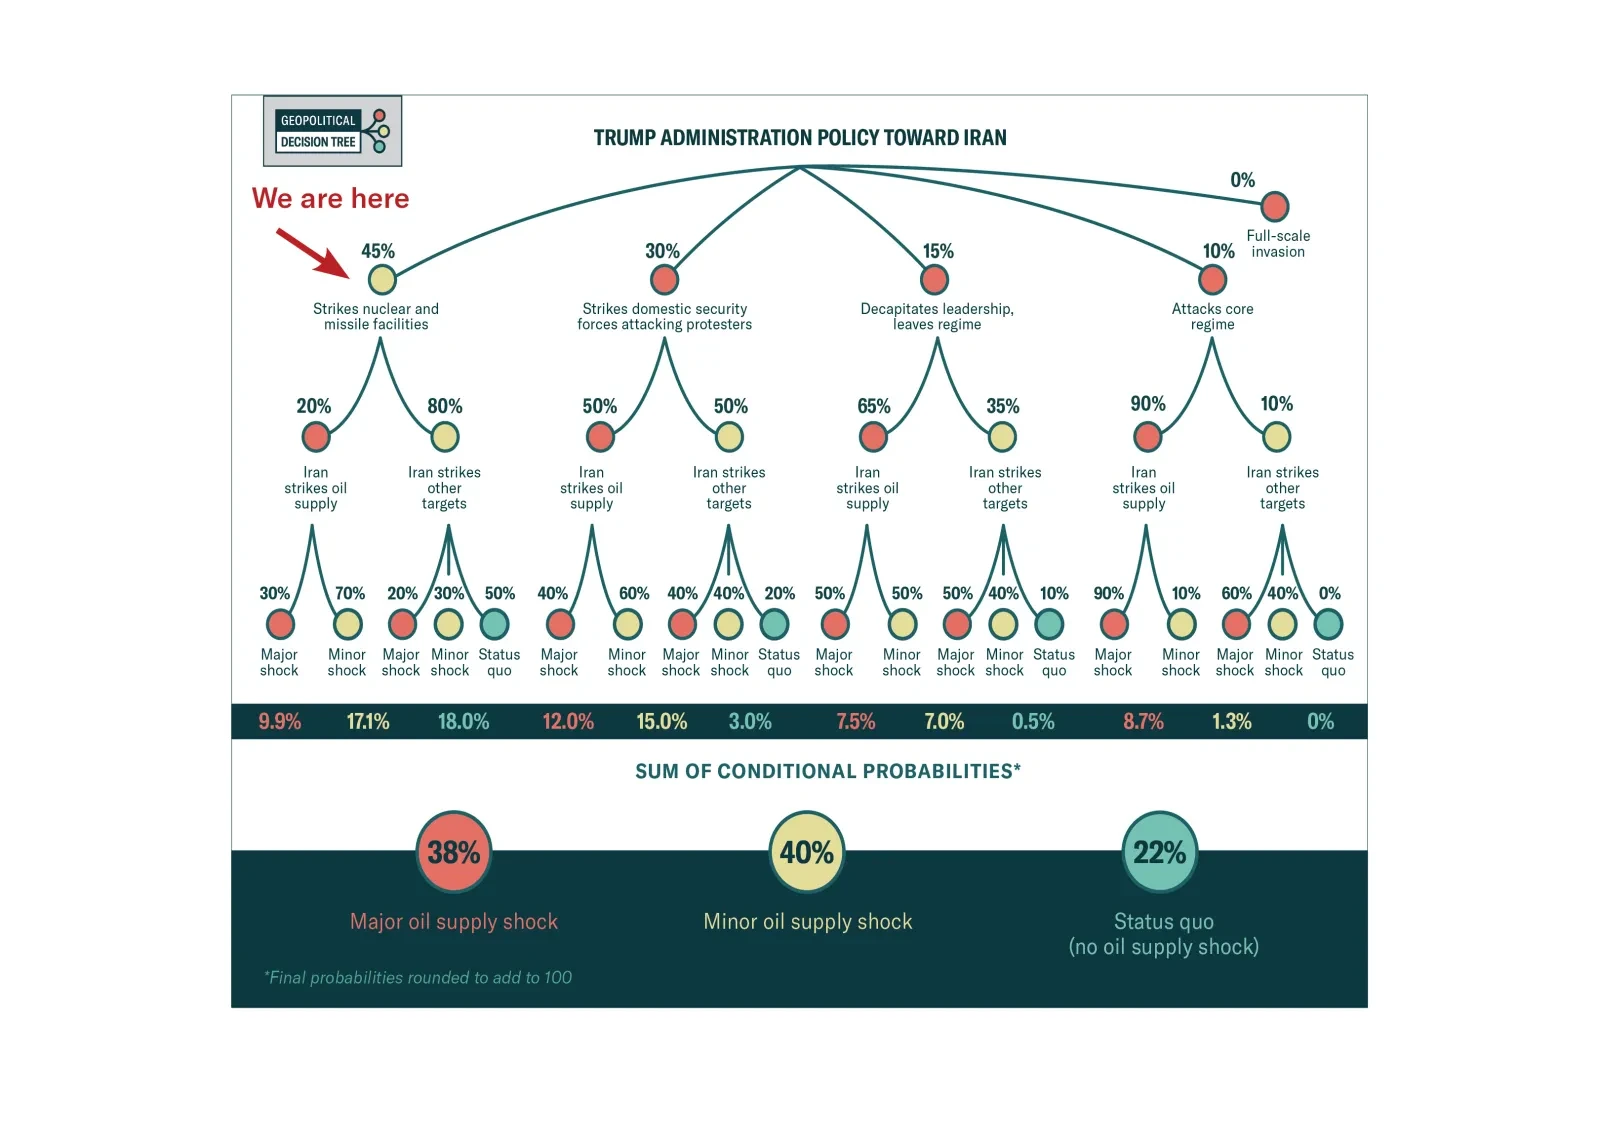
The US is likely to take significant military action in Iran, justifying our 40% risk of a major oil shock. Tactically go long Brent crude.
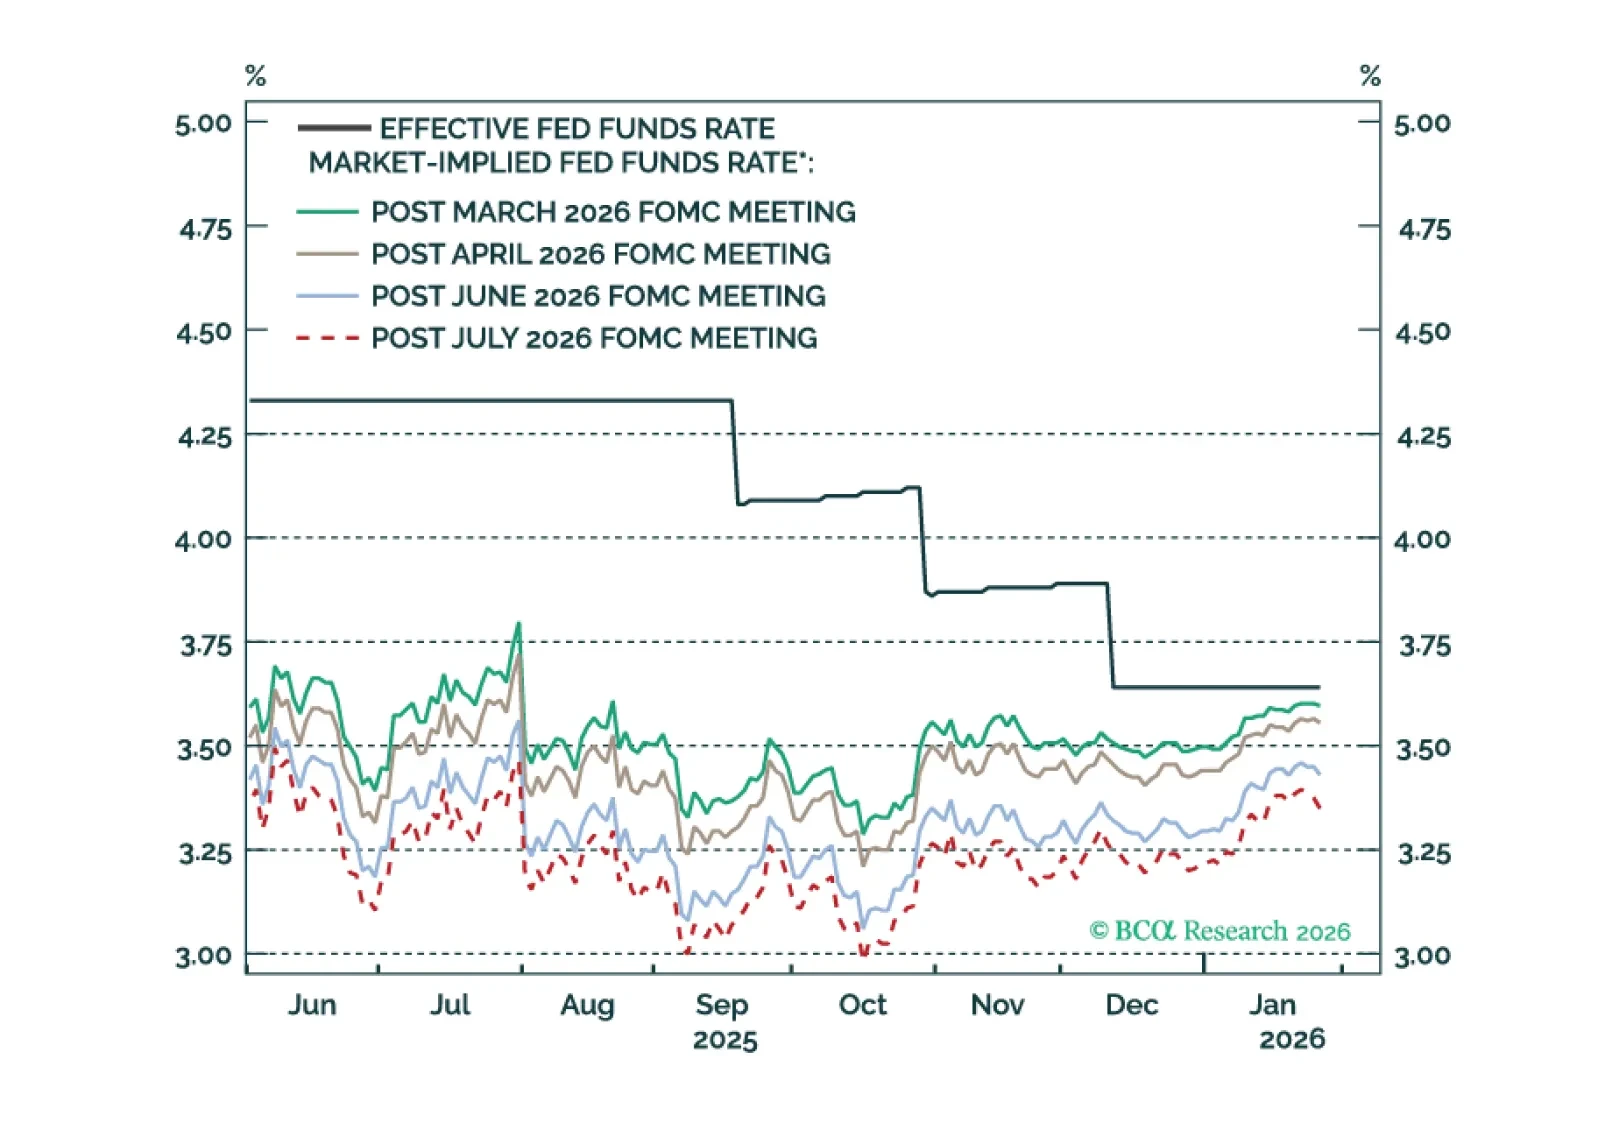
The Fed will keep rates on hold in H1 2026, but dovish policy surprises are likely in the second half of the year.

Our first release of the China High-Frequency Indicators for 2026 suggests that economic growth will continue to decelerate in Q1, leading us to adopt a tactically cautious stance on Chinese equities.

The conventional wisdom attributes the fall in the yen and the rise in long-term JGB yields to growing fiscal concerns. This narrative, however, fails to explain why the Japanese stock market has risen by 29% in dollar terms since the start of 2025, outperforming the All Country World Index by 6%.
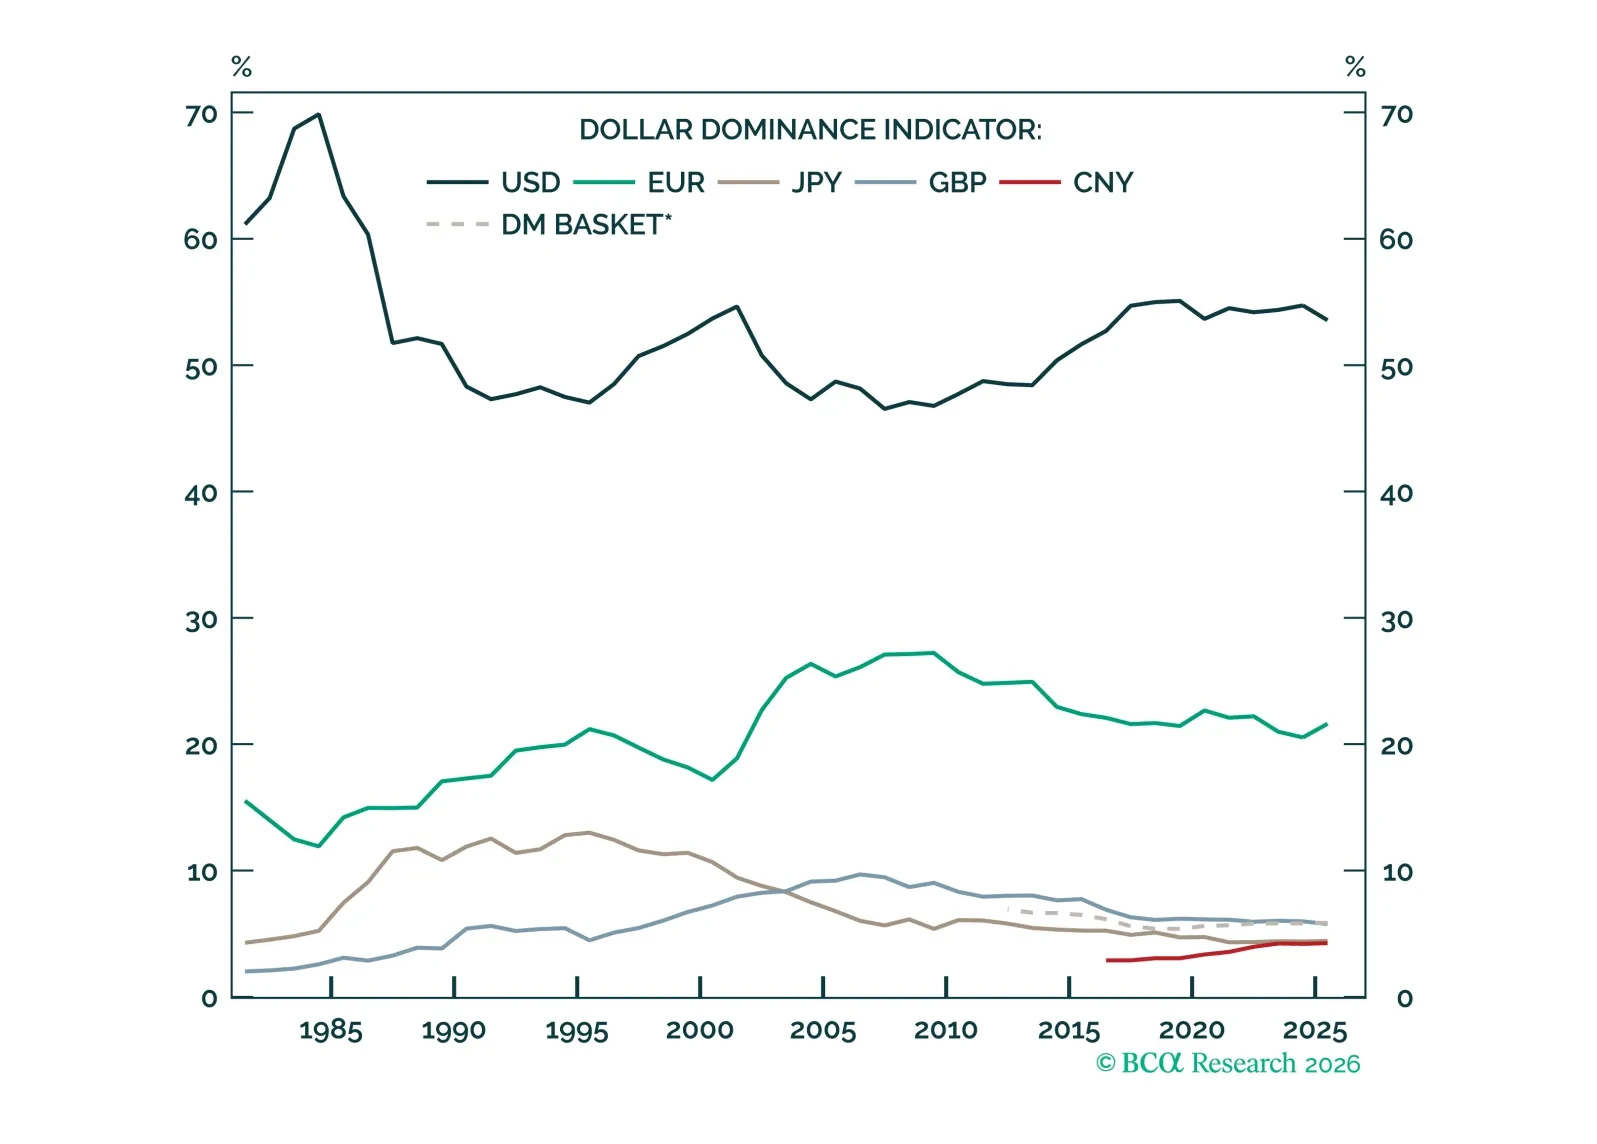
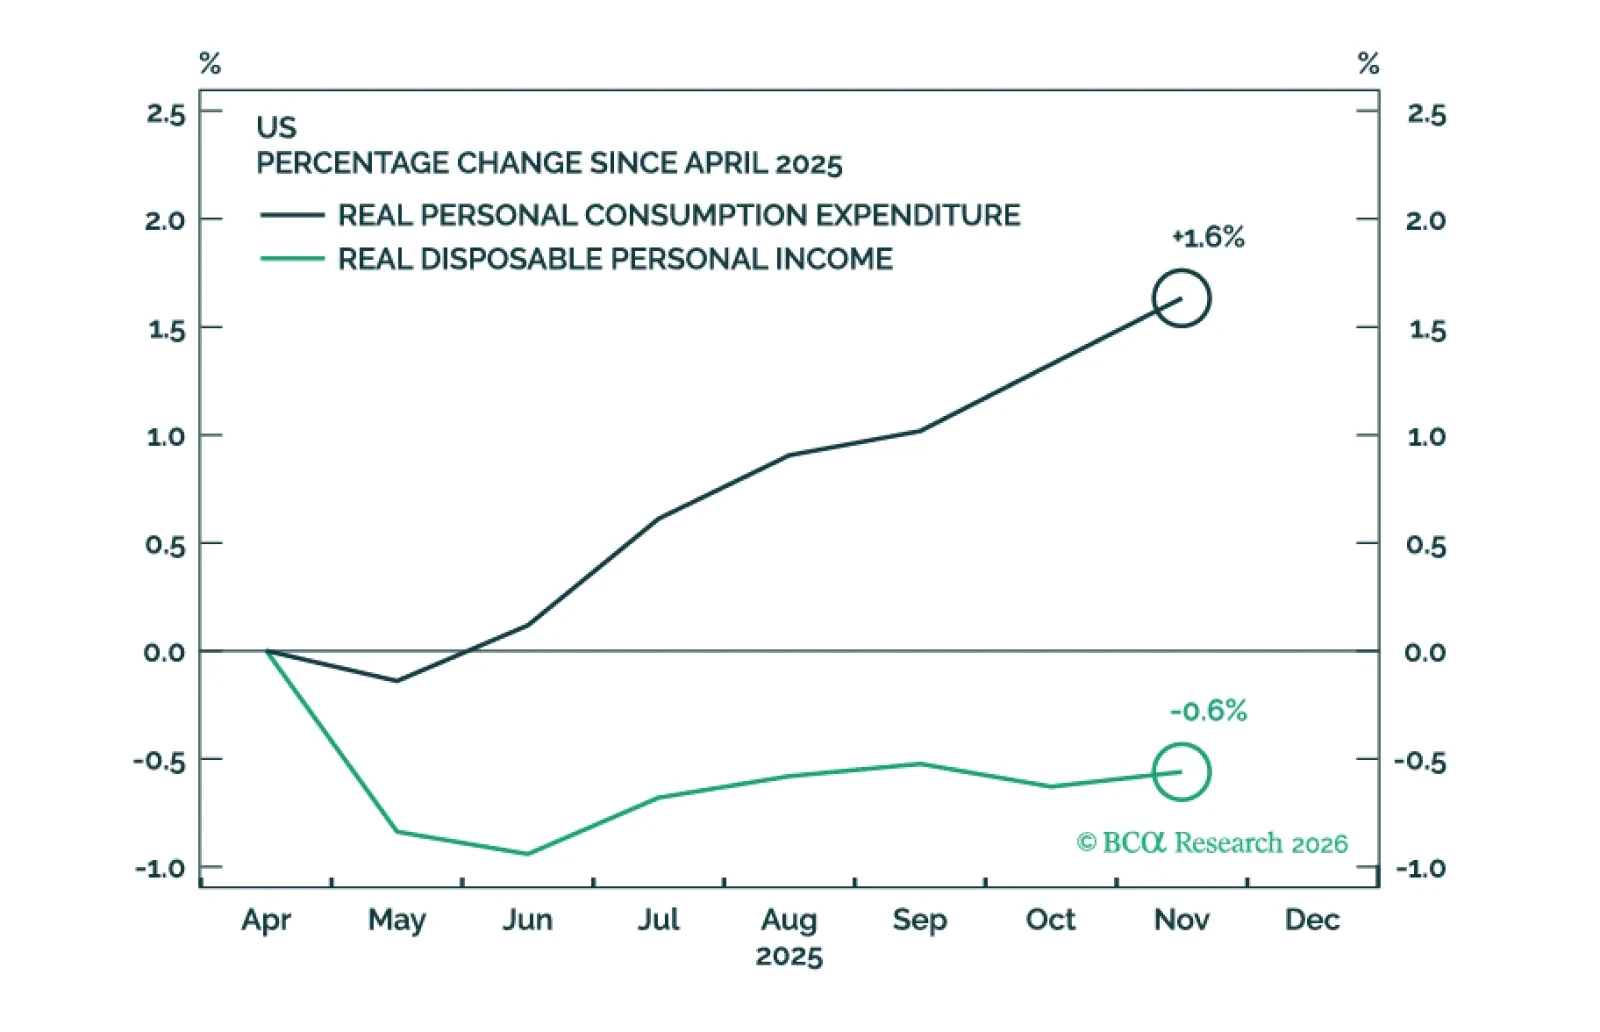
Recent economic data have been reasonably firm. We will cut our 12-month US recession probability to 40% from 50% if the Supreme Court strikes down President Trump’s tariffs. This would take our scenario-weighted year-end 2026 price target for the S&P 500 to 6375 from 6200.
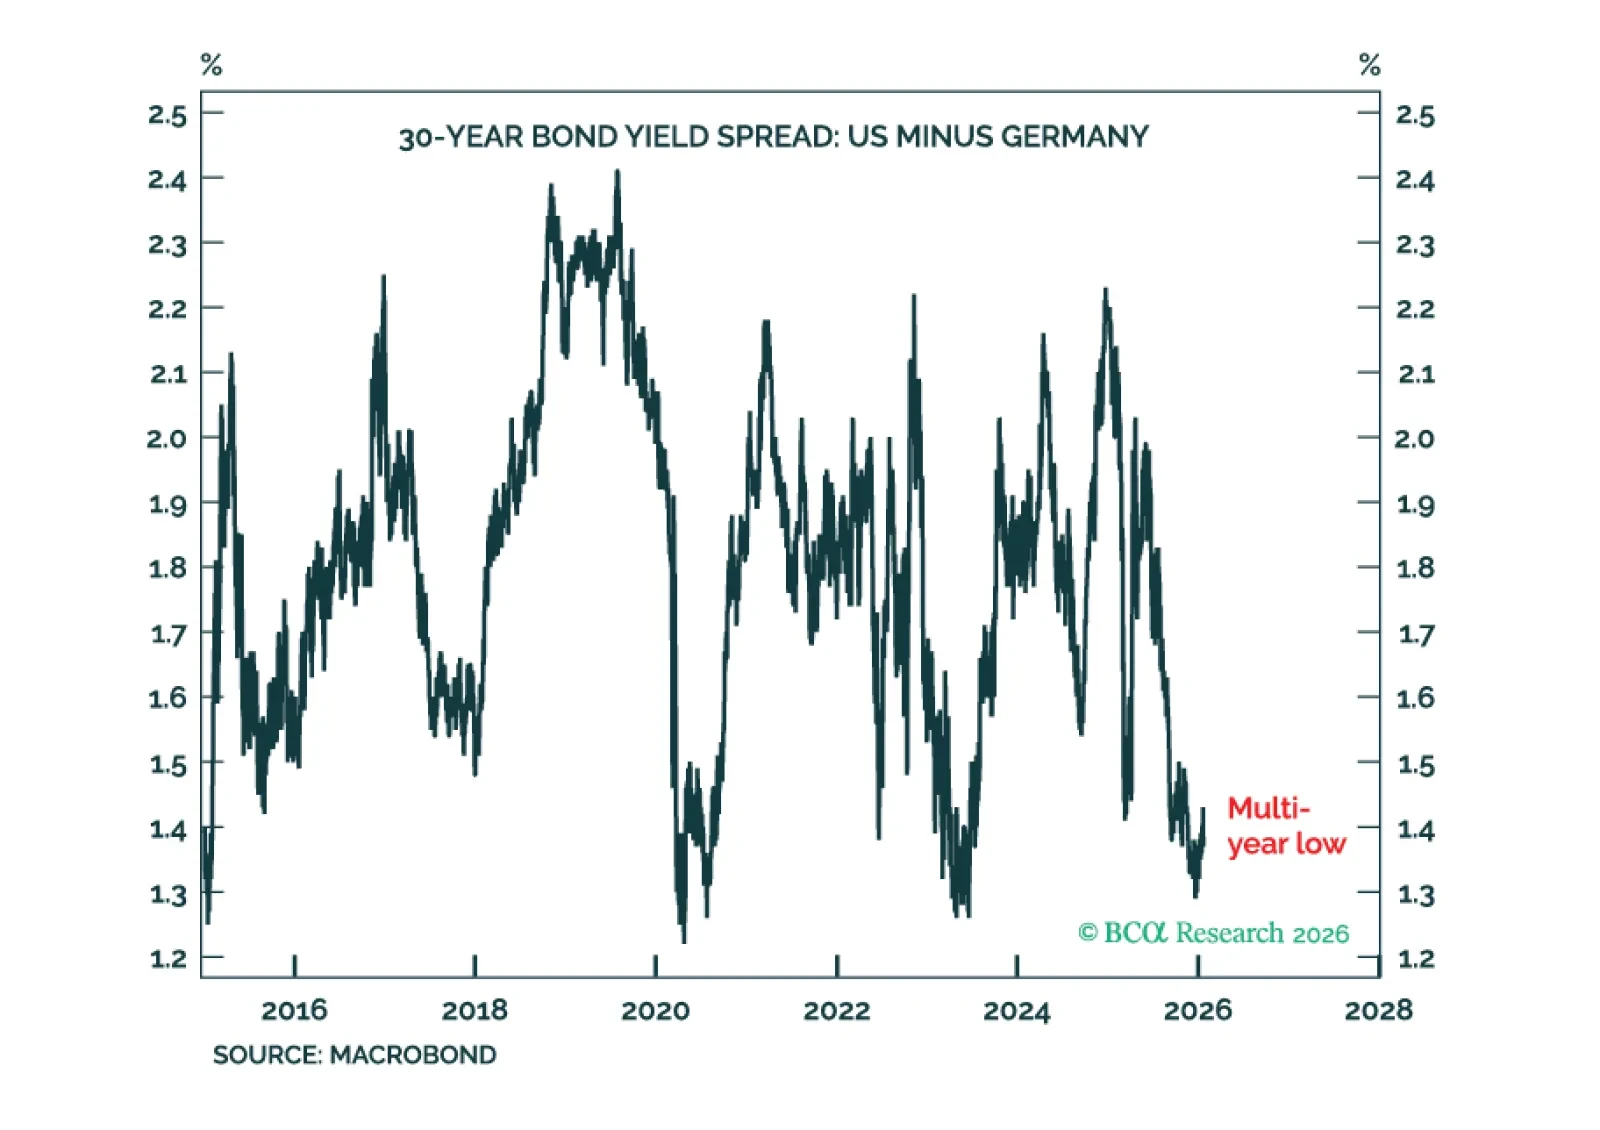
US Treasury yields require a higher premium for both geopolitical risk and inflation risk, but higher bond yields are not necessarily bad for stocks.

Our top five "Black Swan" risks this year are familiar but all too realistic in the current climate. Investors should stay overweight US equities and EM-ex-China until some hurdles are cleared.