Latest from BCA Research

Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.

The US overconsumes and underproduces. China overproduces and underconsumes. There are early signs that this decades-old imbalance has peaked and is beginning to reverse. Upgrade the CNY to overweight.
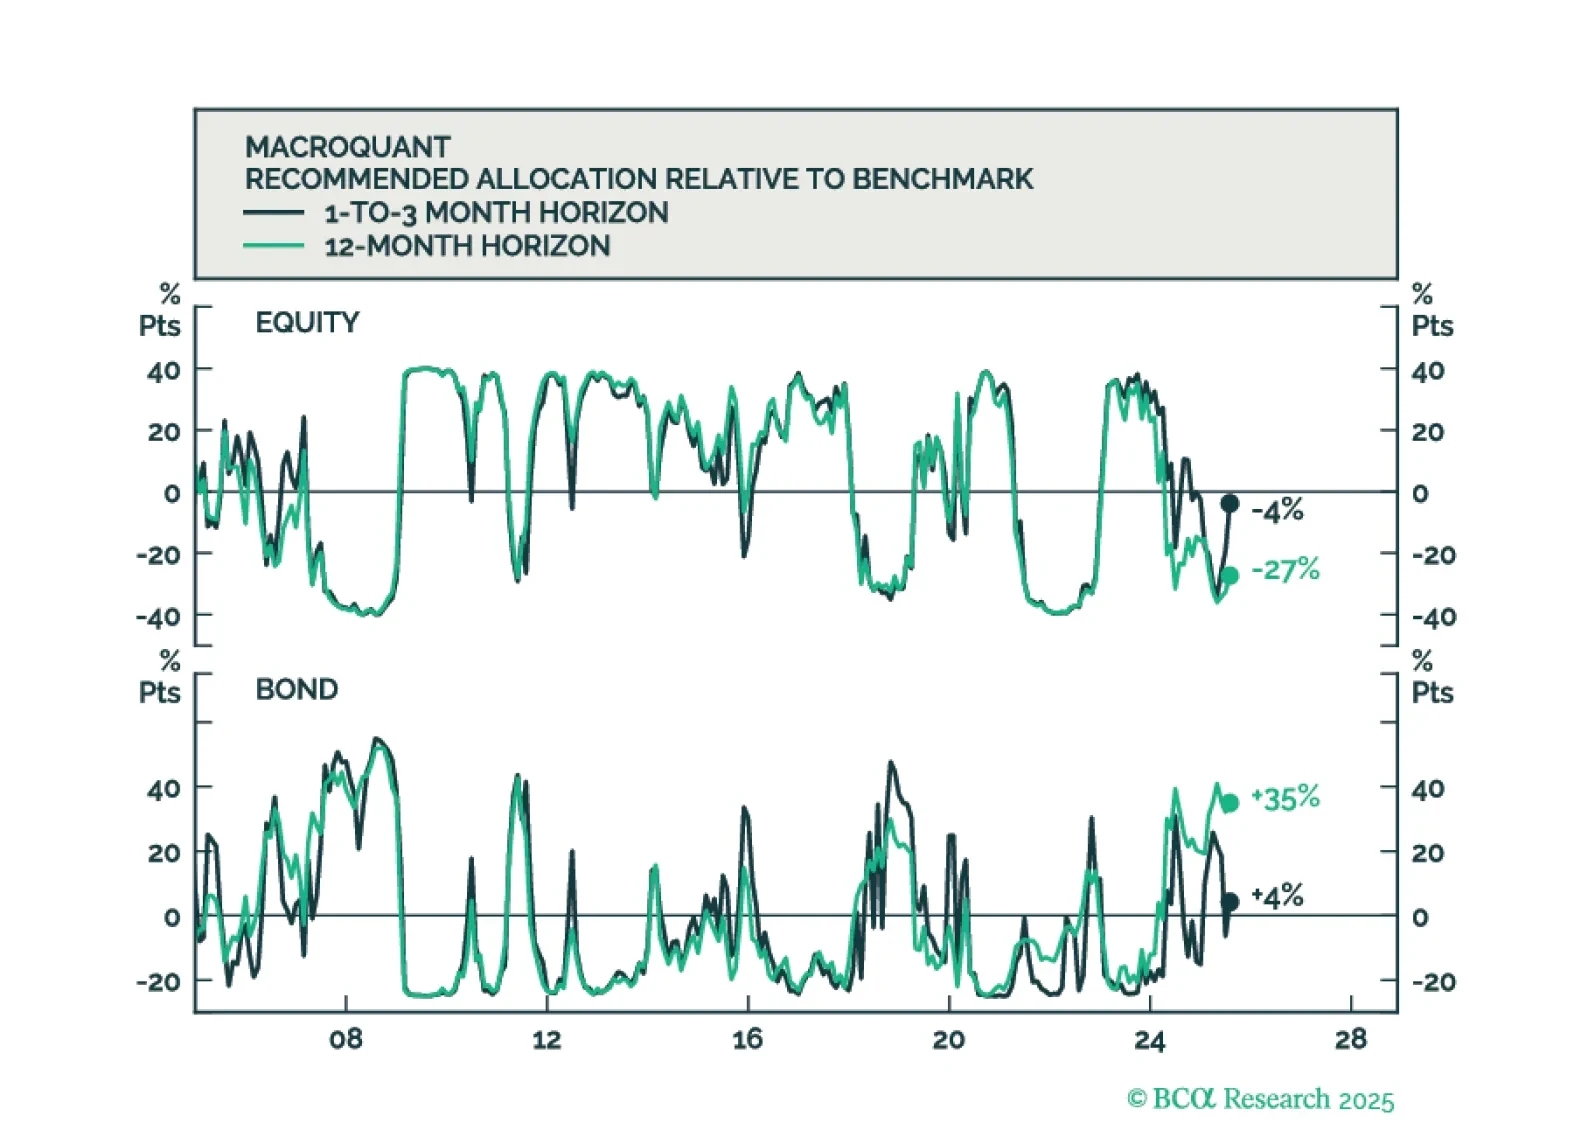
MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.

Trump, the Fed, the Russo-China bloc, Venezuela, and France are all seeing developments that imply some contrarian tactical views: Long USD, overweight US versus Europe, overweight Europe versus China, and short oil.
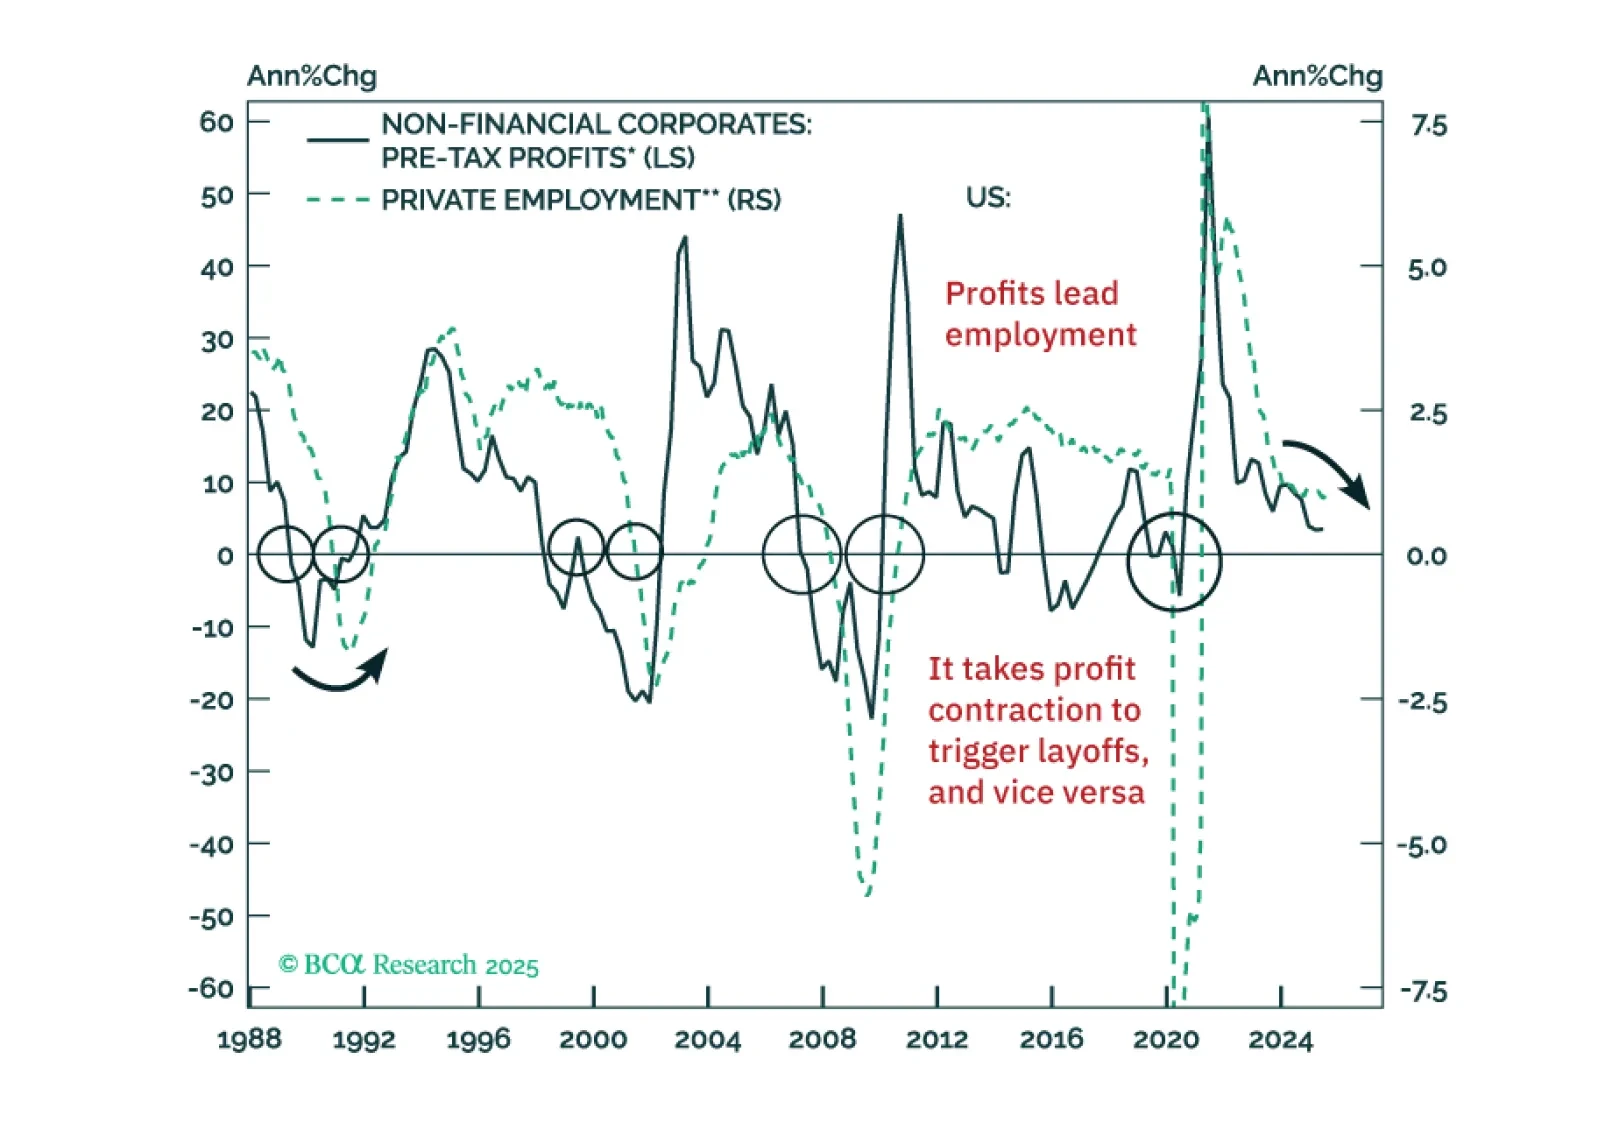
We see two risks that could spoil the rally in US risk assets: (1) a tariff-driven stagflation, and (2) a US Treasury tantrum. Our negative view on EM risk assets is primarily driven by the outlook for global trade, which is set to shrink in Q4 this year.
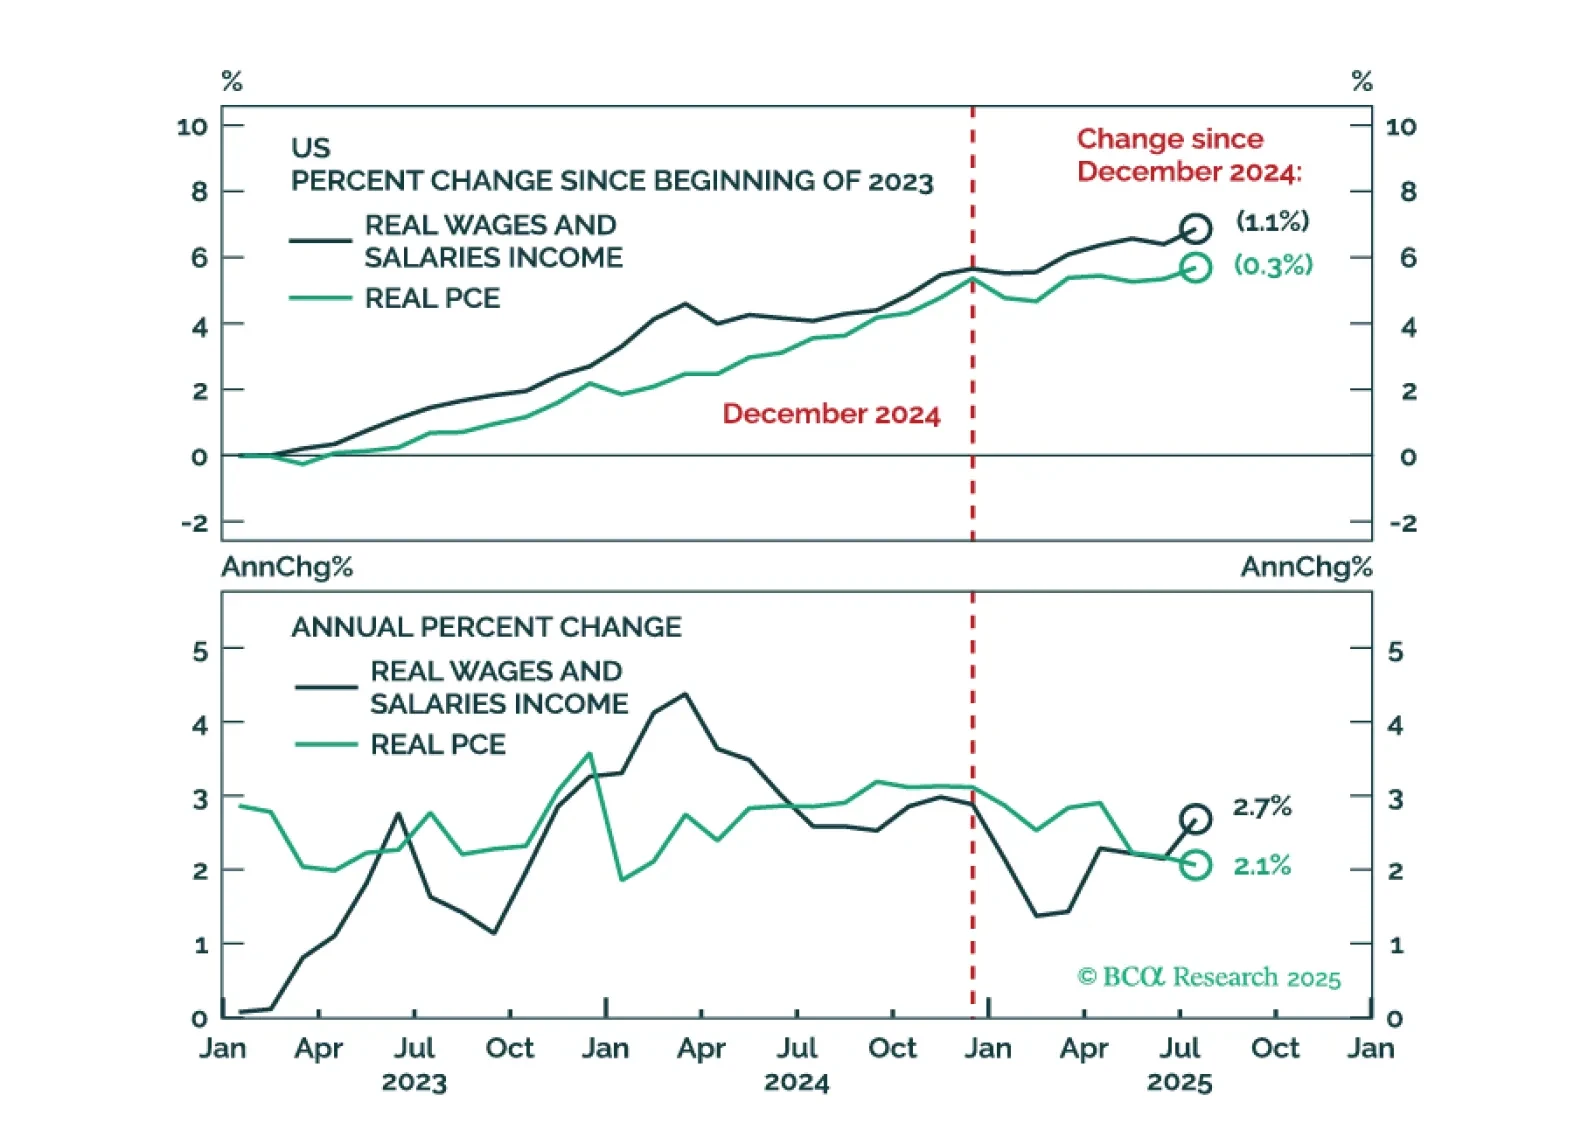
Today’s PCE report was broadly in line with expectations. Real consumer spending rebounded in July but remains only 0.3% above where it was in December.
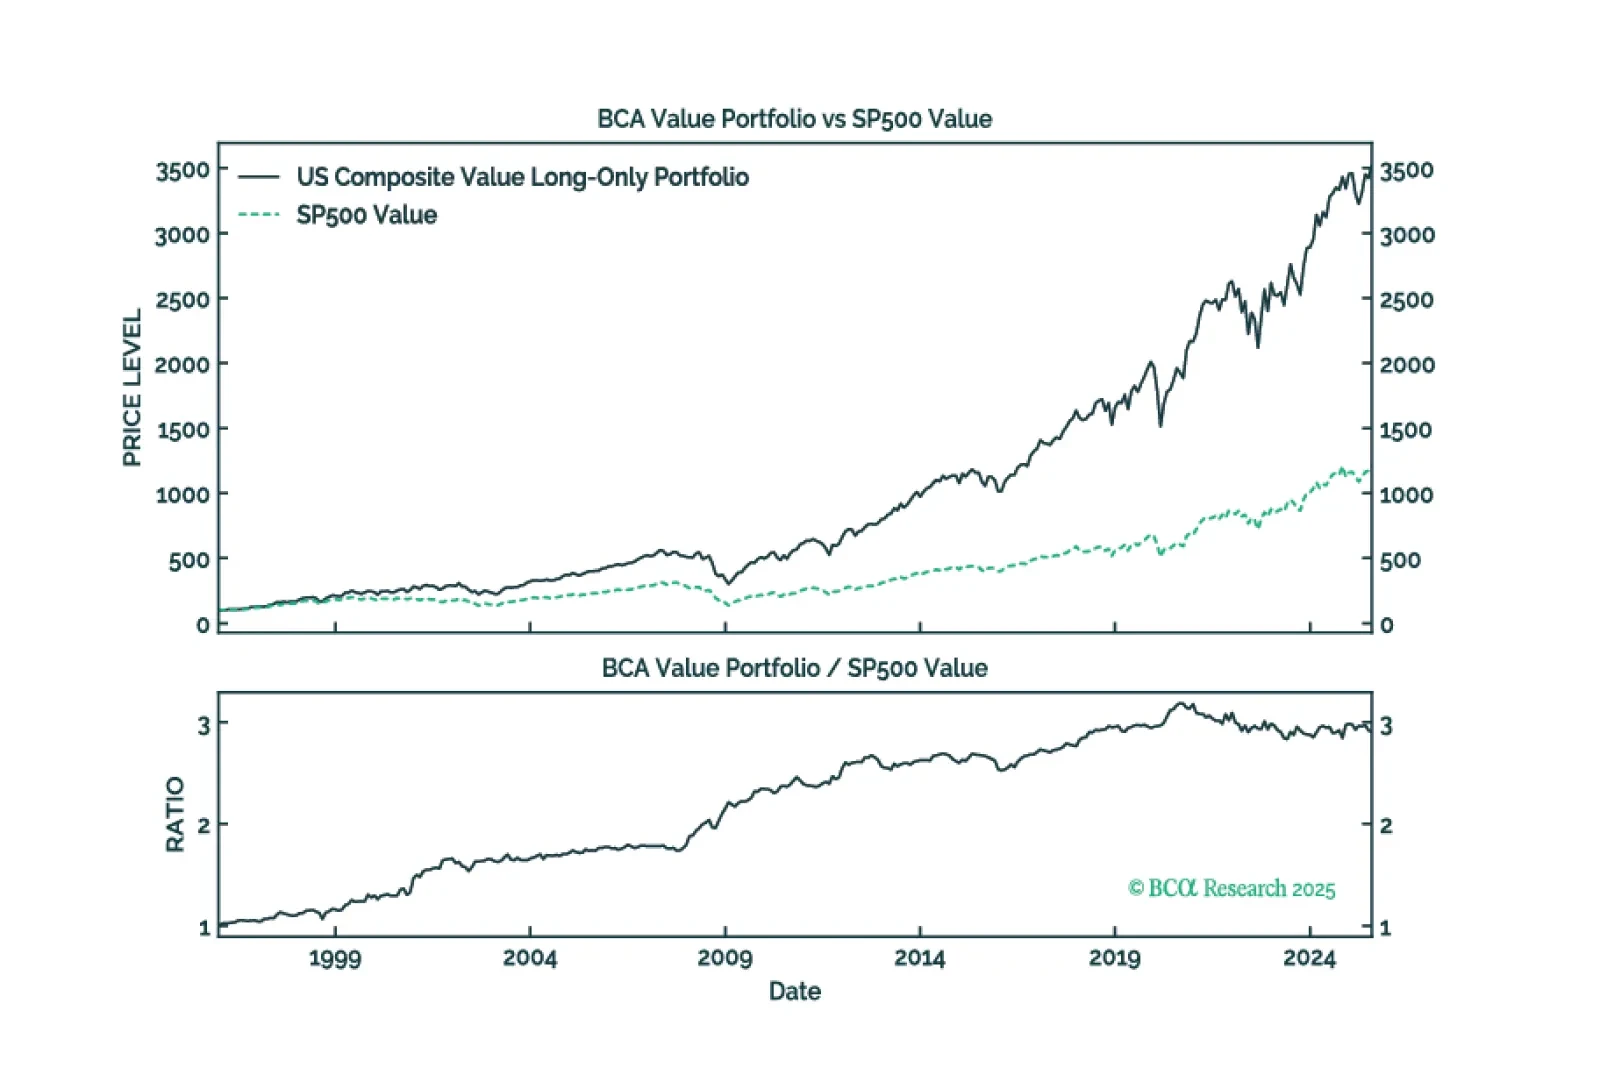
Commercial indices’ limitations have made Value a fertile ground for stock pickers. Our Composite Value model has shown promise in circumventing these flaws and capturing alpha.