Latest from BCA Research

This month, we focus on the One Big Beautiful Bill Act (OBBBA). Our assessment in the Alpha report is that there won’t be any remaining alpha to harvest by shorting duration. The team that coined the “Human Steepener” moniker for President Trump is, effectively, throwing in the towel on looking for more upside to yields. There are many reasons for that view, but the main one is that the OBBBA legislation is just not that profligate, especially not relative to the investors’ expectations in the early days of the Trump 2.0 term.
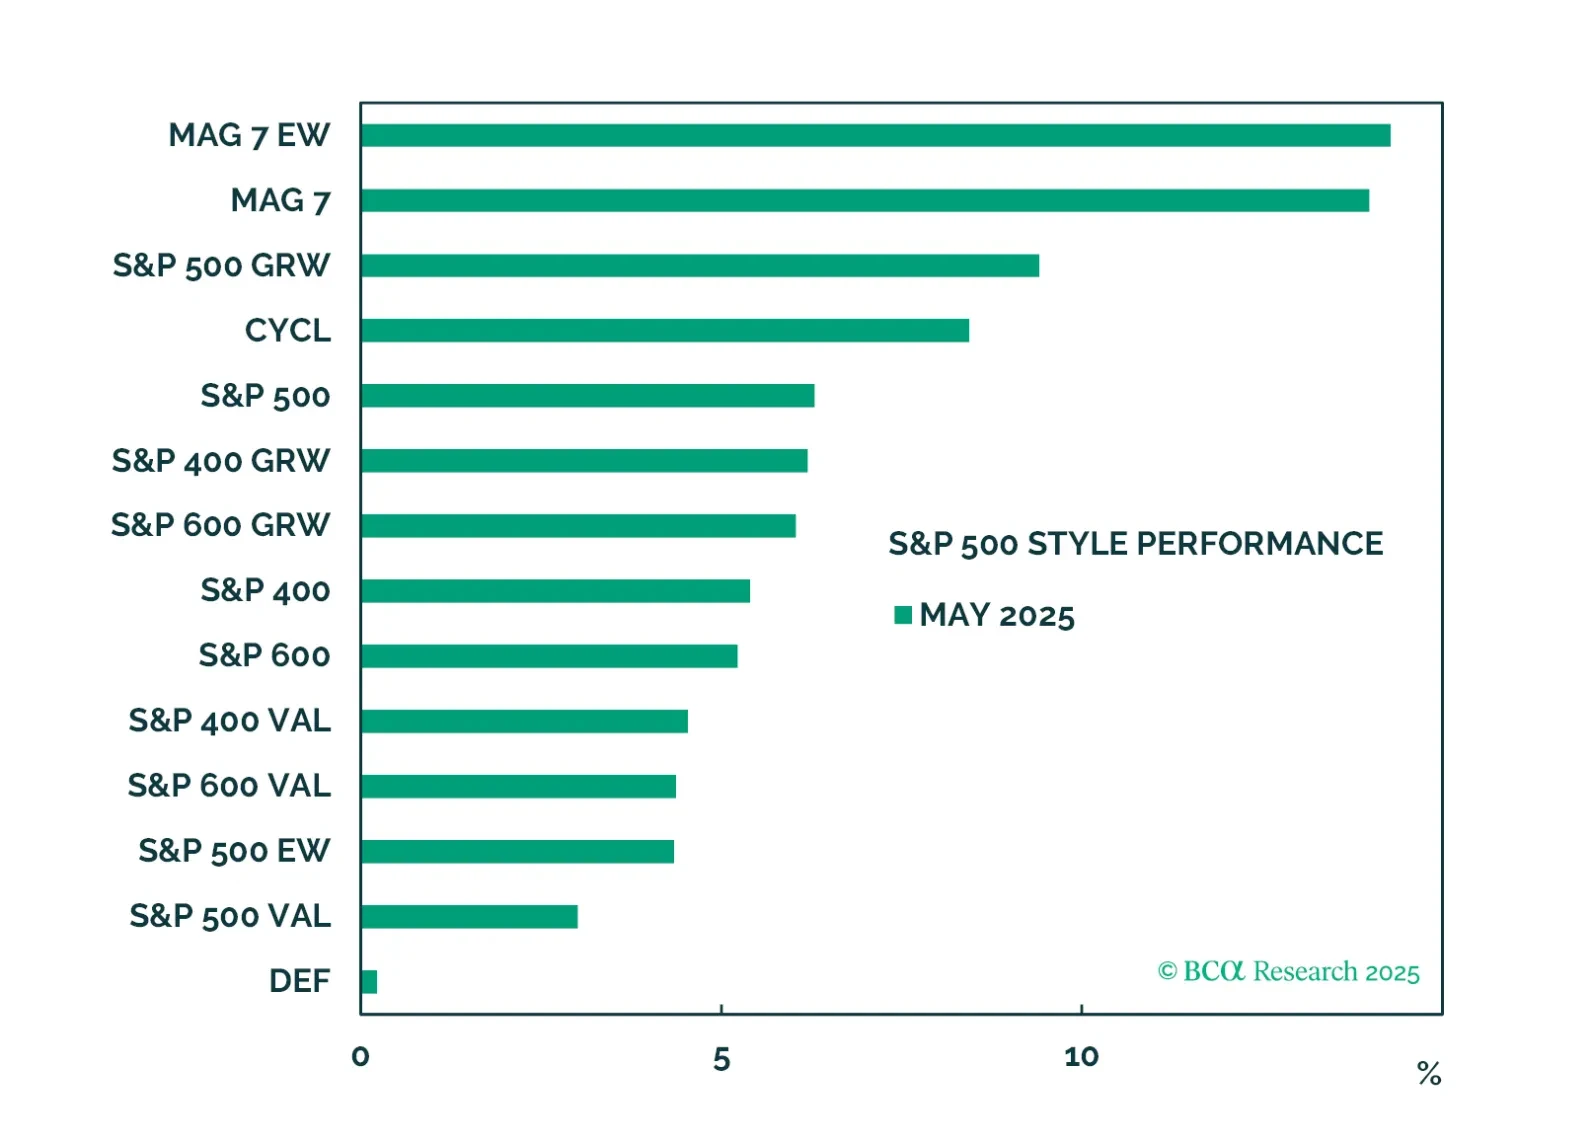
In the front section of the chart pack, we review May’s performance and adjust our portfolio positioning.
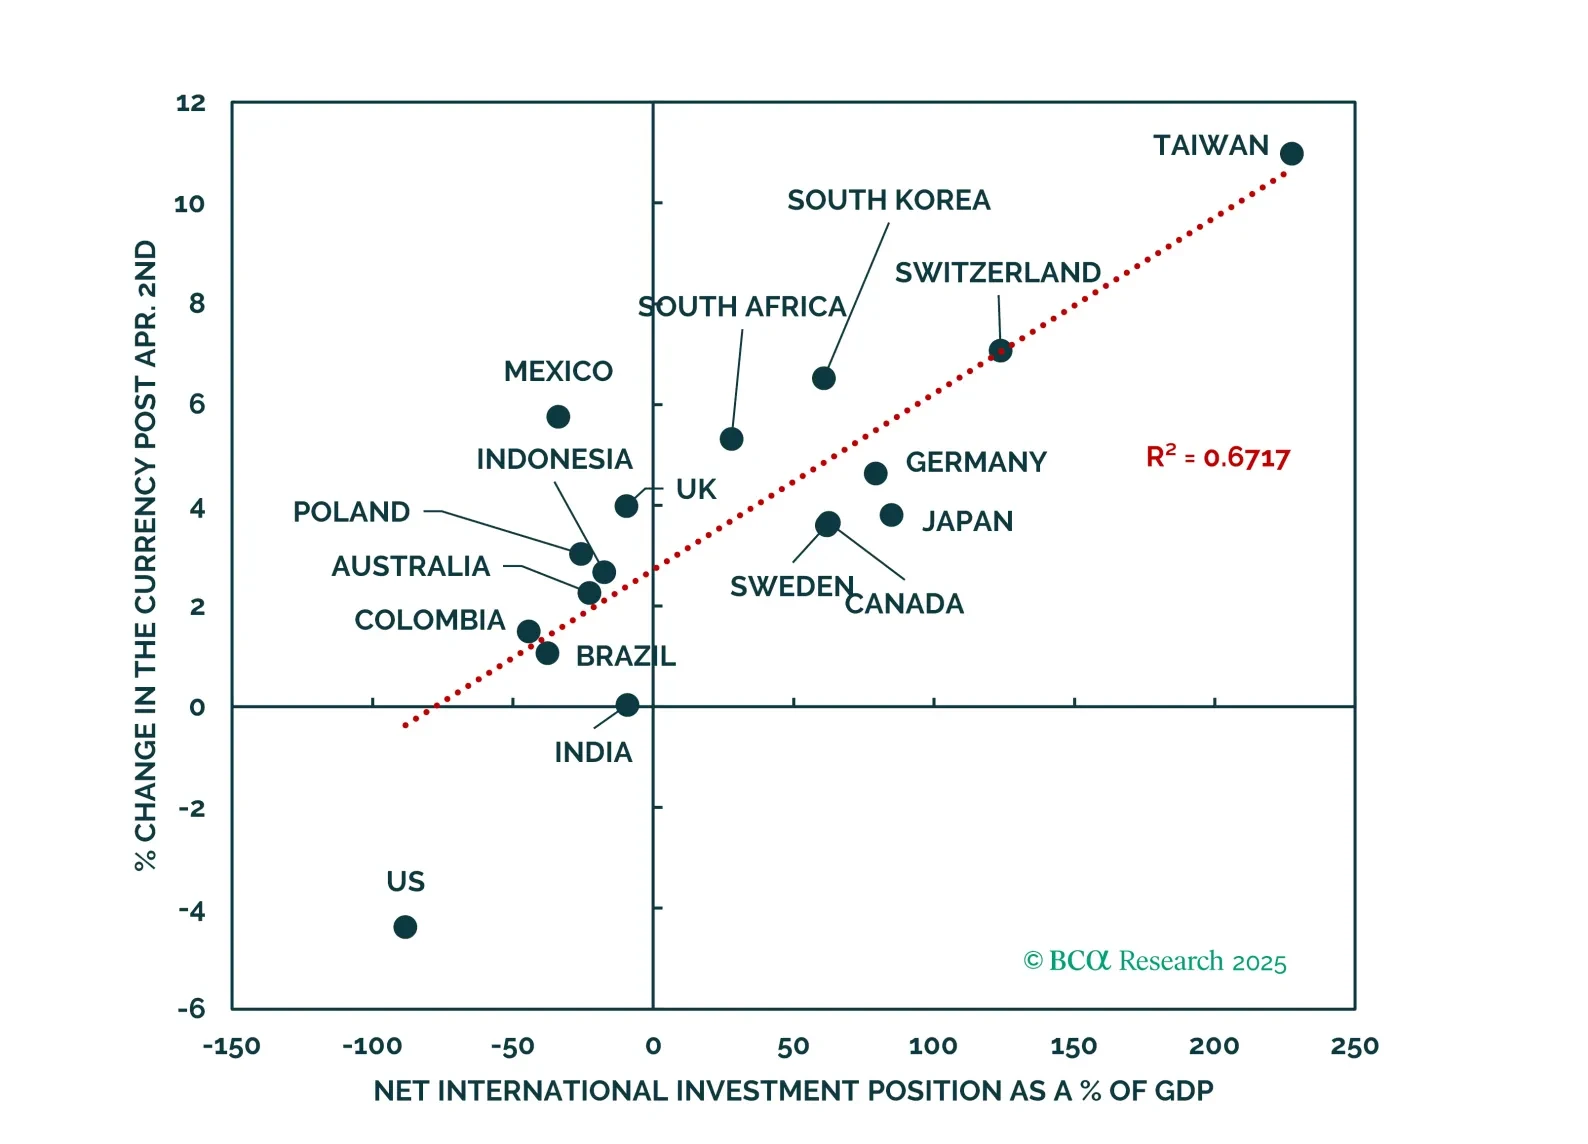
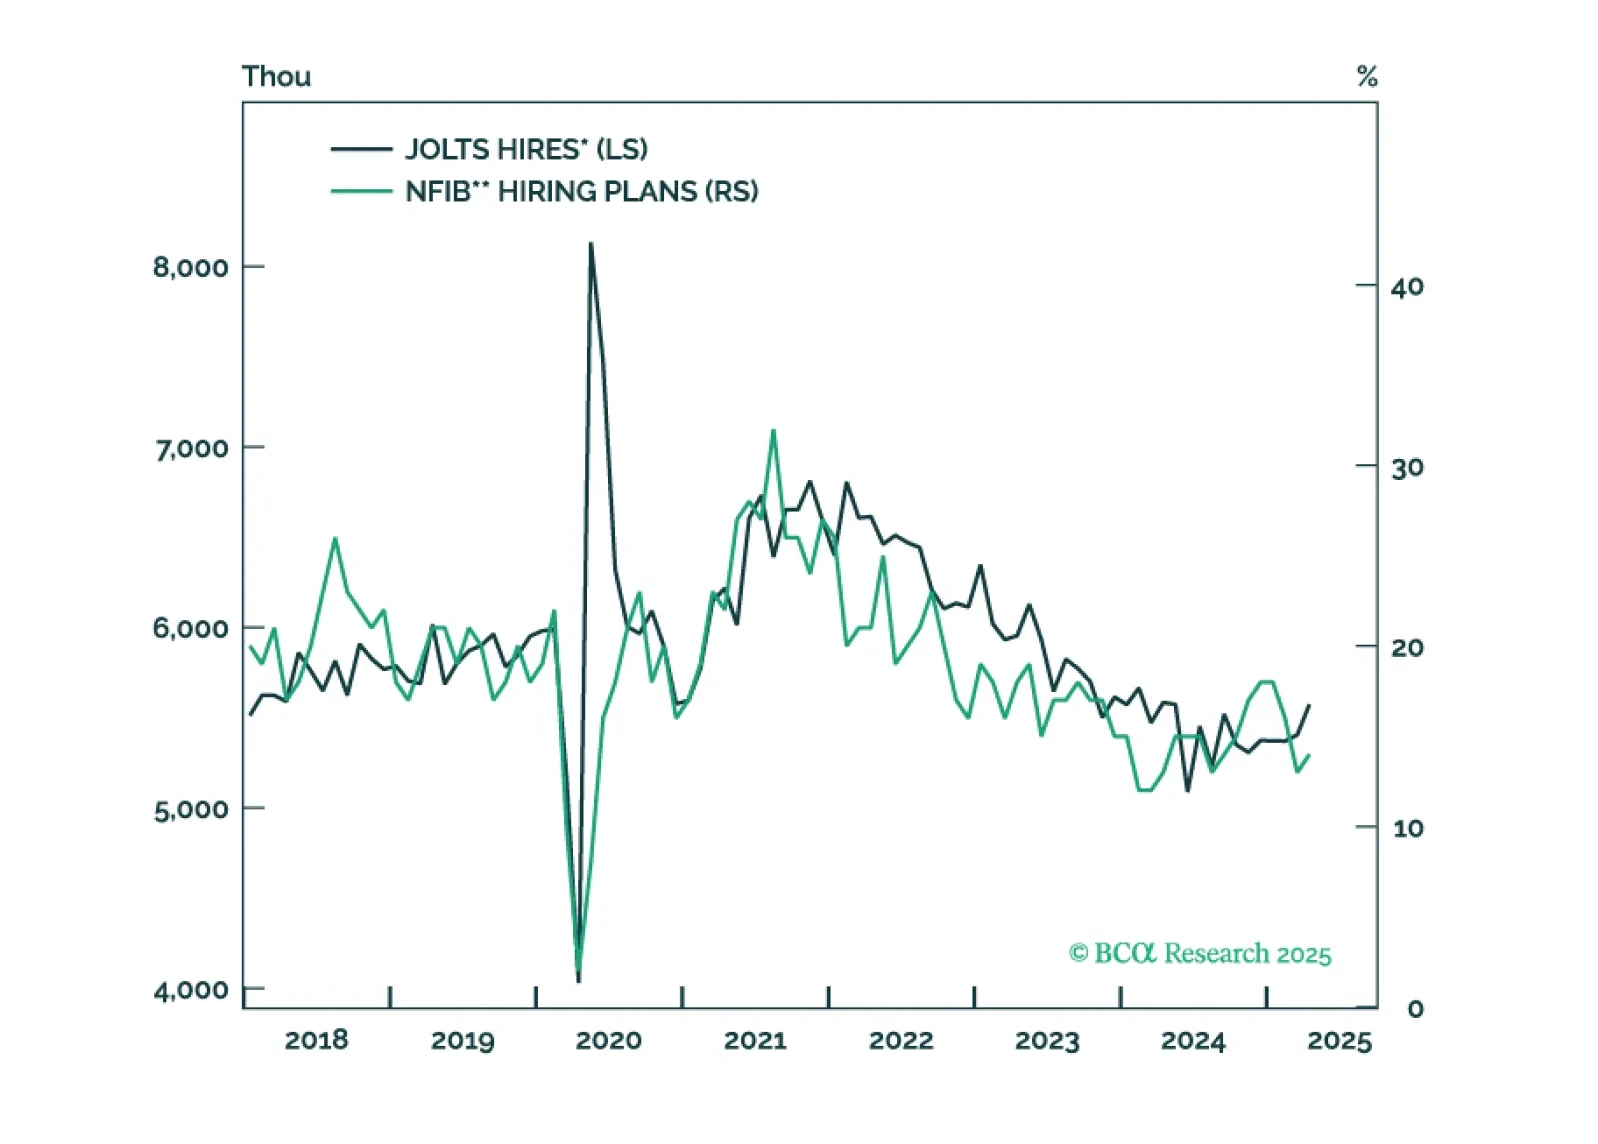
Fiscal policy, not tariffs, is now driving markets as Congress advances the One Big Beautiful Bill. The Senate cannot afford to remove the spending cuts in the bill, as they risk sparking a bond market riot. Even with this more modest bill, US interest rates are already pressuring housing and labor markets. US assets are also losing their defensive tilt. Better opportunities for both equity and fixed income investors are available internationally. We conserve our defensive stance but do not want to be dogmatic. Sentiment is more cautious than last year, and the US economy is not showing signs of imminent collapse. We remain underweight the US dollar and US equities. Upgrade Communication Services and downgrade Consumer Staples. Upgrade the CNY and EM currencies to neutral.
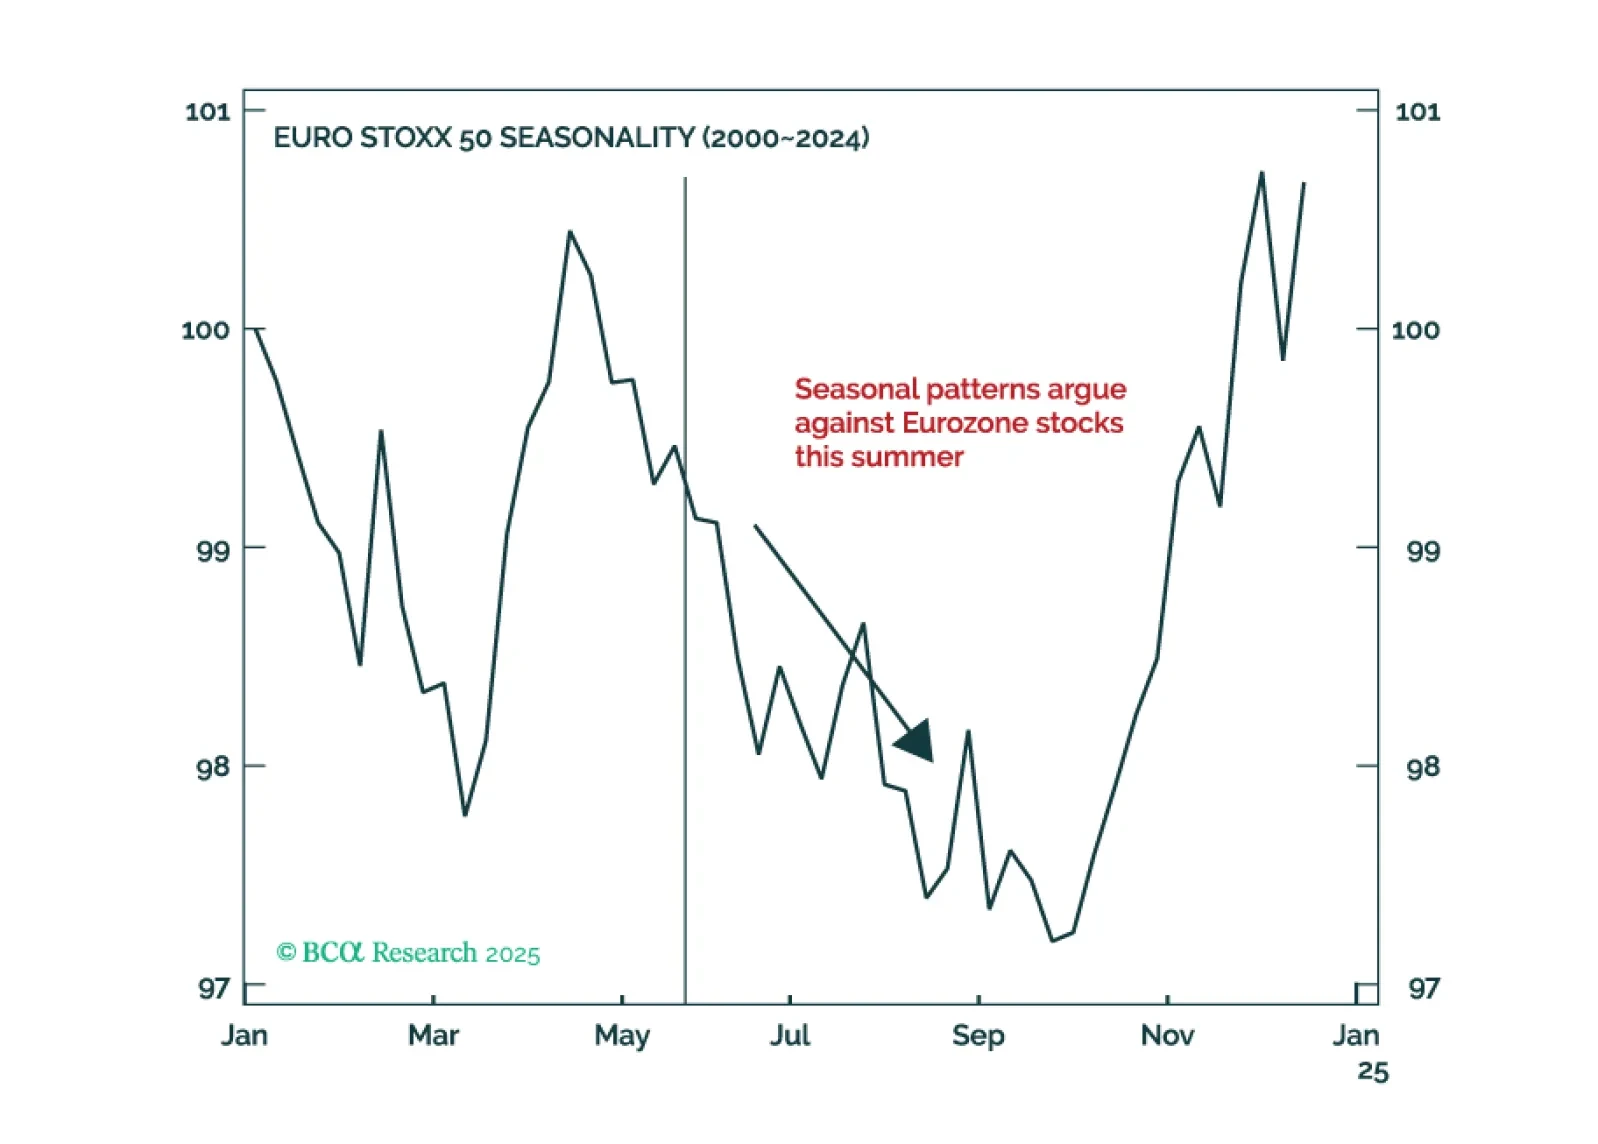
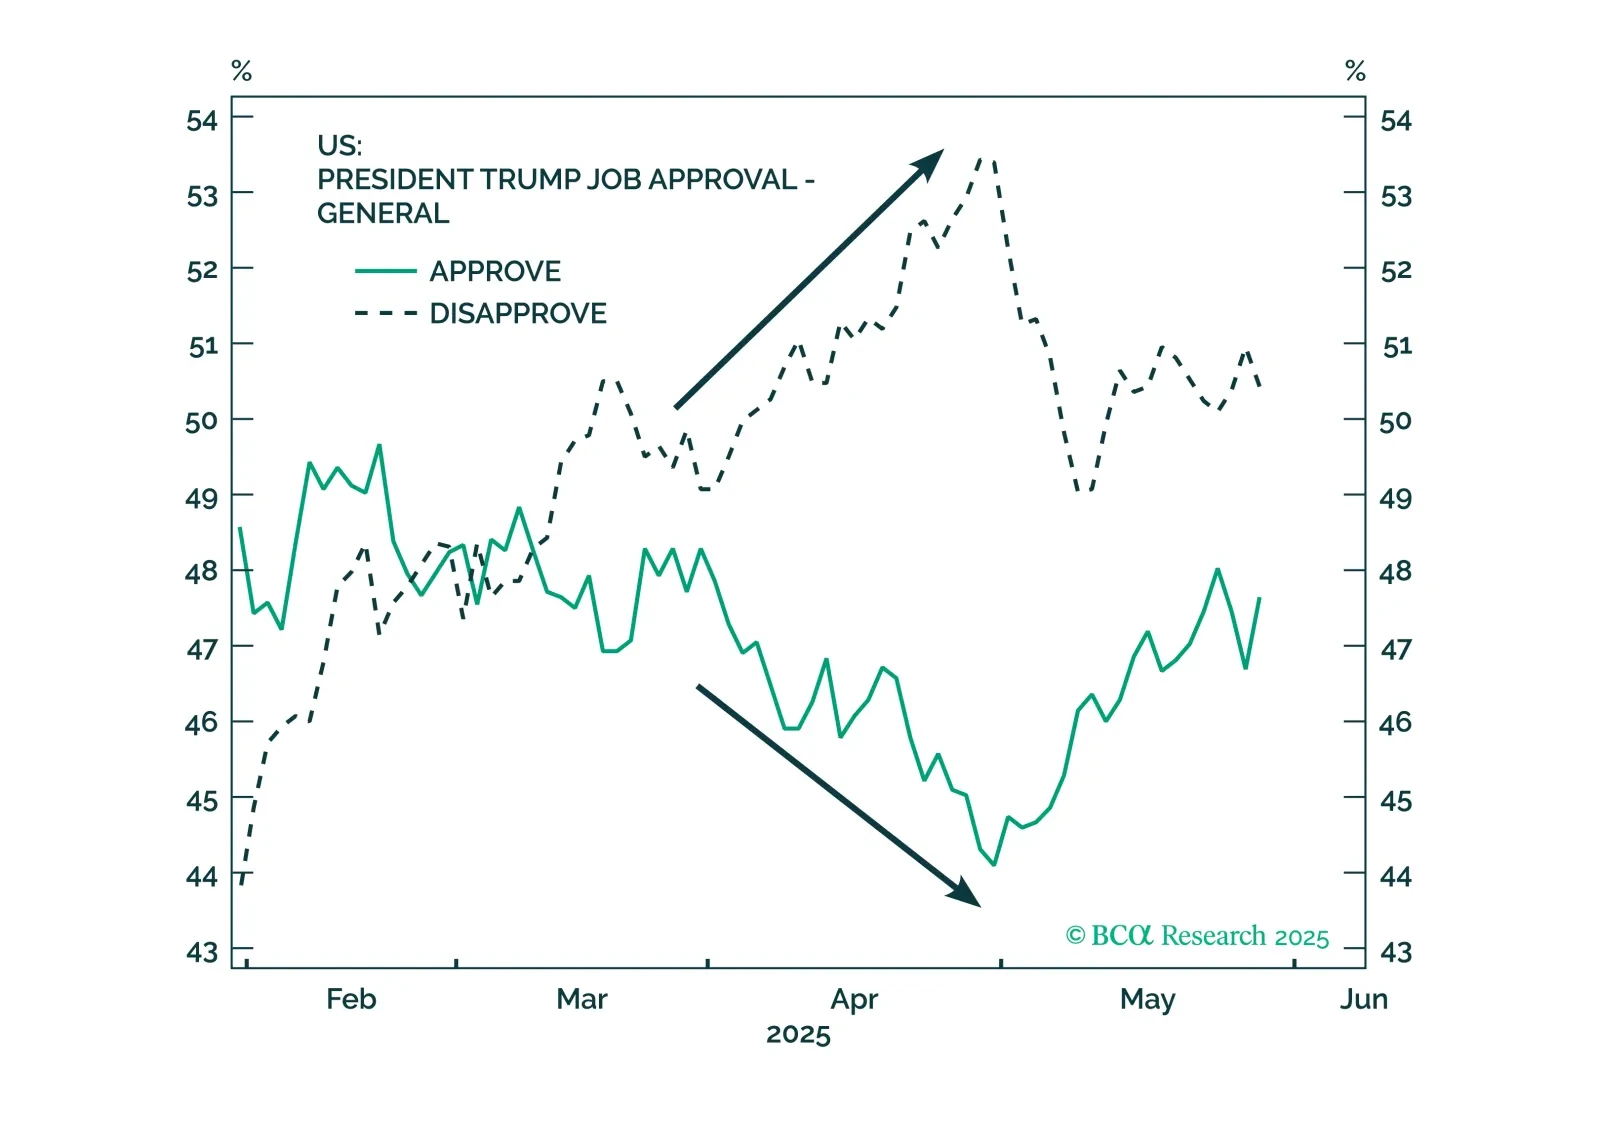
After considering some of the most common bullish arguments, we stand by our recession view and reiterate our defensive asset allocation recommendations.
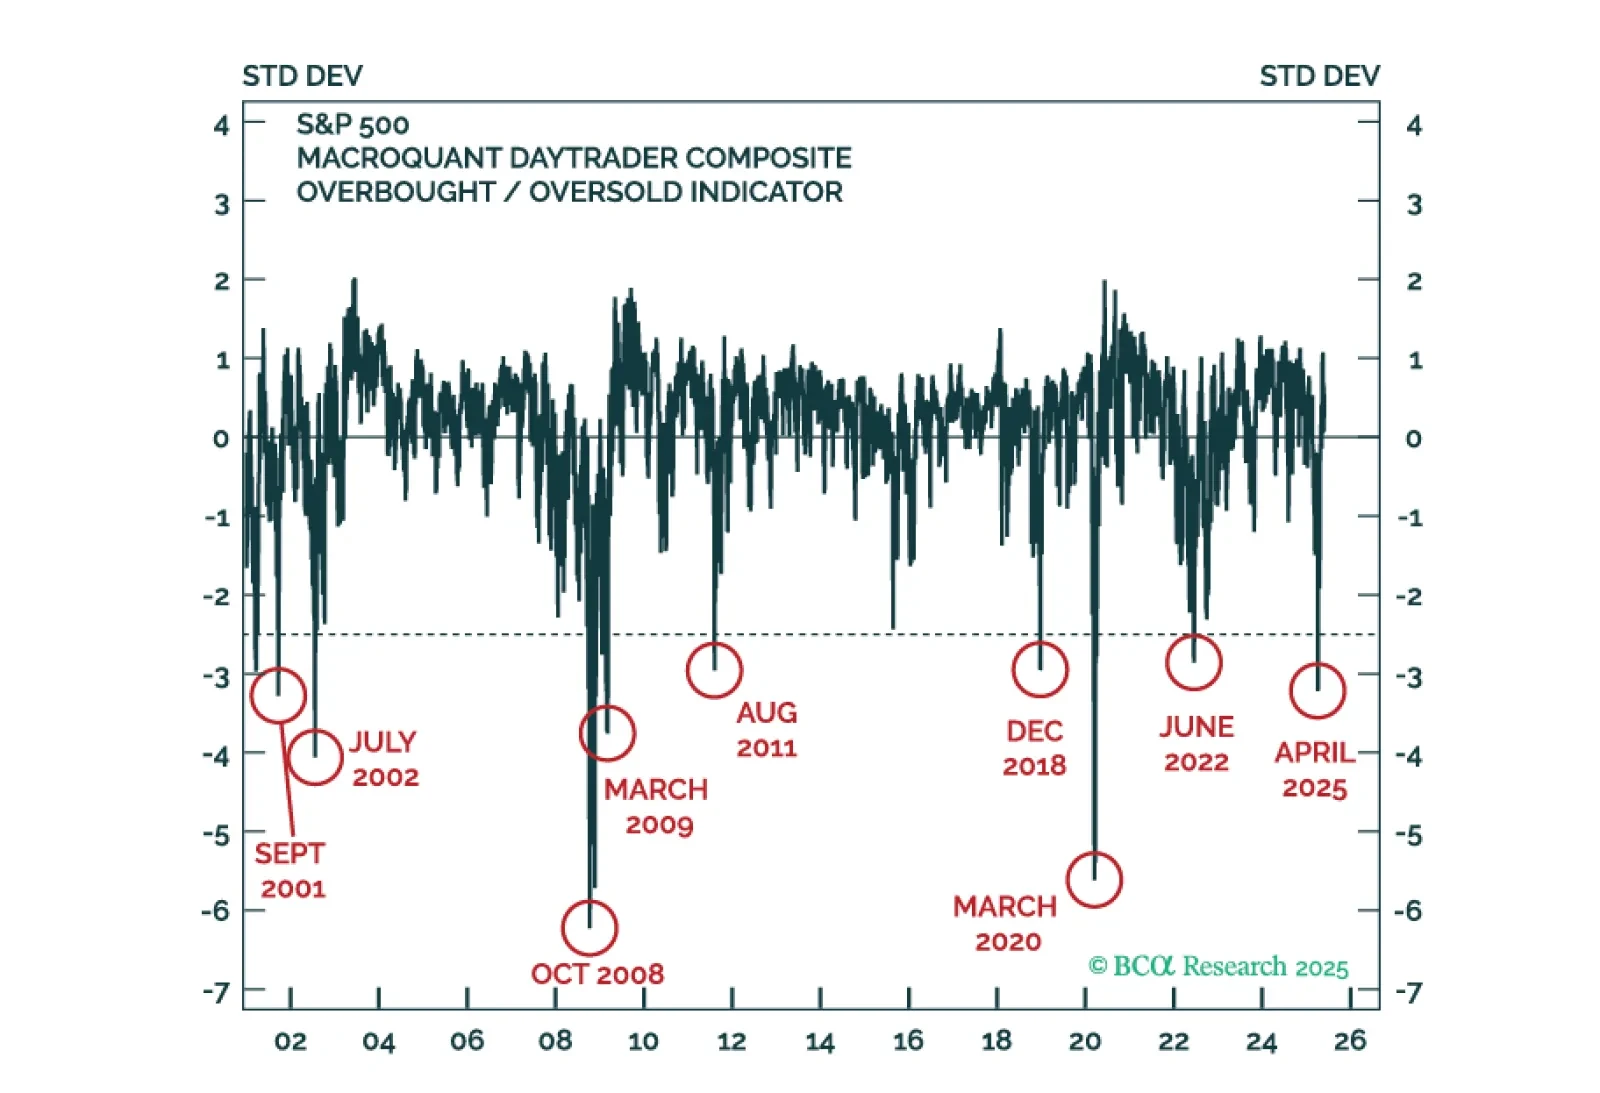
MacroQuant warns that US equities are pricing in very little economic risk. The model is shunning equities and recommends a large overweight to cash.
MacroQuant warns that US equities are pricing in very little economic risk. The model is shunning equities and recommends a large overweight to cash.
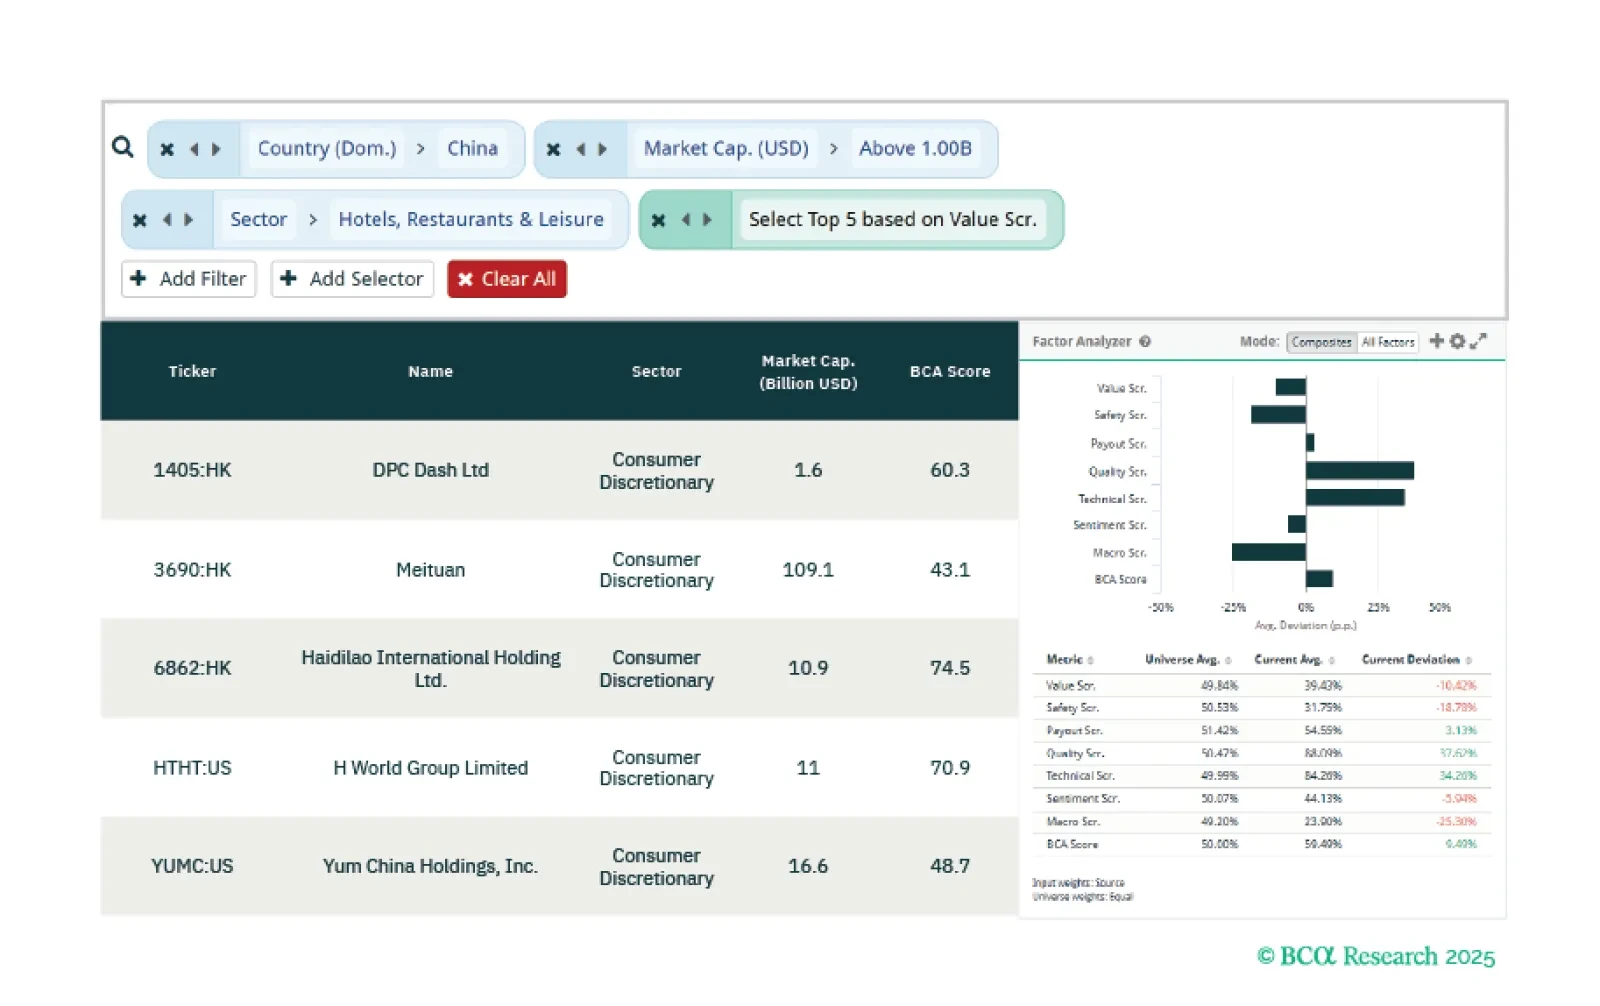
This week, our three screeners explore opportunities in: Chinese tourism, European telecoms, and US health care stocks.

Private Credit return expectations edge lower. Middle Market Direct Lending remains attractive, rivaling Middle Market Buyouts.