 CoreMacro
| Emerging Markets
Research on emerging economies, from in-depth country reports to calls on EM stocks, bonds, and currencies.

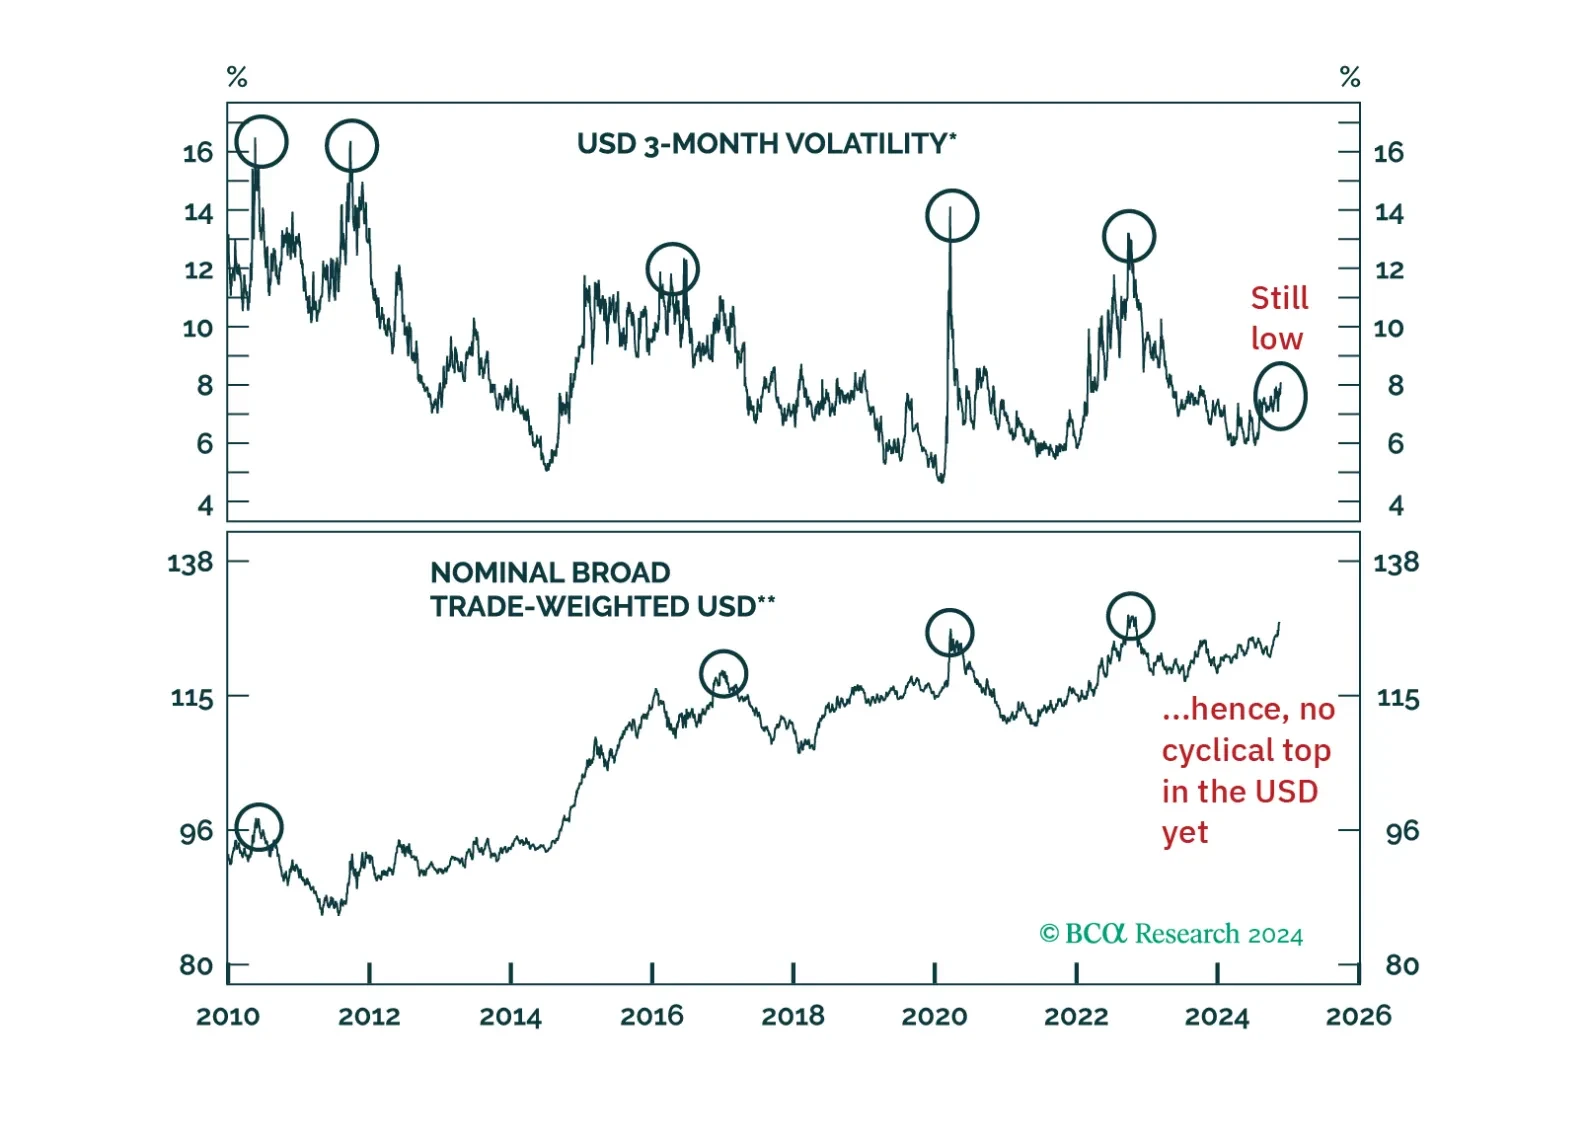
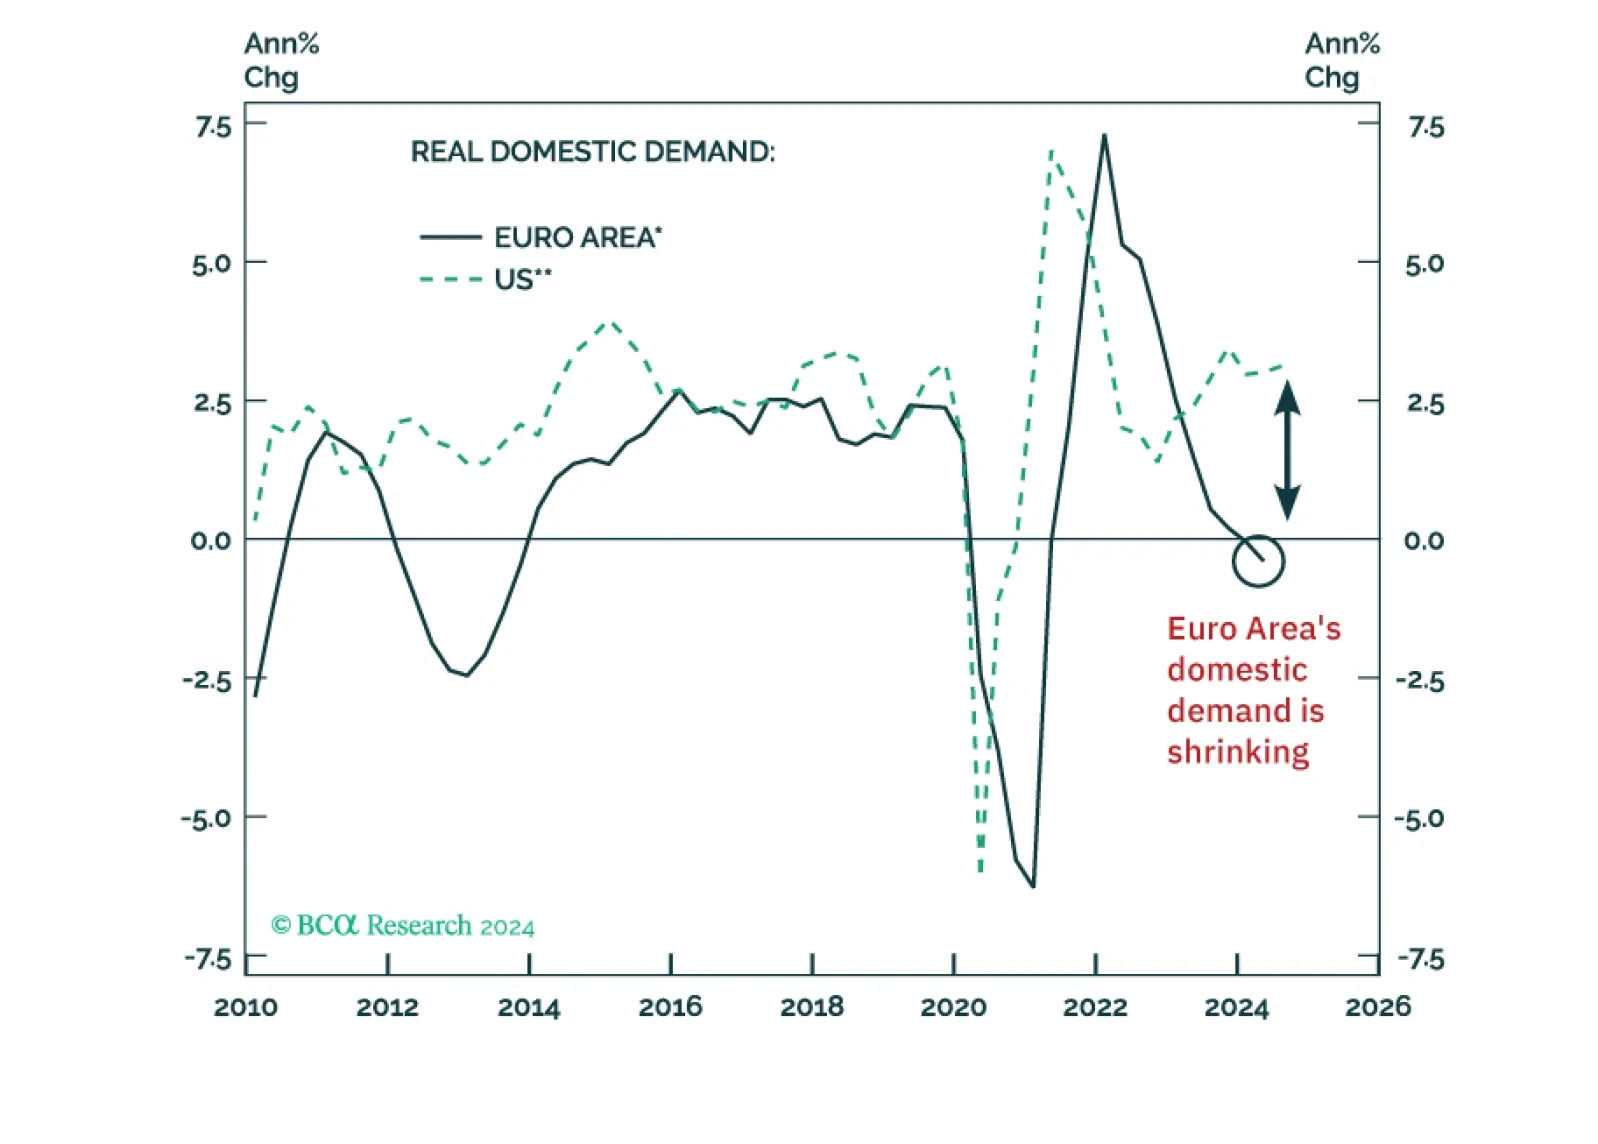
The threat of import tariffs and US growth outperformance versus the rest of the world will continue supporting the US dollar rally over the near term. Nevertheless, the Trump administration’s medium- to long-term goal will be a US dollar devaluation to boost the country’s manufacturing competitiveness. We will recommend upgrading EM stocks and bonds when we downgrade our US dollar view.
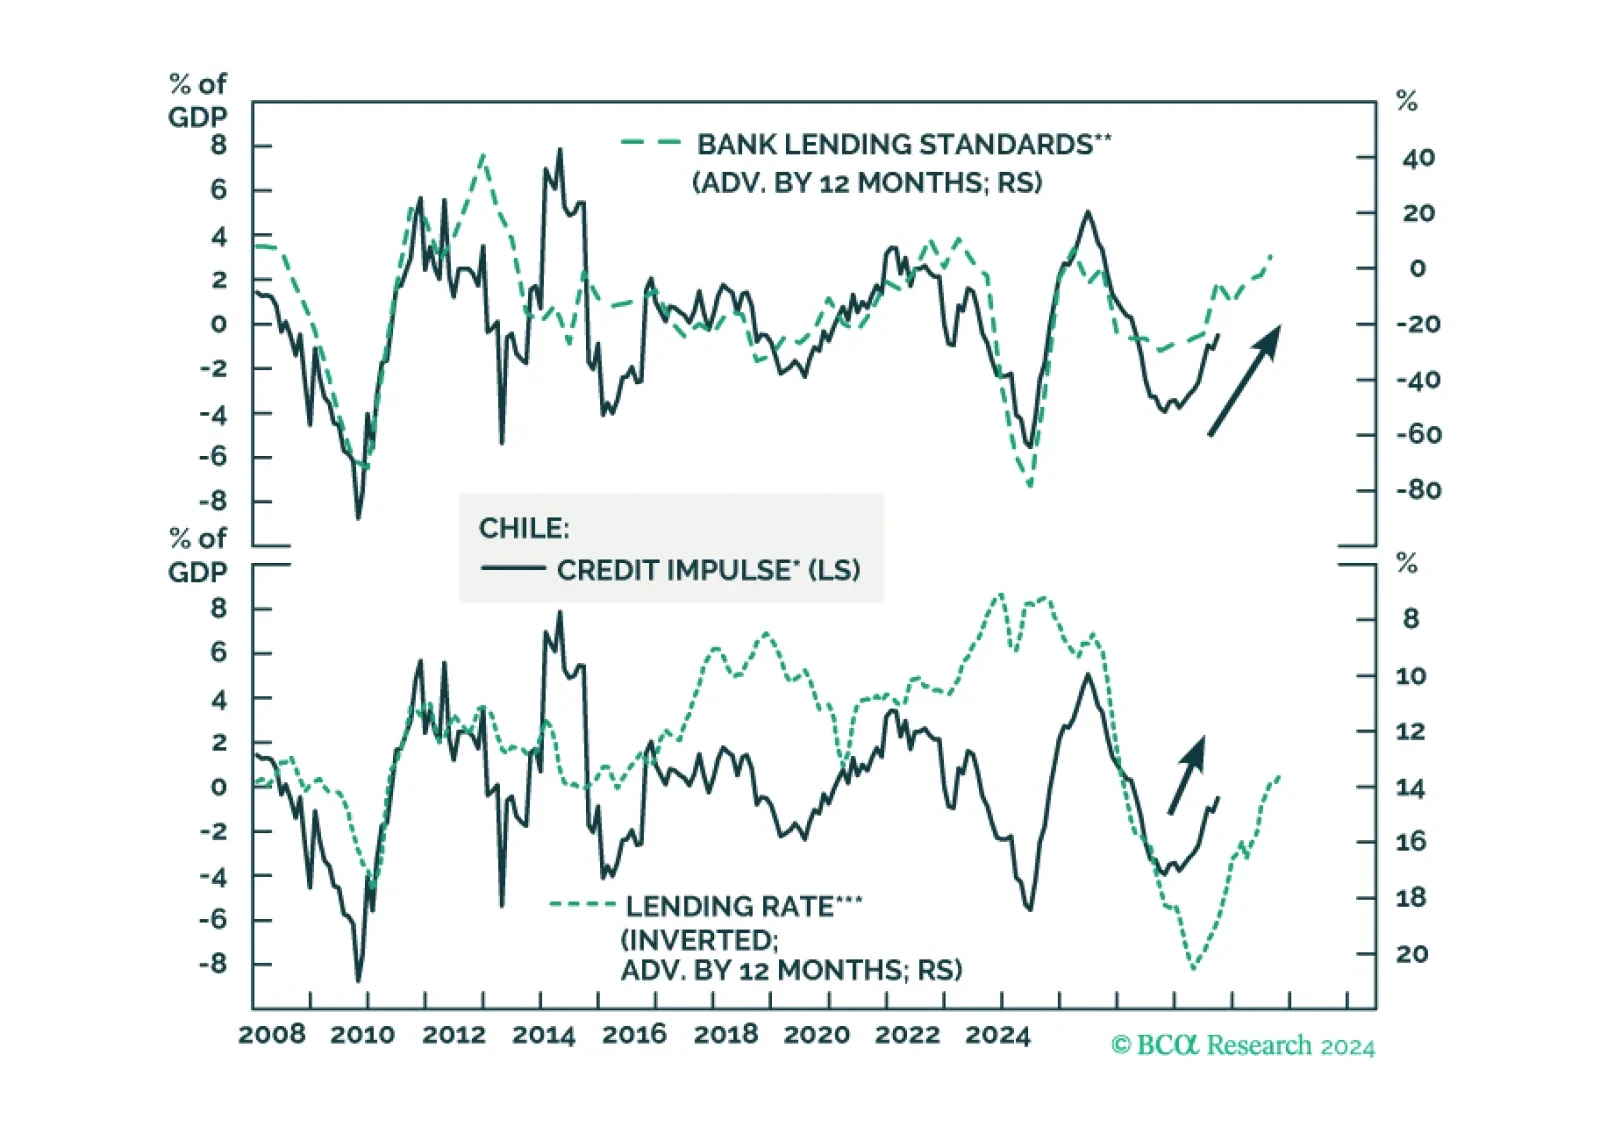
In absolute terms, Chilean markets and the currency will fall given a strengthening trend in the US dollar and weak global trade. However, Chile’s economy can withstand the global trade slump relatively well due to substantial monetary easing at home, which will help Chilean markets outperform EM peers. Moreover, a favorable and improving political backdrop and attractive valuations will benefit Chilean equities and the peso versus their EM counterparts.
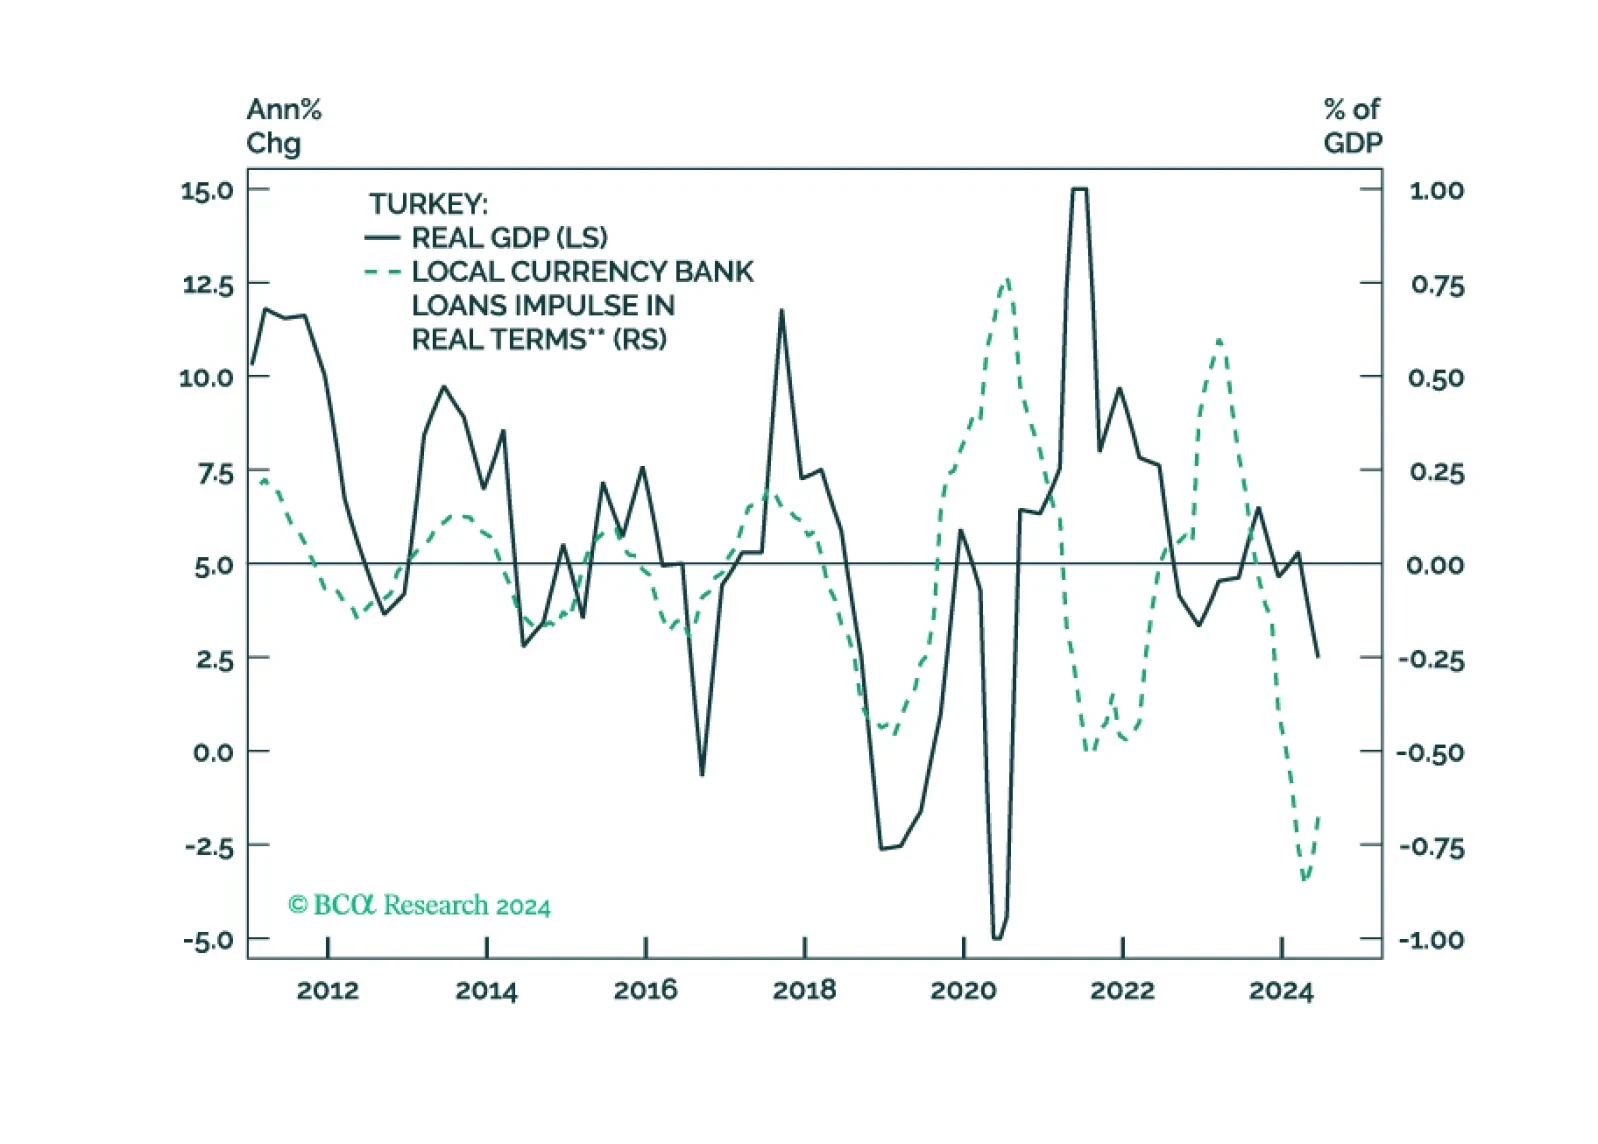
Turkey has a path toward sustained disinflation. But that will require tight macro policies for an extended period. The question is, will the authorities tolerate the consequent growth slowdown, even a recession, and surging unemployment, as the necessary cost to break the back of inflation?
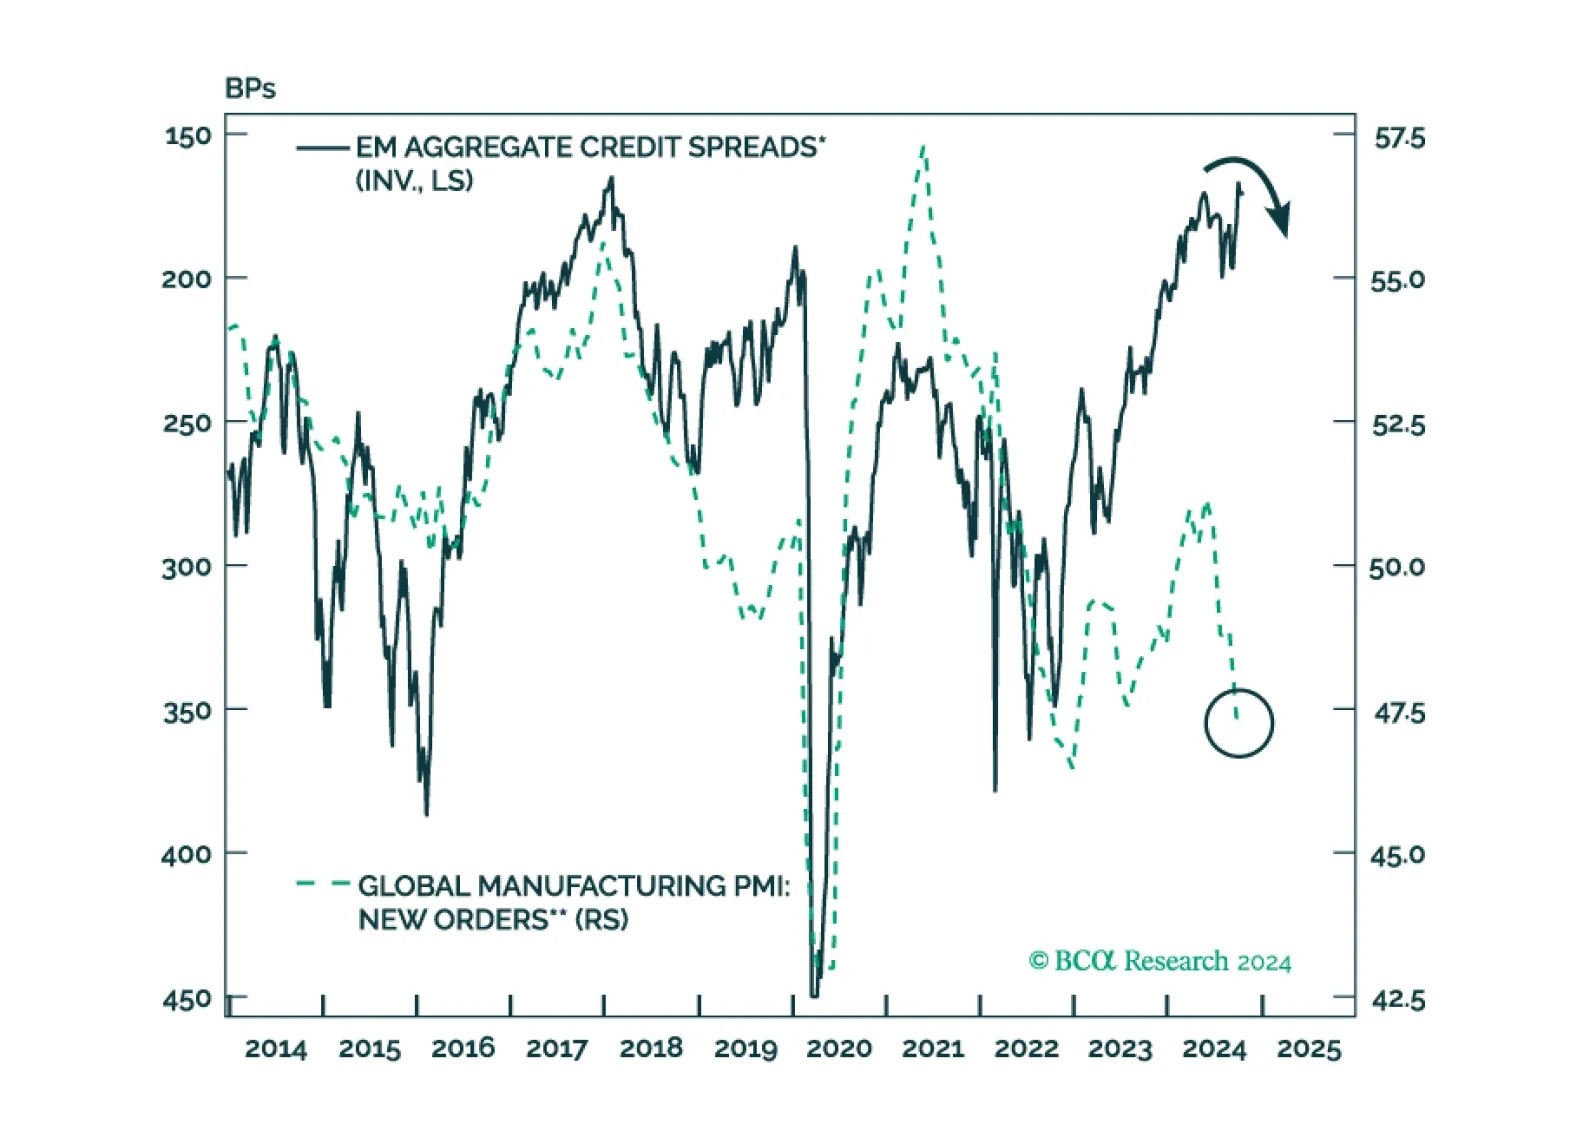
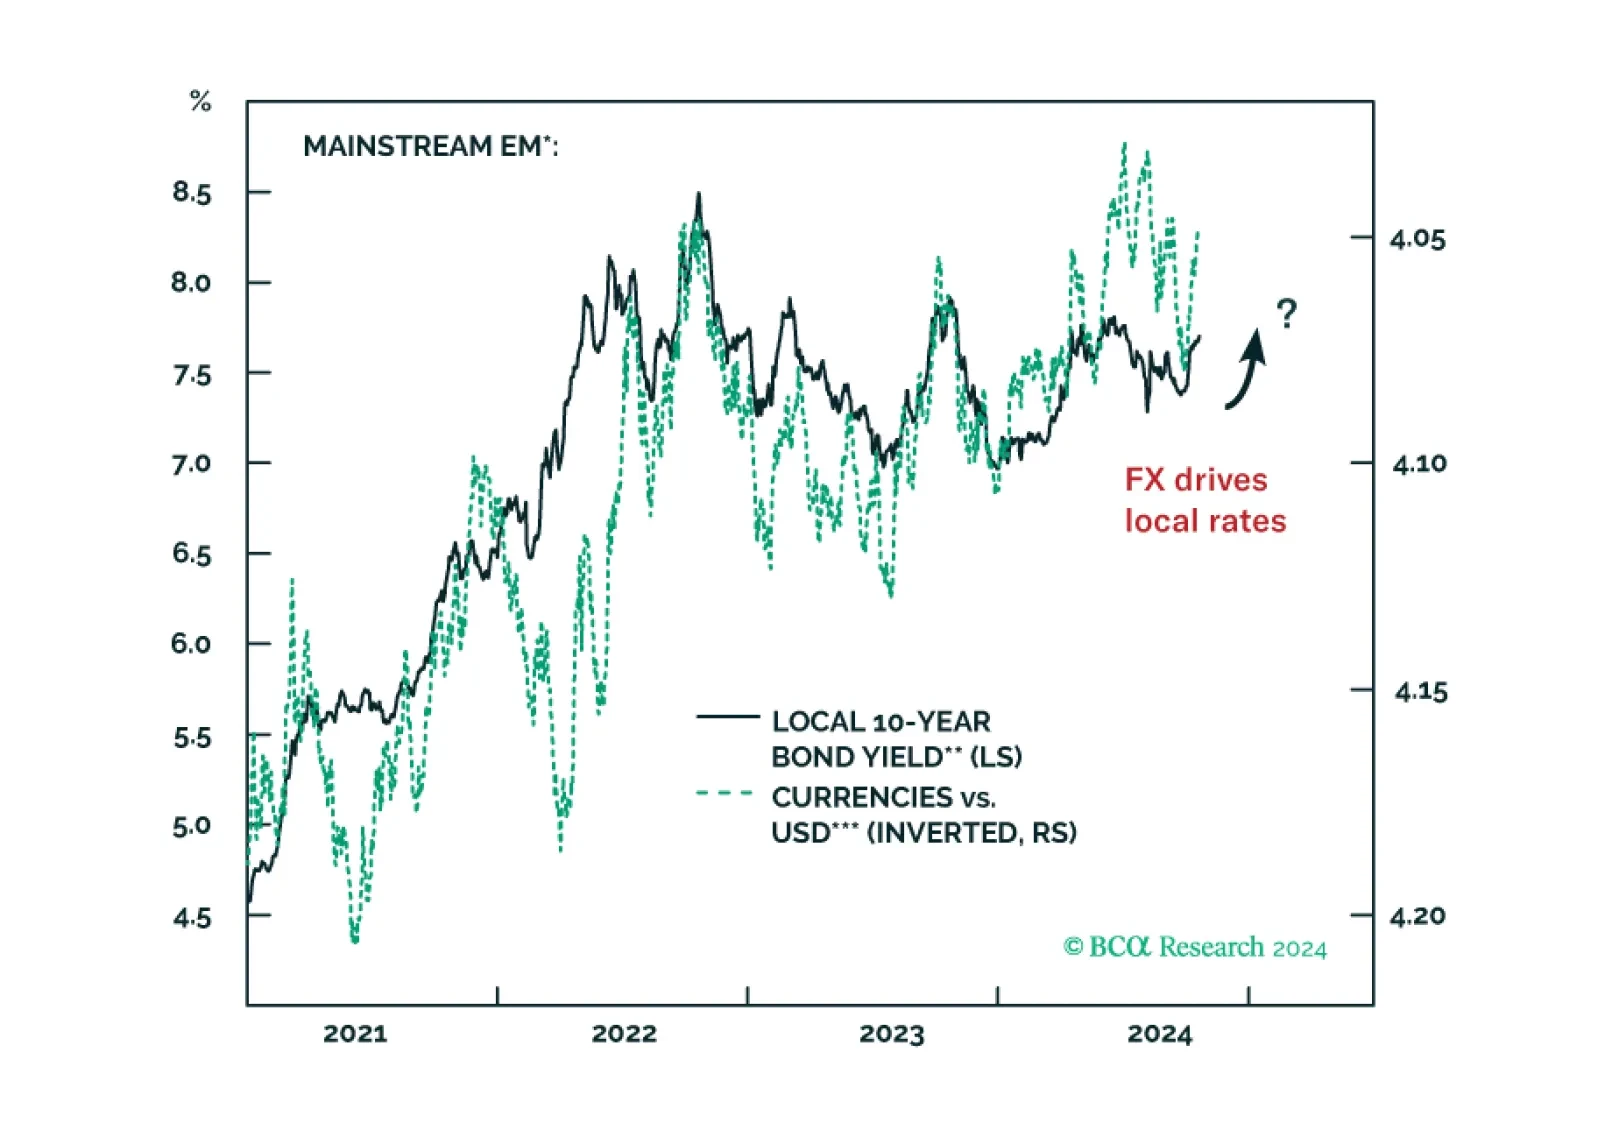
As the odds of a Trump victory increase, there are indications that the “Trump trade” has commenced in global financial markets, with negative short-term implications for EM. In short, the US dollar will strengthen, and US bond yields will rise in the lead-up to and after the election if Trump wins. In response, EM countries’ currencies will depreciate, and their fixed-income and equity markets will suffer over the coming months.