 CoreMacro
| Europe
Country-by-country analysis of Europe’s economy, policy, and politics, pinpointing opportunities across the region.
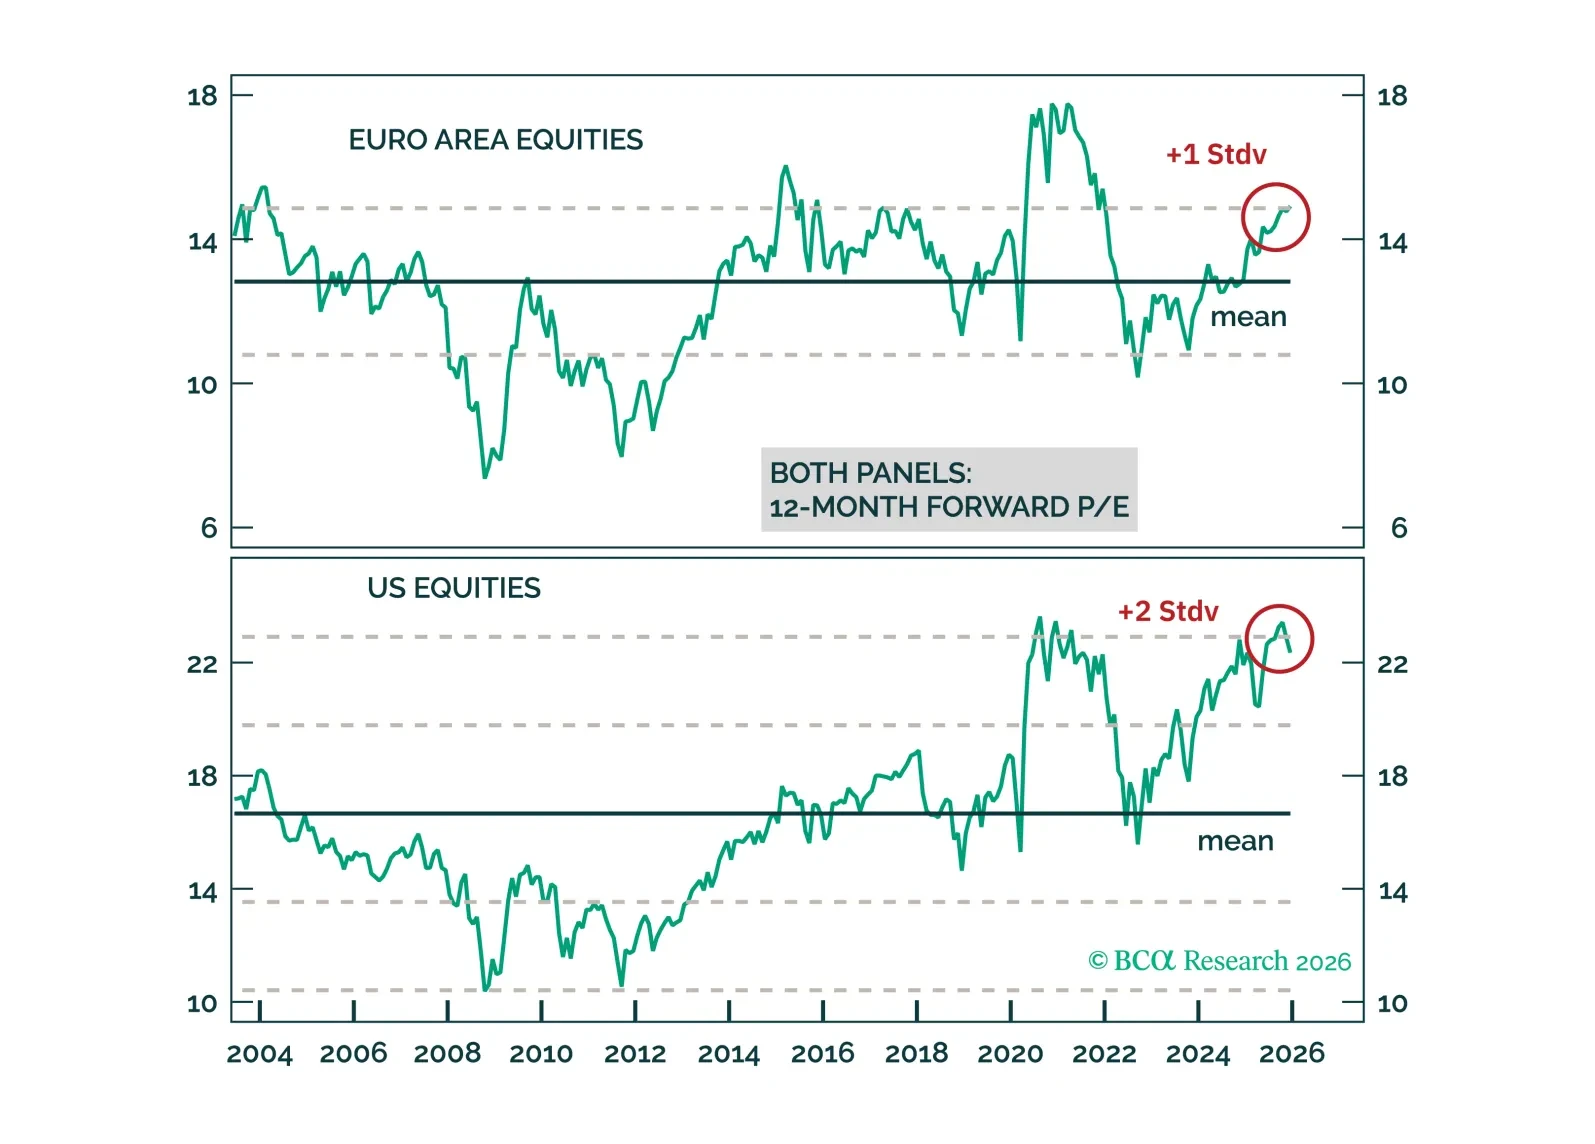
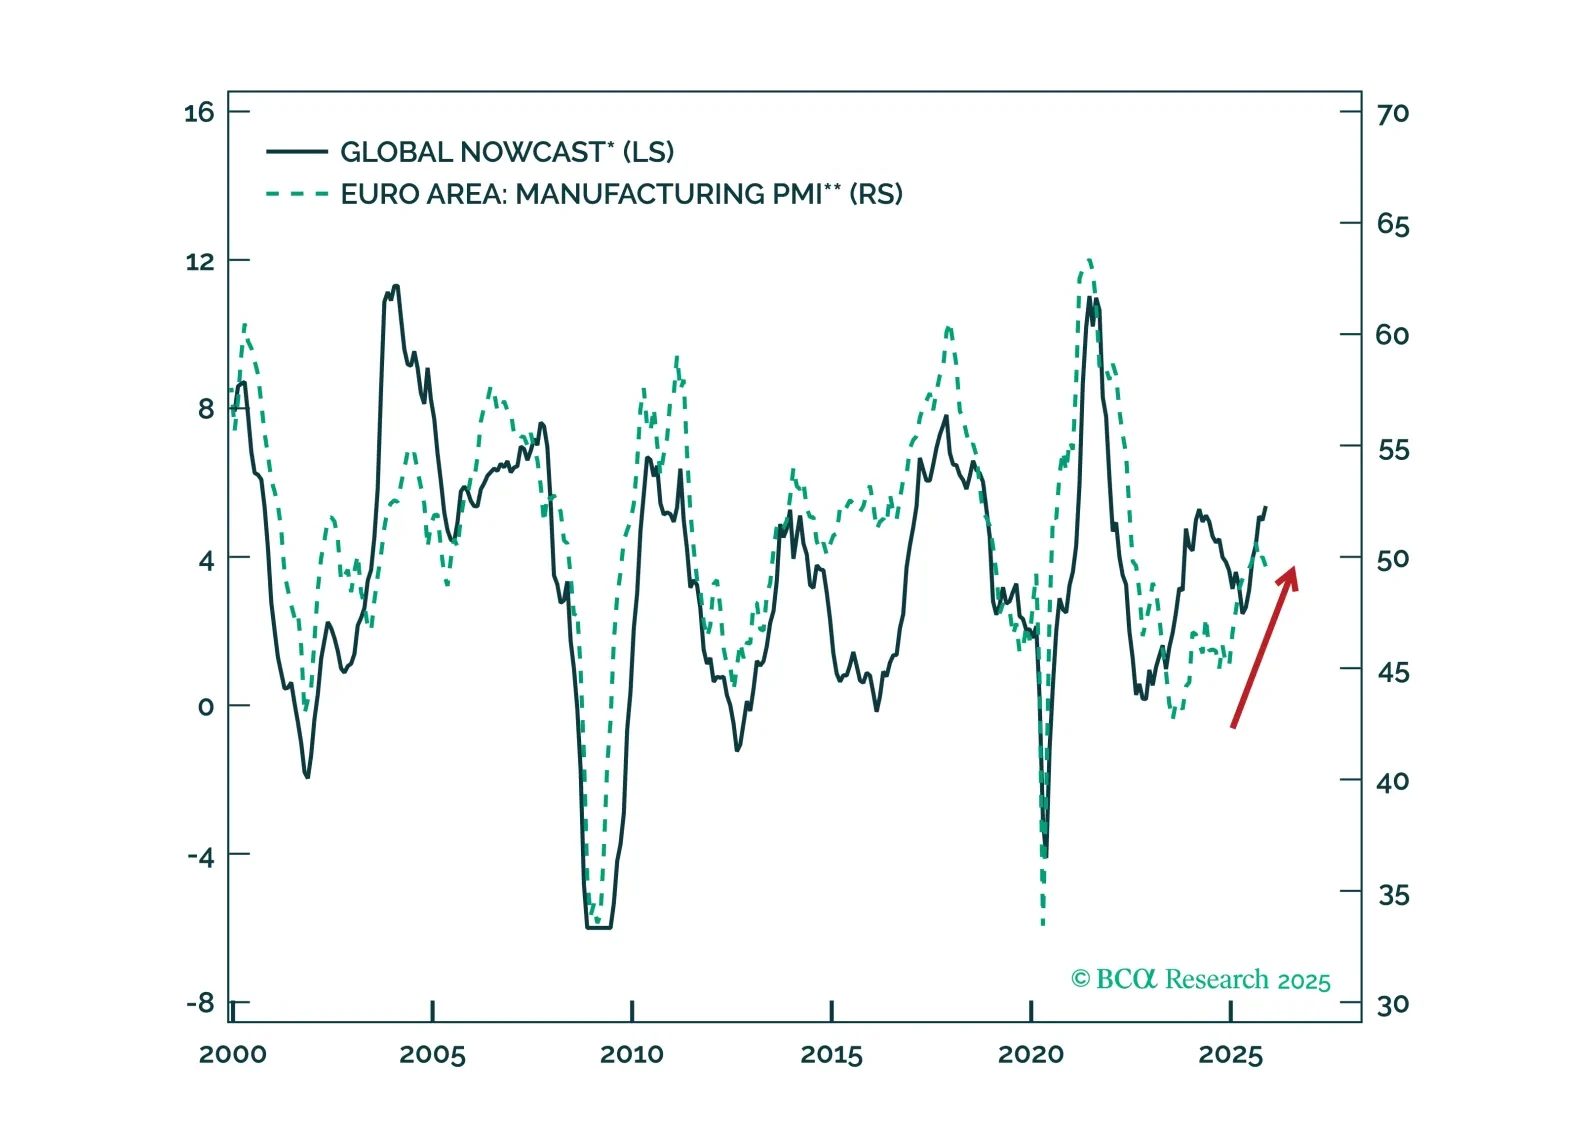
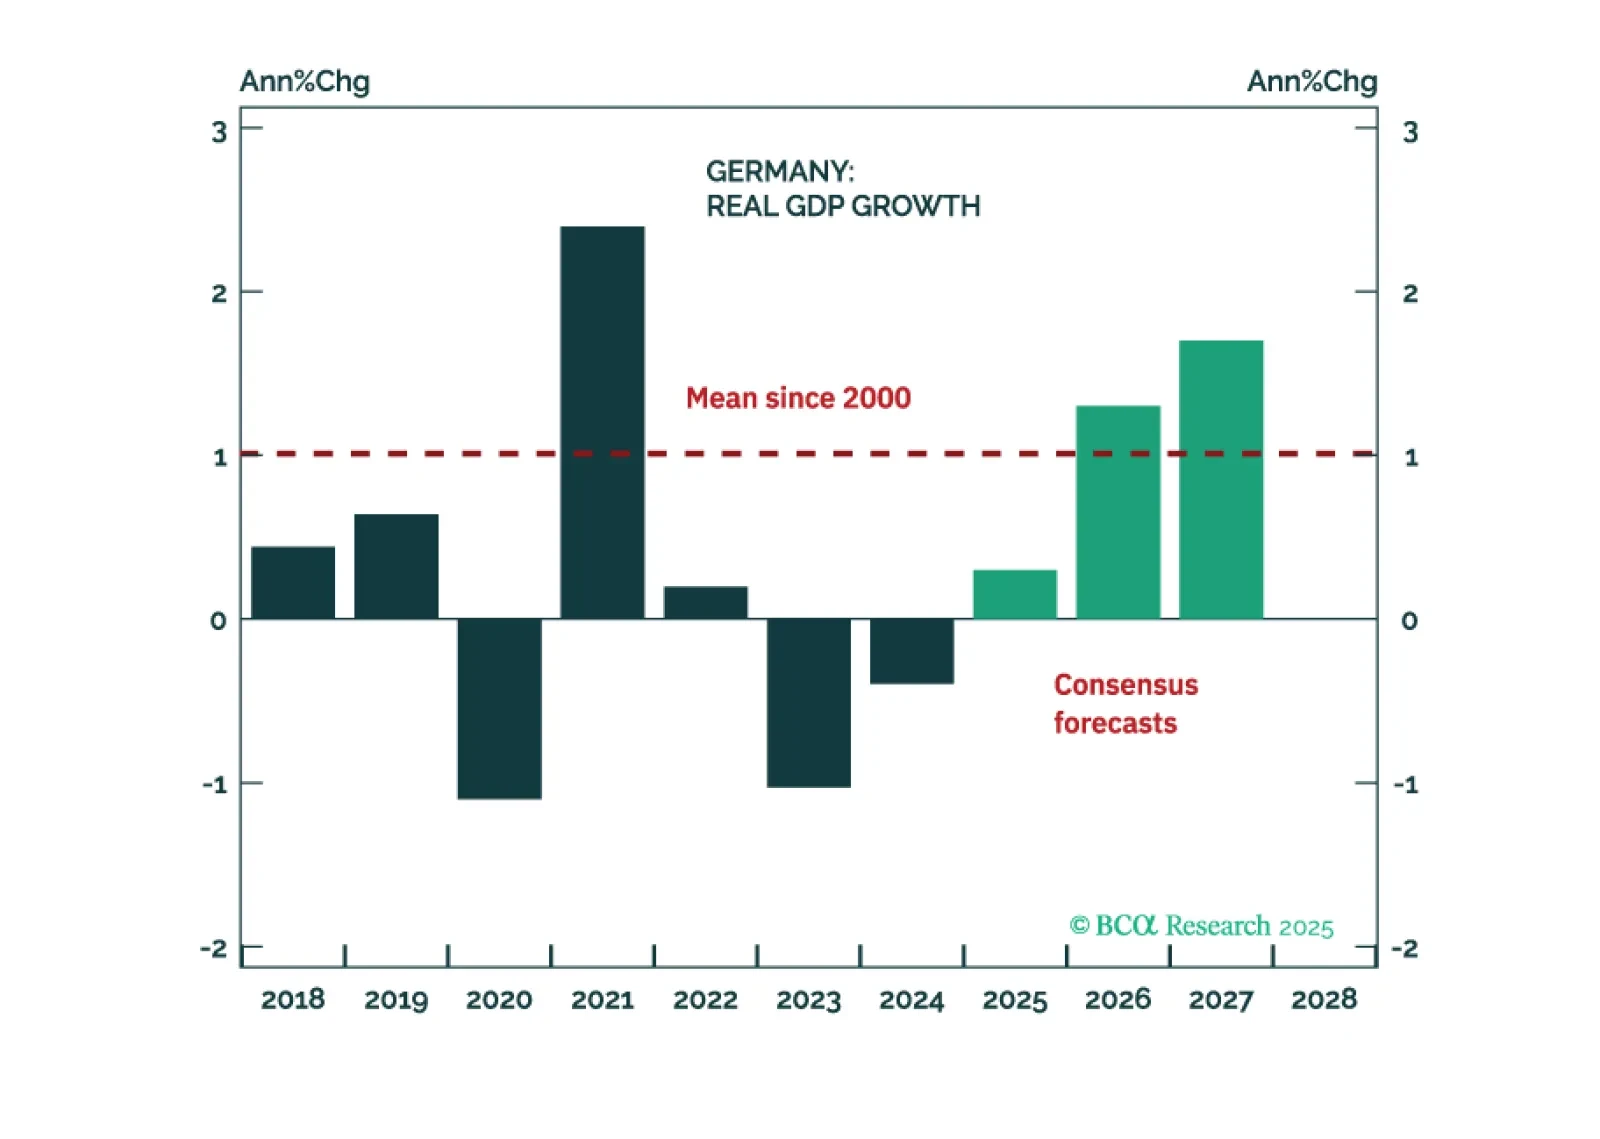
Europe is in a geopolitical sweet spot. Exaggerated fears of Russian military aggression and abandonment by the United States, as well as increased competition from China, create a geopolitical imperative to stimulate, reflate, and reform. Taken together with fading cyclical headwinds, it suggests that European risk assets can continue to outperform US ones on a cyclical investment time horizon. Remain long European stocks, in particular industrials, and EUR/USD.
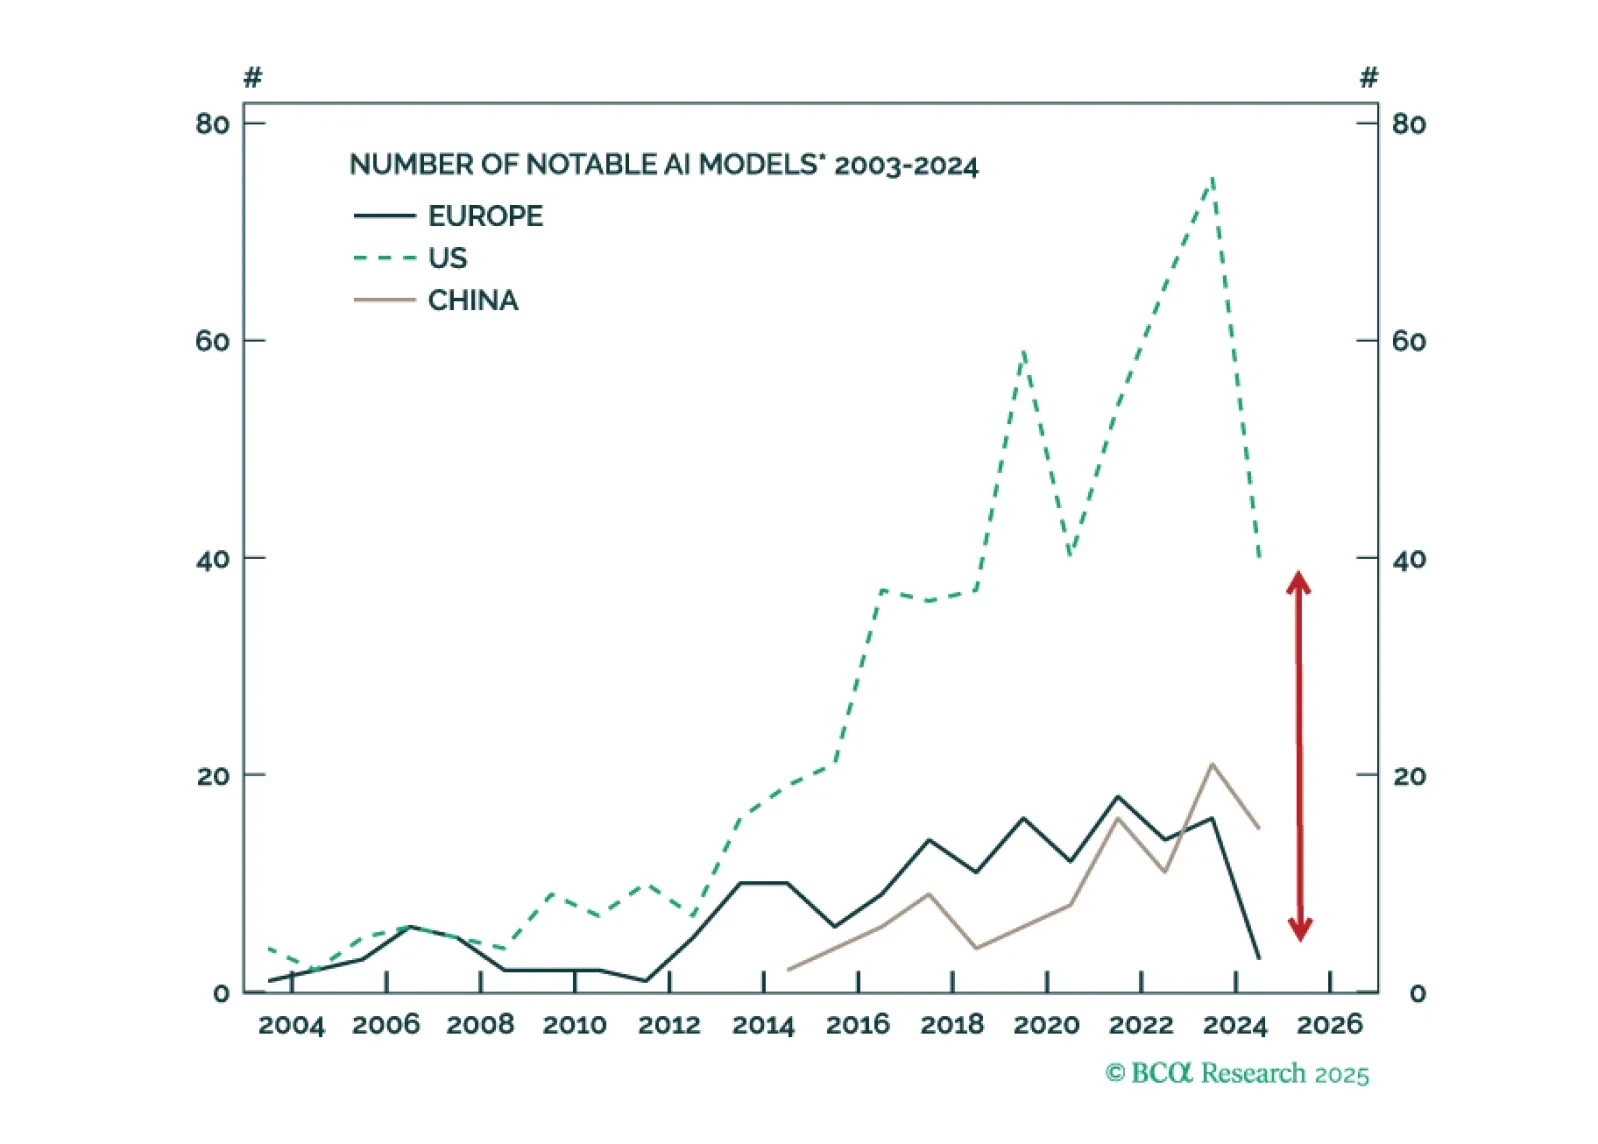
Europe is not left out of the AI race. Despite lagging US and China in LLMs and AI capex, Europe is quietly making progress where it matters, including industrial adoption. European capitals and the EU seem committed to not let that technology slip away, and are investing to support a “second-wave” role in AI. Scaling remains uneven, especially for SMEs, but will not prevent productivity gains in the region.
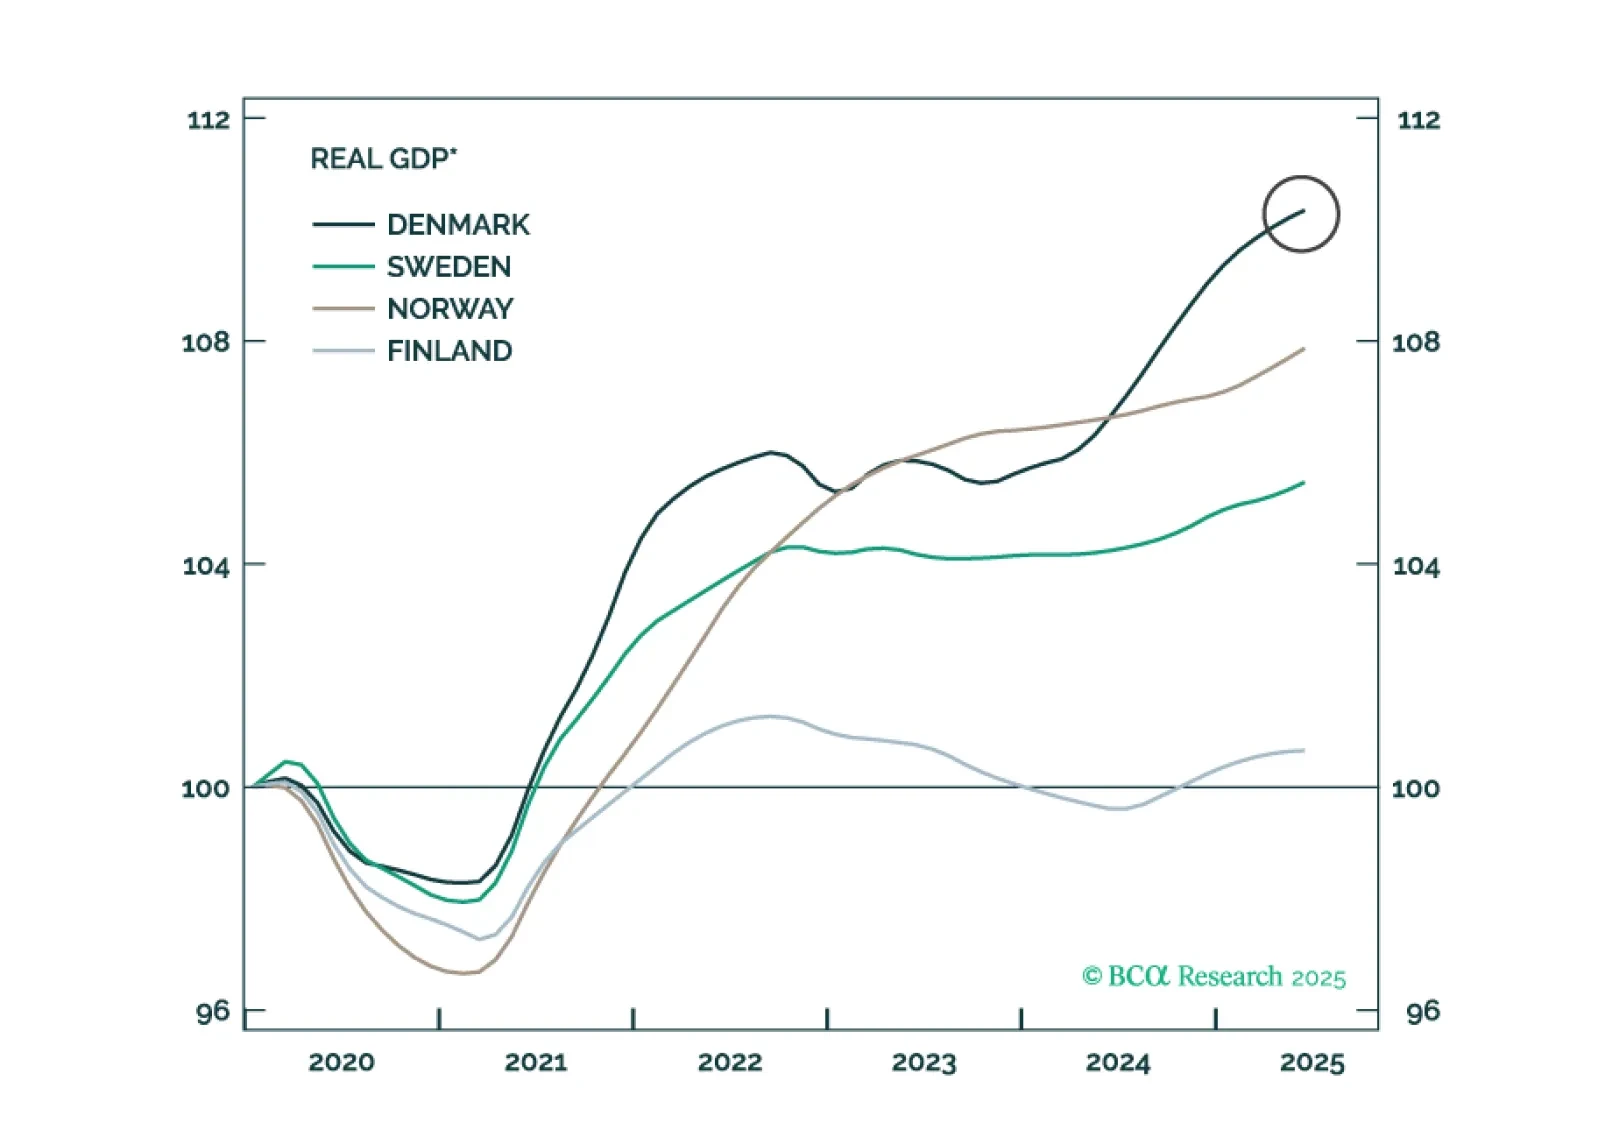
The Nordic central banks are now aligned in pause mode, but their economies are diverging. With Swedish prospects improving and Norwegian headwinds mounting, we are turning overweight on Swedish equities and shorting NOK/SEK.
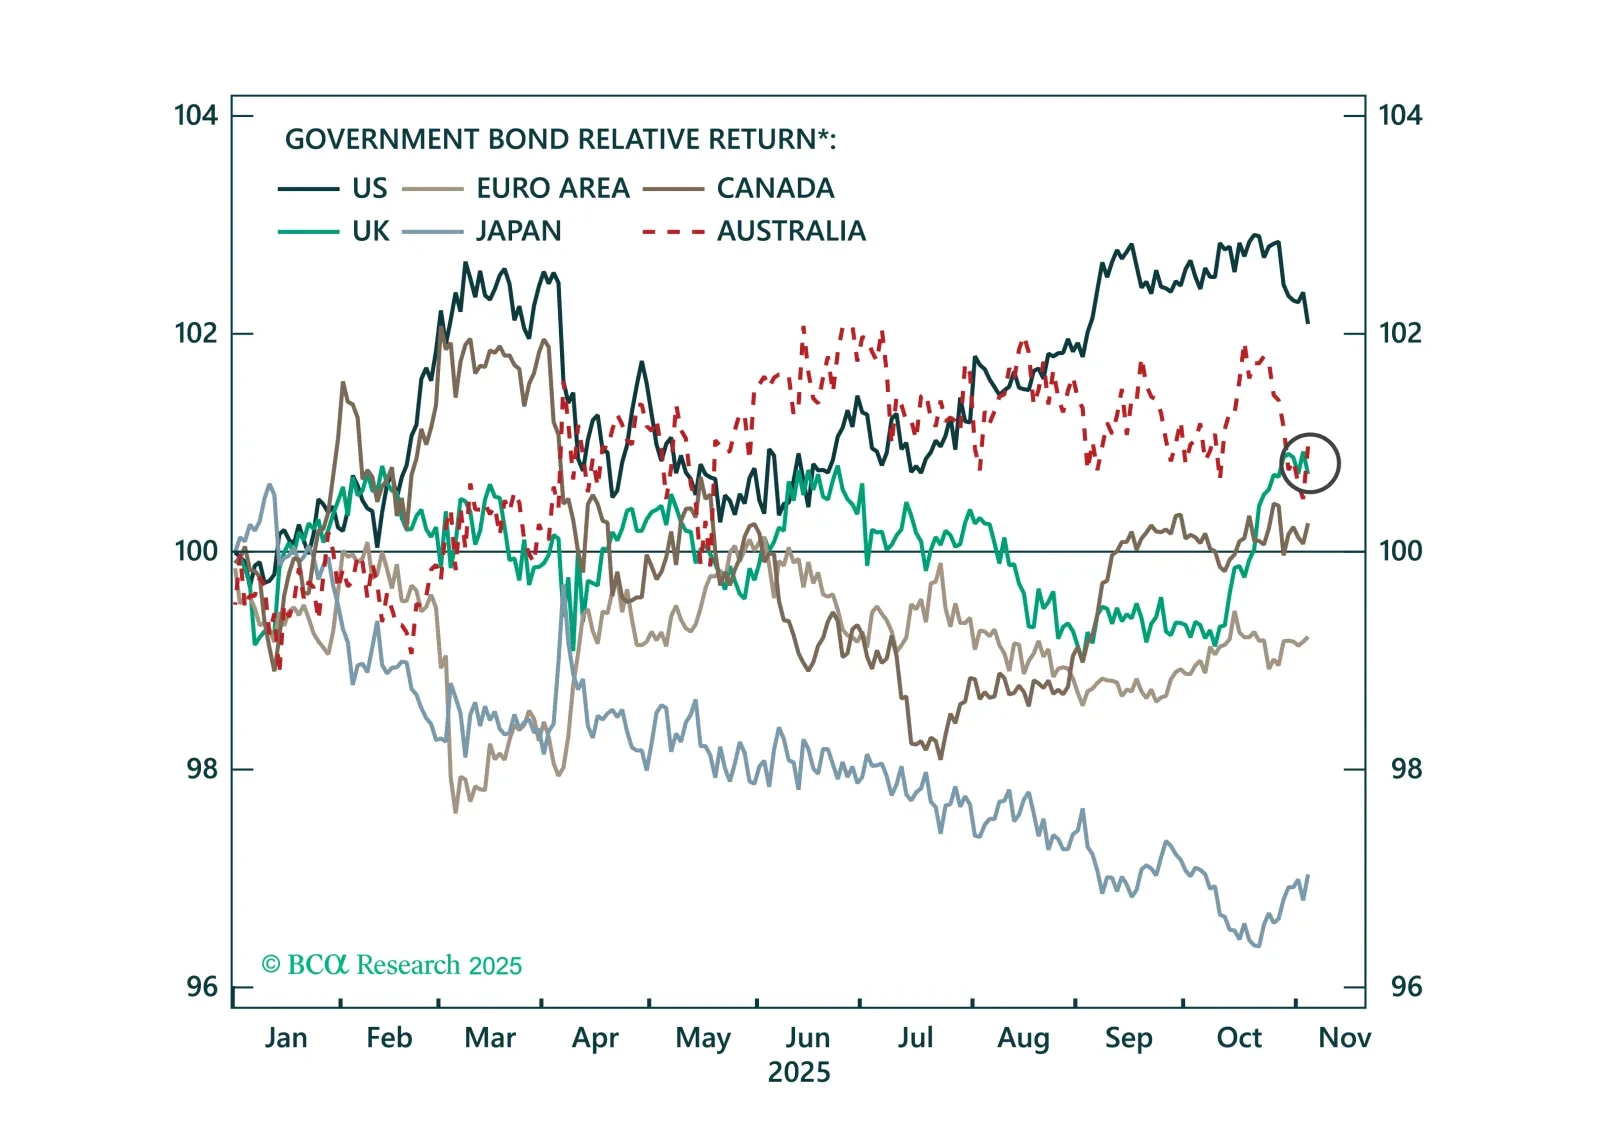
The Bank of England will resume rate cuts in December after the autumn budget is passed. Today’s Strategy Insight discusses what this means for UK gilts and the pound.
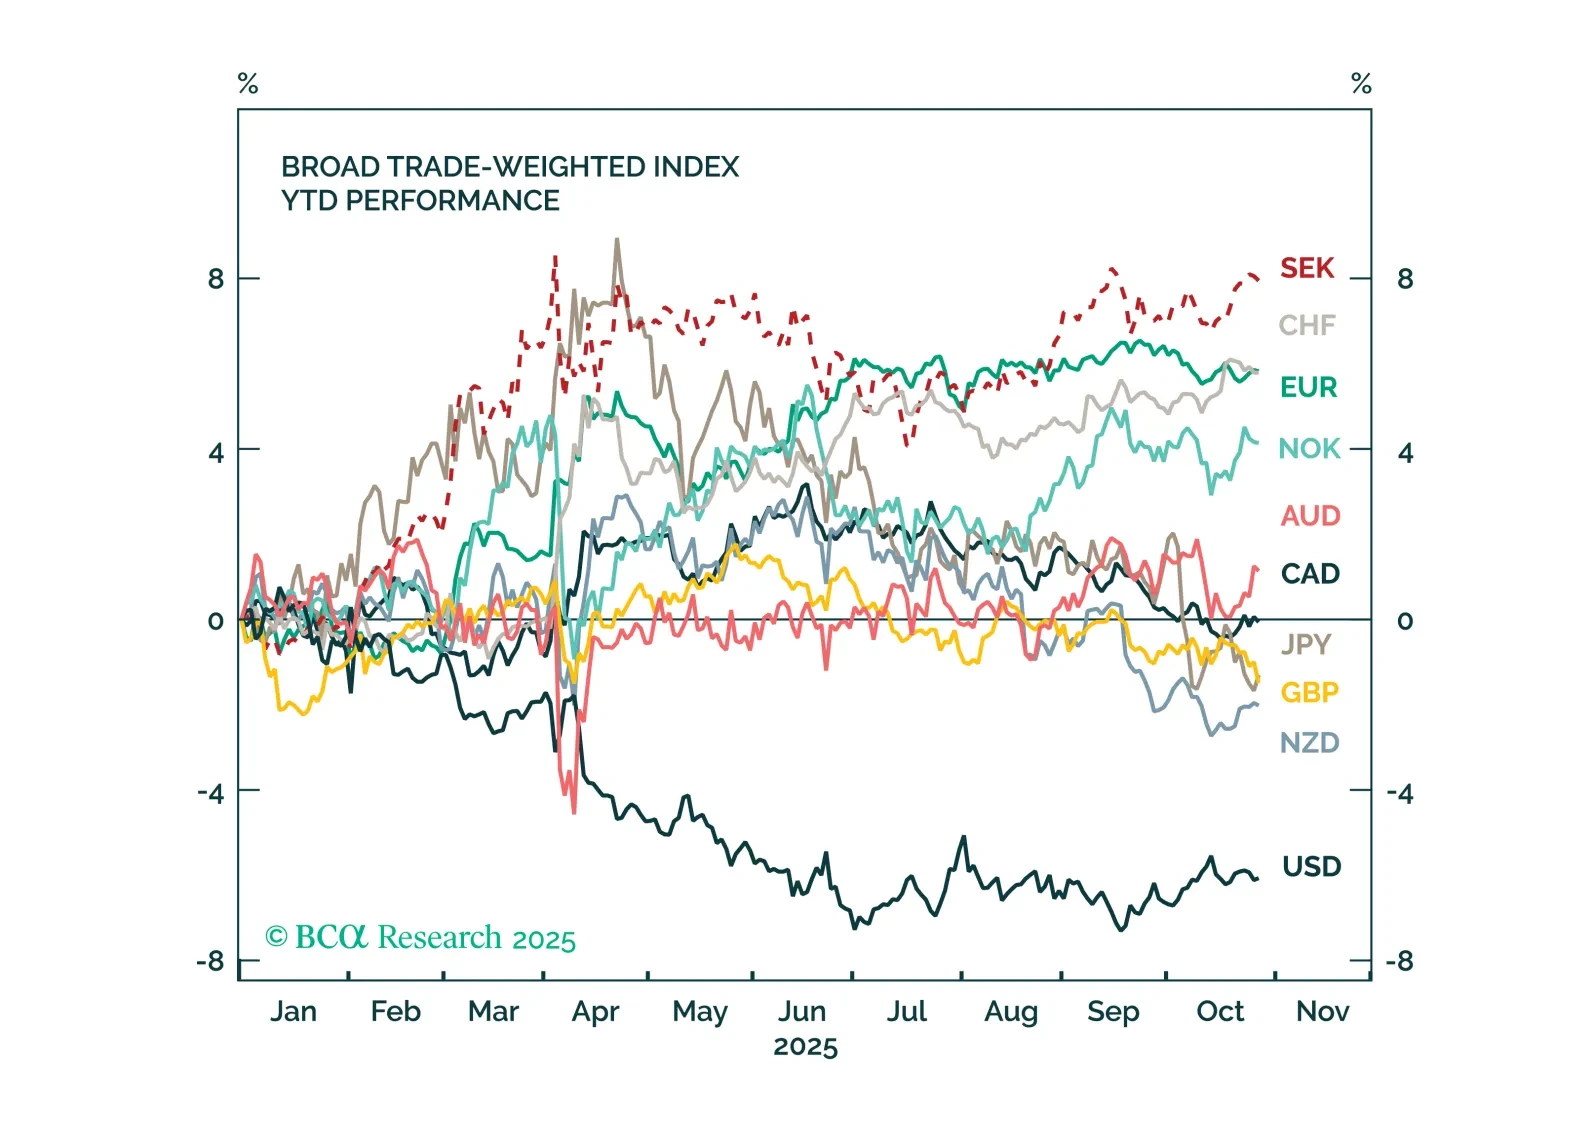
Markets are increasingly pricing an end to the global easing cycle, with many central banks expected to remain on hold. But uncertainty remains high, and policy surprises are likely going into 2026. This Strategy Report breaks down the current drivers behind G10 central bank policies, and how to position for the next moves across FX and fixed income.

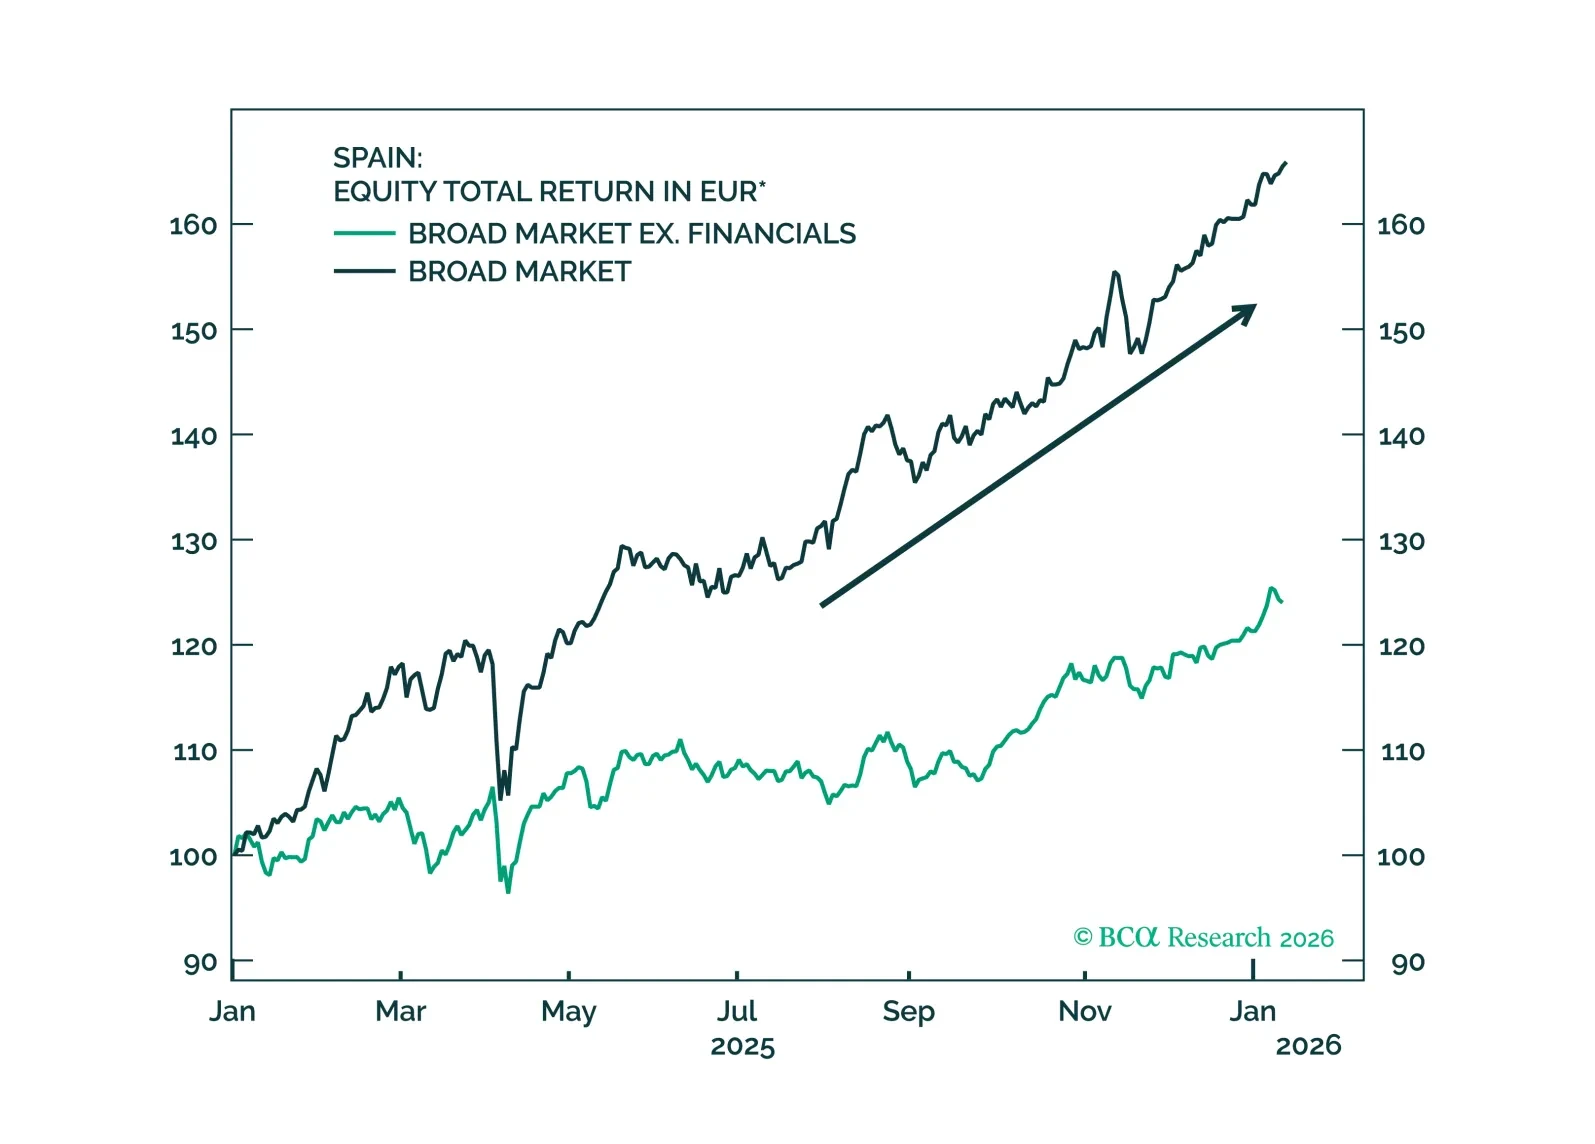
In this week’s note, we share the main implications for European investors from what was discussed at the BCA Conference in New York and provide a short list of the questions most frequently asked by investors we met recently in Lisbon, Madrid, and Barcelona.
