CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
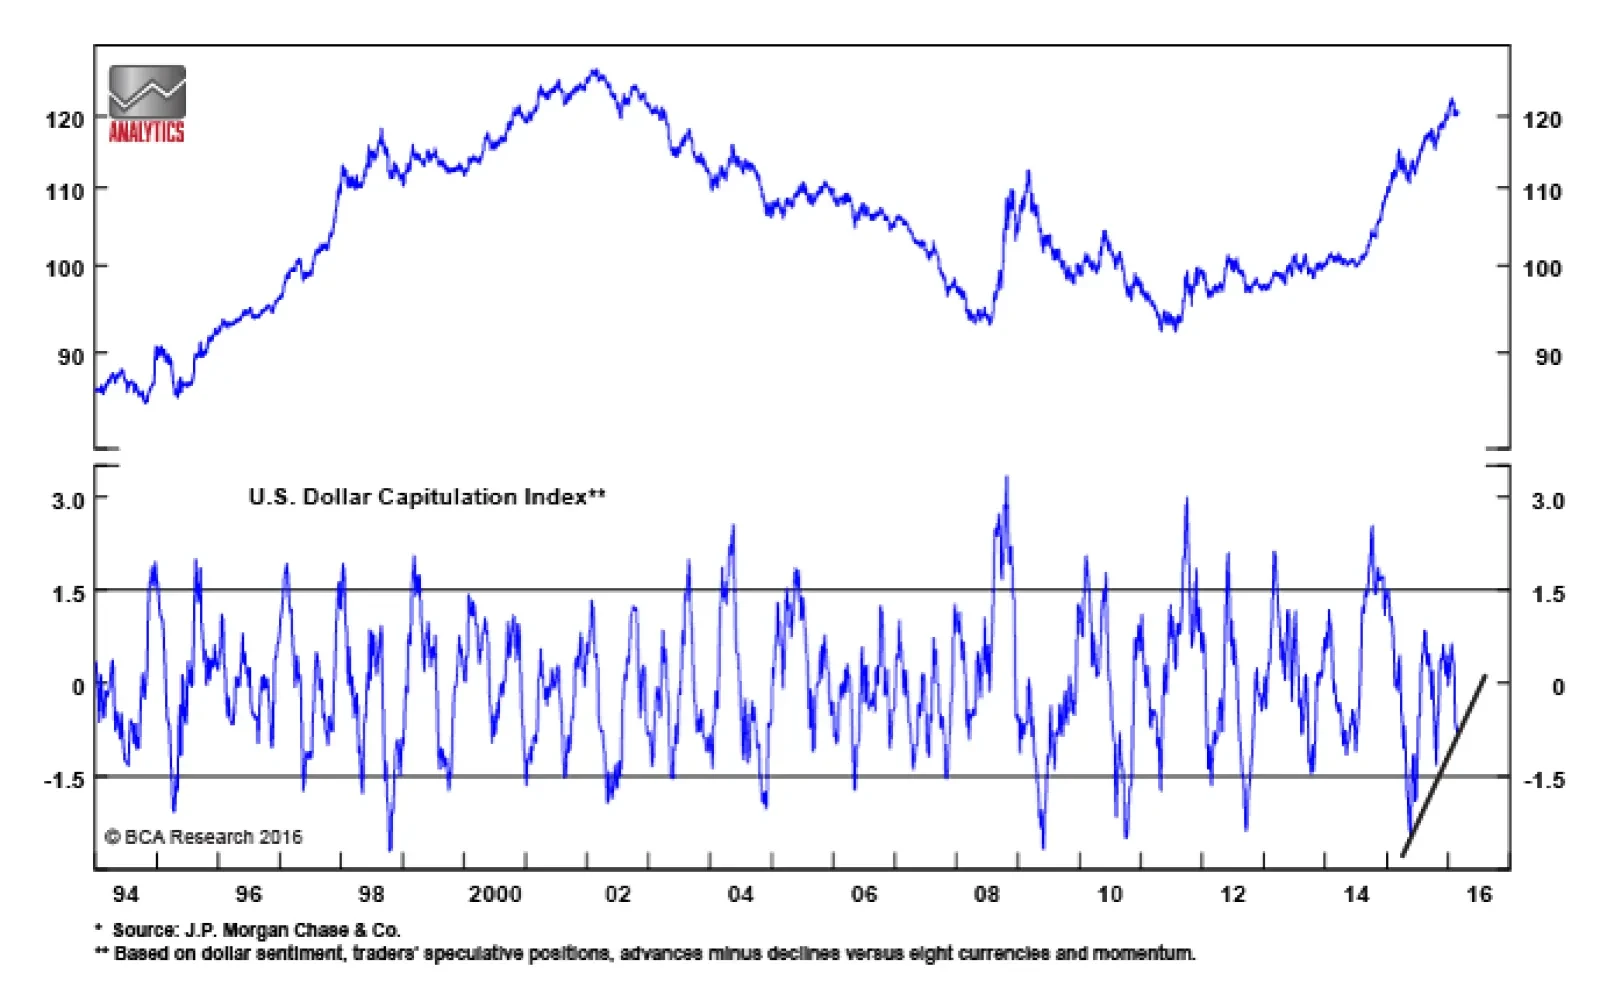
Risk assets will continue to edge higher over the next couple of months on improving economic data, notably from China. Longer term however, EMs - including China - are starting a prolonged deleveraging cycle, keeping commodities and cyclical stocks on the back foot. The dollar will likely follow the mirror image of commodities: down slightly the next two months, up substantially thereafter. A stronger dollar, in turn, will limit any rise in Treasury yields. Long-term investors should remain modestly overweight duration.
We are sending you the Q2 Global Investment Strategy Outlook, which discusses the ten predictions we expect to drive global financial markets throughout the rest of the year.
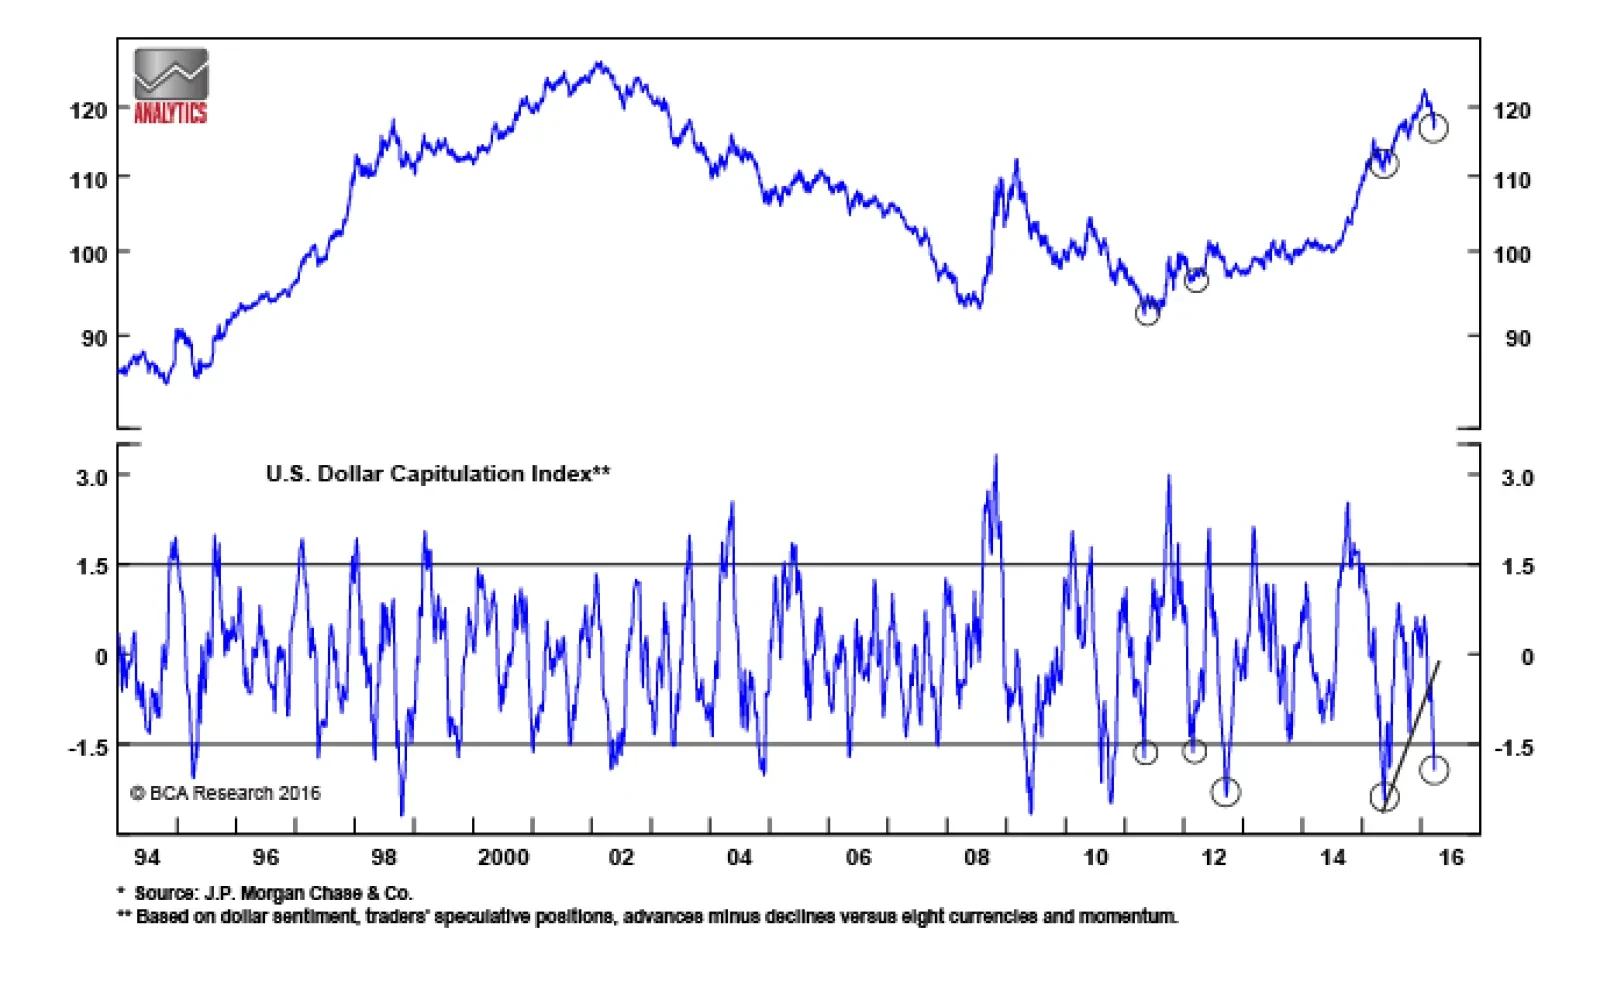
For the month of March, the model outperformed both global and U.S. equities in U.S. dollar terms. For April, the model has further pared back its equity risk exposure, shifting the allocation into cash. While Europe remains the largest equity overweight, there was a modest recalibration to defensive markets such as the U.S. and Switzerland. The allocation to EM was also nudged up a bit, on momentum and valuation grounds. In the fixed-income space, the model is sticking with U.S., Italian and Spanish paper.
While the FOMC was more dovish than expected, rising inflation may cause the Fed to escalate hawkish rhetoric. The bounce in oil should help high-beta stocks. Underweight U.S. equities versus Europe, Japan and H-shares. We estimate U.S. equities will deliver returns of 4%, ann. over the next 10 years, vis-à-vis 9% for the euro area and Japan, and 14% for H-shares. Central banks have more options to combat any possible debt-deflation spiral in Europe/Japan/China than is often recognized.
Near-term, global yields will remain depressed, but the structural forces suppressing yields should abate and even reverse in the long-run. Slower potential GDP growth - and lower commodity prices - will eventually shift from tailwind to headwind for bonds. Stepped-up efforts to increase inflation will boost long-term nominal yields; populist politics and calls to curb income inequality will amplify this trend. Long-term investors should stay neutral global bonds for now, but prepare to shift to a structural underweight beyond this decade.
For the month of February, the model underperformed both global and U.S. equities. For March, the model has modestly pared back its equity risk exposure, shifting the allocation into bonds. While Europe remains the largest equity overweight, EM and Canada also received some allocation. The U.S. and New Zealand were slightly downgraded. In the fixed-income space, the model is sticking with Italy and Spain.