FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
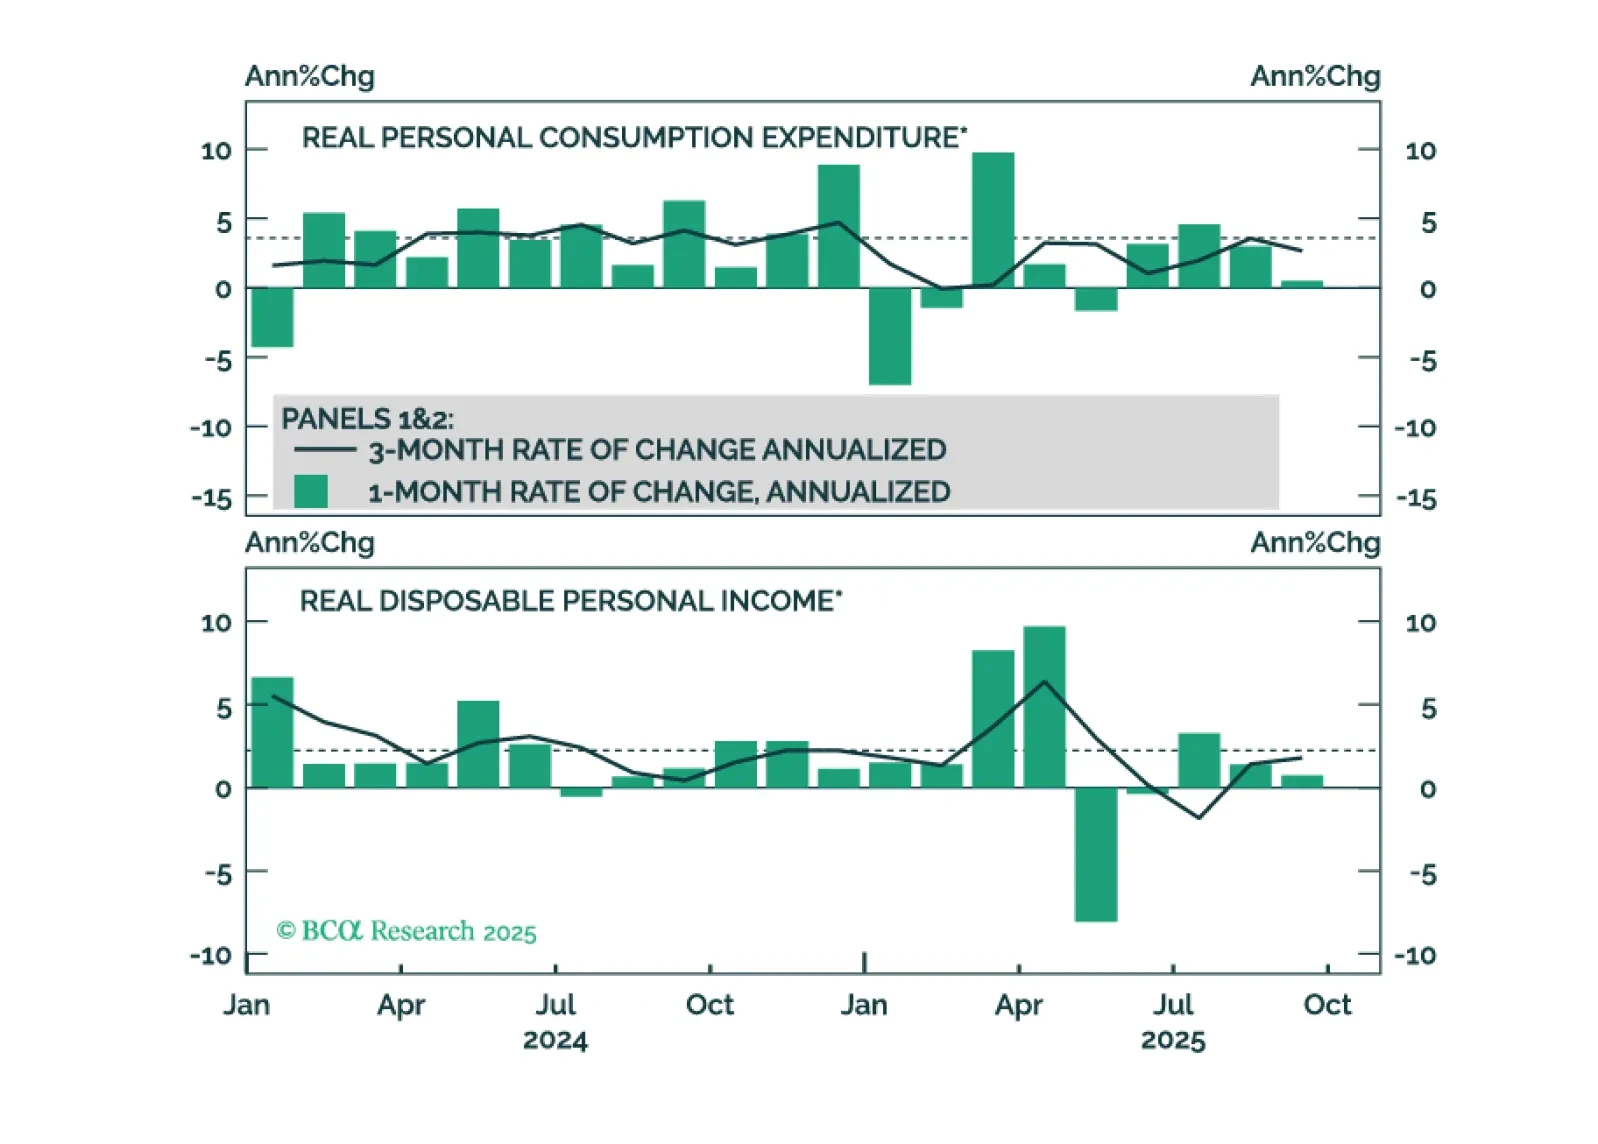
September’s weak consumer spending data challenge the K-shaped recovery narrative and suggest that spending will slow to match already-weak employment growth.


Japanese financial assets will finally have unfettered access to outsized returns. This performance will come in fits and starts, but we are comfortable laying our cards down on buying the yen, and Japanese industrial stocks.
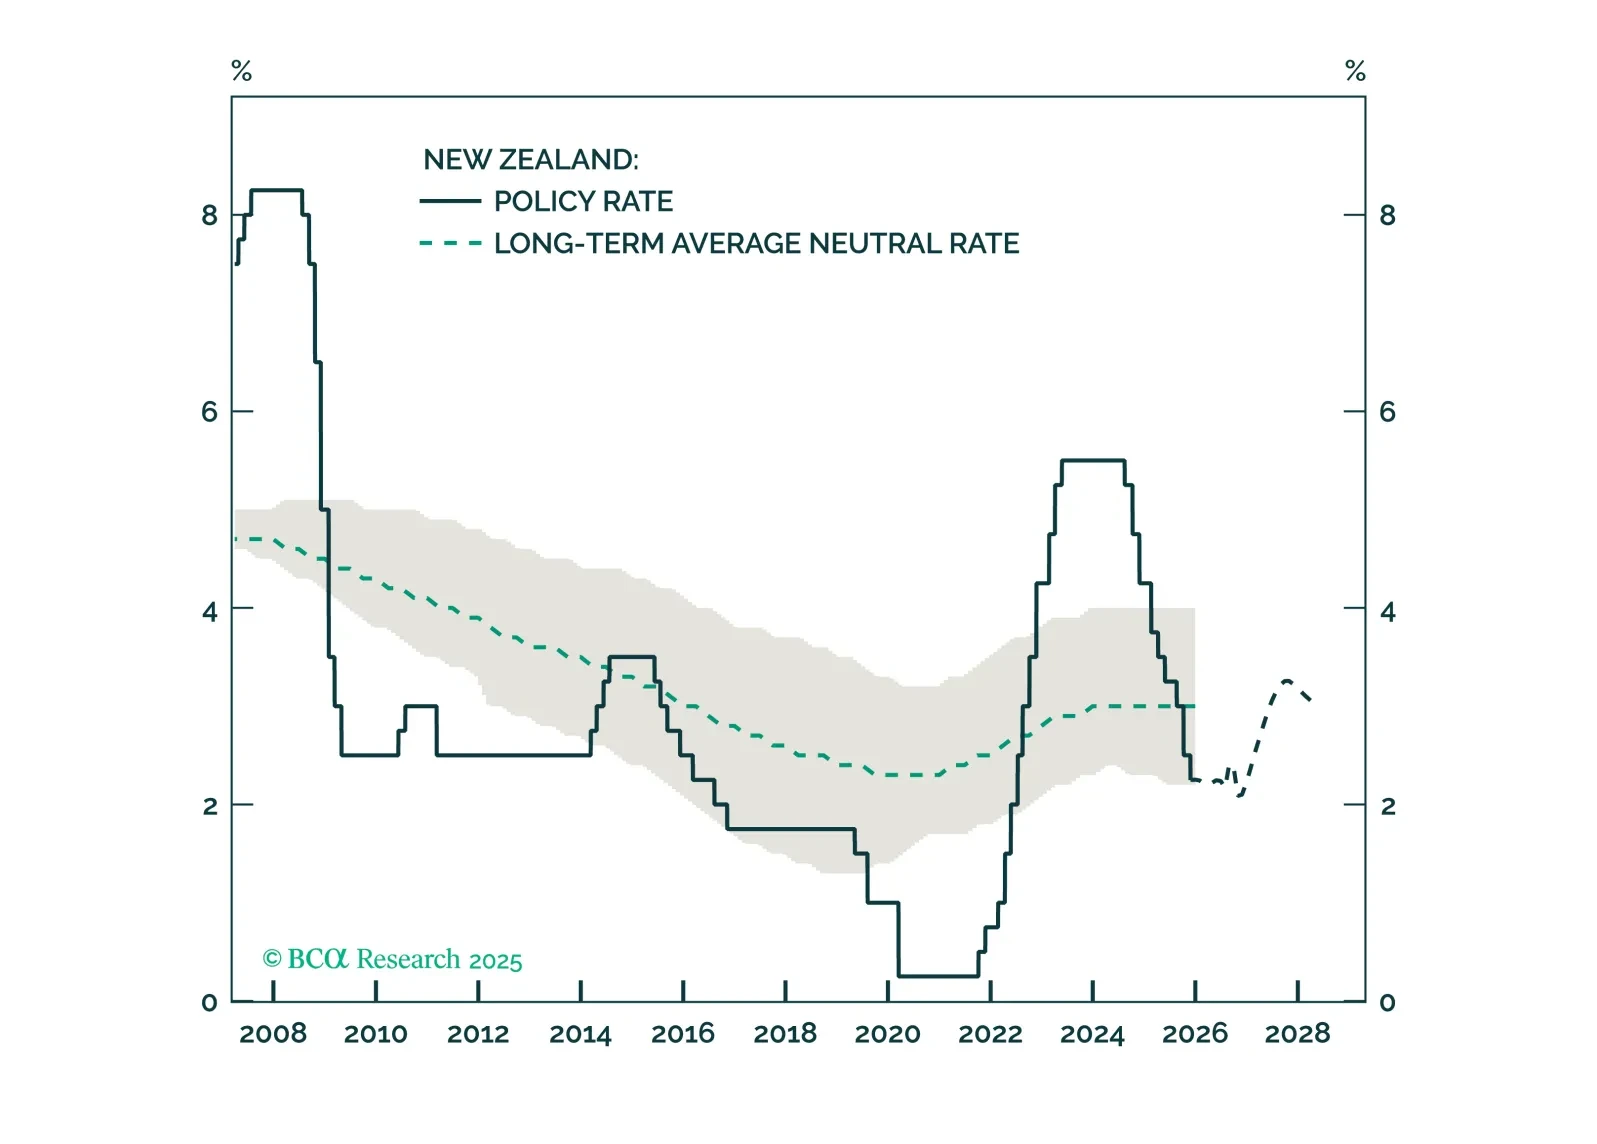
The RBNZ has concluded its aggressive easing blitz. With New Zealand economy finally showing signs of life, both the kiwi and local rates now look ripe for a reversal.
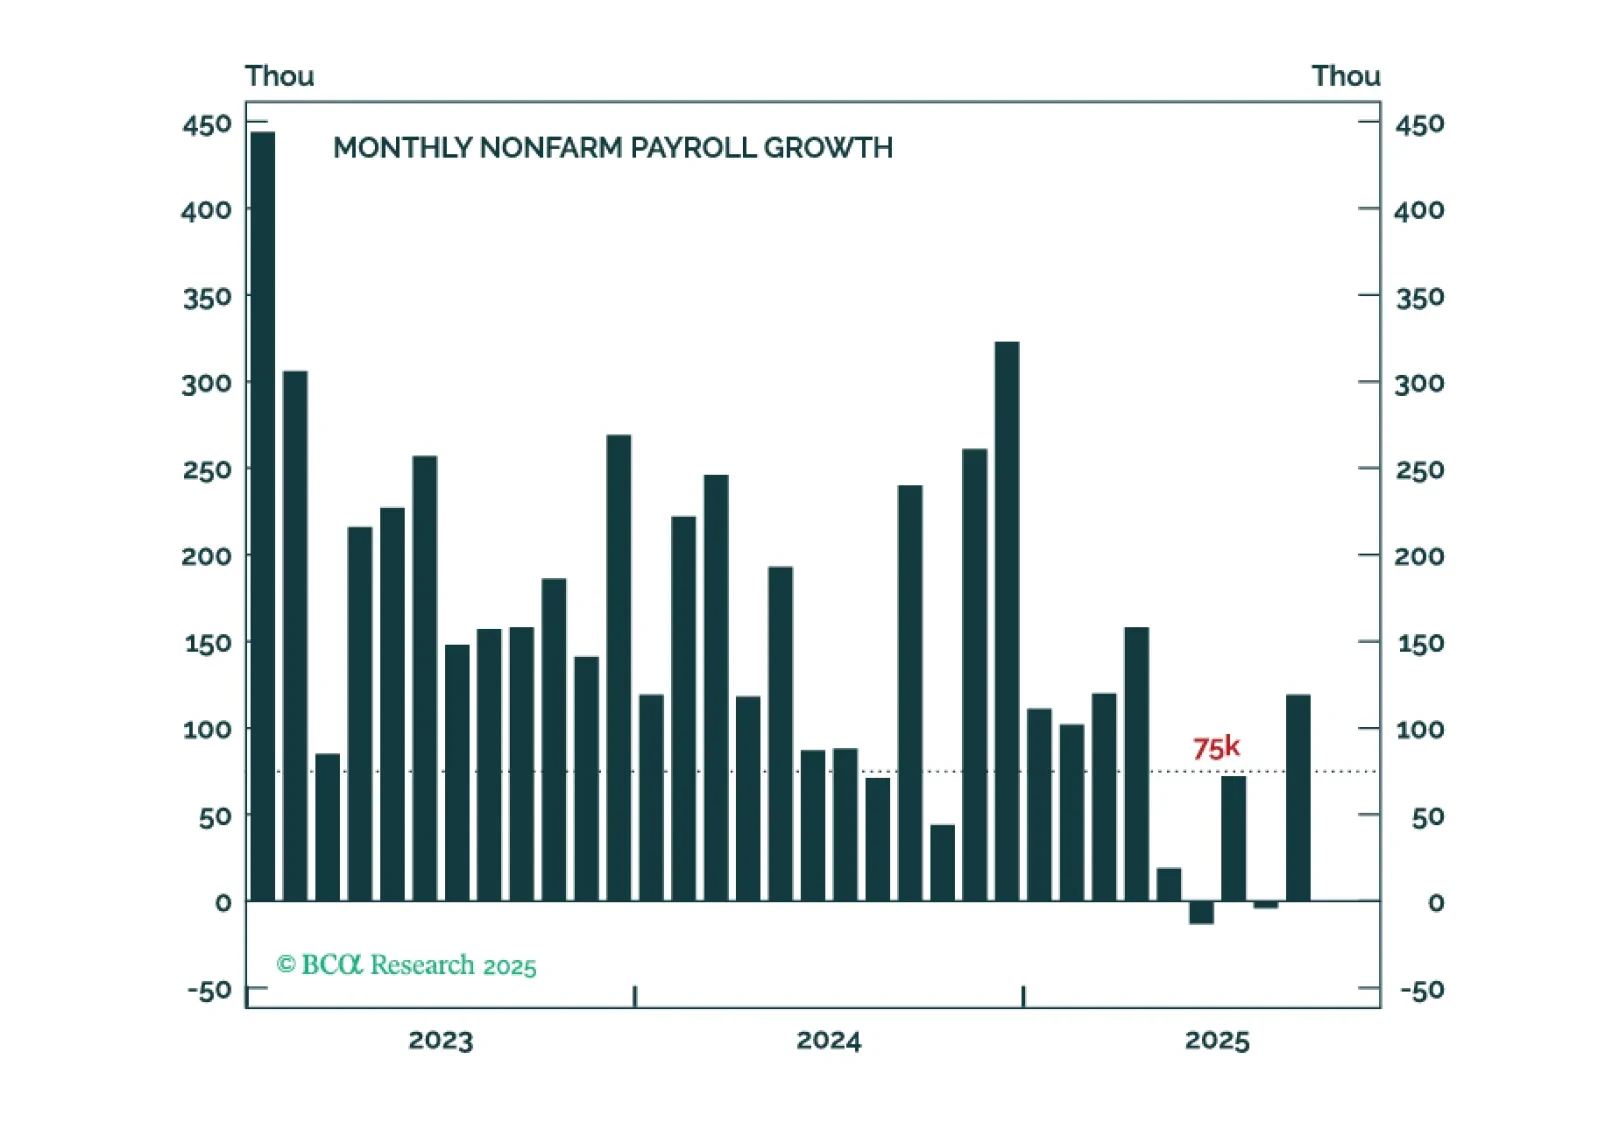
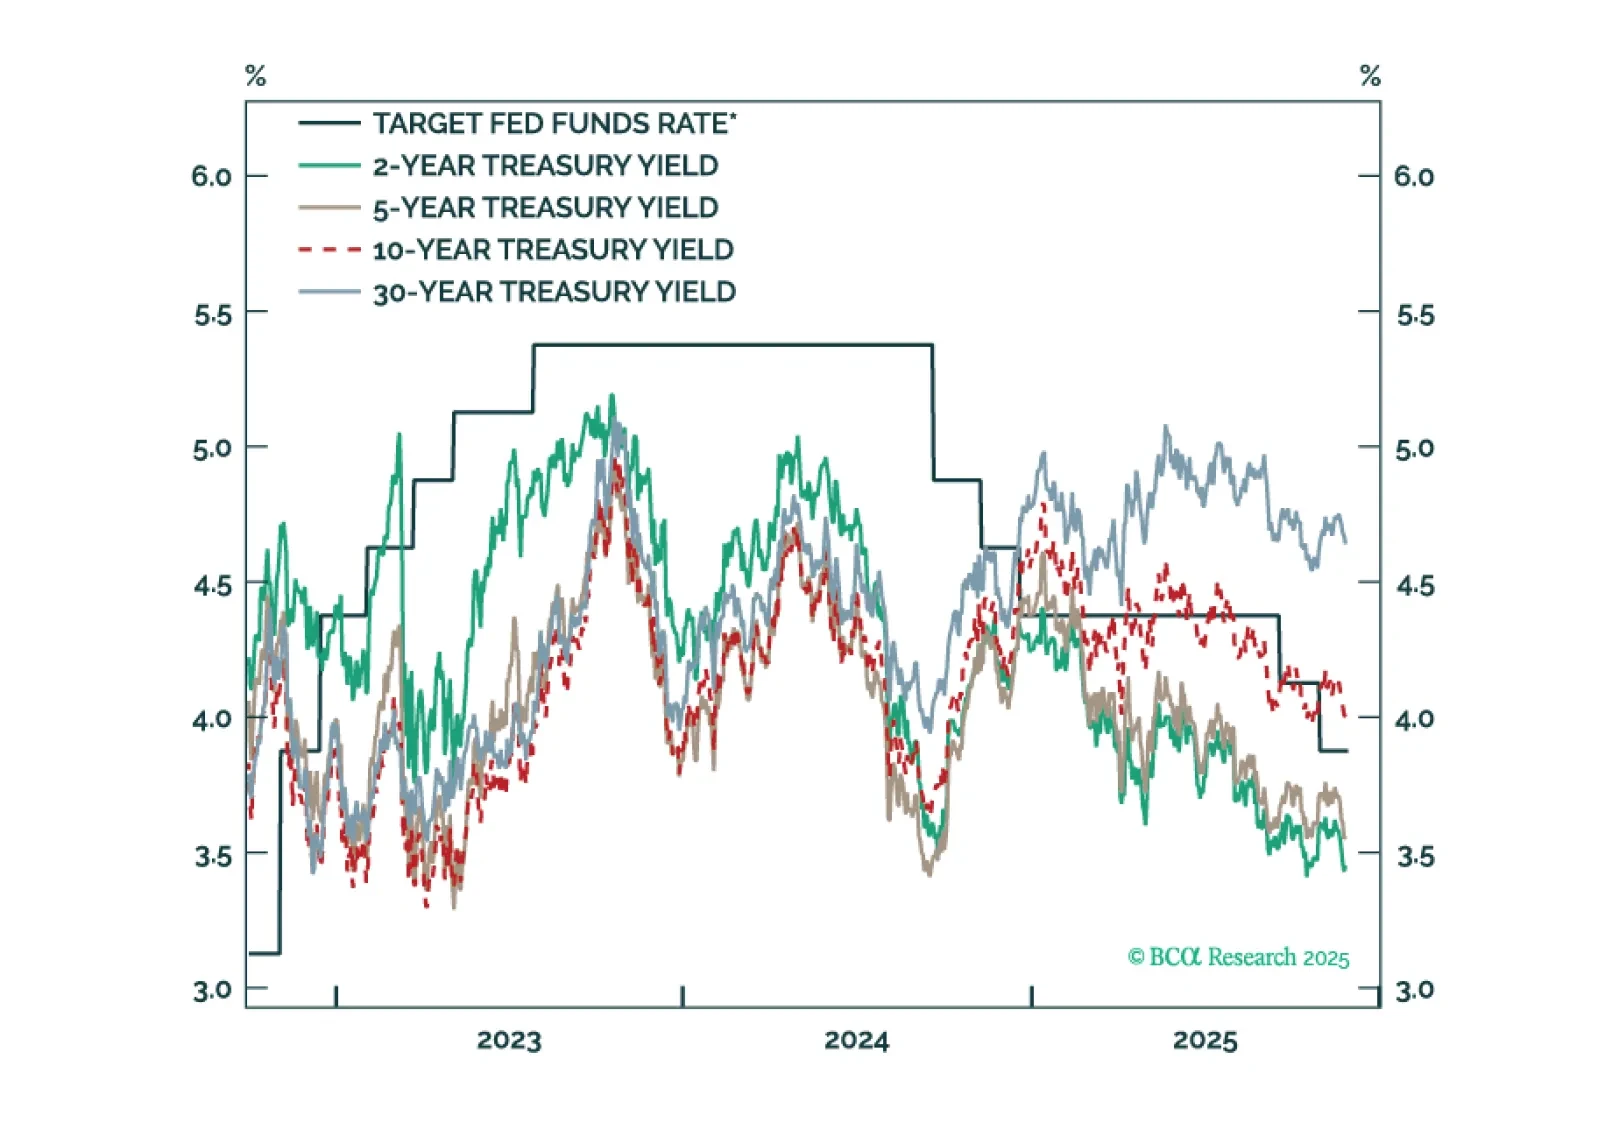
The September employment report probably won’t convince enough hawks to vote for a rate cut in December.