 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
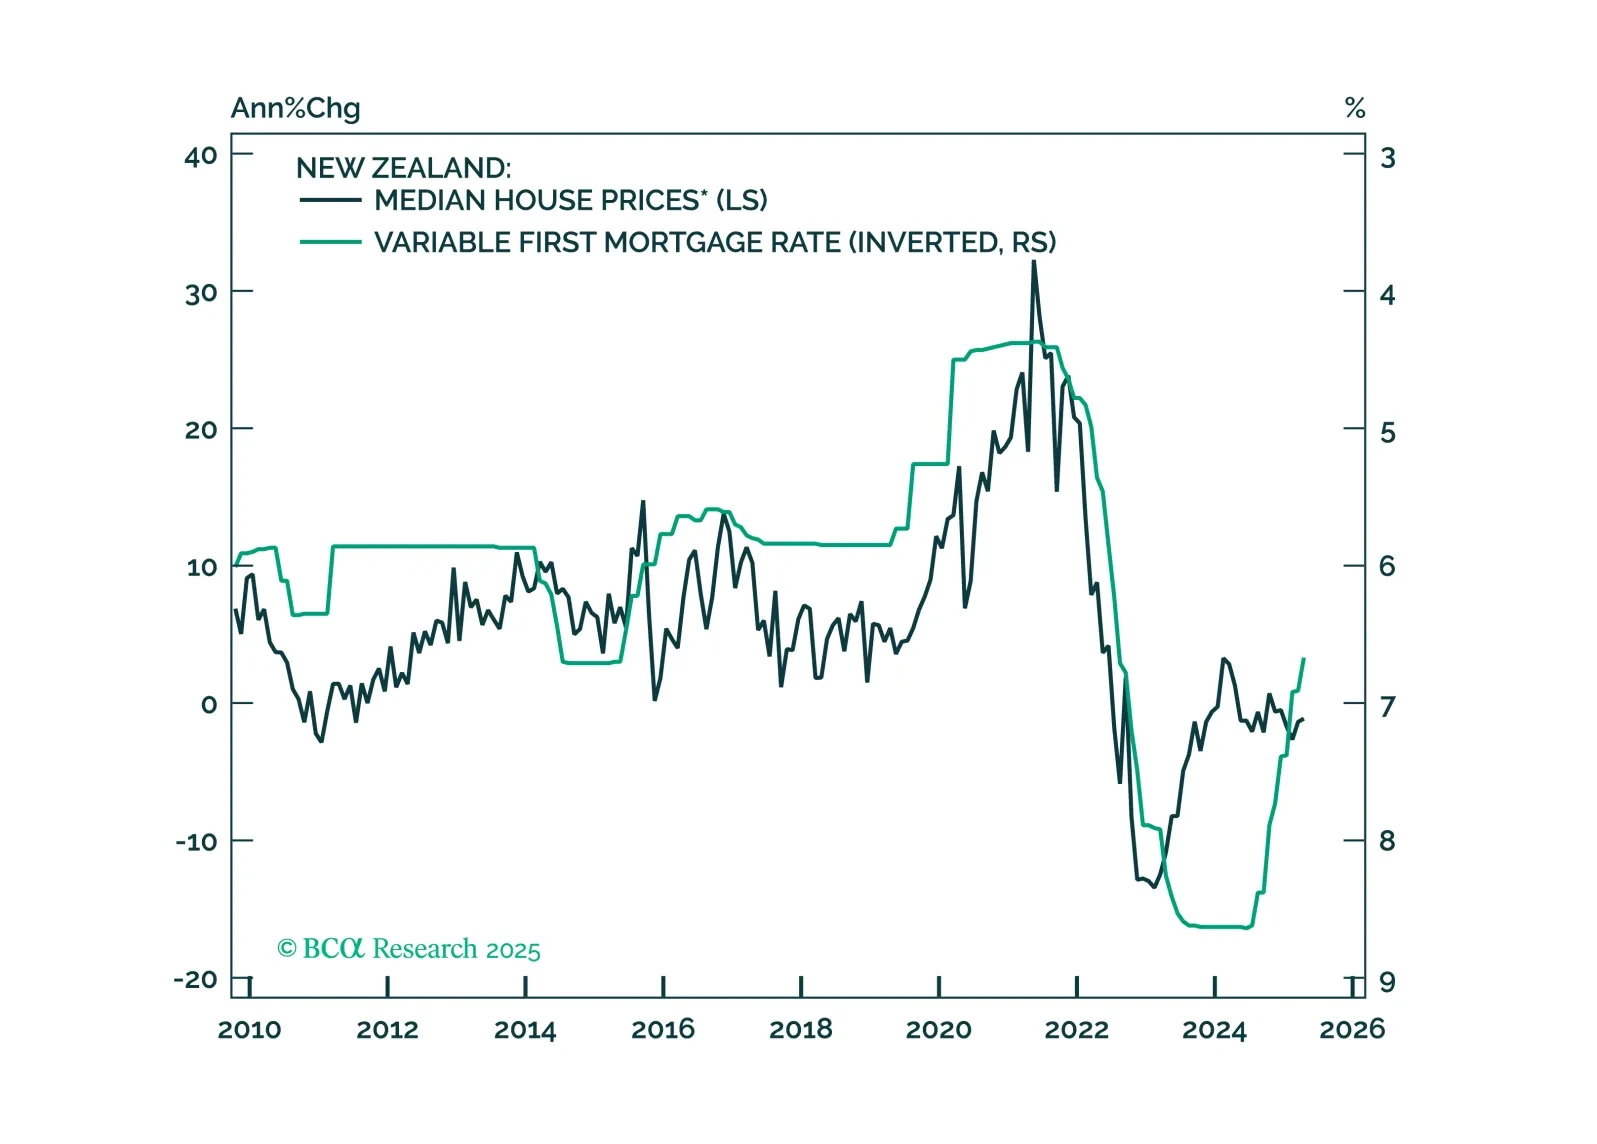
This Insight looks at the implications of the RBNZ’s rate cut on New Zealand assets.
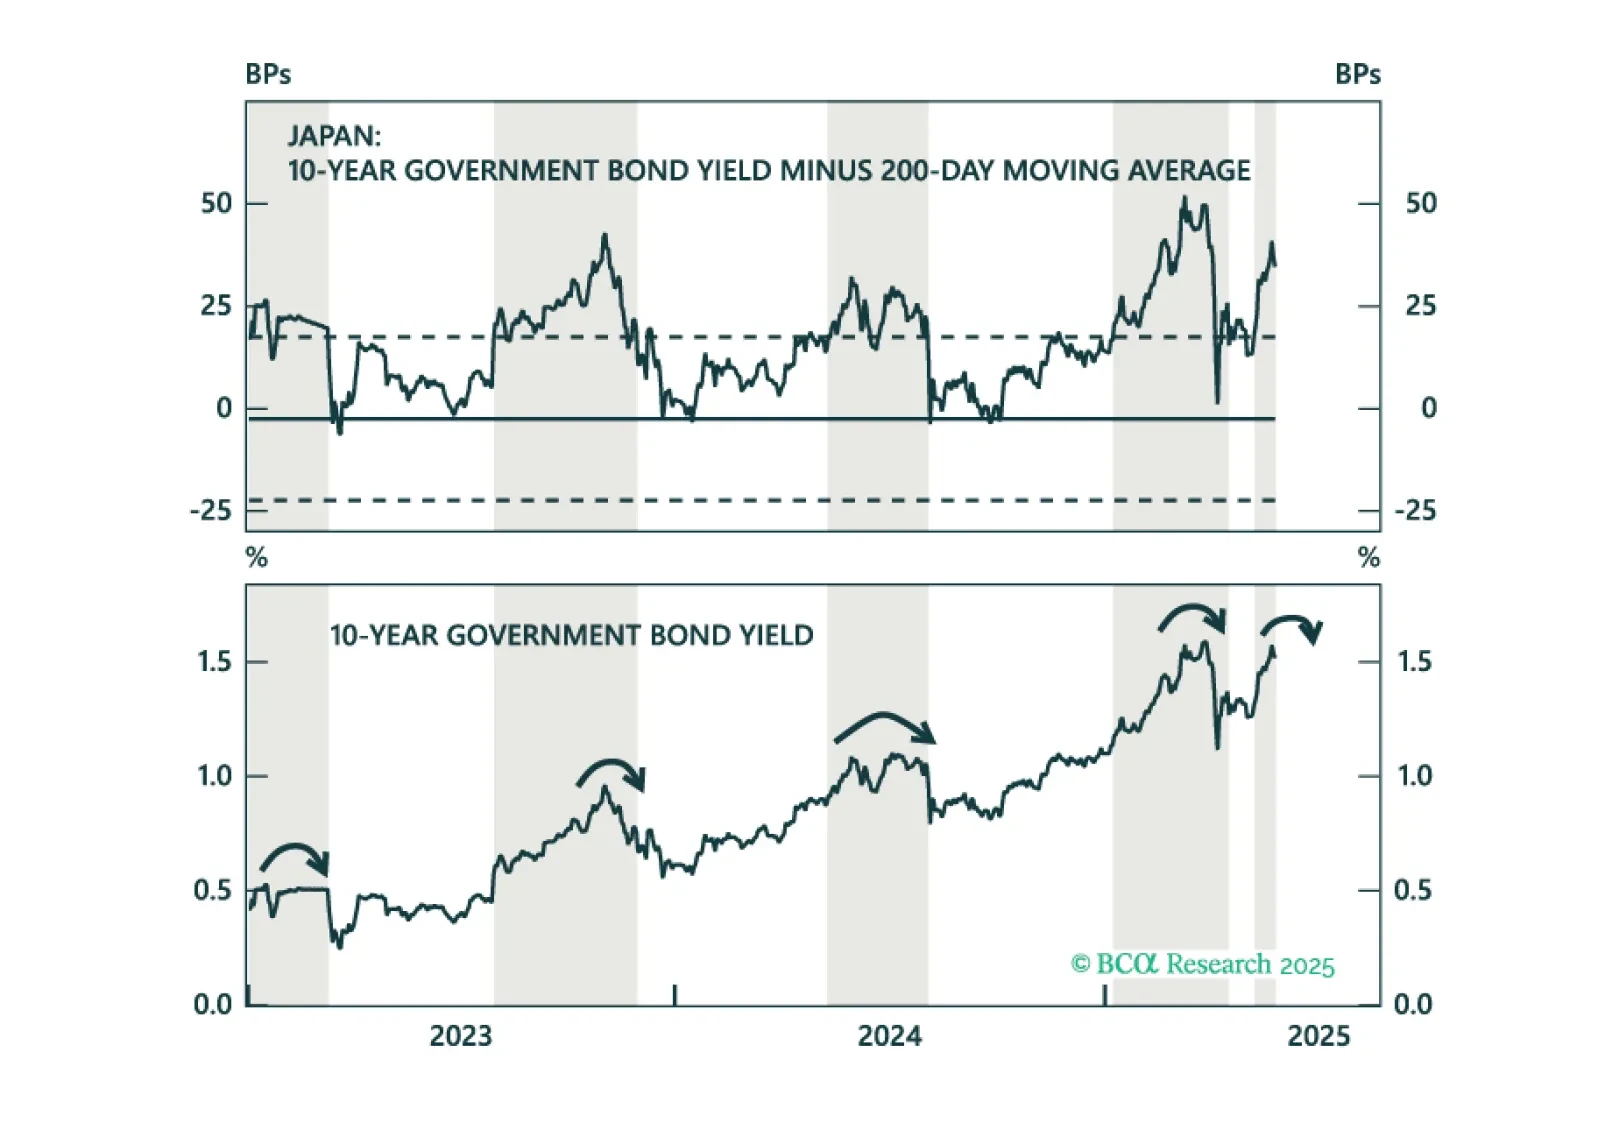
Are bond yields overextended? We introduce a new global technical indicator that helps spot mean-reversion opportunities and shows which markets are nearing exhaustion.
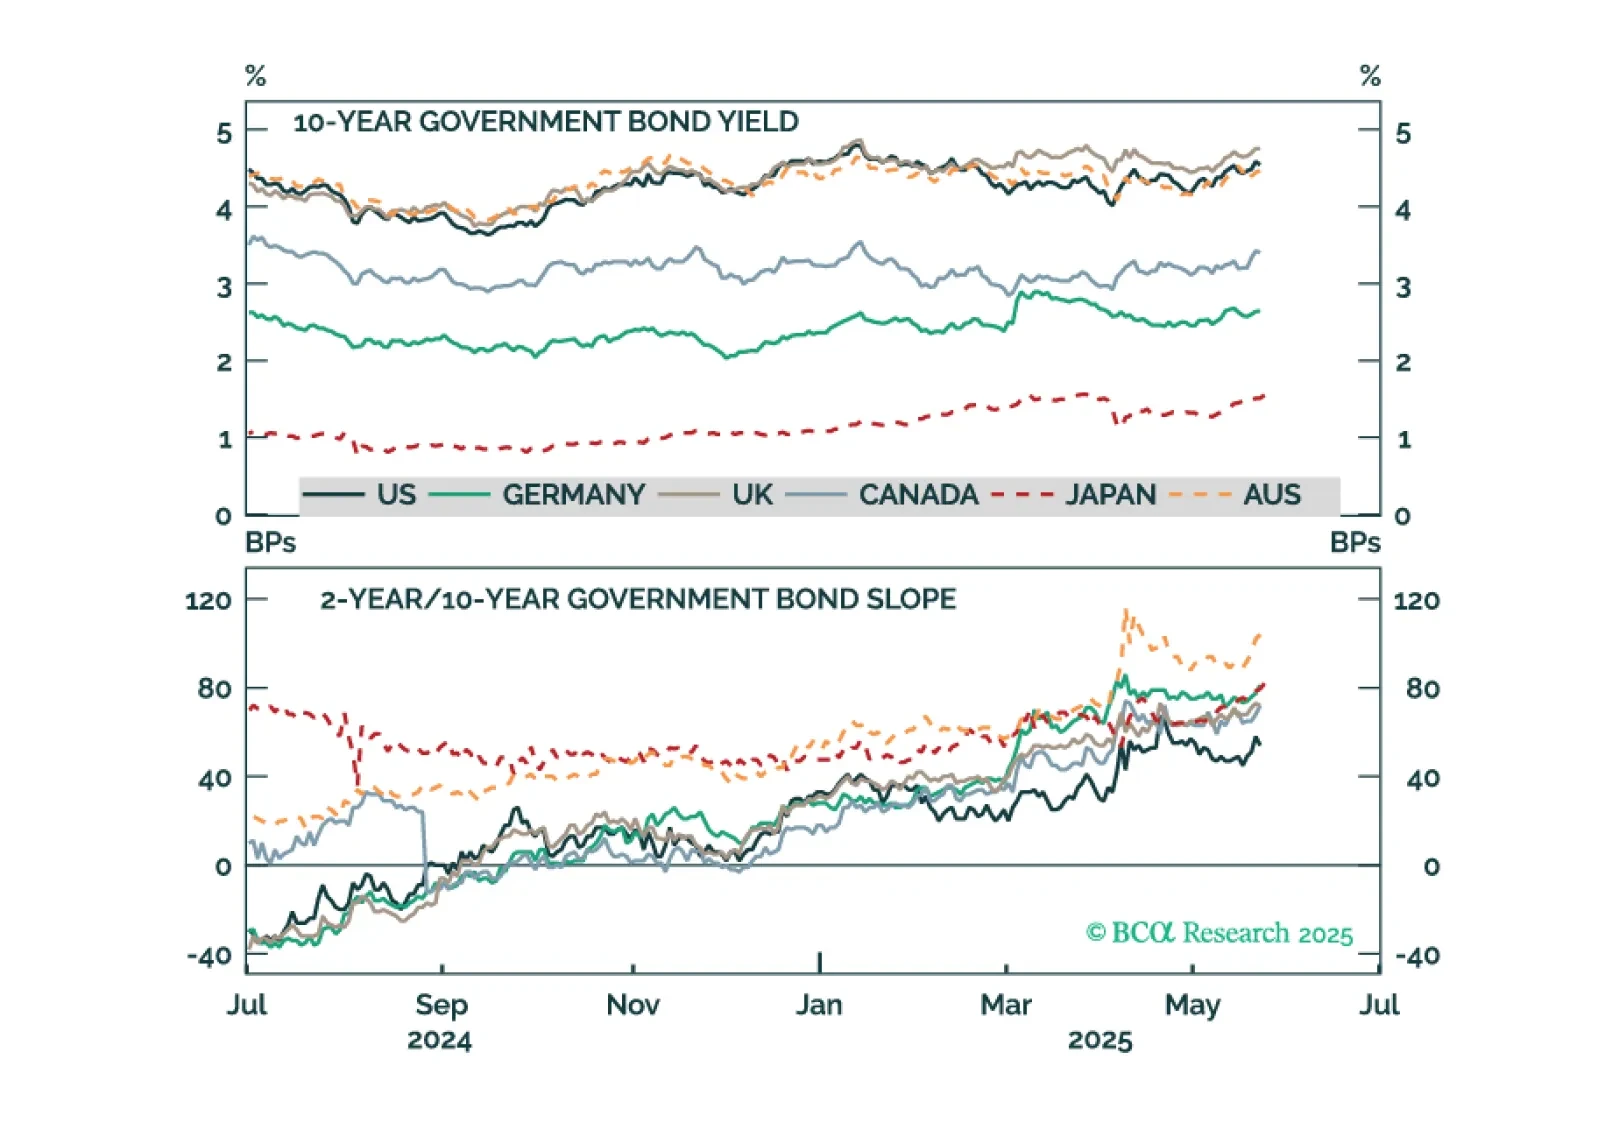
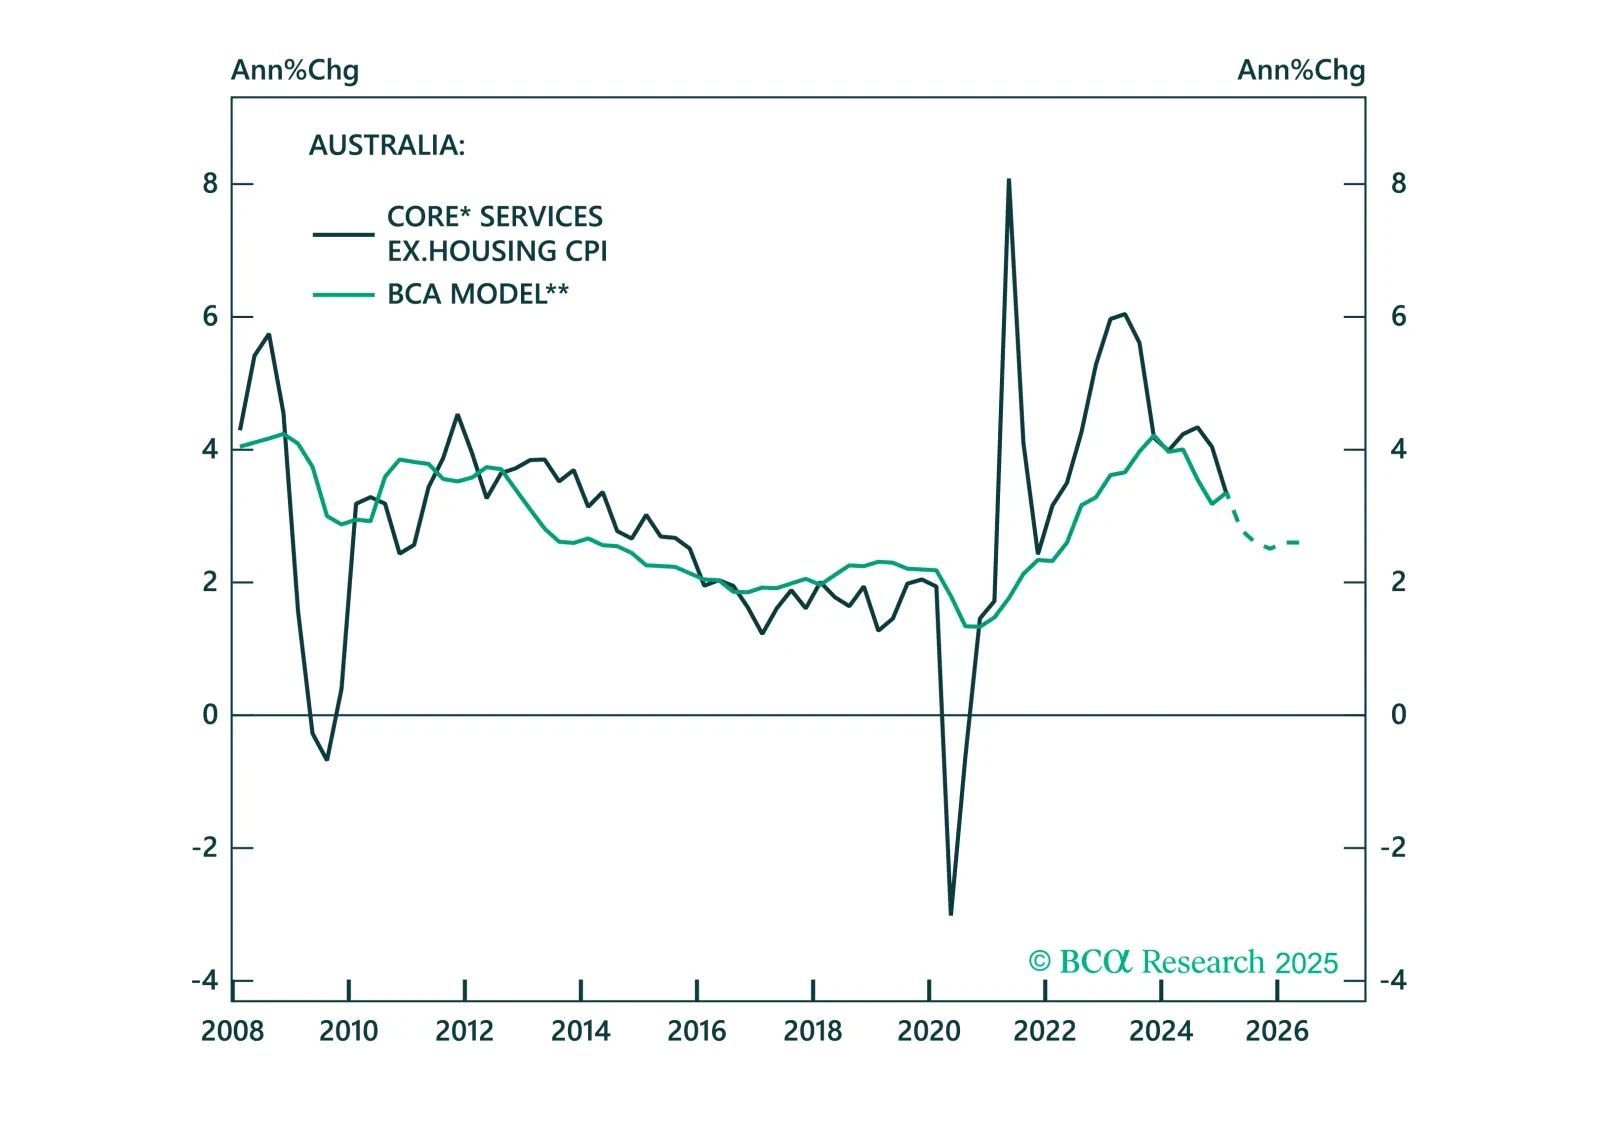
The RBA just turned dovish, but the macro data do not justify many more cuts. We unpack why Australia’s strong labor market and sticky inflation limit the scope for further easing.
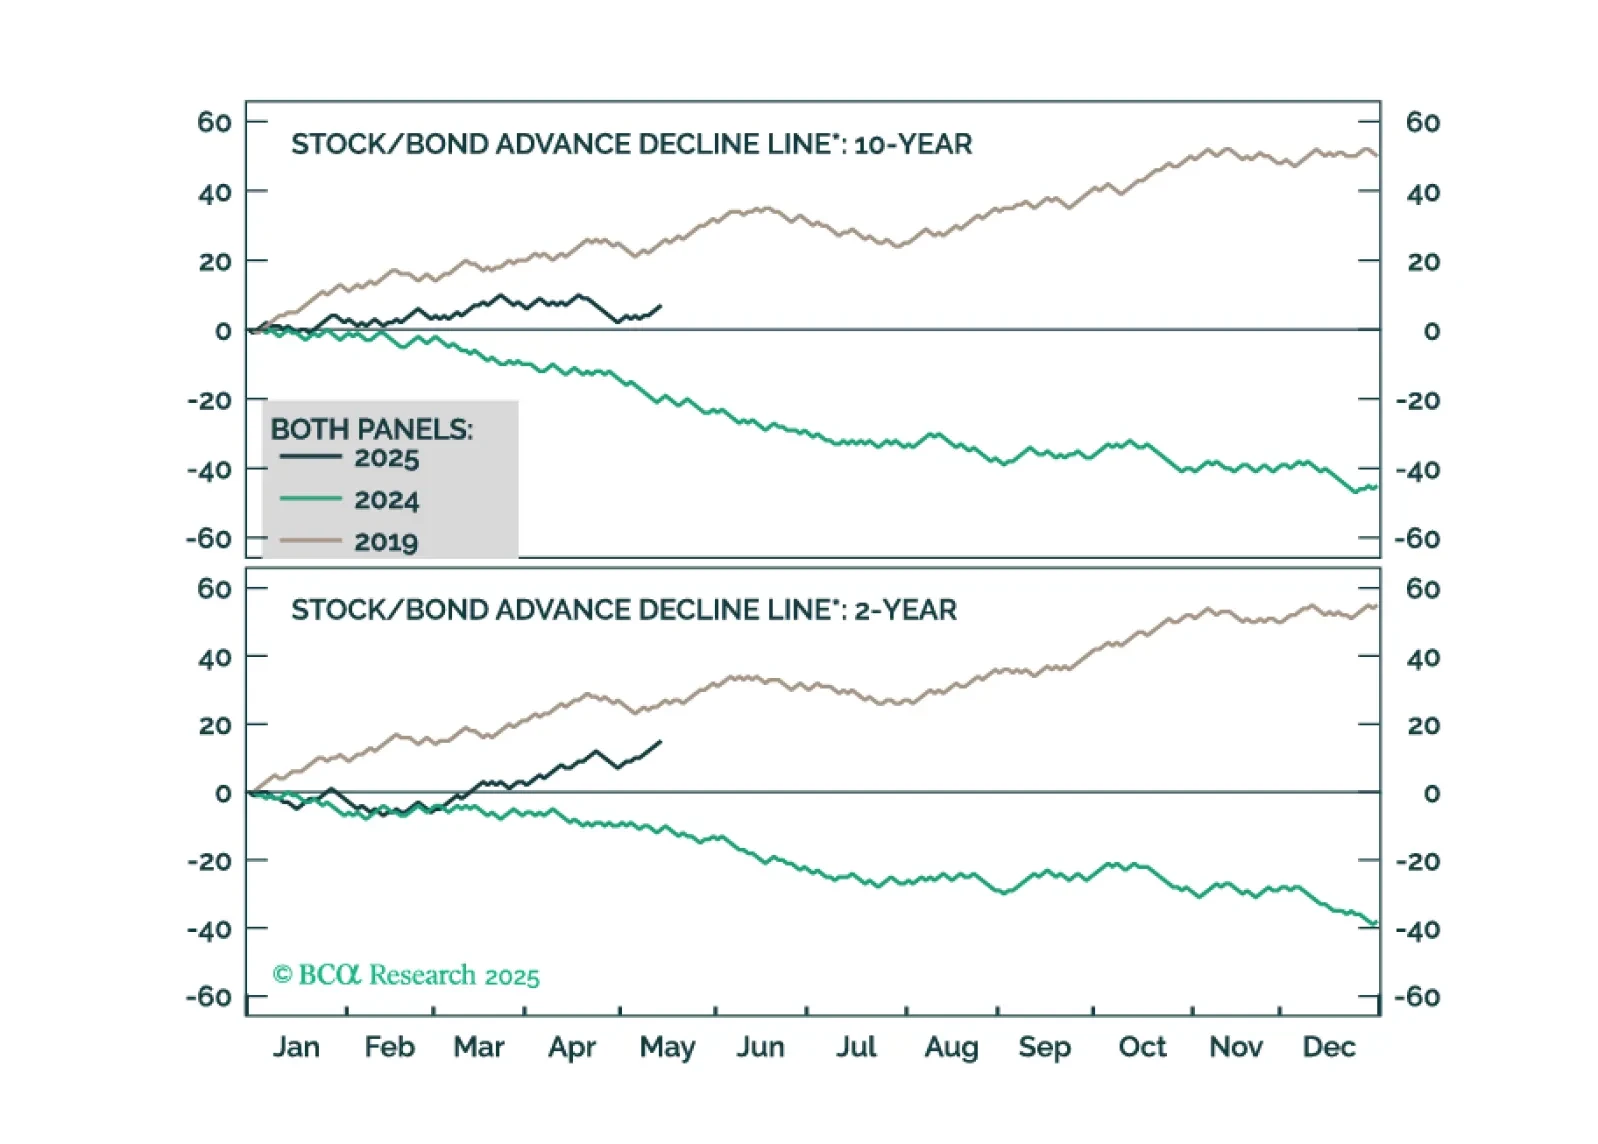
Tariff front-running behavior makes the April hard economic data difficult to interpret, but we take the strong reading from Food Services spending as a signal that the US consumer has not yet buckled.

A weakening economy will apply downward pressure to Treasury yields, but the Trump term premium will keep long-dated yields higher than they would otherwise be. This makes Treasury curve steepeners the most attractive trade in US fixed income.
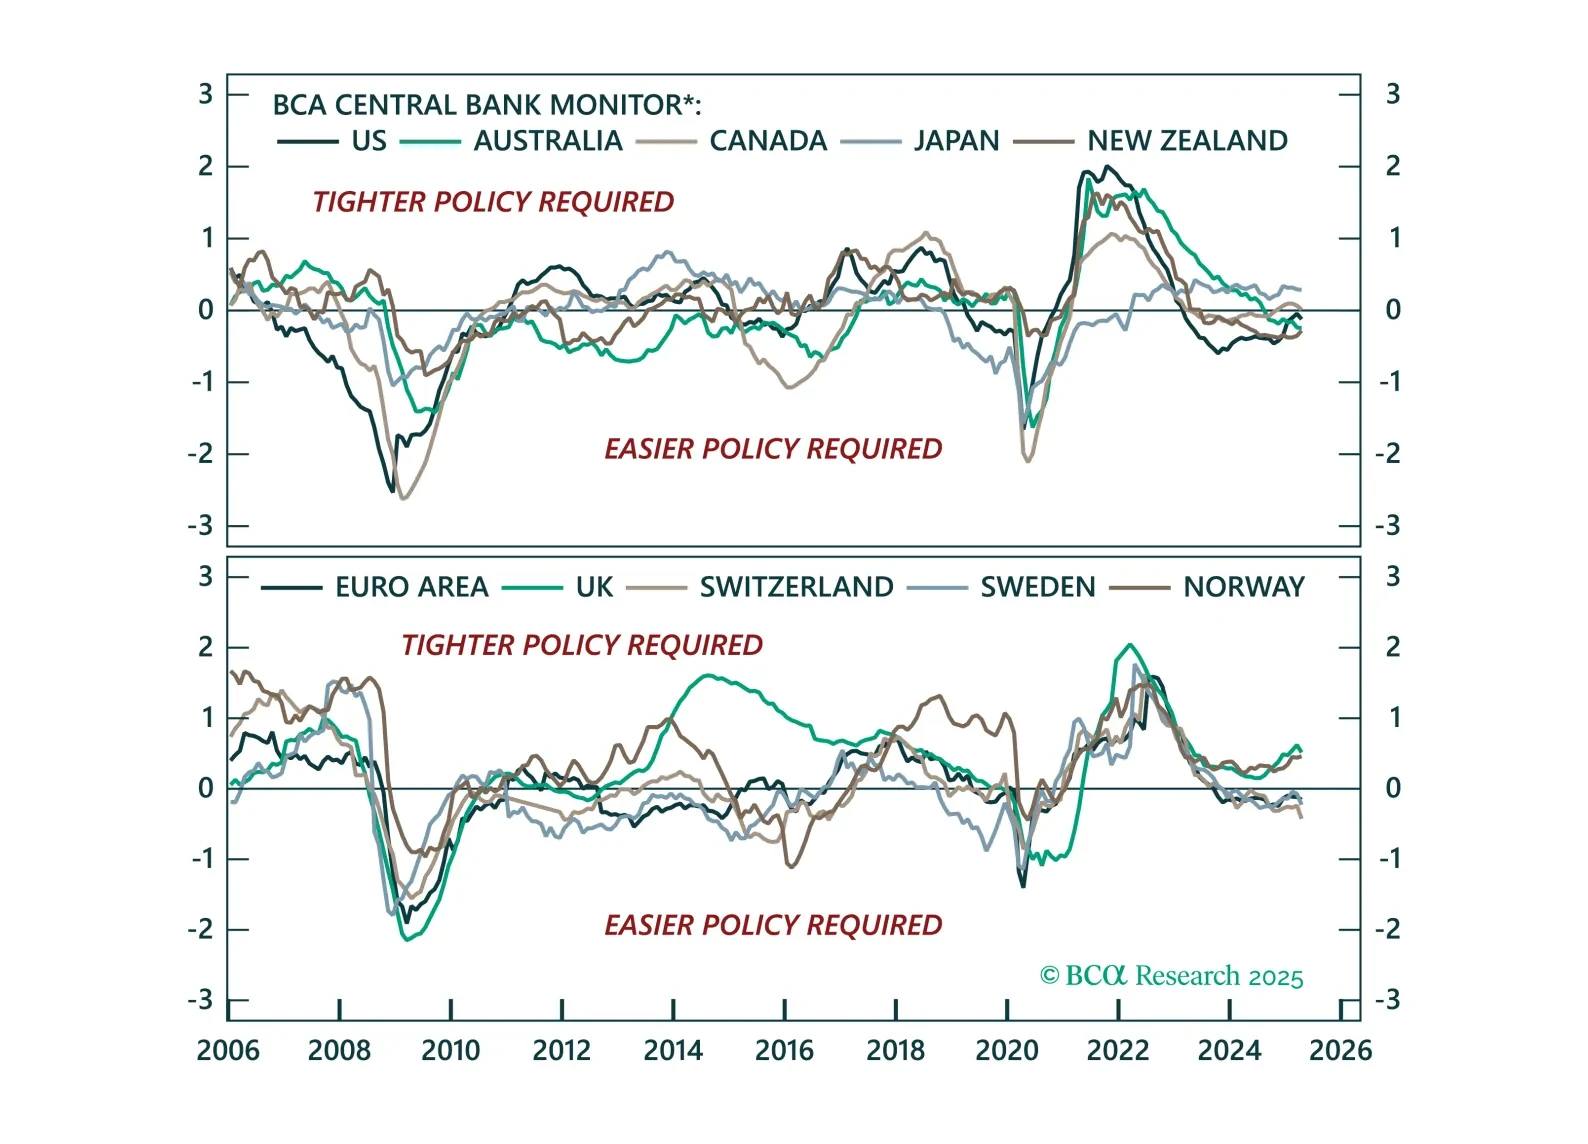
The easing bias remains, but not all central banks are equal. This Central Bank Monitor update reveals who is ready to cut more and who is still pretending not to.
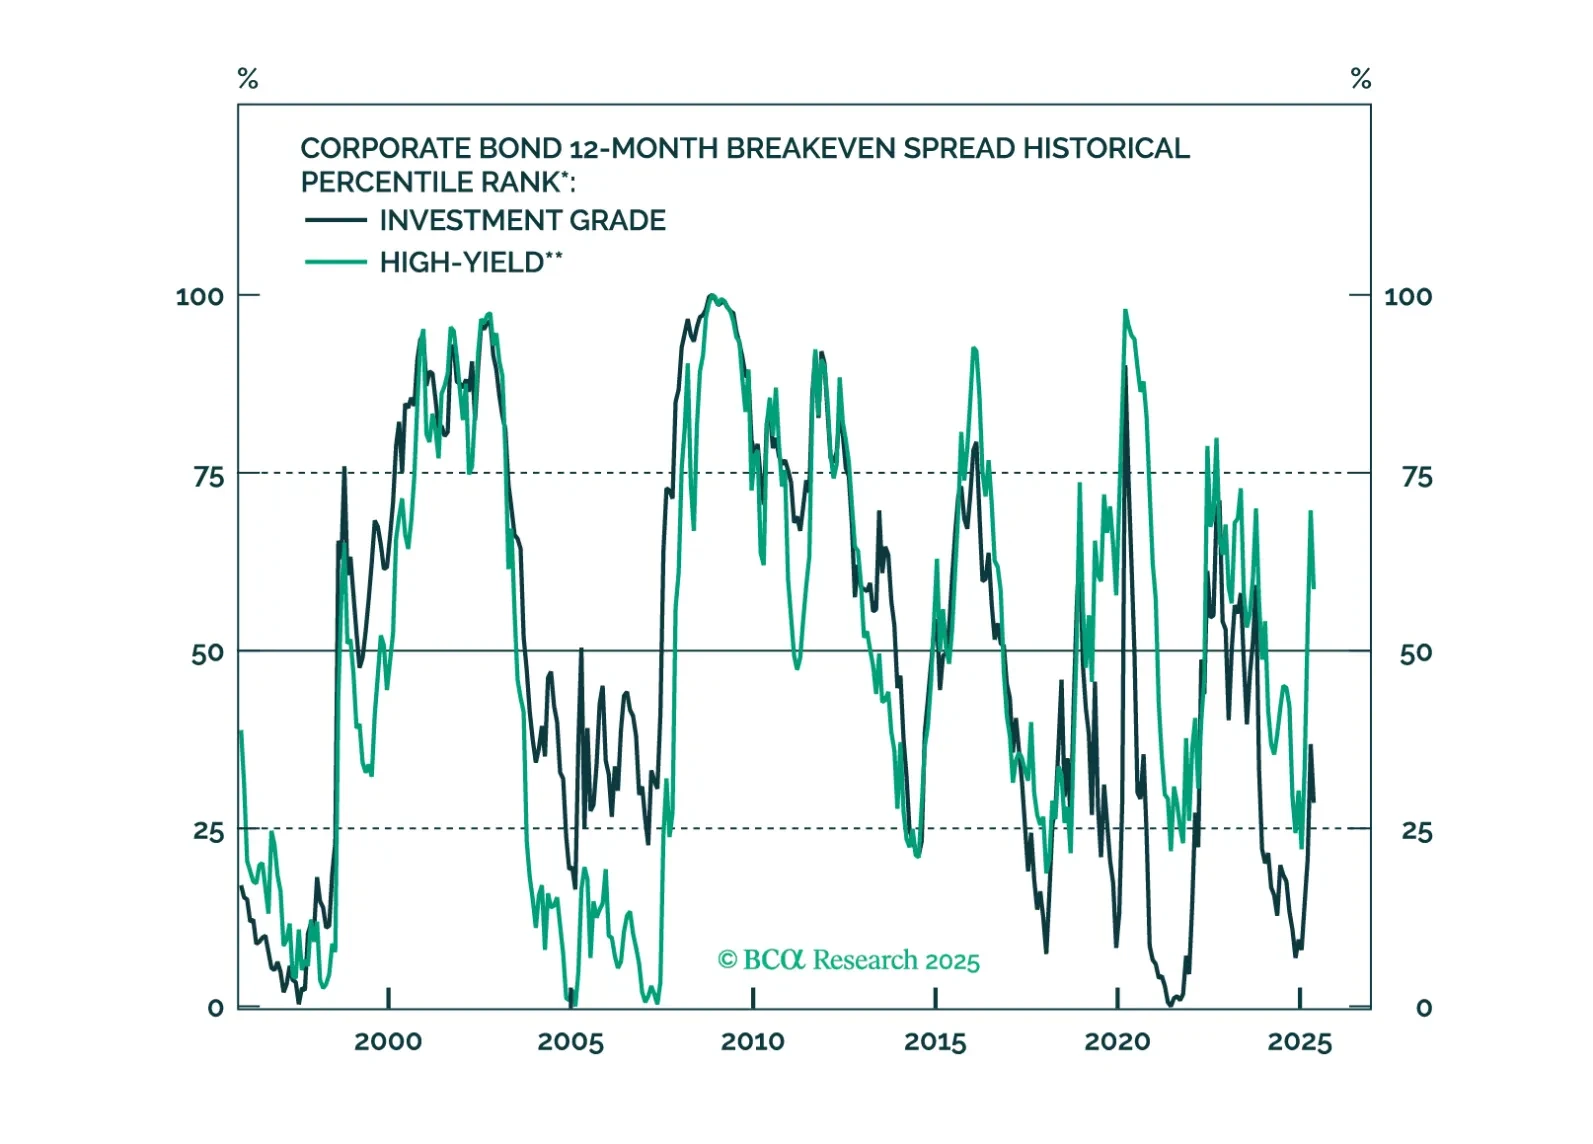

Rate cuts, recession risks, and relative value. This report unpacks how the BoE, Riksbank, and Norges Bank are reacting to global trade turmoil and where the opportunities lie.
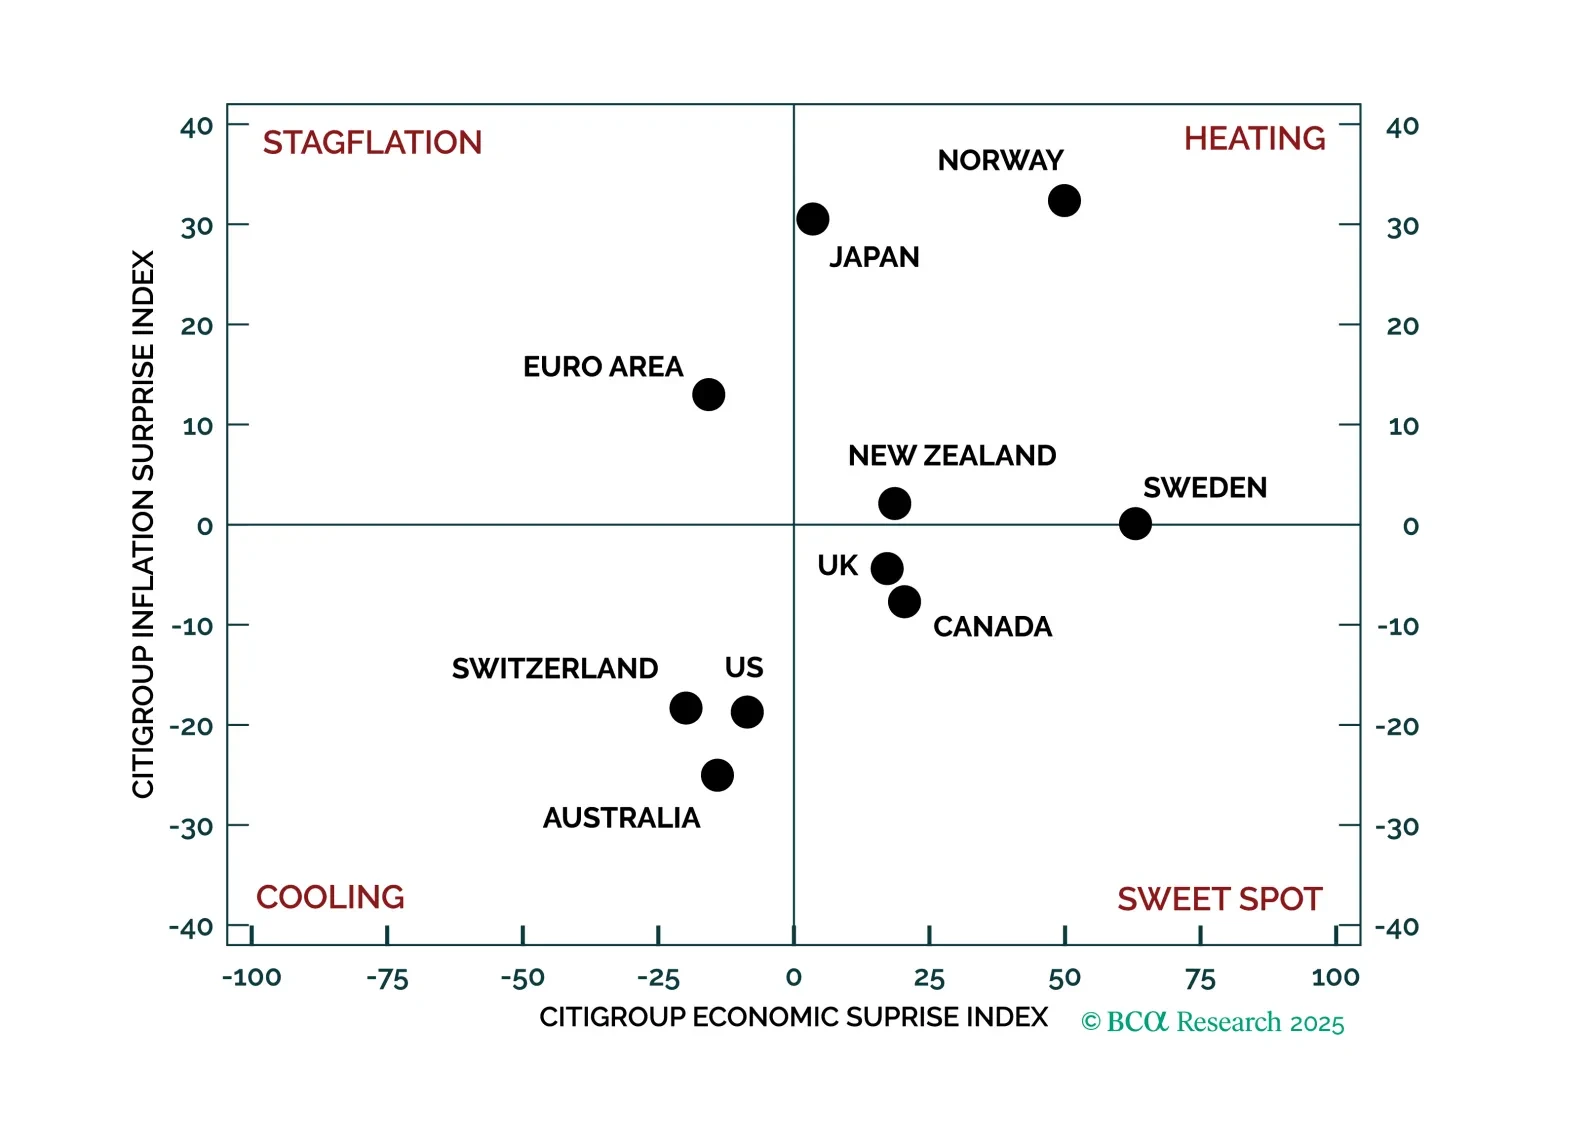
We apply our systematic approach to investing based on economic, inflation, and monetary policy surprises to the major global bond markets. The economic regimes defined by the current macro-surprises setup confirm our existing fixed-income portfolio tactical recommendations.