FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
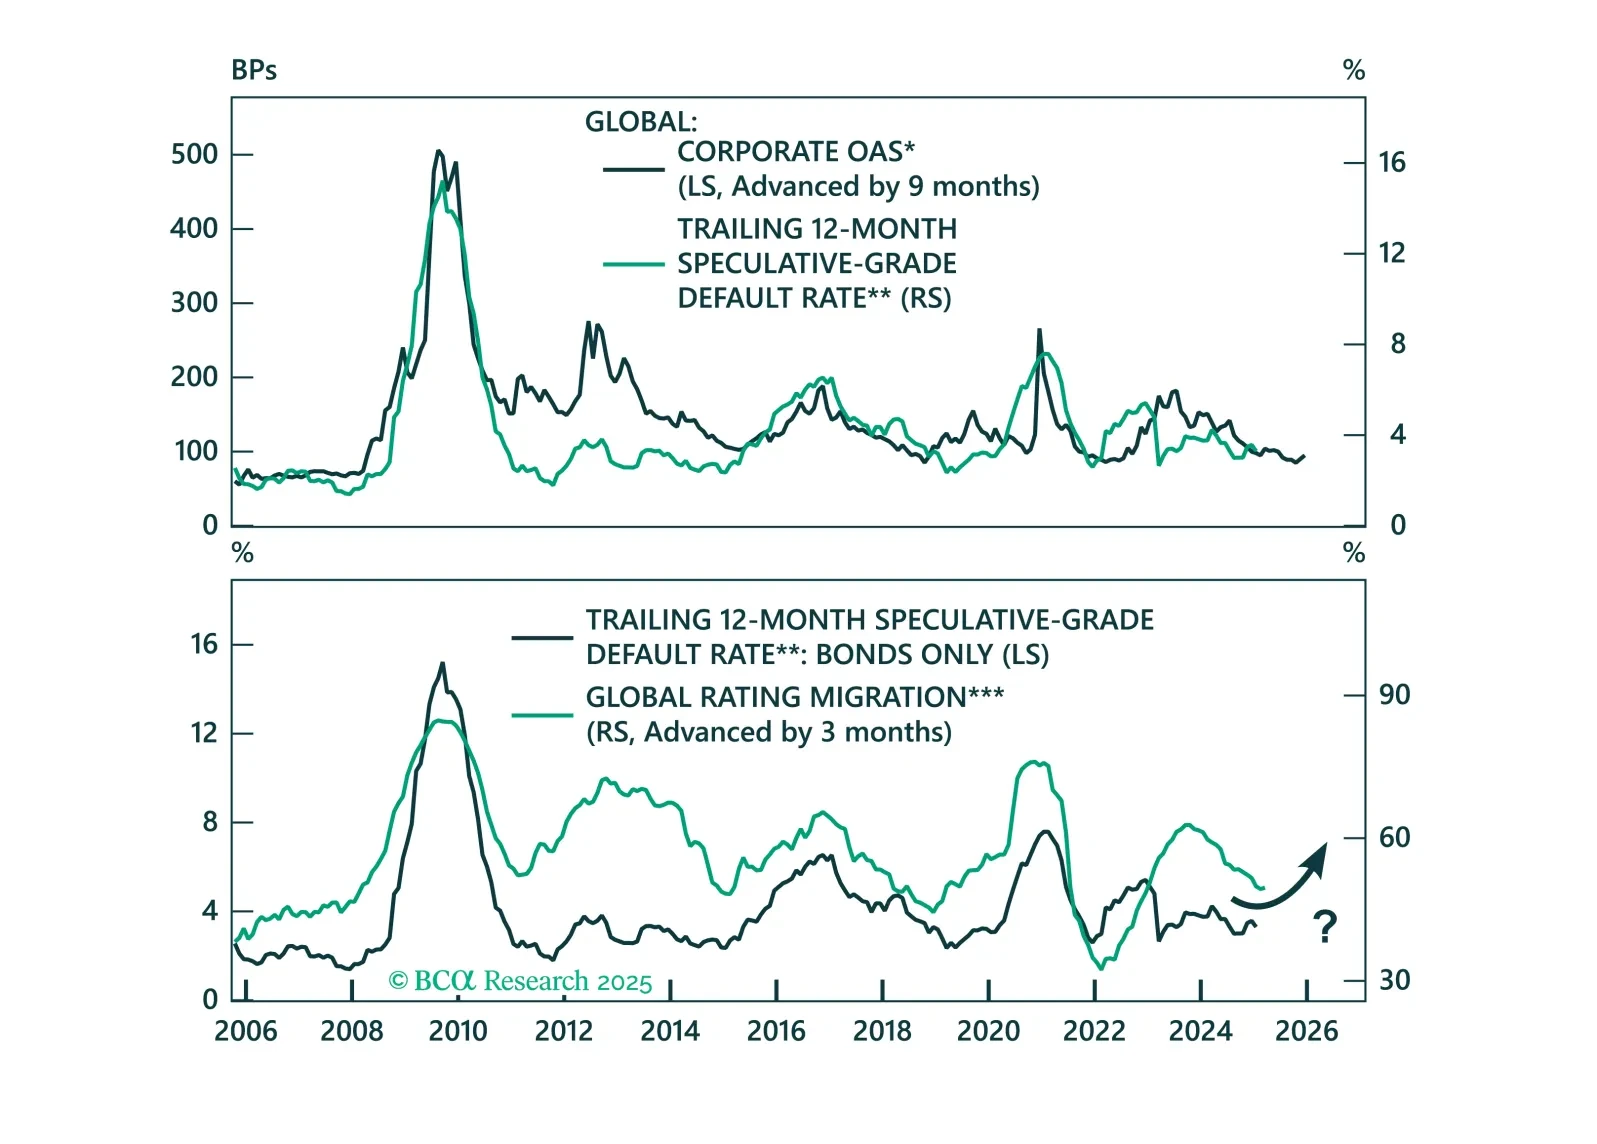
Corporate bond spreads are tight around the globe and do not adequately compensate for the risk of a deterioration in credit quality. We examine the global corporate credit landscape to identify which markets are best equipped to perform in the current environment.
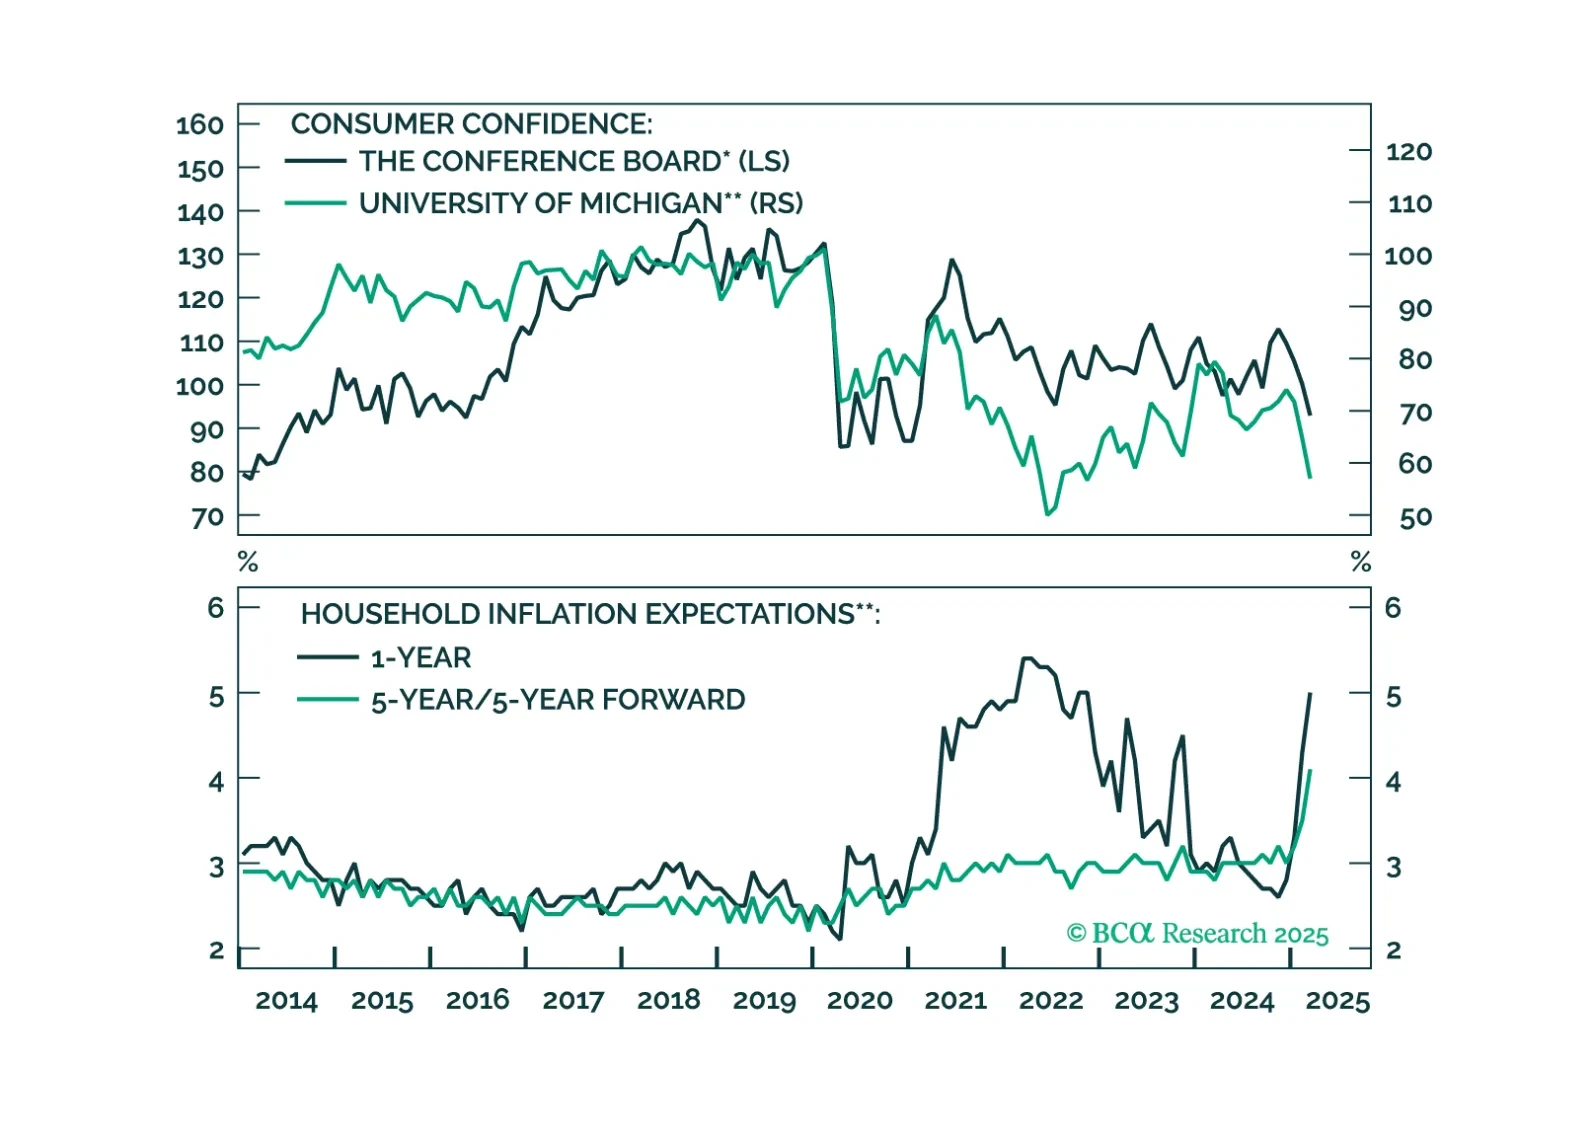
This morning’s weak consumer spending and strong inflation data reinforce our sense that the US economy is heading toward recession.

This report is a quick take on our views on UK bonds and FX, given the recent budget.
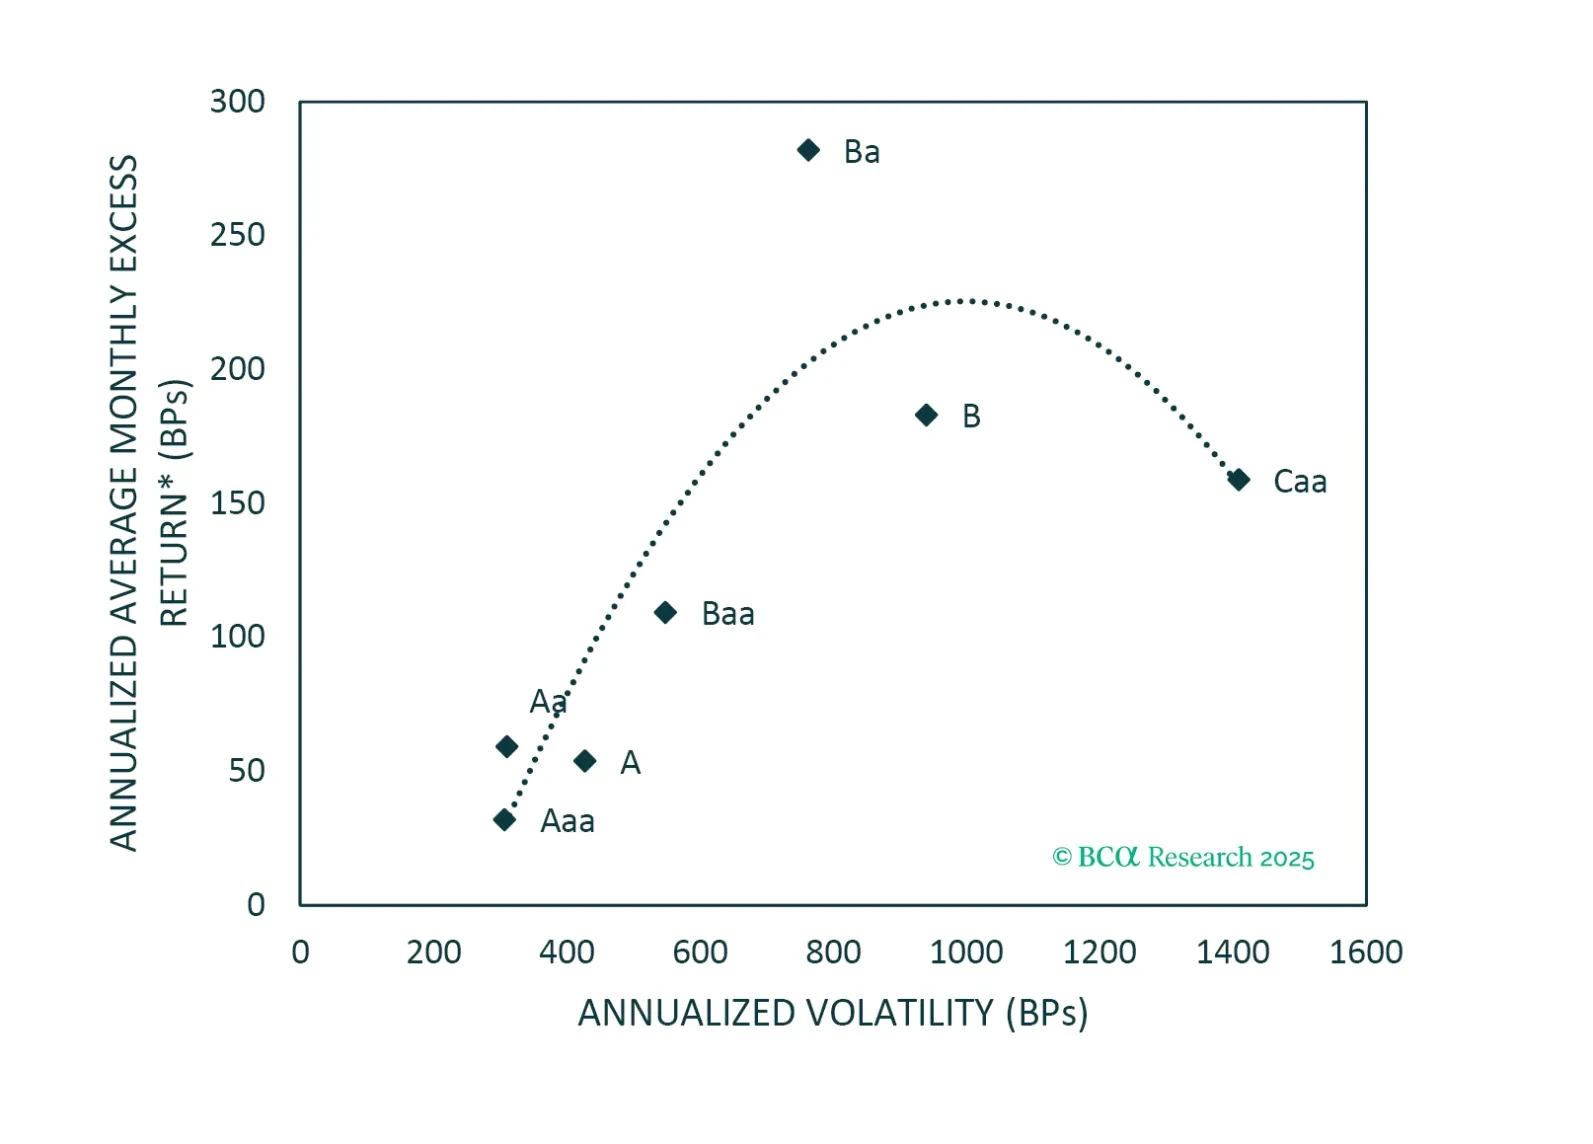
An analysis of historical data shows that Ba-rated bonds outperform other corporate credit tiers in the long-run on a risk-adjusted basis. That said, today’s fragile macro environment warrants a more cautious allocation.
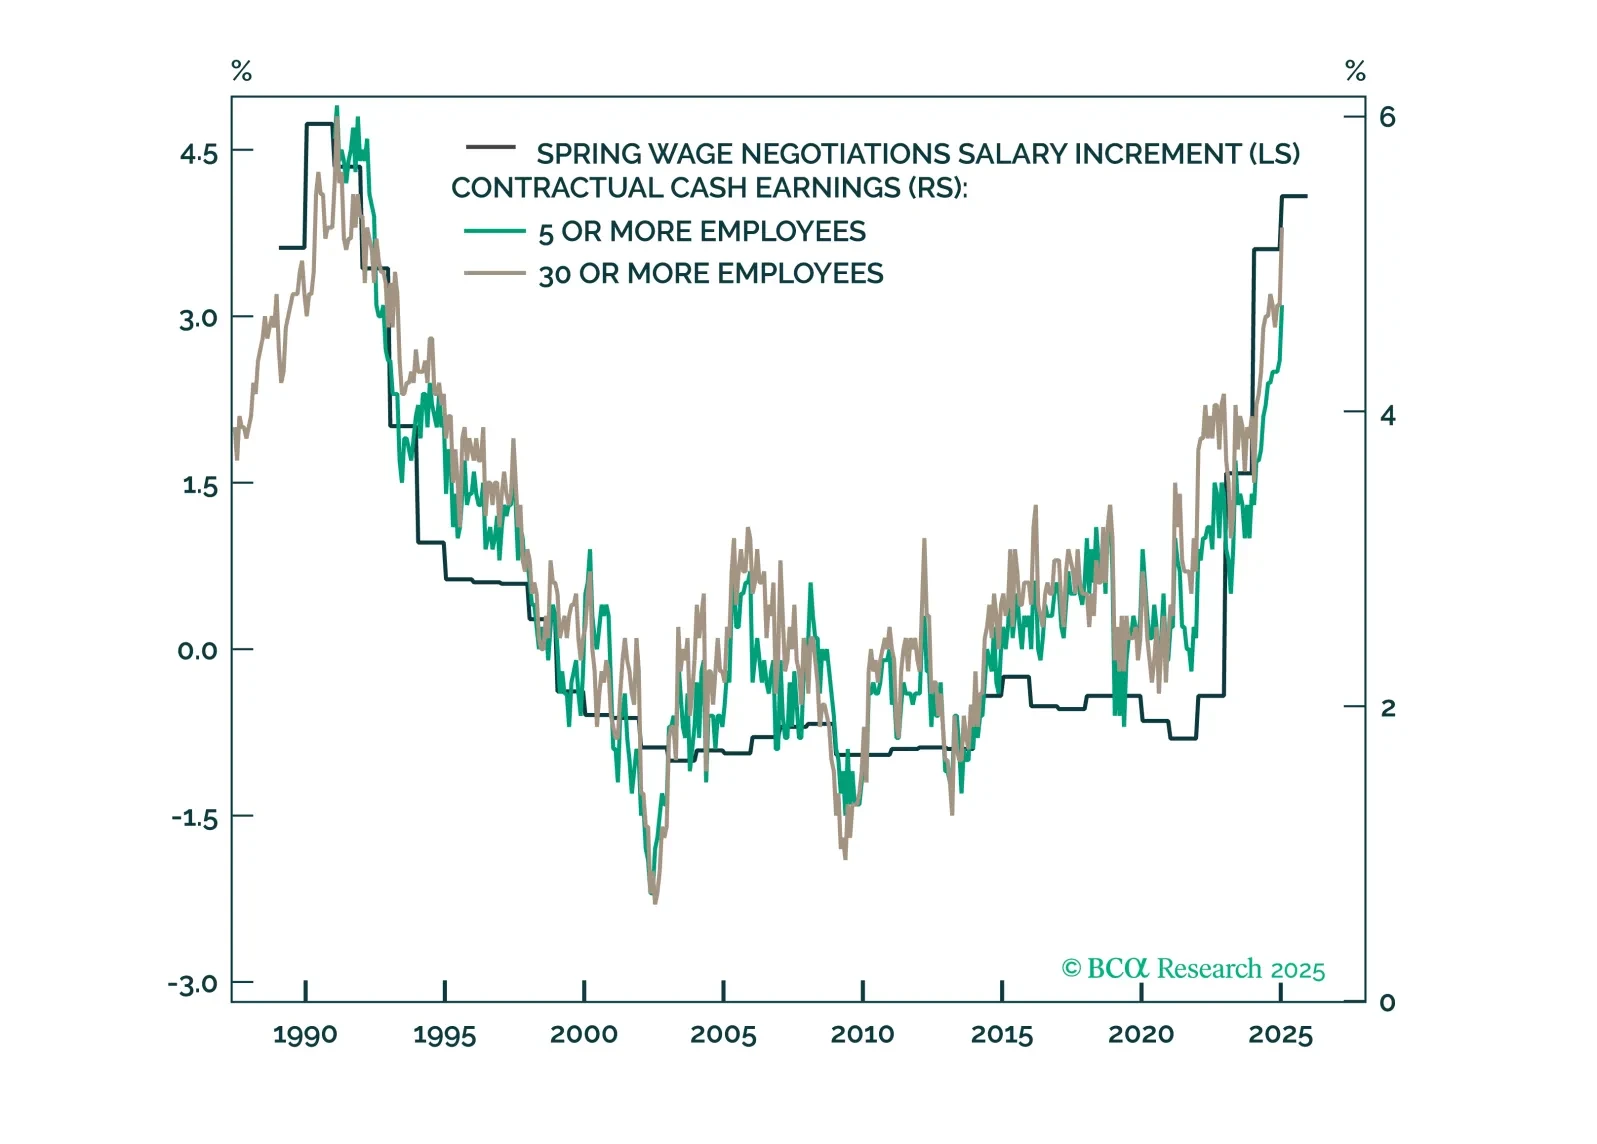
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are: Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30. Underweight JGBs. Correspondingly, be long the yen. A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.
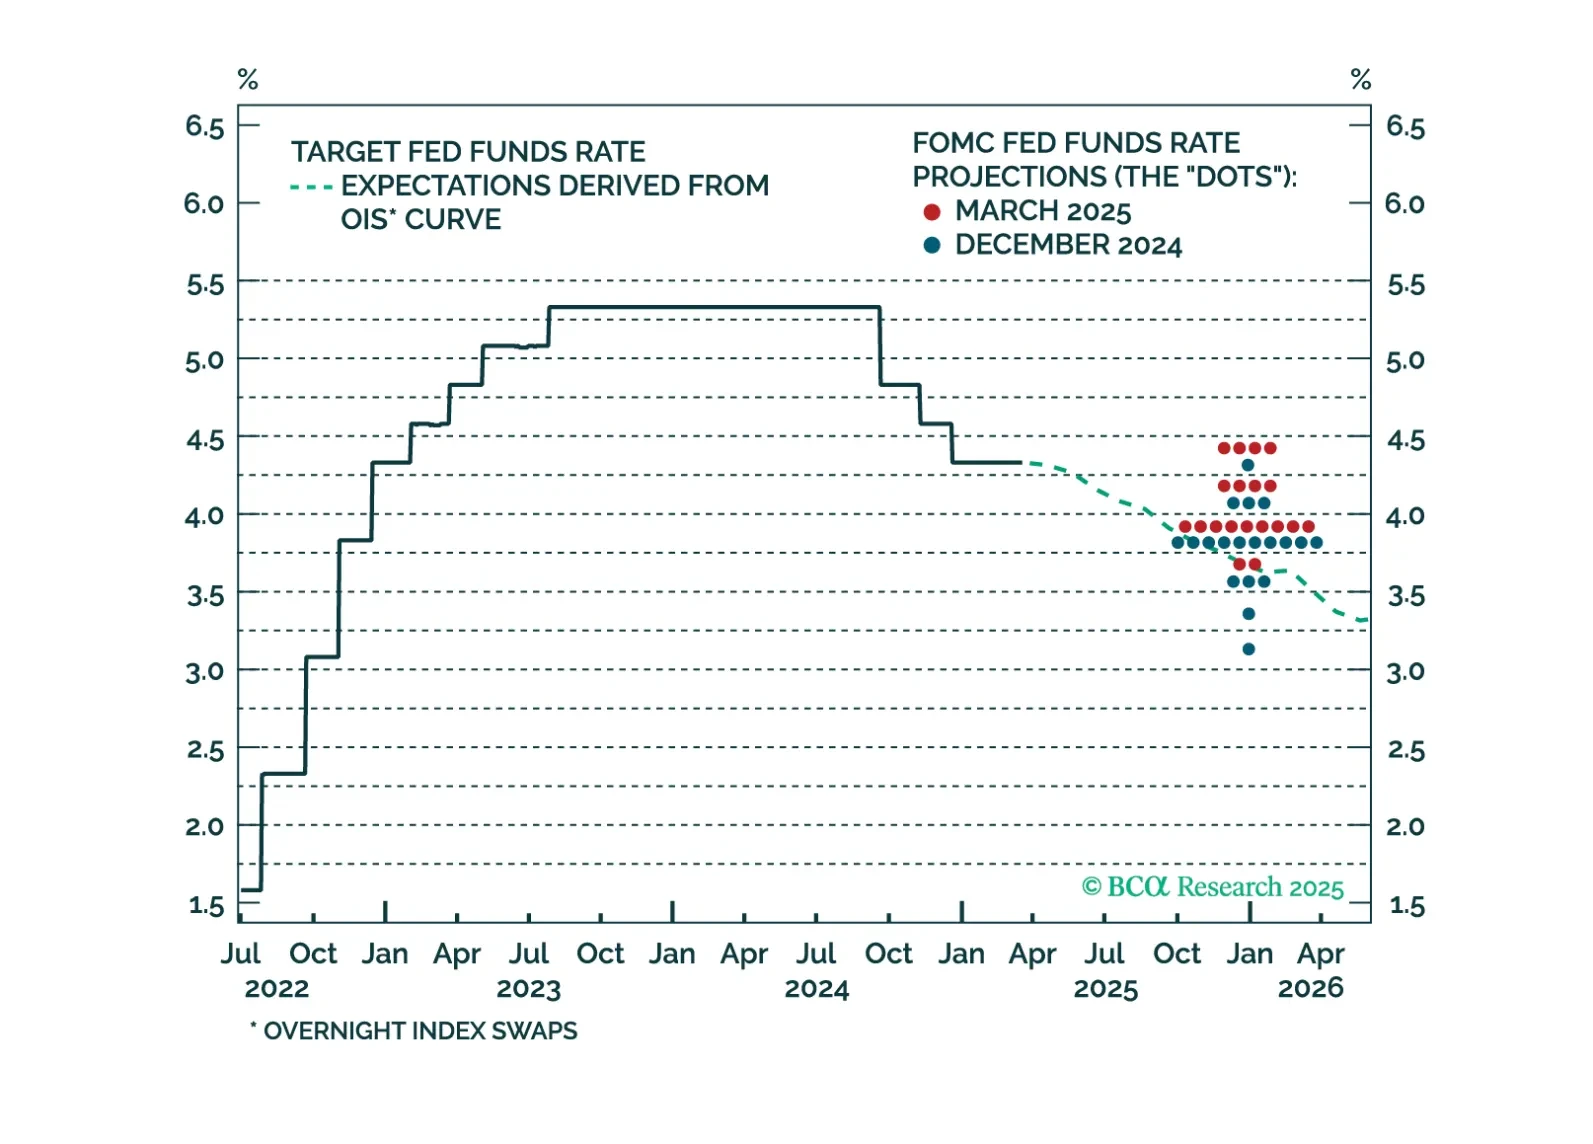
The market reaction to this afternoon’s Fed meeting looks overdone. Investors could be in for a hawkish surprise when it becomes apparent that the Fed won’t ease policy into higher tariff-driven inflation prints.
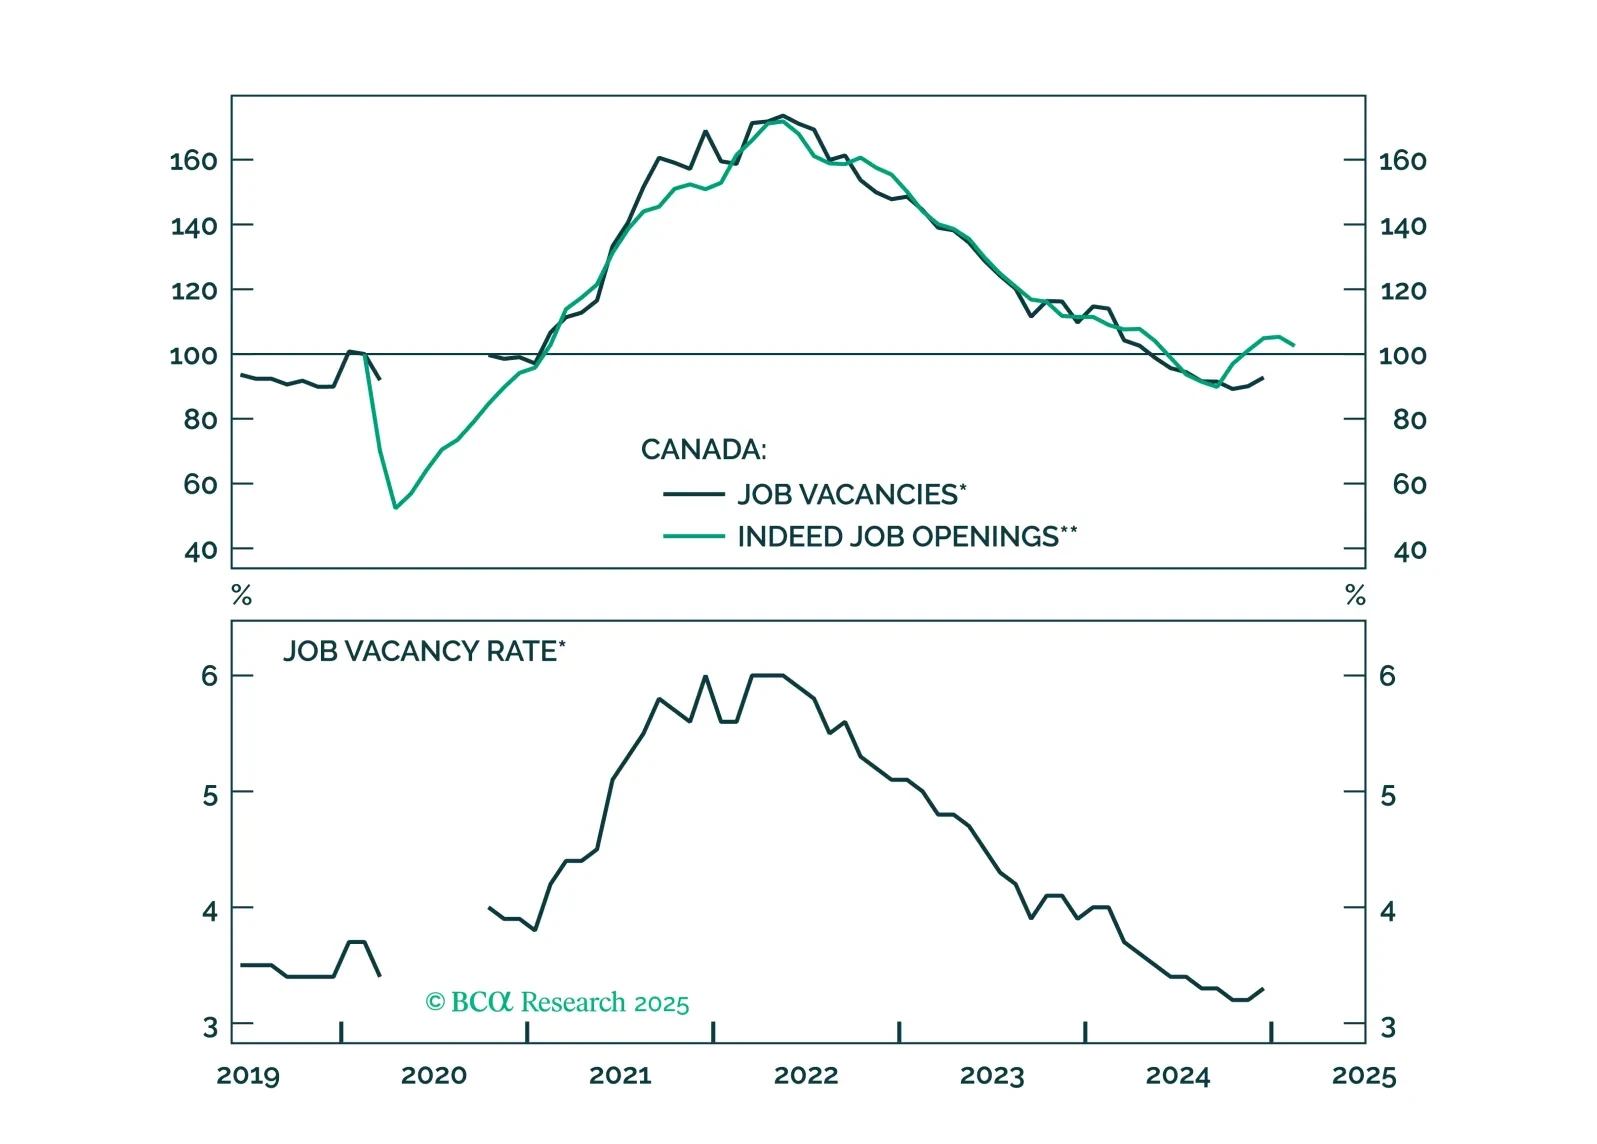
The trade war complicates the Bank of Canada’s task to achieve stable inflation. But the bottom line is that rising uncertainty, which will dampen business sentiment, will cause the BoC to cut rates by at least what is priced in the CORRA curve, and likely to 2%. The CAD, which is very oversold, might not depreciate much. The big trade is a bet on a spread widening for Canadian provincial bonds.
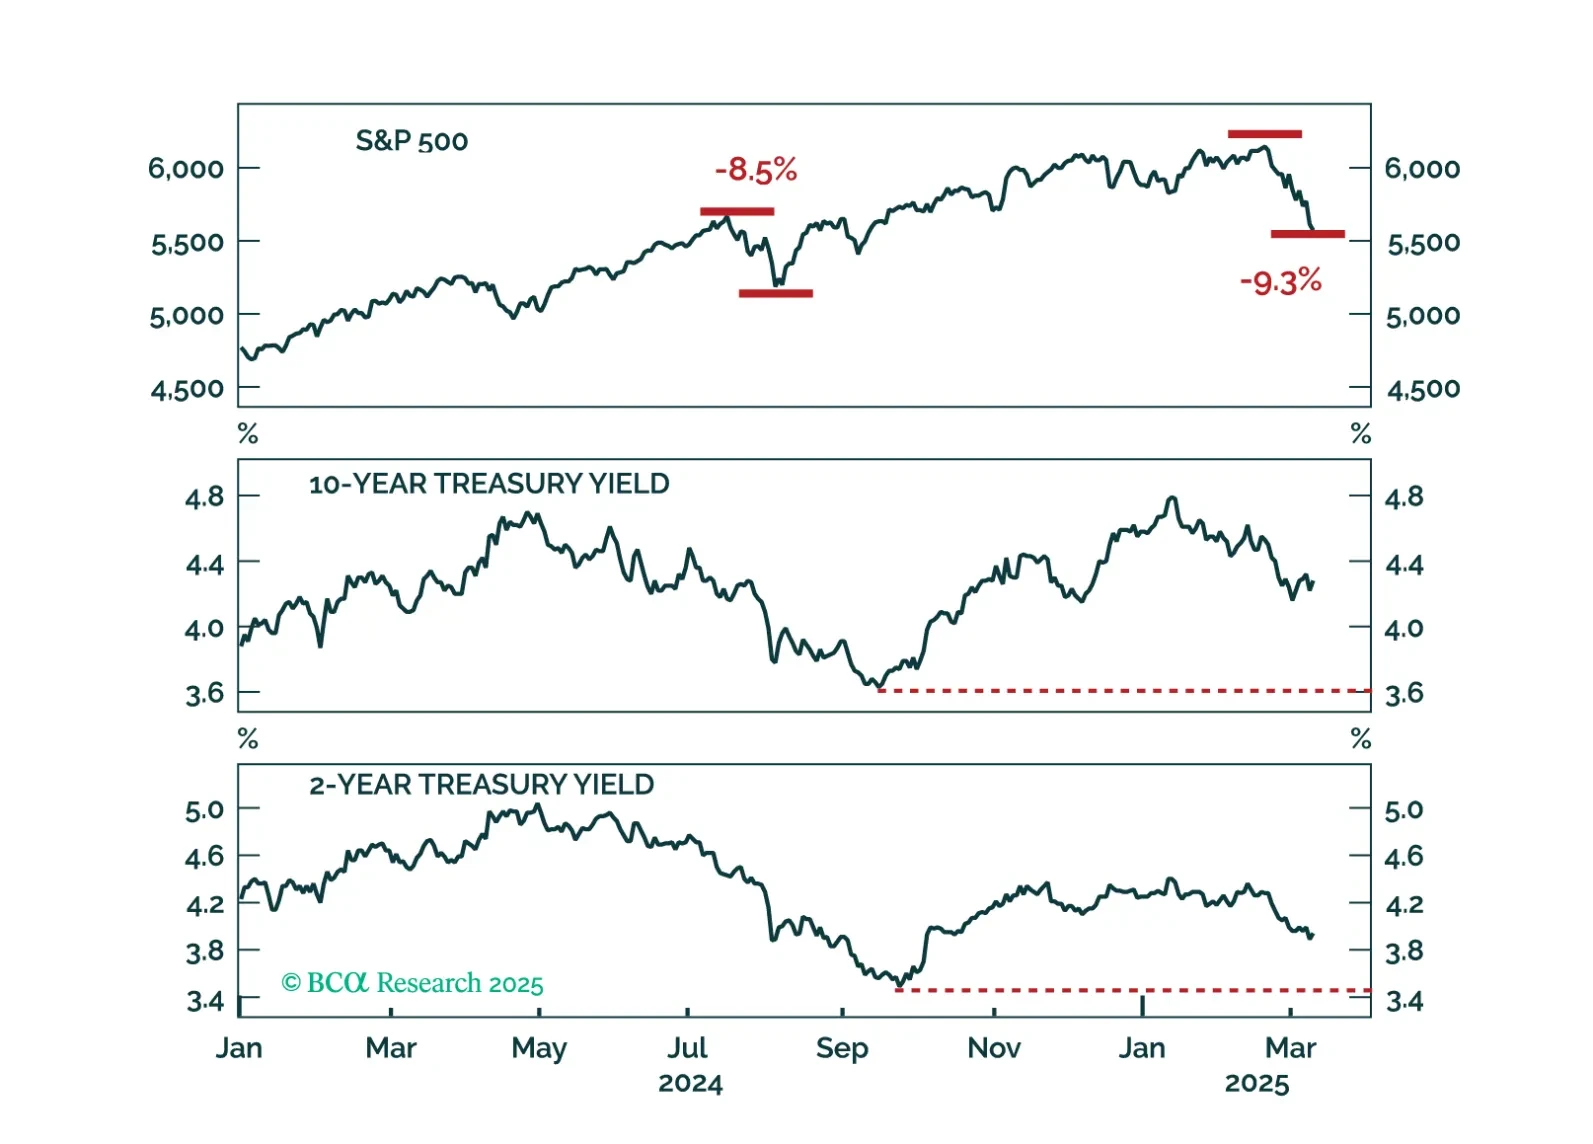
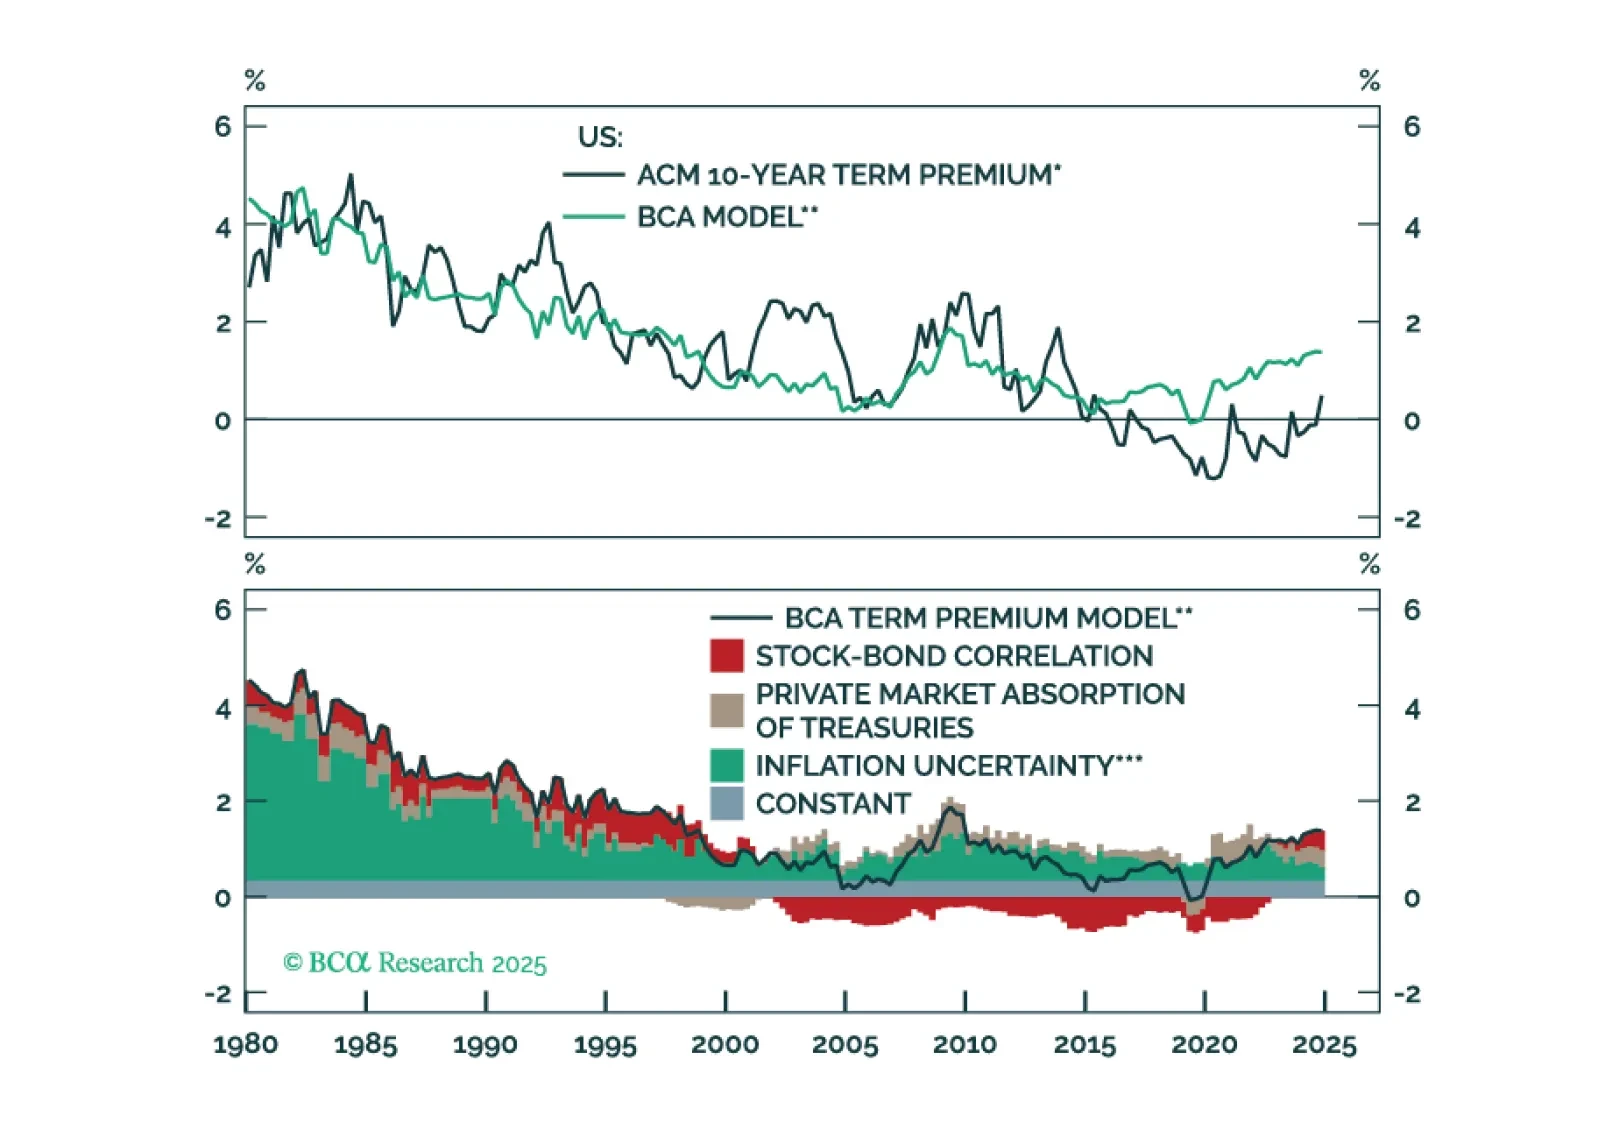
A falling stock market and sticky bond yields represent the worst of both worlds for investors. We interrogate why bond yields haven’t dropped more given the large selloff seen in equities.
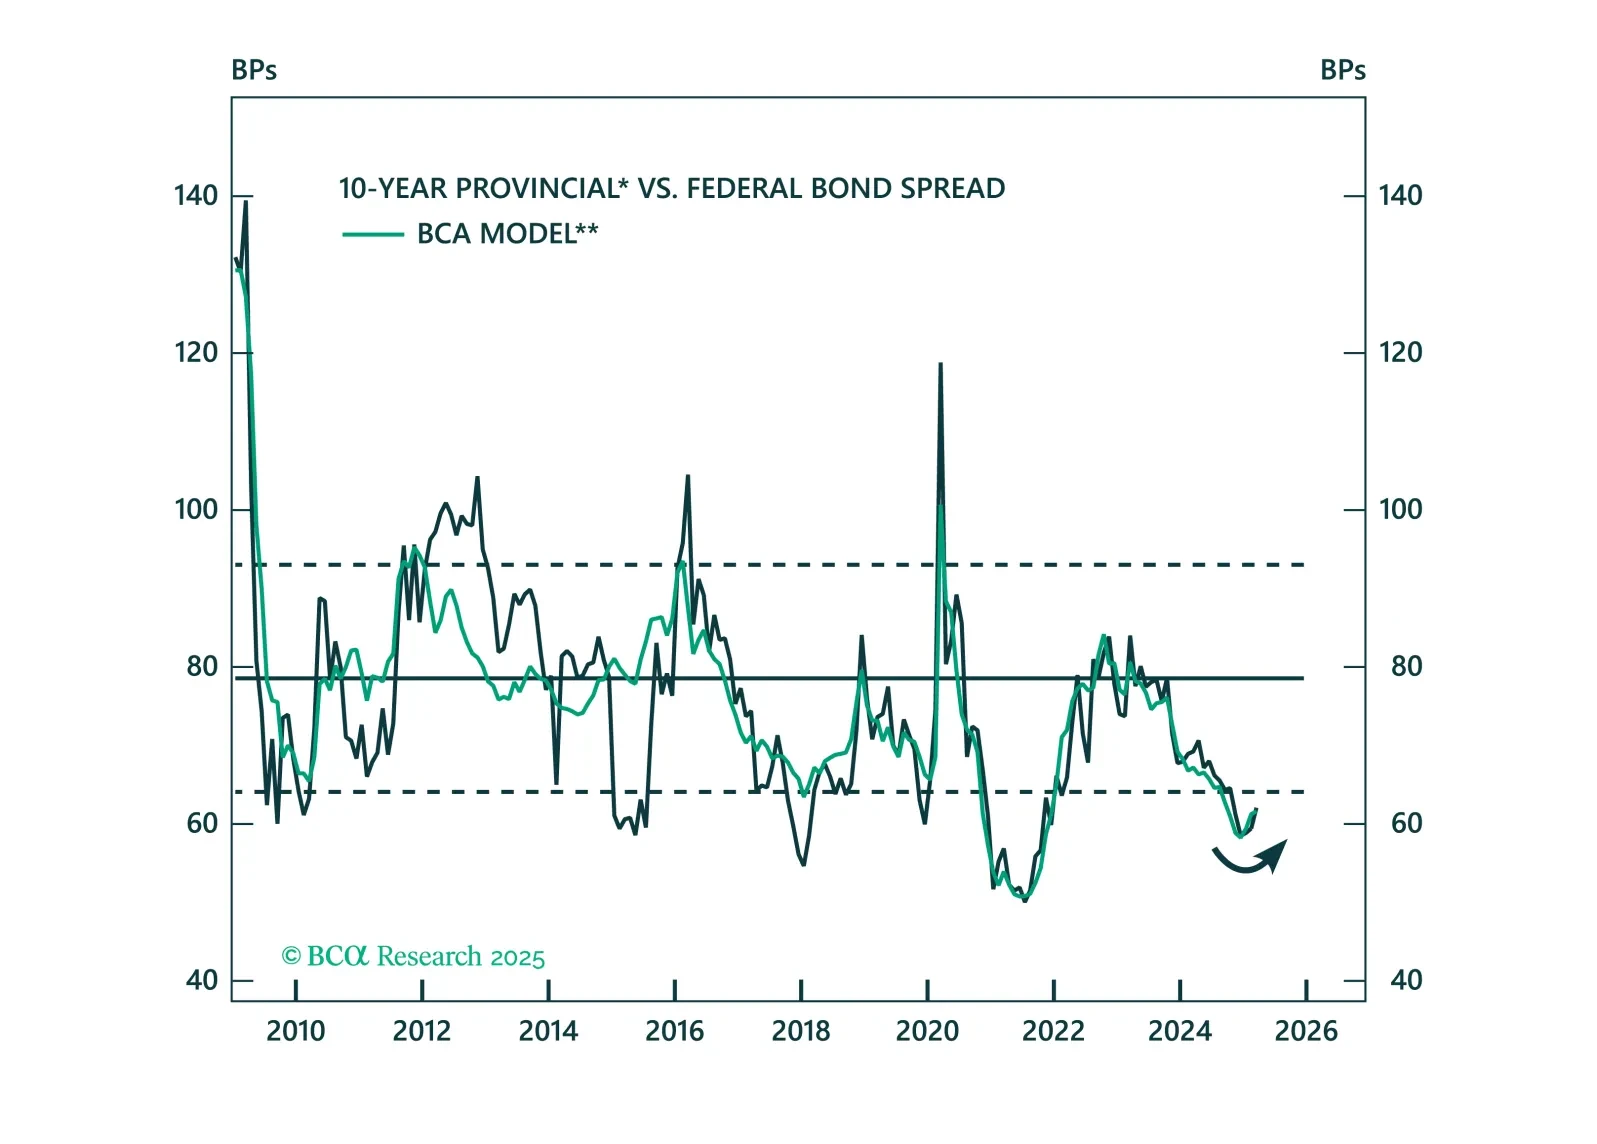
In this report, we explore the Canadian provincial bond market by developing a model to analyze its main drivers and understand the impact of a potential trade war between Canada and the US.