 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
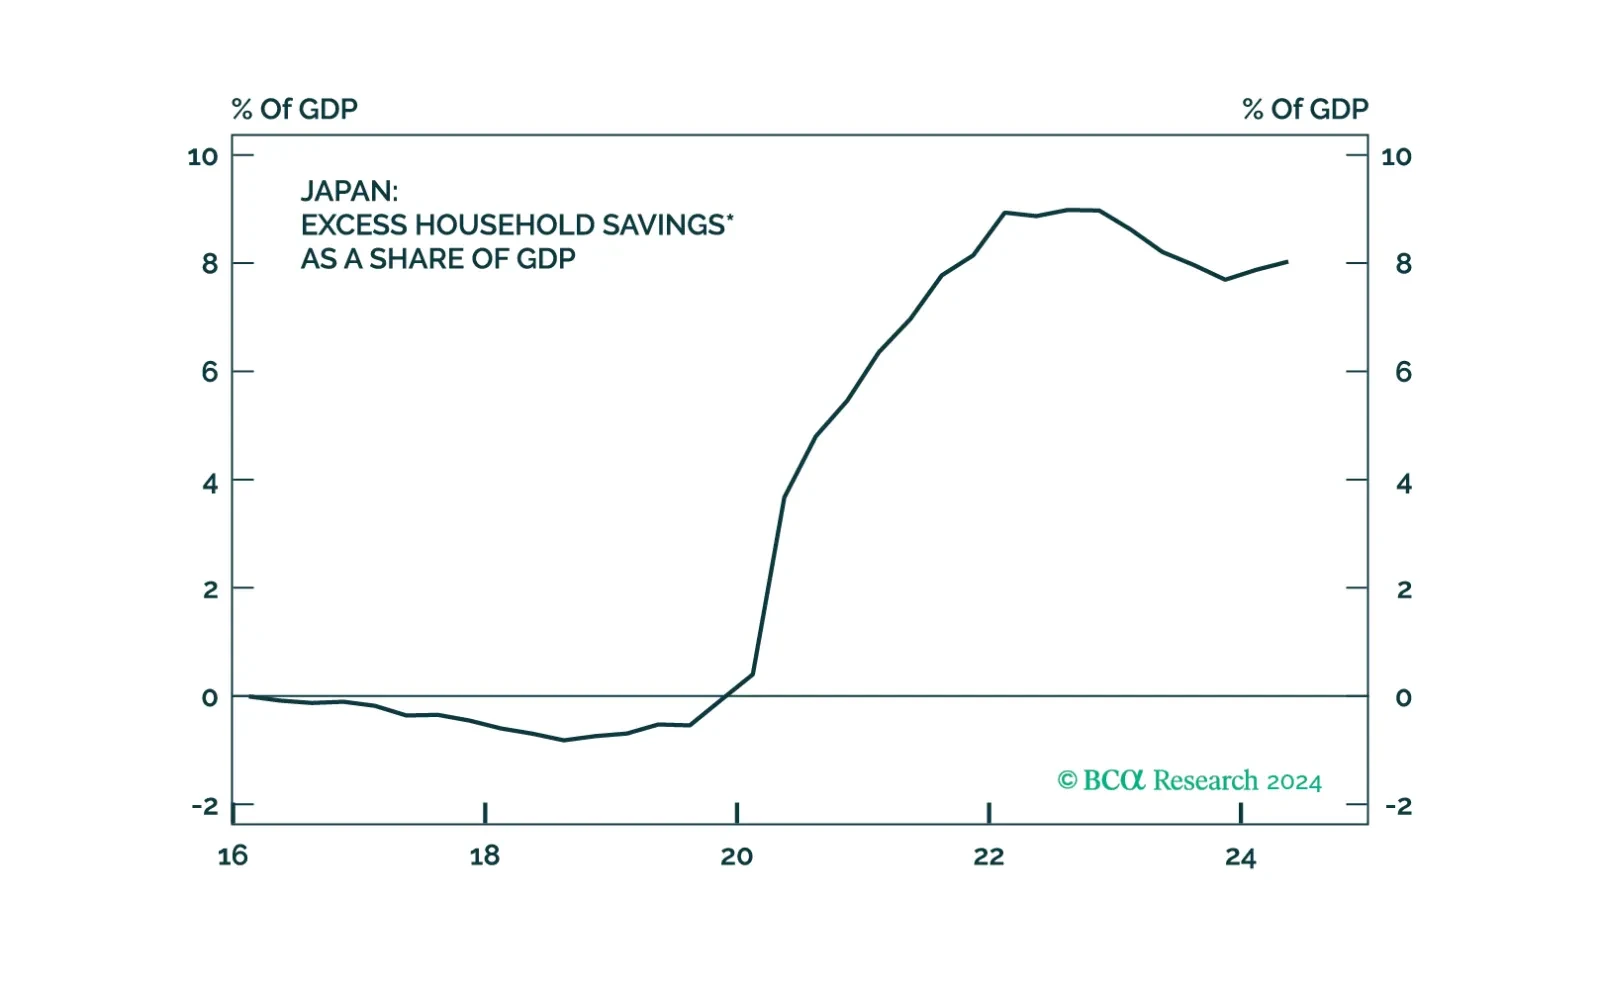
The latest Bank of Japan meeting did not alter our high-conviction views of being long the yen and underweight JGBs.
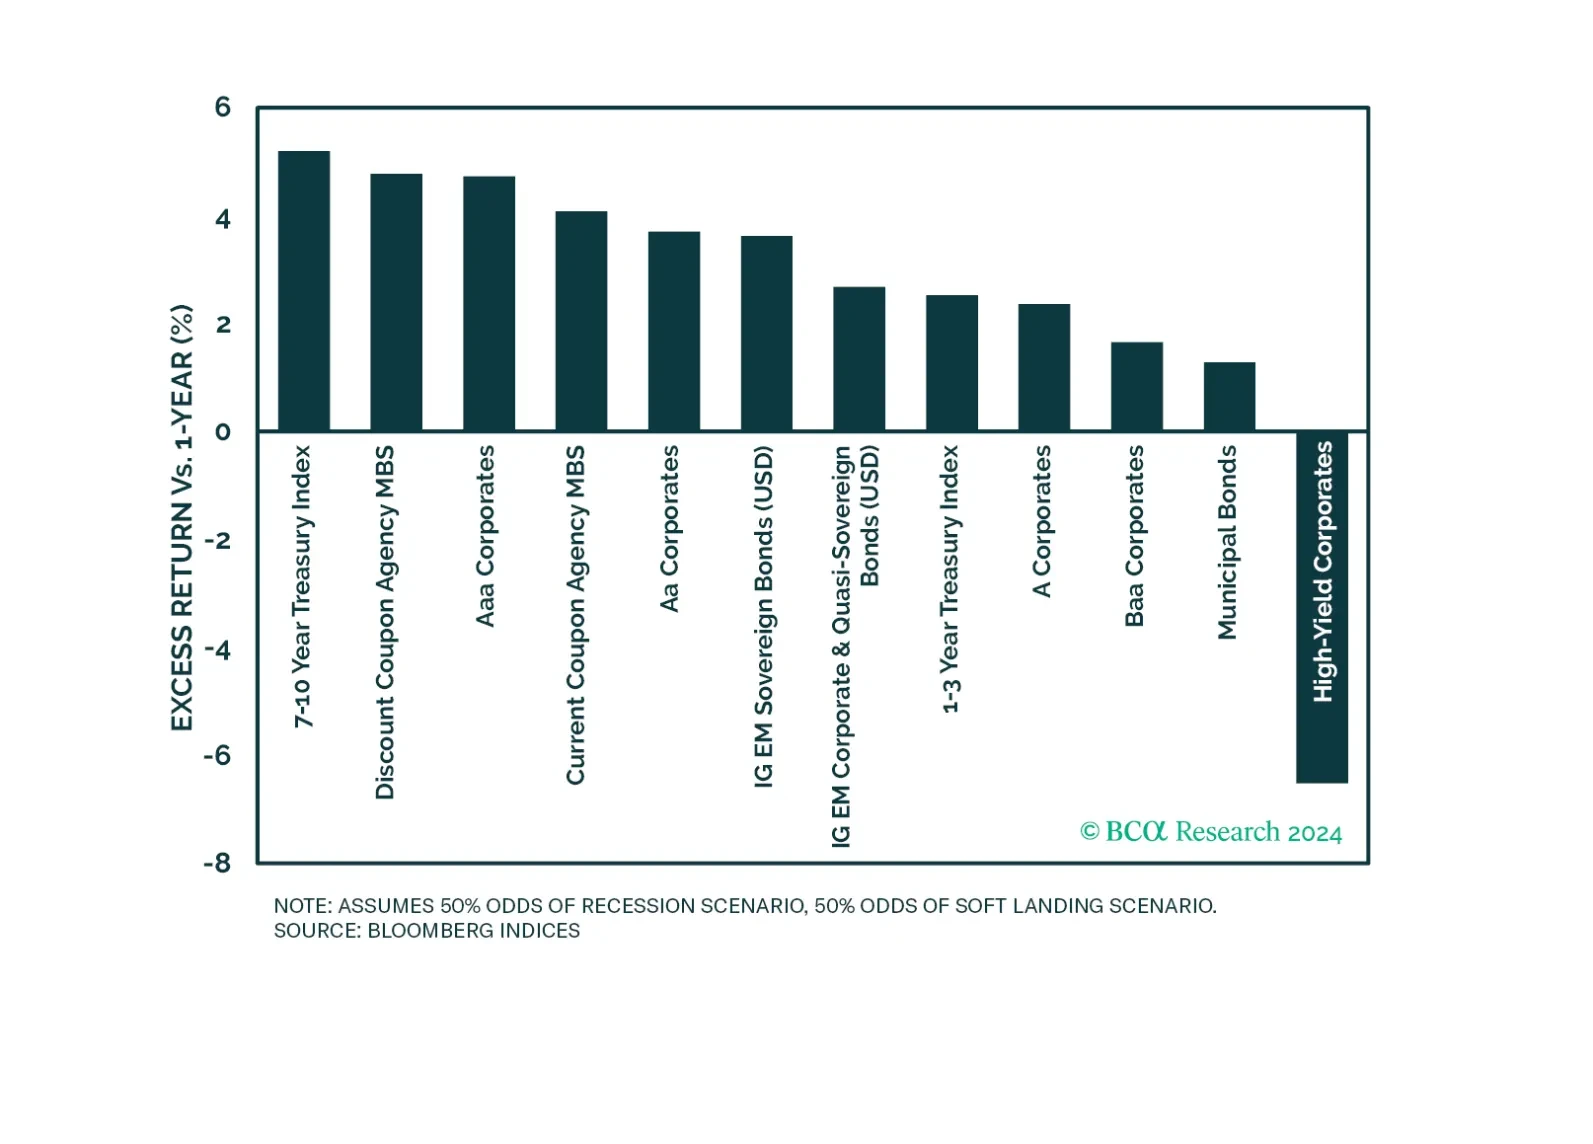
We update our 12-month return projections for different US fixed income sectors in soft-landing and recession scenarios.

In this Insight, we evaluate if there is more juice in our macro bet of being long June 2025 CORRA versus SOFR futures, and correspondingly, being short the CAD, for investors with a 1-3 month horizon.
A Donald Trump victory would send bond yields higher during the next few weeks, but yields will fall in 2025 no matter the election outcome.

This Insight looks at the likely direction of bond yields and the dollar, from the lens of money velocity.
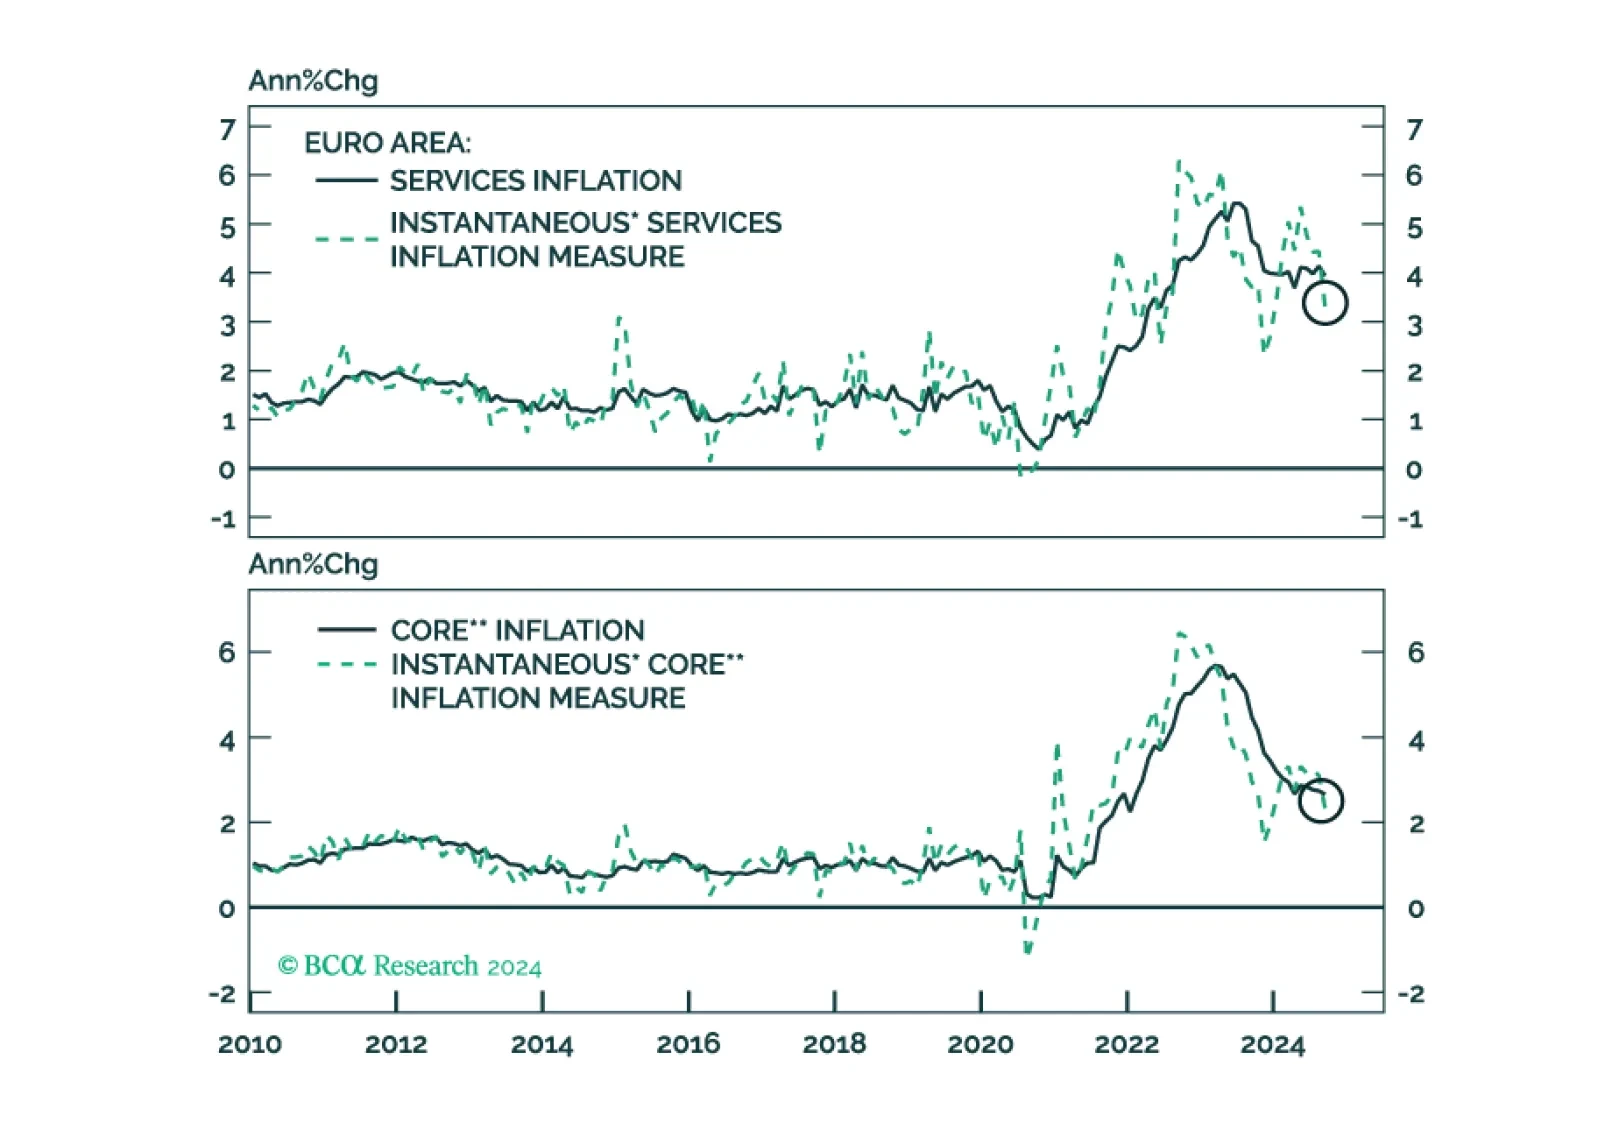
Yesterday, the ECB solidified its recent dovish tilt in response to weaker growth and decreasing inflationary pressures. It is now set to cut rates 25bps each meeting. How low will the ECB deposit rate ultimately go and what does this imply for yields and the euro?
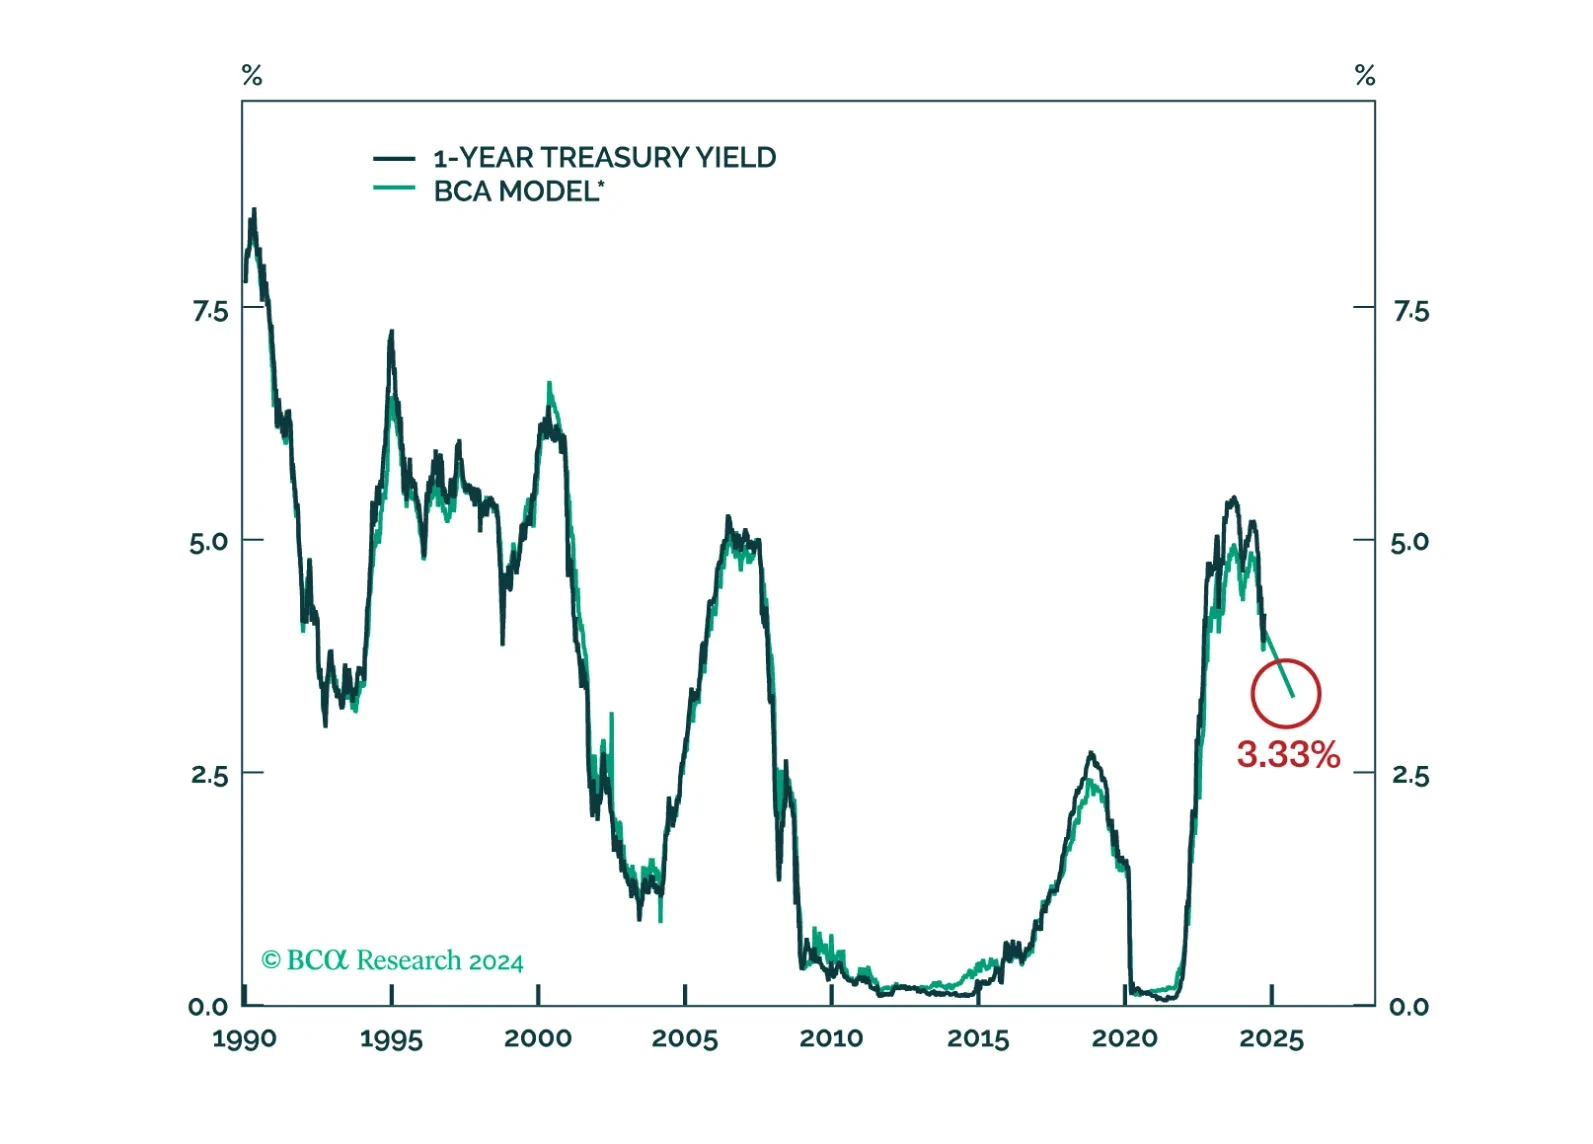
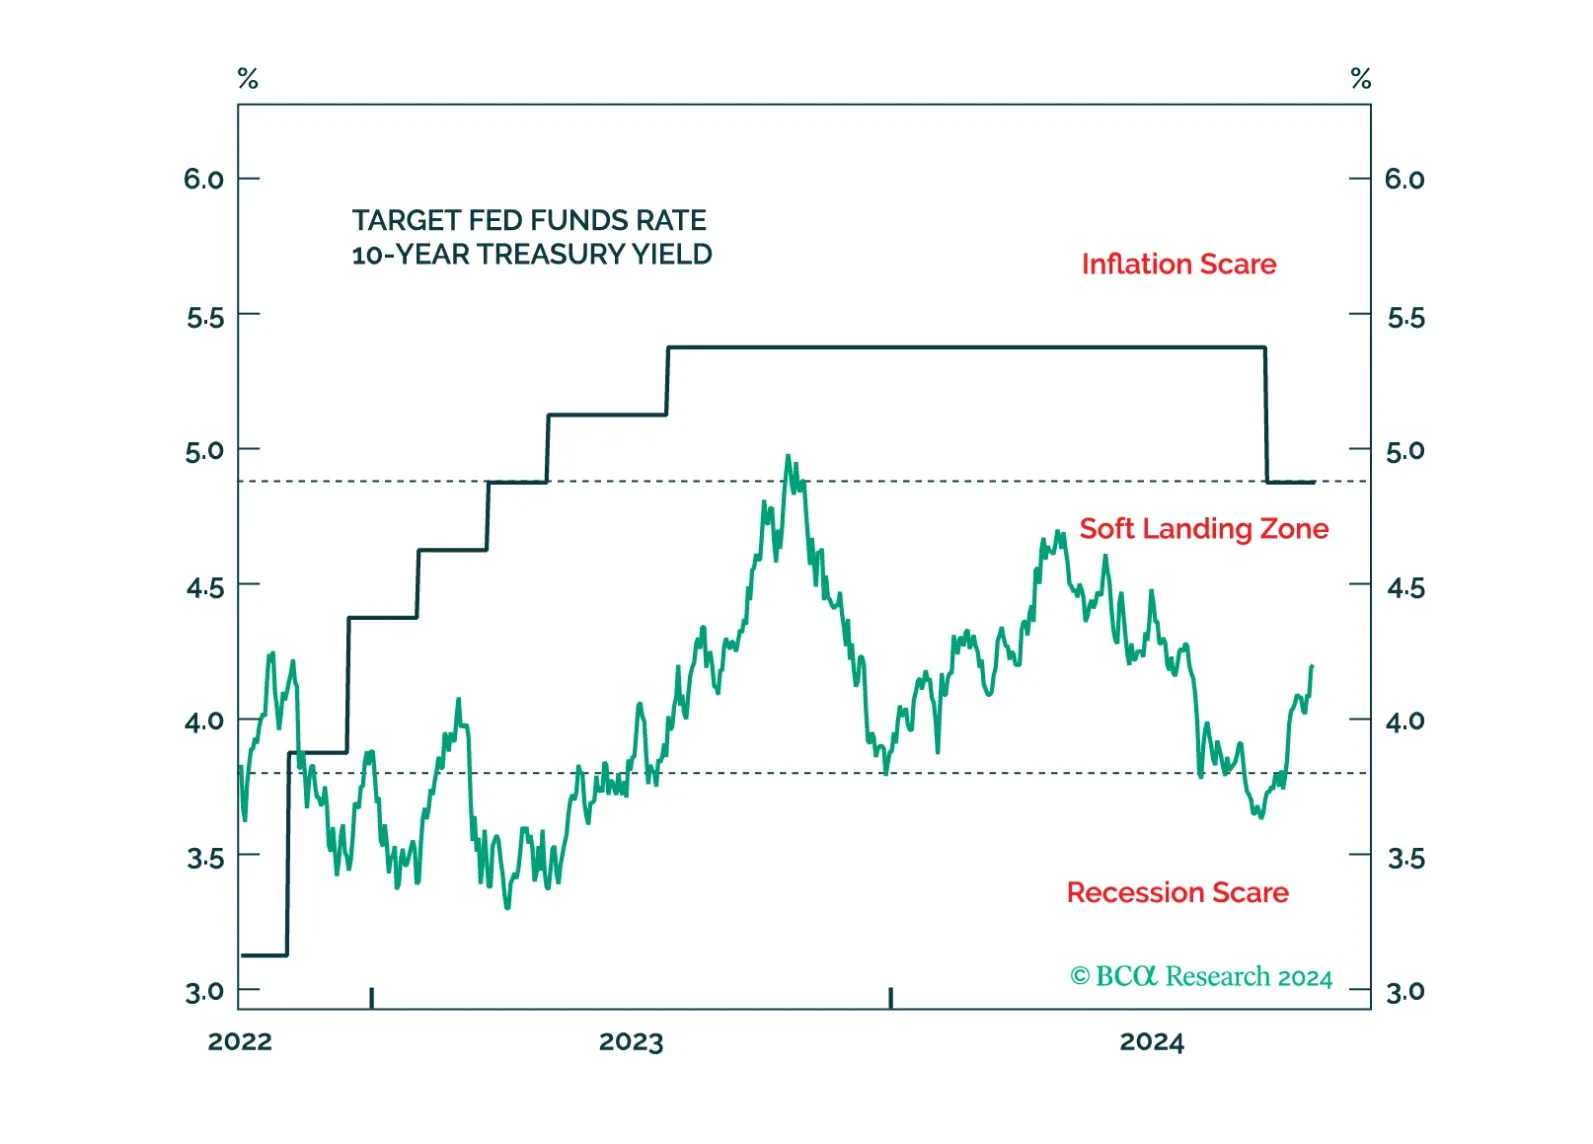
We estimate where Treasury yields might go in a soft landing economic scenario.
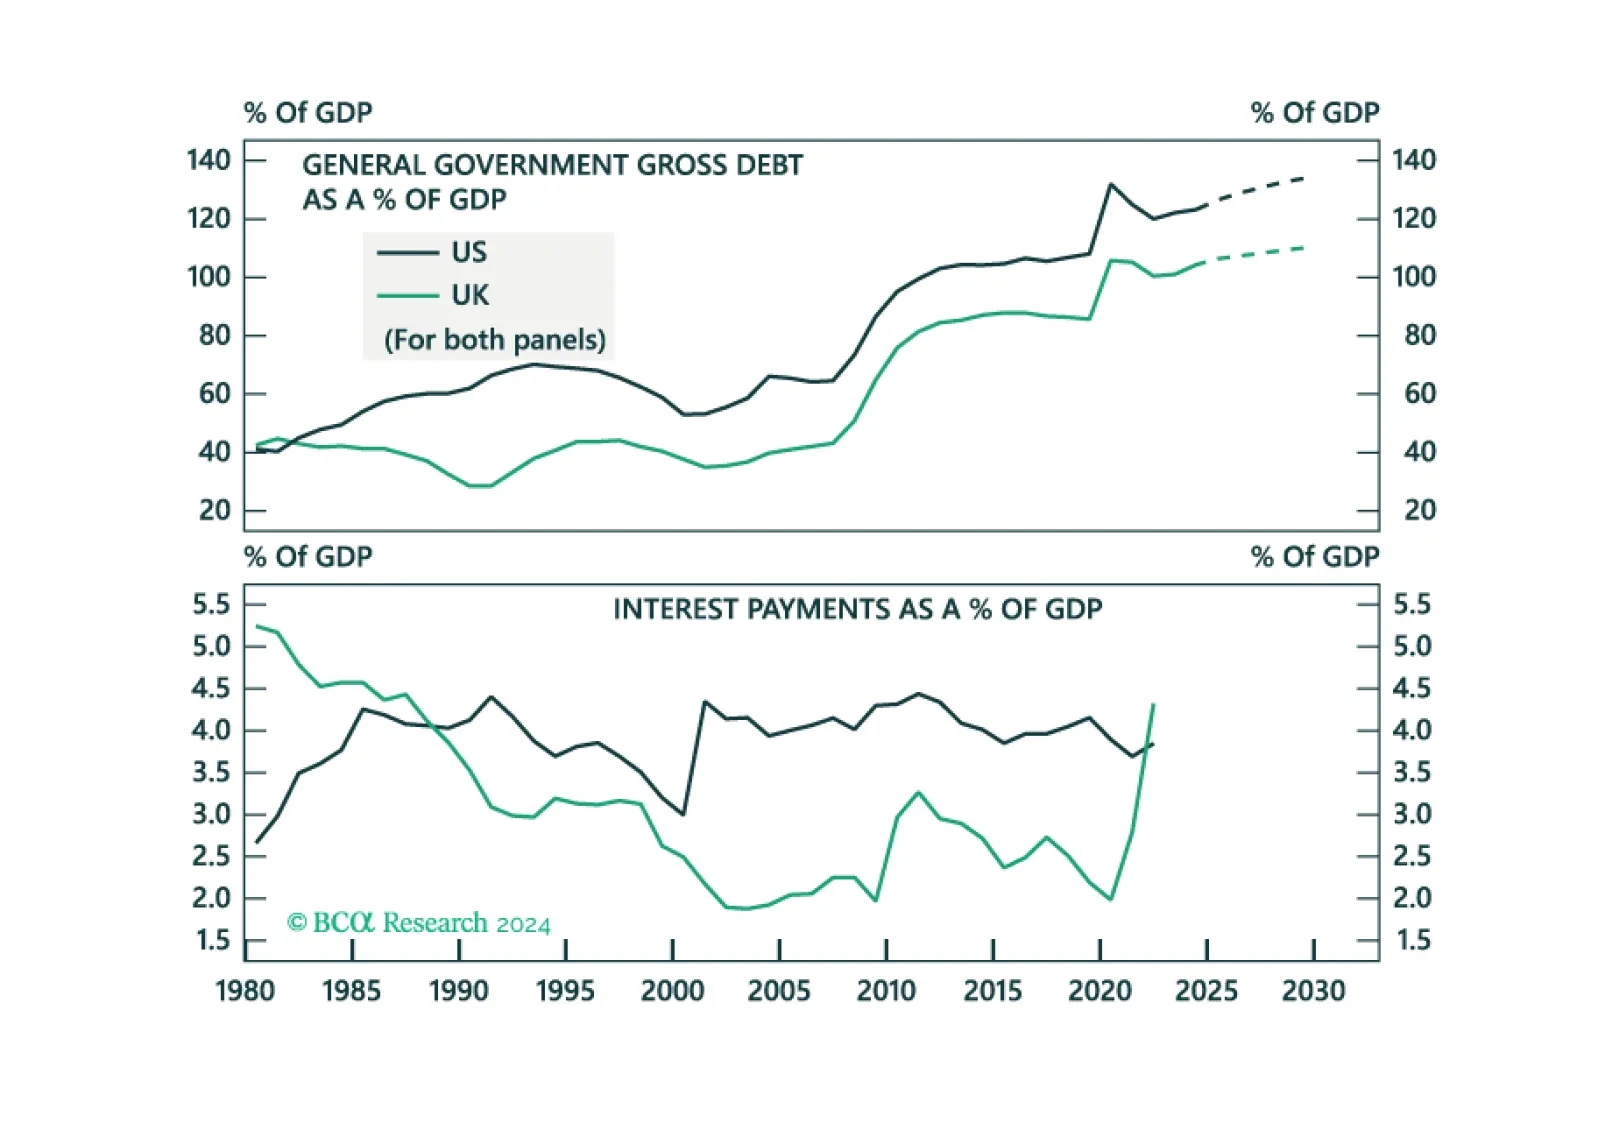
In this Insight, we assess whether investors should expect fiscal turbulence in the UK, that will drive UK yields higher and the pound lower.
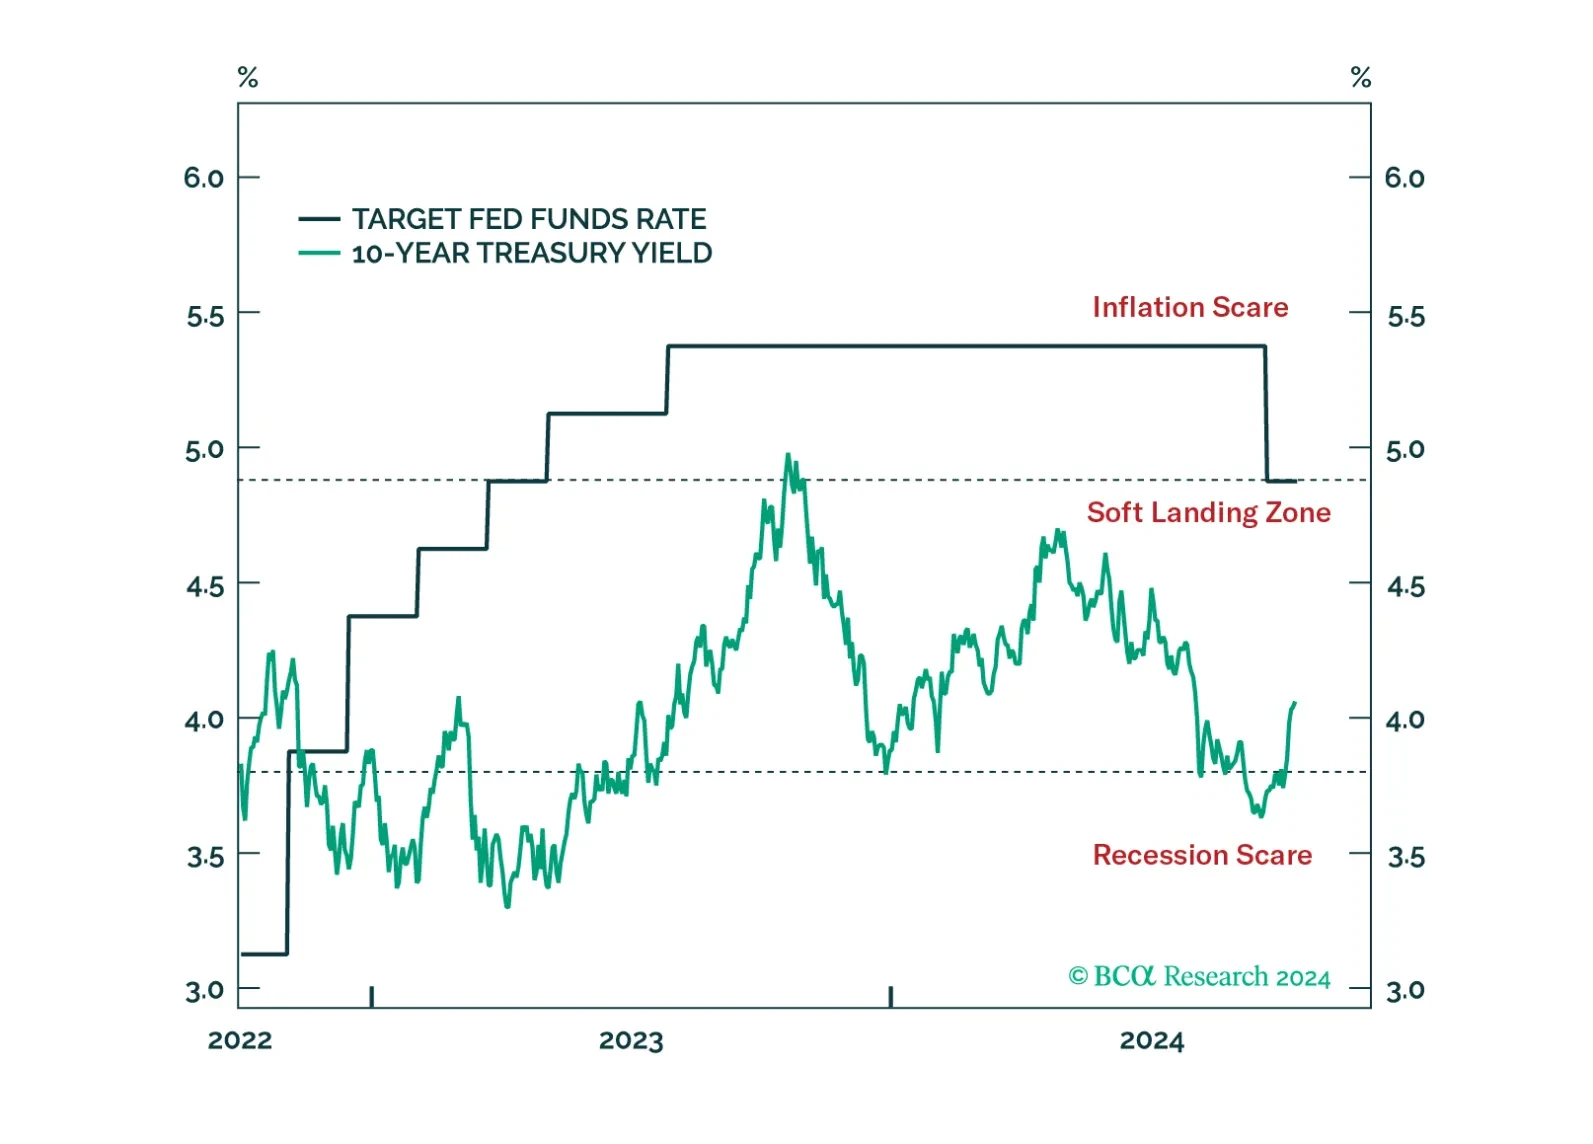
We give our thoughts on this morning’s CPI release and (lack of) market reaction. We also close our short position in January 2025 fed funds futures.
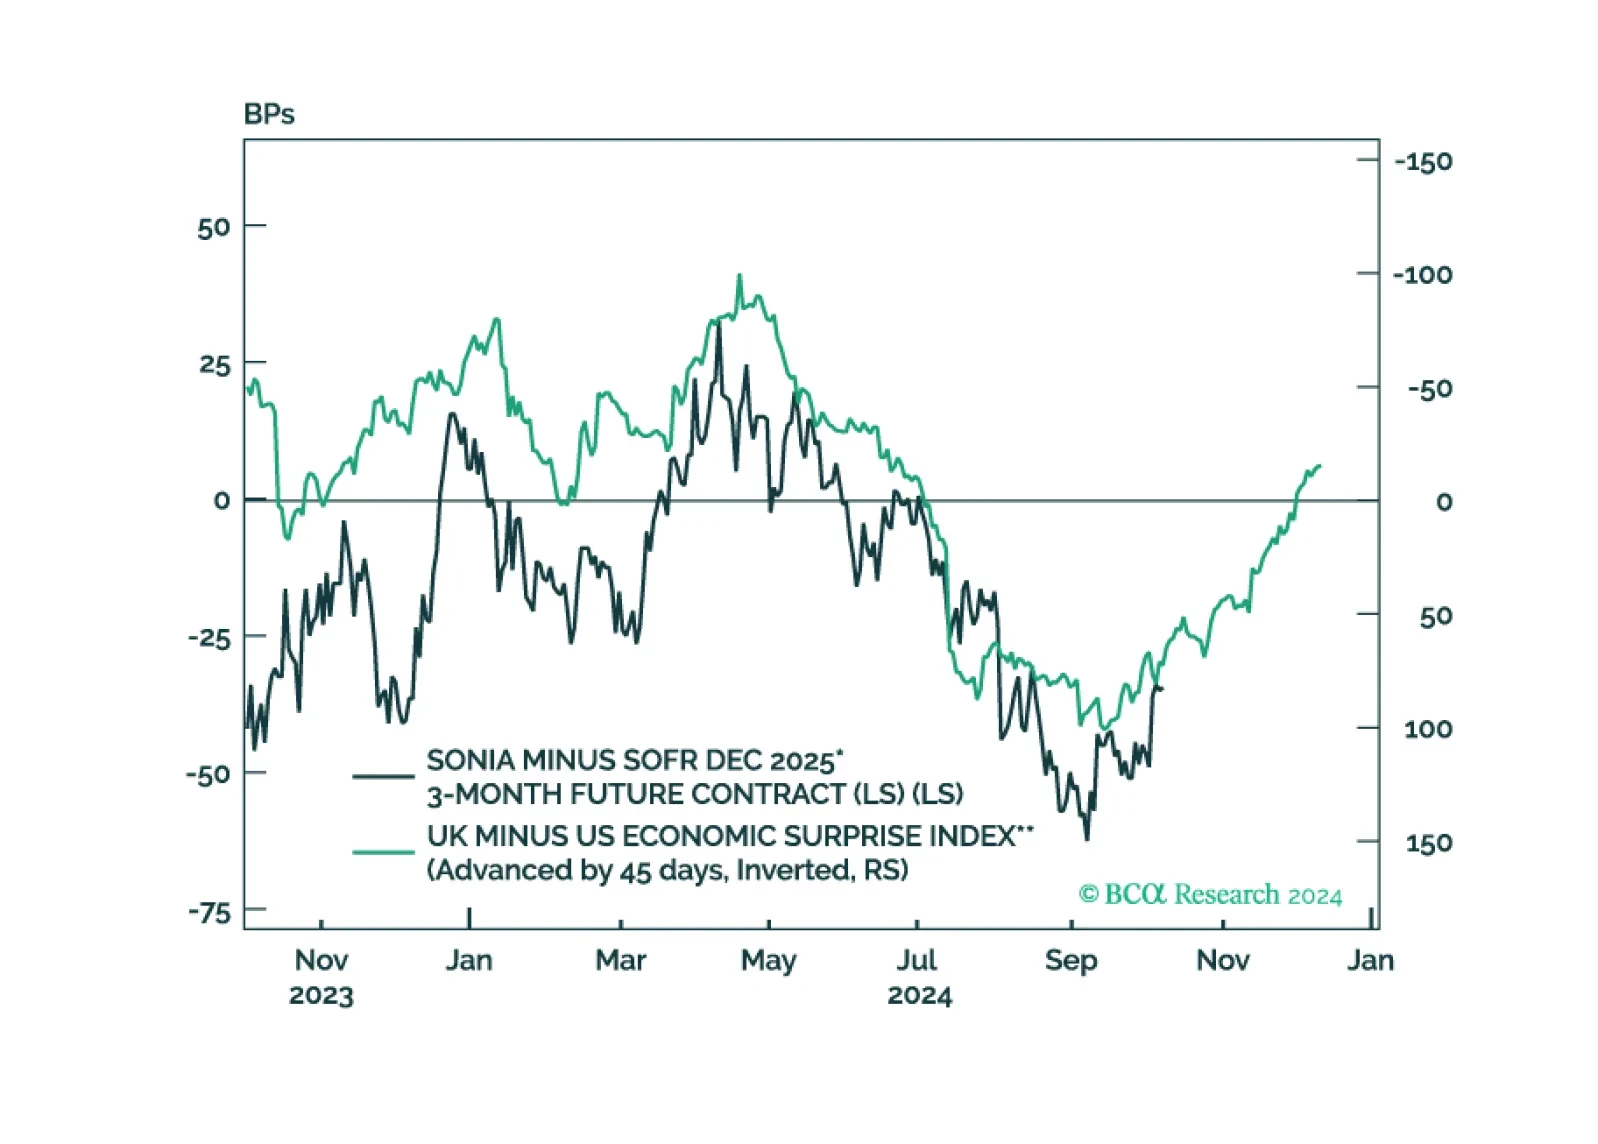
Our Q3 portfolio was defensive, which we believe will be the appropriate stance in the next six-to-twelve months. Data coming out of the US has remained robust which could cause US bond yields to temporarily overshoot. An overshoot in US bond yields will be an opportunity to dial up the portfolio’s defensive tilt. The average decline in 10-year Treasury yields 12 months after the first Fed rate cut is 100 bps. This time should be no different. There are not many changes to this quarter’s portfolio allocation. We have upgraded UK gilts to overweight and downgraded European credit to underweight. Portfolio duration remains the same. In terms of future changes, we are generally watching the trend in inflation given many central banks are delivering jumbo rate cuts. Any pause in the disinflationary trend we have seen will send bond yields soaring. This is a risk to our view. Otherwise, a recession in the first half of 2025 will cement our long duration stance.