Skip to main content

FICC

| Bonds

Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
Explore FICC
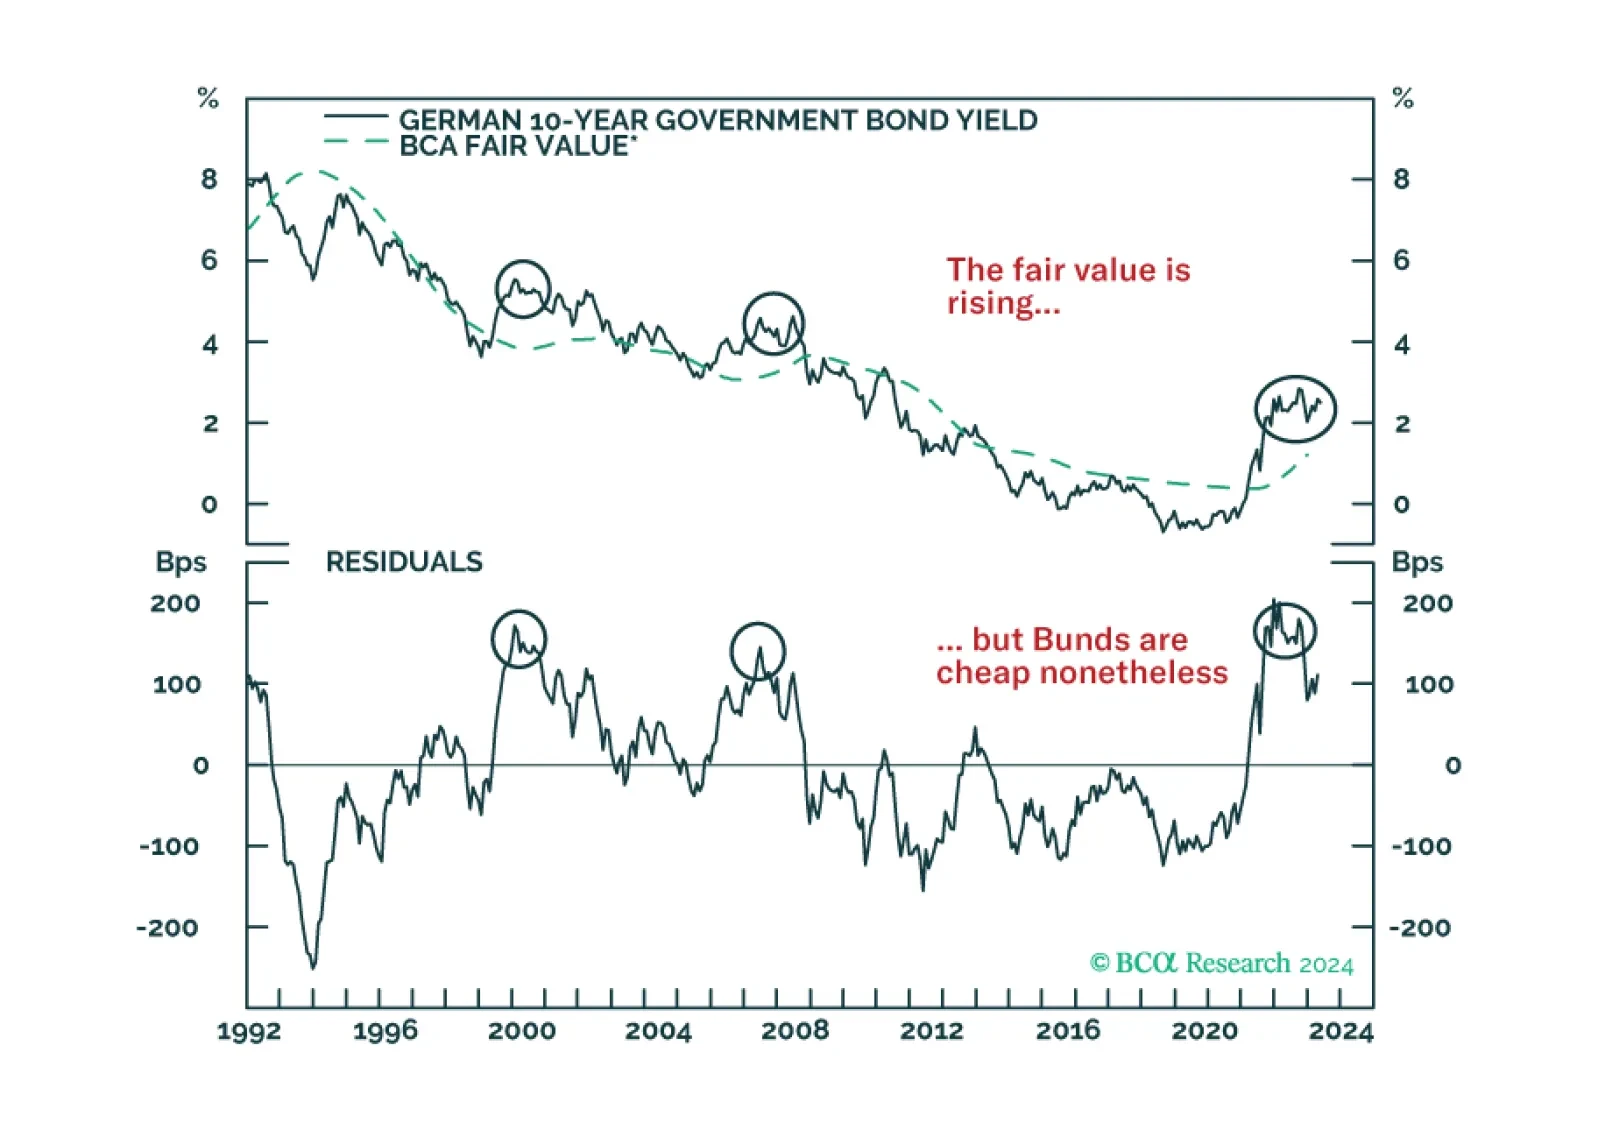
German Bunds have cheapened considerably, and the ECB is about to start cutting rates. Does this combination guarantee immediate profits from buying these bonds?
In this report, we review our trade recommendations based on incoming data in the last month.
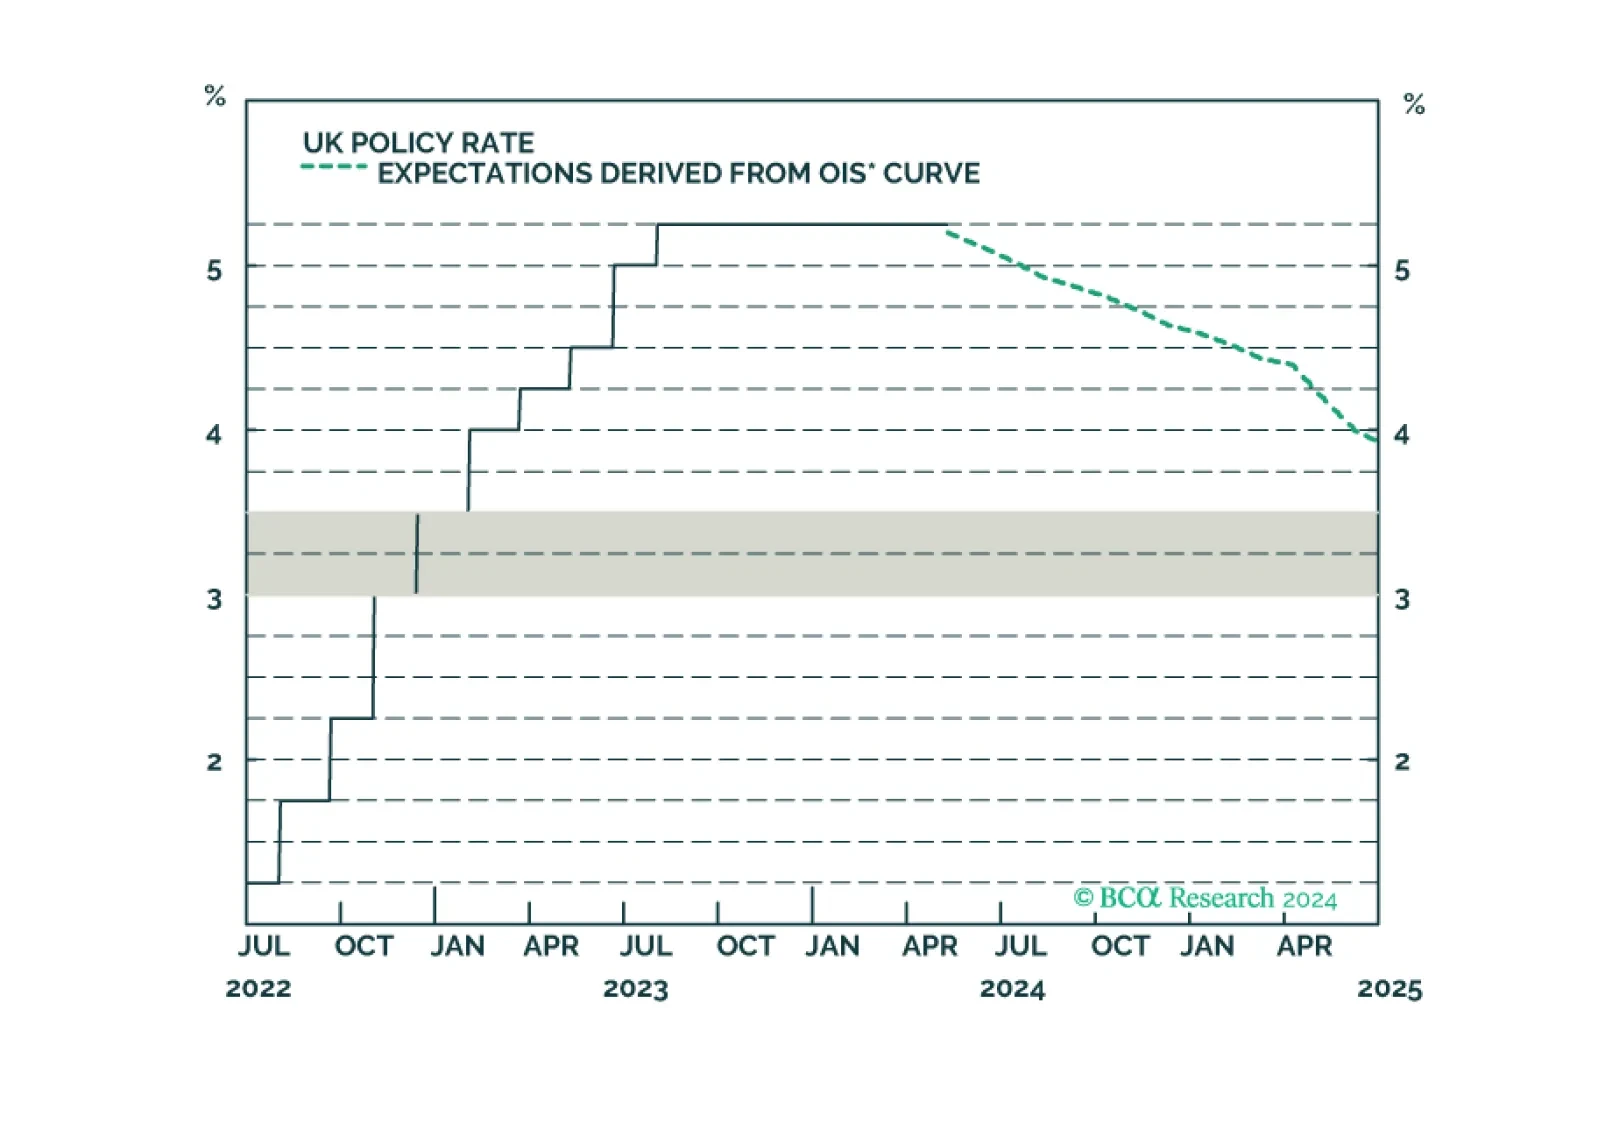
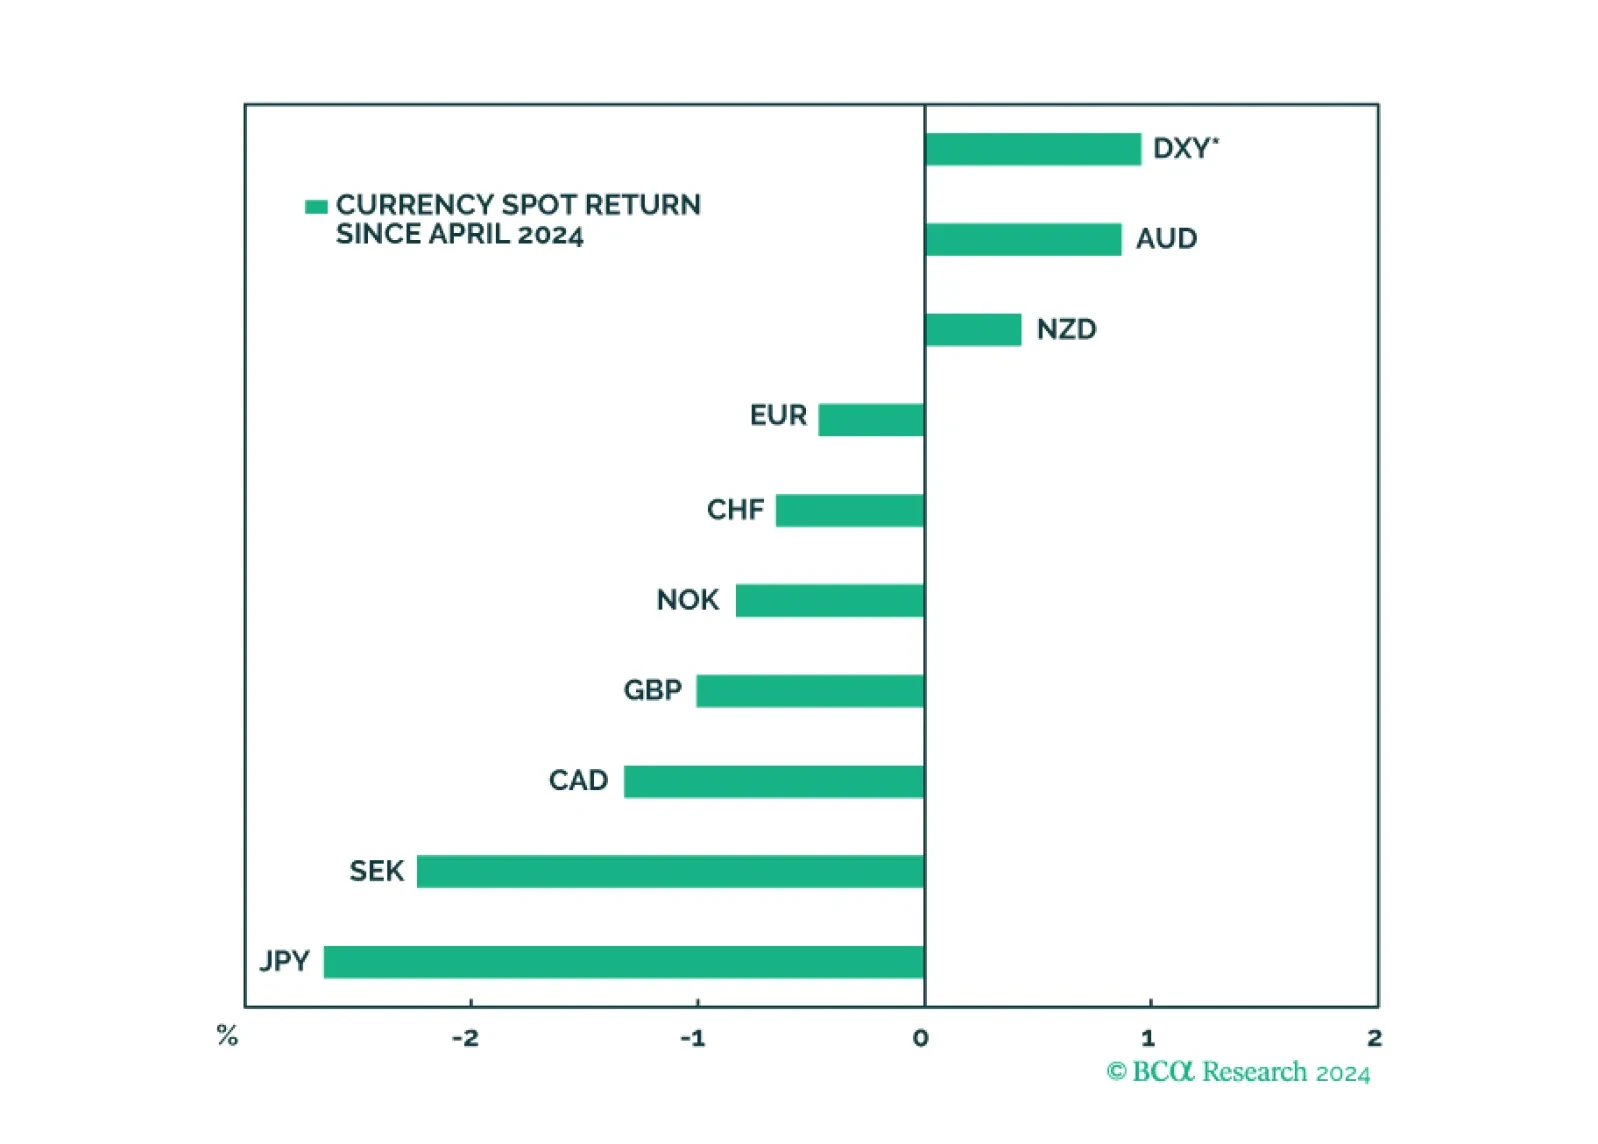
An update to our views on UK rates and currency following today’s Bank of England meeting.
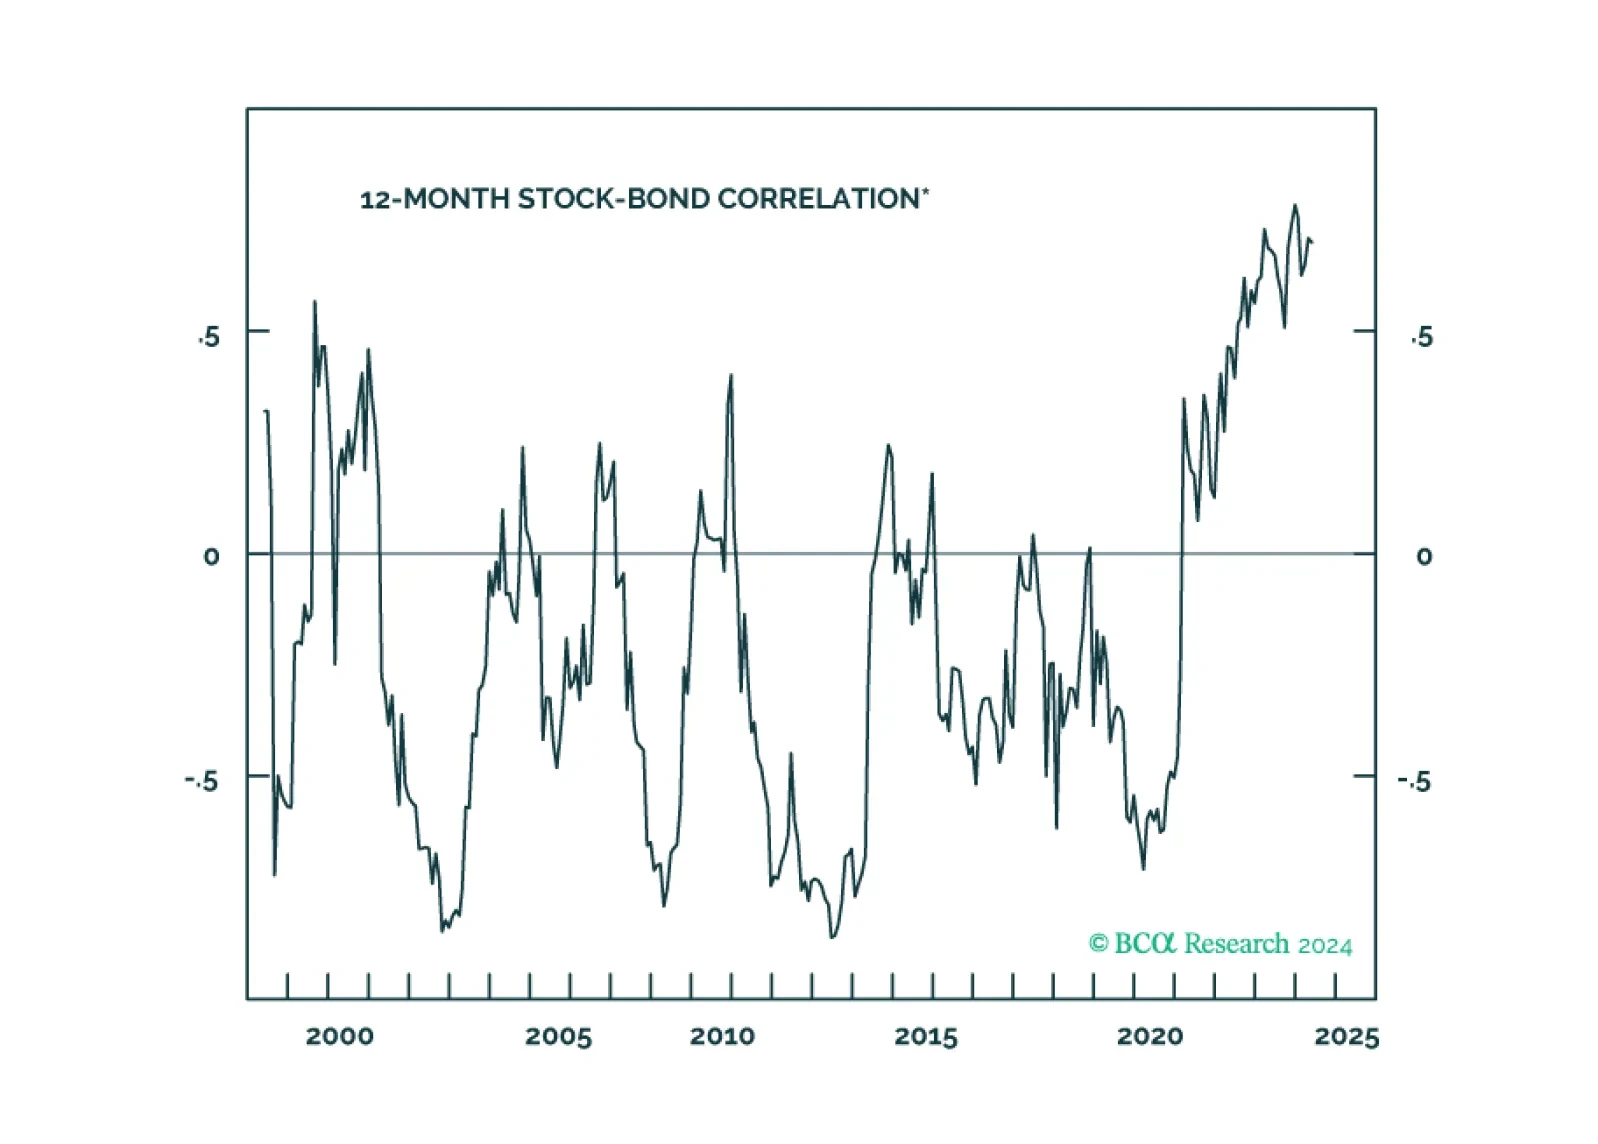
Our Portfolio Allocation Summary for May 2024.
Some thoughts on this morning’s employment report and recent trends in US economic data.
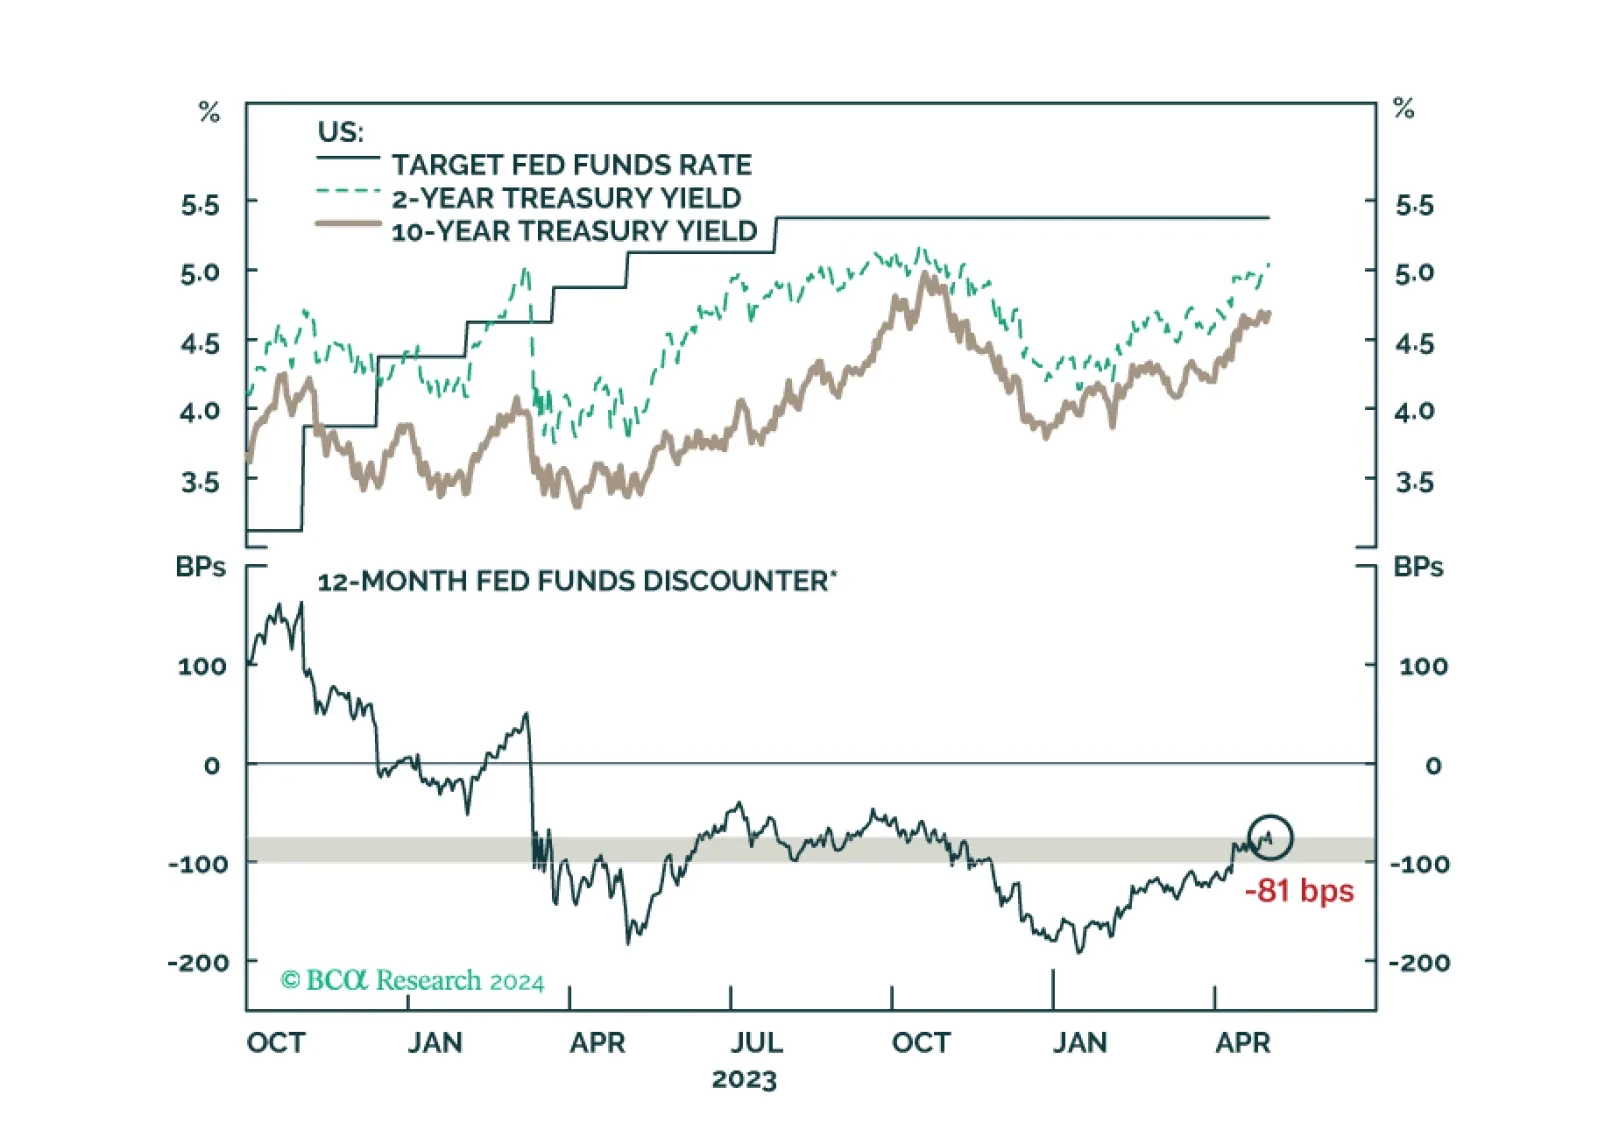
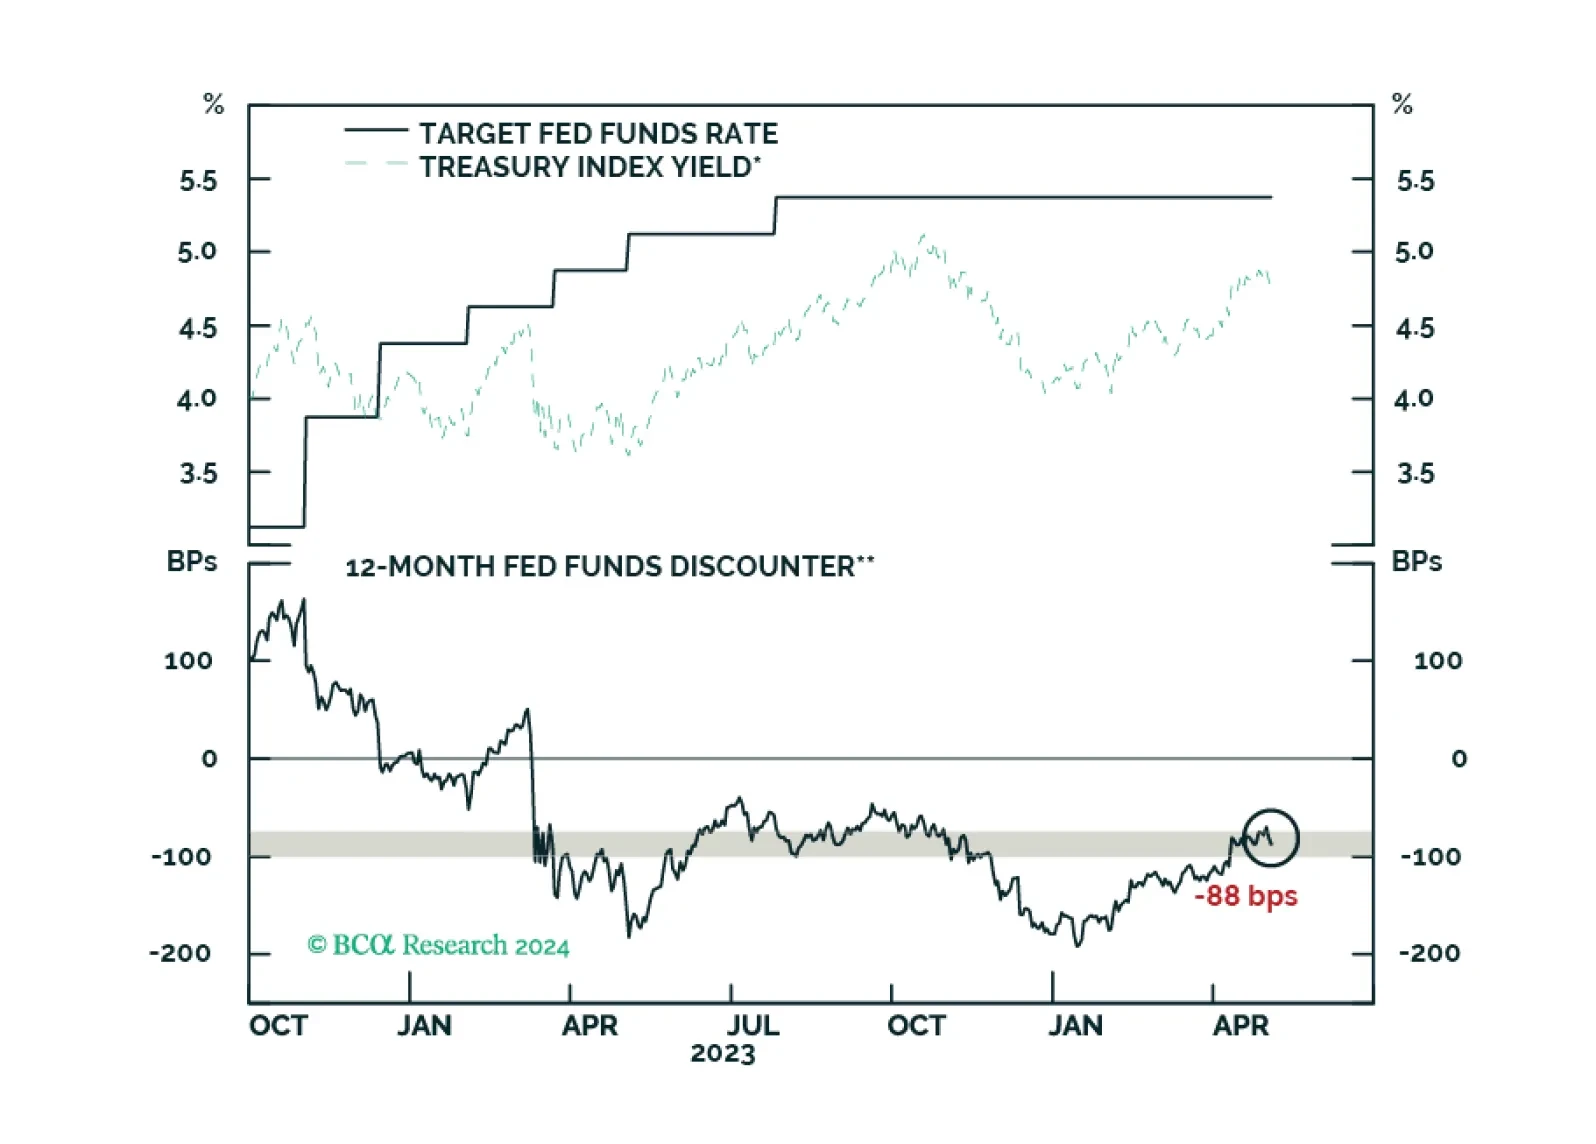
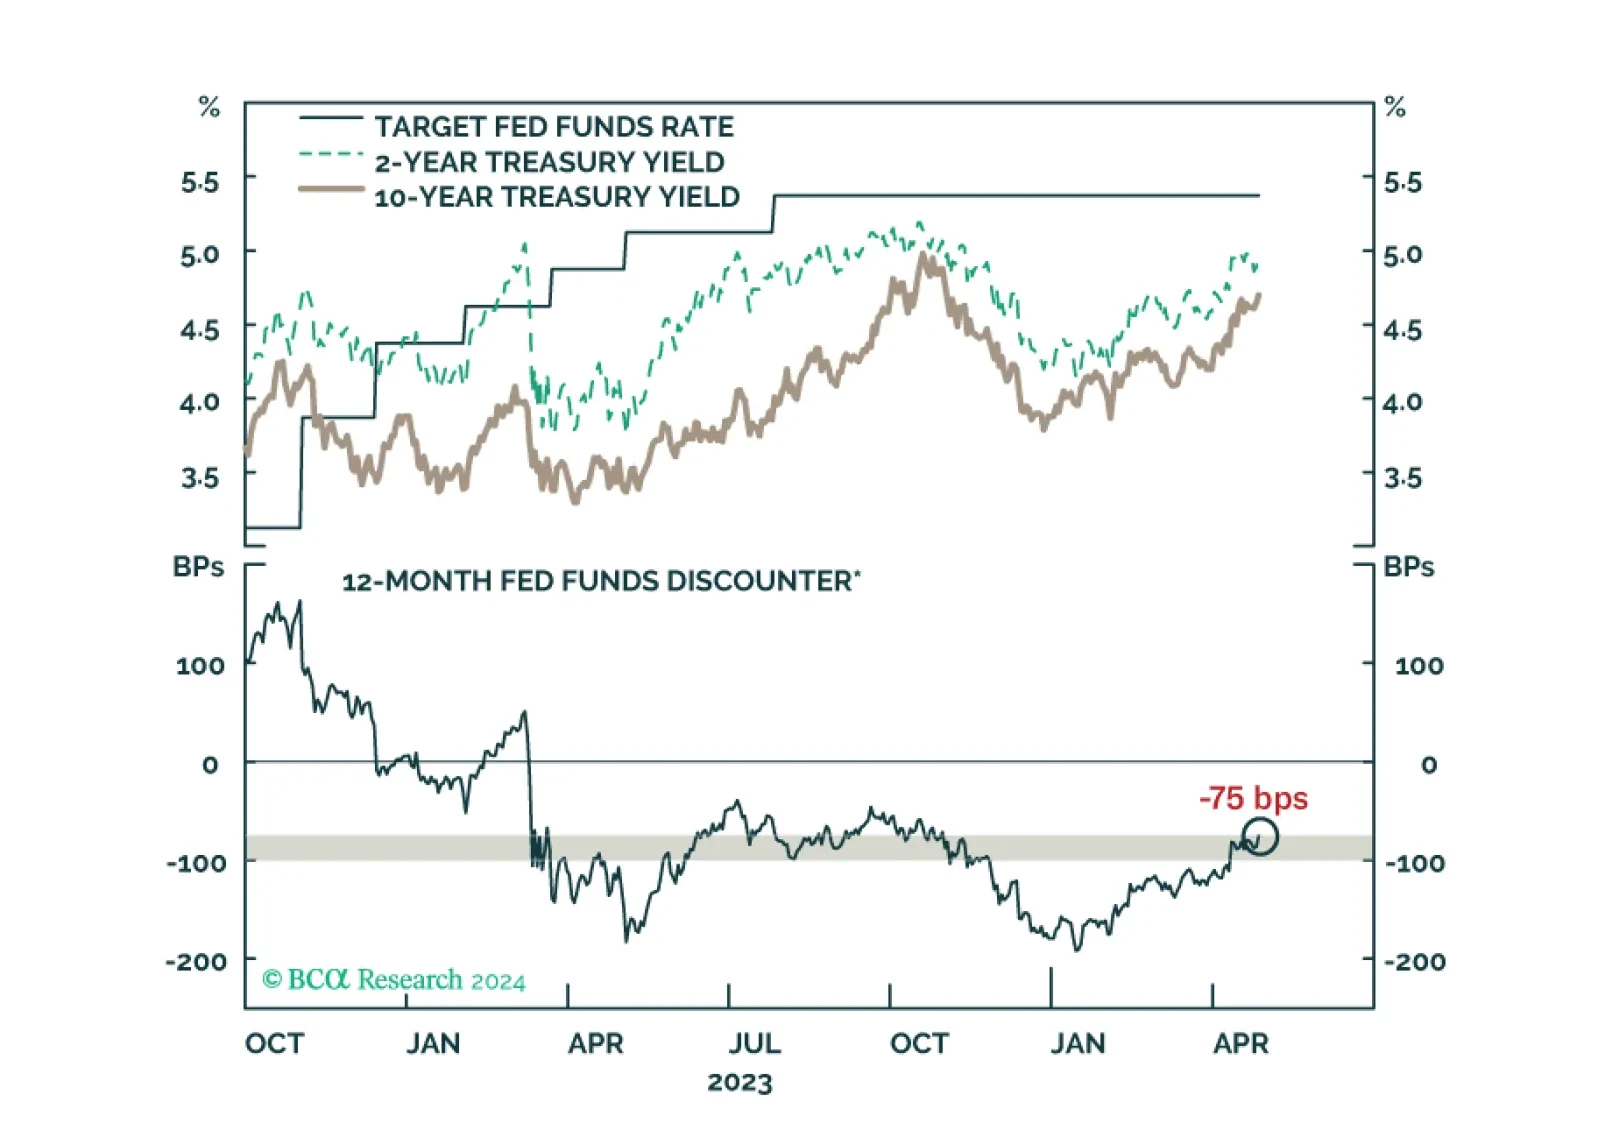
Updated views on US Treasury yields and the dollar following today’s FOMC meeting.
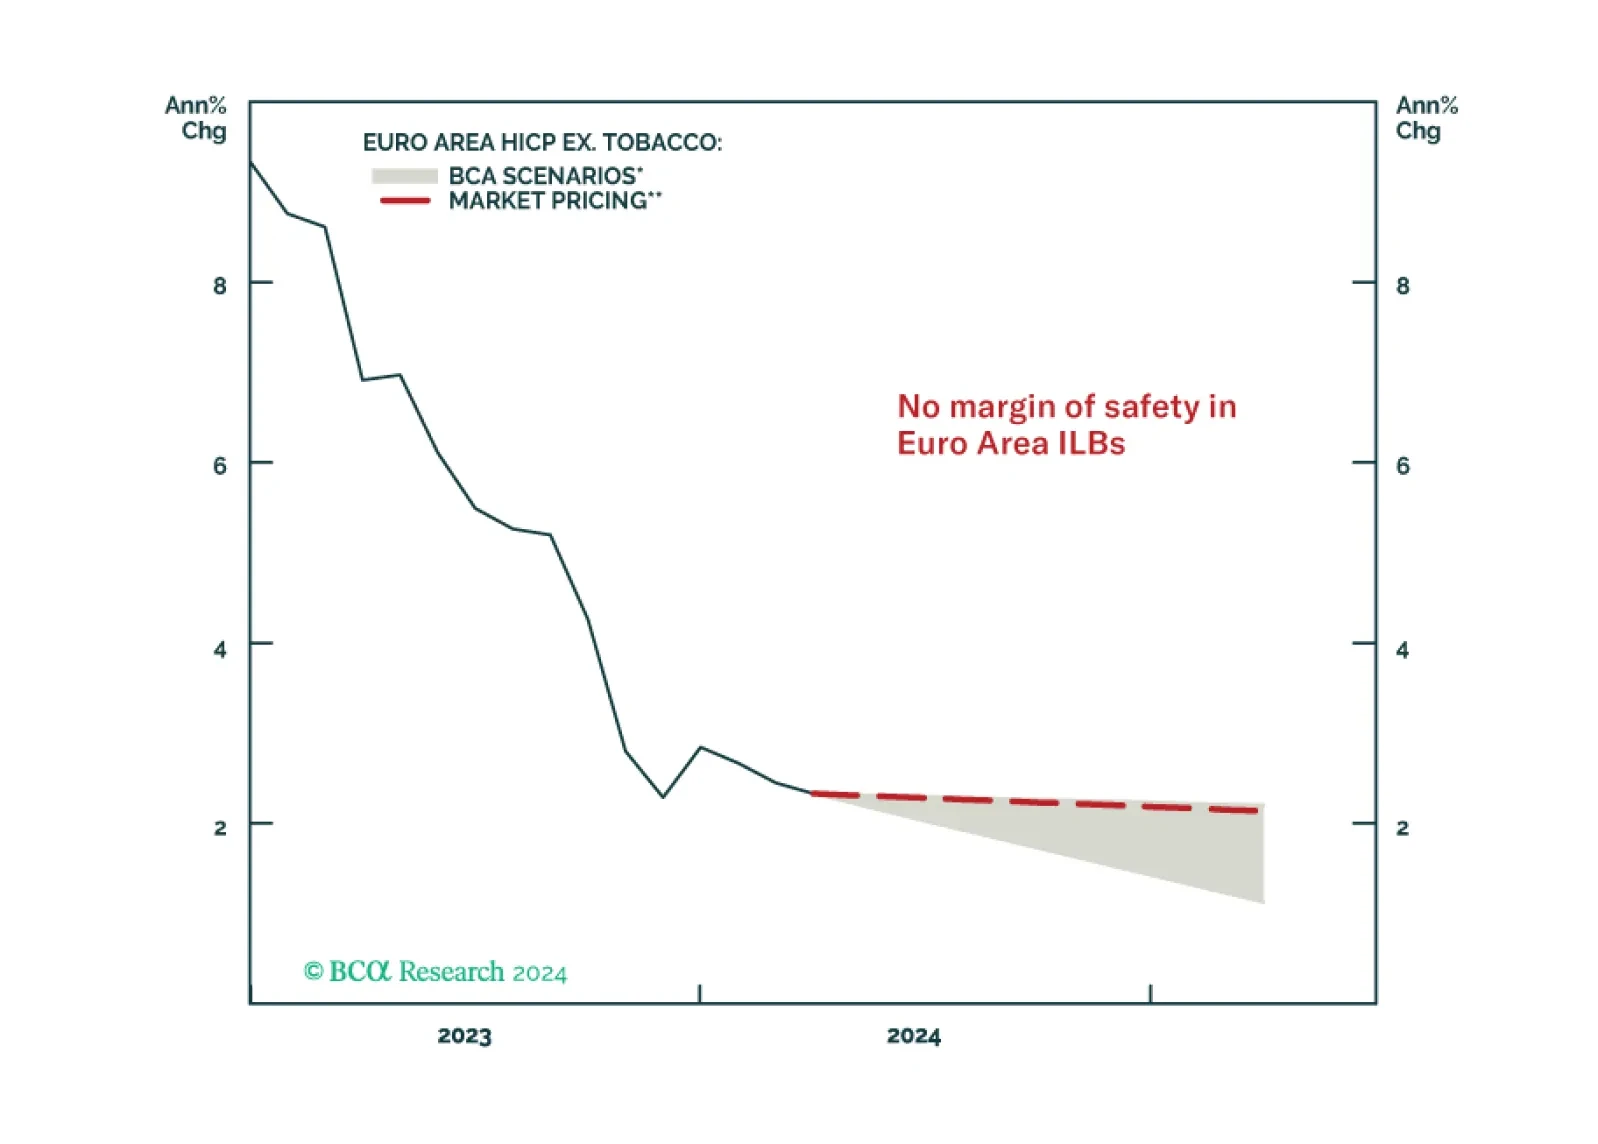
Special Report In this Special Report, we introduce our Euro Inflation-Linked Golden Rule – a framework to profitably trade and invest in Euro Area inflation-linked bonds versus nominals. The Rule is currently signaling that nominal government bonds should outperform inflation-linked bonds over the next year as disinflation in the Euro Area continues.
Our latest views on the recent increase in Treasury yields and some key things to watch at next week’s FOMC meeting.
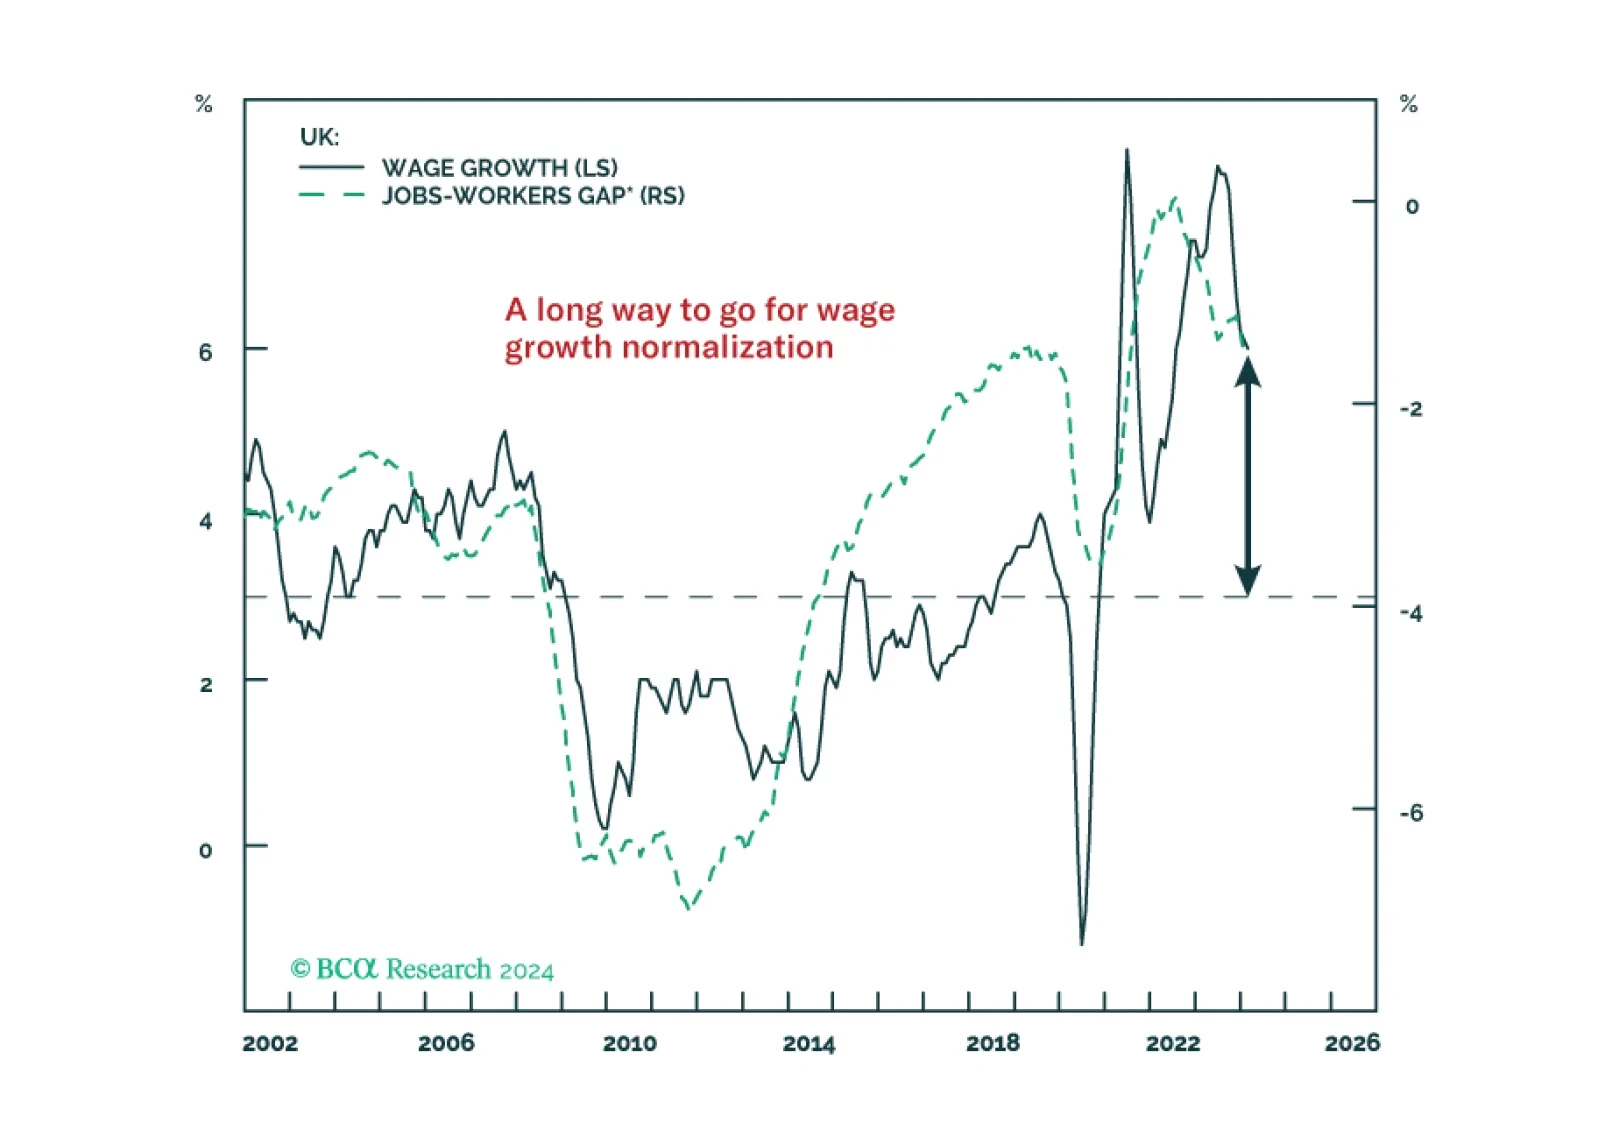
Special Report The UK labor market remains far too tight to expect wage growth to slow to levels consistent with the Bank of England inflation target. A true recession with rising unemployment is needed to finally slay the UK inflation beast. 2024 rate cuts are off the table, with the central bank having to keep monetary policy tighter for longer than markets expect and the UK economy now rebounding. We recommend downgrading UK gilts to underweight in global bond portfolios, while also looking for opportunities to buy the British pound on pullbacks versus the euro, Canadian dollar and Swedish krona.
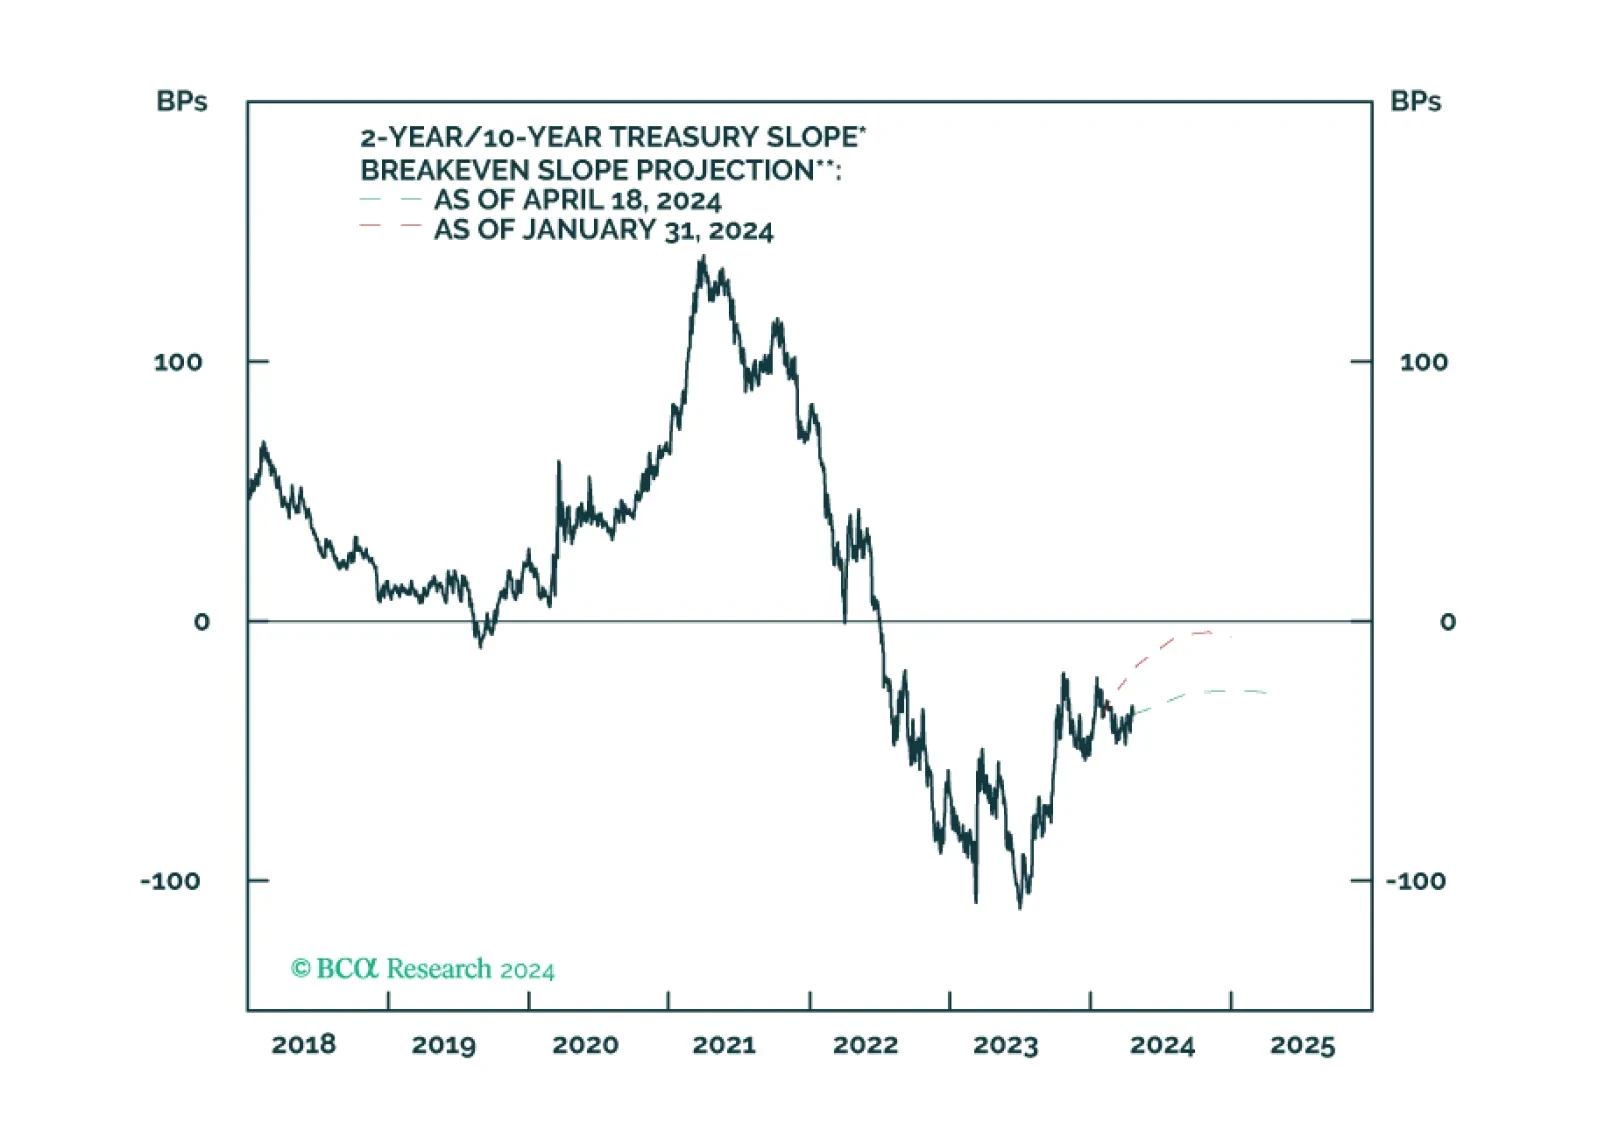
Special Report This Special Report introduces a framework for assessing the relative importance of slope change and initial yield in curve trade performance. The yield penalty for curve steepeners has fallen significantly since the beginning of the year, and we recommend shifting out of Treasury curve flatteners and into Treasury curve steepeners in US bond portfolios.