 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
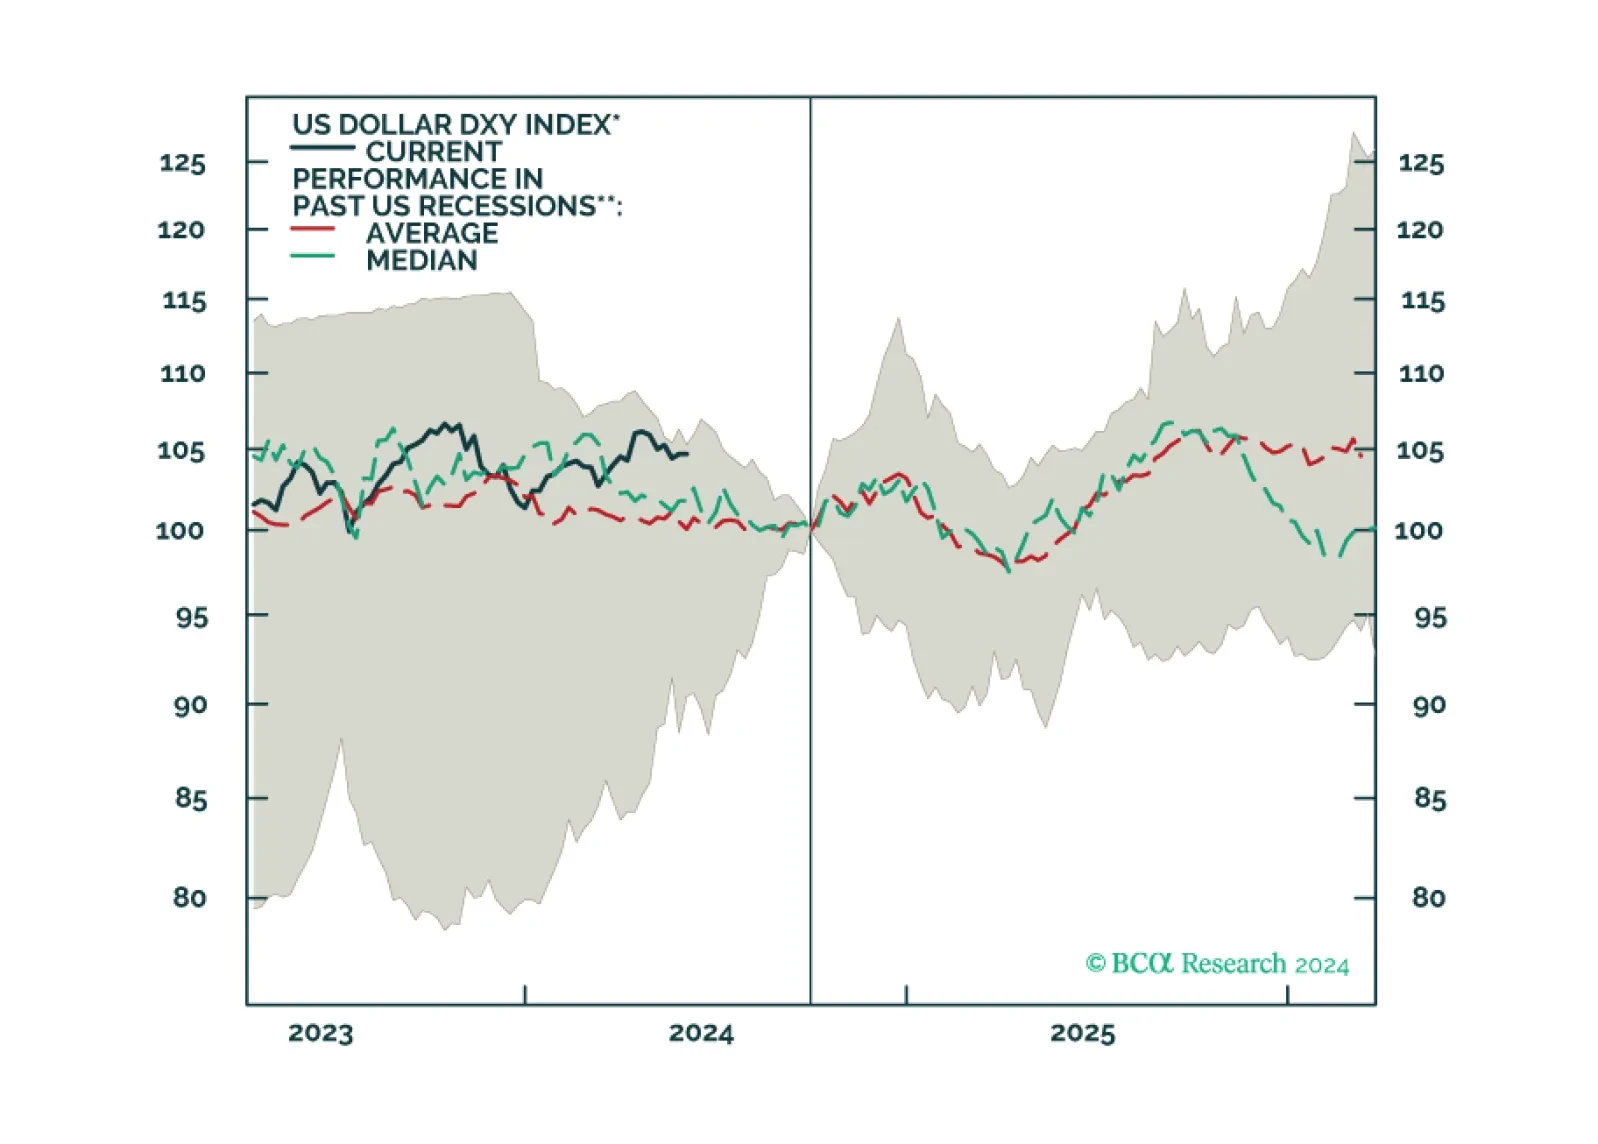
In this report, we gauge the outlook for the dollar given client visits in Africa.
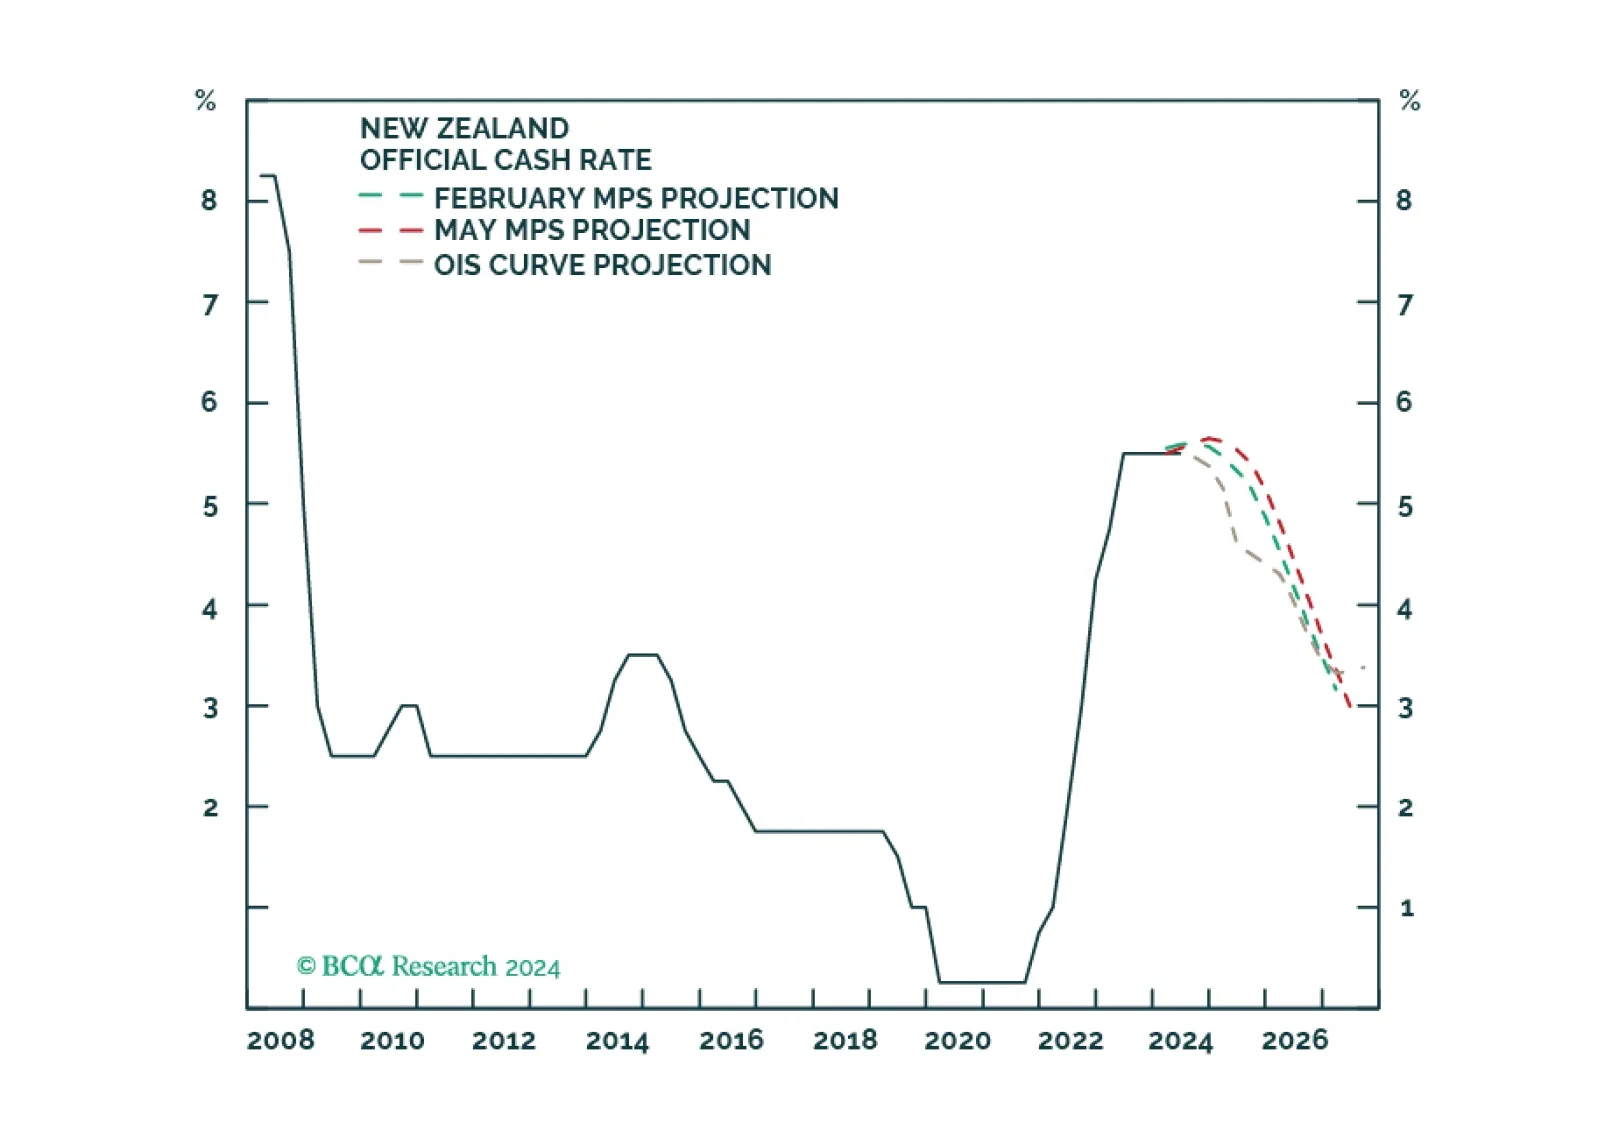
In this Insight, we revisit our "higher for longer" theme for the Reserve Bank of New Zealand, in light of the latest central bank meeting. In conclusion, we are inching towards a more dovish RBNZ ahead. Ergo, we recommend some fixed income and currency trades.
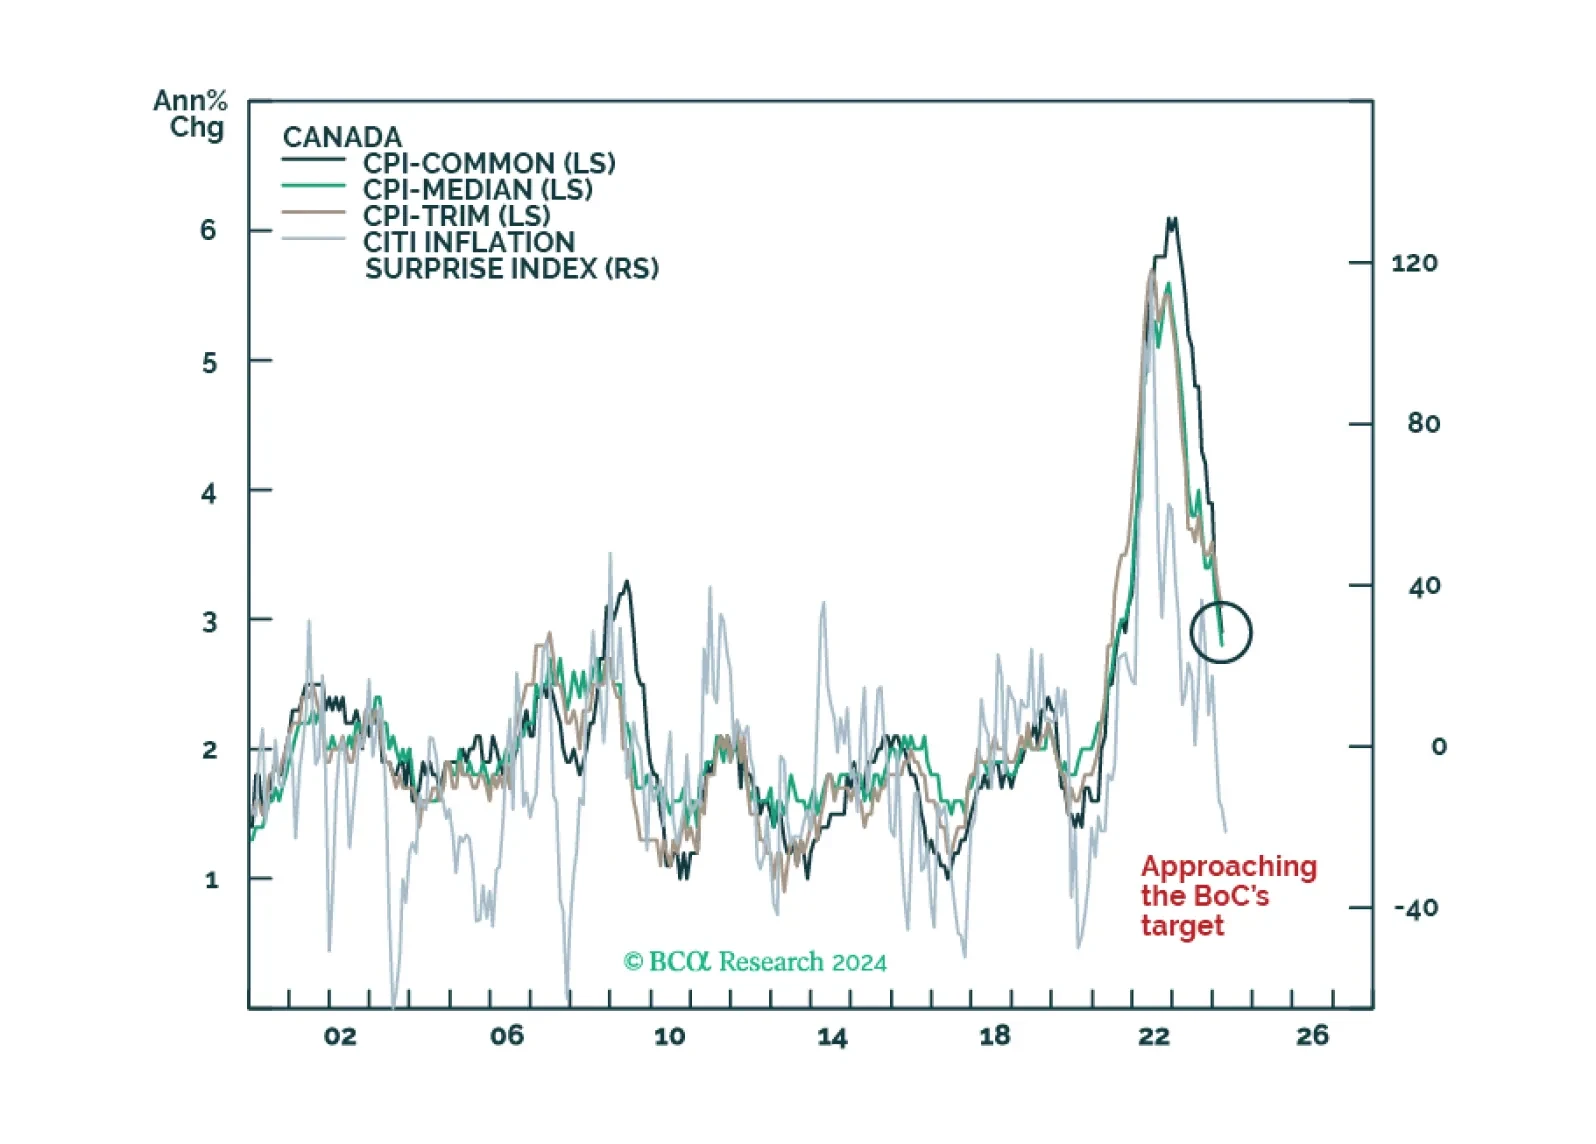
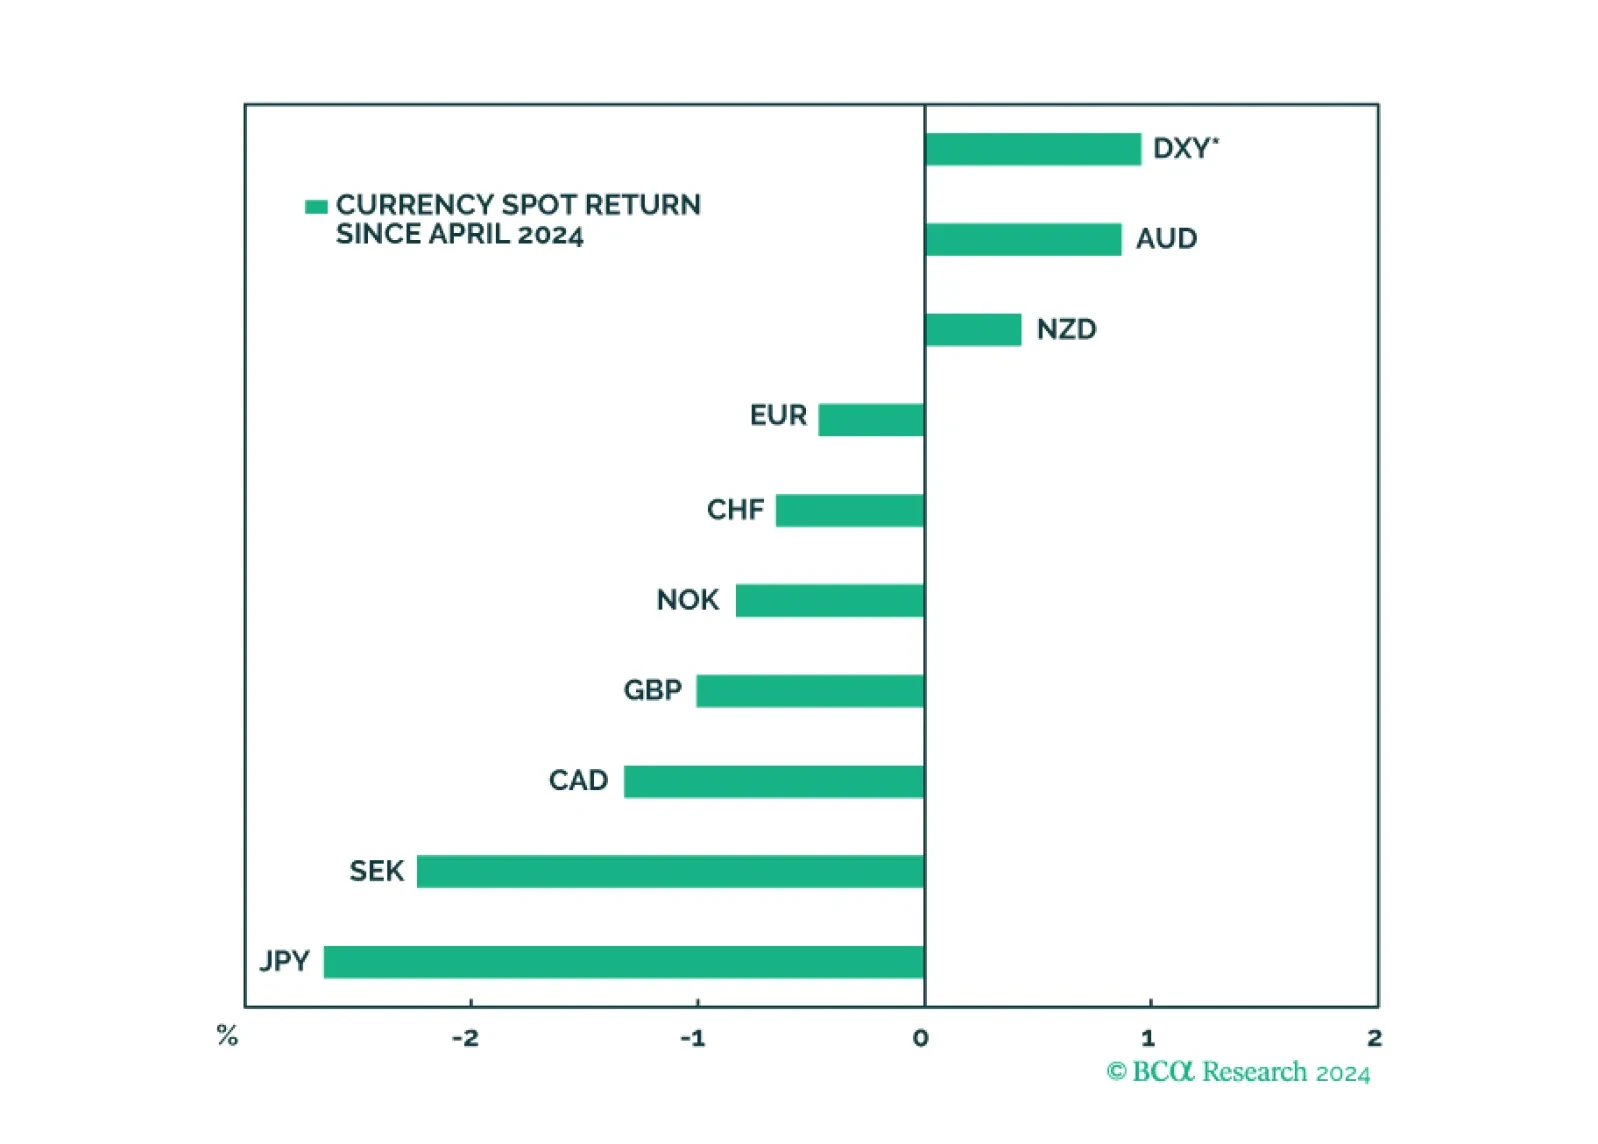
In this report, we review our trade recommendations based on incoming data in the last month.
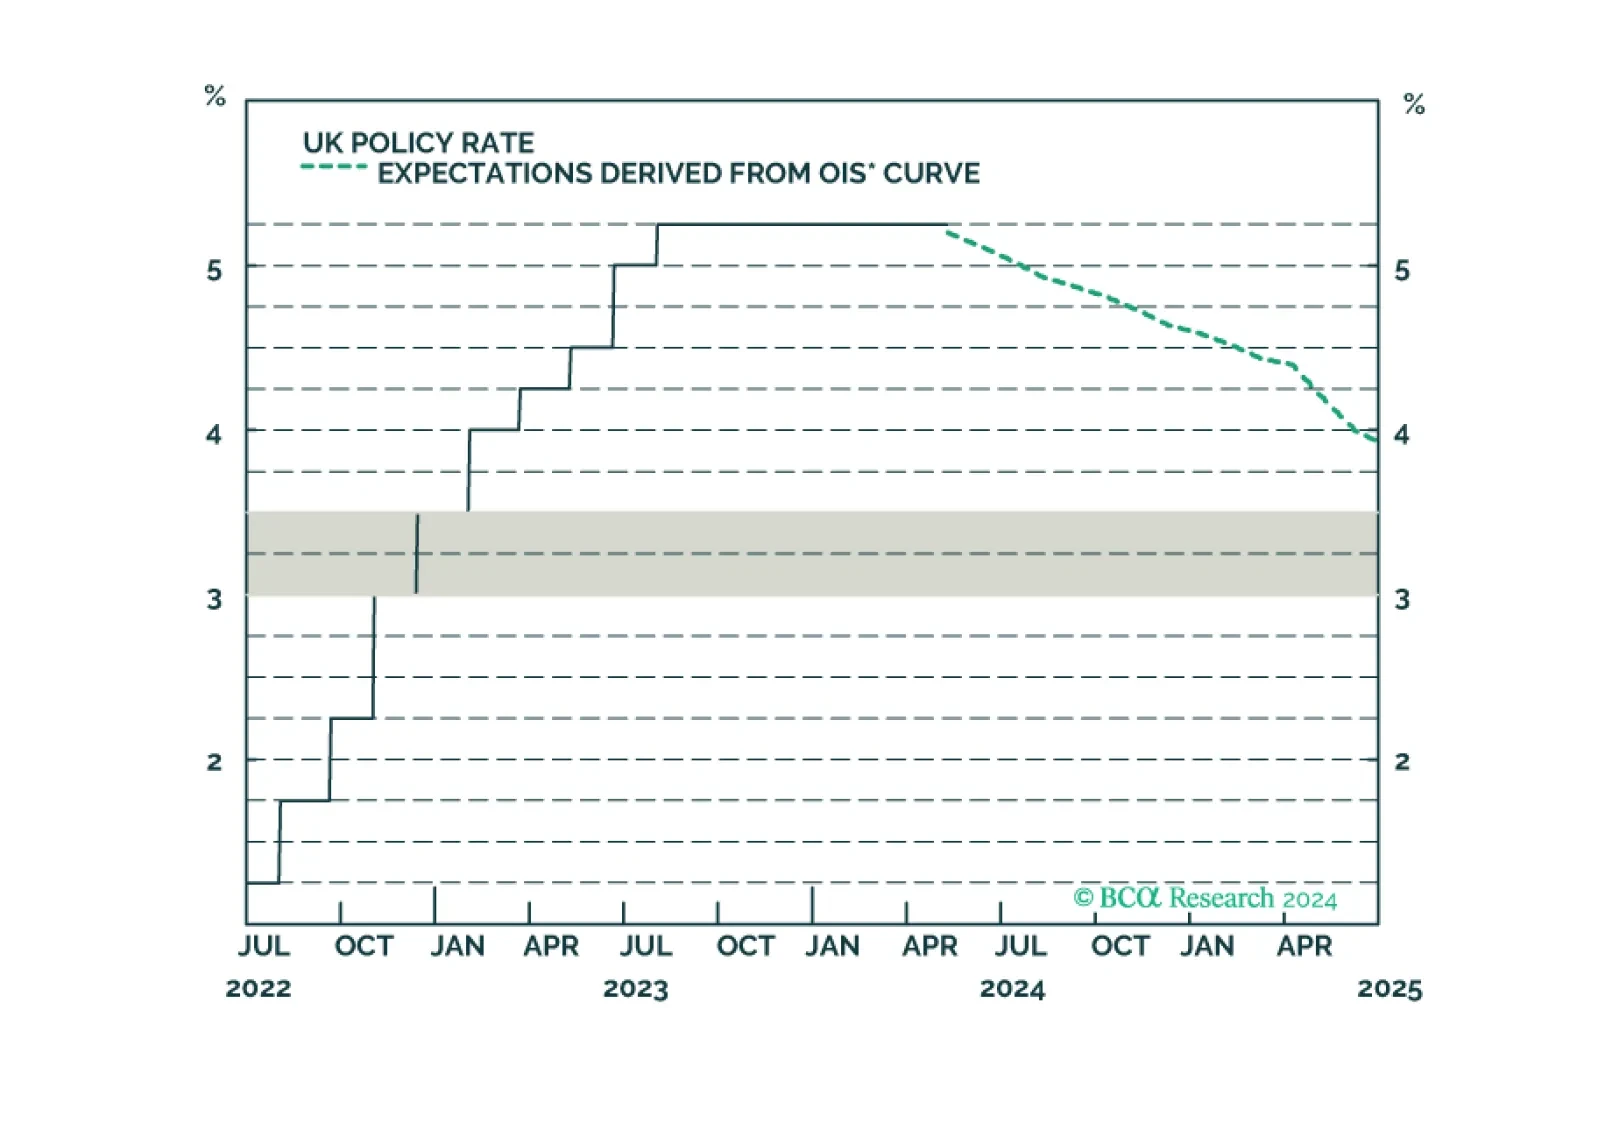
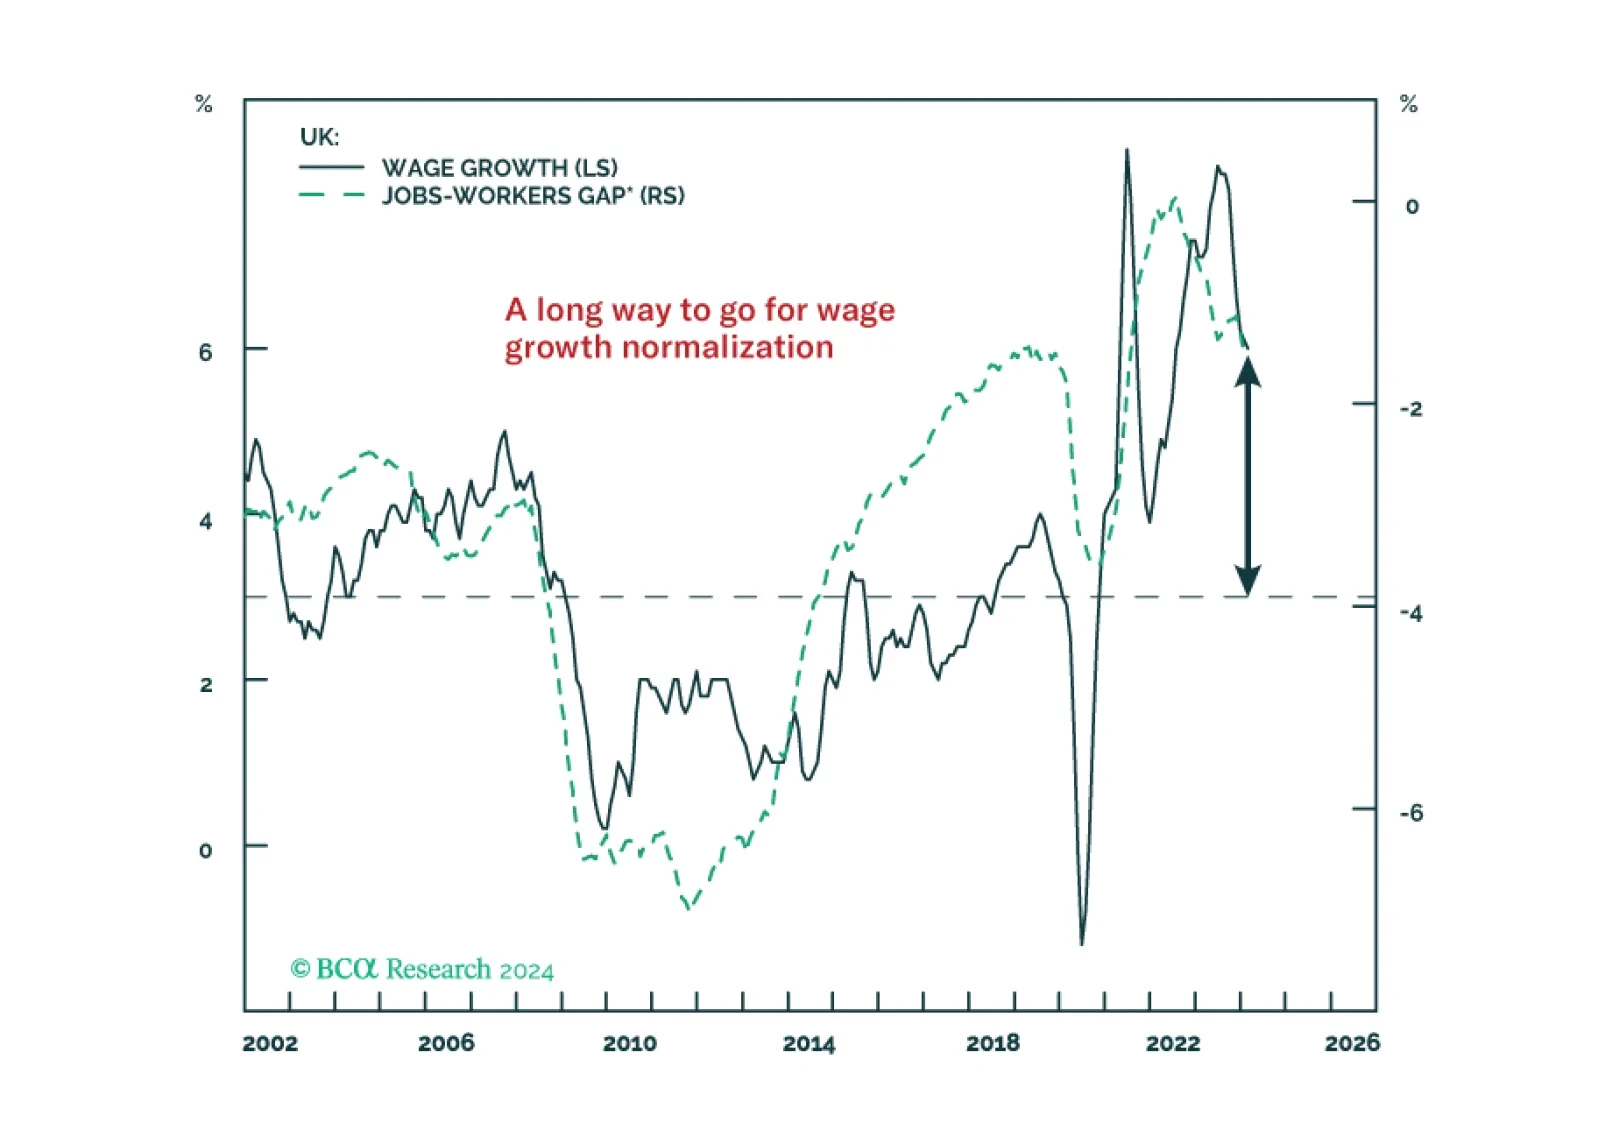
An update to our views on UK rates and currency following today’s Bank of England meeting.
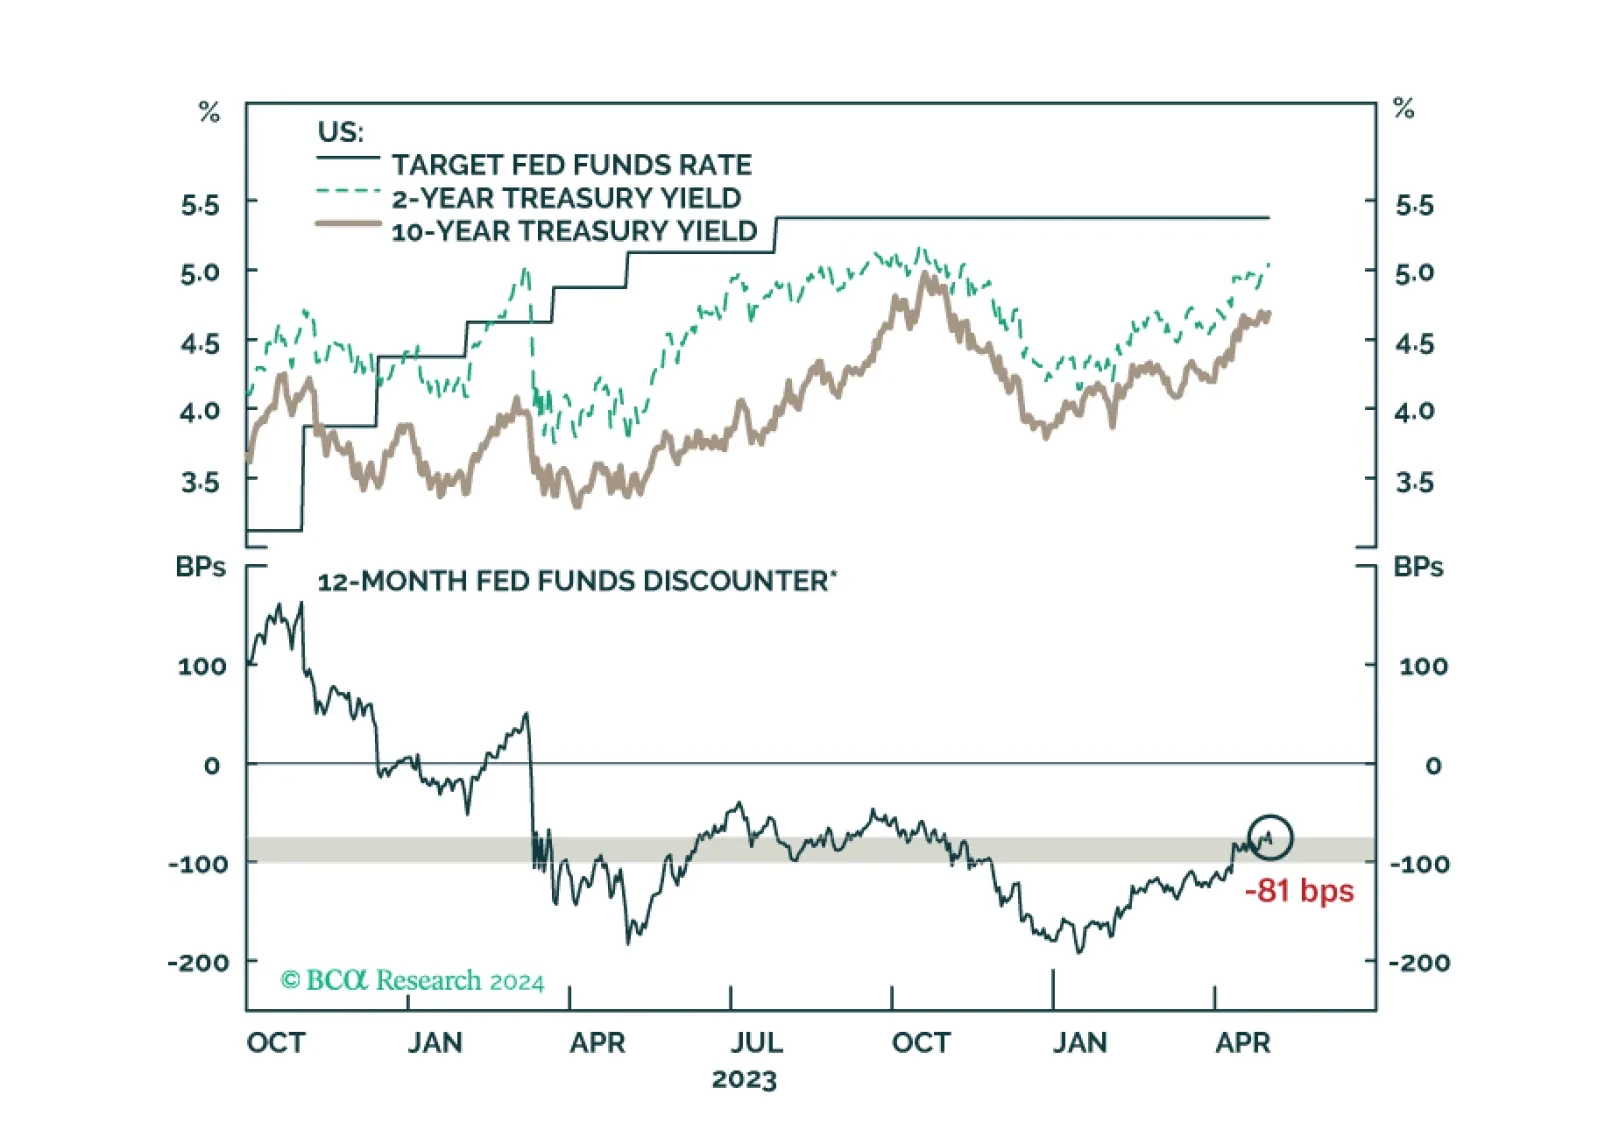
Updated views on US Treasury yields and the dollar following today’s FOMC meeting.
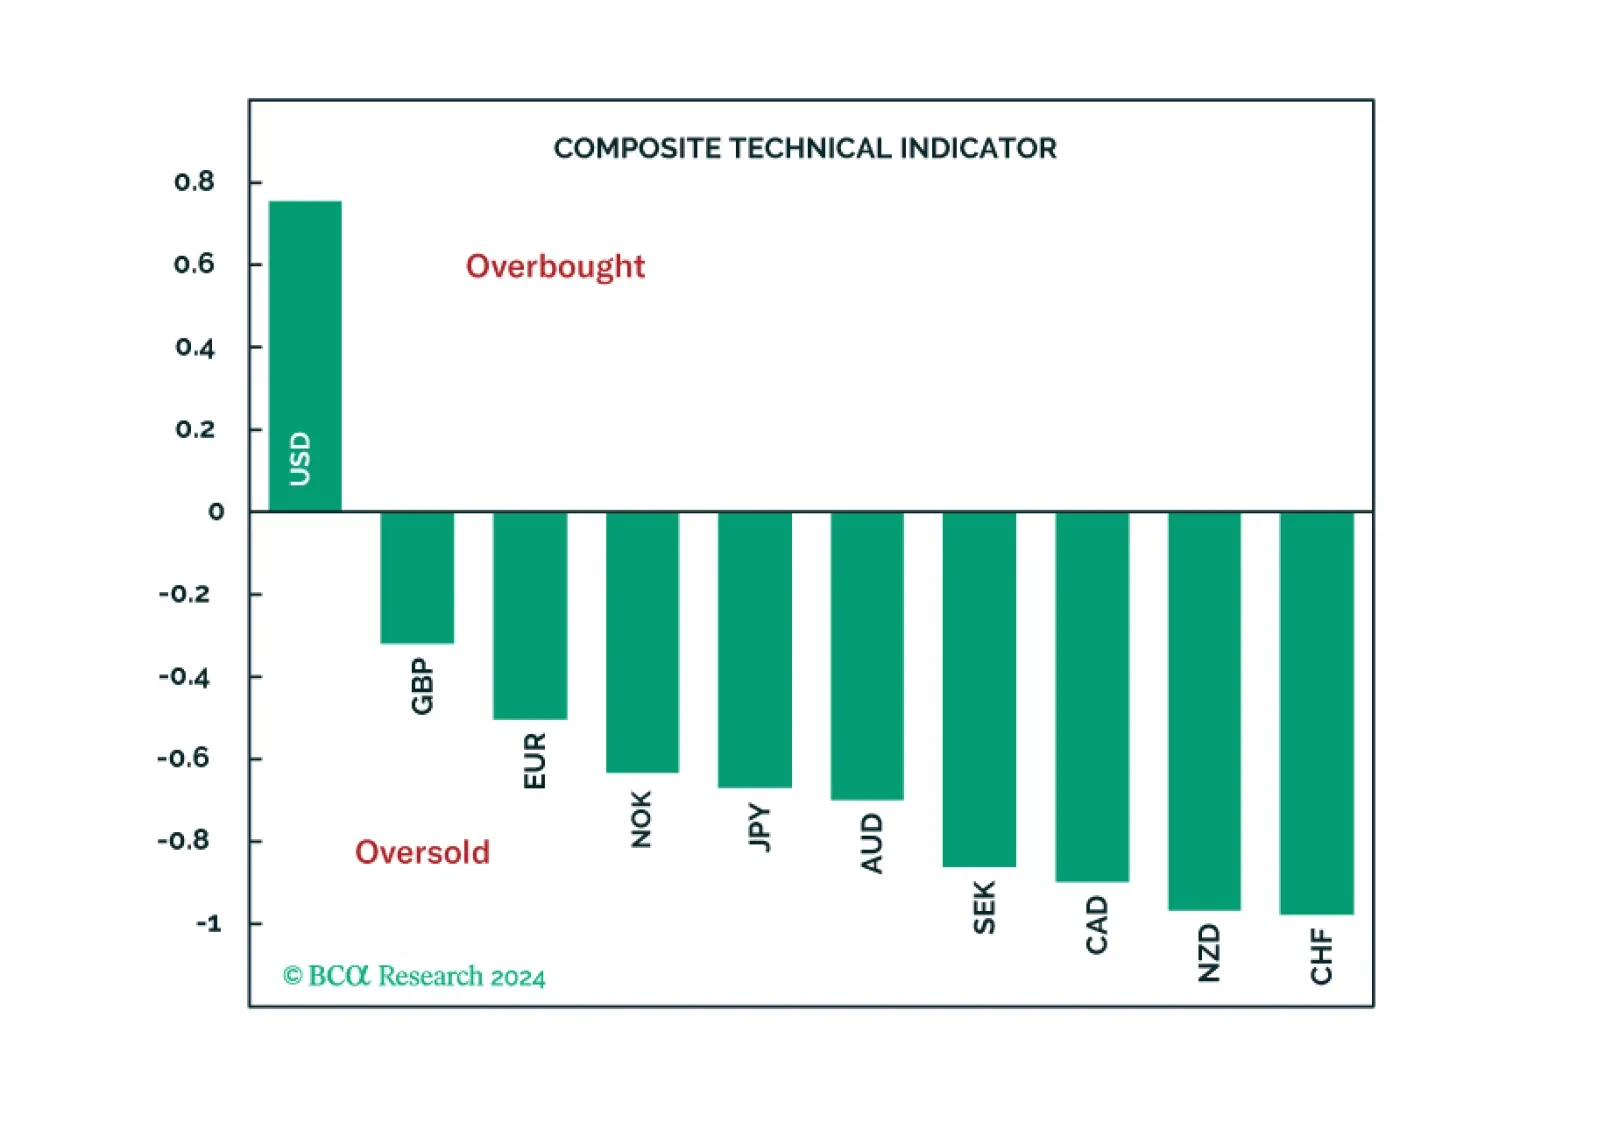
In this report, we review what our technical indicators are telling us about the G10 currencies.
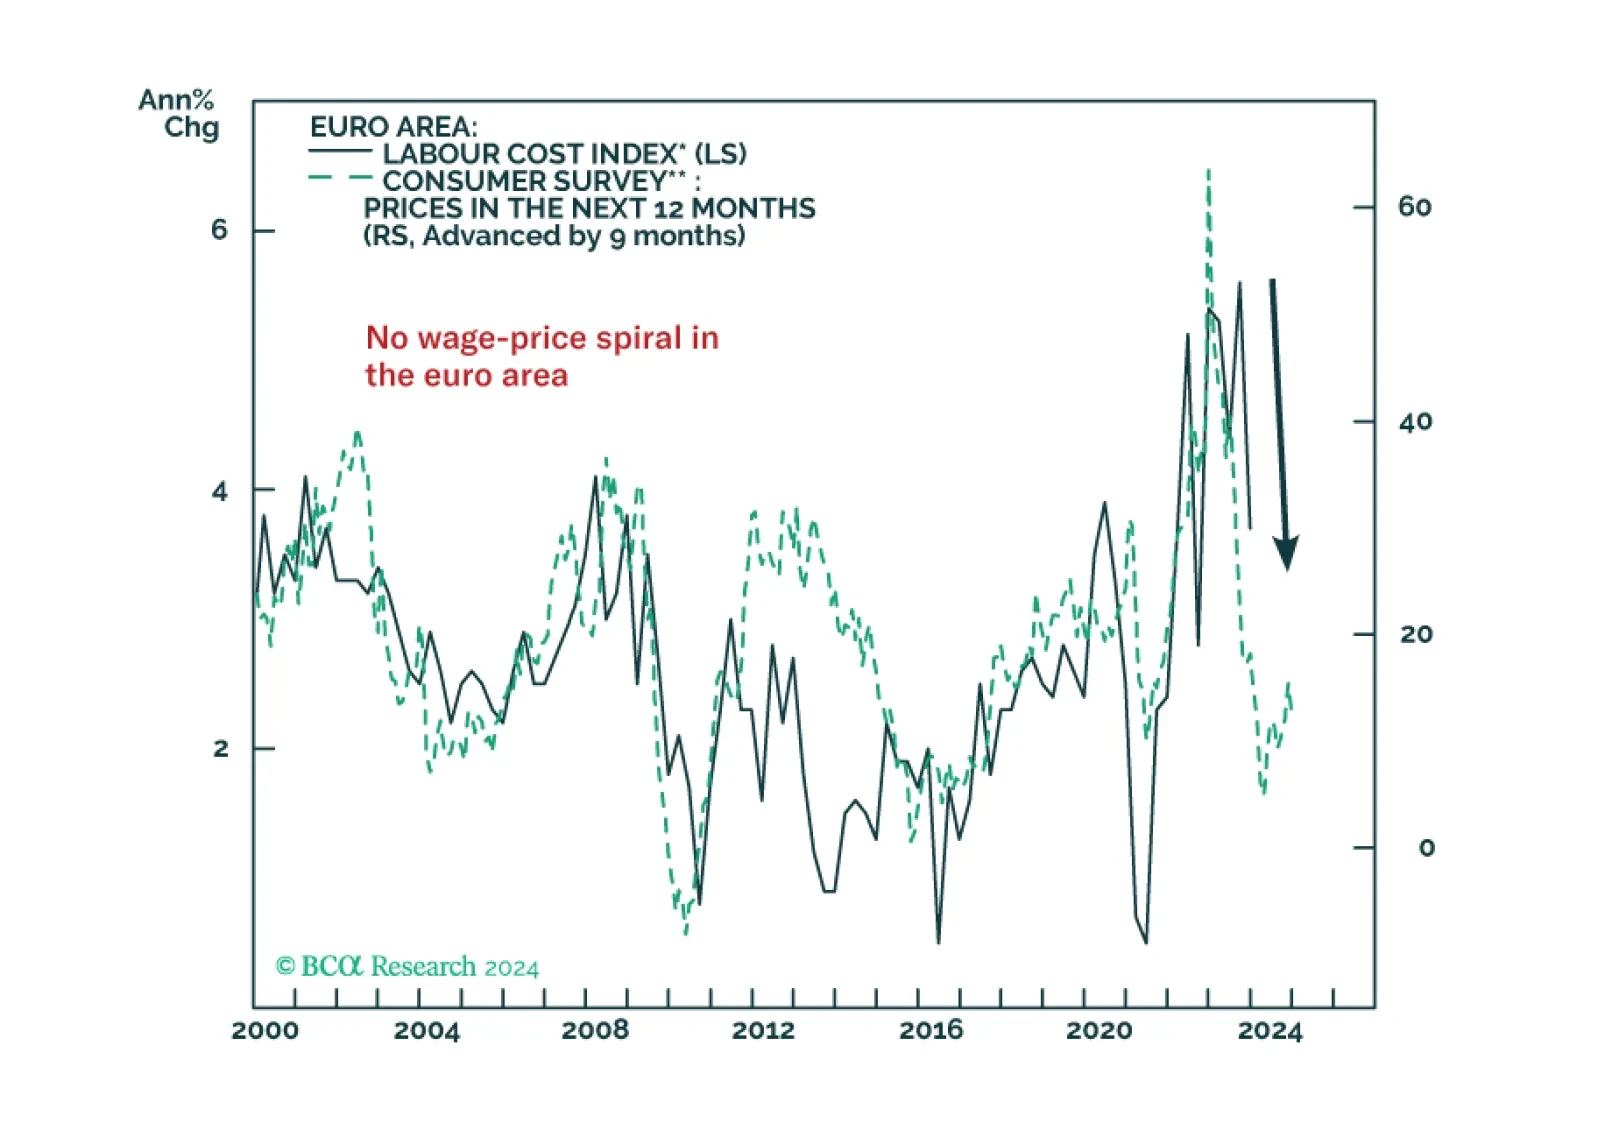
At today’s monetary policy meeting, the ECB gave strong hints that rate cuts will begin as soon as the next meeting in June. In this Insight, we share our thoughts on today’s meeting and discuss the implications for European bond yields and the euro.
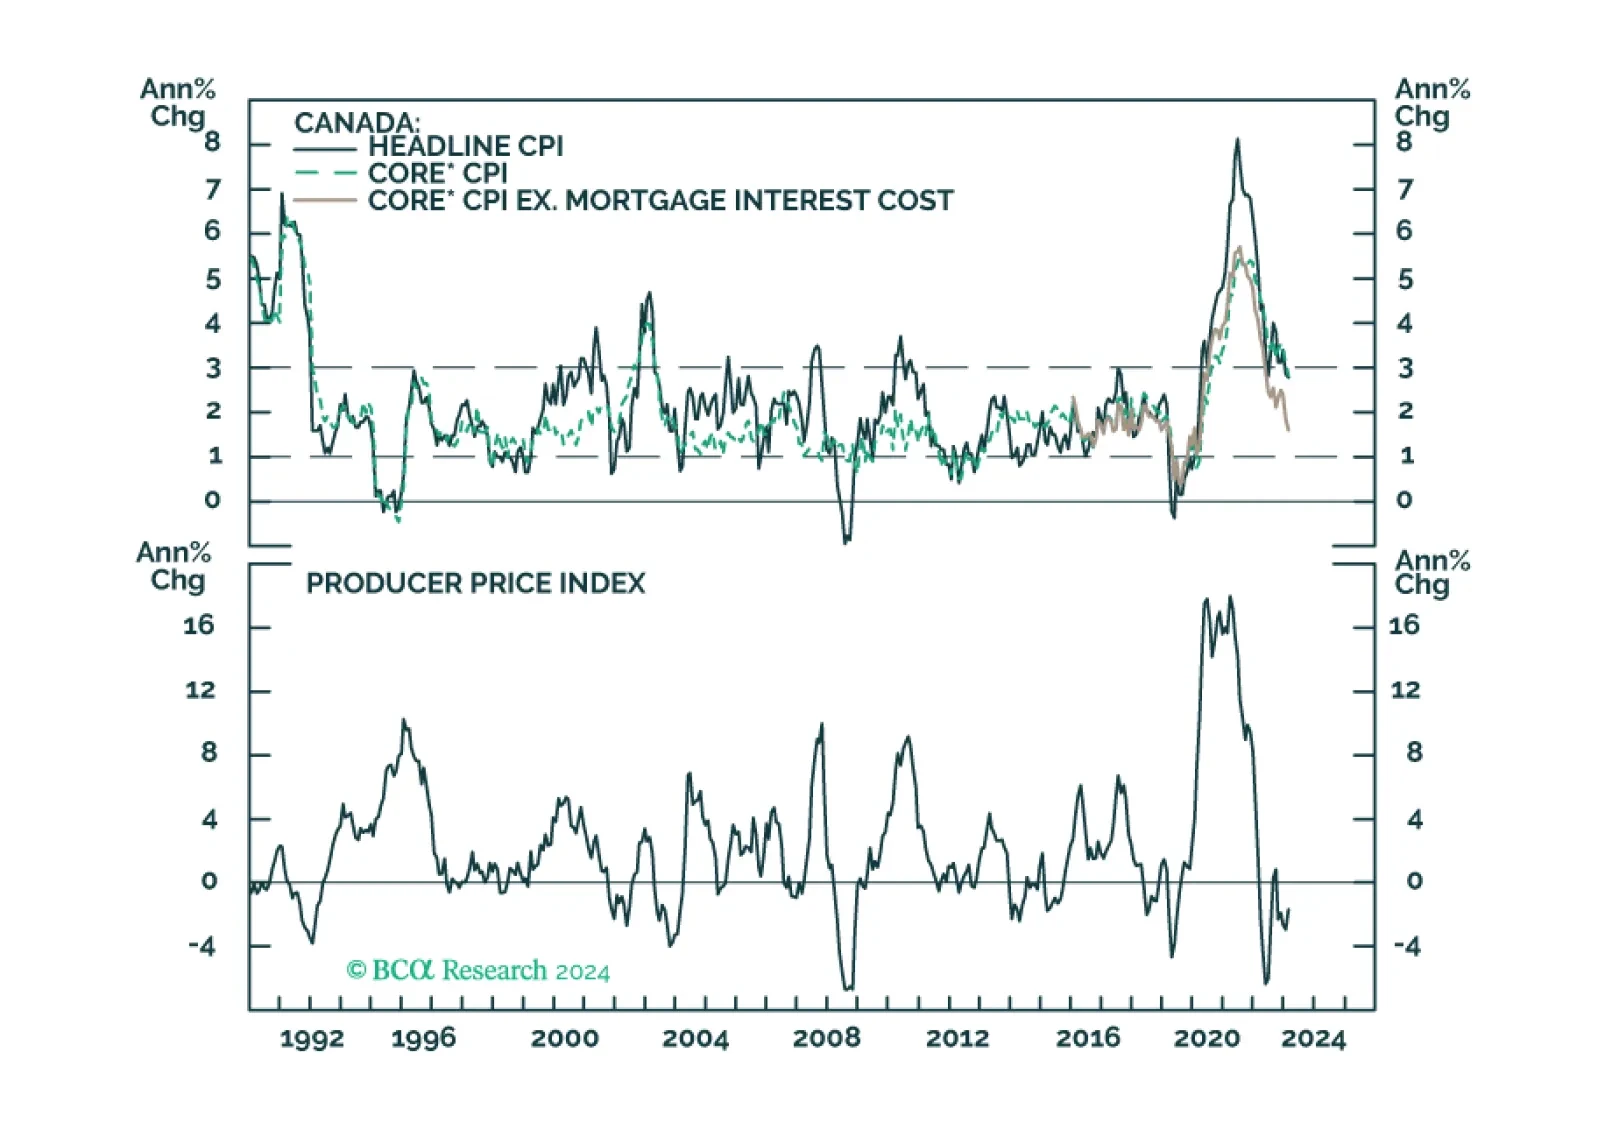
In this insight, we calibrate our investment views based on the latest Bank of Canada decision.