FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
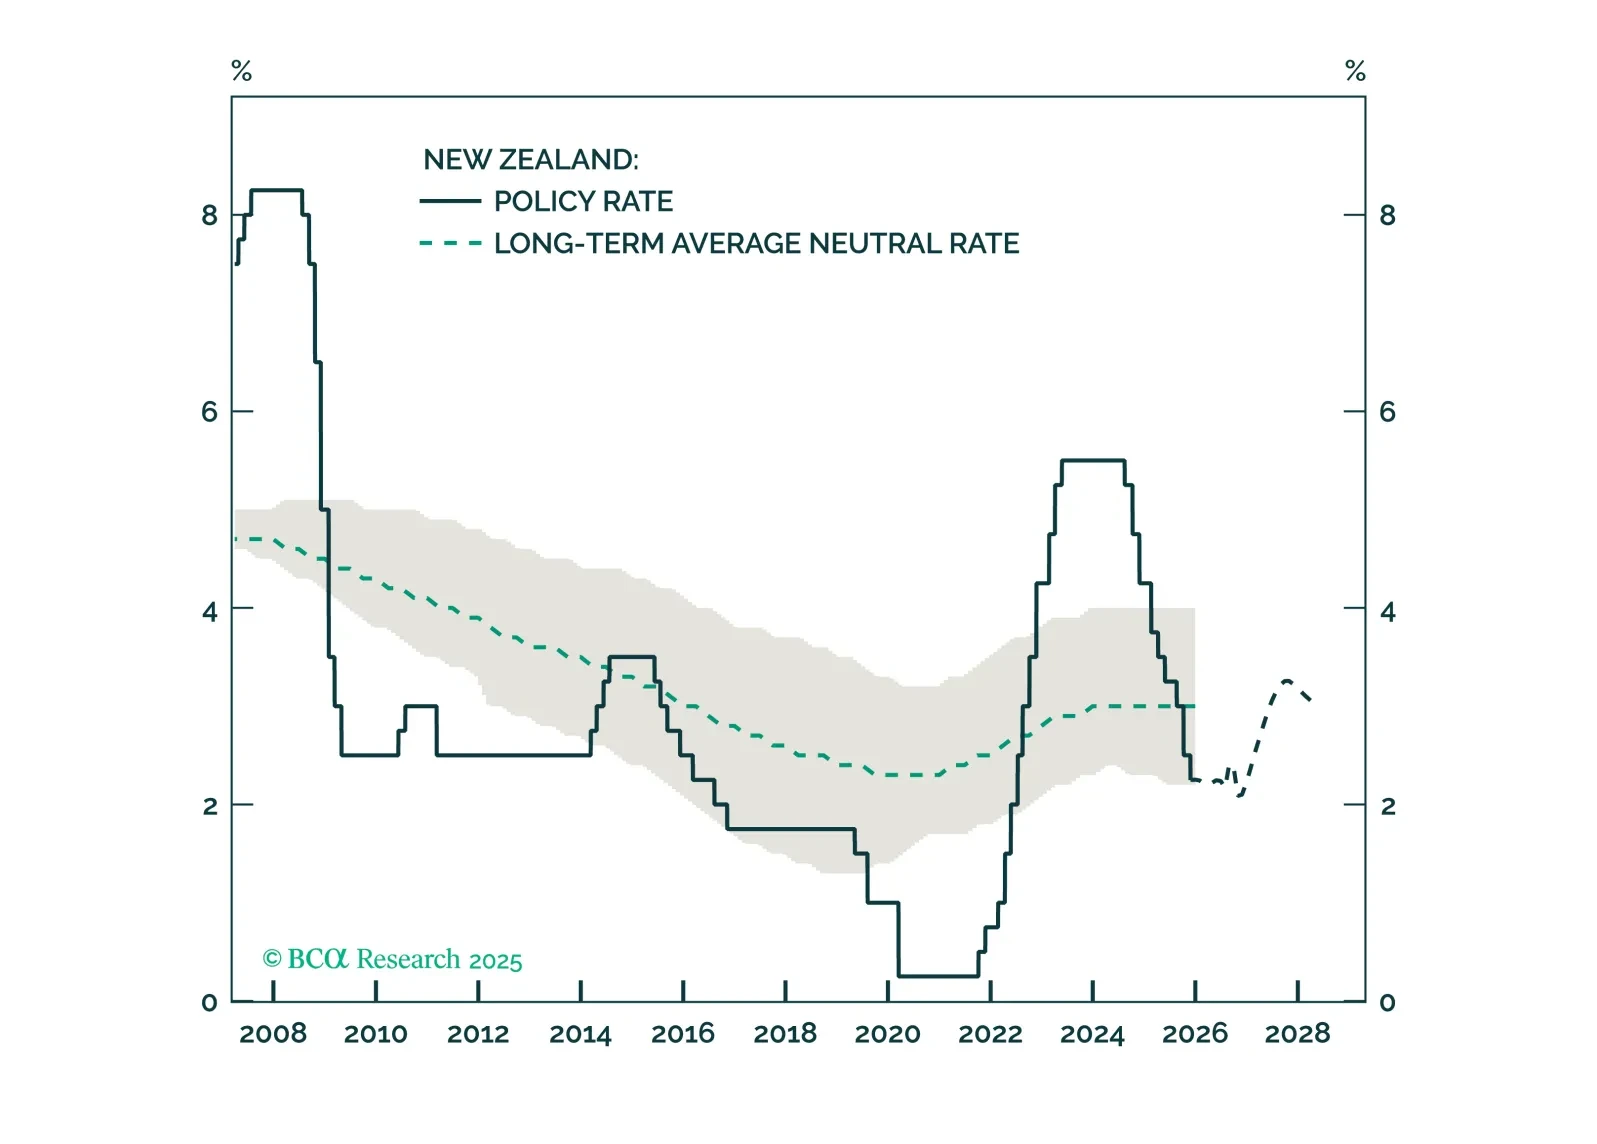
The RBNZ has concluded its aggressive easing blitz. With New Zealand economy finally showing signs of life, both the kiwi and local rates now look ripe for a reversal.
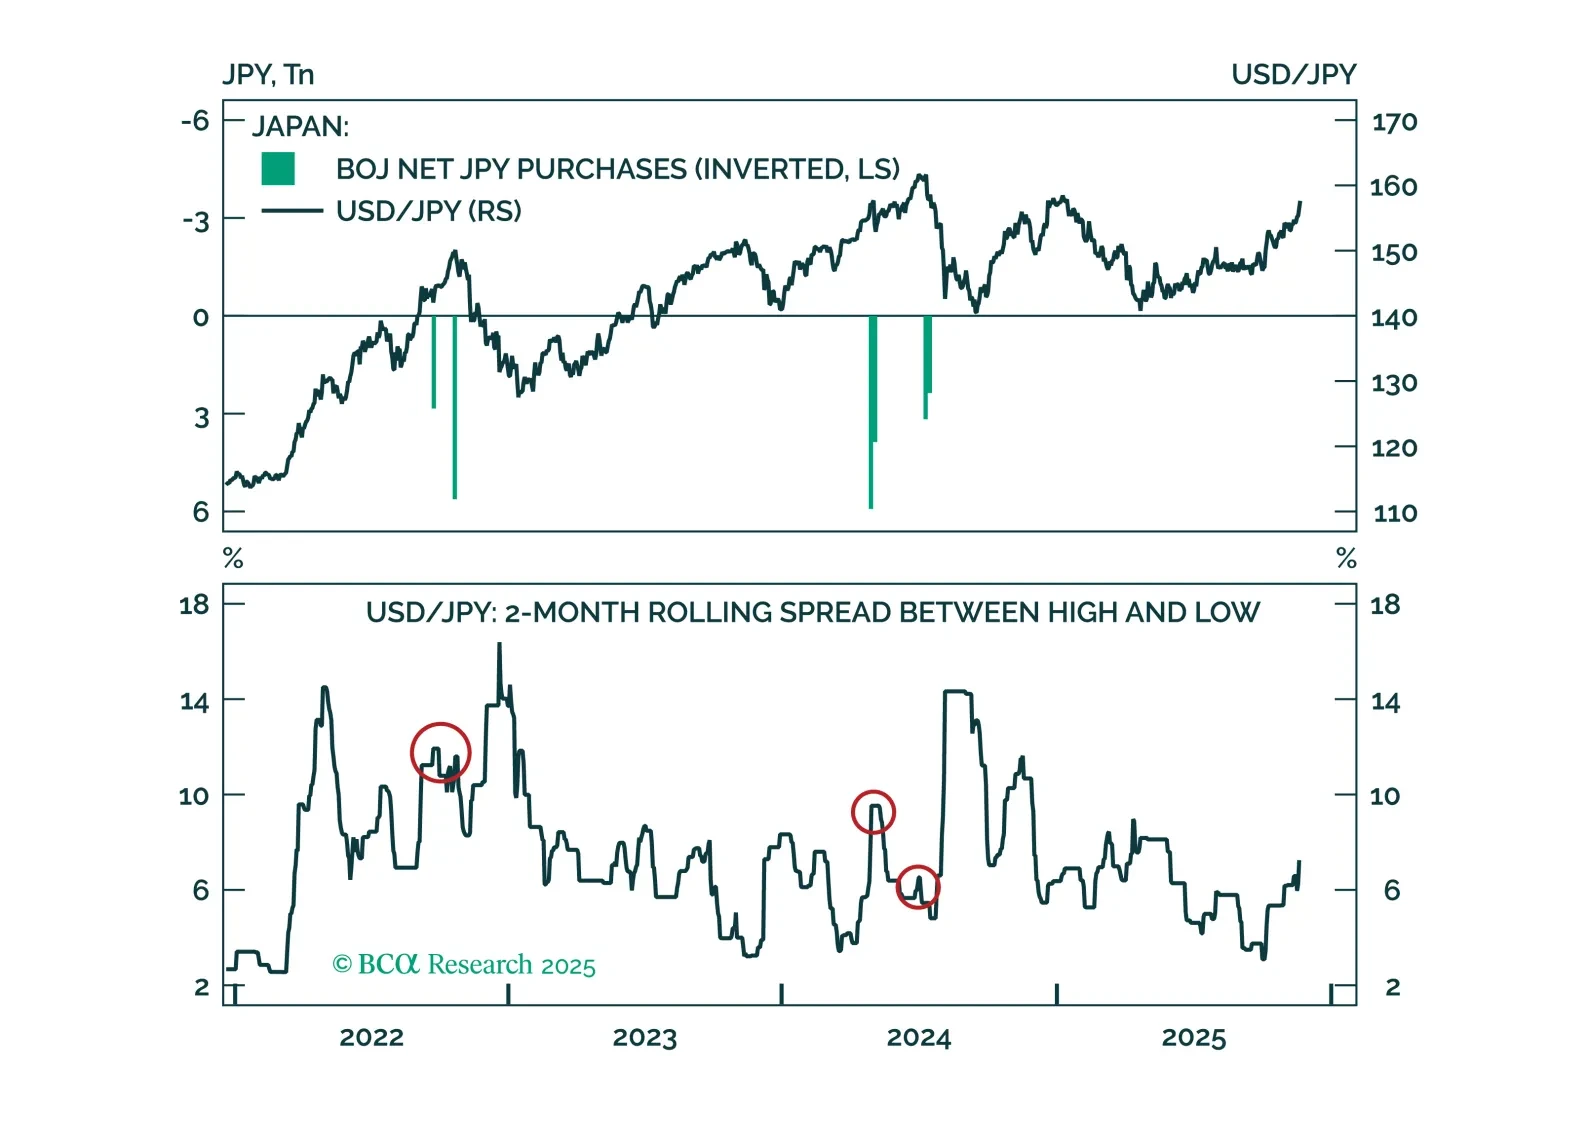
Markets are misreading Japan’s fiscal headlines. Our latest Insight examines what will shape BoJ policy next, when intervention might come, and the timing of a yen reversal.
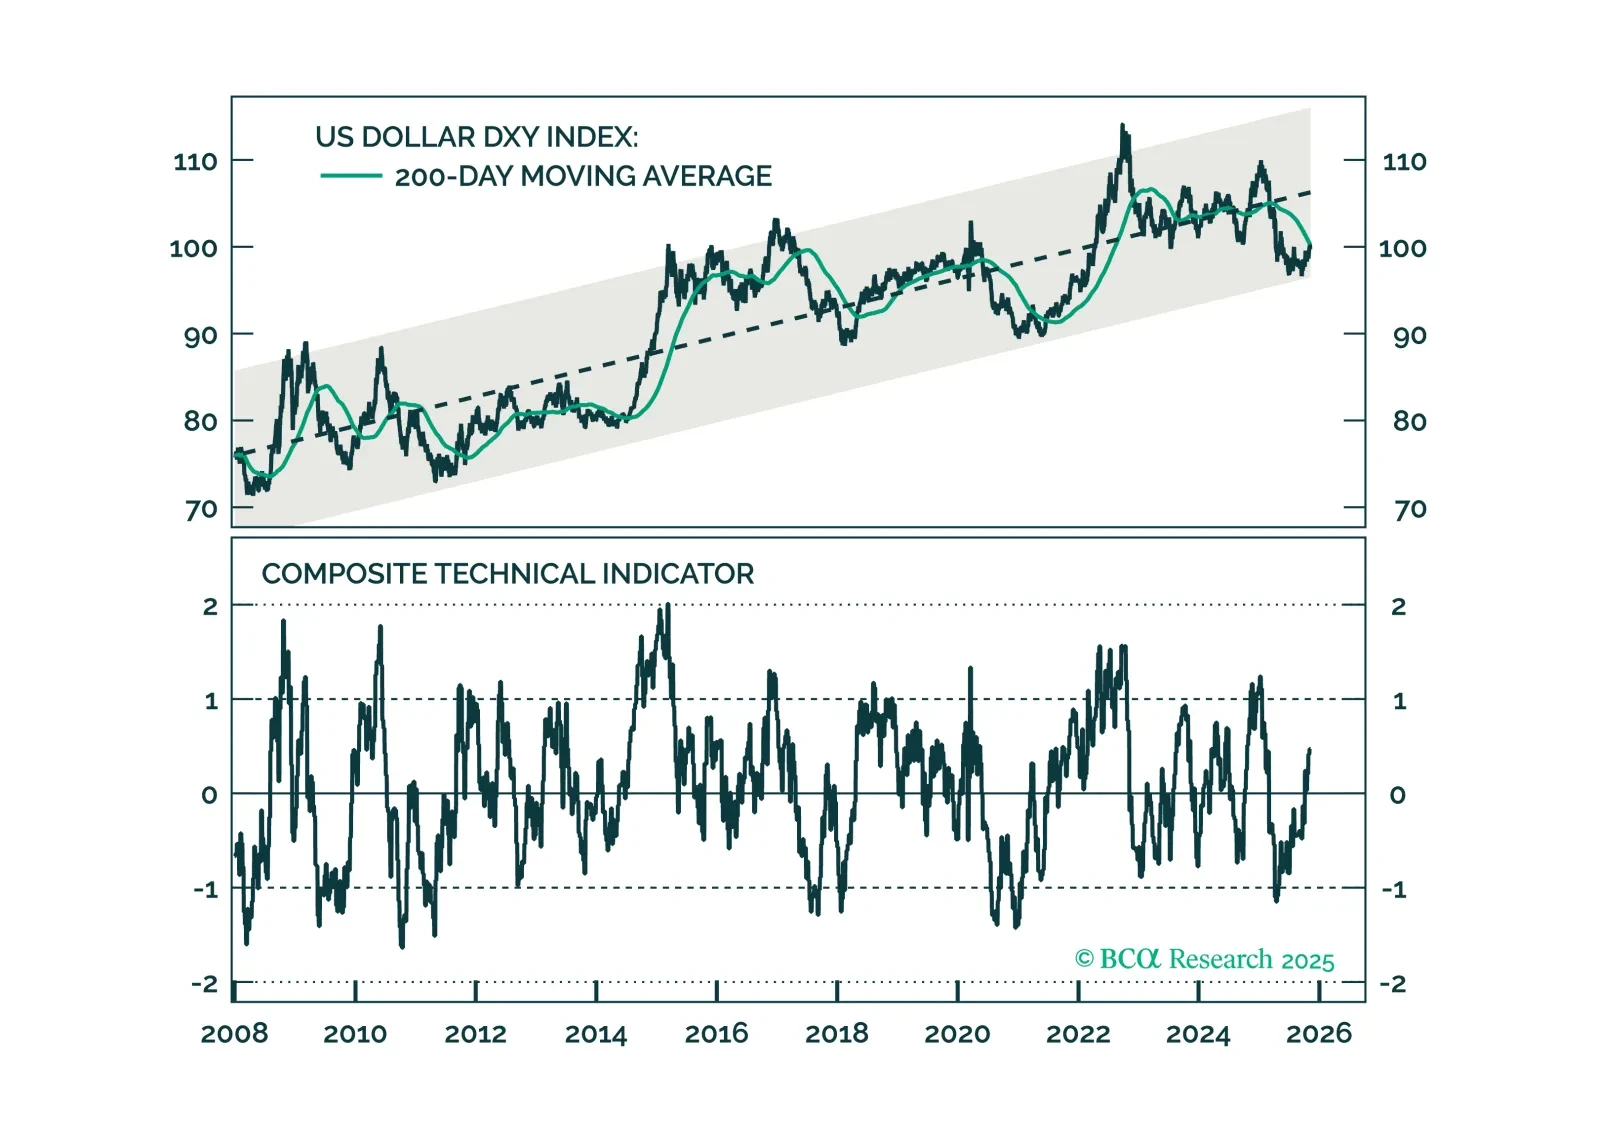
The dollar rebound has paused, but not yet peaked. With near-term momentum still intact, we see room for further upside before structural headwinds reassert, favoring selling into strength.
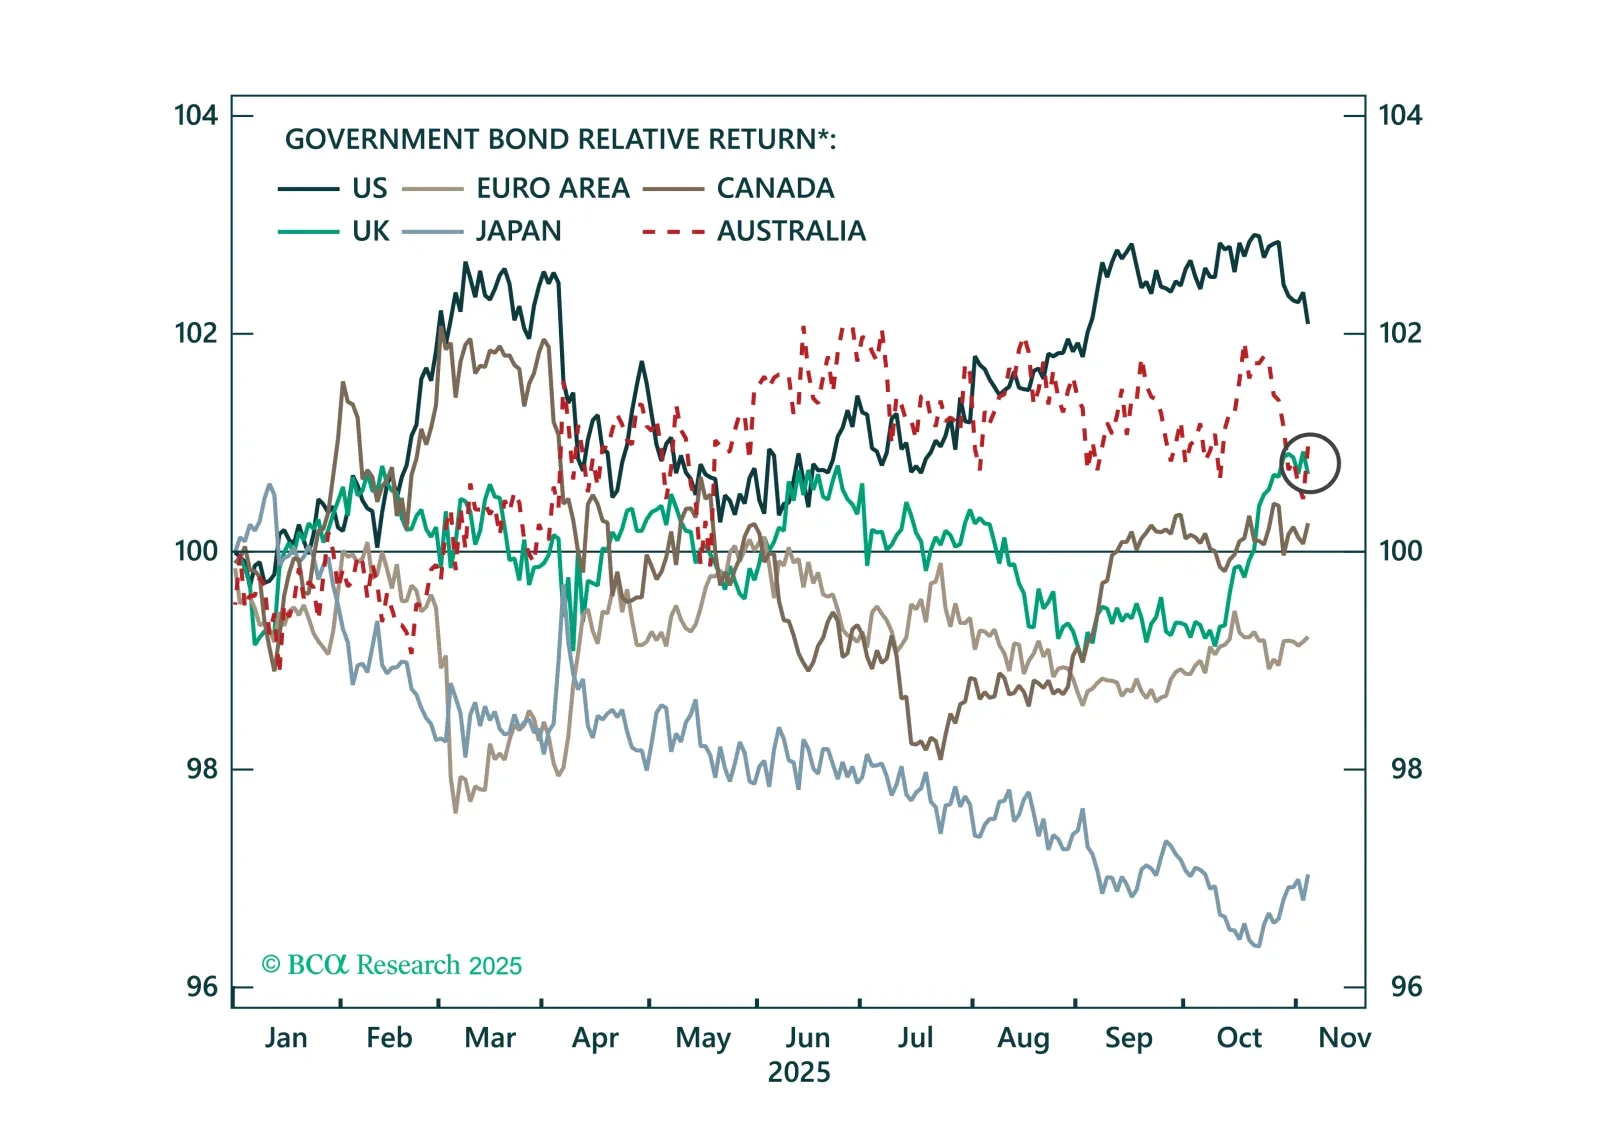
The Bank of England will resume rate cuts in December after the autumn budget is passed. Today’s Strategy Insight discusses what this means for UK gilts and the pound.
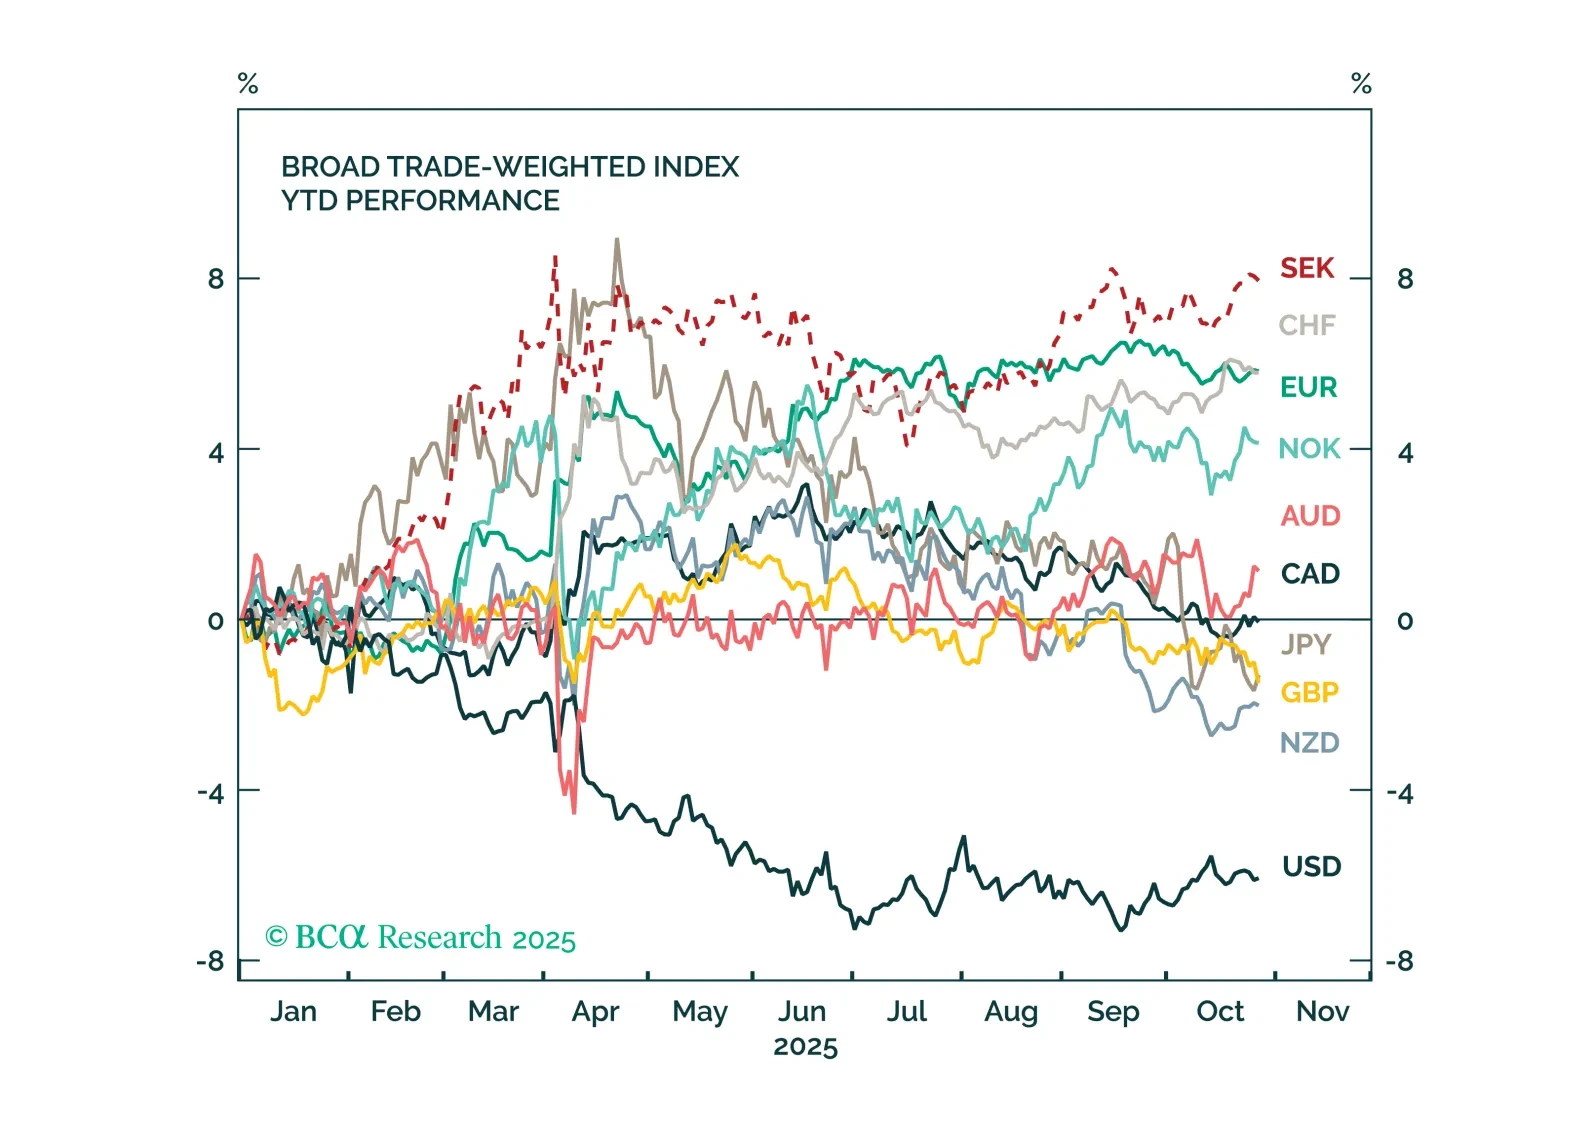
Markets are increasingly pricing an end to the global easing cycle, with many central banks expected to remain on hold. But uncertainty remains high, and policy surprises are likely going into 2026. This Strategy Report breaks down the current drivers behind G10 central bank policies, and how to position for the next moves across FX and fixed income.
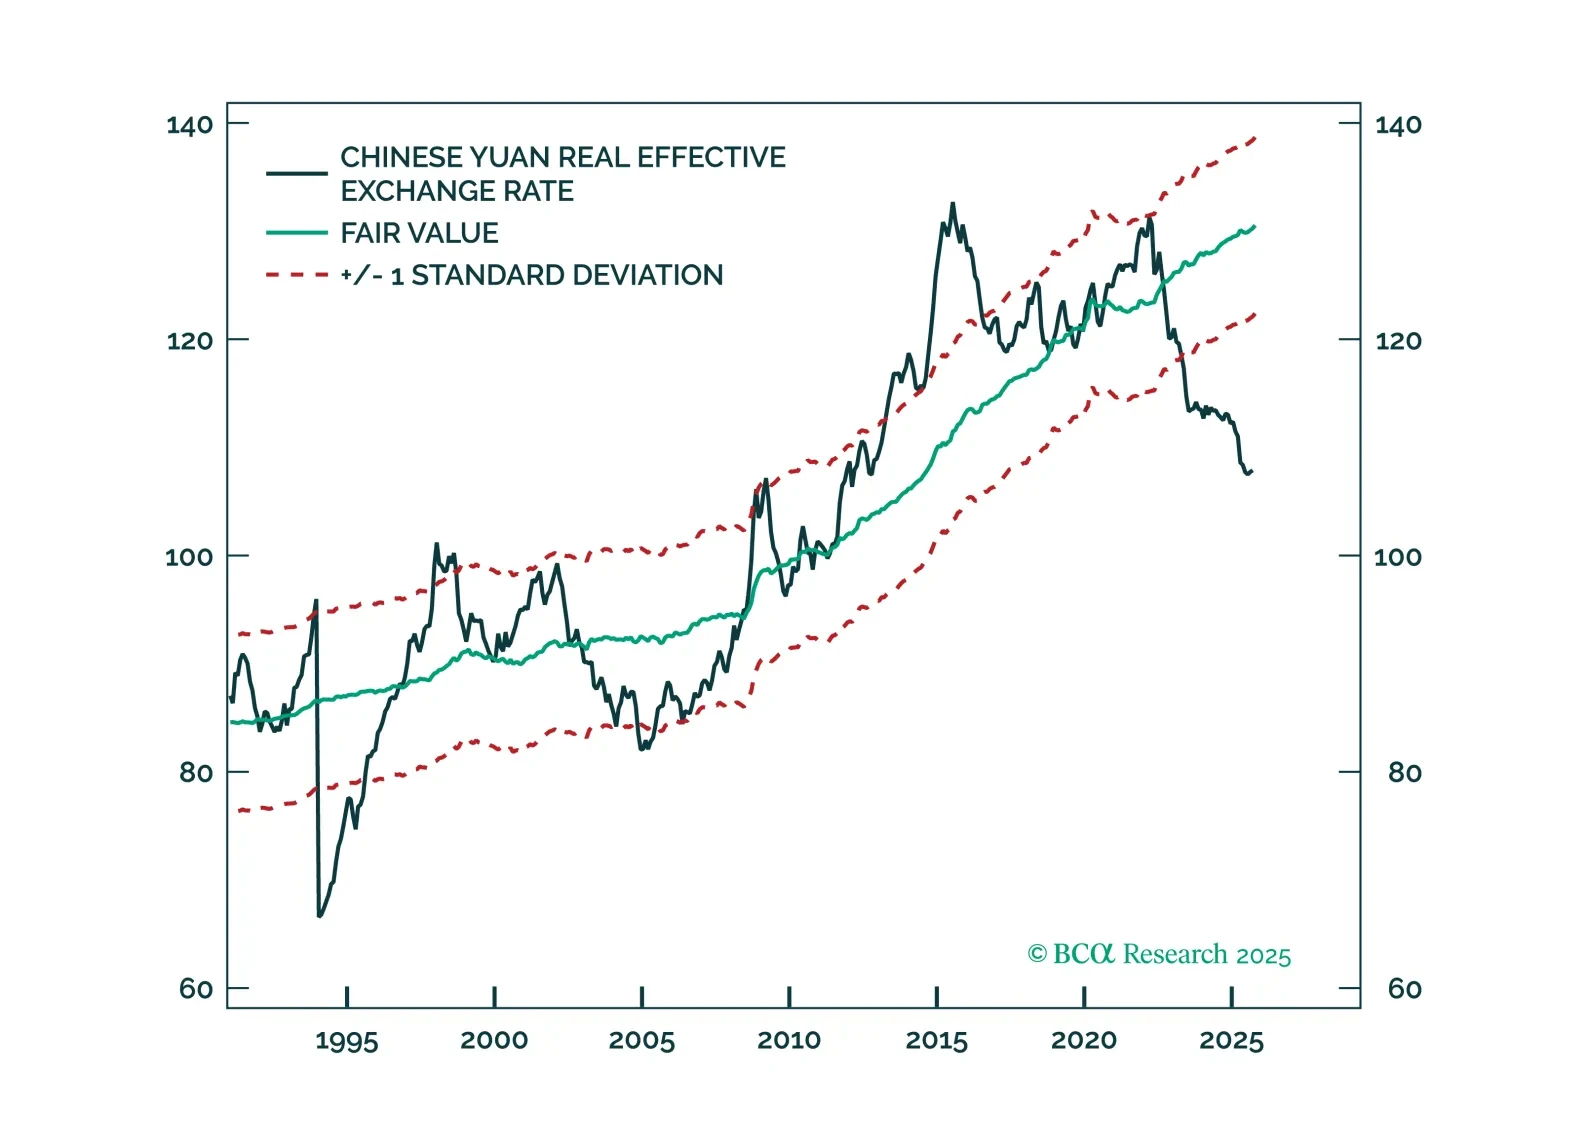
Beijing’s quiet pivot toward RMB strength and a deep valuation discount set the stage for a multi-year appreciation. Our latest FX Insight explores why we see the CNY rising to 6.5–6.8 versus the USD over the next year.
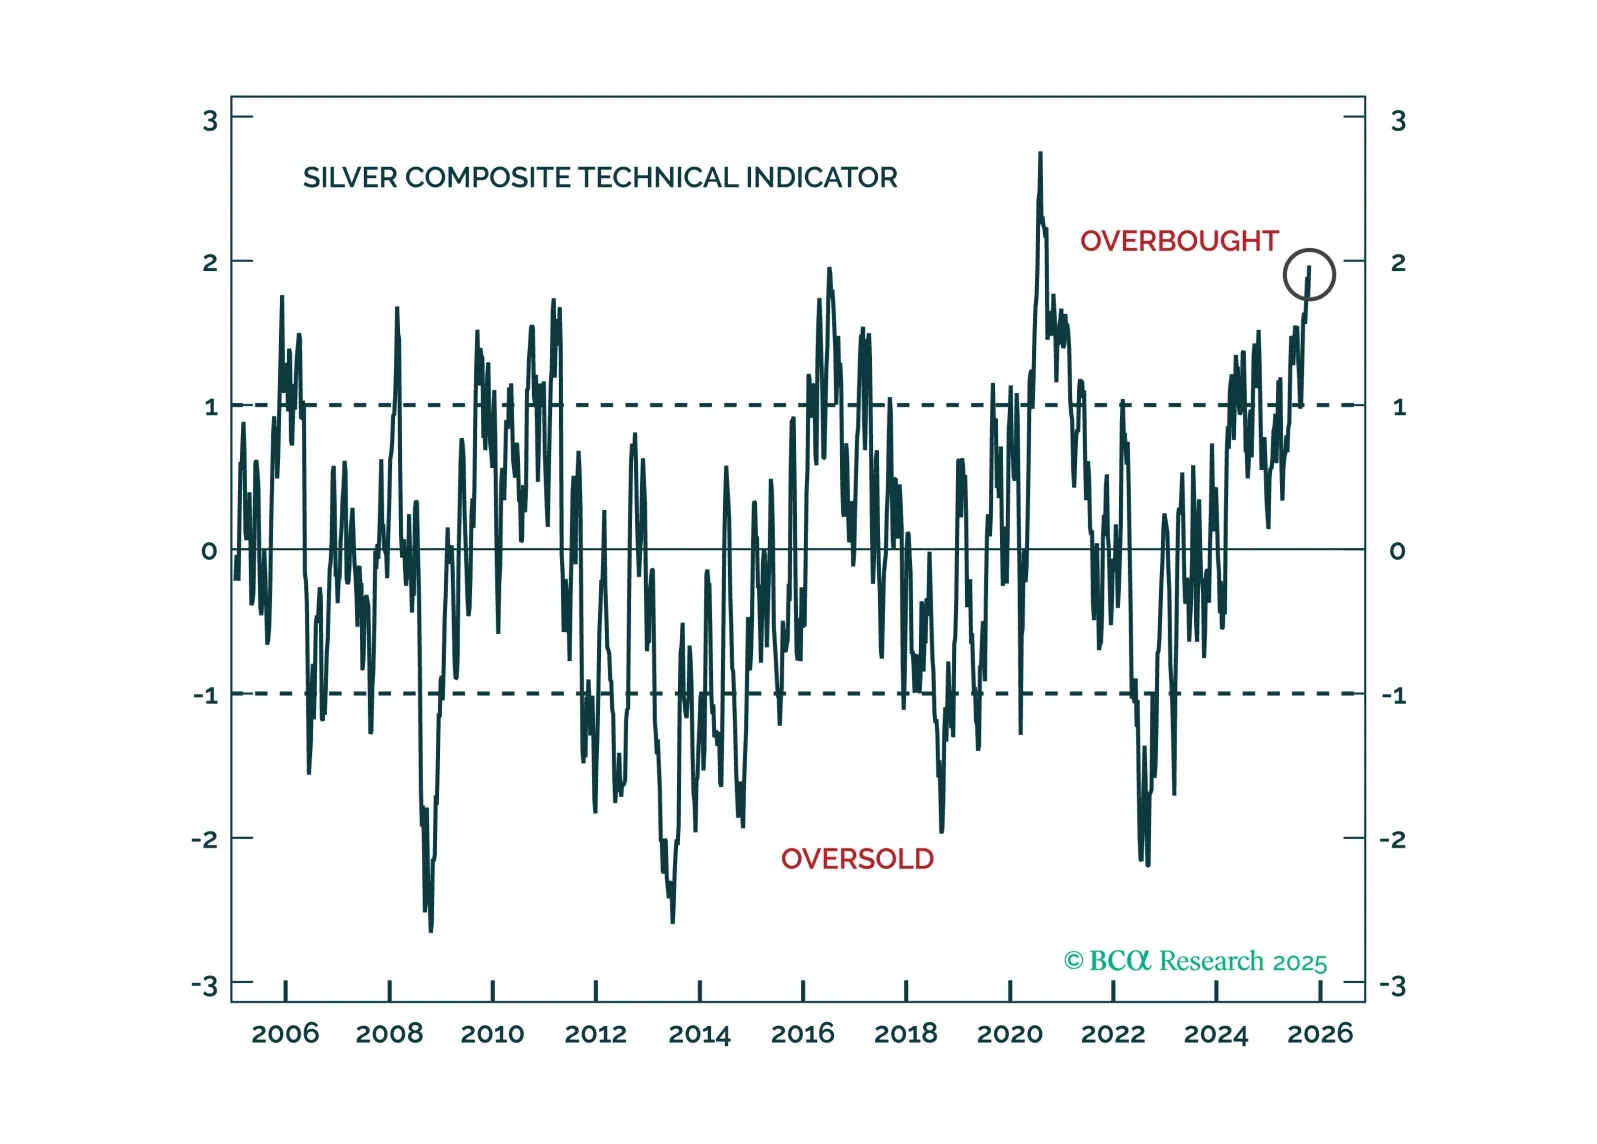
Speculative froth has built up across all precious metals, yet gold’s structural tailwinds will allow it to weather corrections better than its peers.
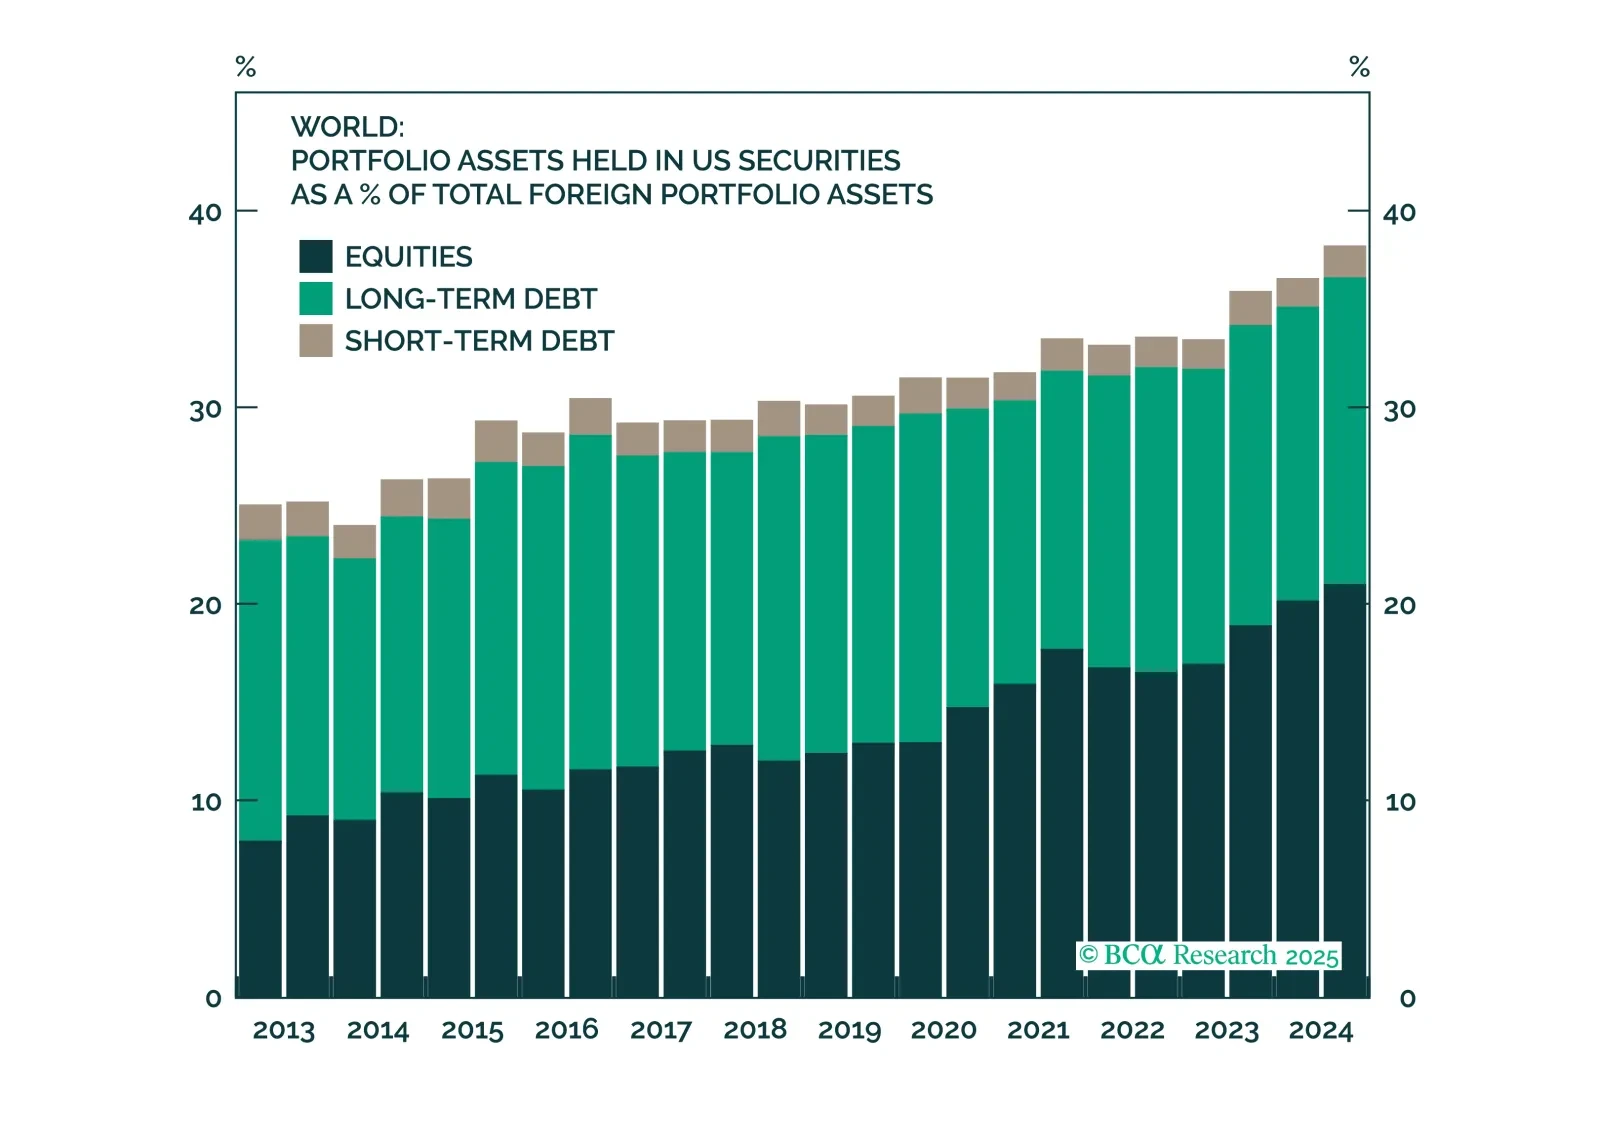
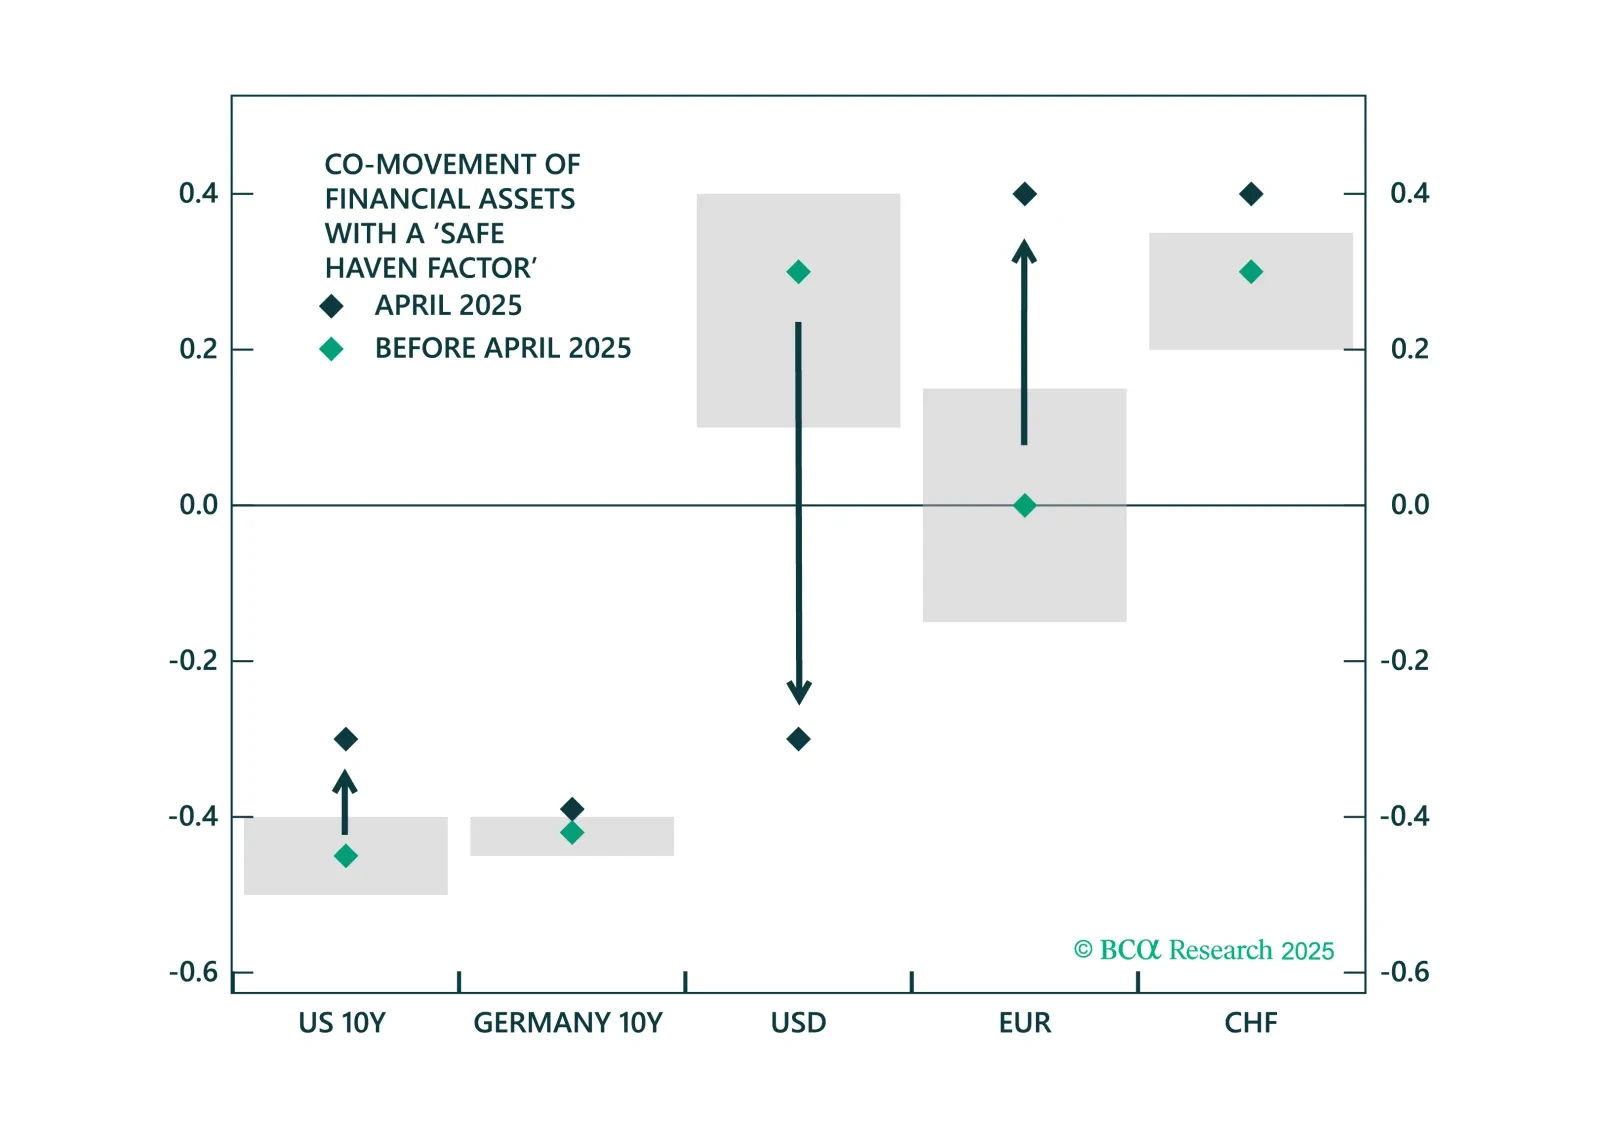
The dollar’s early 2025 decline was a reflection of a global rush to hedge accumulated USD exposure, not a mass exodus from US assets. With most hedging now complete, currency moves should again follow fundamentals, setting the stage for a tactical USD rebound in the months ahead.
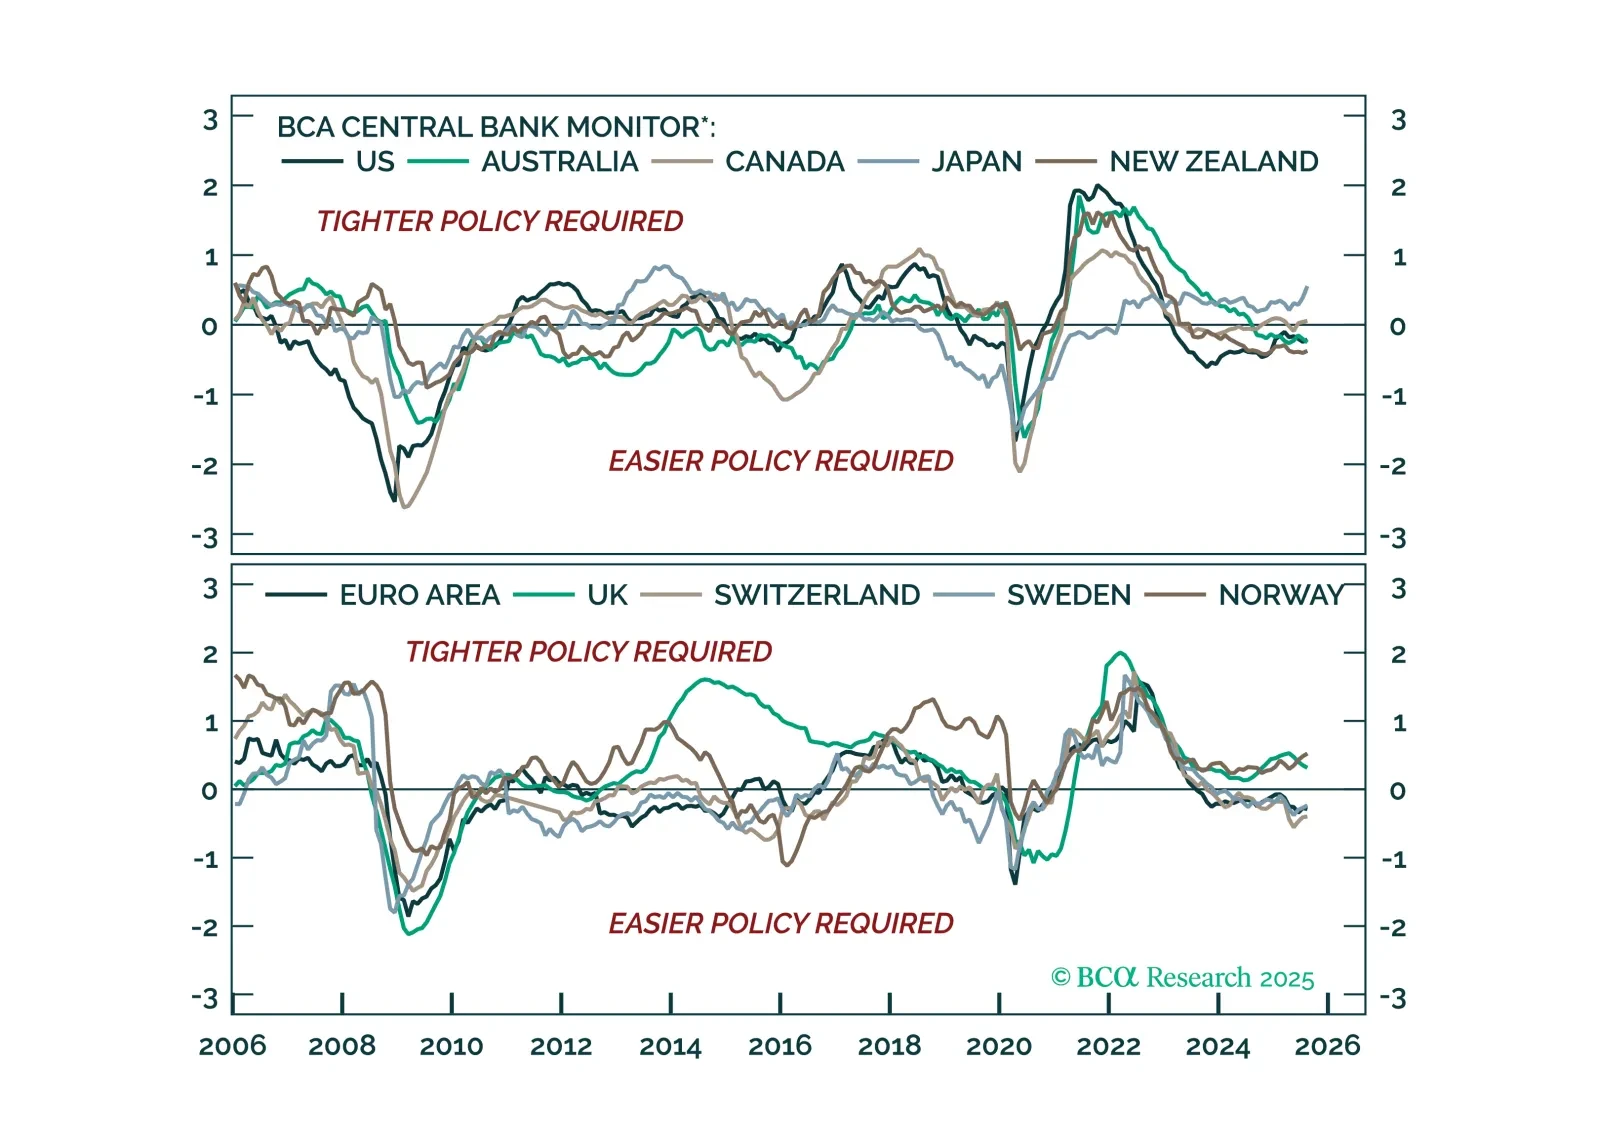
Monetary policy divergences are re-emerging. We rely on BCA’s Central Bank Monitor to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.