 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
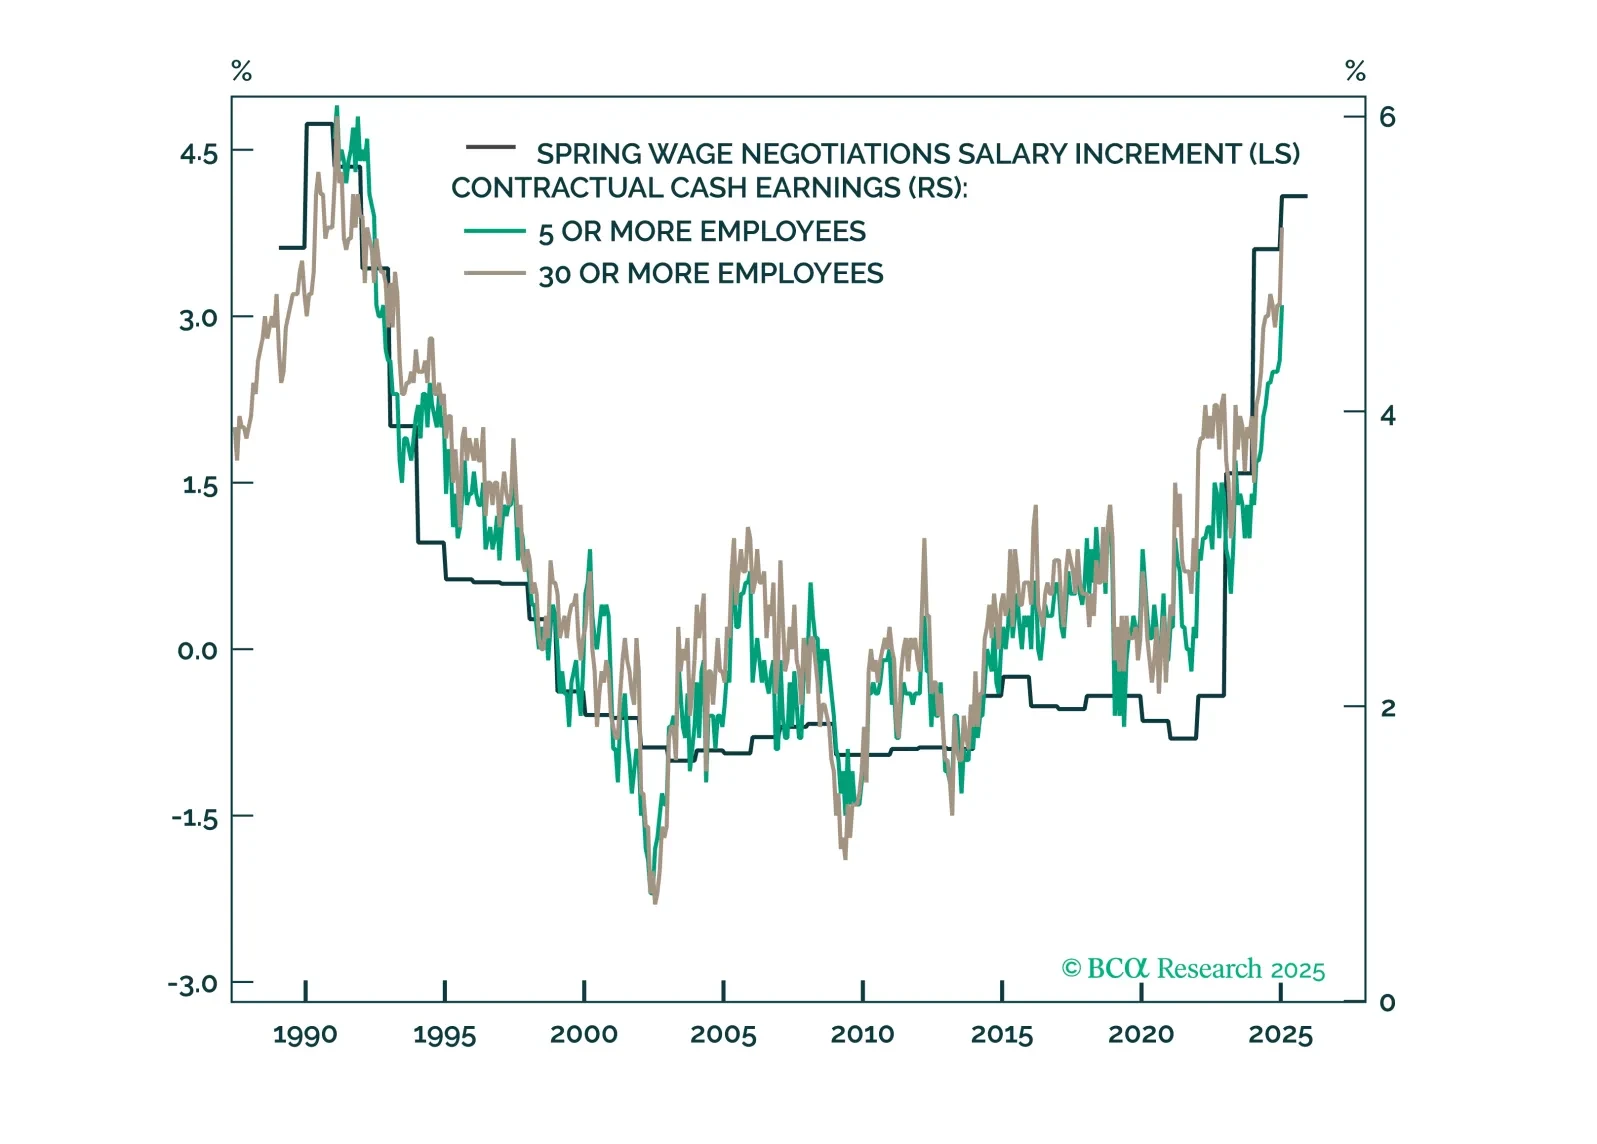
Given the meetings between the Bank of Japan, the Bank of England, and the Swiss National Bank, our highest convictions views are: Overweight UK Gilts. It is also time to sell sterling. We are short sterling, as of 1.30. Underweight JGBs. Correspondingly, be long the yen. A short CHF/JPY position remains a core holding. Selling GBP/JPY is also a great trade.
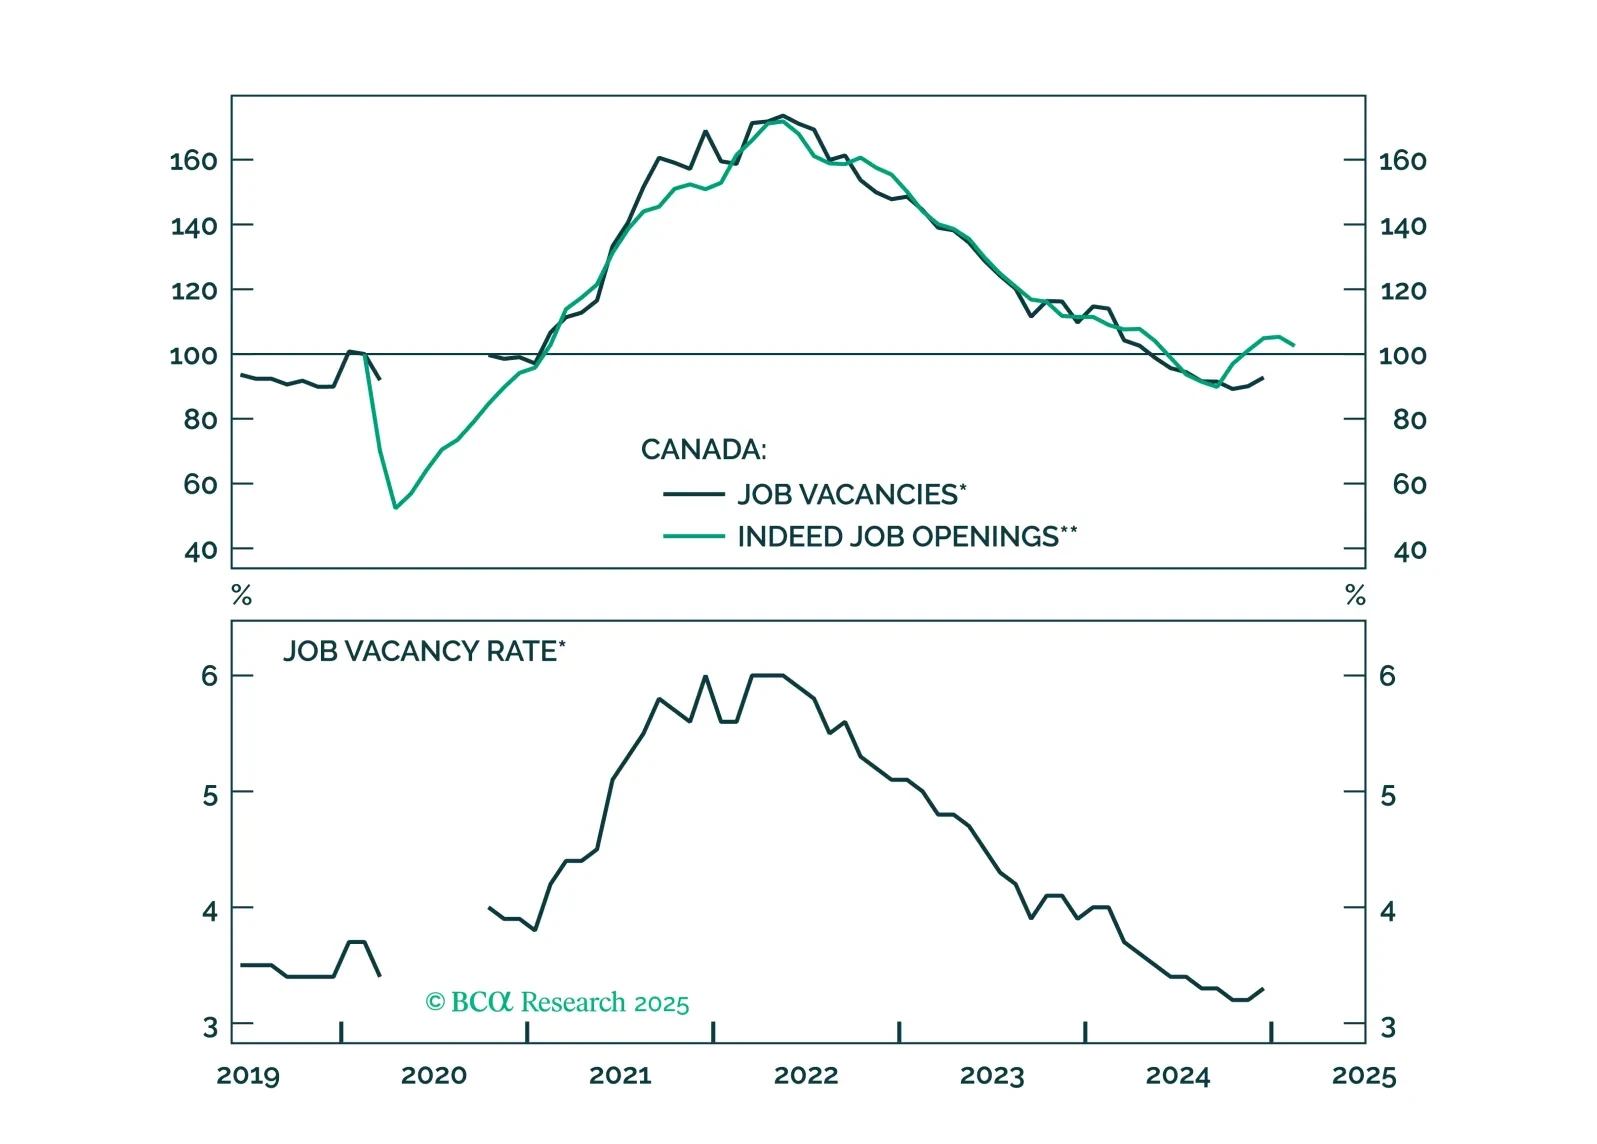
The trade war complicates the Bank of Canada’s task to achieve stable inflation. But the bottom line is that rising uncertainty, which will dampen business sentiment, will cause the BoC to cut rates by at least what is priced in the CORRA curve, and likely to 2%. The CAD, which is very oversold, might not depreciate much. The big trade is a bet on a spread widening for Canadian provincial bonds.
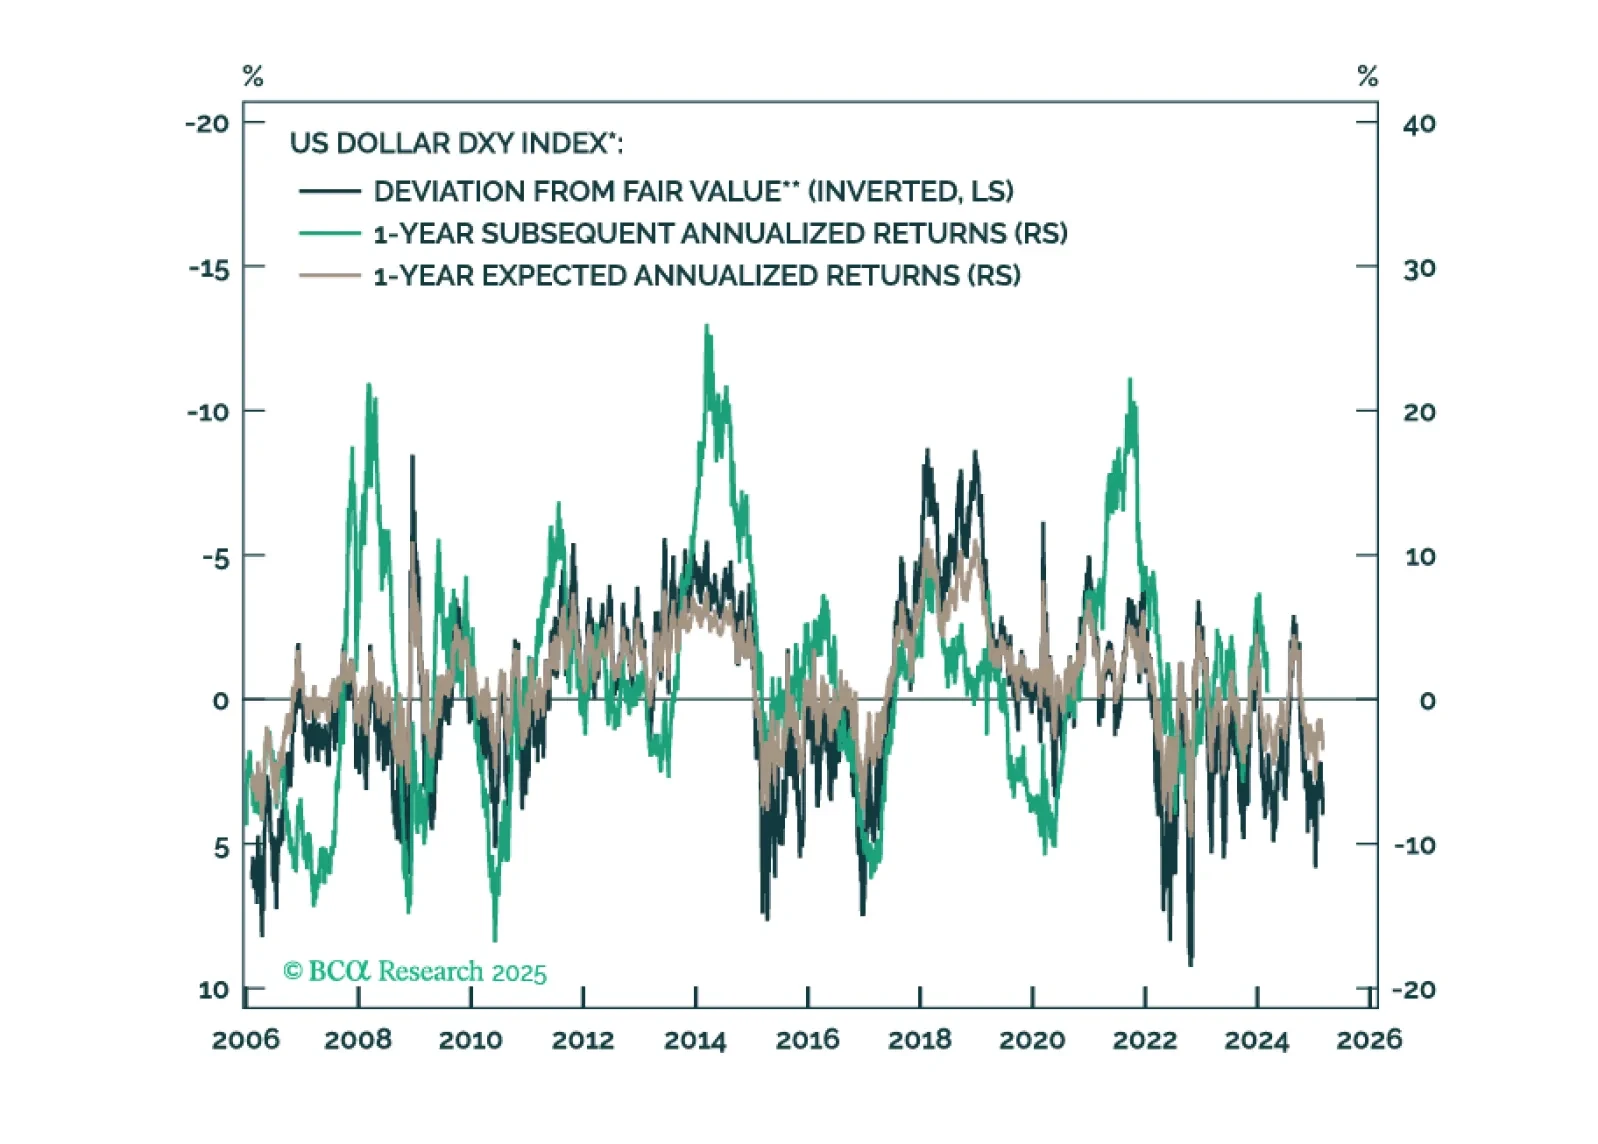
This report is our Part III series on valuation and subsequent returns, where we recalibrate our short-term models to emphasize signals over the next nine-to-twelve months. We will henceforth call these models STTM: Short Term Timing Models.
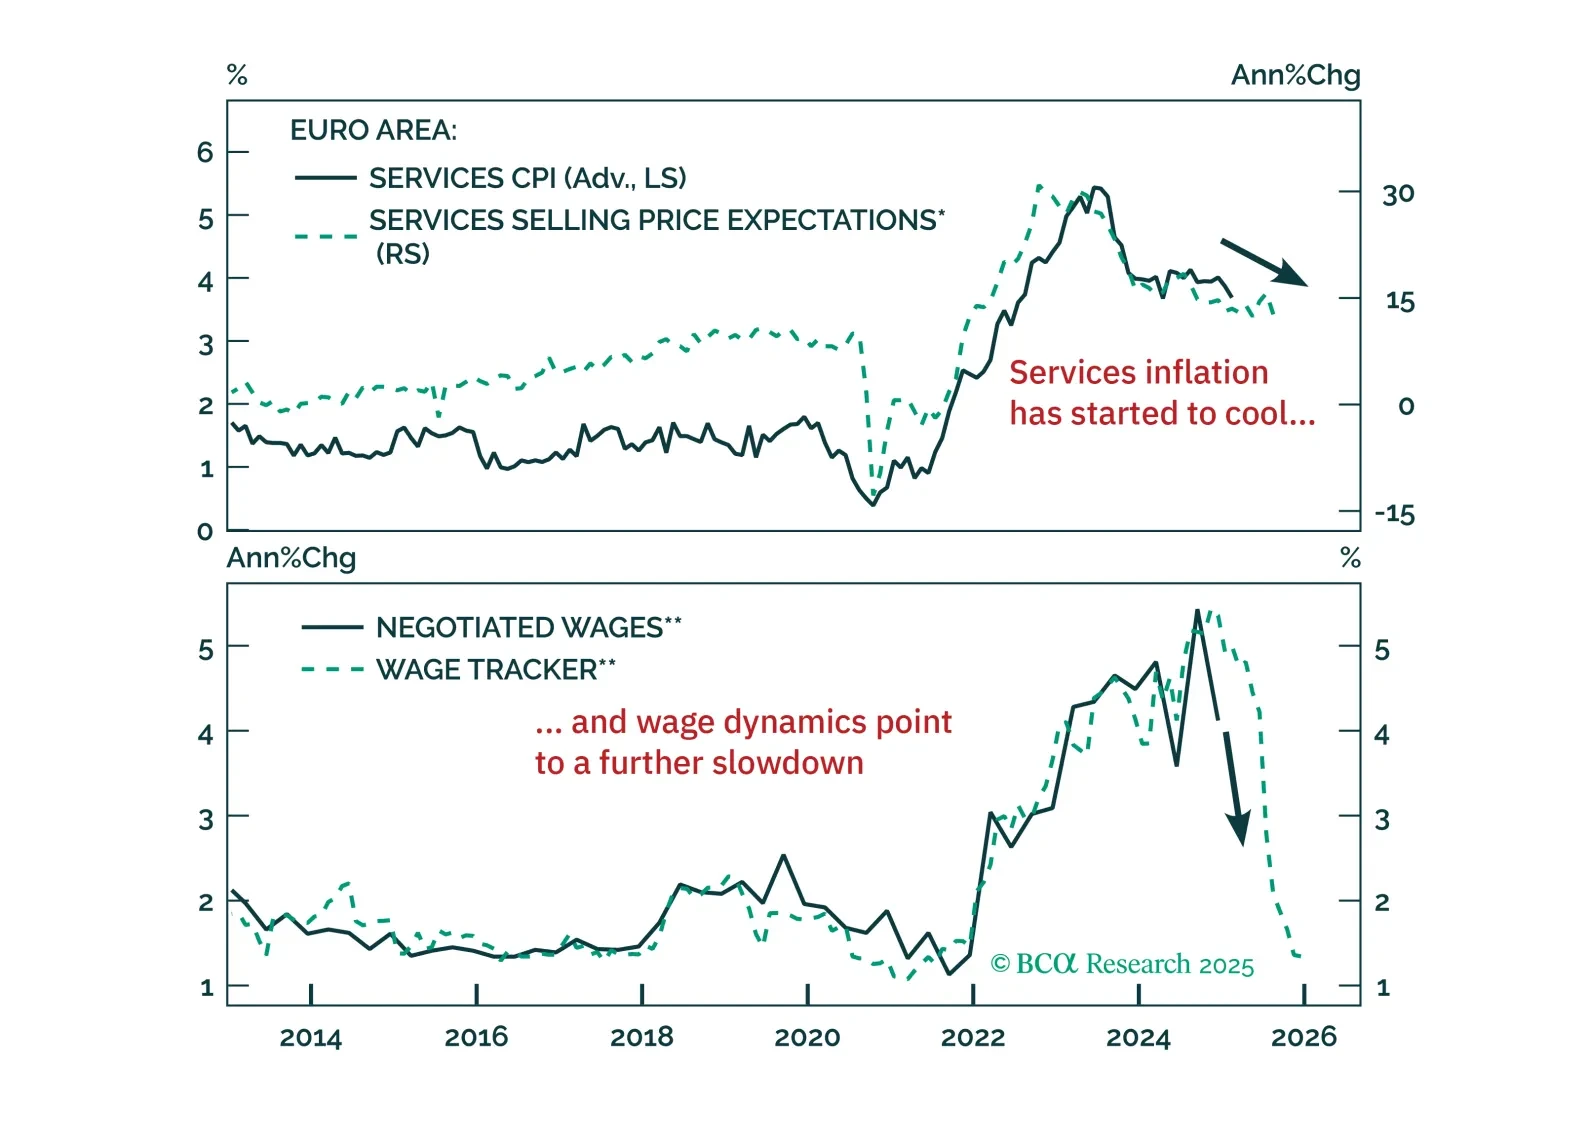
The ECB cut rates as expected, but rising yields and a stronger euro are tightening financial conditions just as fiscal policy shifts the macro landscape. With more rate cuts ahead and market positioning stretched, we outline the key risks, investment opportunities, and our updated call on the ECB’s terminal rate. Read our full report for actionable insights.
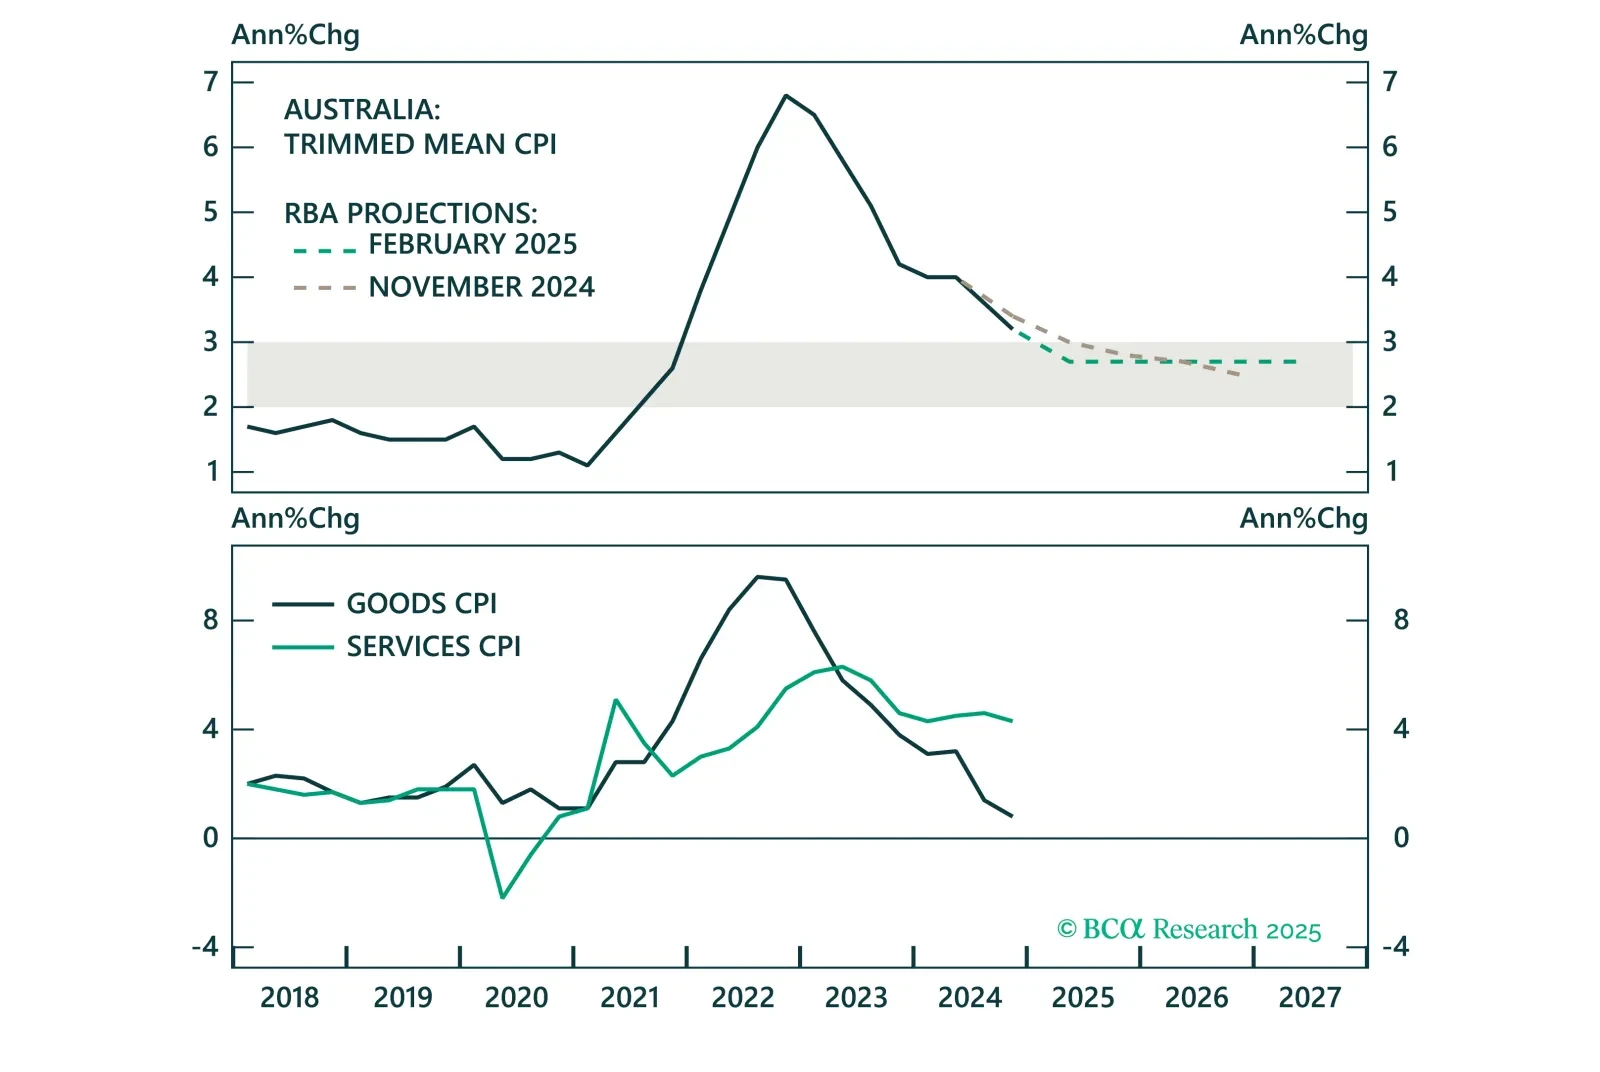
Overnight, the RBA cut the cash target rate for the first time since 2022, marking the beginning of the policy easing cycle in Australia. However, the RBA will proceed cautiously with further rate cuts, given a tight labor market and still elevated services inflation. This will keep Australian government bond yields elevated versus global yields, benefitting the Australian dollar.
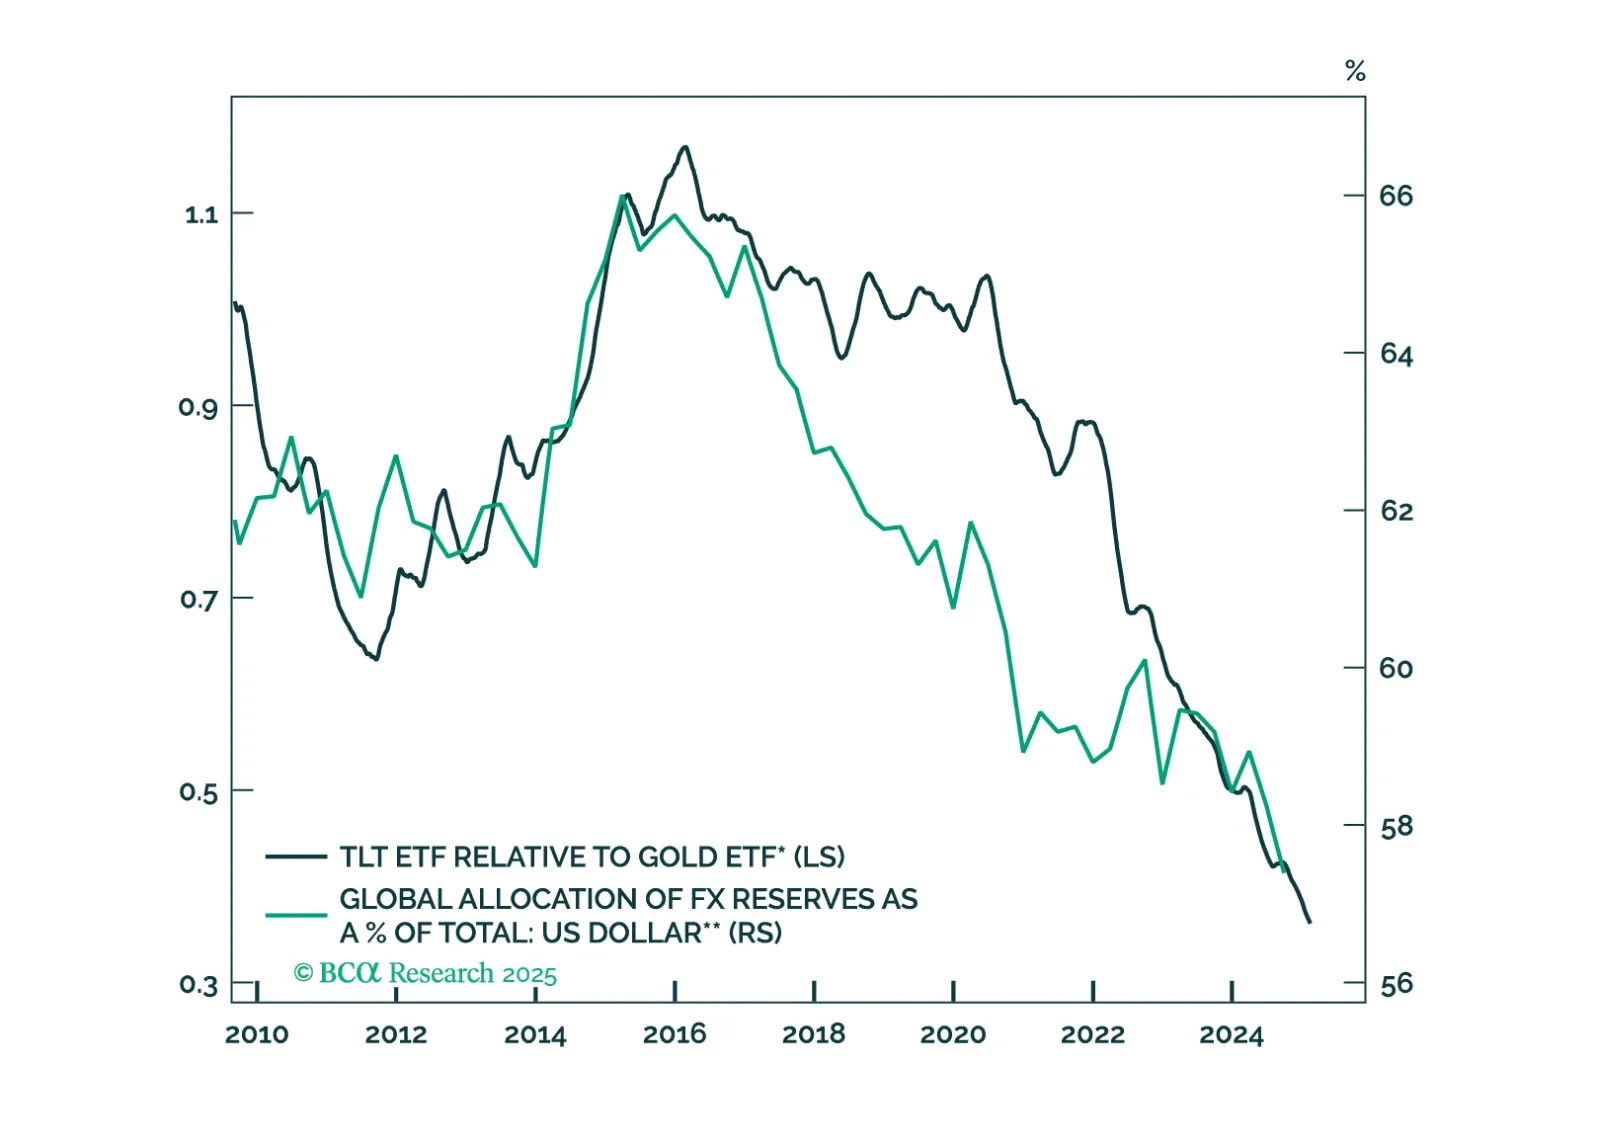
In lieu of all the geopolitical and economic news in media, this report looks at where next the dollar is likely to trend in the next one-to-three months. Our view is down, though on a cyclical horizon (six-to-twelve months), we would not be short the dollar, for now.
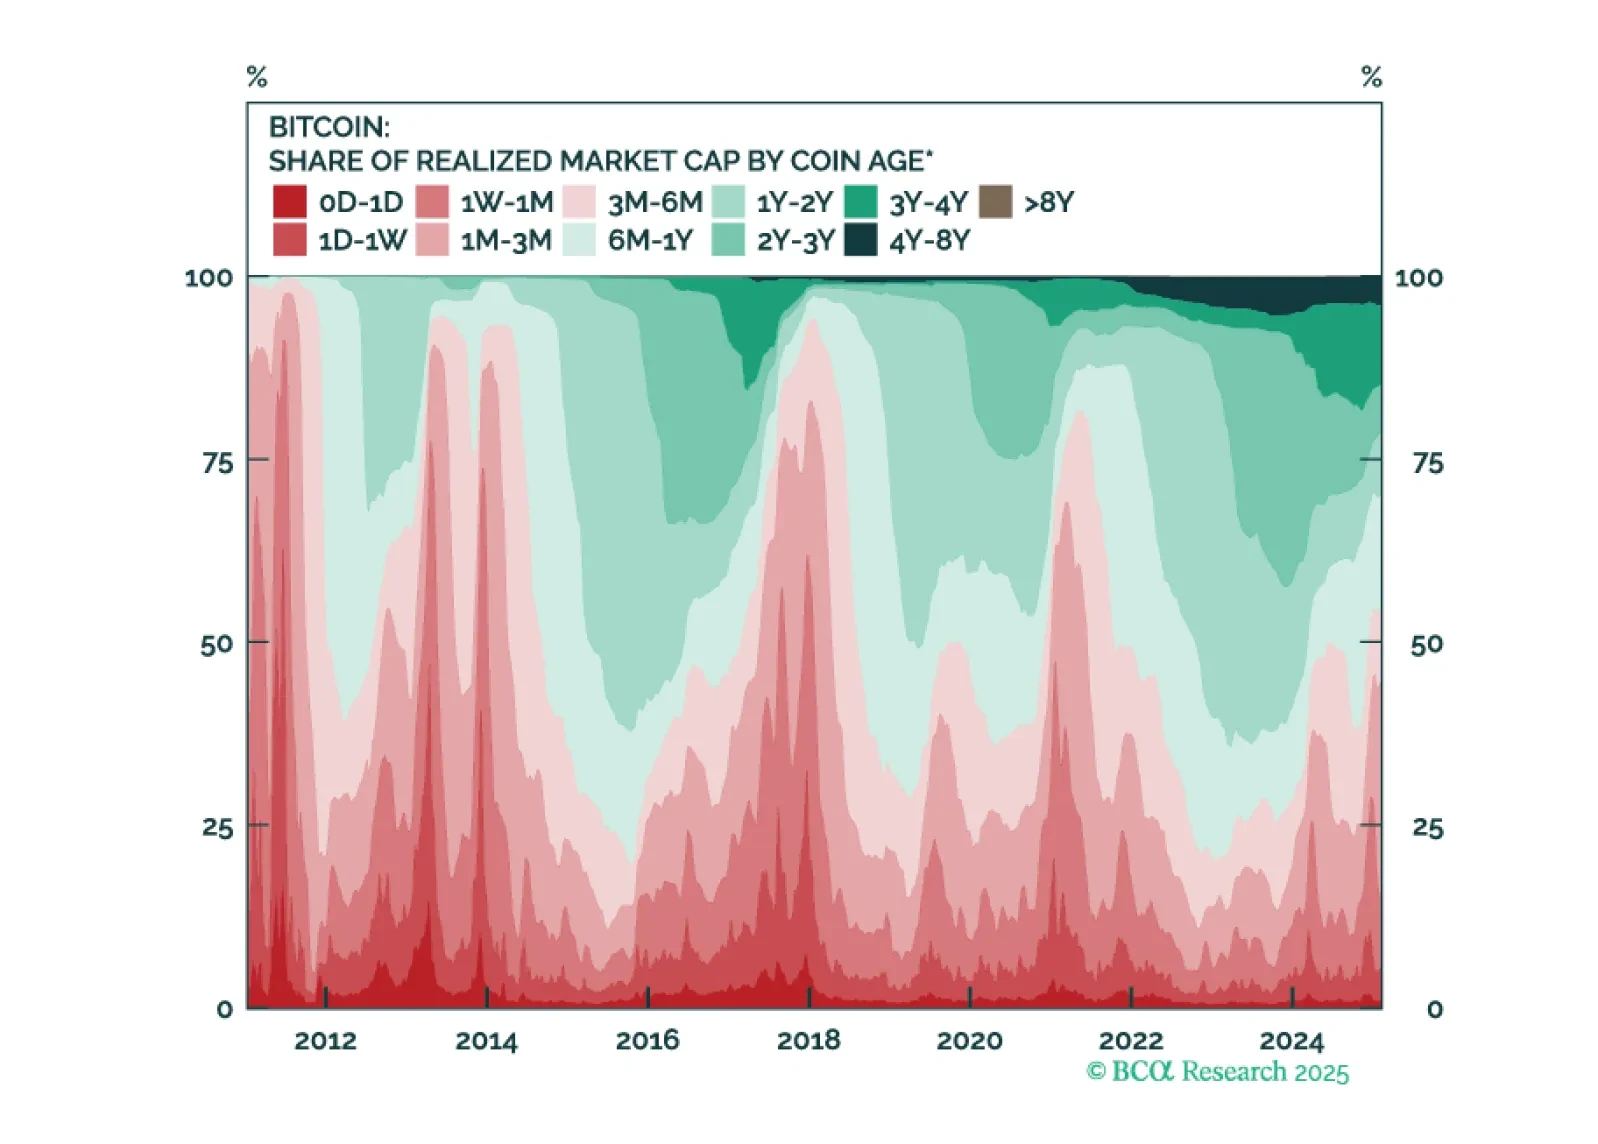
In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.
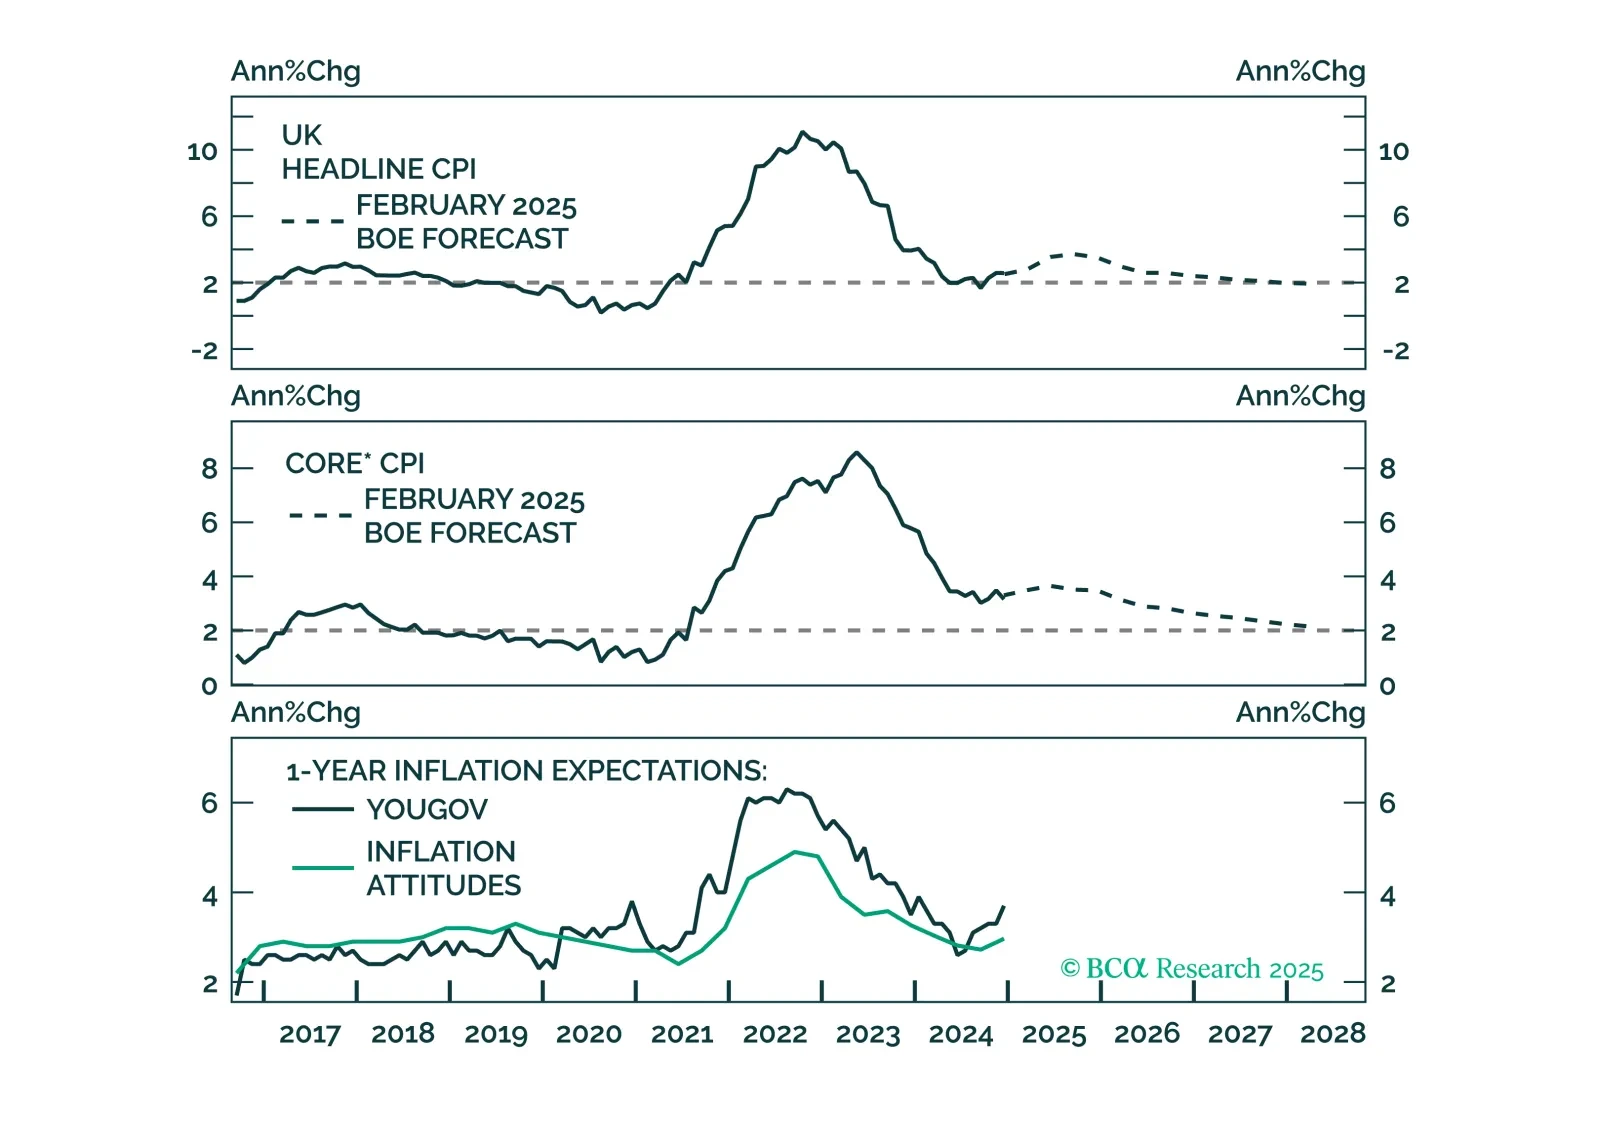
Following today’s Bank of England’s policy meeting, at which the policy rate was cut by 25 bps, we discuss our outlook for monetary policy in the UK. We expect the gradual easing to continue and discuss the investment implications for UK gilts and sterling.

This Insight is a post mortem on Canadian assets, after the threat of tariff wars.

This Insight looks at what investors should do with CAD and fixed-income assets, given the rate cut by the Bank of Canada today.