 GeoMacro
A blend of geopolitics and macro, synthesizing the new and old macro to generate alpha and identify the beta through probability-weighted market views.
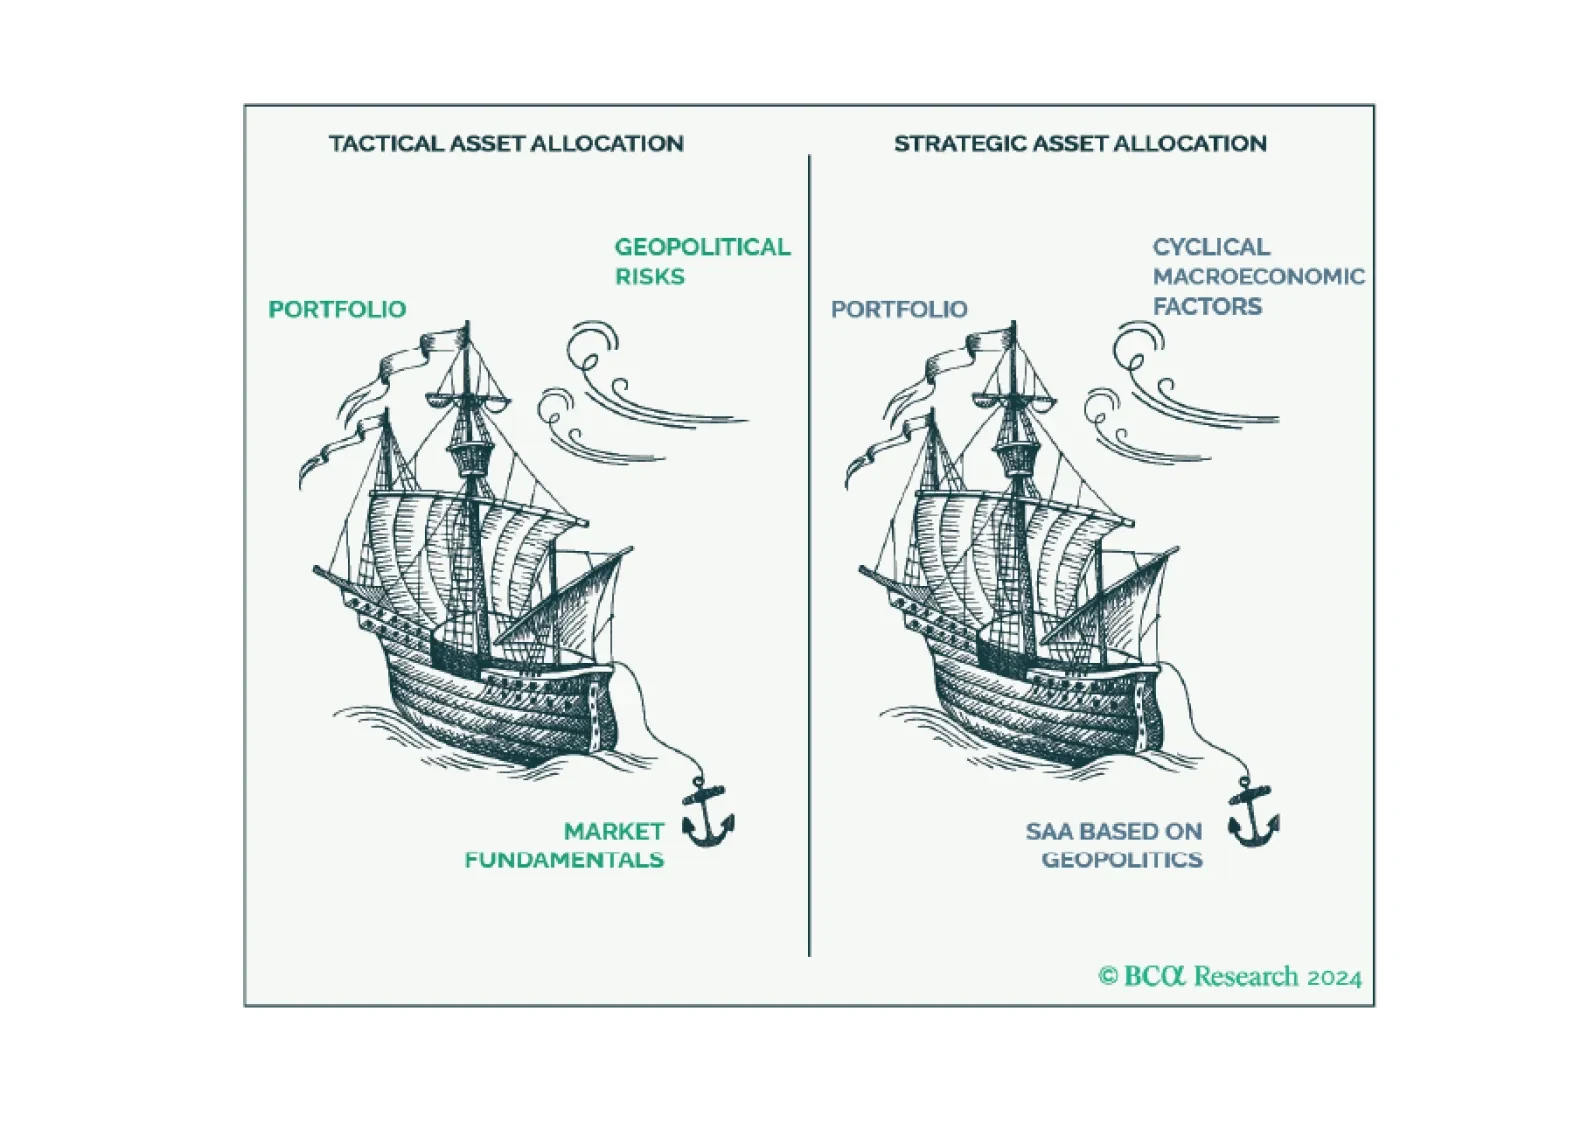
There are many different paths to macro investing. In our Volume II – The Beta Report – we present our own, which we have dubbed GeoMacro. We are very confident that we are “on to something,” but are humbled constantly by the markets, brilliant applications of different frameworks, and the confidence that, at BCA Research specifically, GeoMacro Strategy is housed in a collective of other approaches and methodologies that will greatly enhance our own capabilities. Our conclusion is simple: When it comes to searching for beta, nothing but geopolitics and politics matters. When it comes to searching for alpha, the macro fundamentals far outweigh geopolitics and politics.
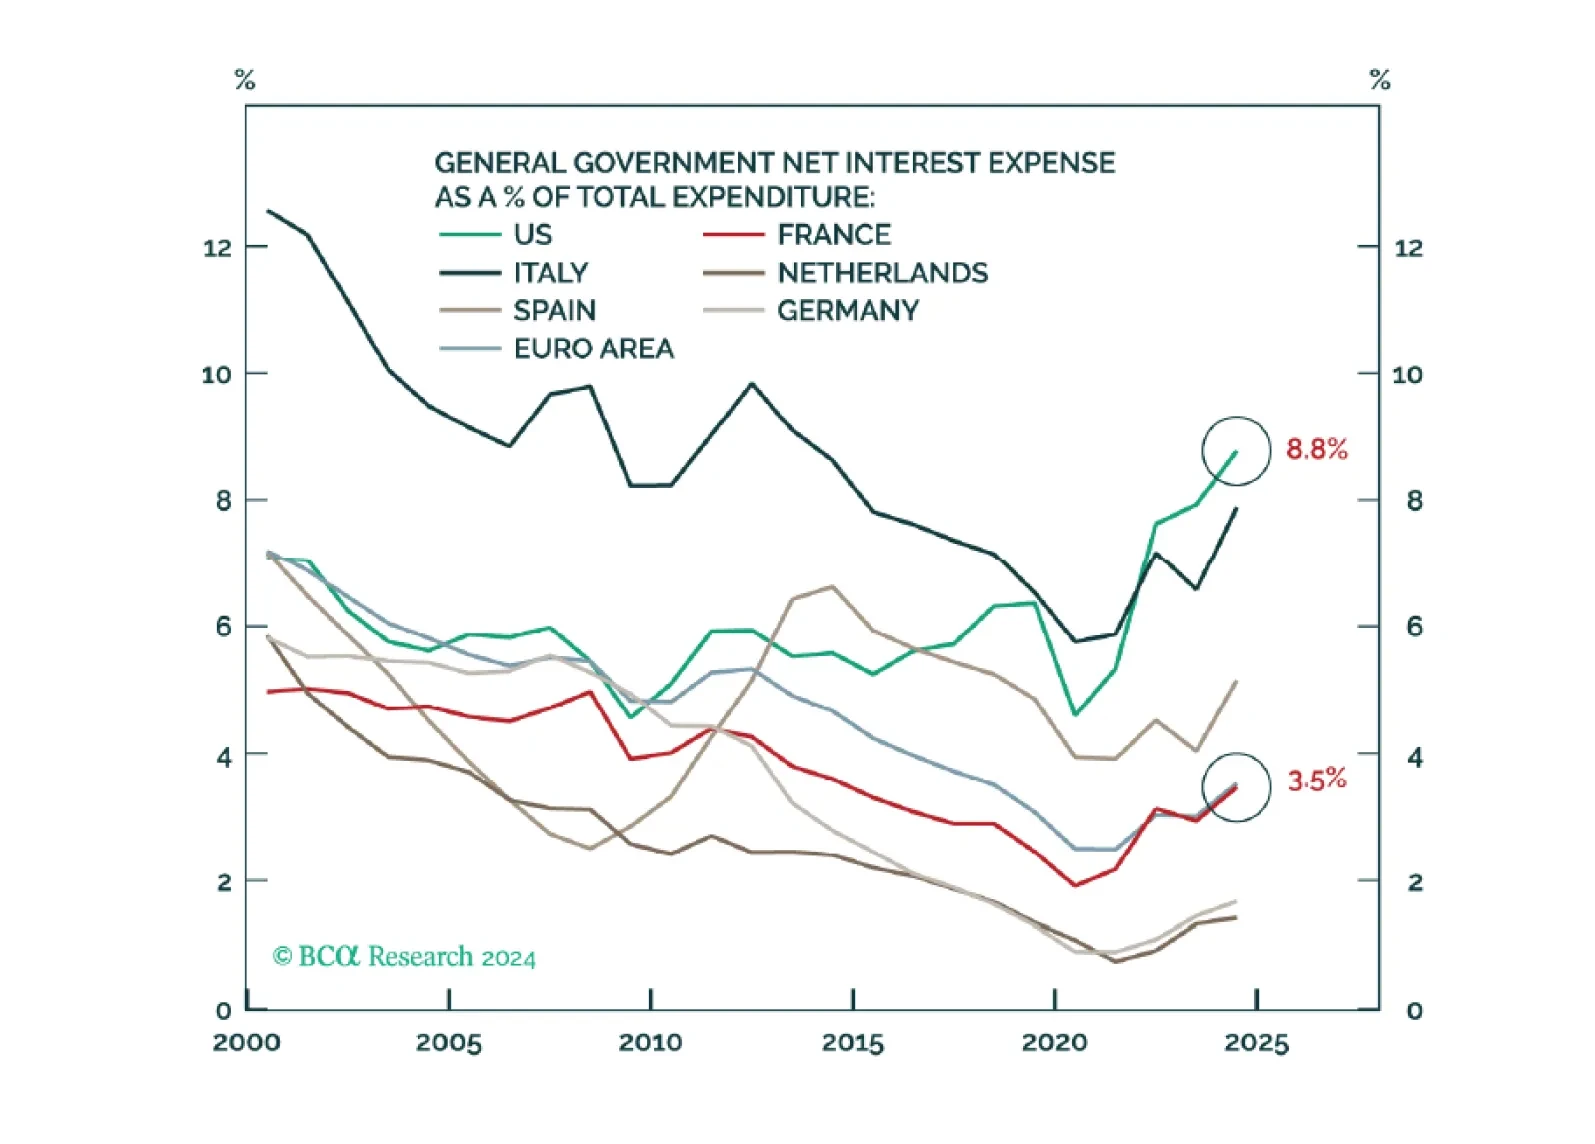
In our Volume I – The Alpha Report – we posit that the French bond market reaction is a mere amuse bouche for what is coming to the US. All year, we have warned investors that US politics could induce a bond market riot. This moment is nigh. Act accordingly!
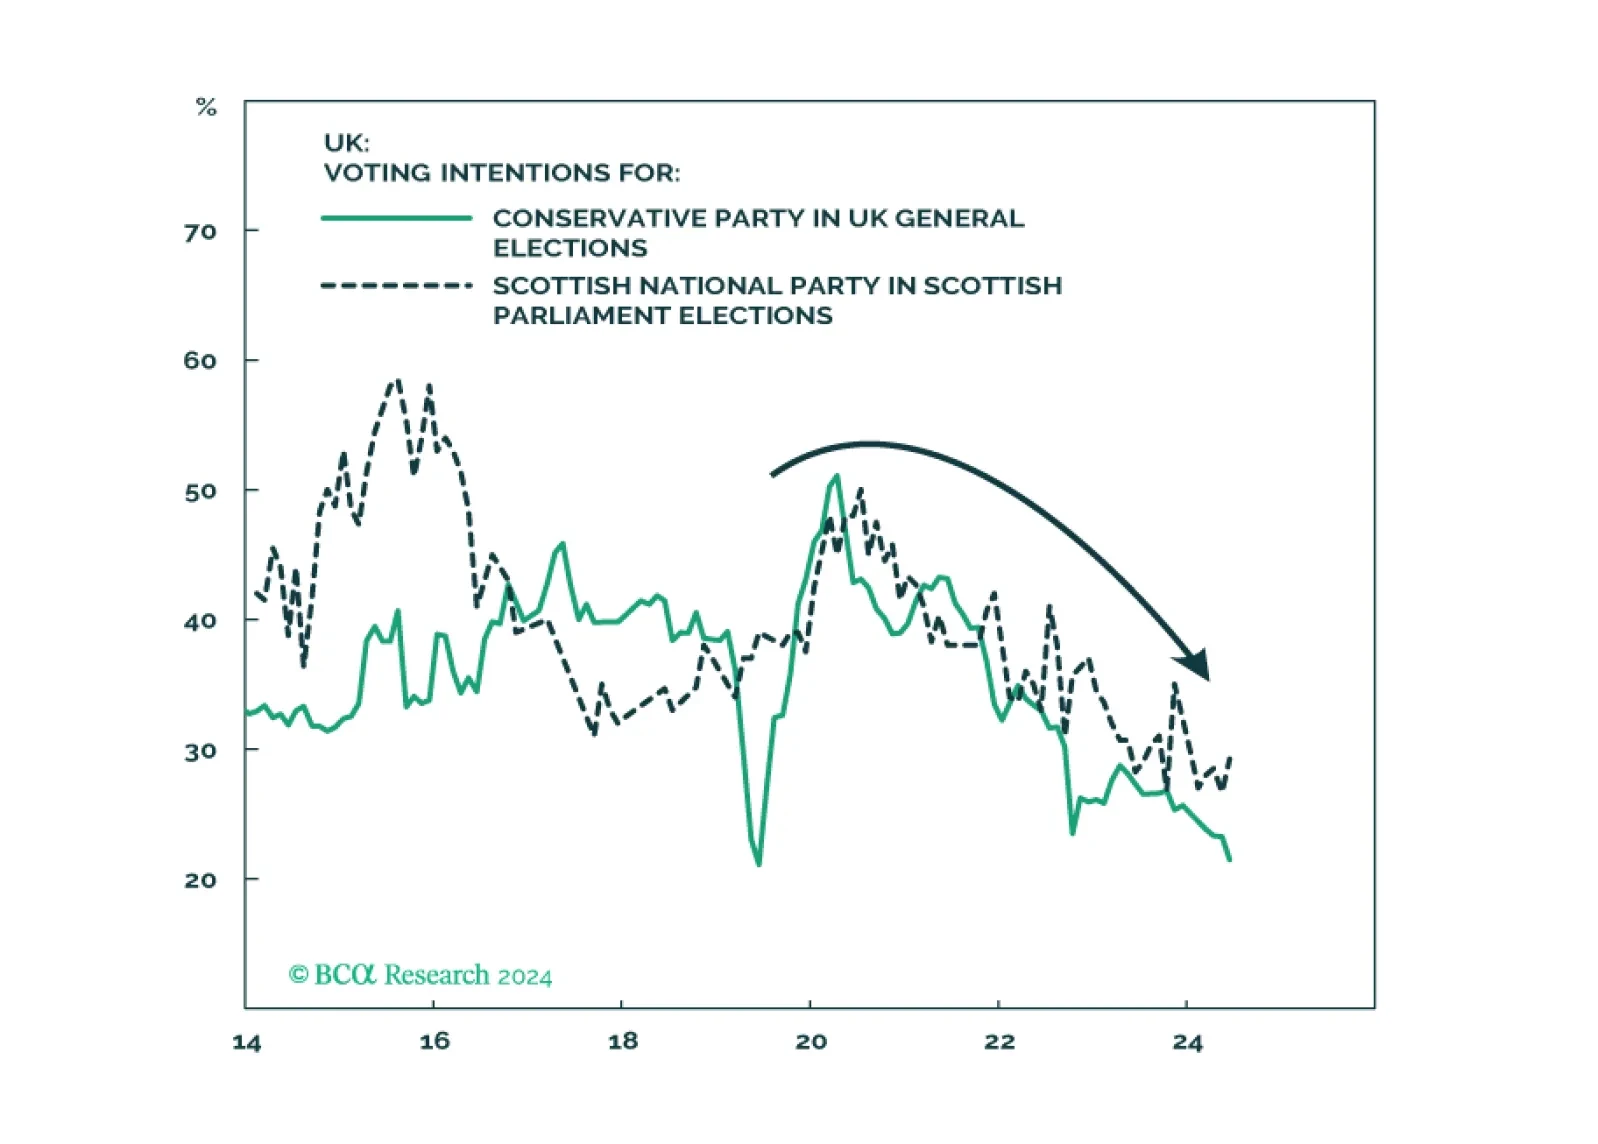

The bond market should sell off and drag stocks down on higher odds of a single-party sweep, policy uncertainty, unorthodox Trump presidency, aggressive tariffs, large tax cuts, large budget deficits, labor shortages, a fired Fed chair, and higher inflation.
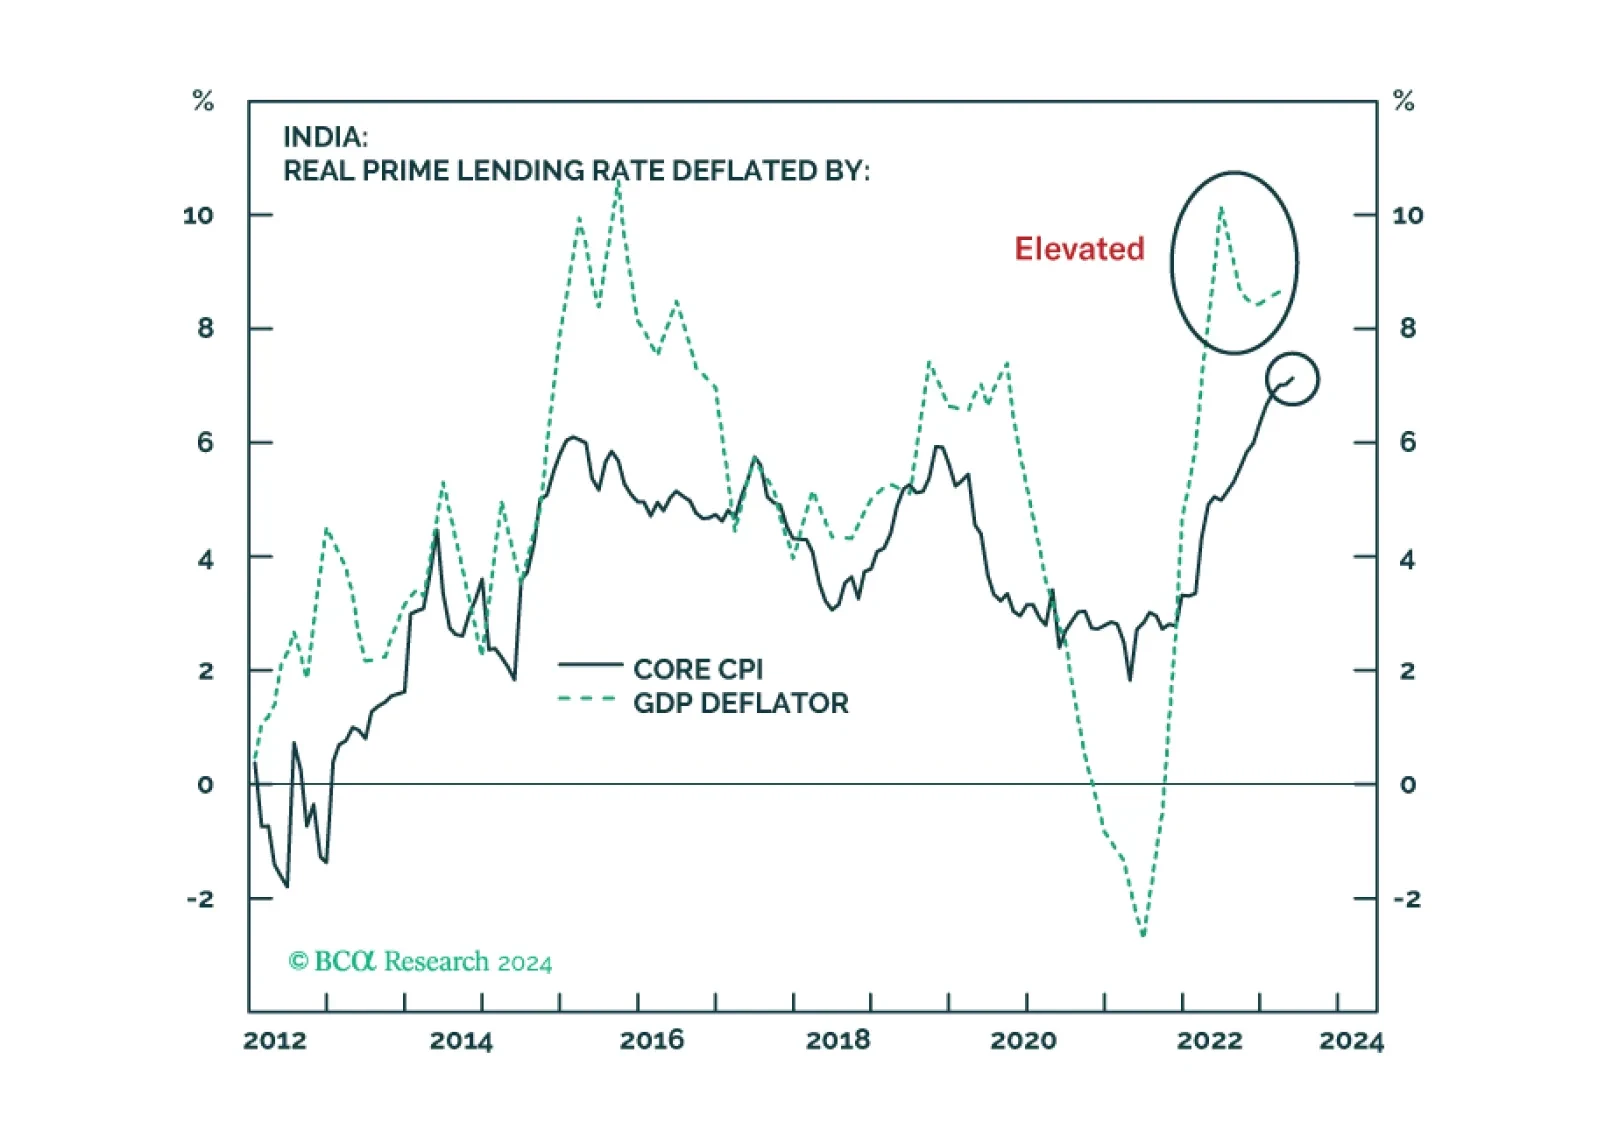
The Indian election outcome is a positive development for the country’s long-term socio-economic outlook. Indian stocks, however, remain vulnerable in the near term due to sharply slowing nominal sales and surging real borrowing costs. Indian domestic bonds, on the other hand, are a buy.


European assets are selling off as investors panic about the upcoming French election. Is this panic justified, and if so, for how long?
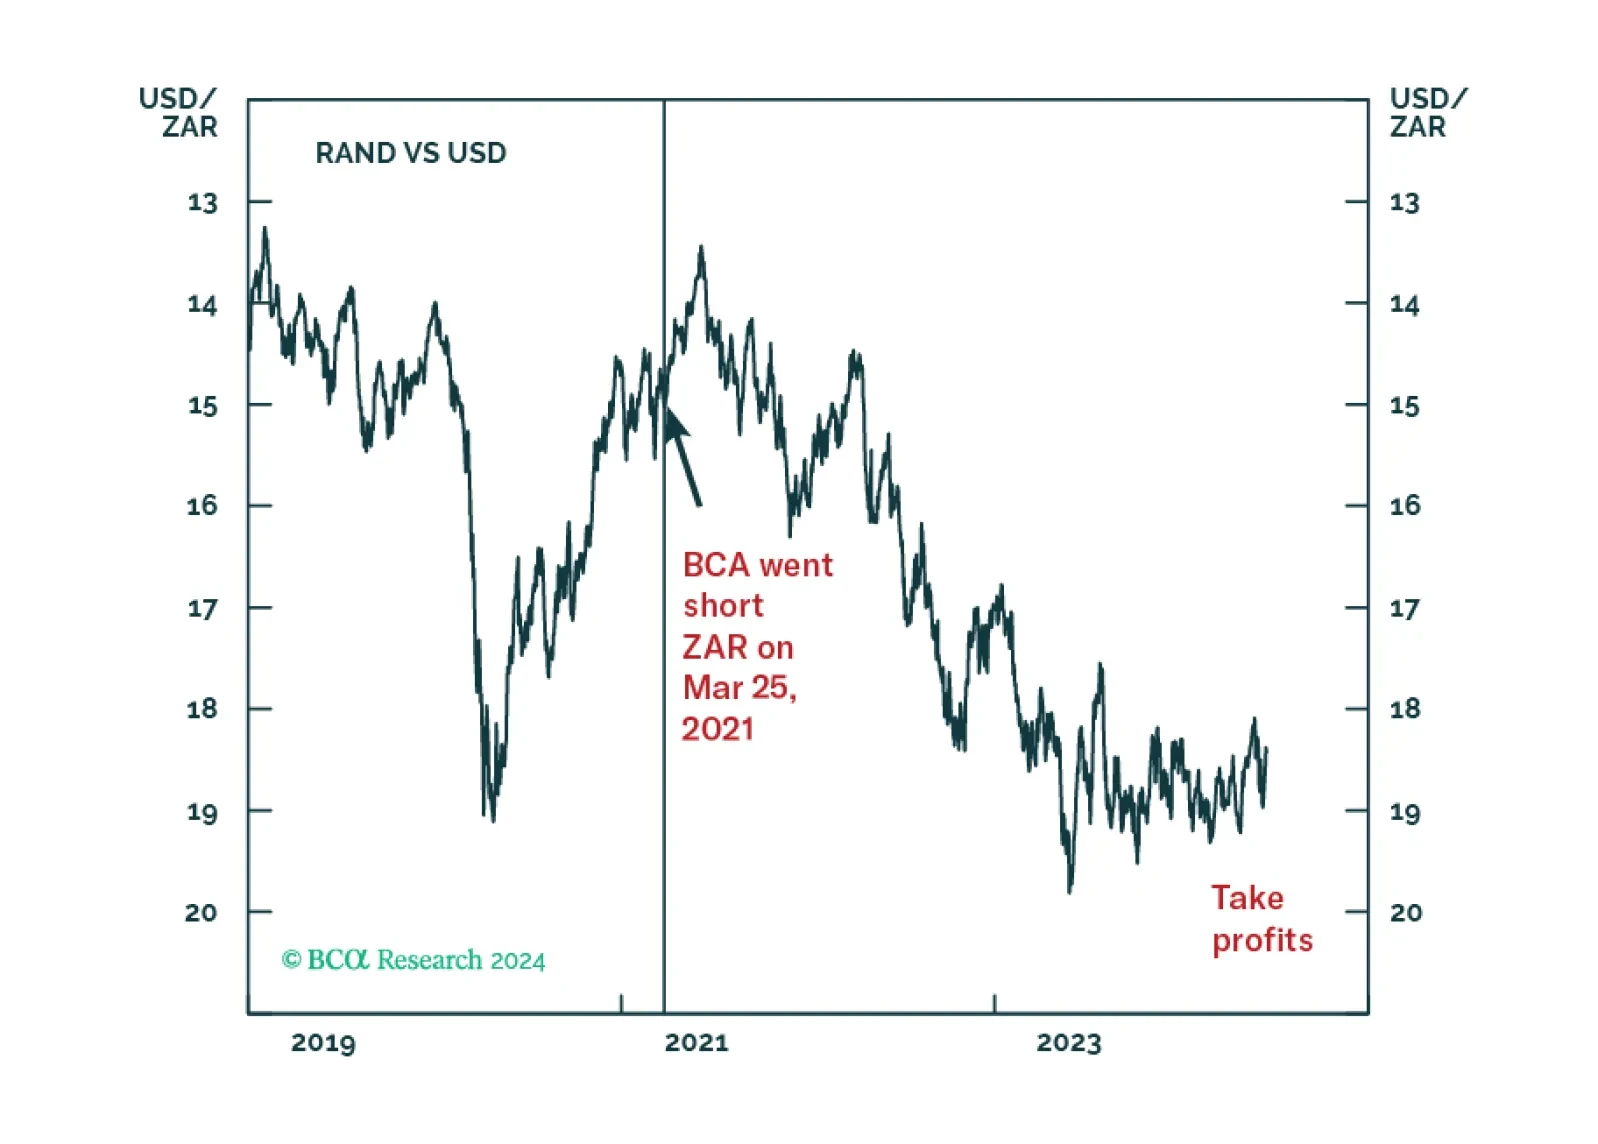

Europe did not witness a major policy reversal. Inflationary pressures are coming down, enabling the ECB to cut rates and European states to maintain soft budgets. Geopolitical challenges ensure that European parties continue to cooperate on national defense, economic security, and energy security.
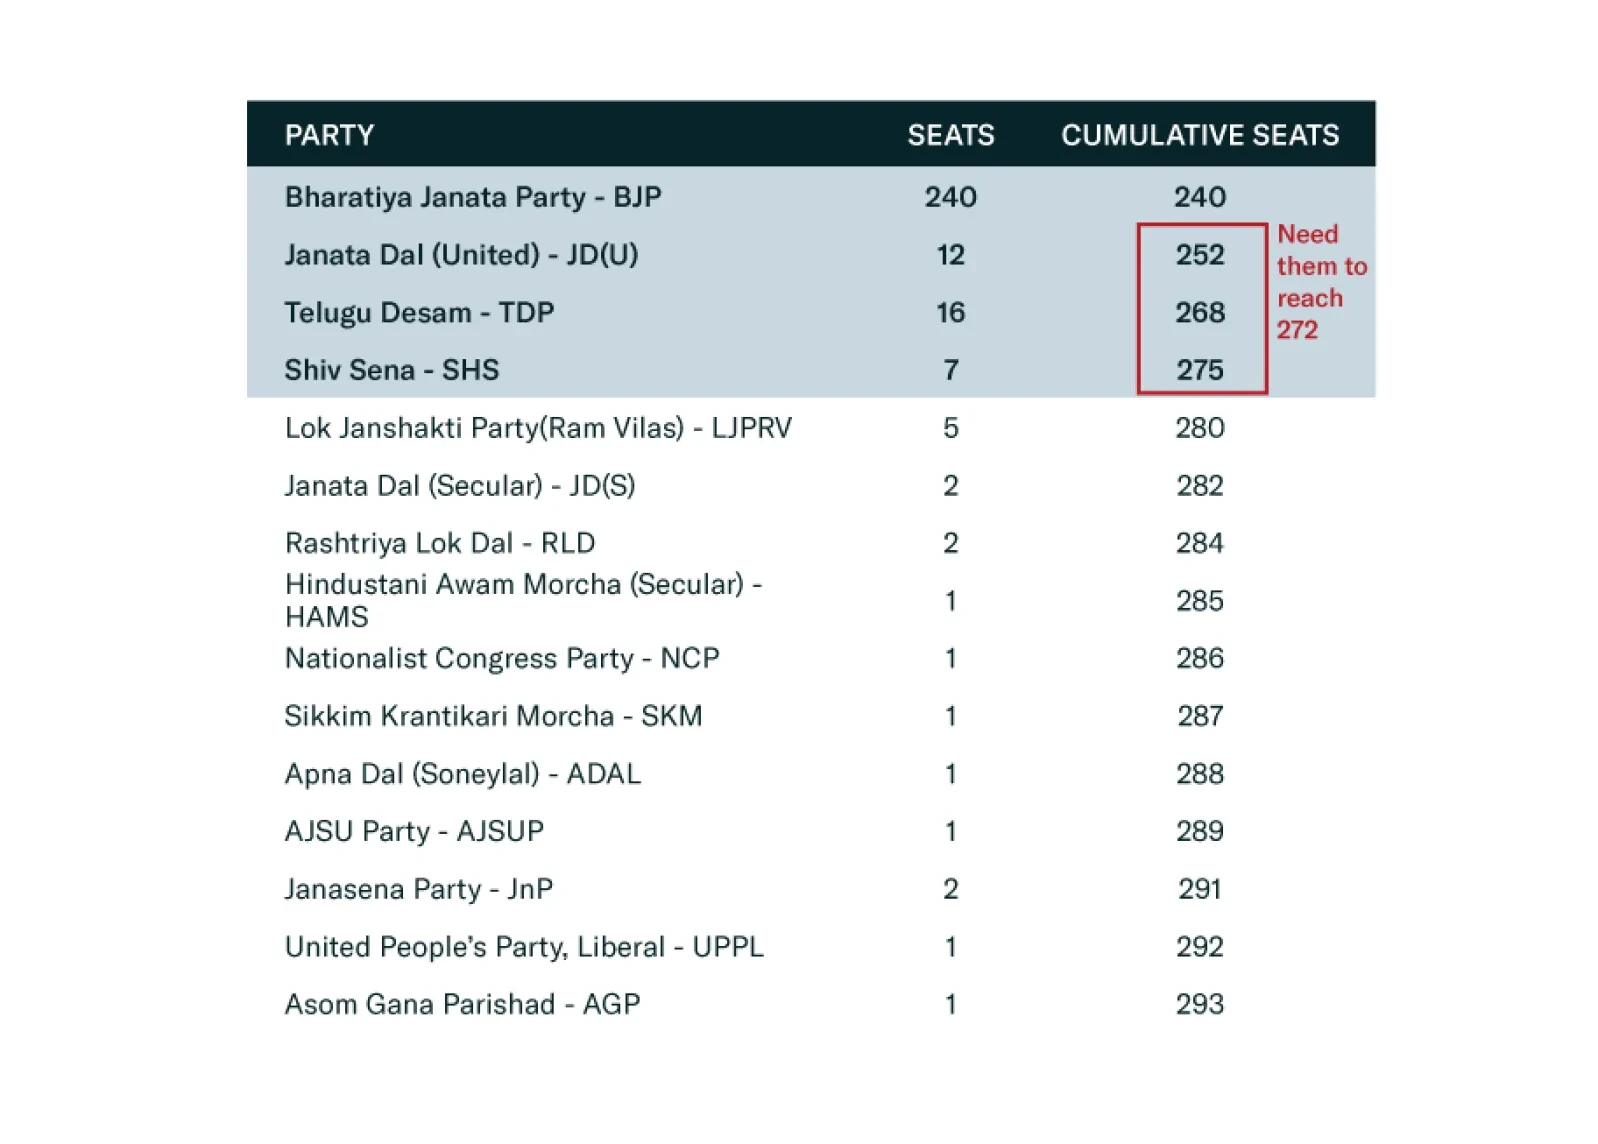
Prime Minister Narendra Modi won a third term and will become the third longest-serving prime minister of India. While investors responded negatively to the BJP’s loss of an outright majority, Modi and the NDA will continue to perpetuate the reforms they have already put into motion. The result also affirms that Indian democracy continues to thrive, contrary to the narrative that Modi had formed an authoritarian grip on the country, a view we always rejected.