Latest from BCA Research

This week, our three screeners cover: Favoring European equities over US equities, cybersecurity stocks, and large caps with large moves in their BCA Score.
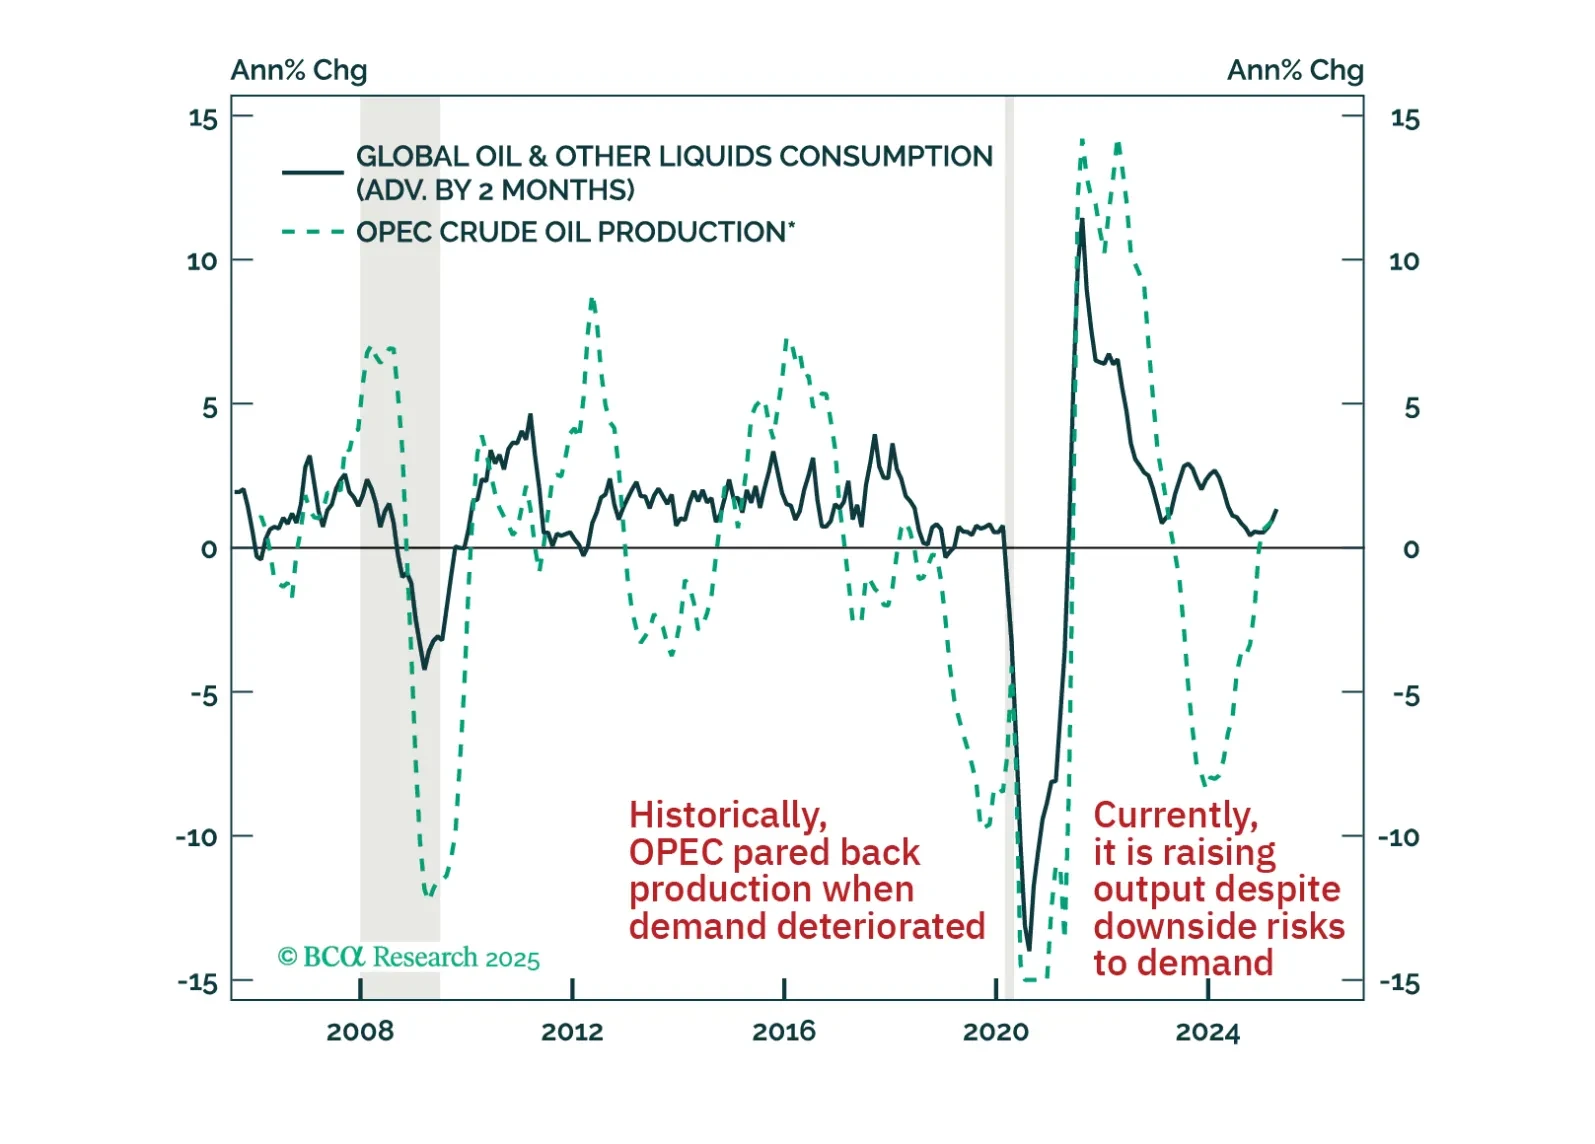
Oil has borne the brunt of the year-to-date deterioration in cyclically sensitive financial assets. It is a key underperformer both within the commodity space and among global risk assets. This underperformance underscores that in addition to the trade war-induced headwind to demand, bearish supply-side developments are also weighing down on crude prices. As we discuss in this report, these dynamics will likely continue exerting downside pressure on oil prices over the coming weeks and months.
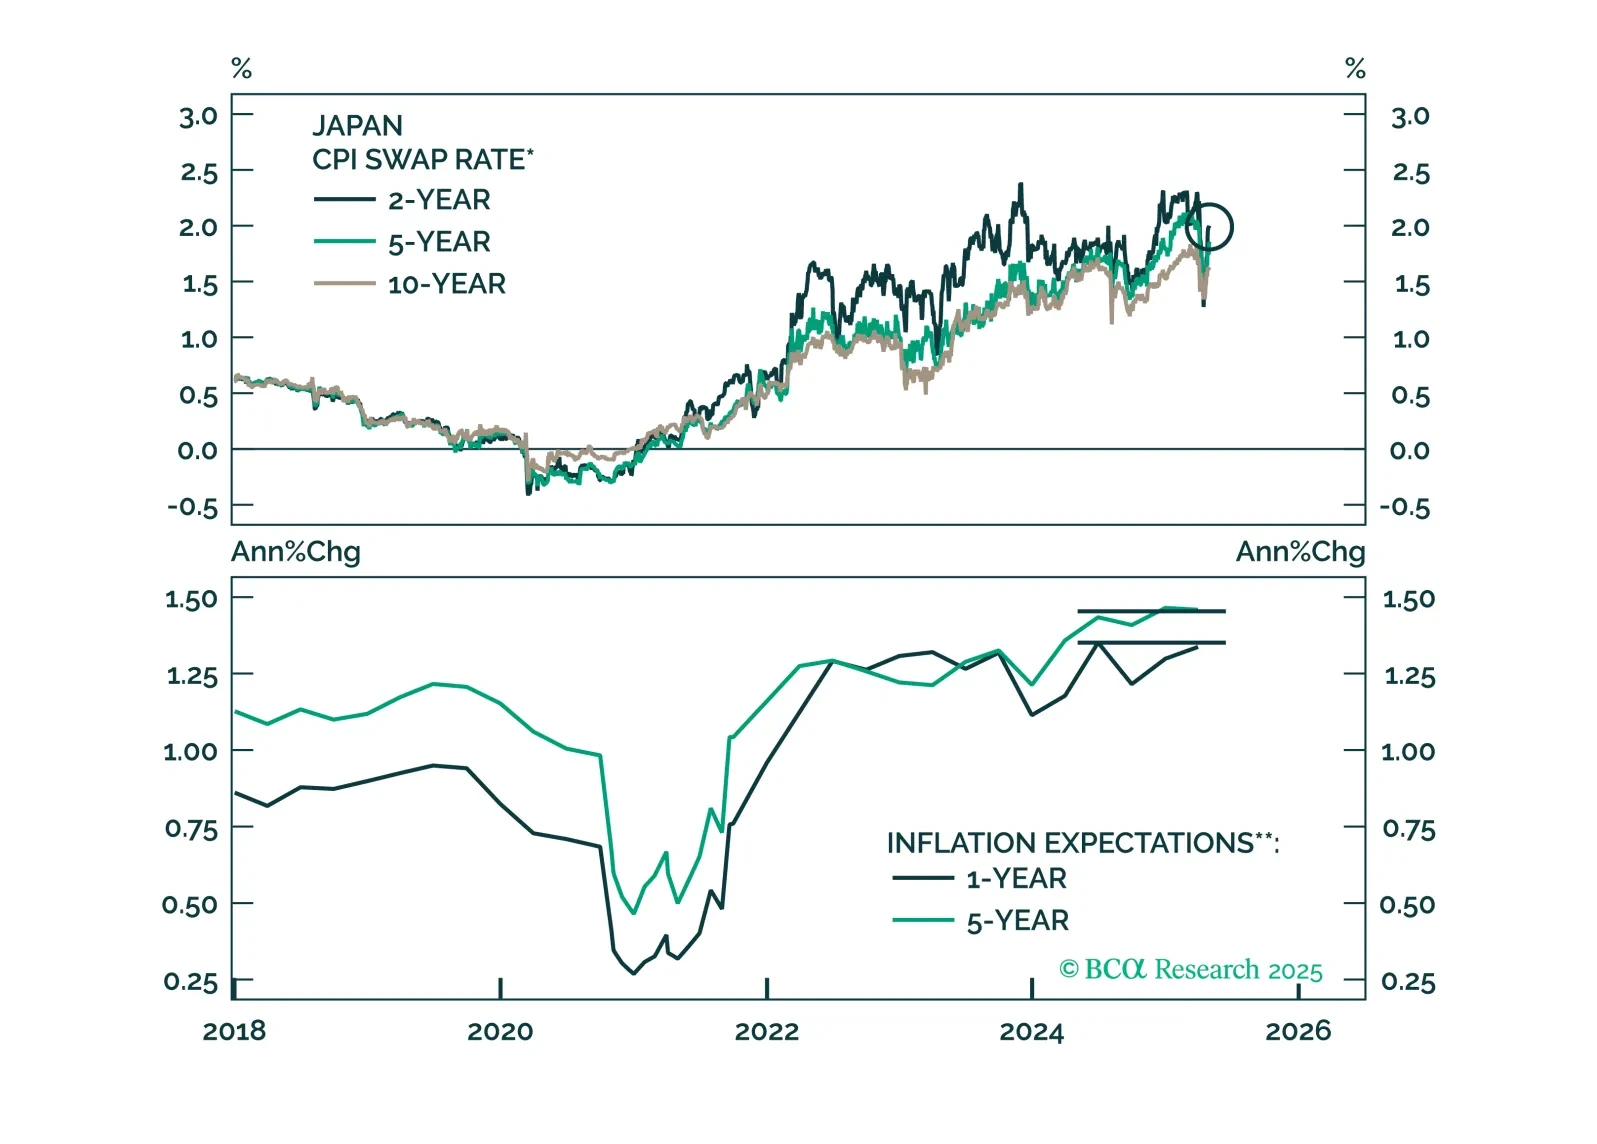
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
This year’s corporate bond sell off has hit high-yield more than investment grade, and high-yield spreads have turned relatively more attractive as a result.
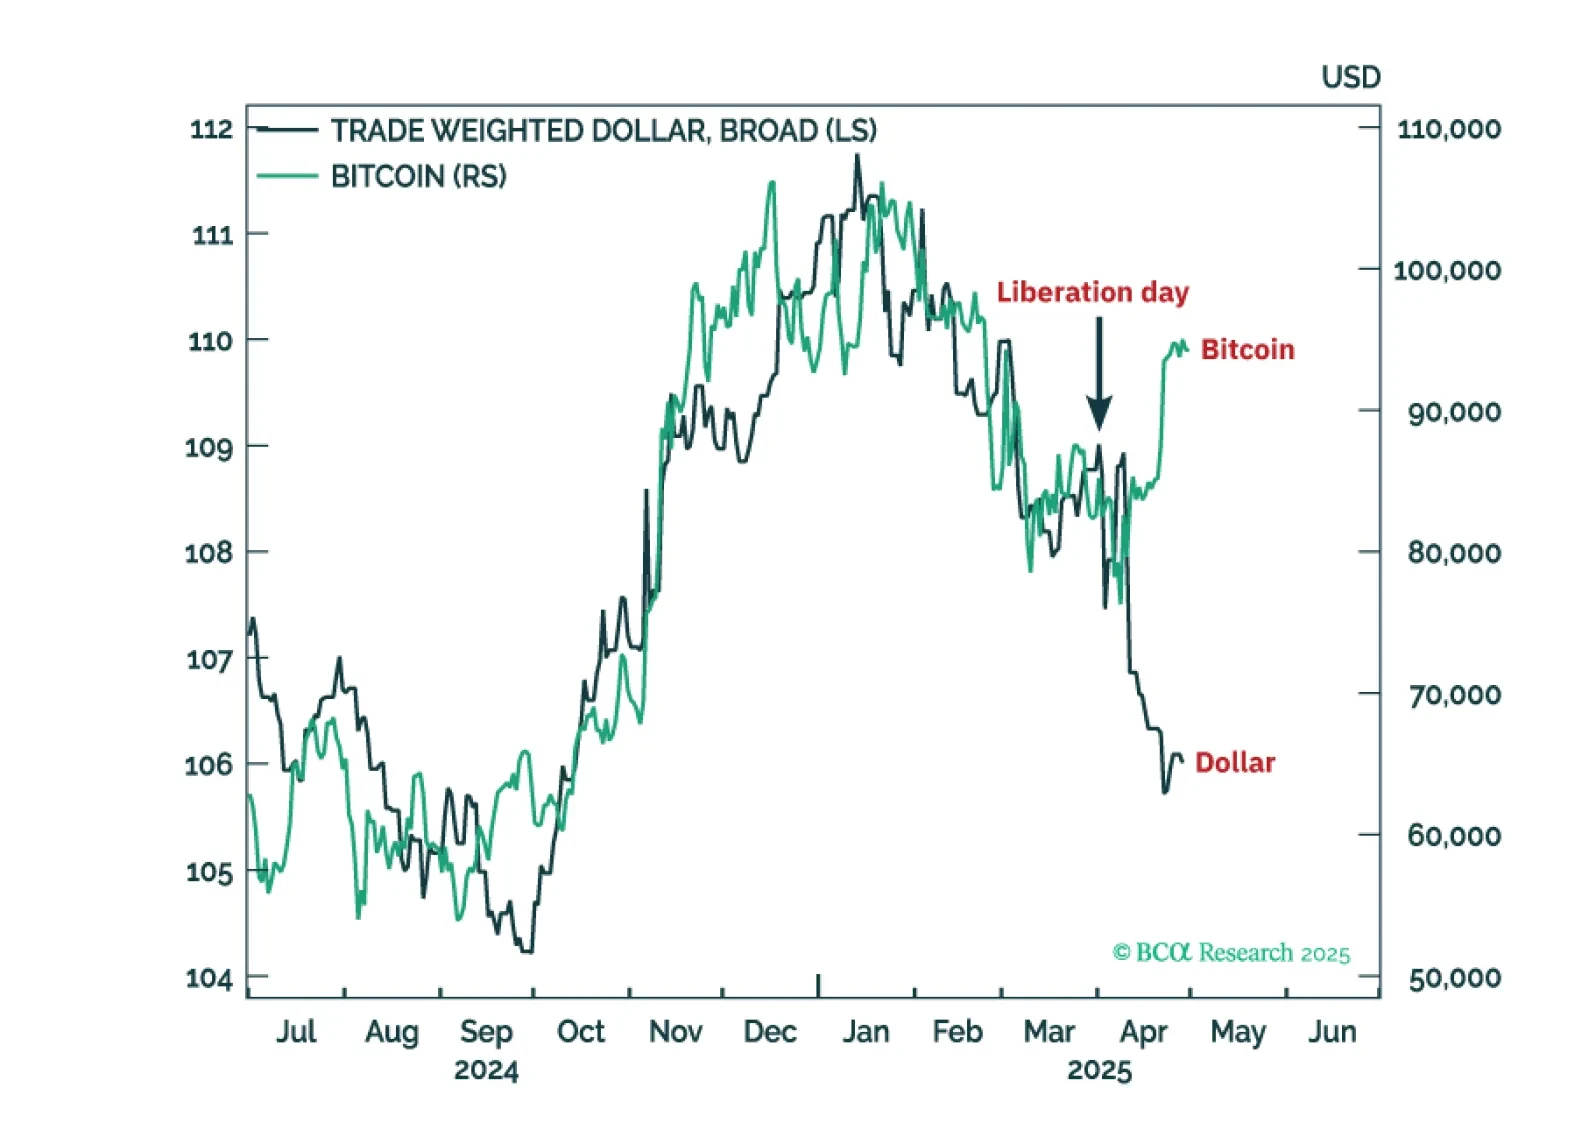
If Trump’s tariffs are ‘America's Brexit’, then UK gilts will recoup ten years of underperformance versus US T-bonds. Meanwhile, as the AI bubble fully deflates, Europe’s stock market valuation versus the US will rerate by about 25 percent. The big ‘currency’ winner of the structural exodus from the US dollar will be bitcoin. Plus: a trade for the next four weeks is to go tactically long USD/CHF.
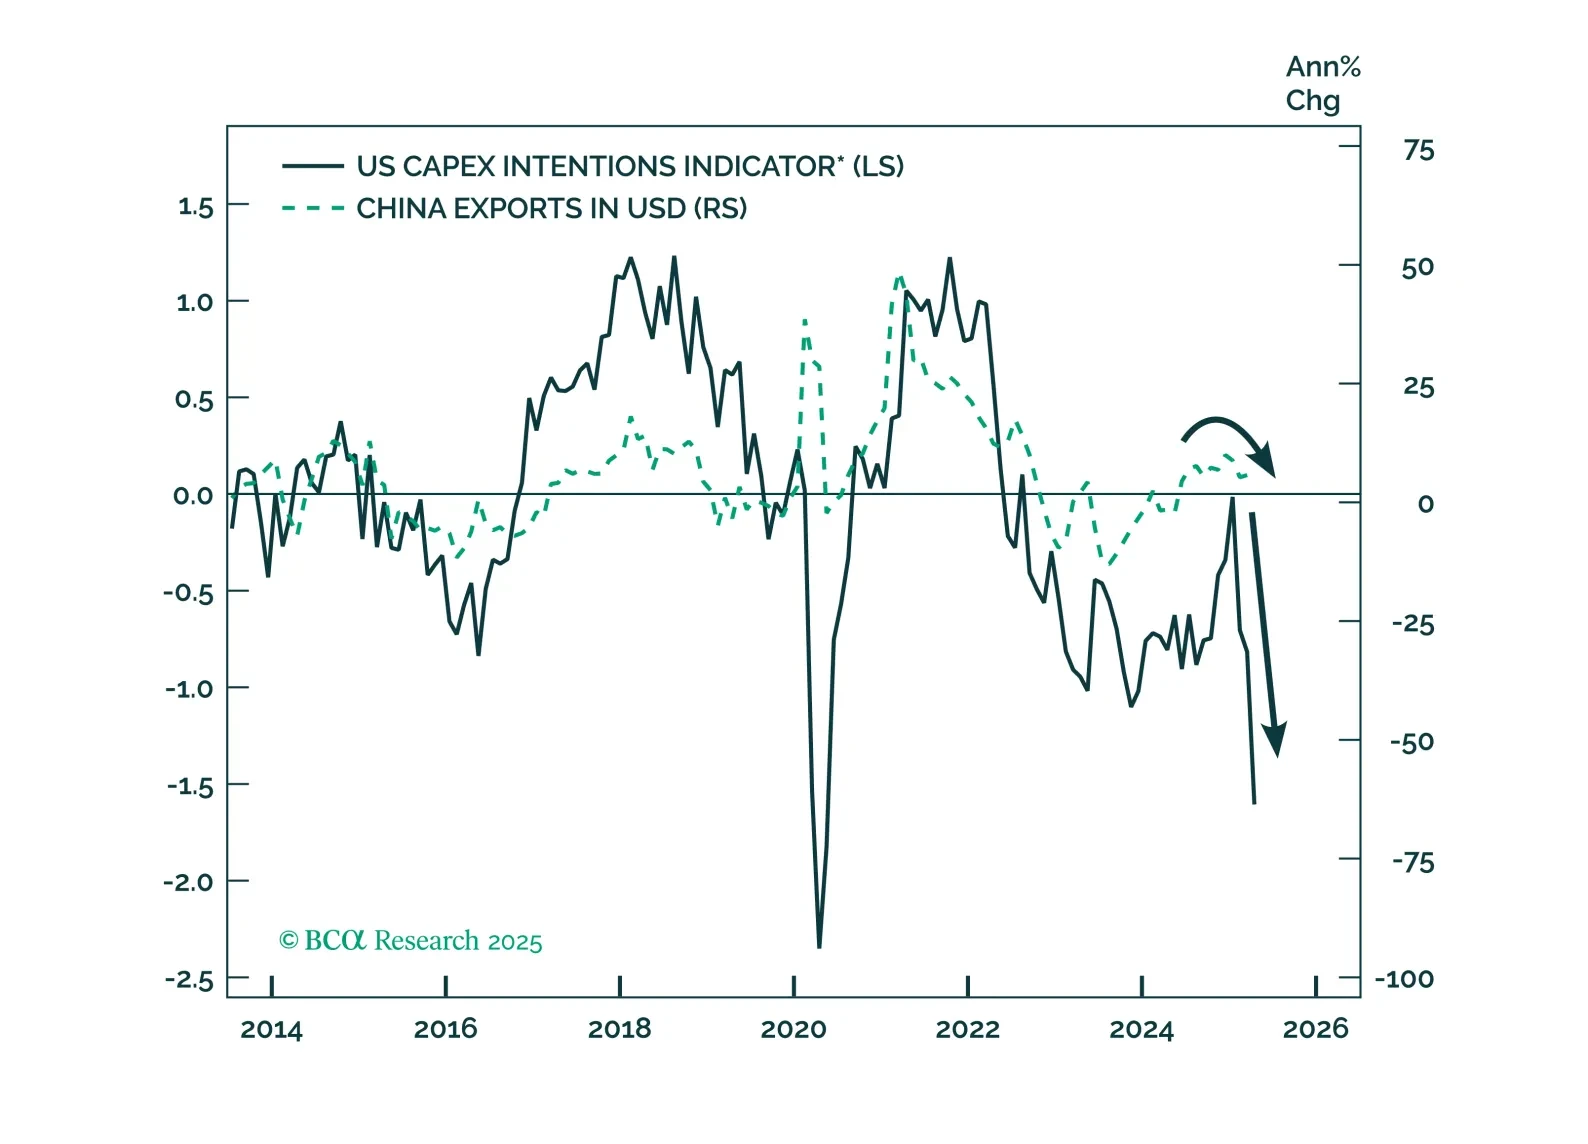
Despite marginal de-escalation in tariffs between the US and China, a sustainable trade agreement remains elusive. In the meantime, economic damage continues to mount, and Chinese equities have yet to fully price in the tariff-induced growth deterioration.
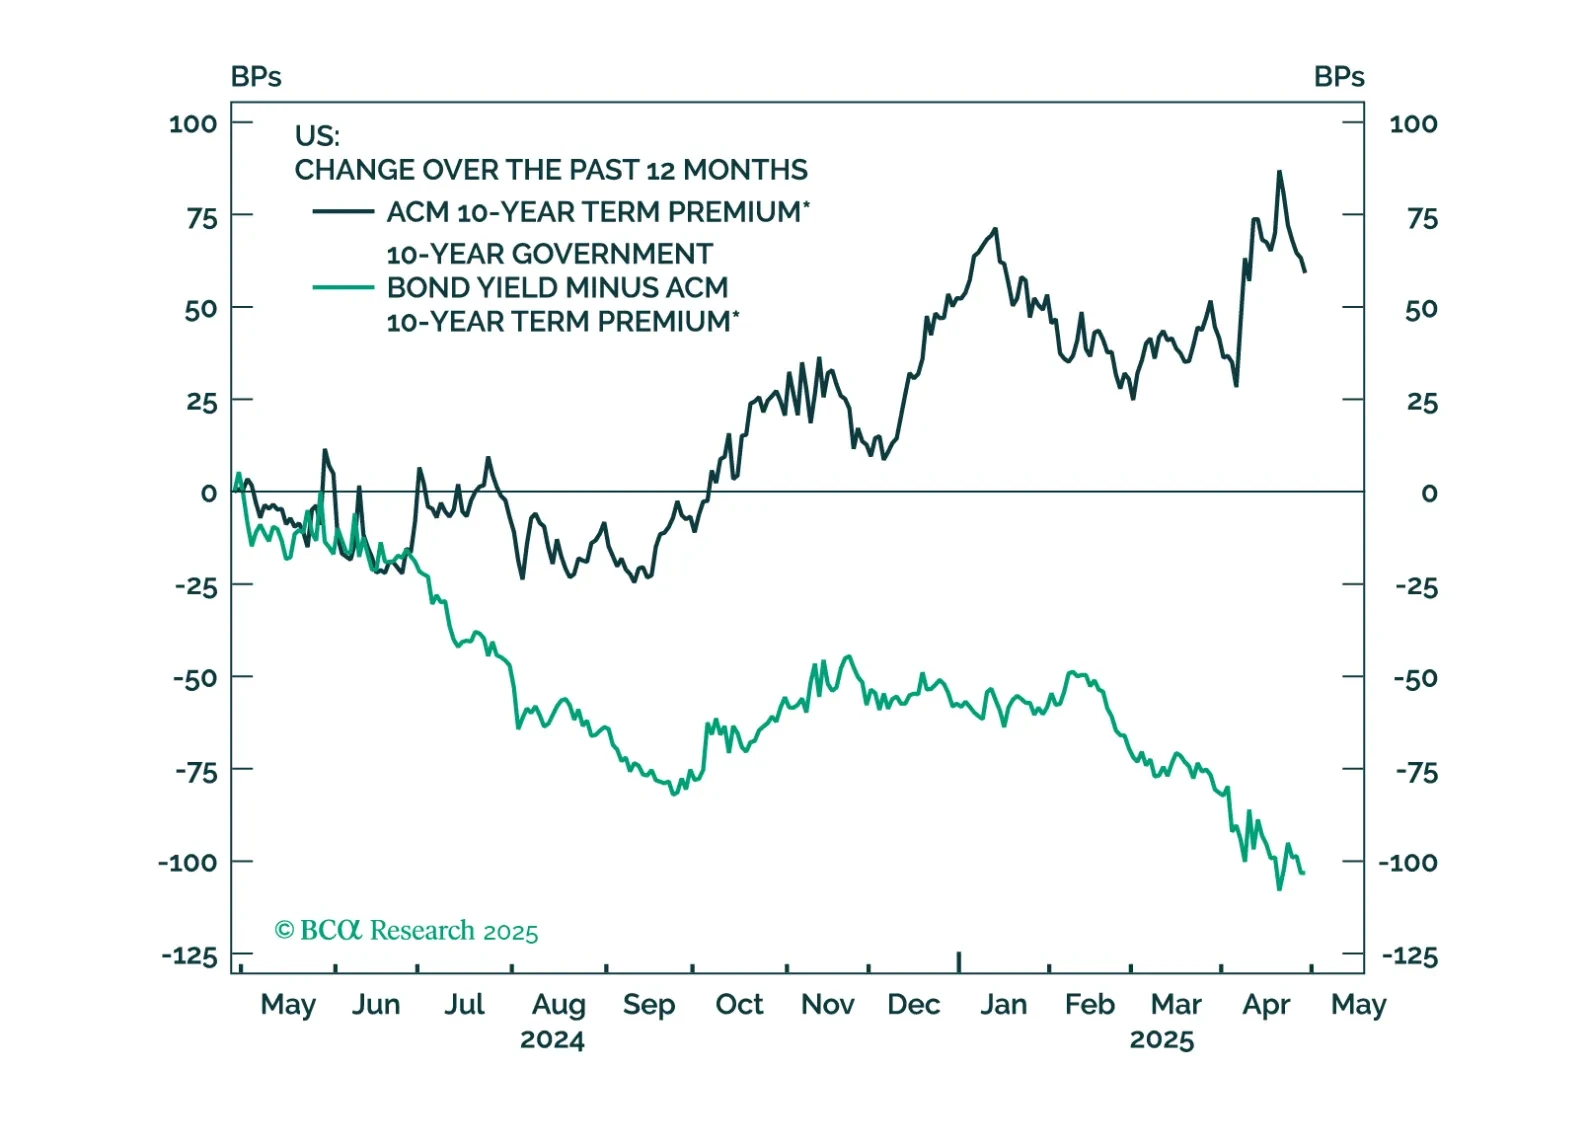
While most investors spent the month of April frantically refreshing their Twitter feeds for the next tariff announcement, we reiterate our stance that details on tariffs should be left to day traders. Long-term investors should be focused on the bigger story: the triple selloff in US stocks, bonds and the dollar. Foreign investors perceive that there has been a deterioration in governance in the US, and are requiring a higher risk premium from America. While Trump has walked back some of his most aggressive rhetoric, business investment will not resume unless we get clarity in policy. We continue to recommend a defensive stance, but downgrade duration from overweight to neutral to protect ourselves against shocks to the term premium. We also introduce Bitcoin to ours asset coverage. We upgrade it from underweight to neutral.
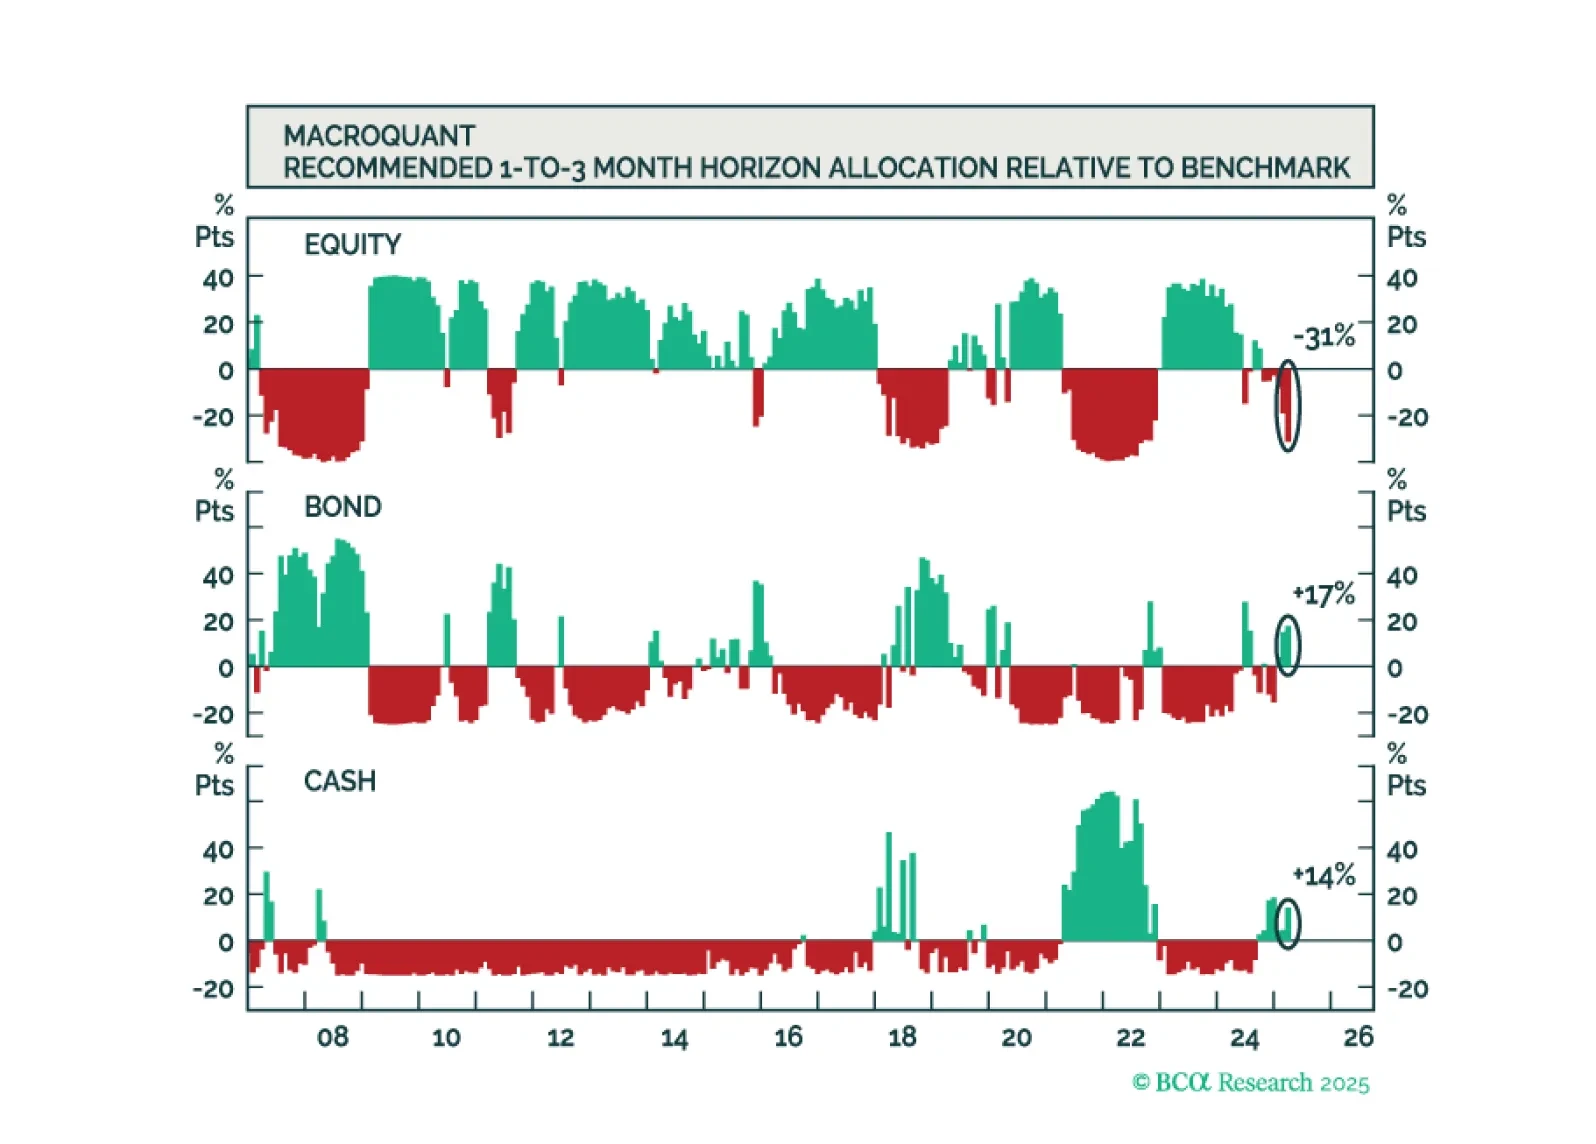
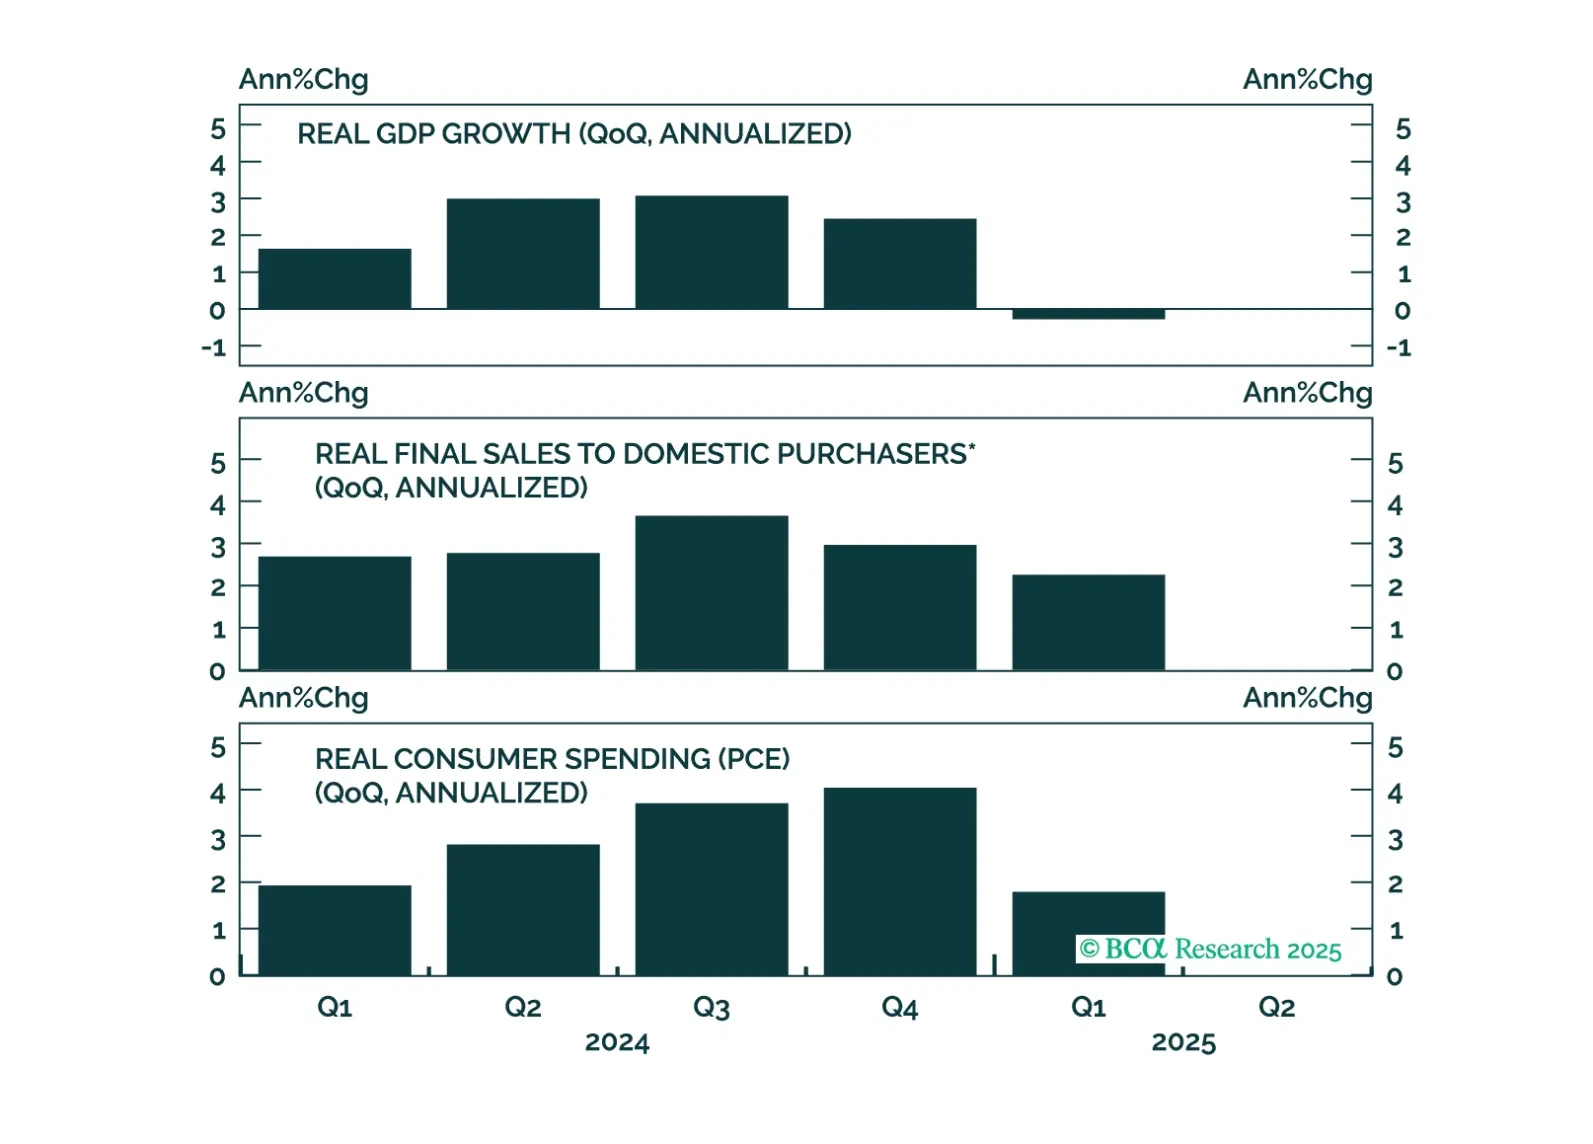
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.
MacroQuant sees the risks to US growth as being to the downside and the risks to inflation as being to the upside. Such a stagflationary brew justifies an underweight on stocks.