Latest from BCA Research
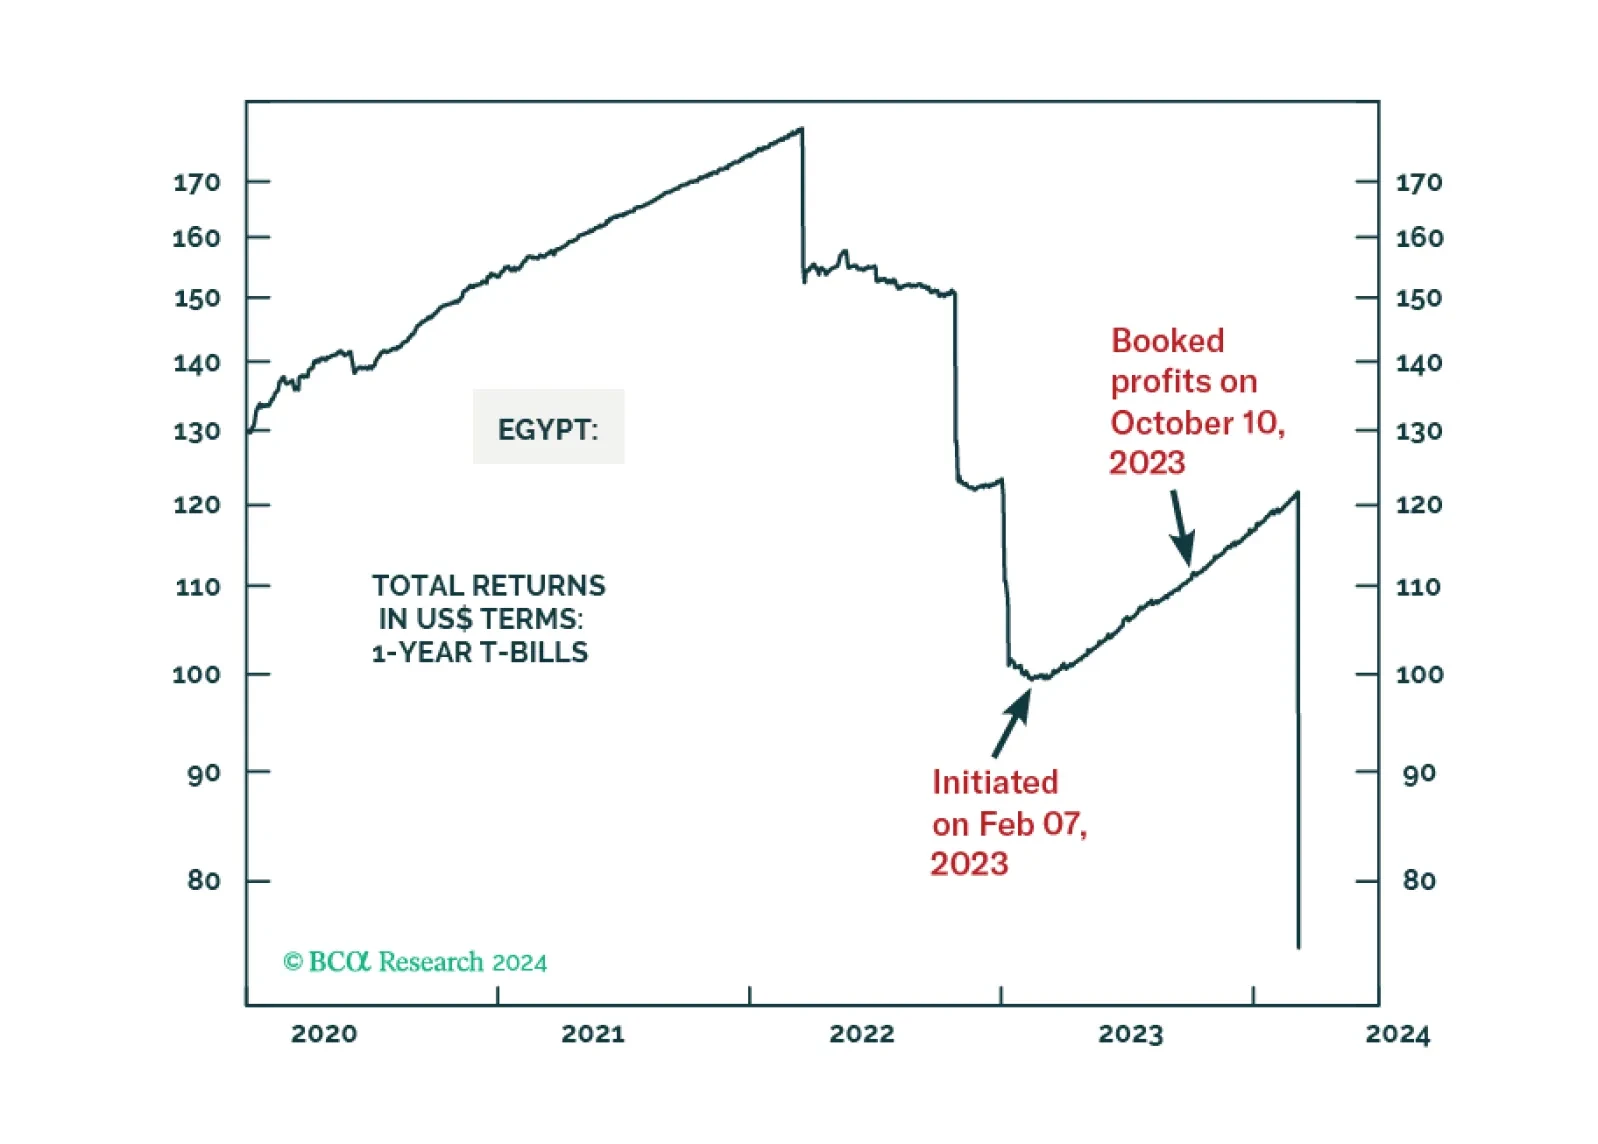
After the significant devaluation of the pound, we now recommend going into Egyptian assets again.
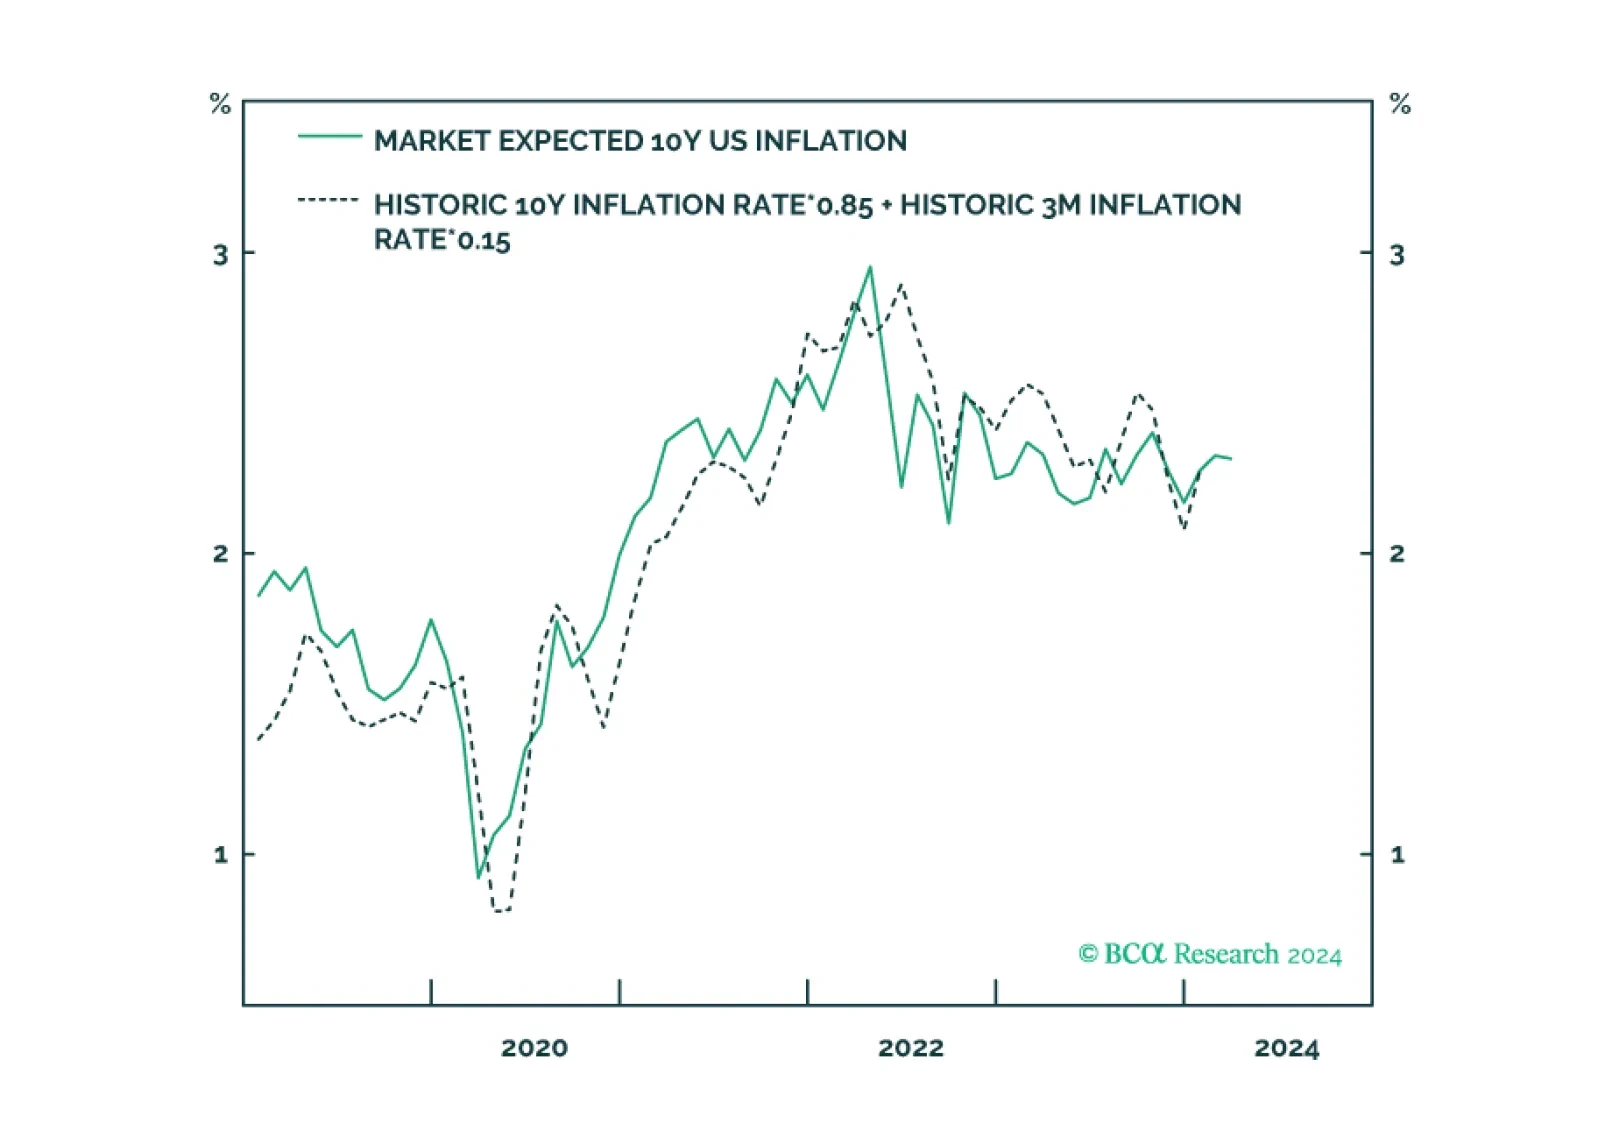
Expected inflation has surged to its highest level in a year. This has surprised many people, but expected inflation is behaving just as expected. Expected inflation is not a prophecy, it is just a mathematical function of delivered inflation. We discuss what this means for central banks in the US, UK, euro area, and Japan. Plus: bitcoin’s structural uptrend to $100,000+ is still intact.
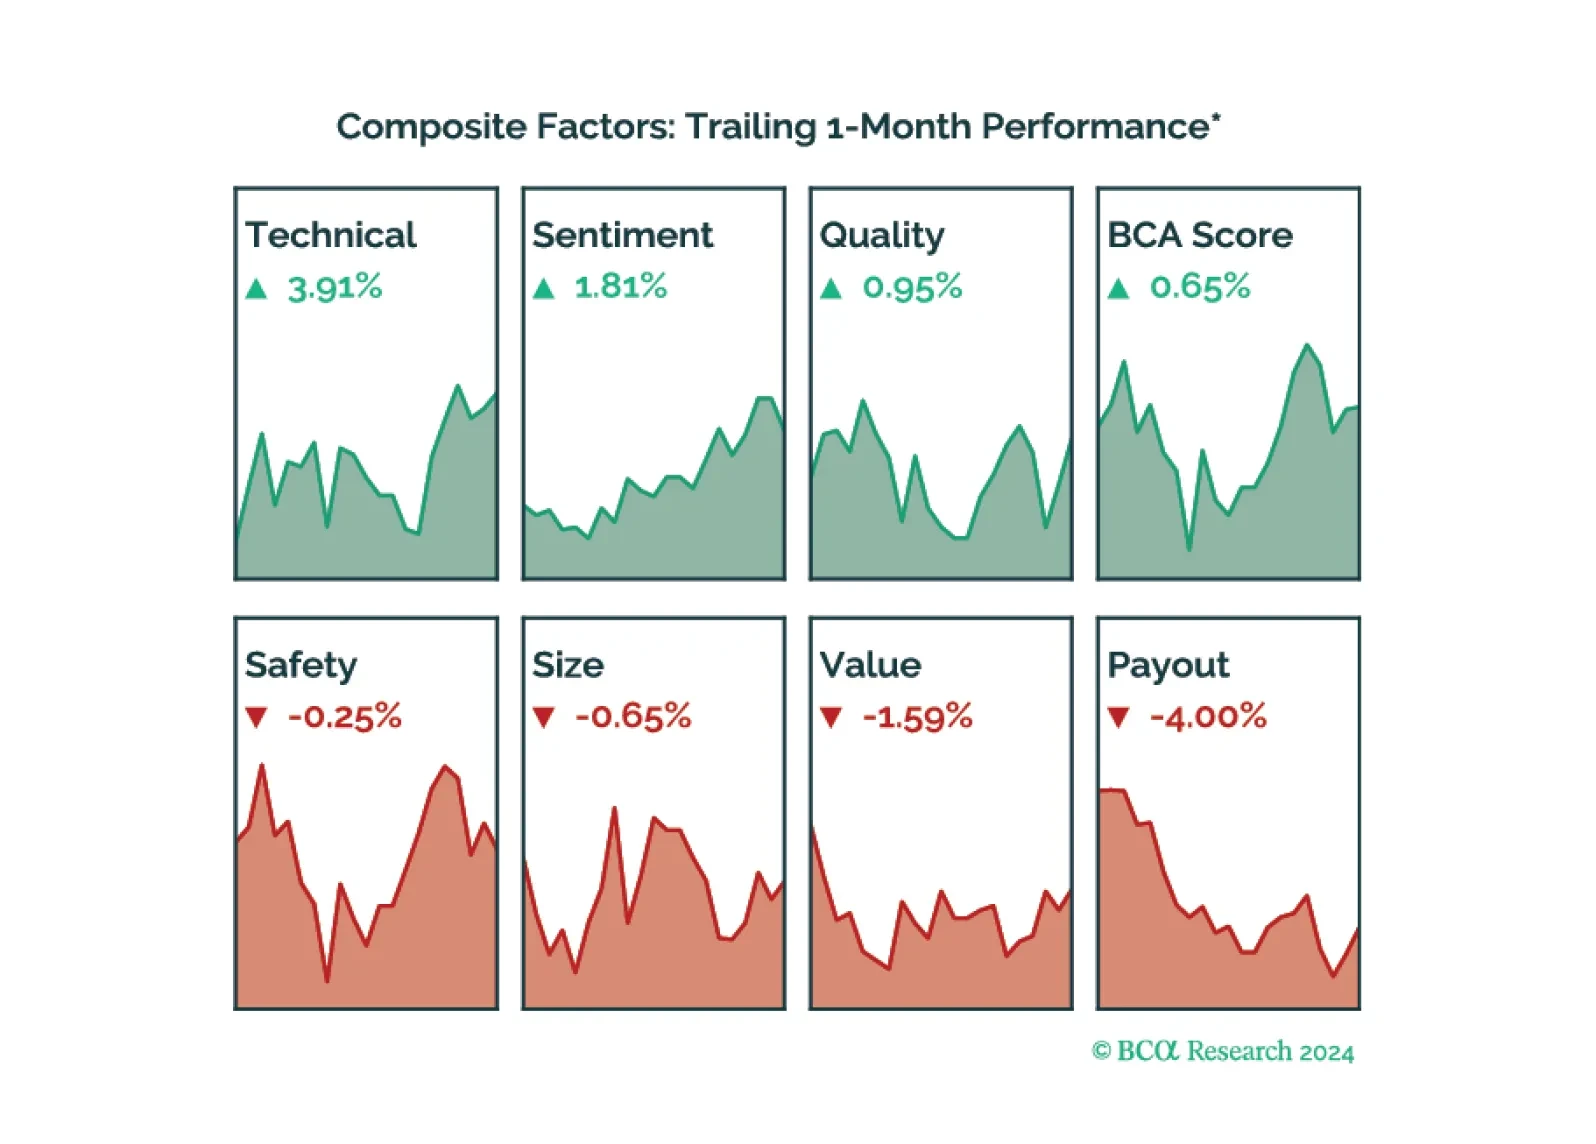
The BCA Score L/S posted a positive return with Technicals and Sentiment leading the way. The USHQ SMID portfolio outperformed its benchmark again and the large cap portfolio fell behind slightly in tech, but made up ground via wins in Consumer Discretionary and Communication Services.
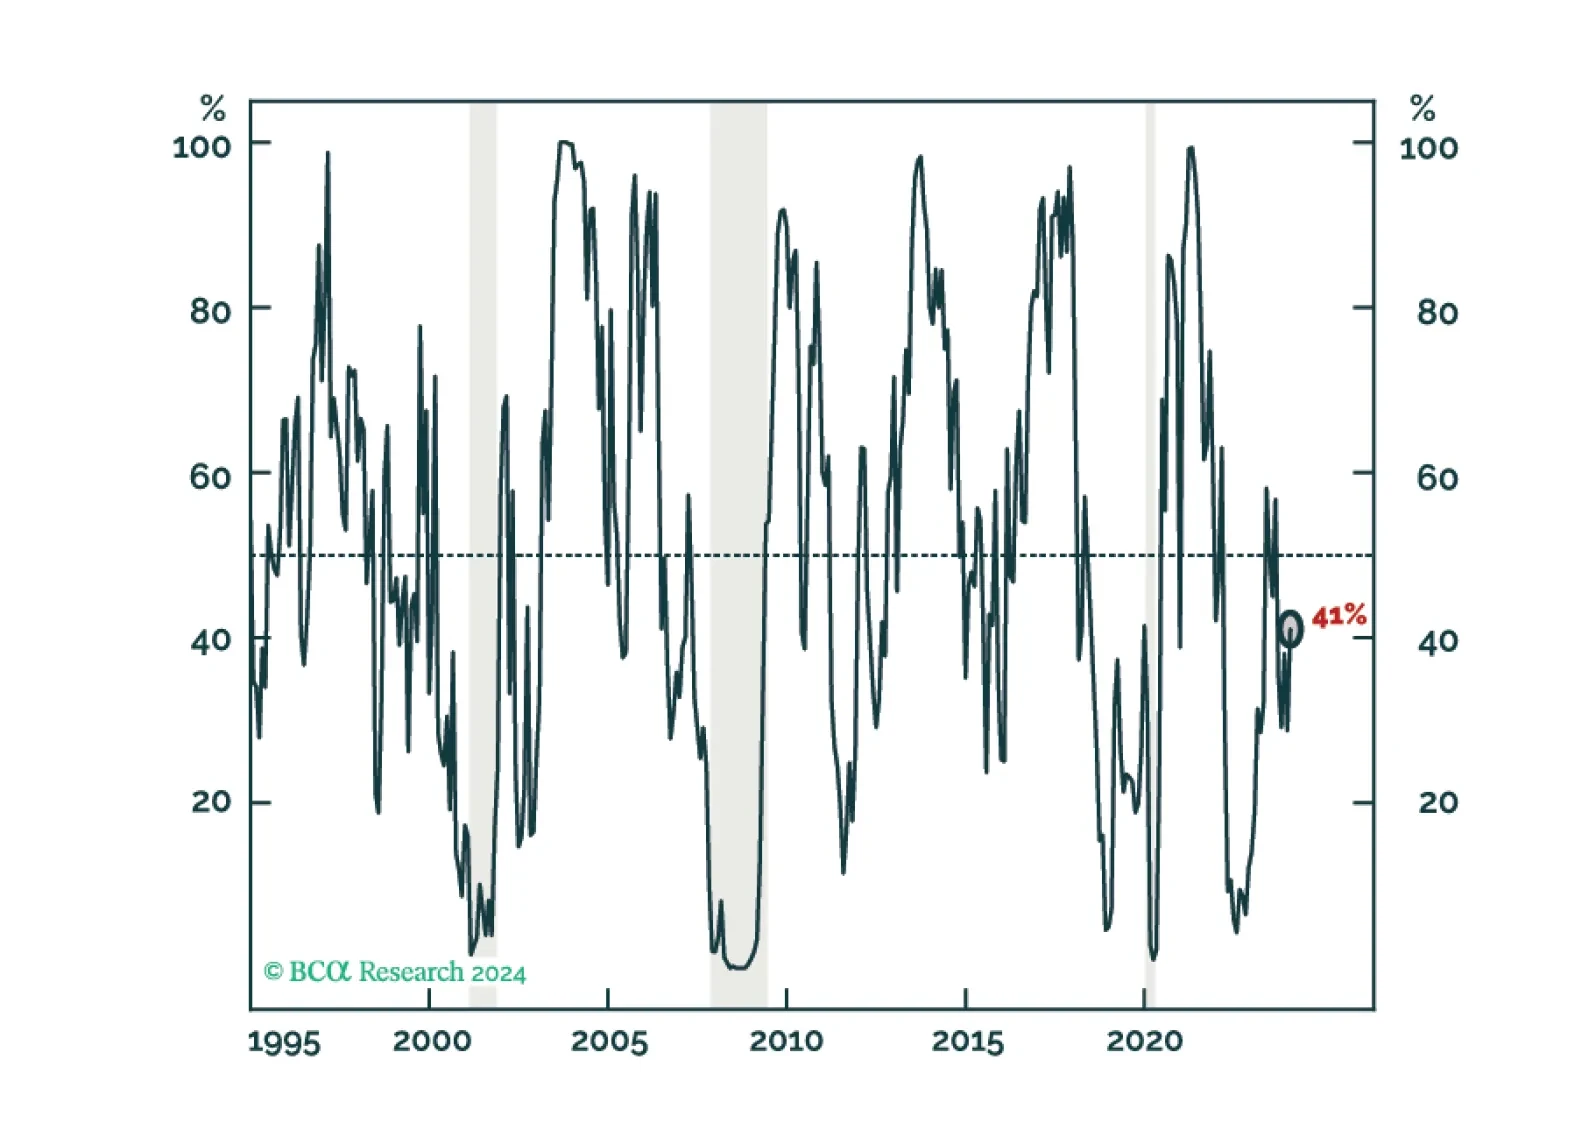
Our model is neutral on stocks on a absolute basis, meaning it expects global equities to perform inline with its historical average. On the sector front the model favors energy and growth with a modest tilt towards defensives.
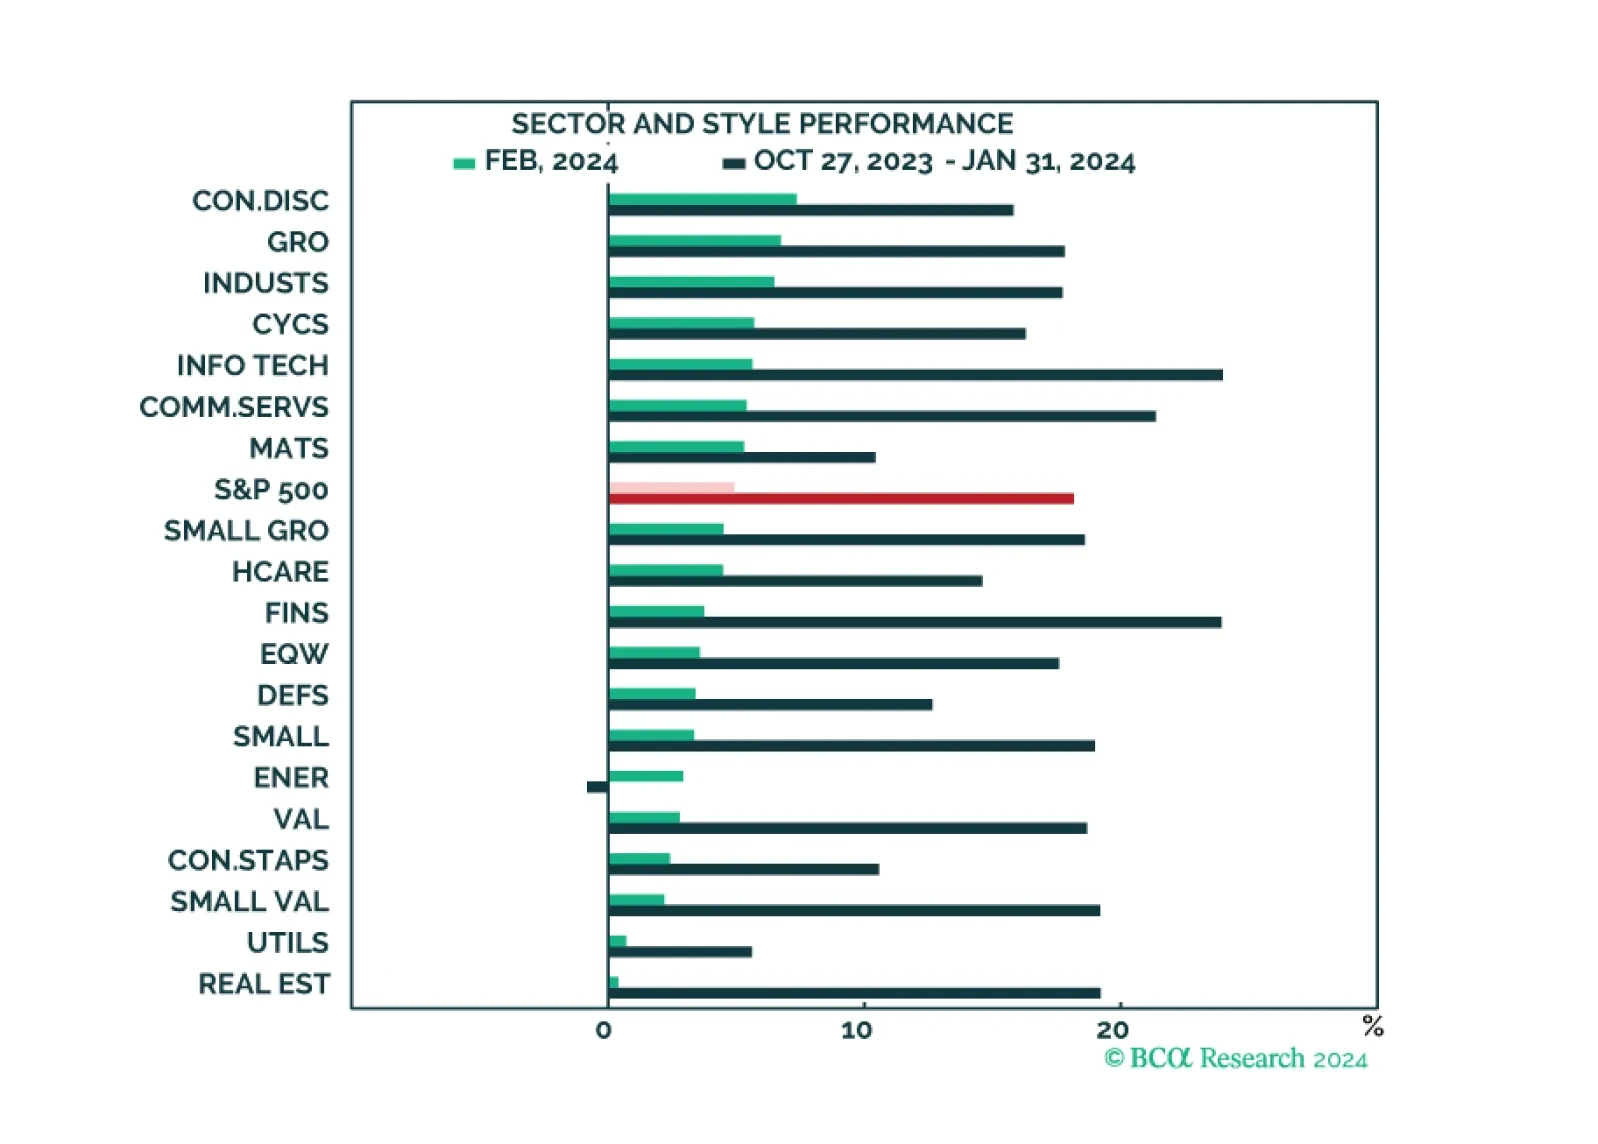
The market narrative continues to be dominated by the Magnificent Six, which drove both market performance and strong Q4 earnings results. While all sectors and styles have recently turned green, the rally is still mostly narrow. Earnings growth appears to be strong, but outside of the Magnificent Six, many companies are struggling. The market appears expensive and overbought, but that is mostly down to the high valuations and the popularity of the Magnificent Six.
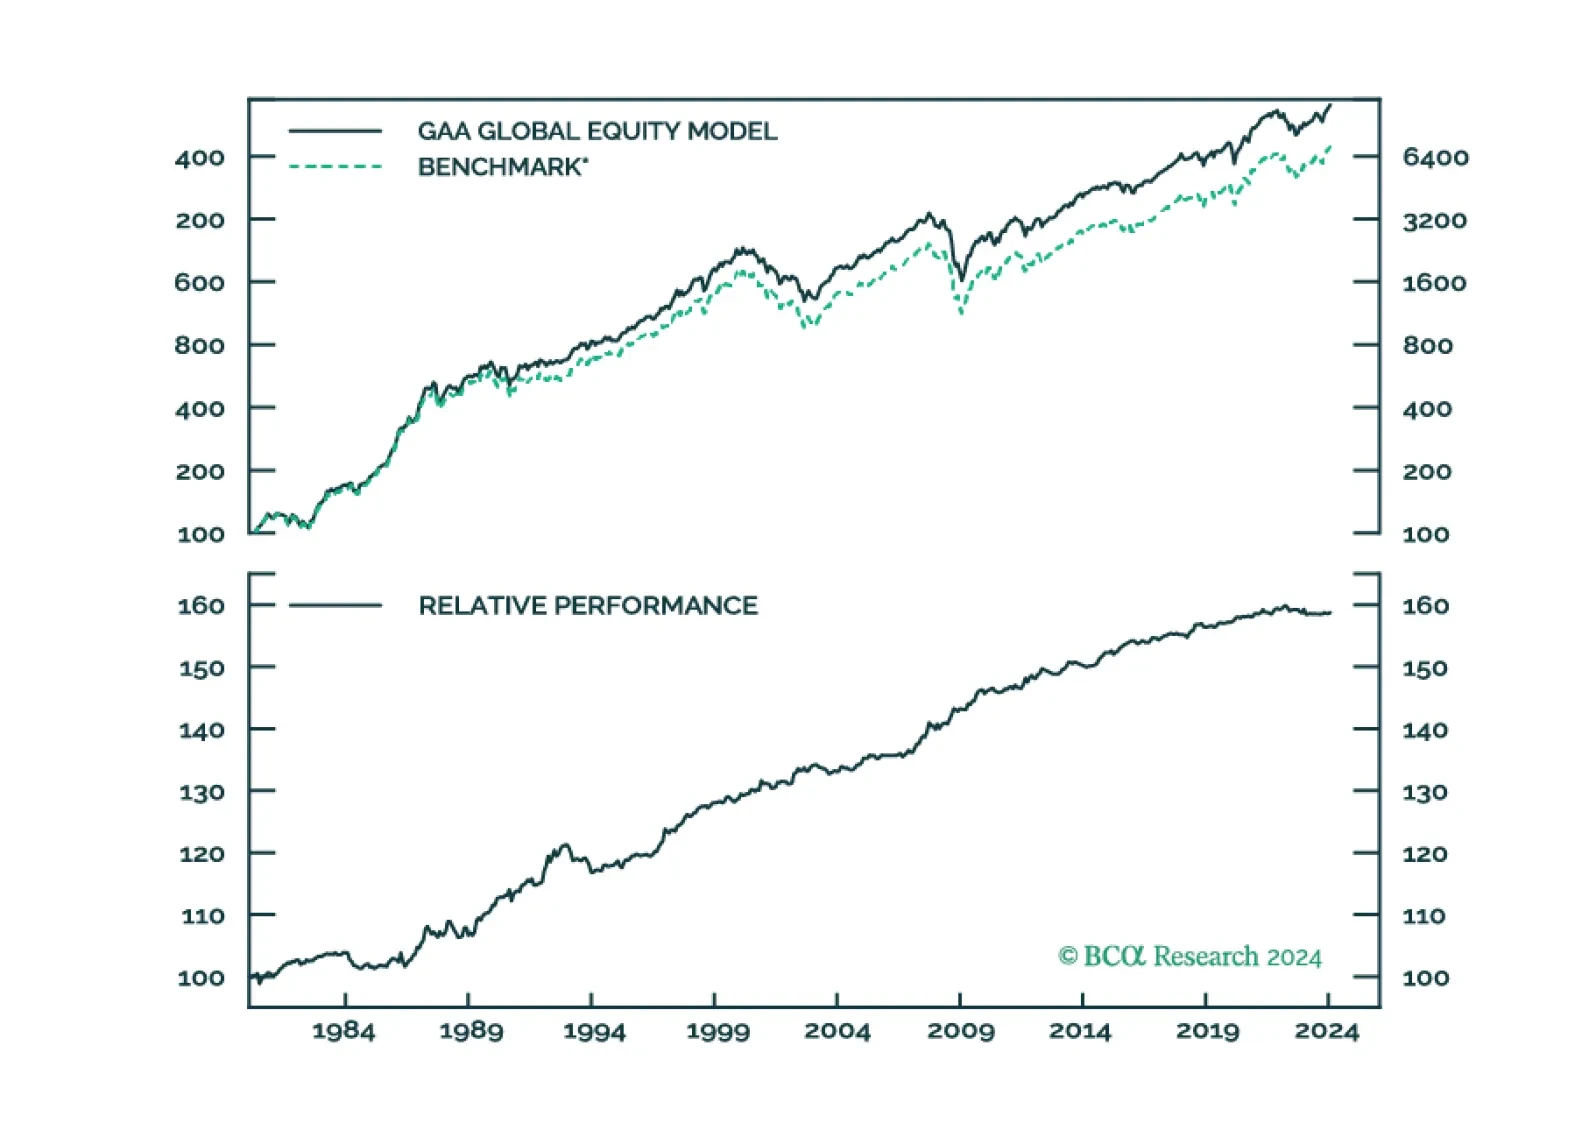
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
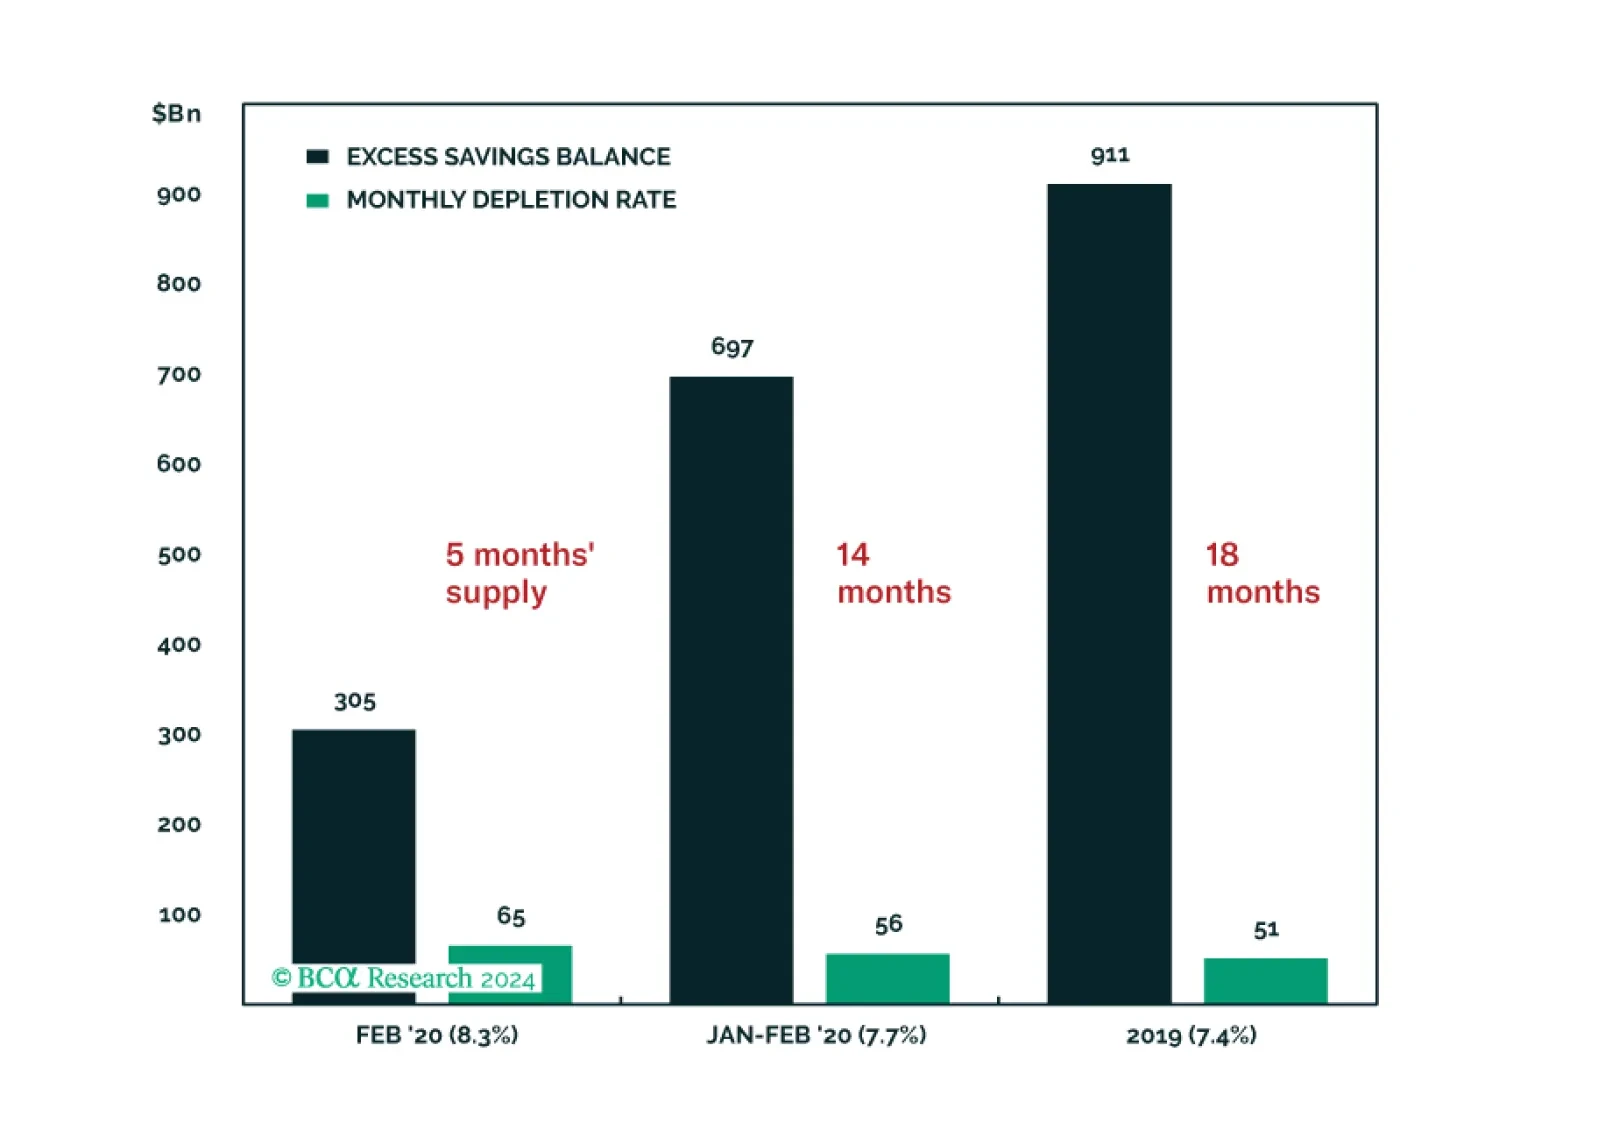
We feel as good about spurning the soft-landing narrative today as we did about spurning the recession narrative a year ago, but we are not giving into complacency. This week’s report looks at two key ways that we may be getting it wrong: by underestimating households’ asset support and the labor market’s durability. We remain tactically neutral but continue to look for opportunities to turn defensive.
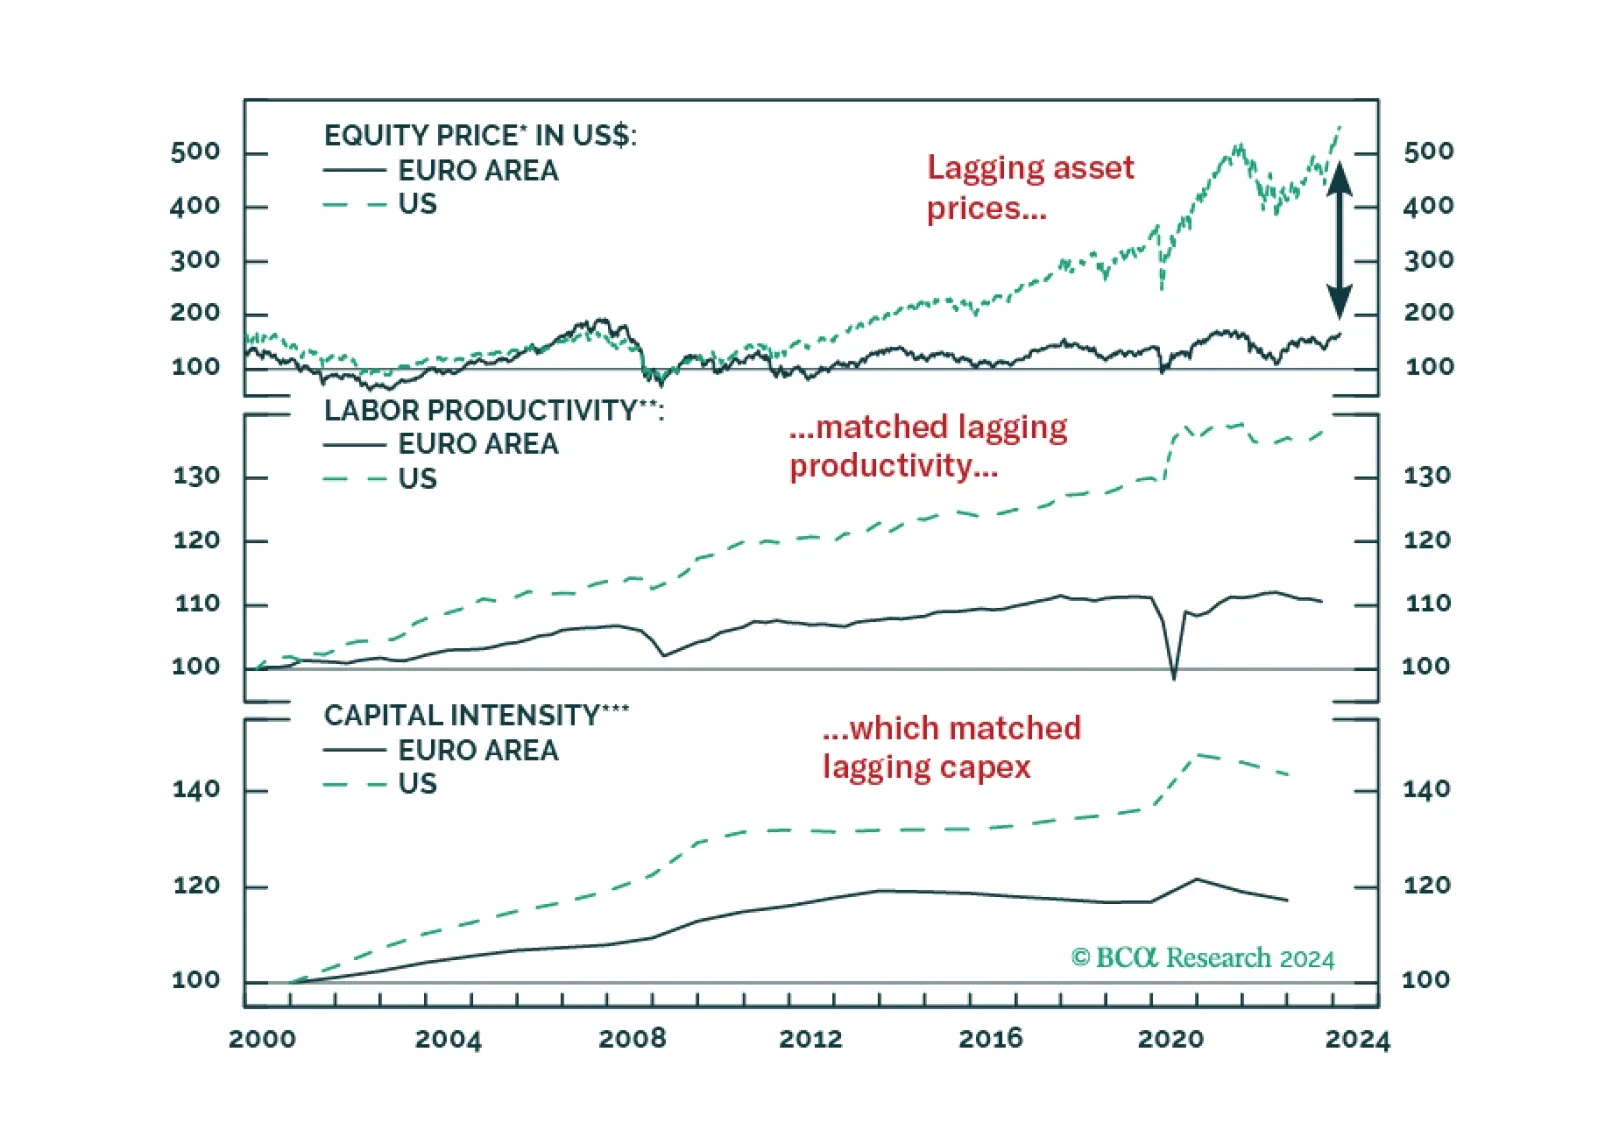
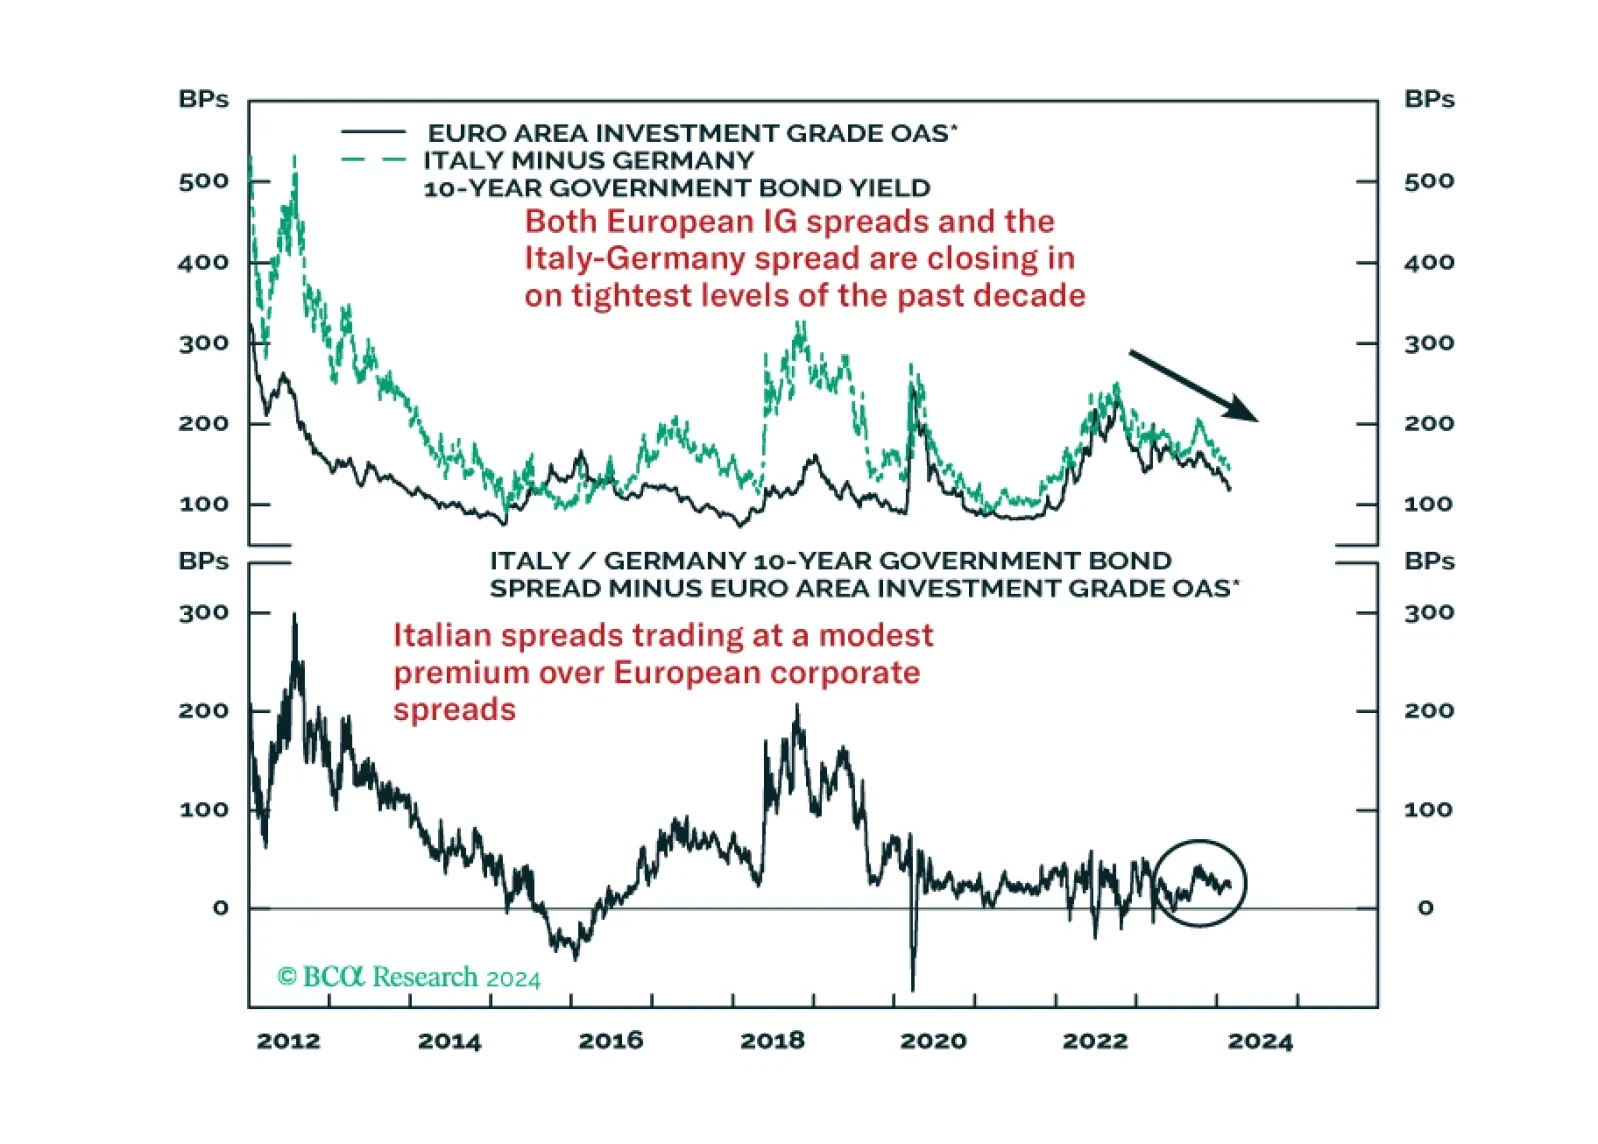
In this Strategy Insight, we take a comparative look at two of the largest spread product sectors in Europe – Italian government bonds and investment grade corporates. We make the case for favoring Italy over investment grade in the event of a downturn in European economic sentiment.
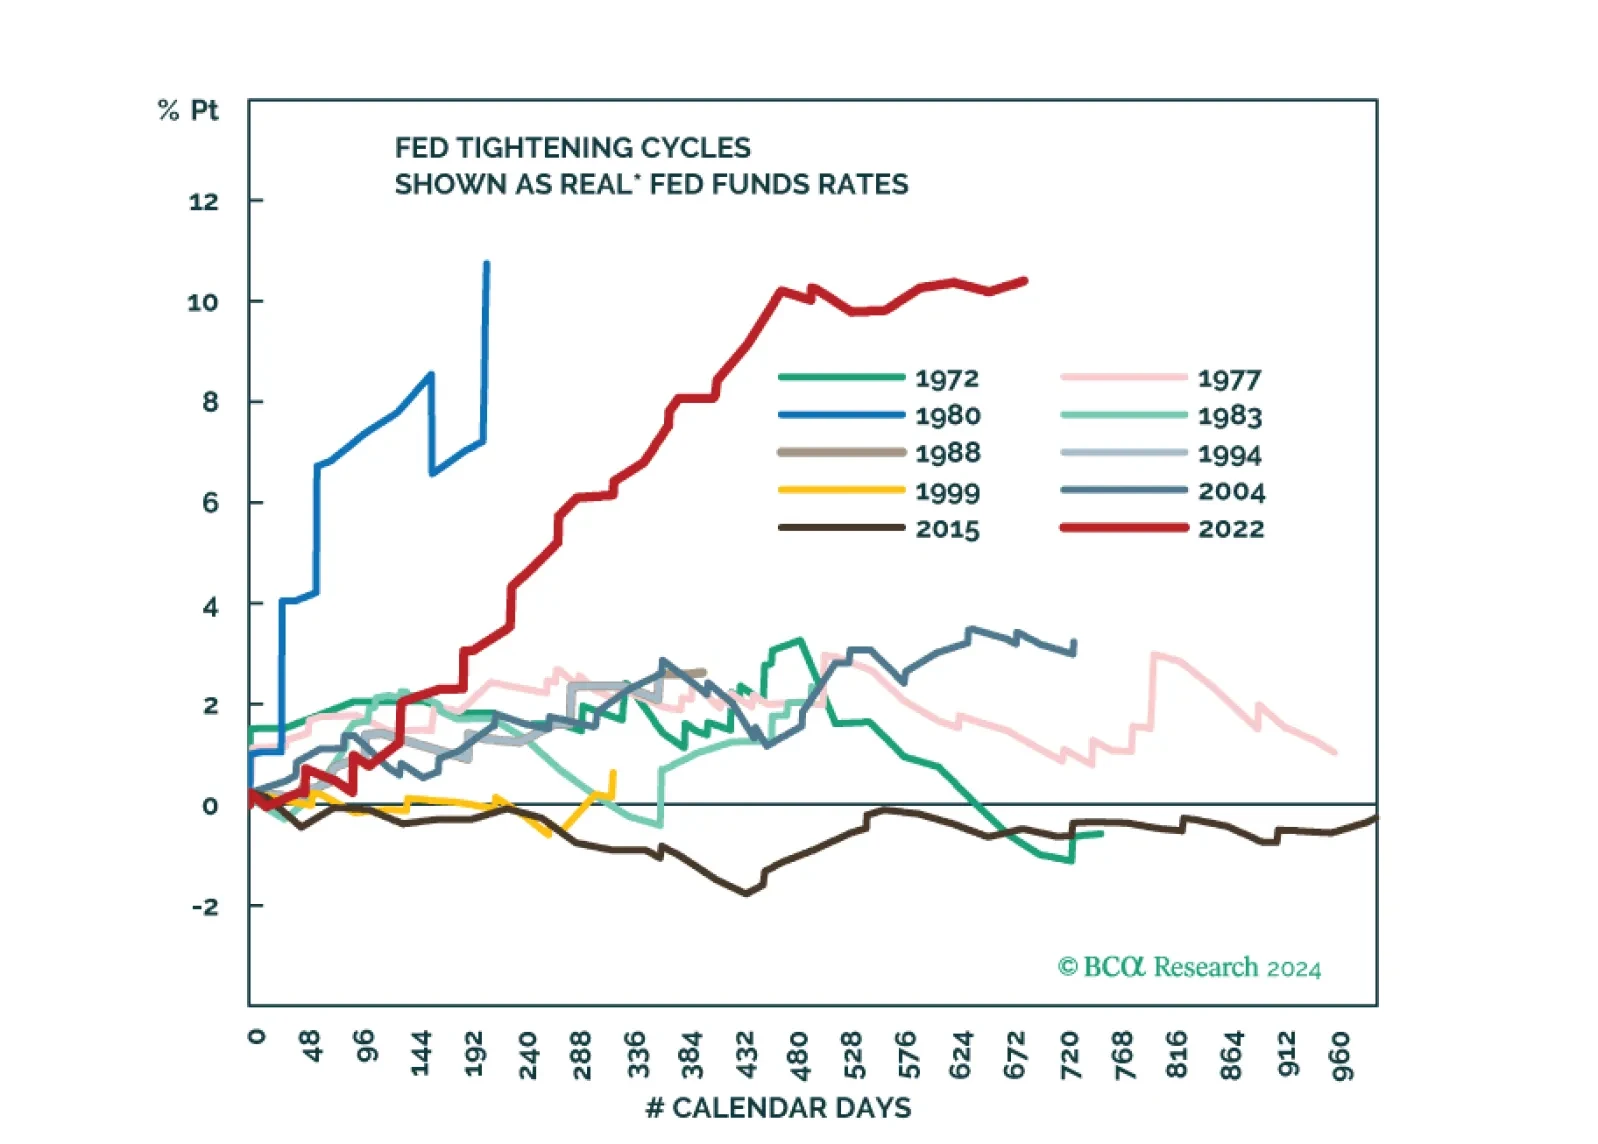
Amid patchy global growth, the US economy remains resilient. However, tight monetary policy will eventually trigger a recession in the US too. The stock market rally has been very narrow. Stay underweight risk assets.