Latest from BCA Research
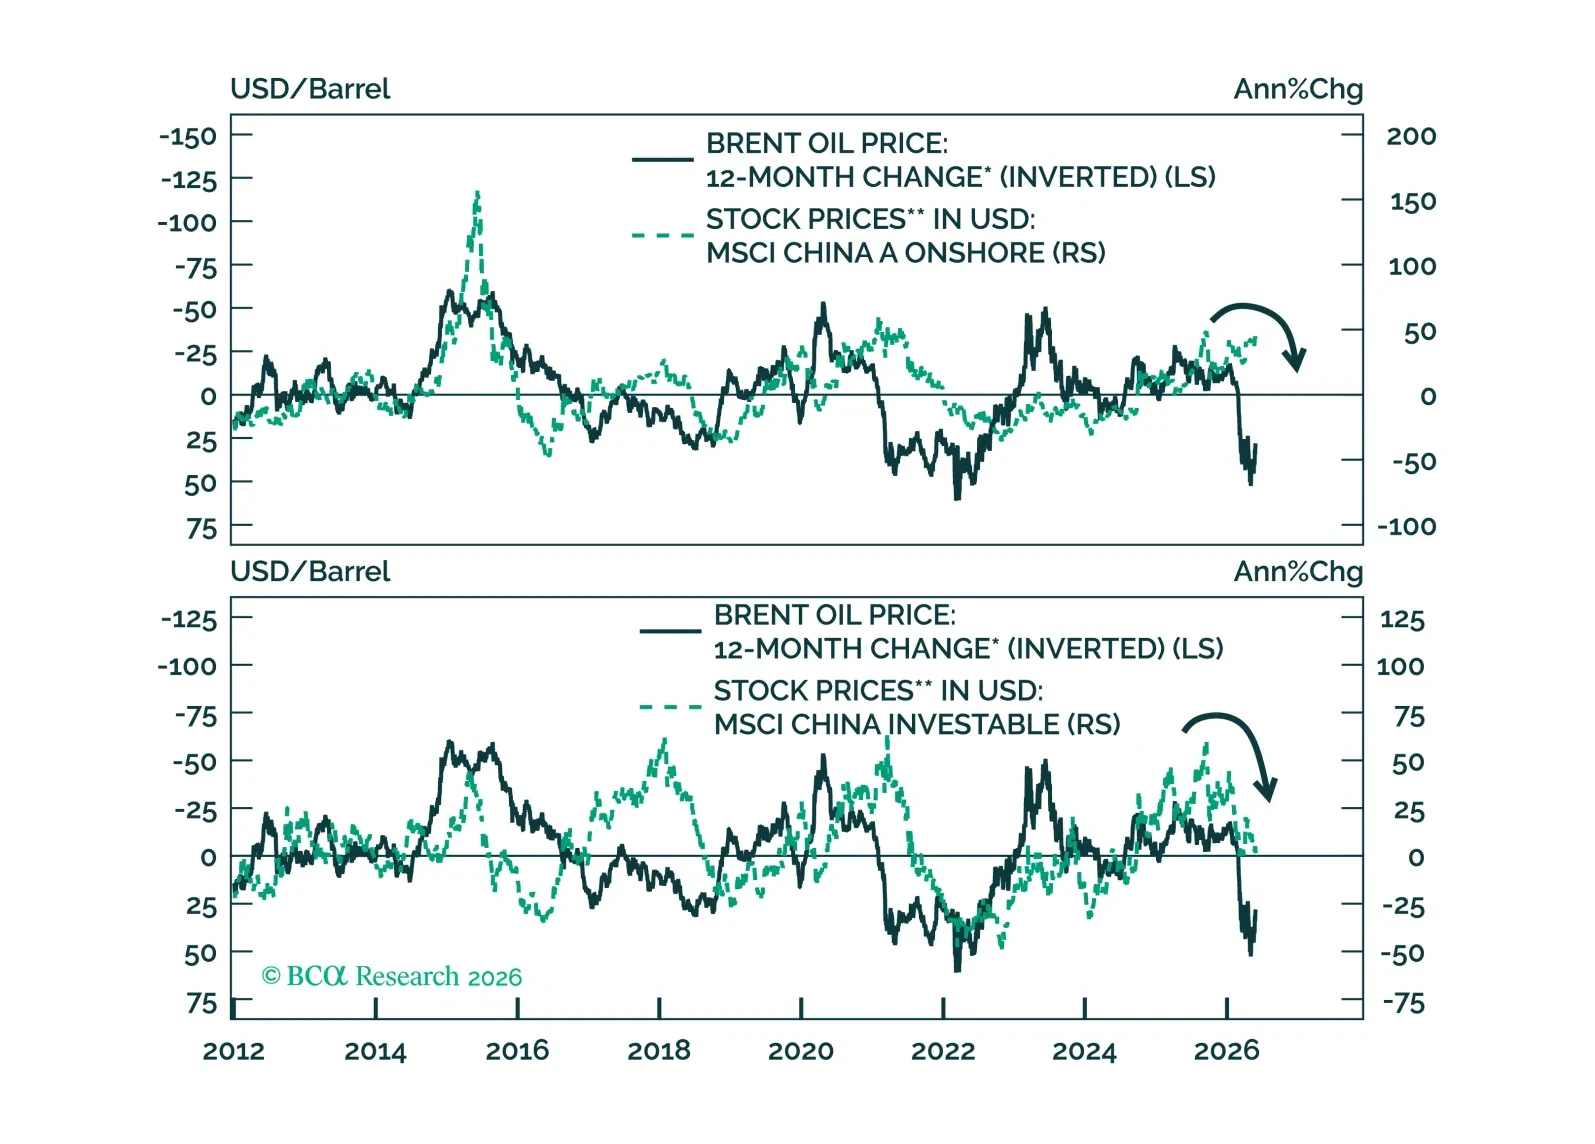
Oil shocks hit economies with a lag. China will feel the delayed pain of surging oil prices, pushing Beijing toward infrastructure spending as its main tool to prop up growth.

MacroQuant recommends a slight underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is very positive on the US dollar, downgrades gold to underweight, upgrades copper to overweight, and remains very bullish on oil.
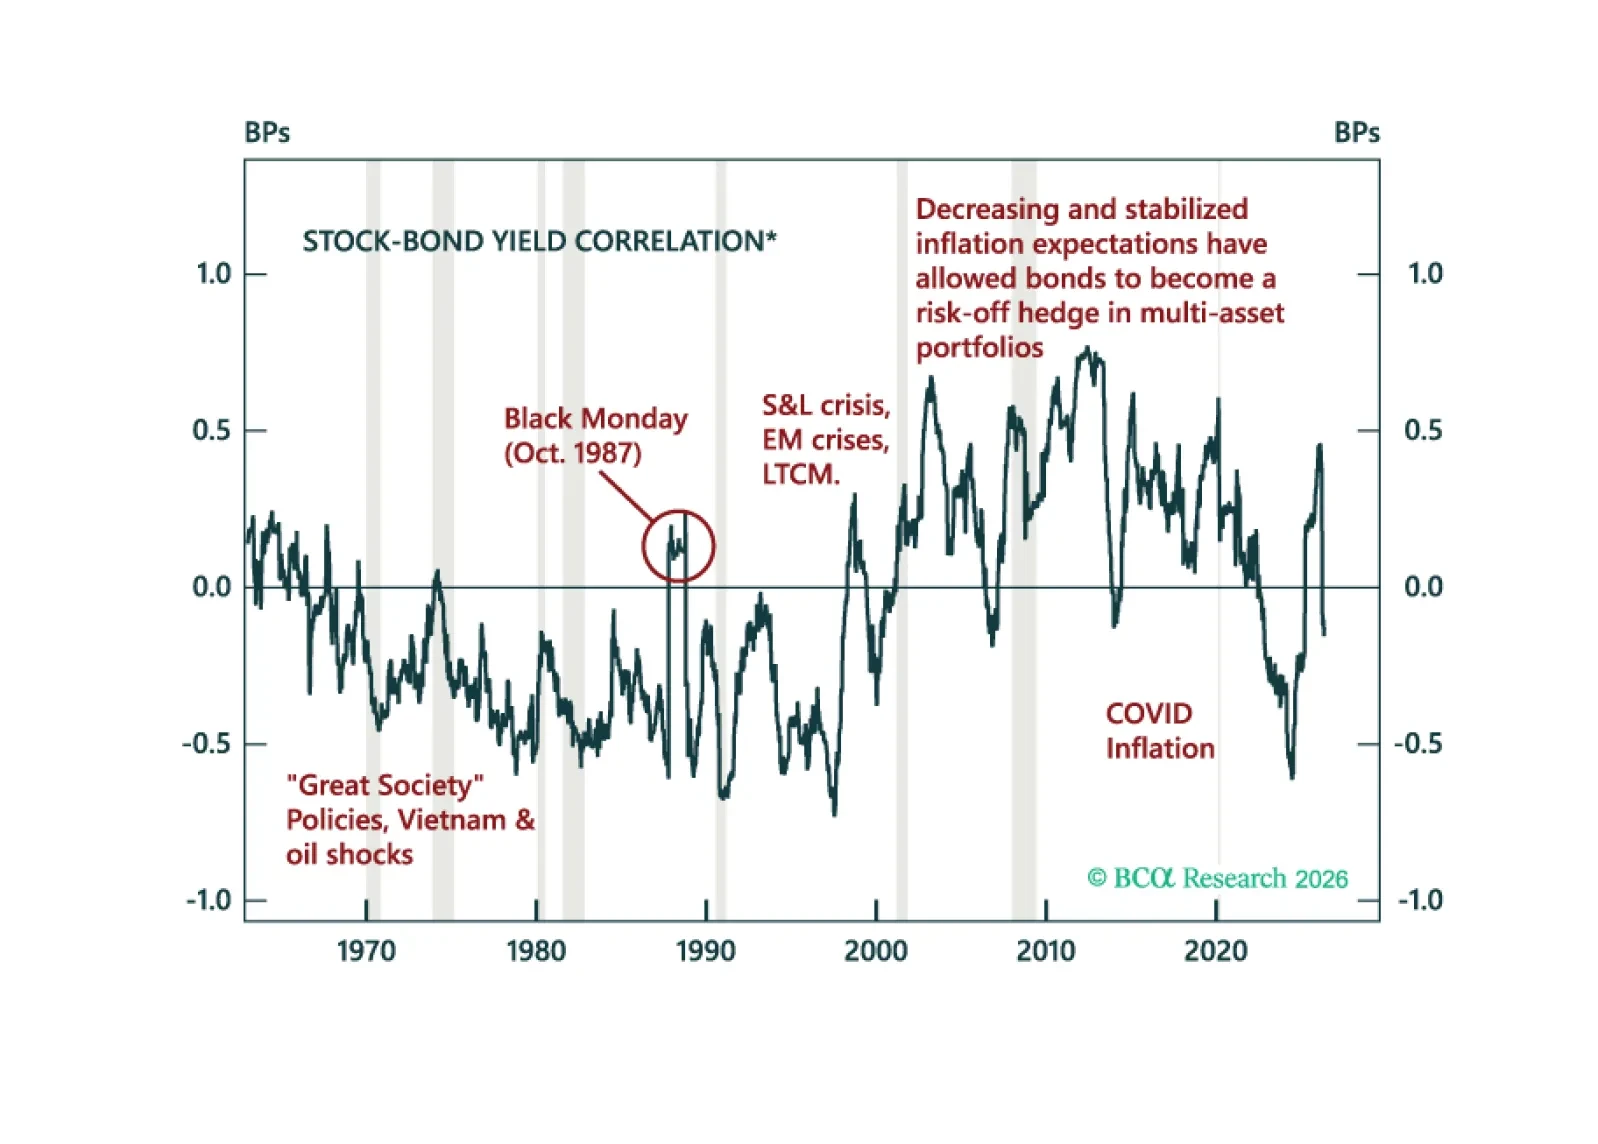
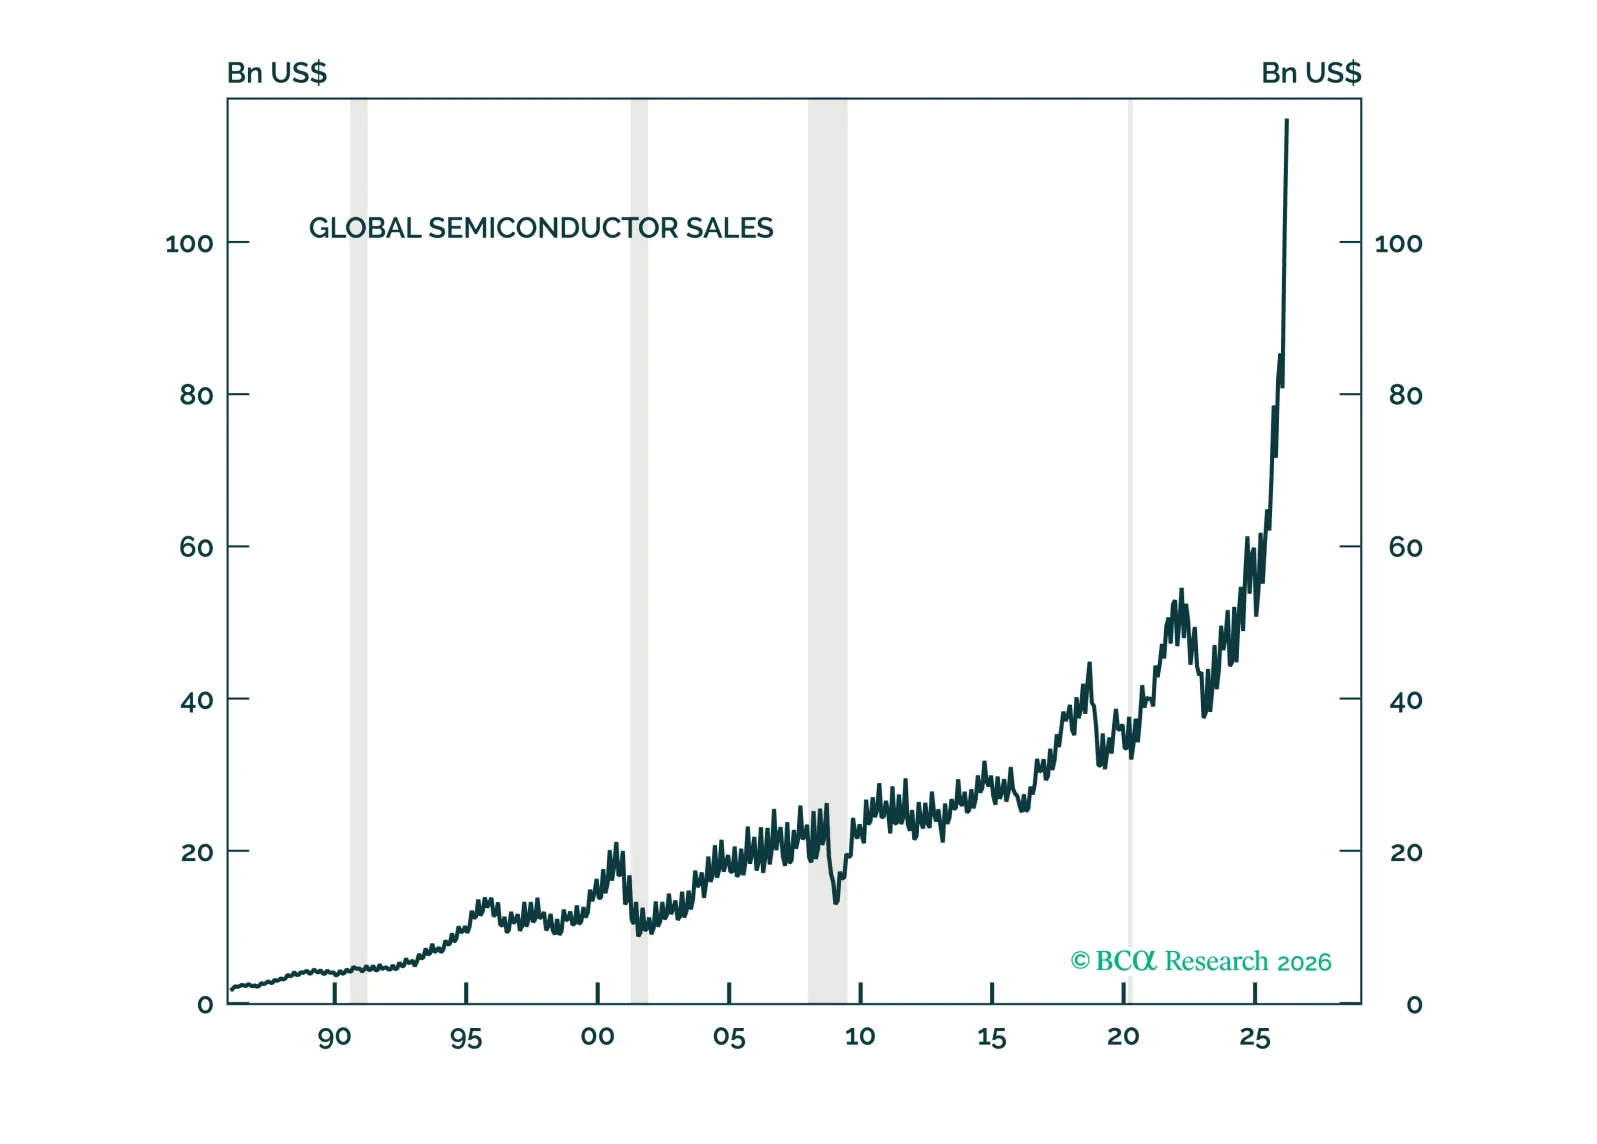
The AI bubble is a different type of bubble. It is primarily an earnings bubble rather than a valuation bubble. Like all bubbles, the AI bubble will burst. For now, however, our AI demand indicators do not suggest that this is imminent.


AI excels at IQ but fails miserably at EQ. Hence, AI will obsolete any job that relies on IQ, including many graduate-level jobs. But high-EQ humans will be in high demand to pair up with AI, and many of these jobs will be middle income jobs. We discuss the implication for the economy and markets. Plus, a new tactical trade is underweight global tech versus healthcare.
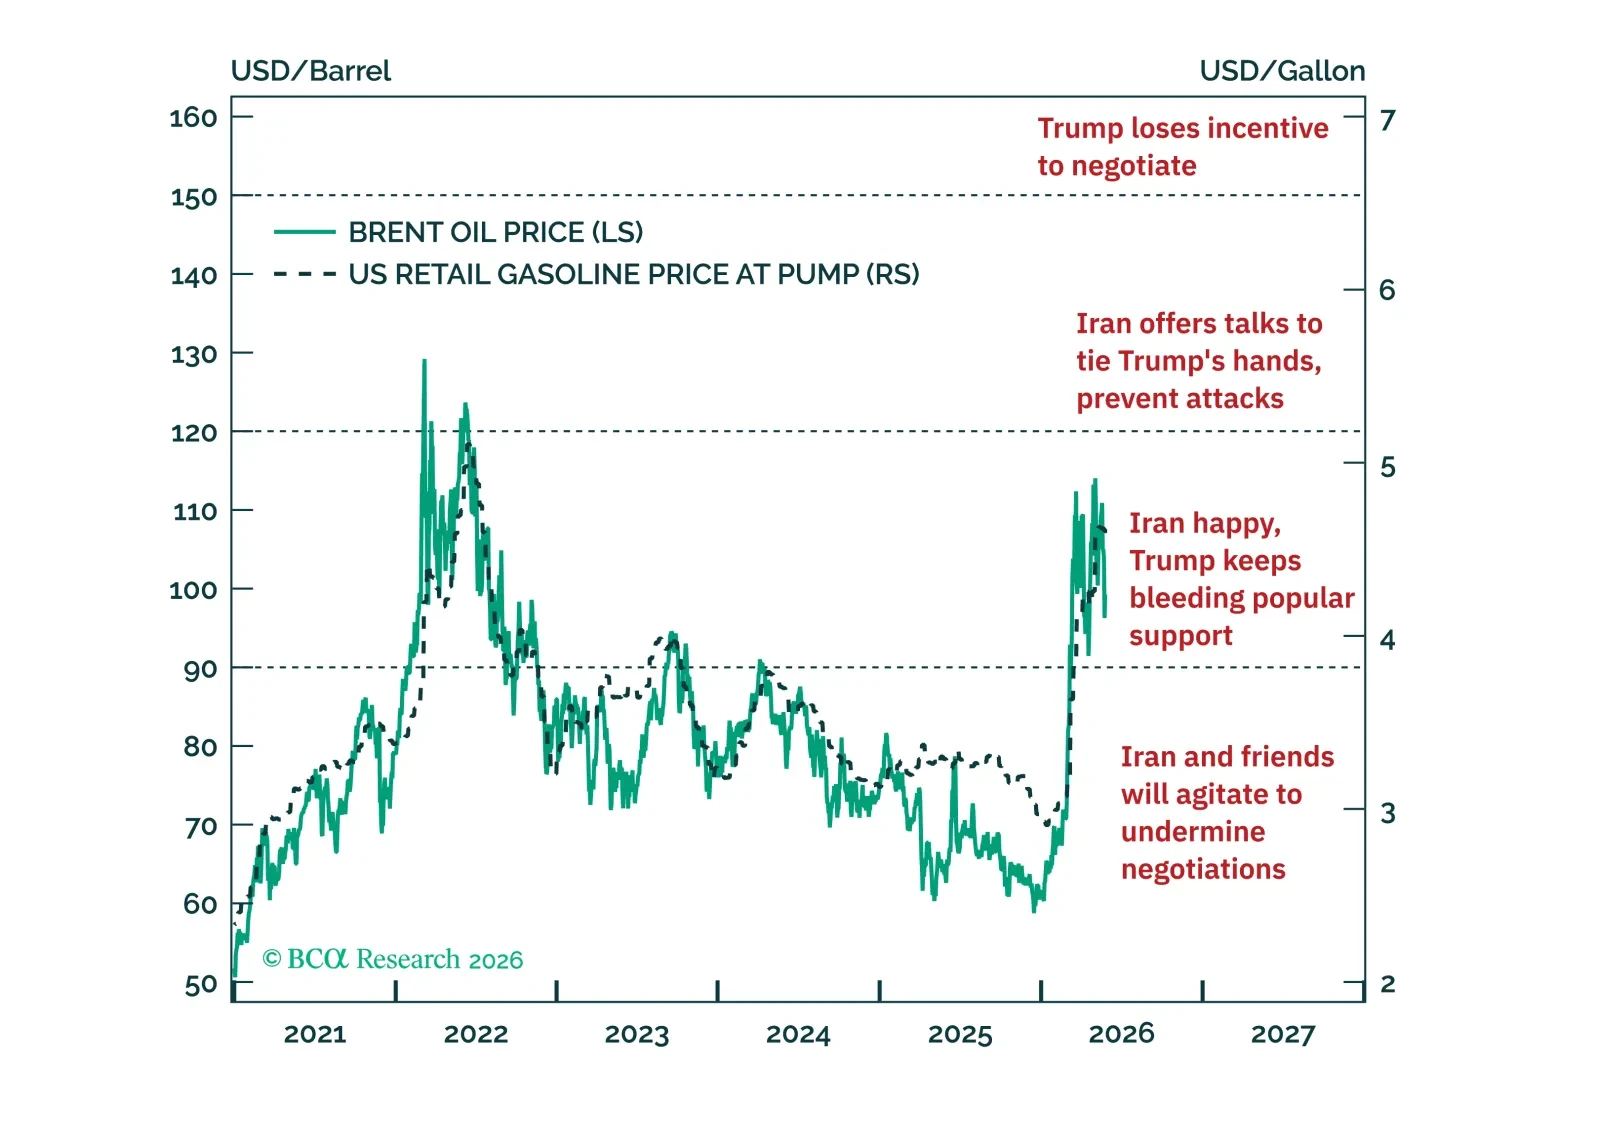
The odds of a near-term US-Iran deal have gone up slightly, but the odds of a Russian provocation that divides NATO have also gone up.

In Romania, large fiscal and current account deficits, high inflation, negative real rates, an overvalued exchange rate, and deteriorating growth point to budding currency devaluation. Investors should short the Romanian currency versus the euro and underweight Romanian local bonds, equities, and sovereign credit.
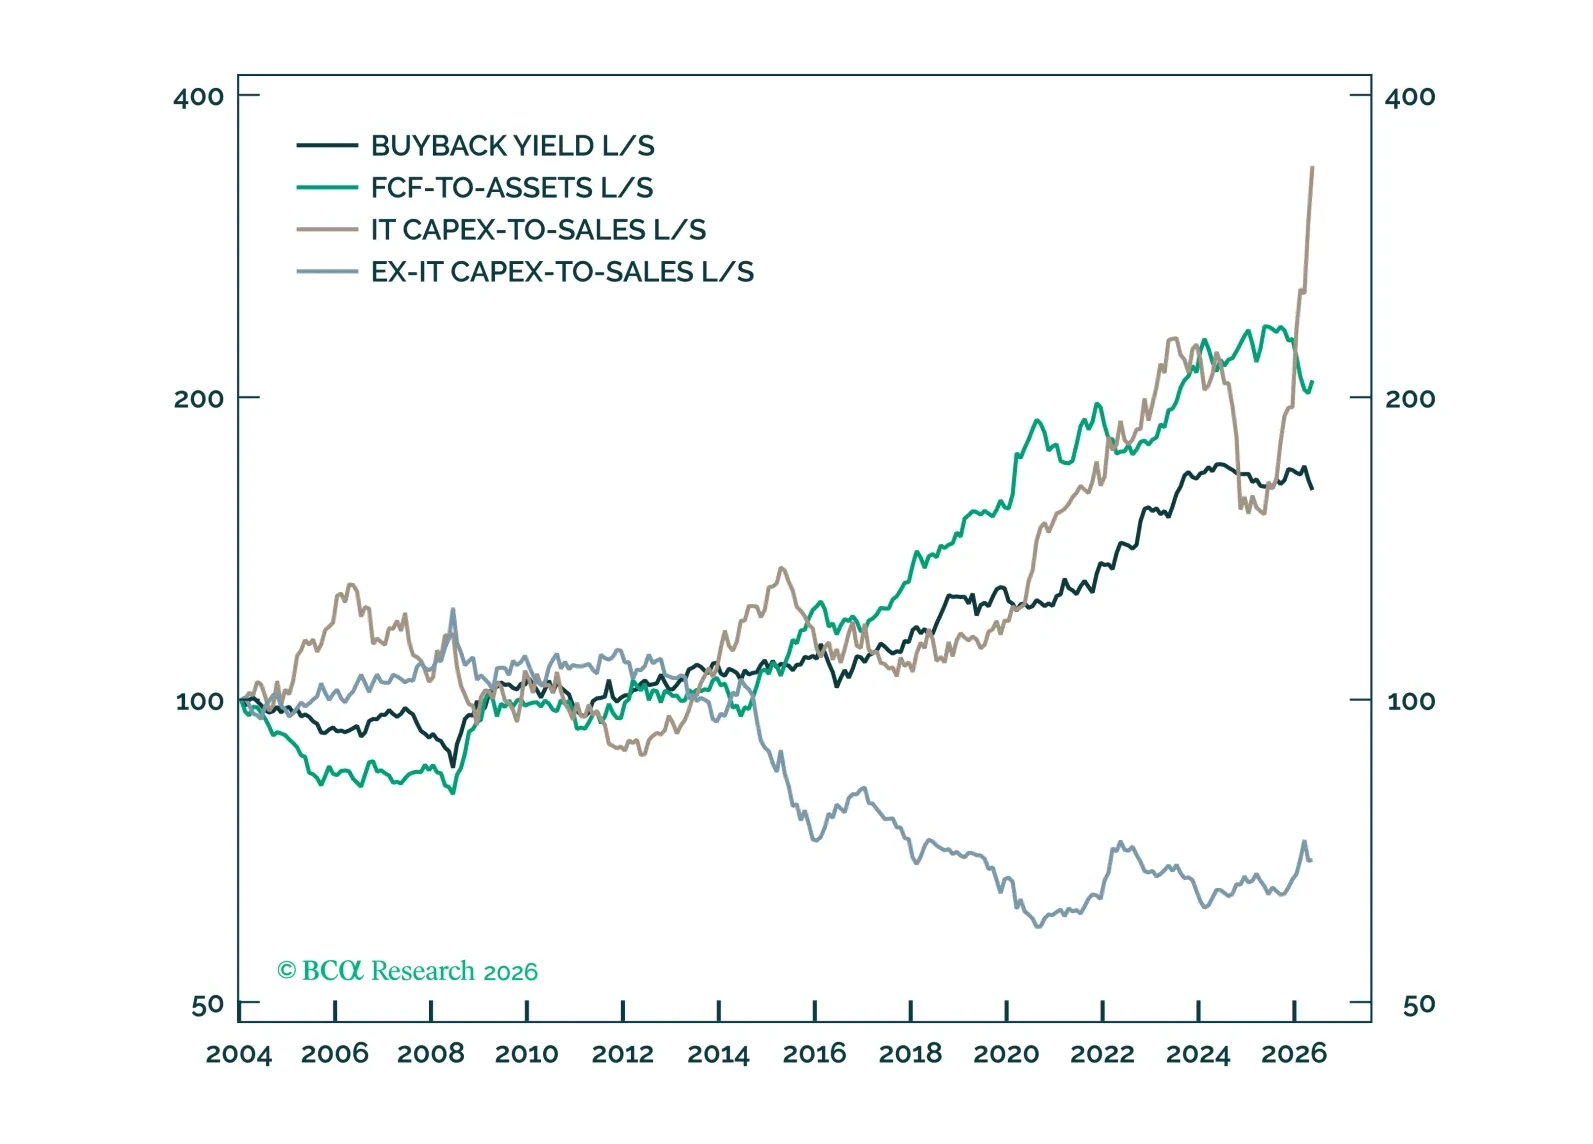
Tech, and increasingly the market, is moving from a cash-return regime to a reinvestment regime. After the GFC, investors rewarded companies that returned cash to investors. In the AI cycle, they are rewarding companies that put that cash back to work. This is not just a story of falling free cash flow; it is the mirror image of a market rewarding reinvestment. Tech has defined both regimes, revealing the old cash-flow “stars” as sector bets masquerading as alpha.