Latest from BCA Research
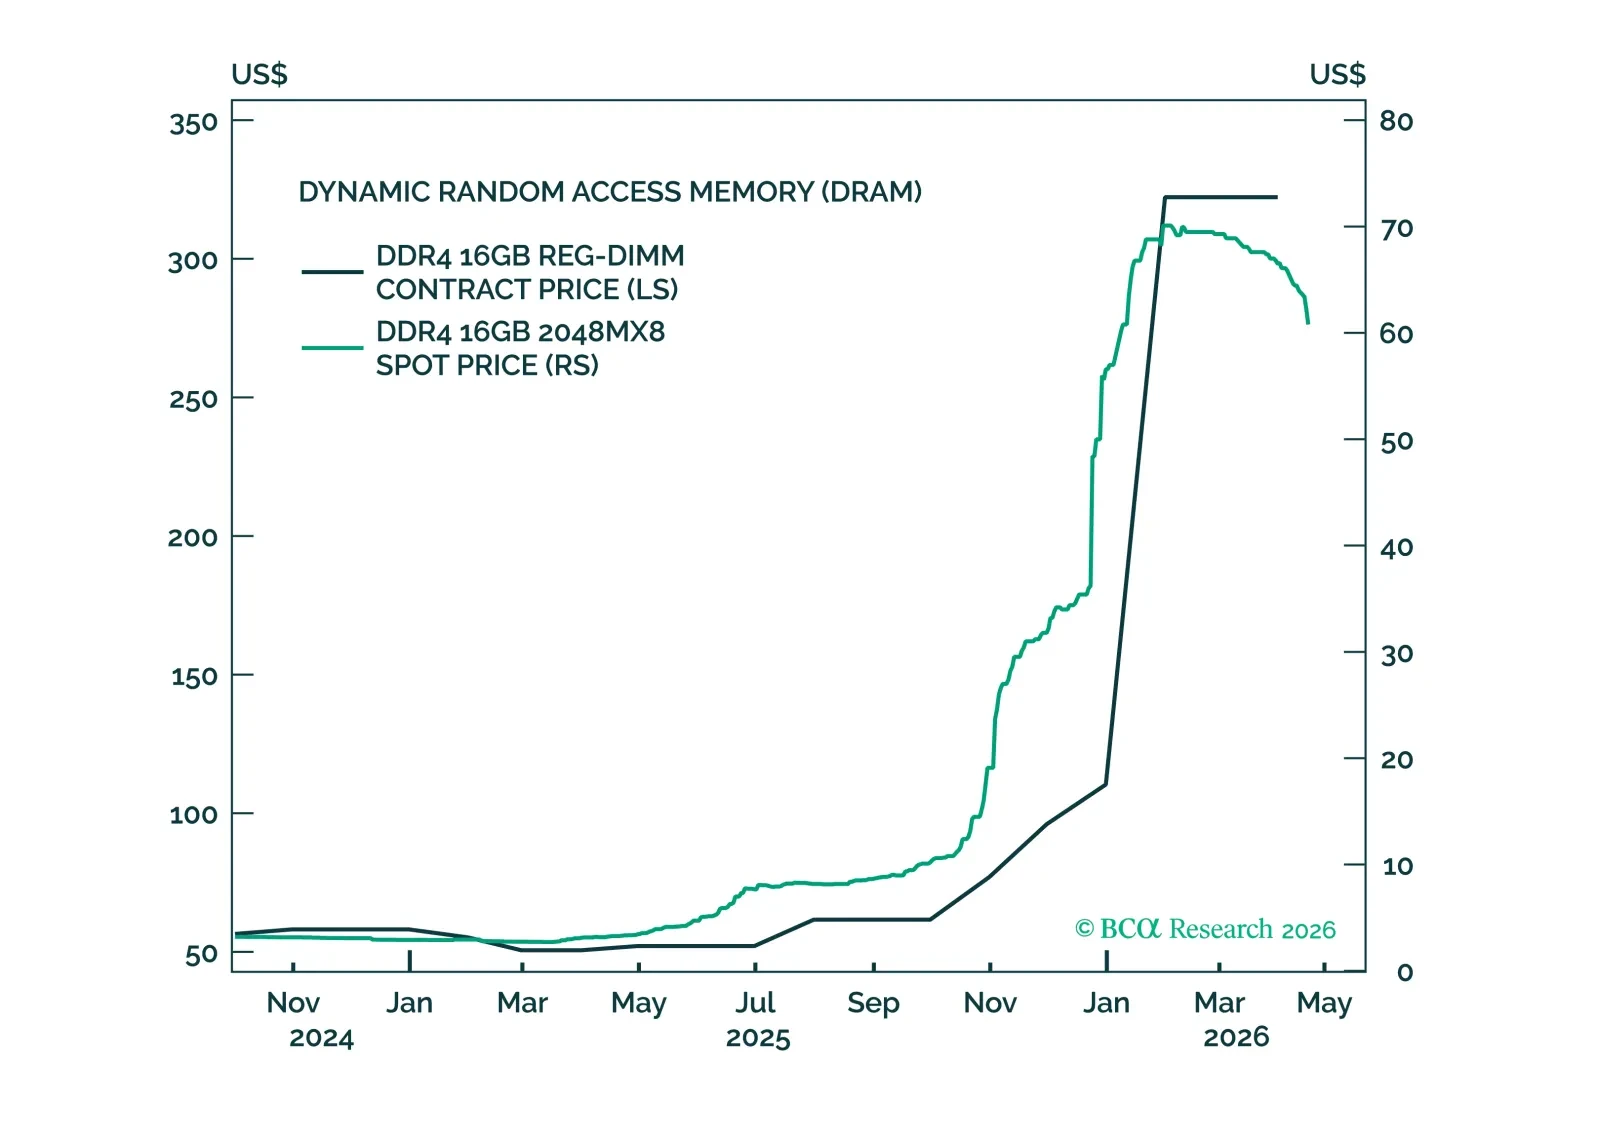
Most of the increase in S&P 500 earnings estimates this year has stemmed from shortages. The oil shortage, which has pushed up estimates for energy companies, will fade once the military conflict is resolved. However, the shortage of semiconductors and other AI paraphernalia could persist for a while longer. As such, we are moving our recommended 12-month equity allocation from a slight underweight to neutral. We are already neutral on a 3-month horizon.
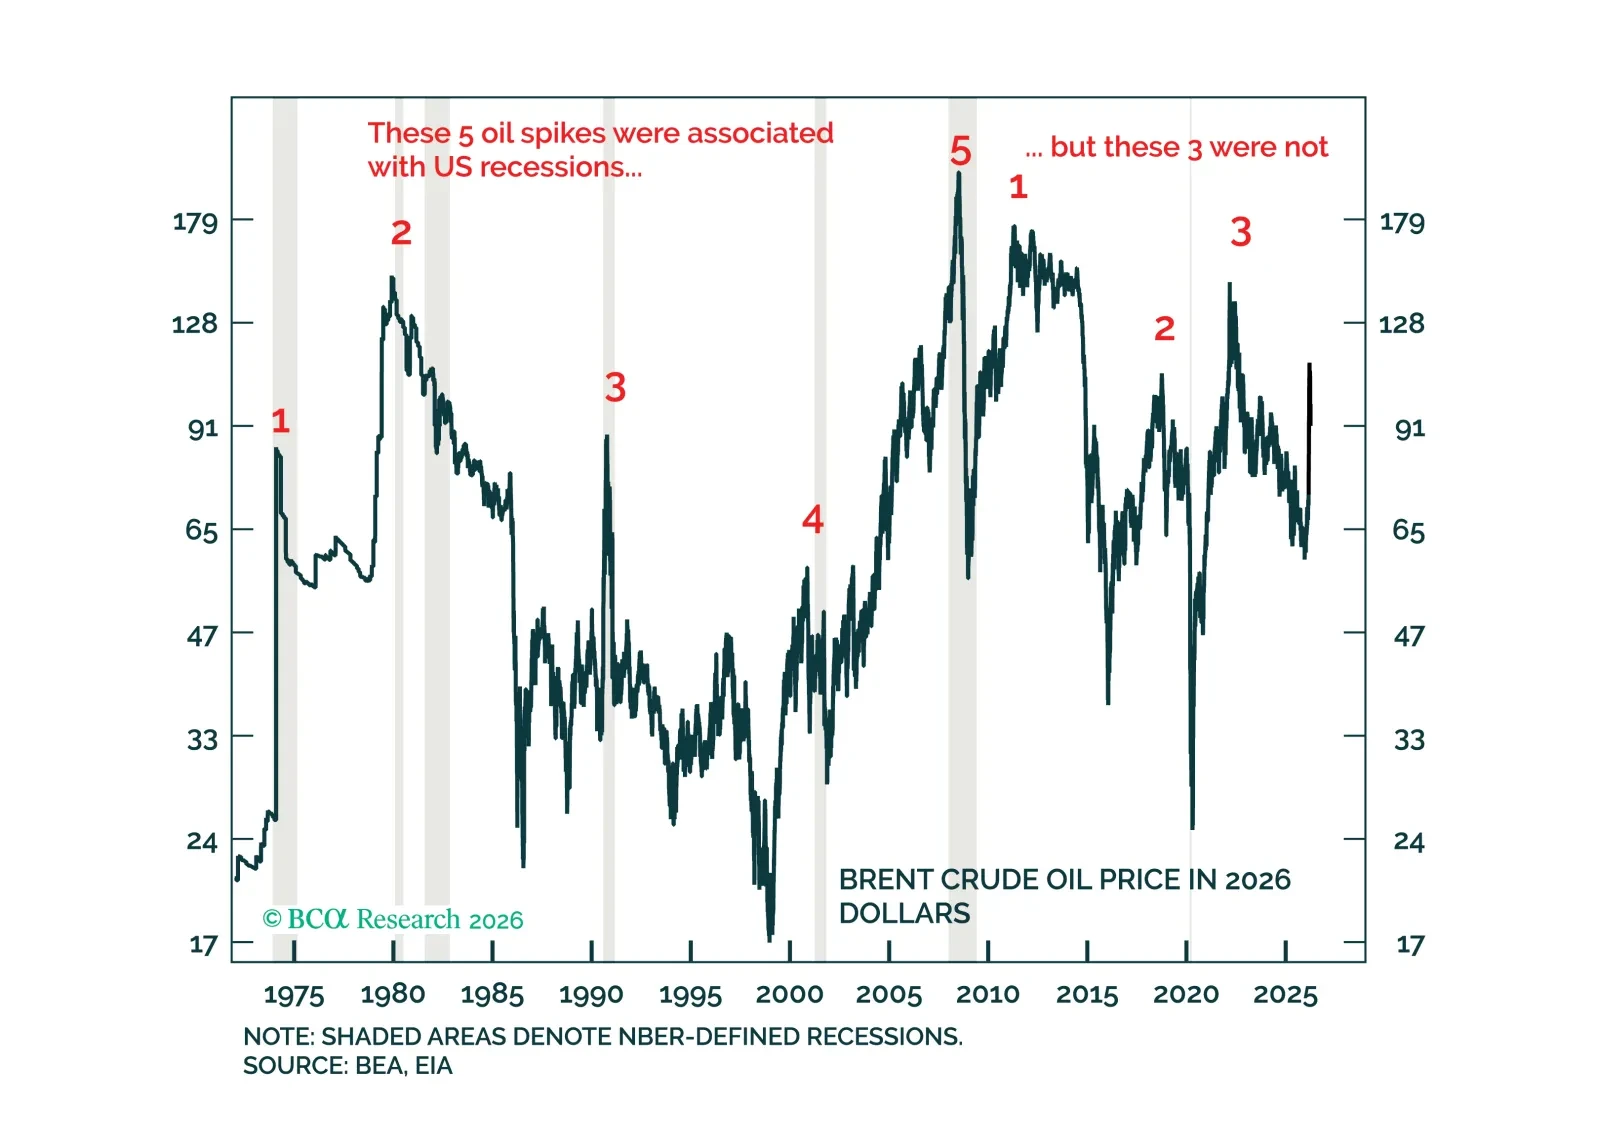
In the US, the oil shock’s impact is more inflationary than recessionary but in the other economies, like the UK, the impact is both inflationary and recessionary. This creates relative value opportunities for bond investors. Plus, we reiterate short AUD/JPY as a trade.
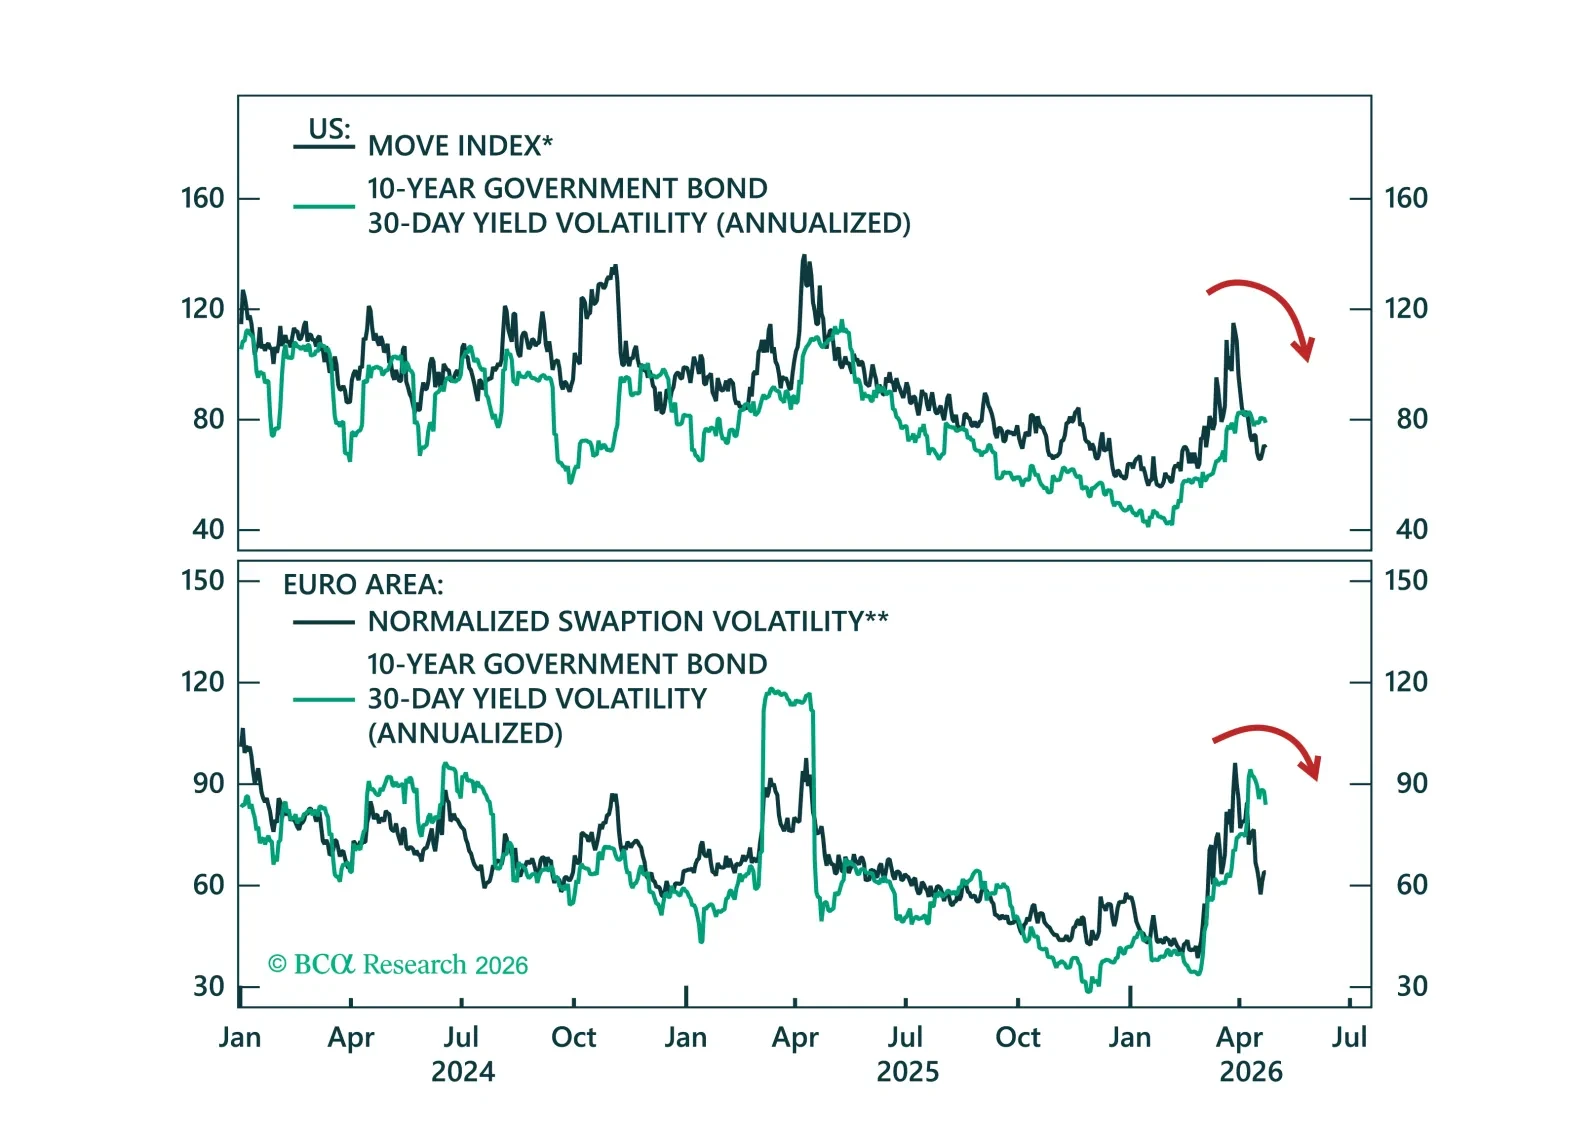
With central banks largely on hold, the return of a lower volatility environment is bringing carry trades back into focus. We outline the most attractive carry opportunities across global fixed income markets.
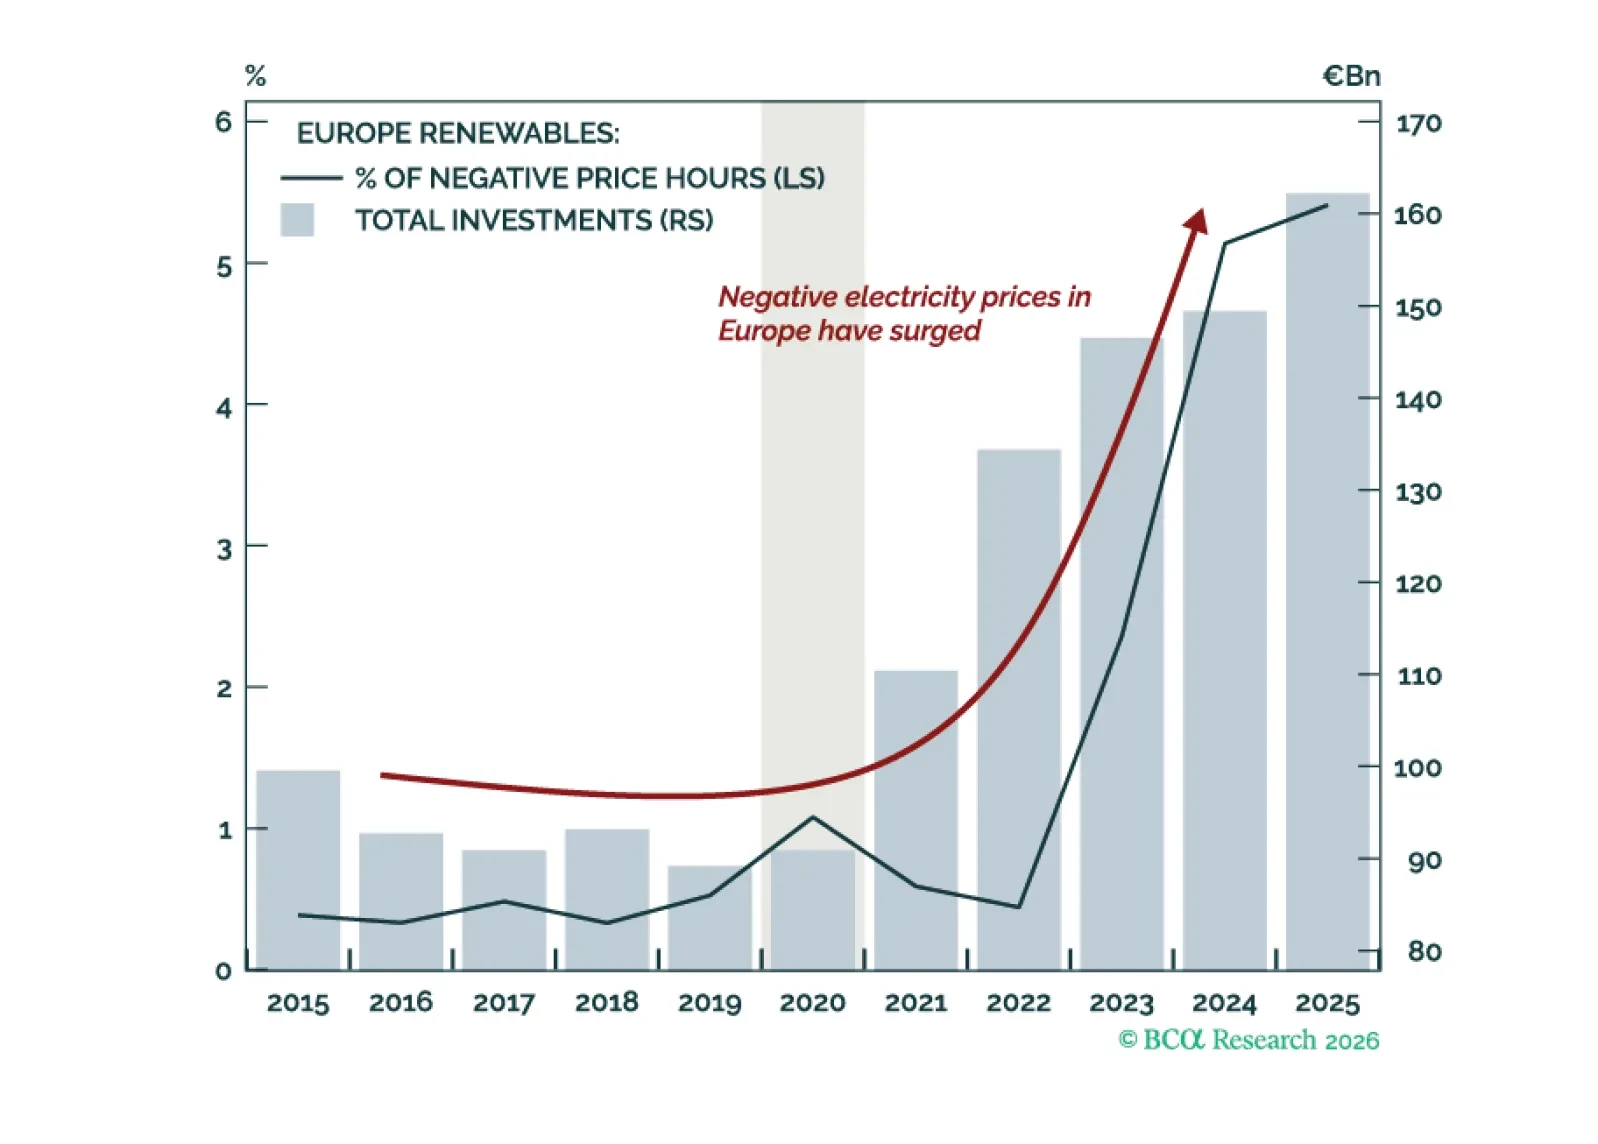
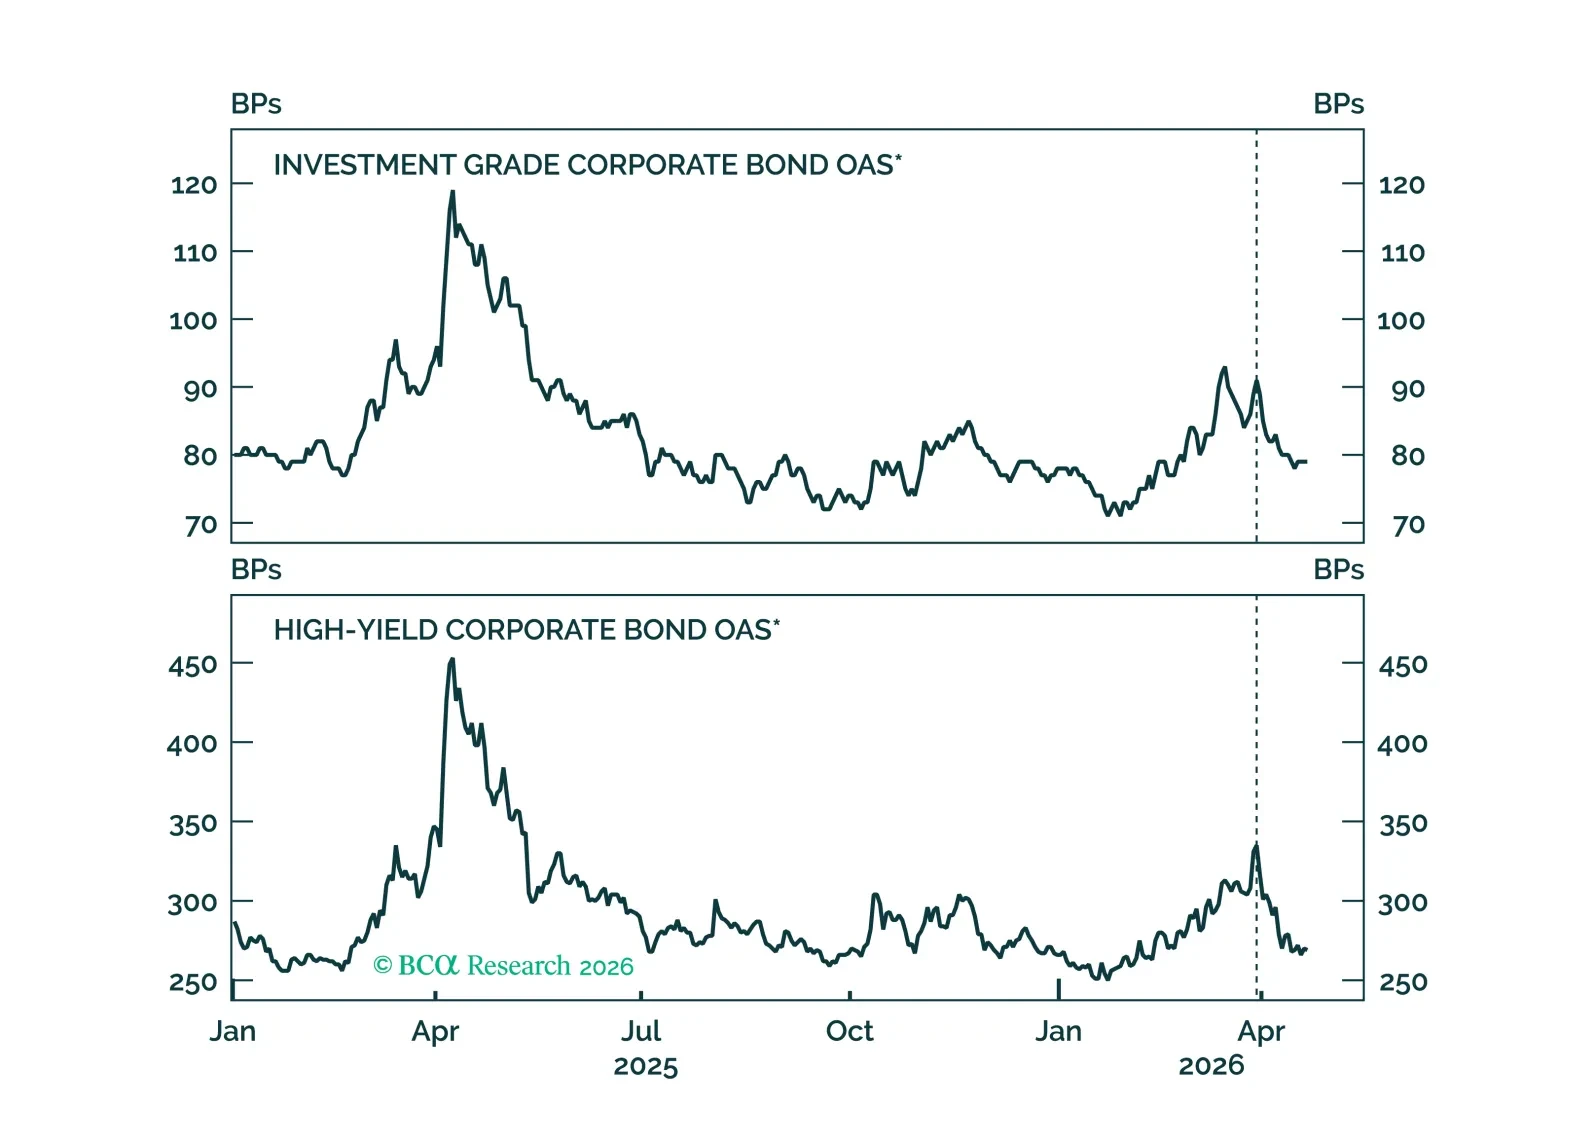
We recommend increasing exposure to spread product as the US economy transitions back into a low rate vol regime.
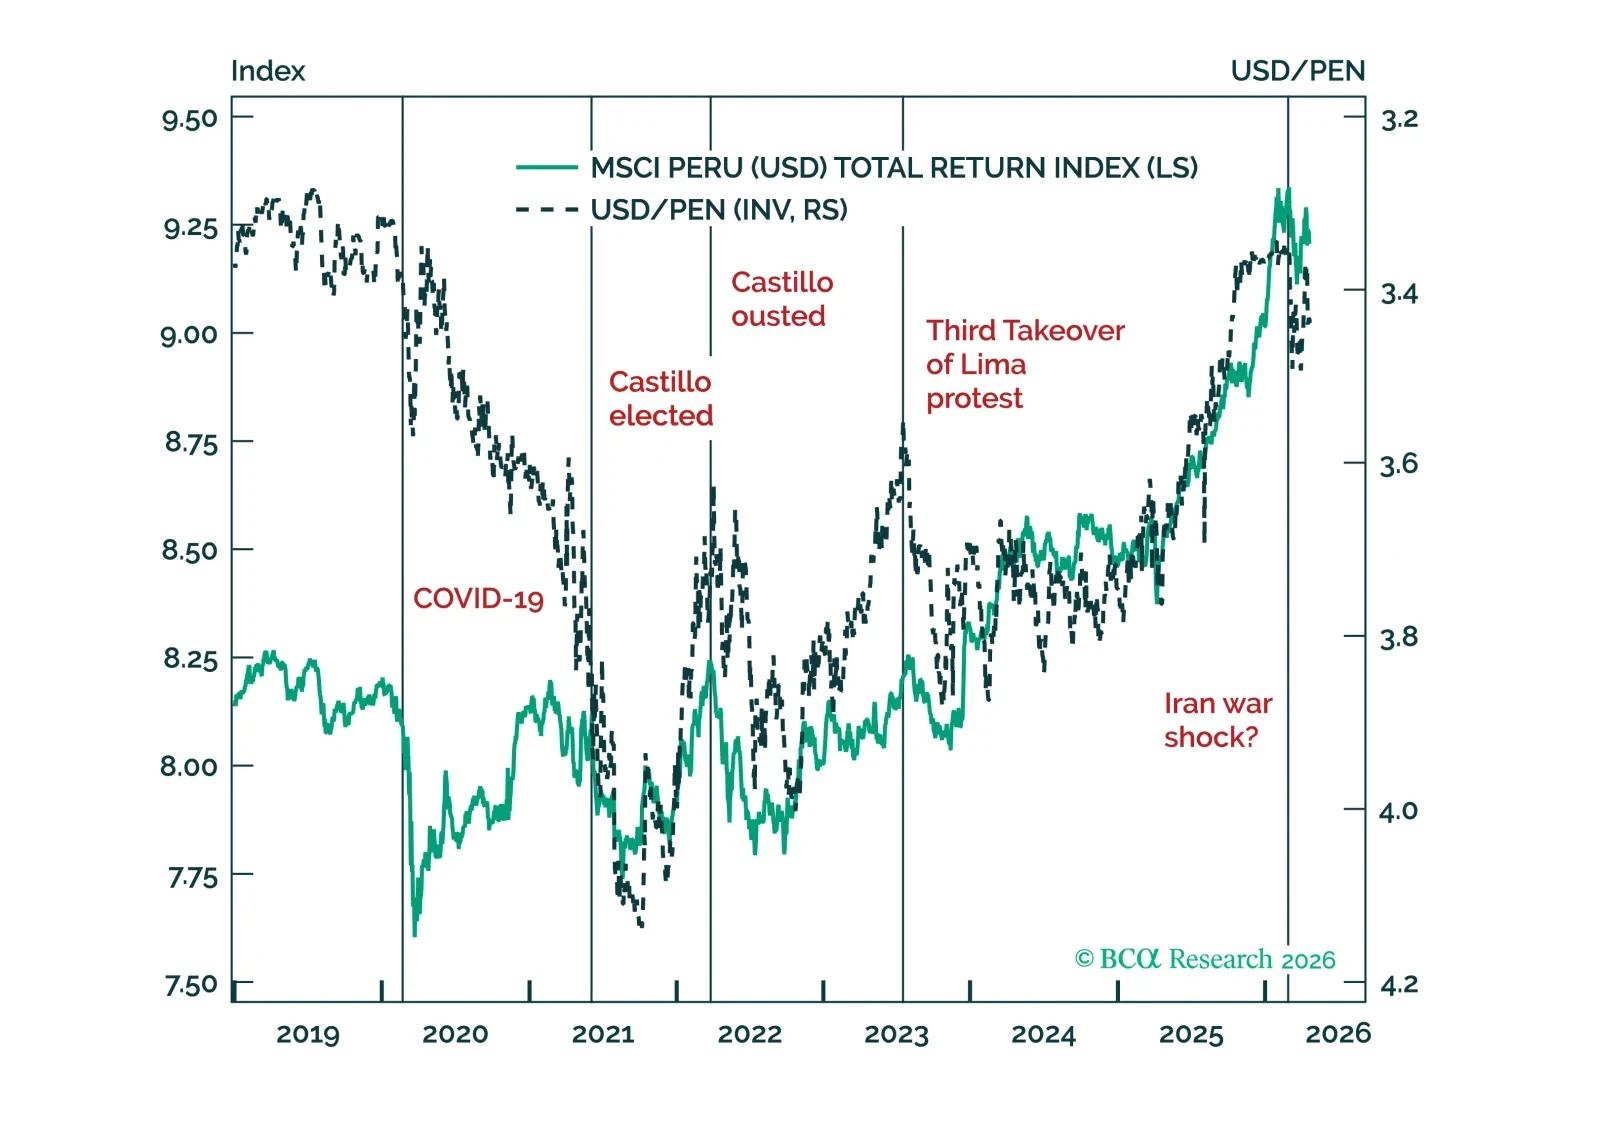
Peru is well established to elect a pro-market government in the June 7 run-off, with institutional constraints limiting left-tail policy risks. We will go long Peruvian assets when Hormuz volatility subsides.

The debate over “what replaces the dollar” is misguided. The real shift is toward a multi-anchor system where reserve functions fragment. That changes everything from term premia to cross-asset correlations. The implication: portfolios built for the old regime are already behind the curve.
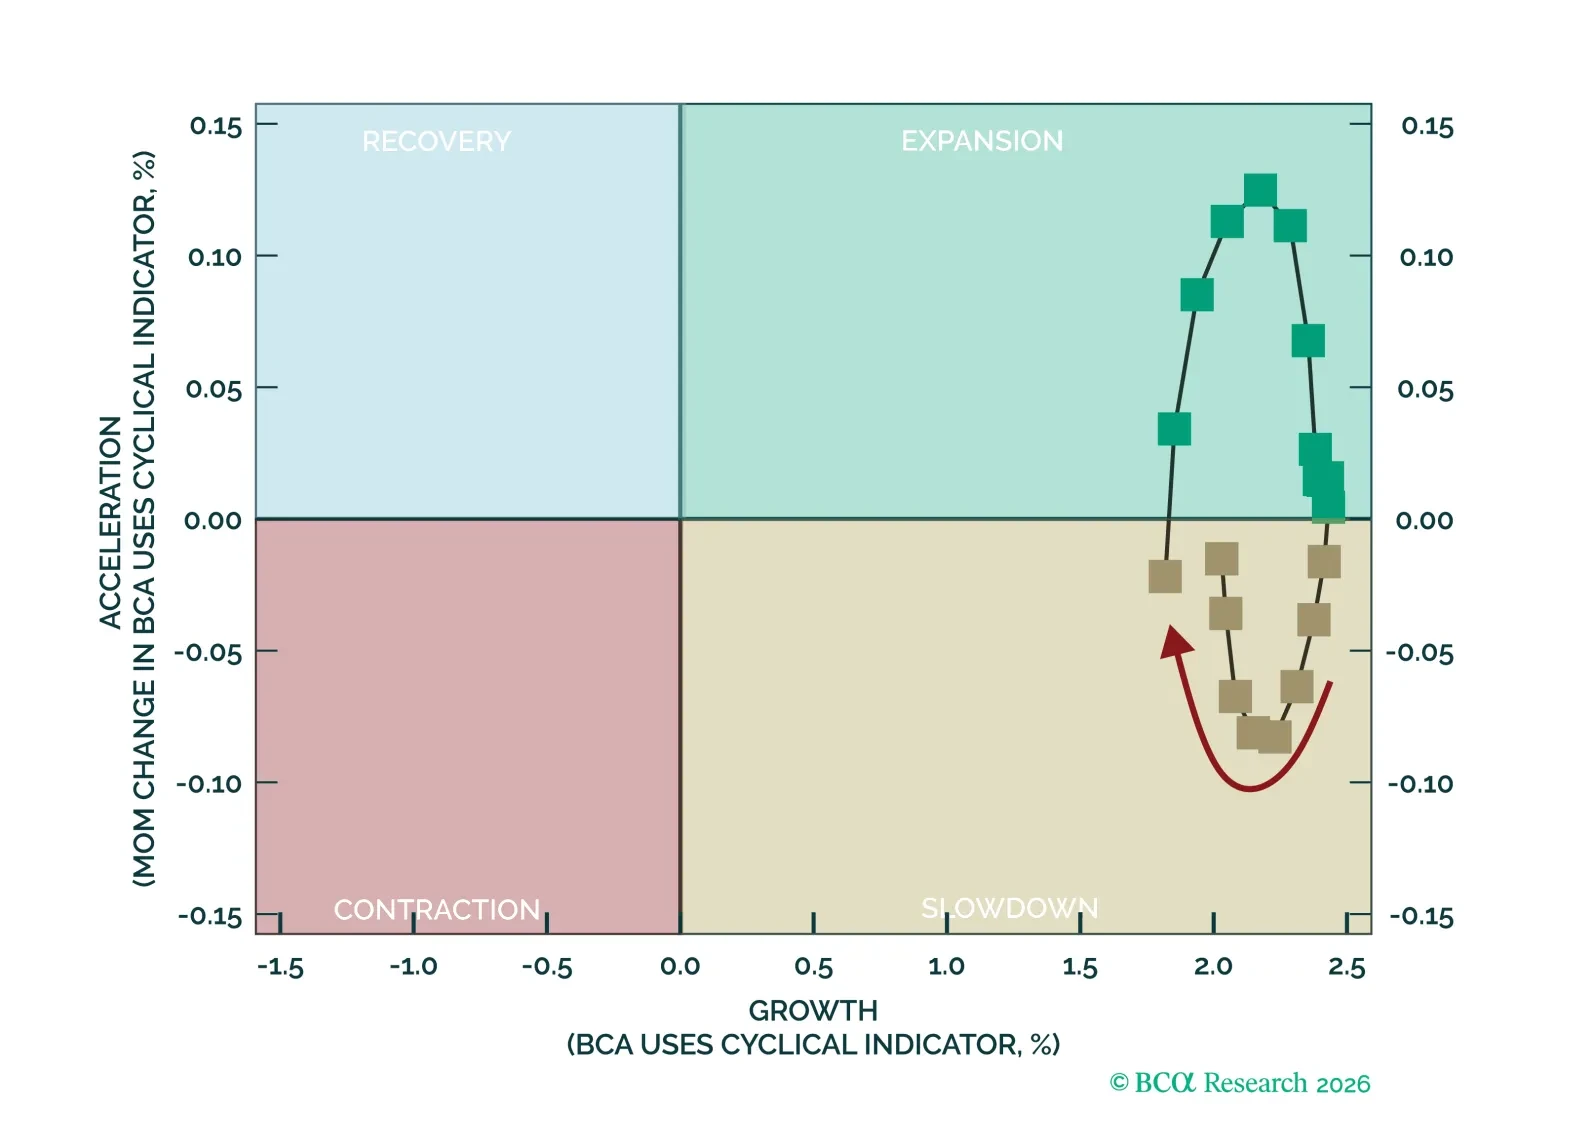
The S&P 500 rally is likely more than just risk-relief. Market internals reflect strengthening economic growth and higher inflation, with support coming from robust earnings. Tight financial conditions have compressed valuations, particularly within the Tech sector. We are initiating a long Software trade ahead of earnings season, given that multiples have declined and earnings growth is strong.
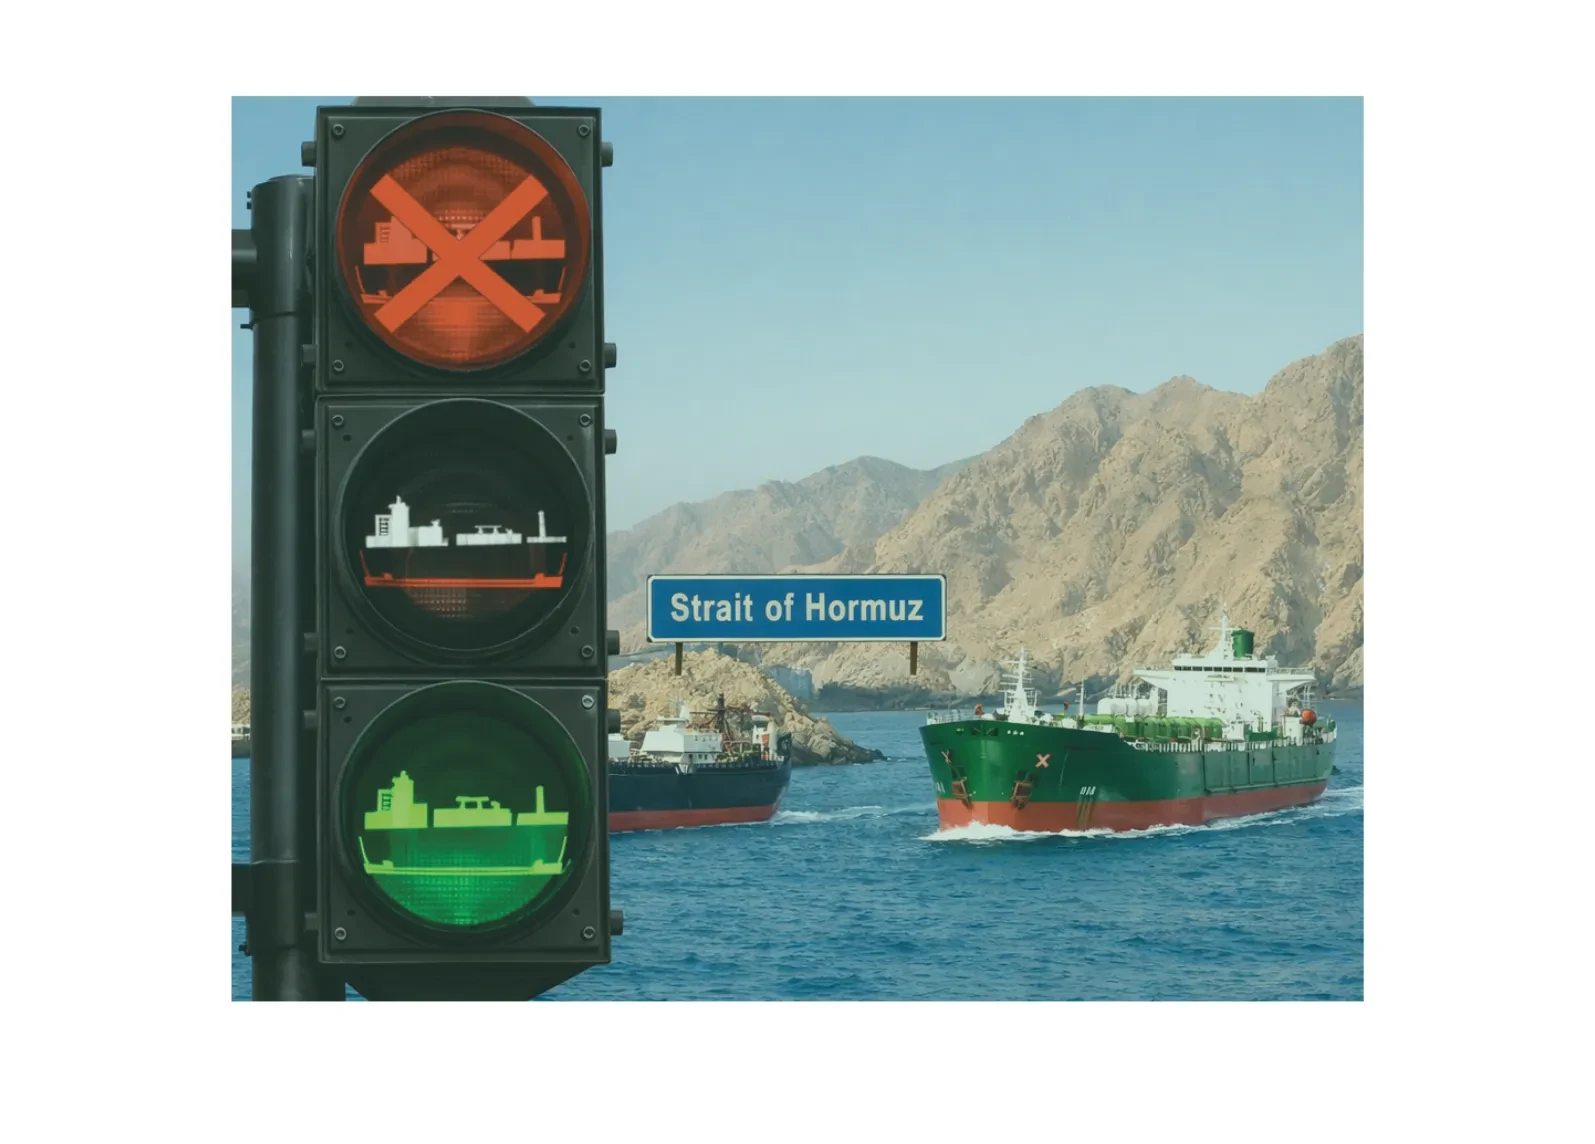
Red Light. Green Light. So much for the “all clear” in the Hormuz saga.
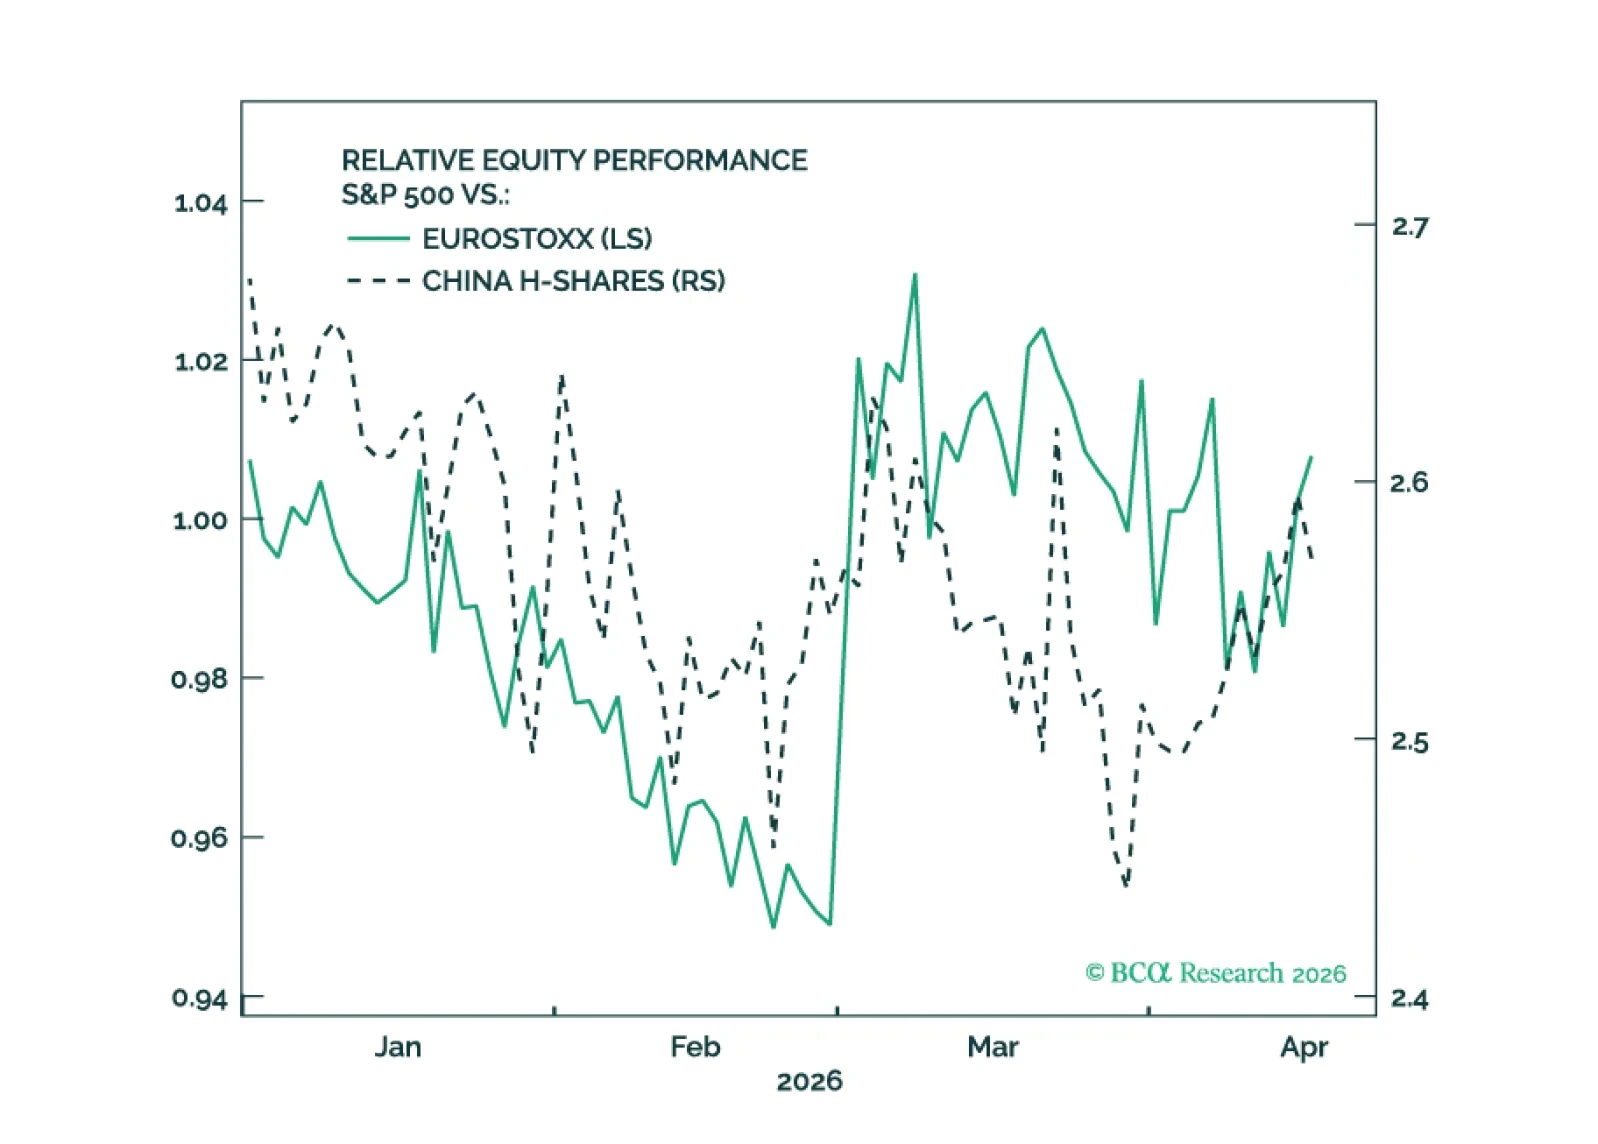
The Iran war is deescalating further — against our expectations — setting up an aggressive return to the risk-on rally.