Latest from BCA Research

Almost all bull markets are built on a foundation of truth. With enough time, however, FOMO takes over, causing prices to overshoot fundamentals. This is what has happened to gold and silver, and increasingly to other metals as well.
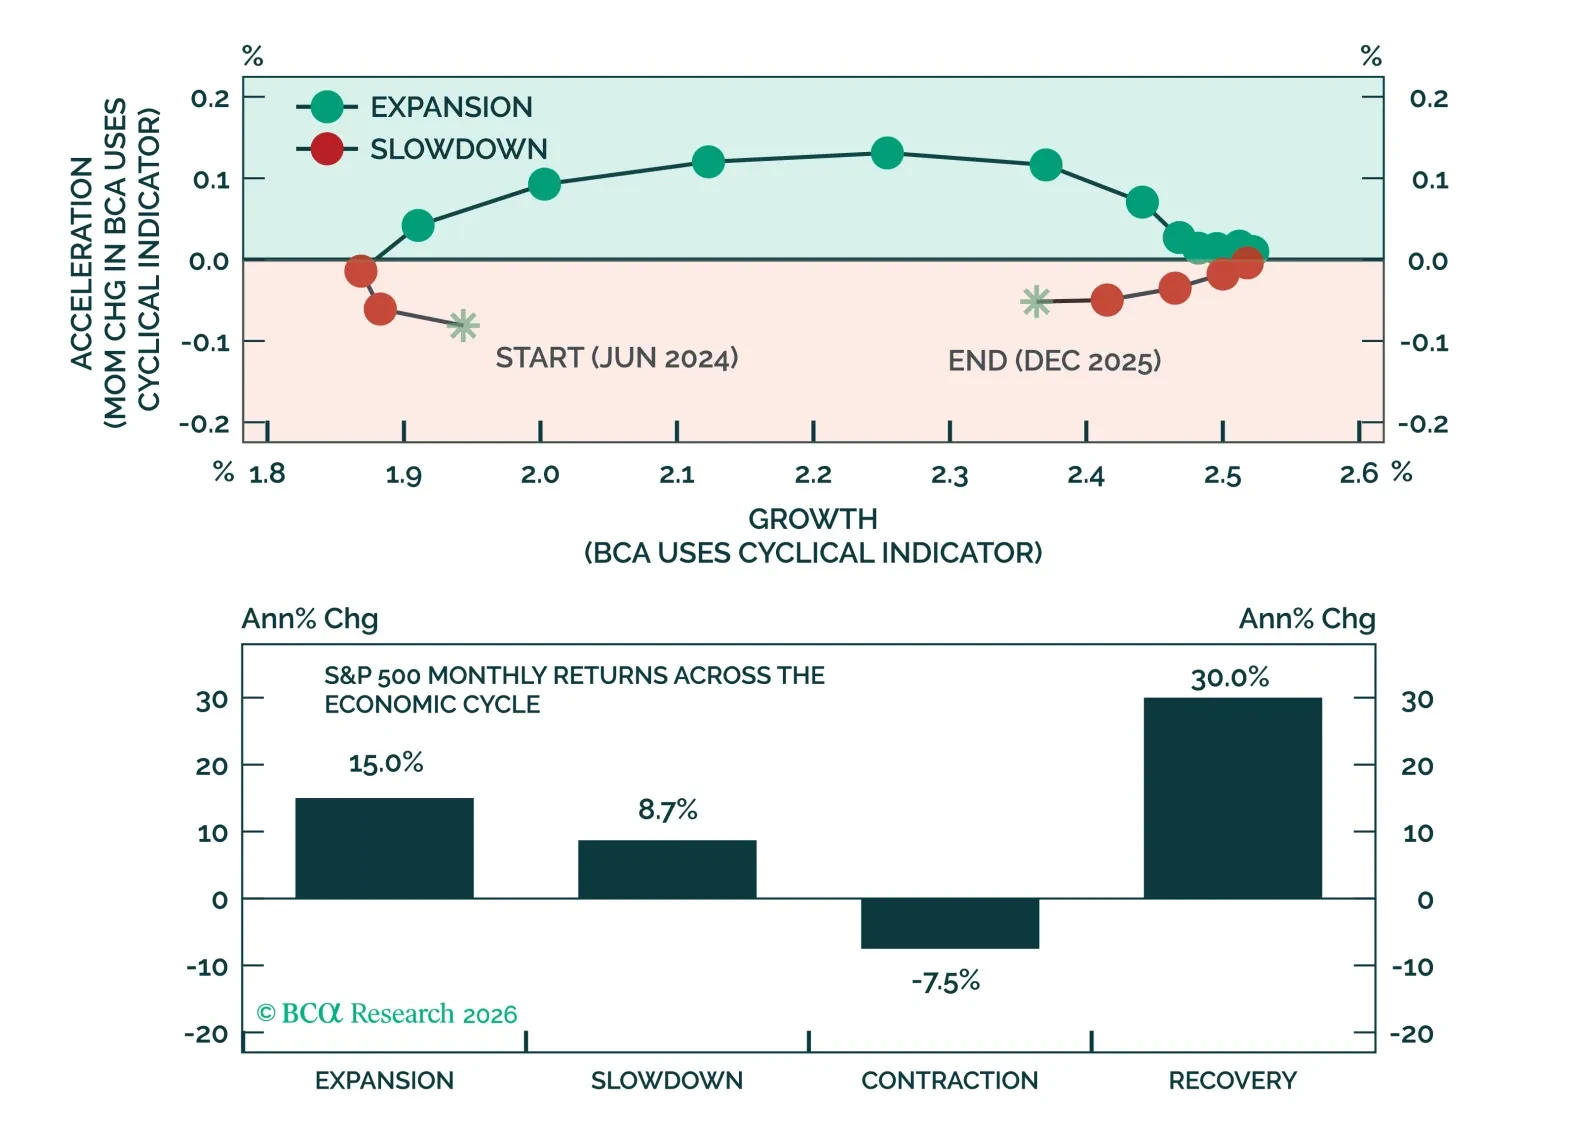
2026 should see another year of gains for the S&P 500, but, as the bull market matures and growth slows, returns will be capped by revenue growth rather than being boosted by expanding margins and multiples. We think Tech can outperform, but leadership will broaden and performance gaps will narrow.
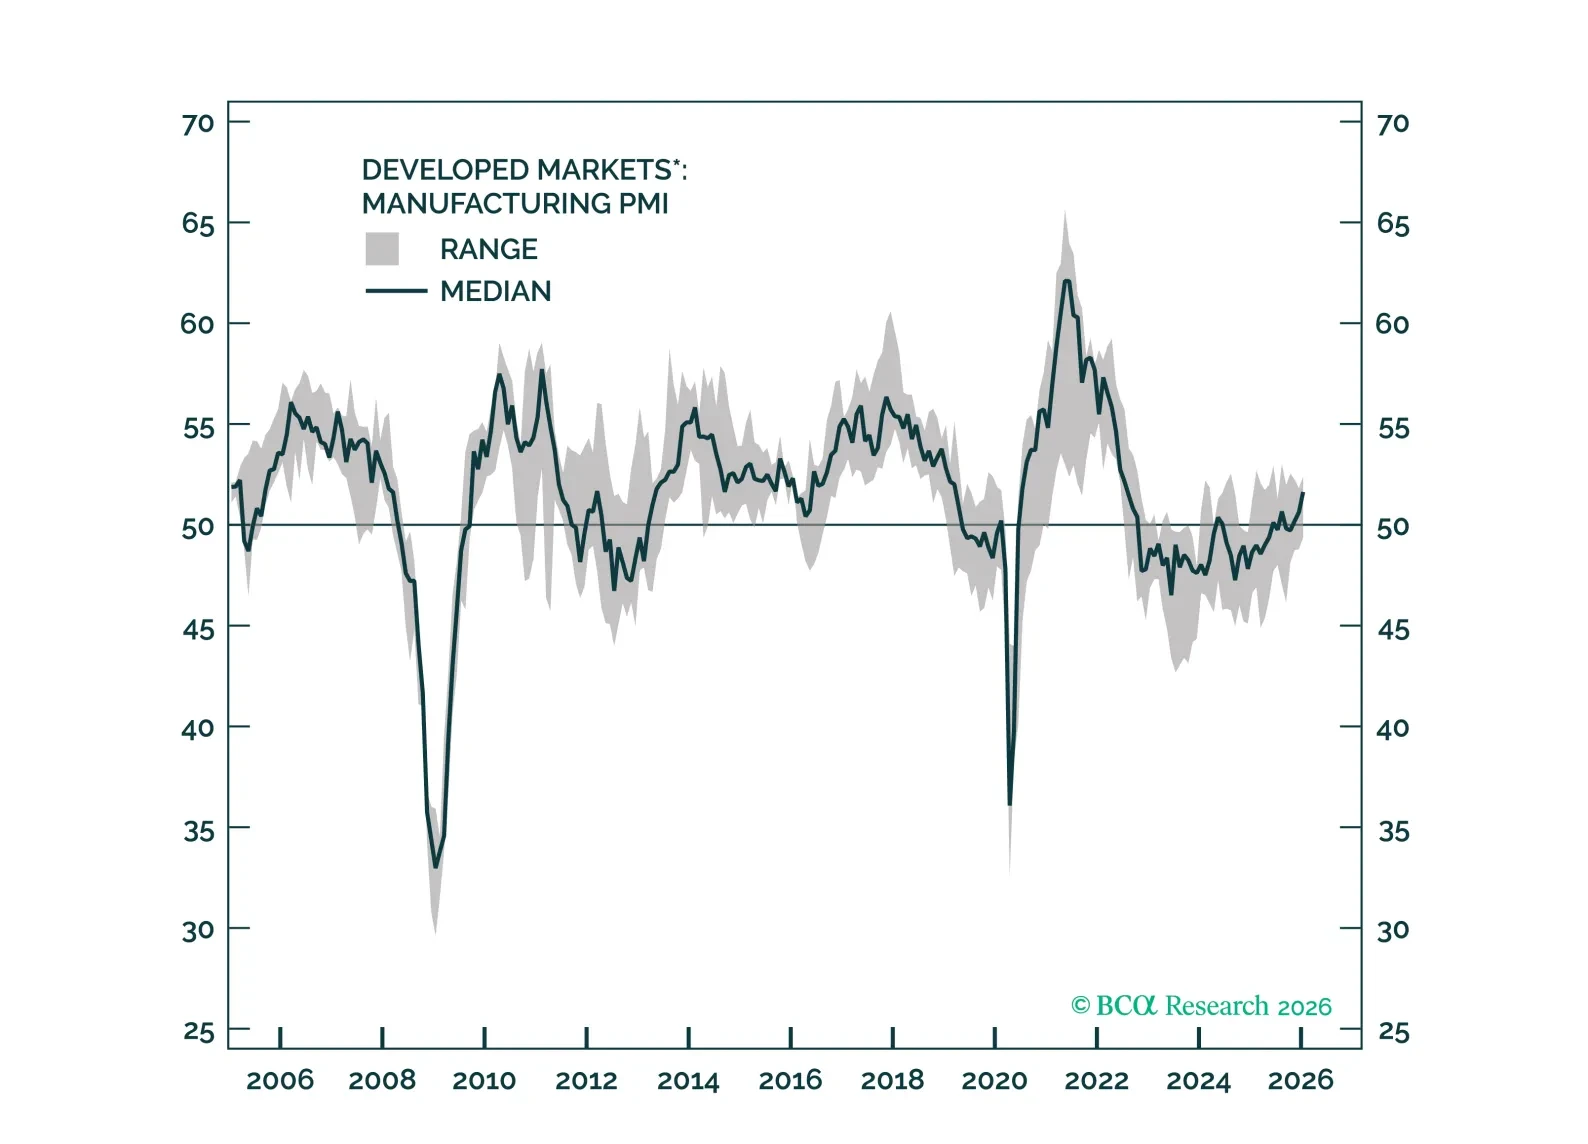
The actions of the Trump administration have dominated the headlines over the past month. They are all noise. Focus on the reactions from the rest of the world. Policy makers outside of the US are now determined to stimulate and reform their domestic economies. Global growth is accelerating without a corresponding increase in inflation. This combination is not only positive for risk assets but is also supercharging returns for Ex-US stocks. Downgrade Fixed Income and duration.
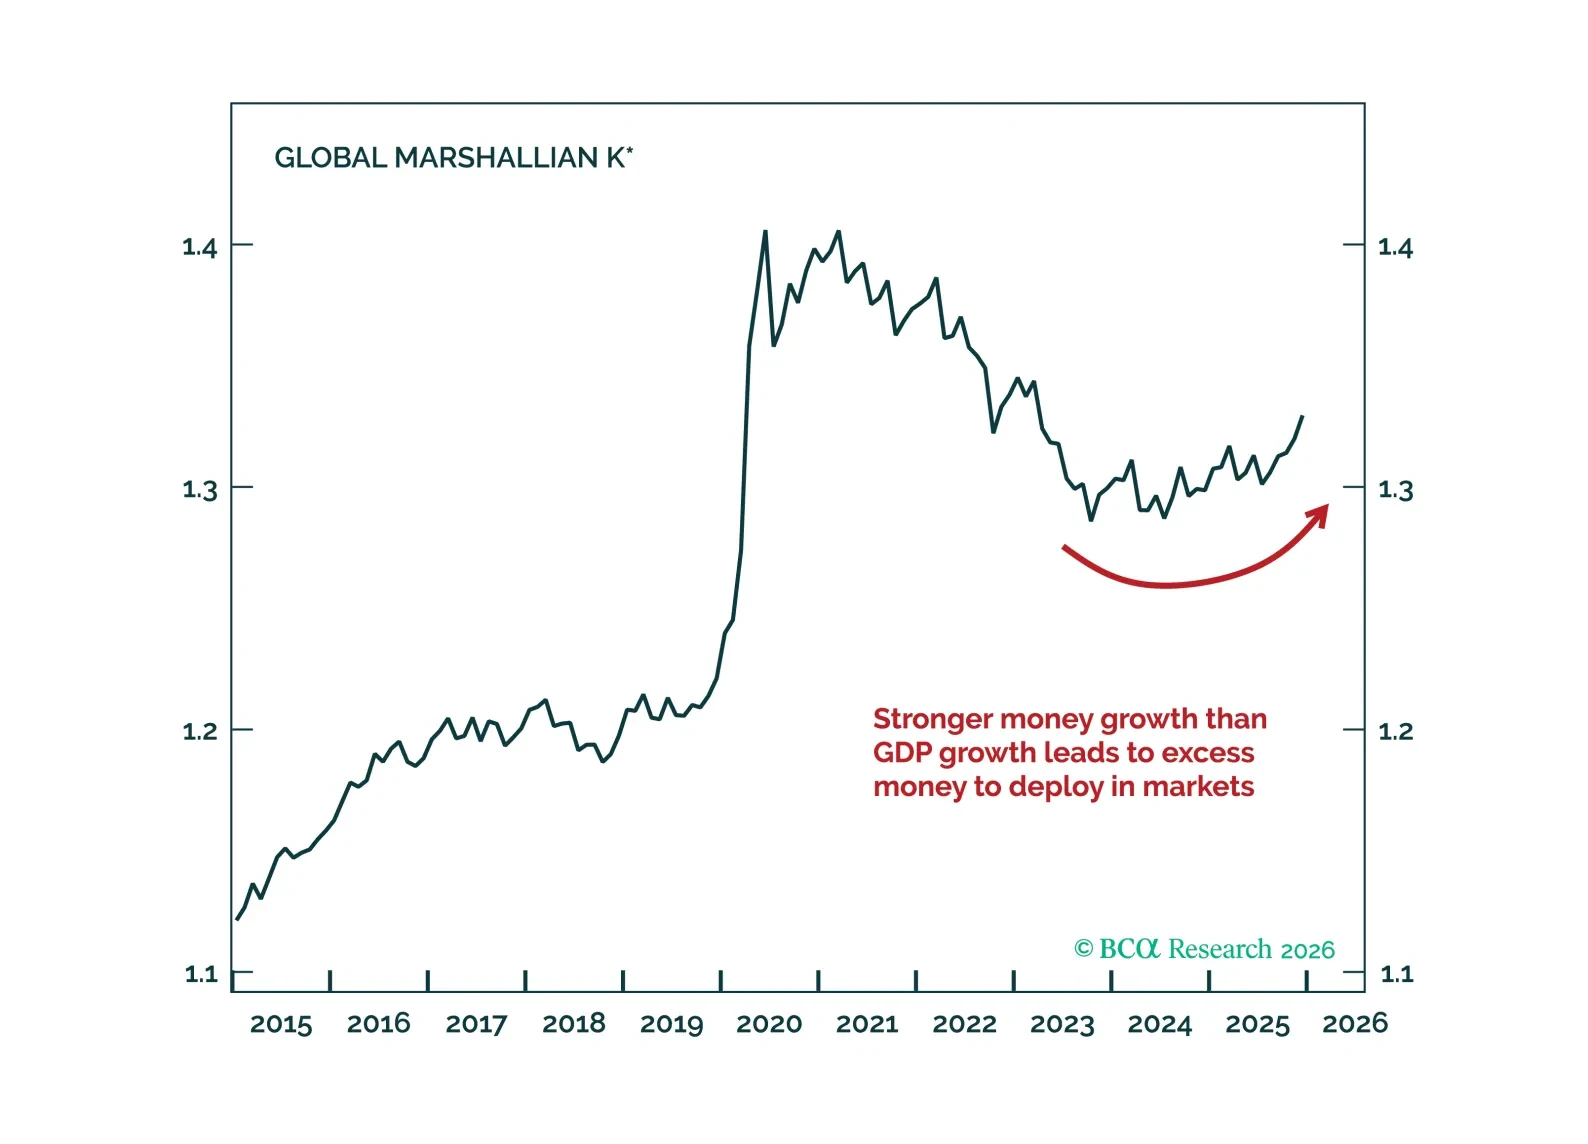
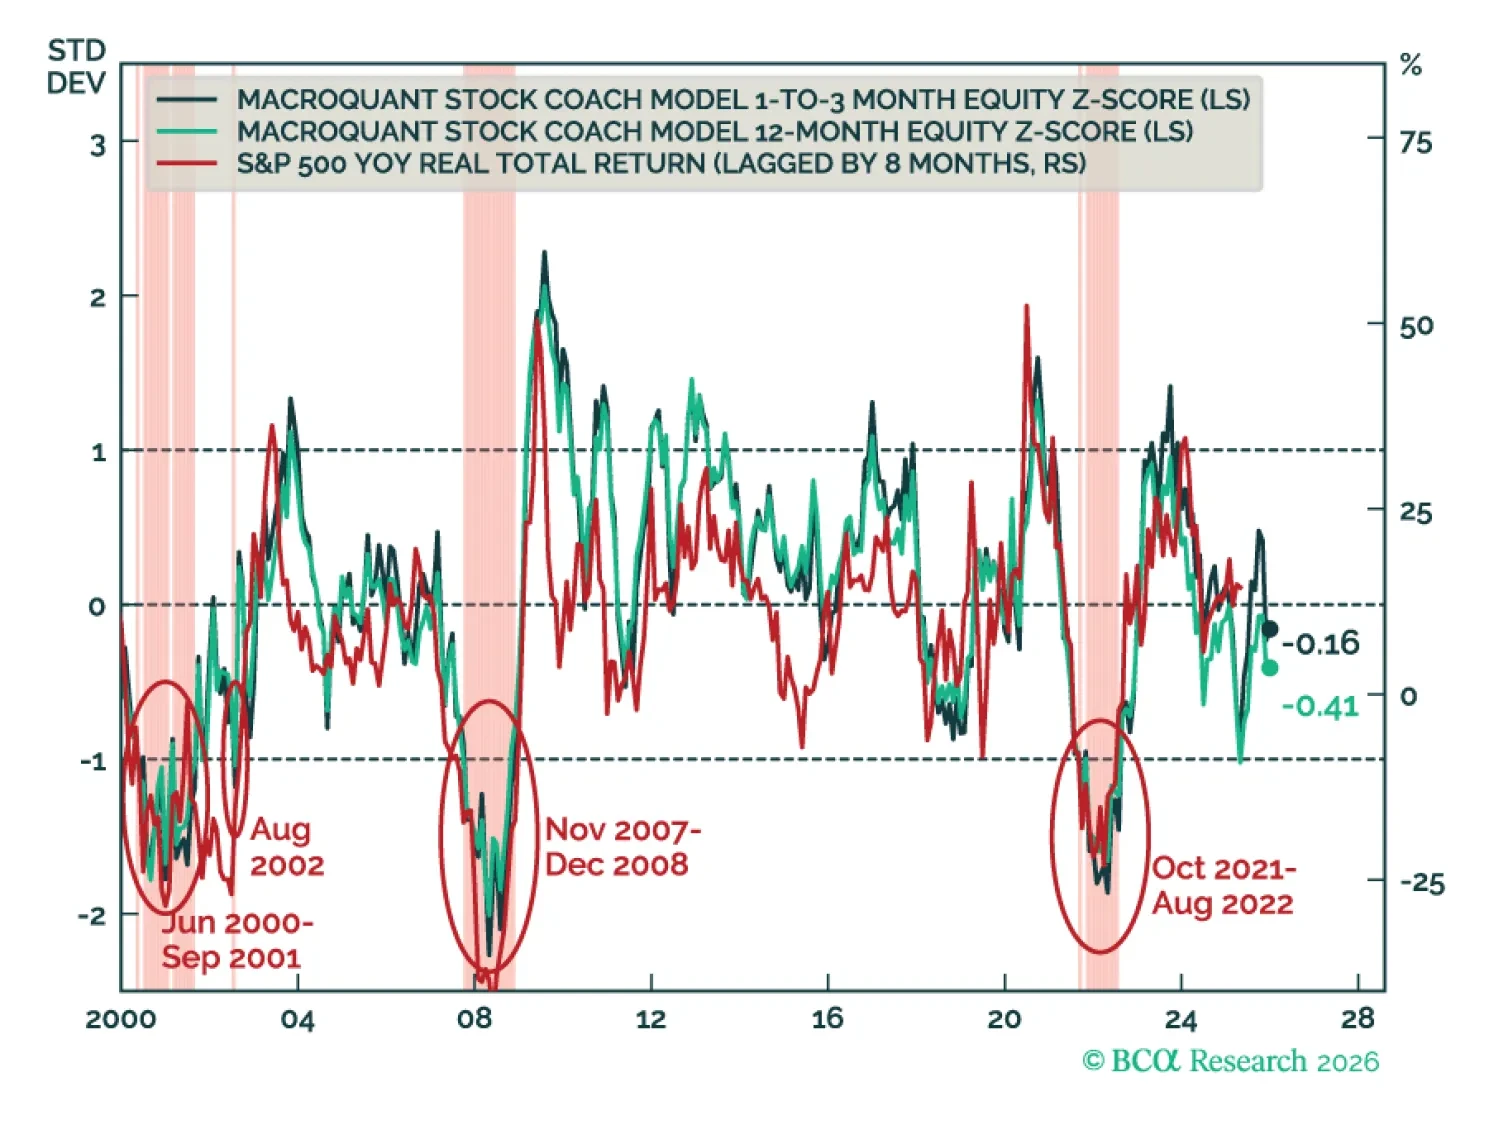
MacroQuant recommends a slight underweight in equities, favors a below-benchmark duration stance in fixed-income portfolios, remains bearish on the US dollar, has upgraded oil and copper to overweight, and is bullish on gold.
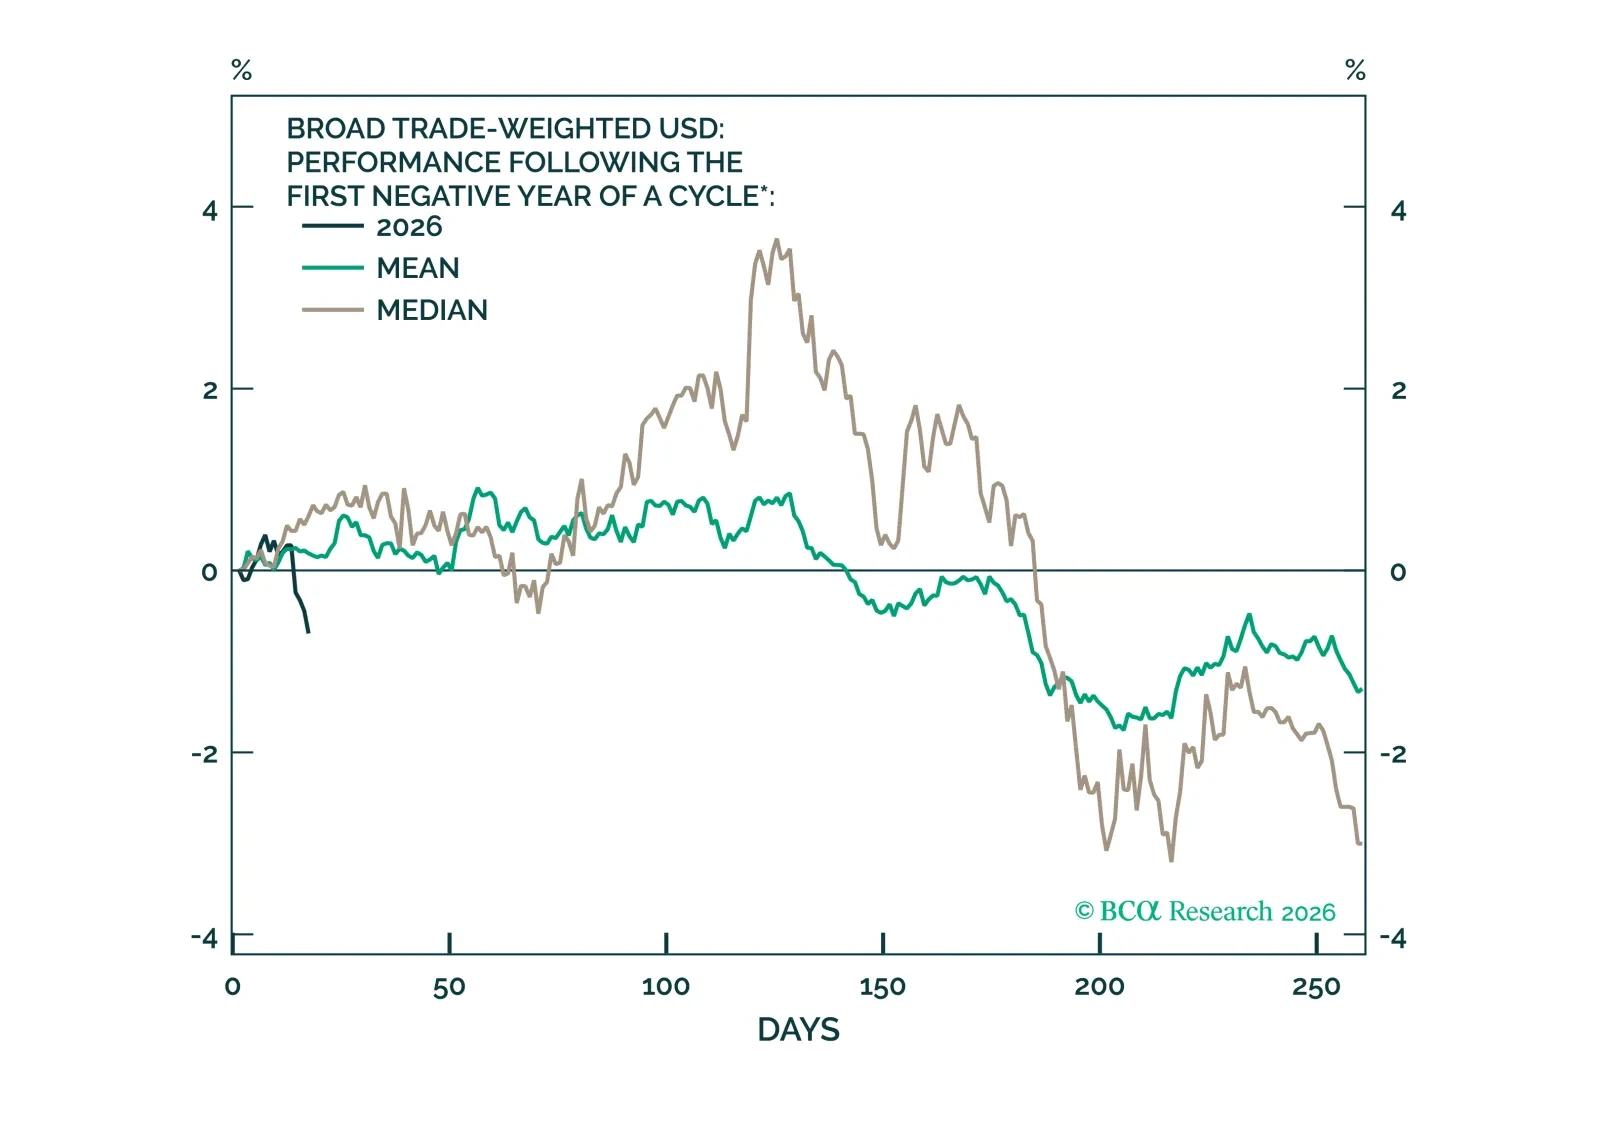
FX markets have dominated headlines over the past week, with a meltdown in the dollar and a surge in the yen. This week’s note unpacks the forces behind these moves and assesses whether recent price action marks a temporary dislocation or the start of a more durable FX shift.
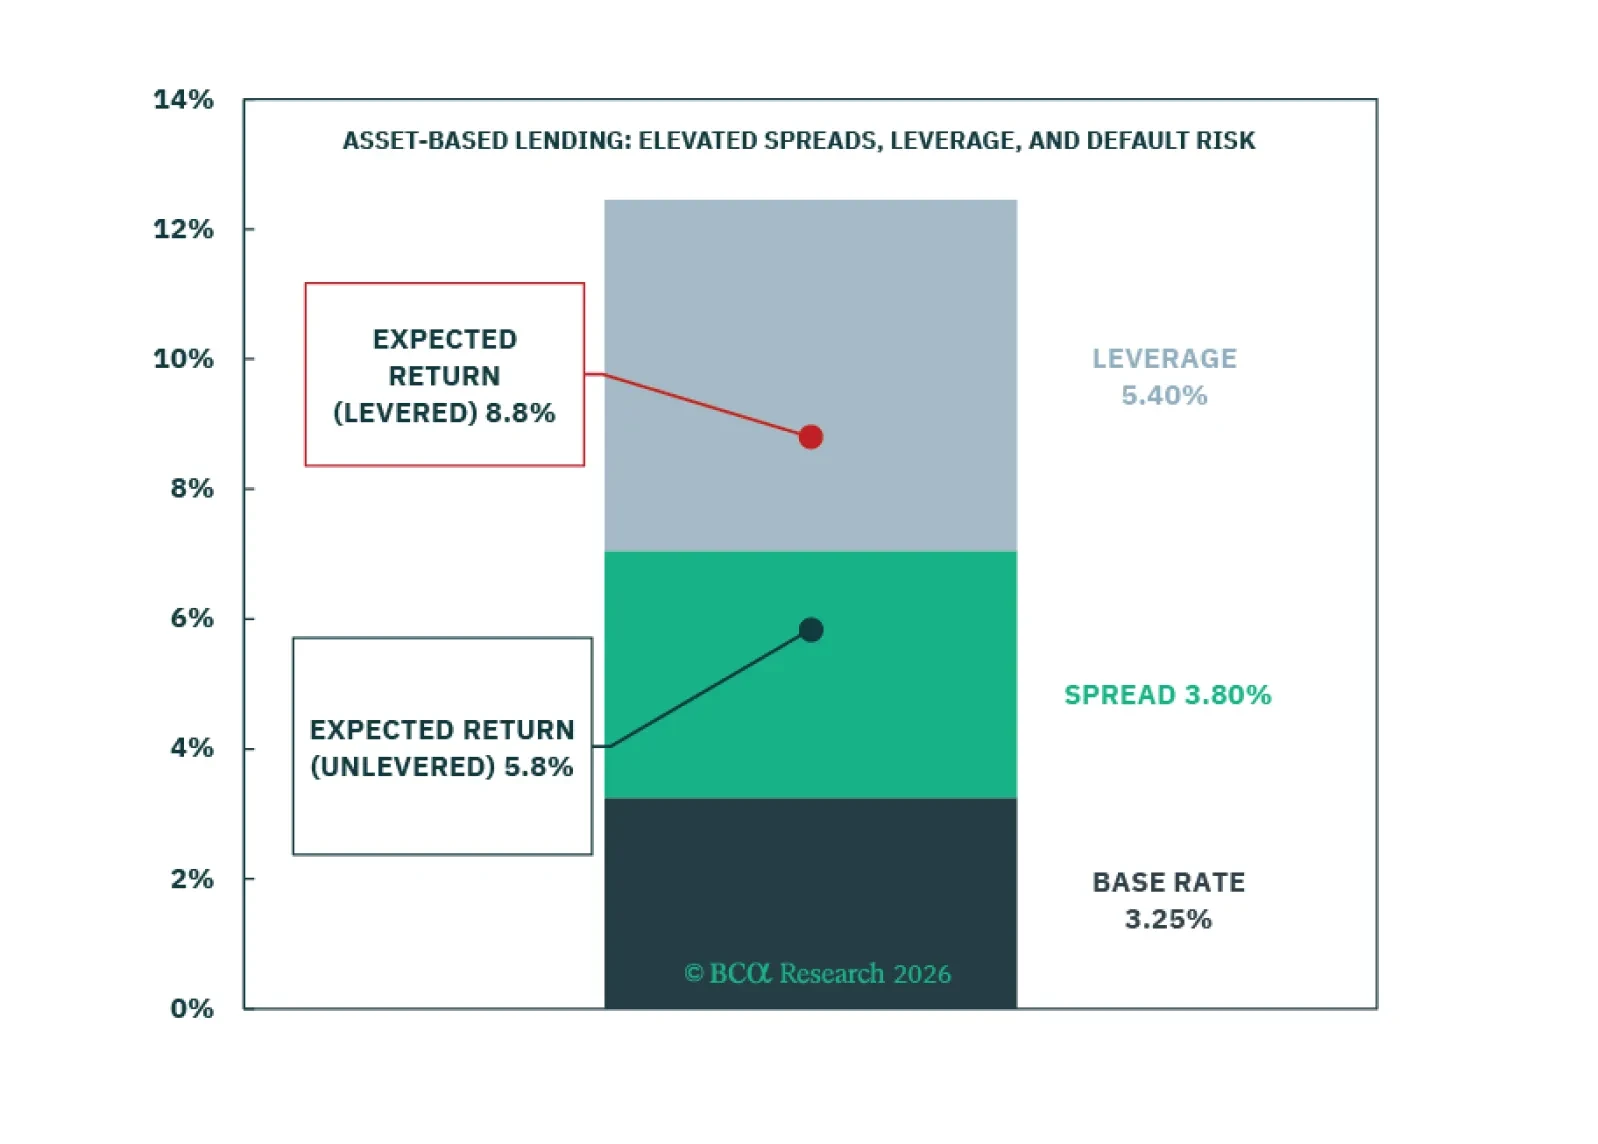
Our new Private Credit taxonomy adds granularity to the opaque lending universe and introduces Asset-Based Lending—attractive entry points, elevated risks. Private Real Estate delivers the largest upgrades from 2025, while Public REITs and Public Infrastructure present compelling opportunities that investors should not overlook.
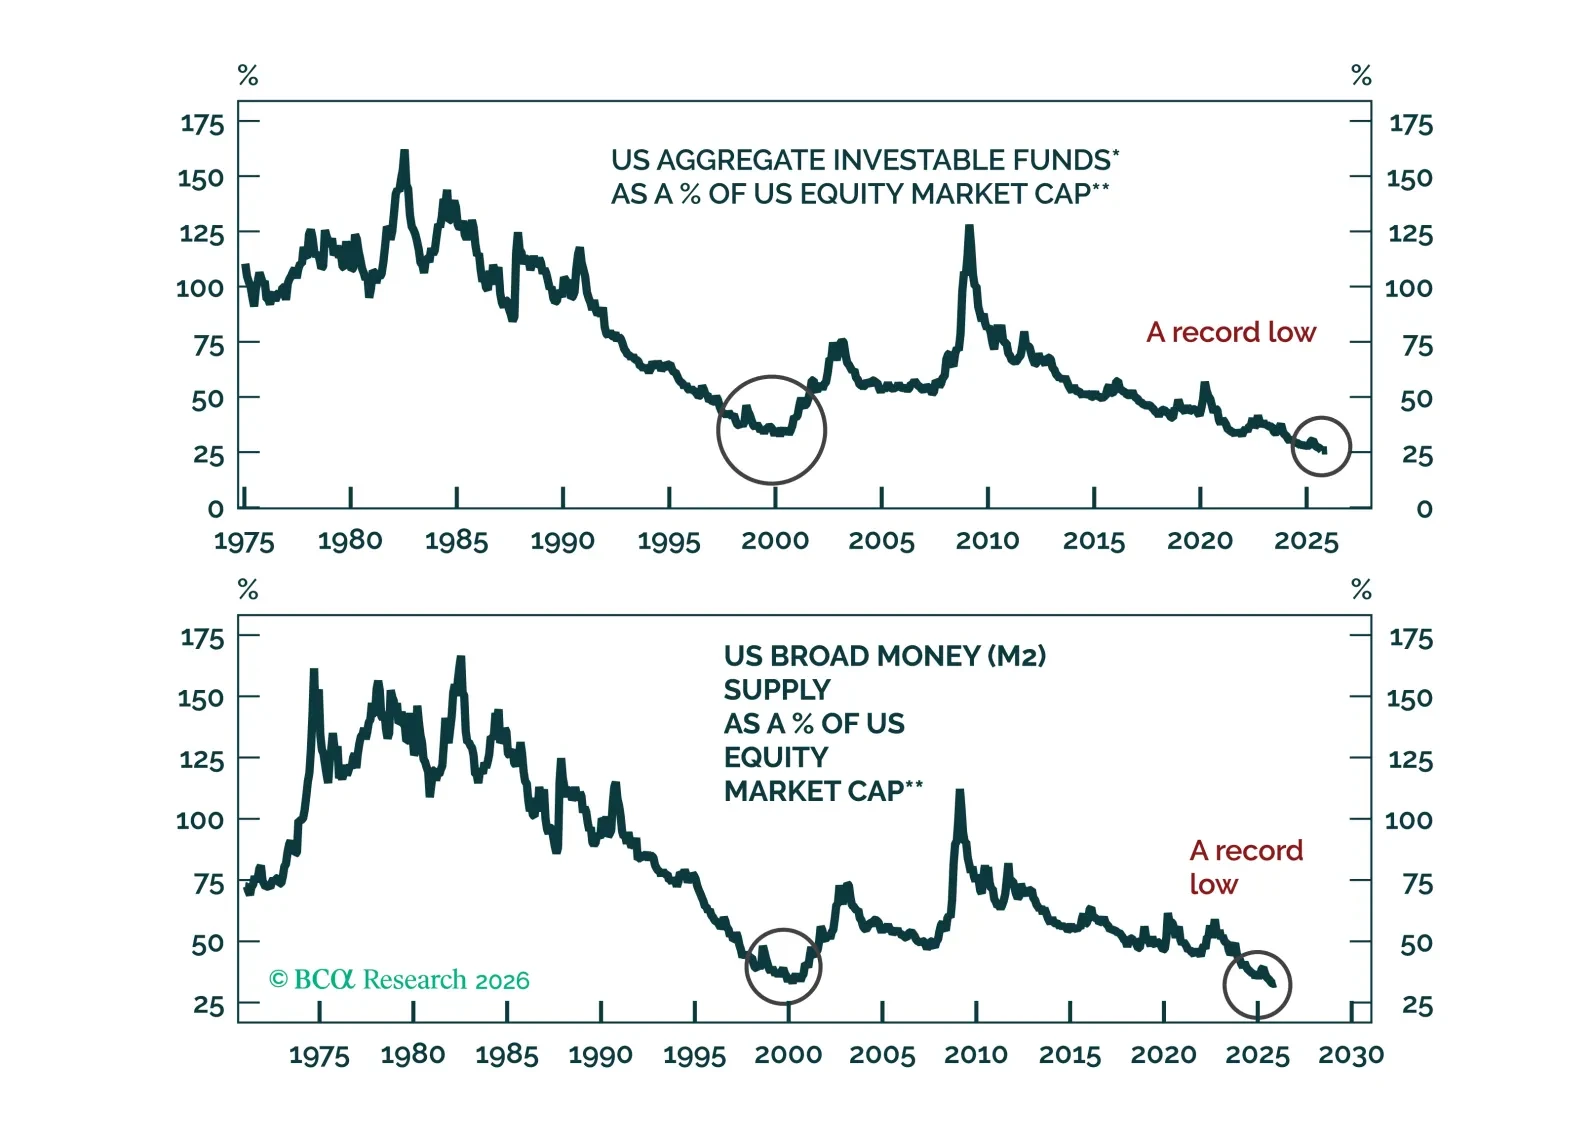
Contrary to widespread narratives, there is little cash on the sidelines. The aggregate amount of investable funds-to-equity market cap ratio is at an all-time low in the US and very low in other developed markets.