Latest from BCA Research
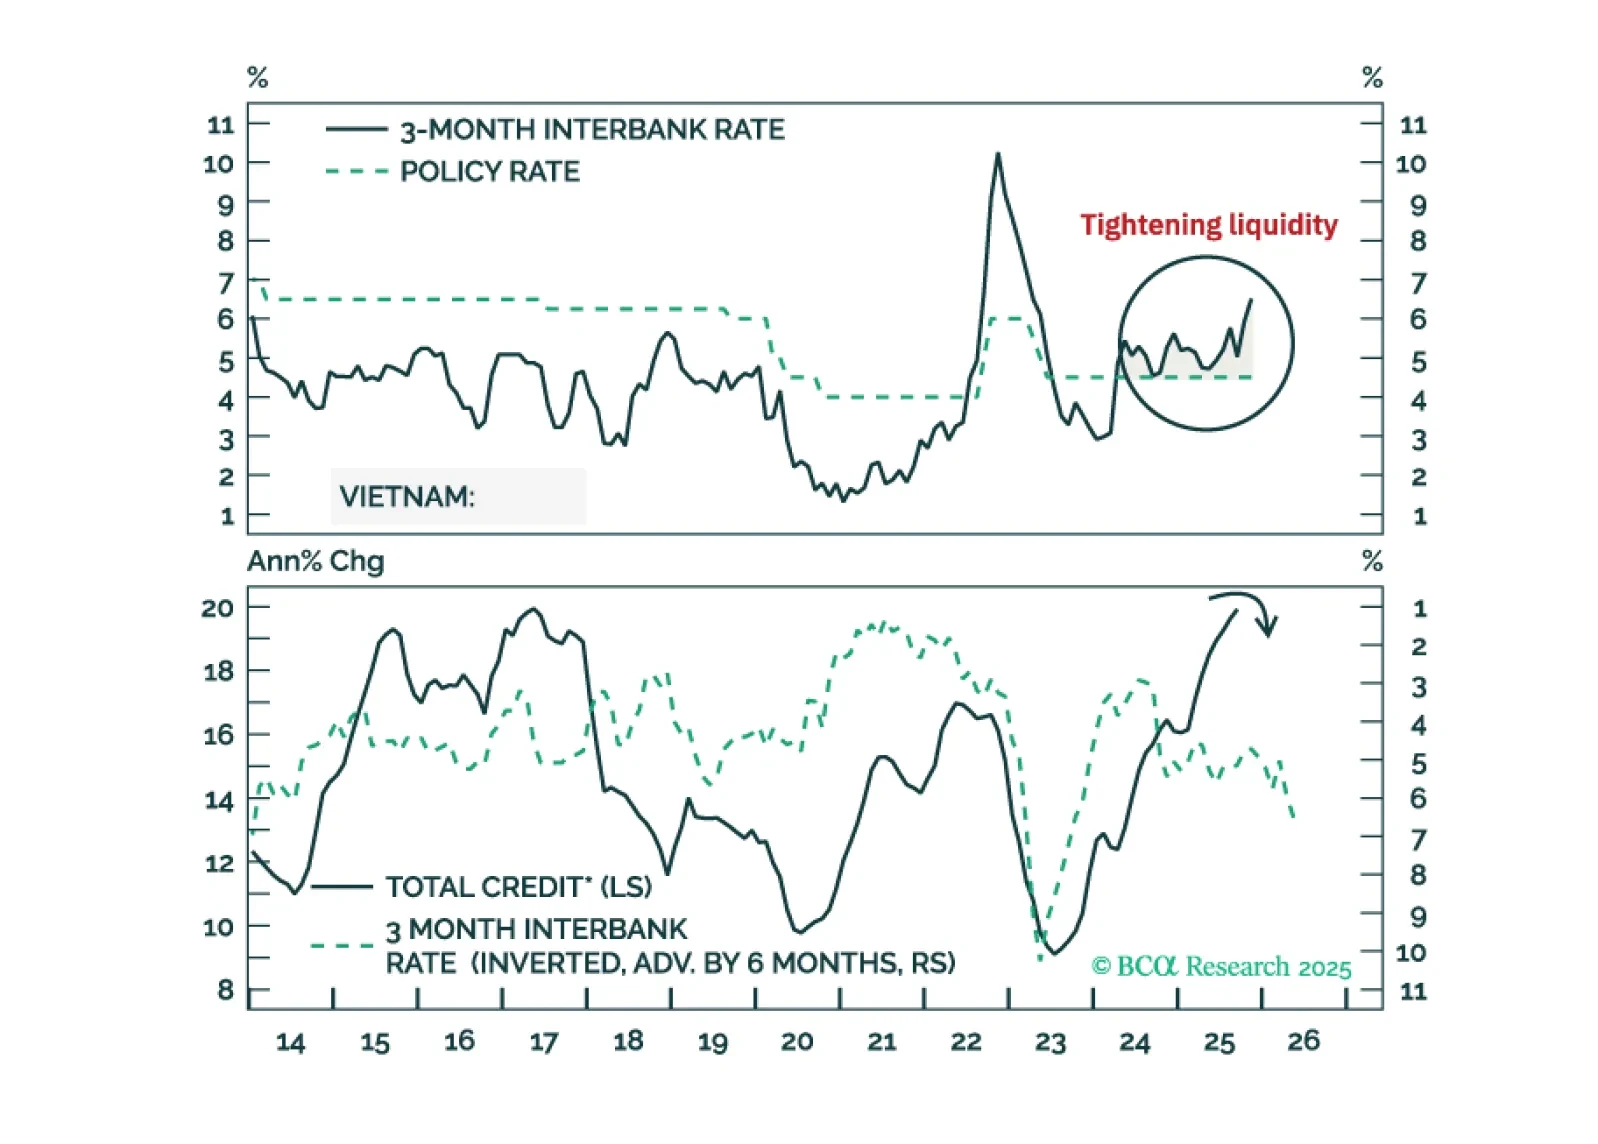
We remain bullish on the alpha-generating potential of Vietnamese stocks over the medium and long term. But our negative outlook on global/EM beta makes us bearish on this bourse in absolute terms over the medium term.
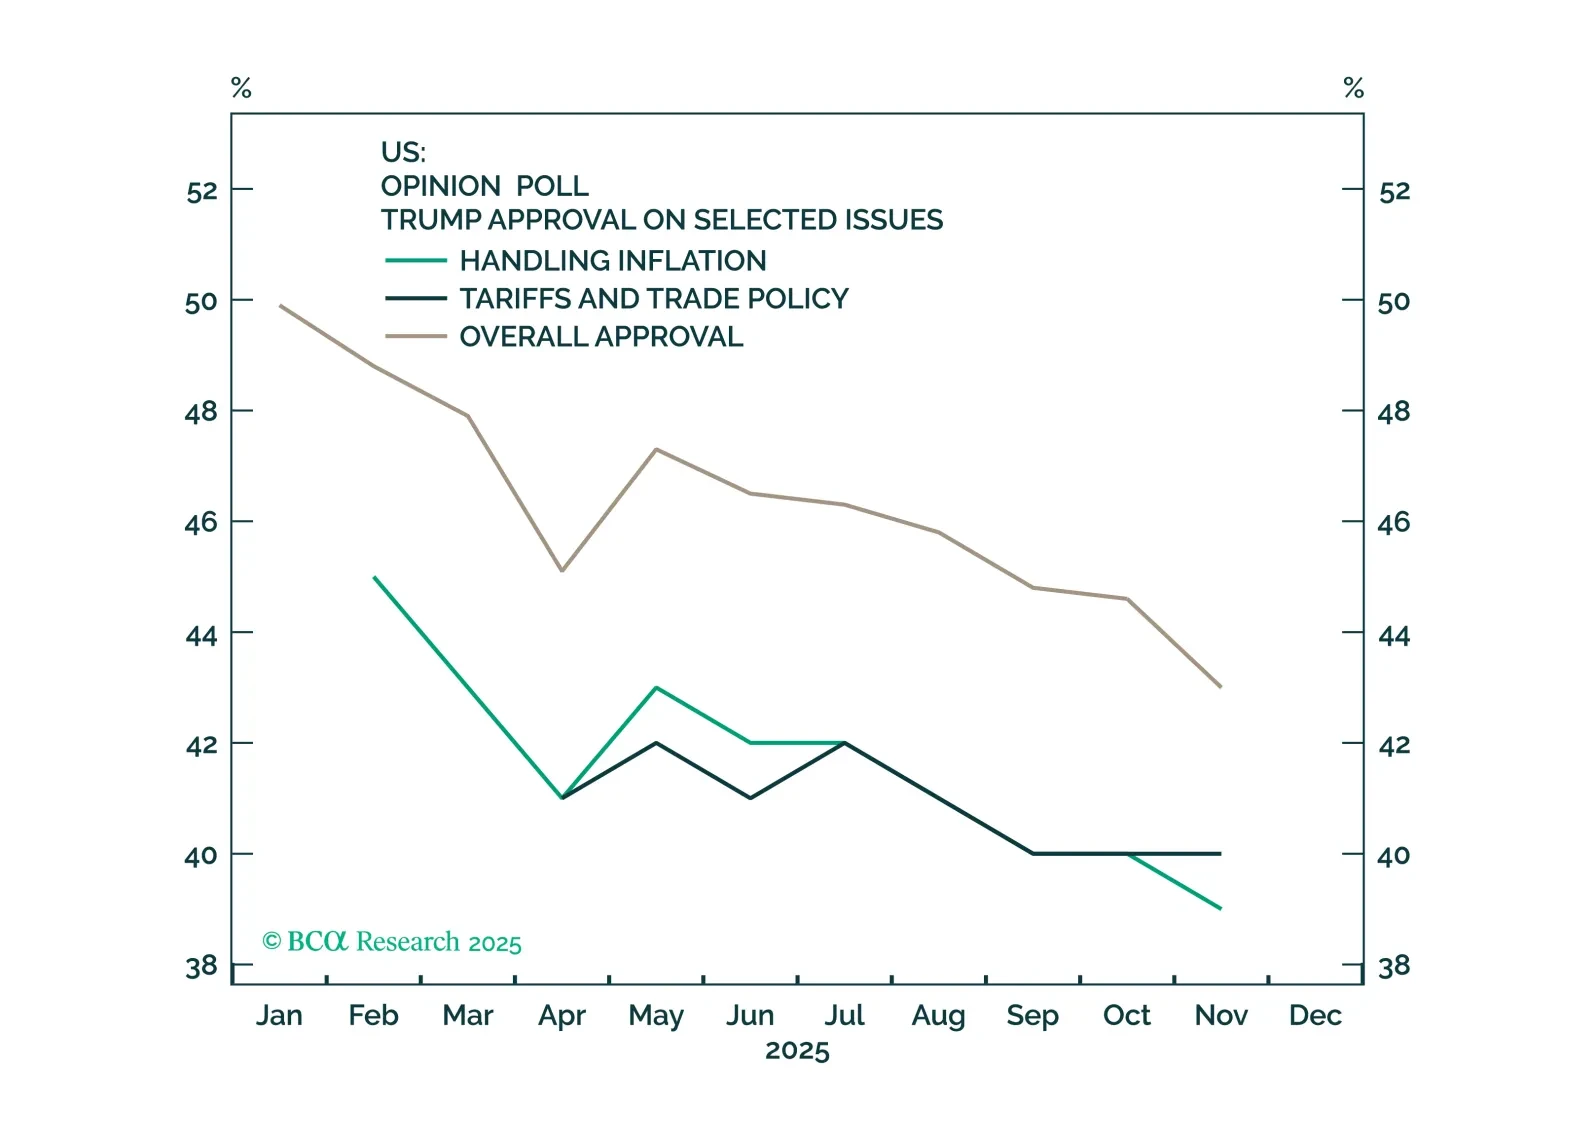
On purely macroeconomic terms, the US economy appears to be heading towards a recession. But the whole point of our framework – GeoMacro – is to forecast the interplay between politics, geopolitics, and macro. The White House is taking control of the Fed in 2026 and, together, they will look to re-lever the US consumer.

Japanese financial assets will finally have unfettered access to outsized returns. This performance will come in fits and starts, but we are comfortable laying our cards down on buying the yen, and Japanese industrial stocks.
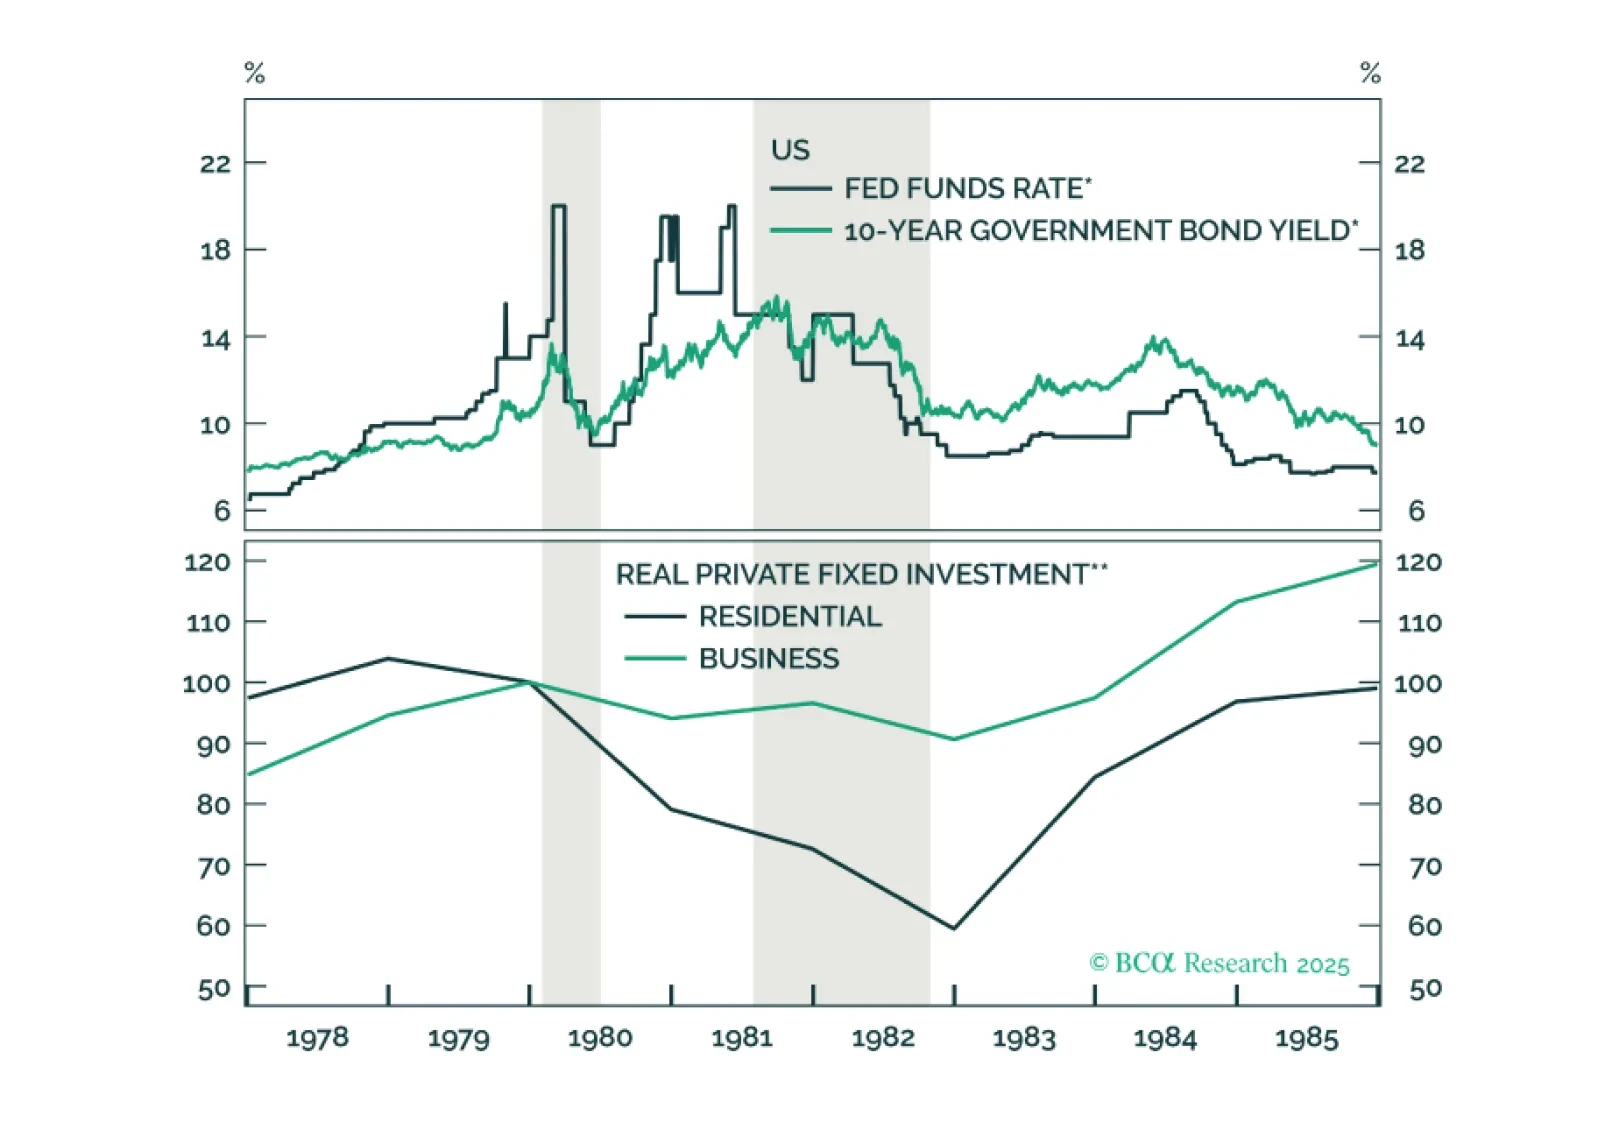
There is an old joke about the drunk who searches for his keys under the light post. When asked why he is looking for his keys there, he replies that “this is where the light is.”

The real reason behind the overt support by the US of Argentina’s experiment is far less exotic and yet also far more lucrative for global investors.

The outperformance of the S&P 500 relative to the S&P 500 EW index is likely to continue over the next year, supported by stronger earnings growth. However, extreme levels of market concentration will ultimately halt the outperformance of the mega-caps.
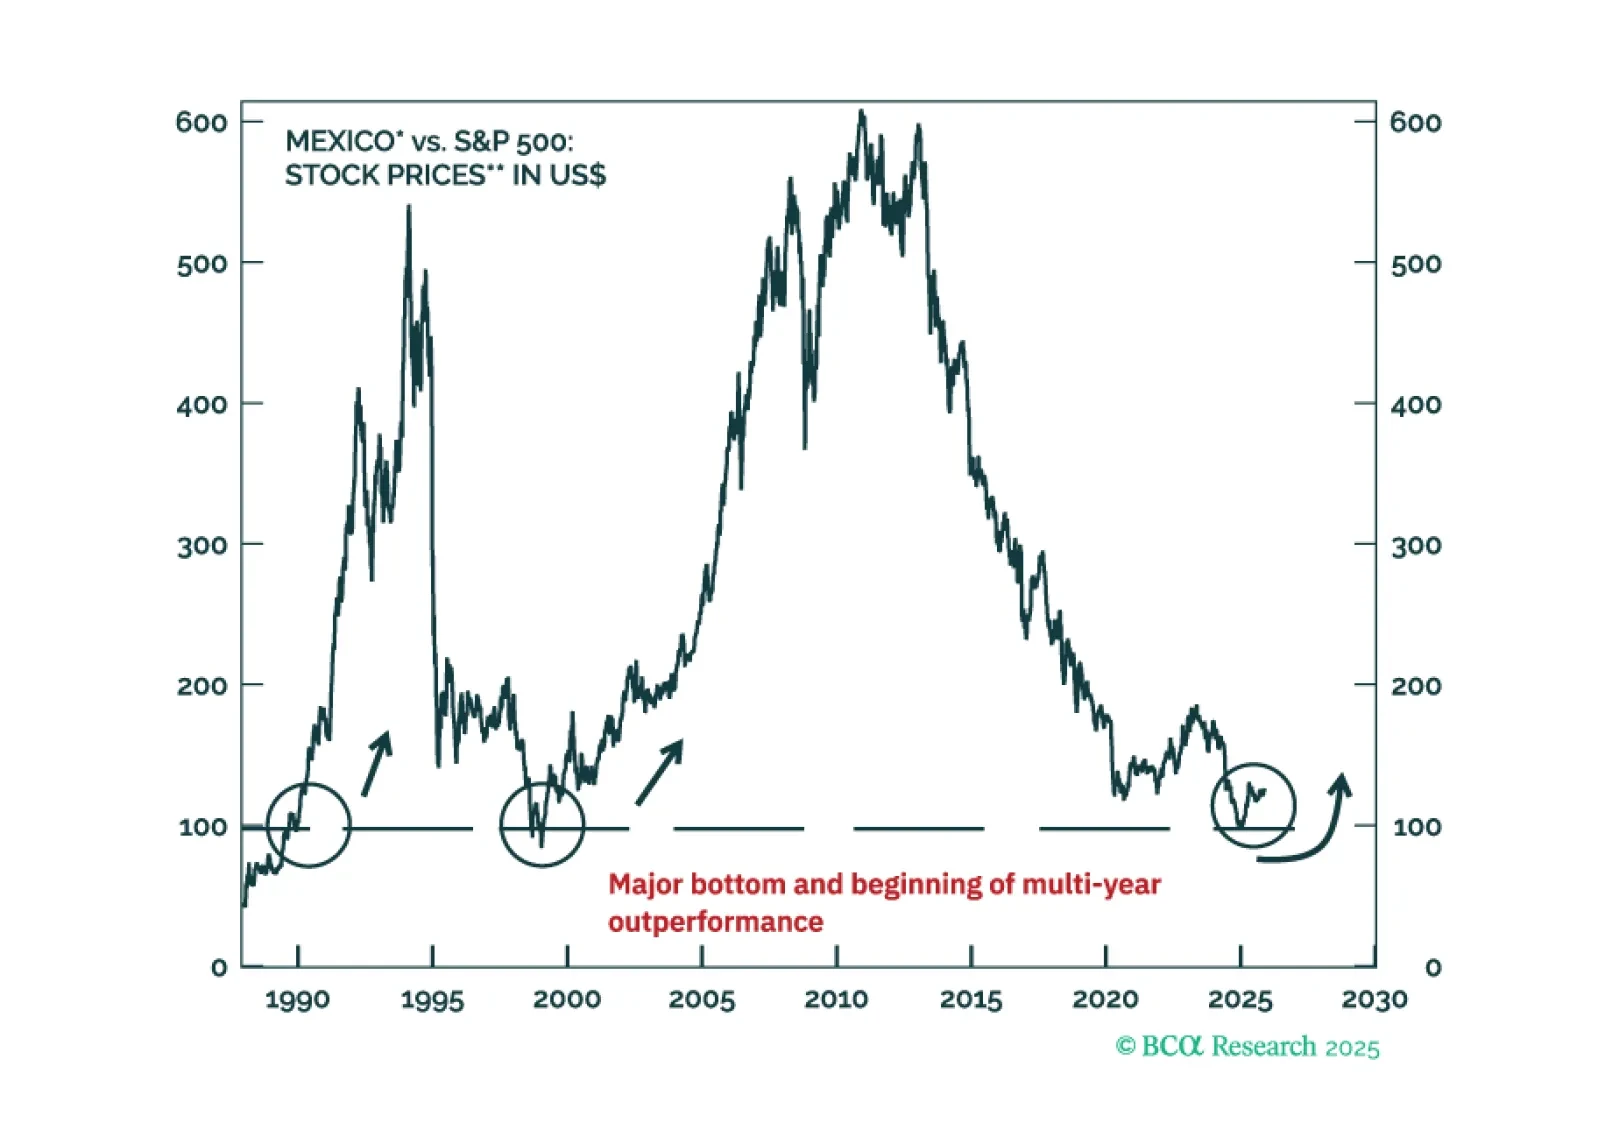
Mexican equity and fixed-income markets will continue outperforming their EM counterparts, regardless of whether global risk assets sell off or not. Also, we recommend a new trade: long Mexican stocks / short the S&P 500.
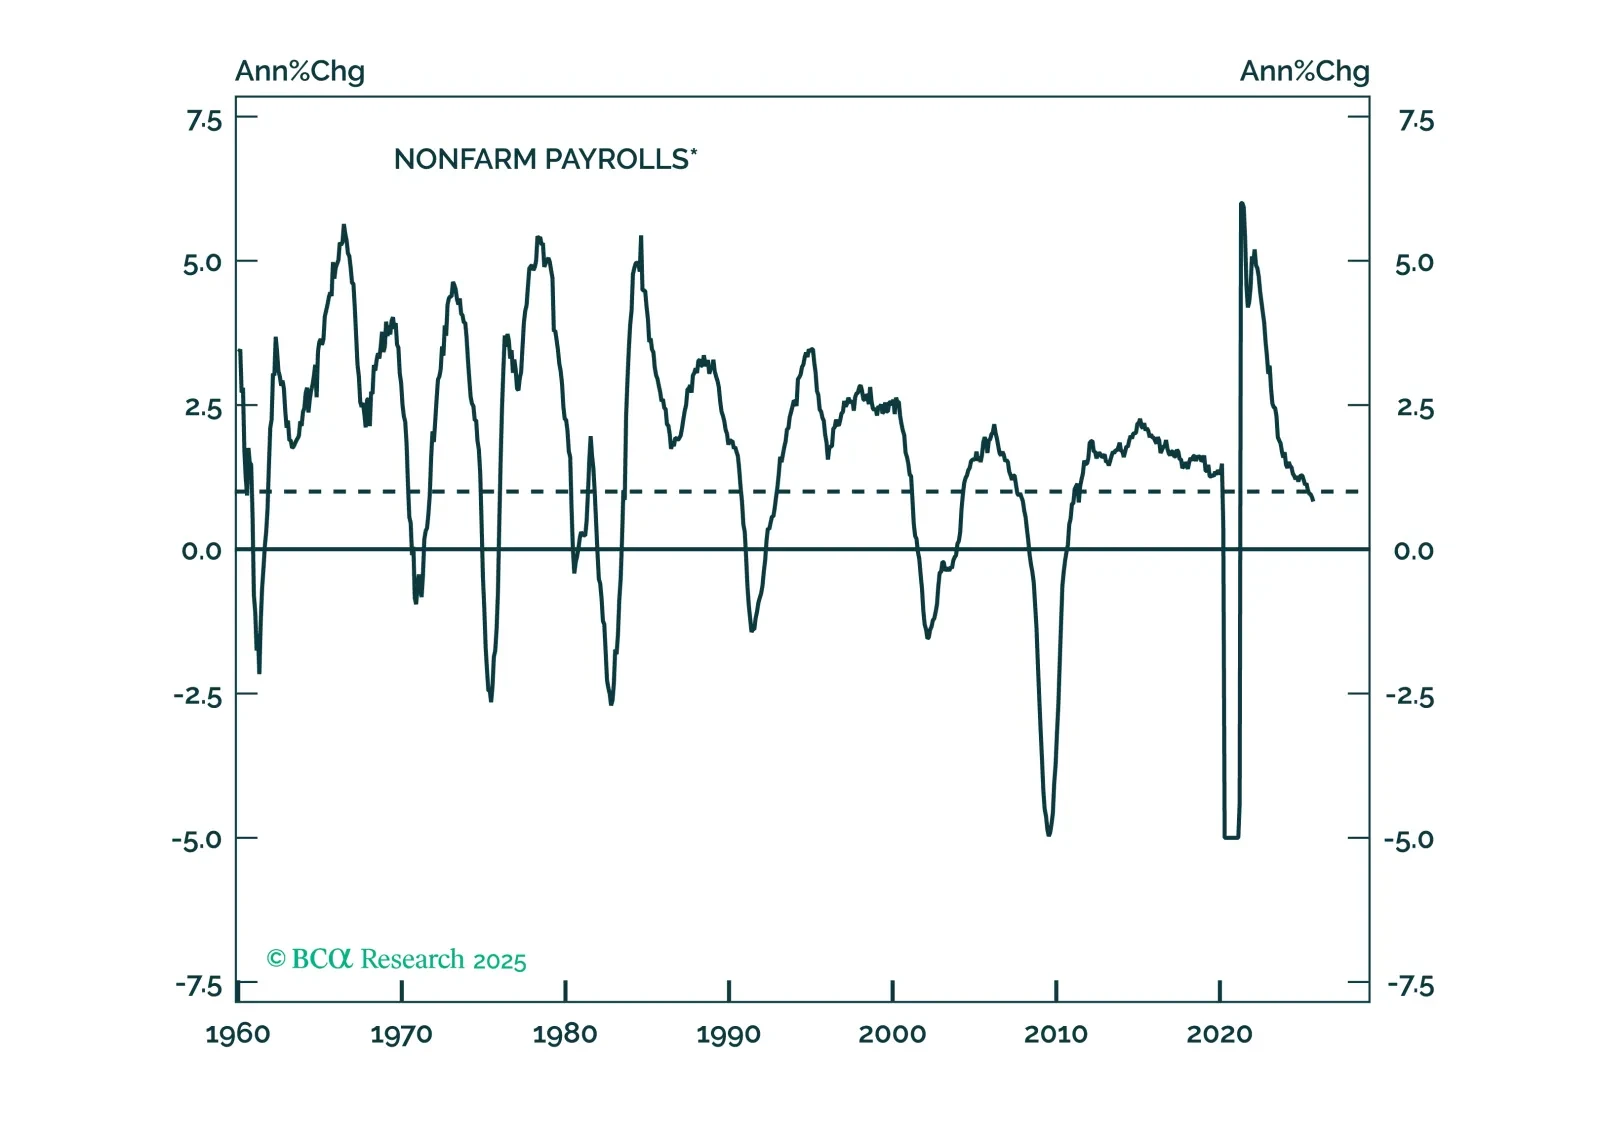
September job gains topped modest expectations, but year-over-year payrolls growth appears to have fallen below stall speed. We remain concerned about US activity.
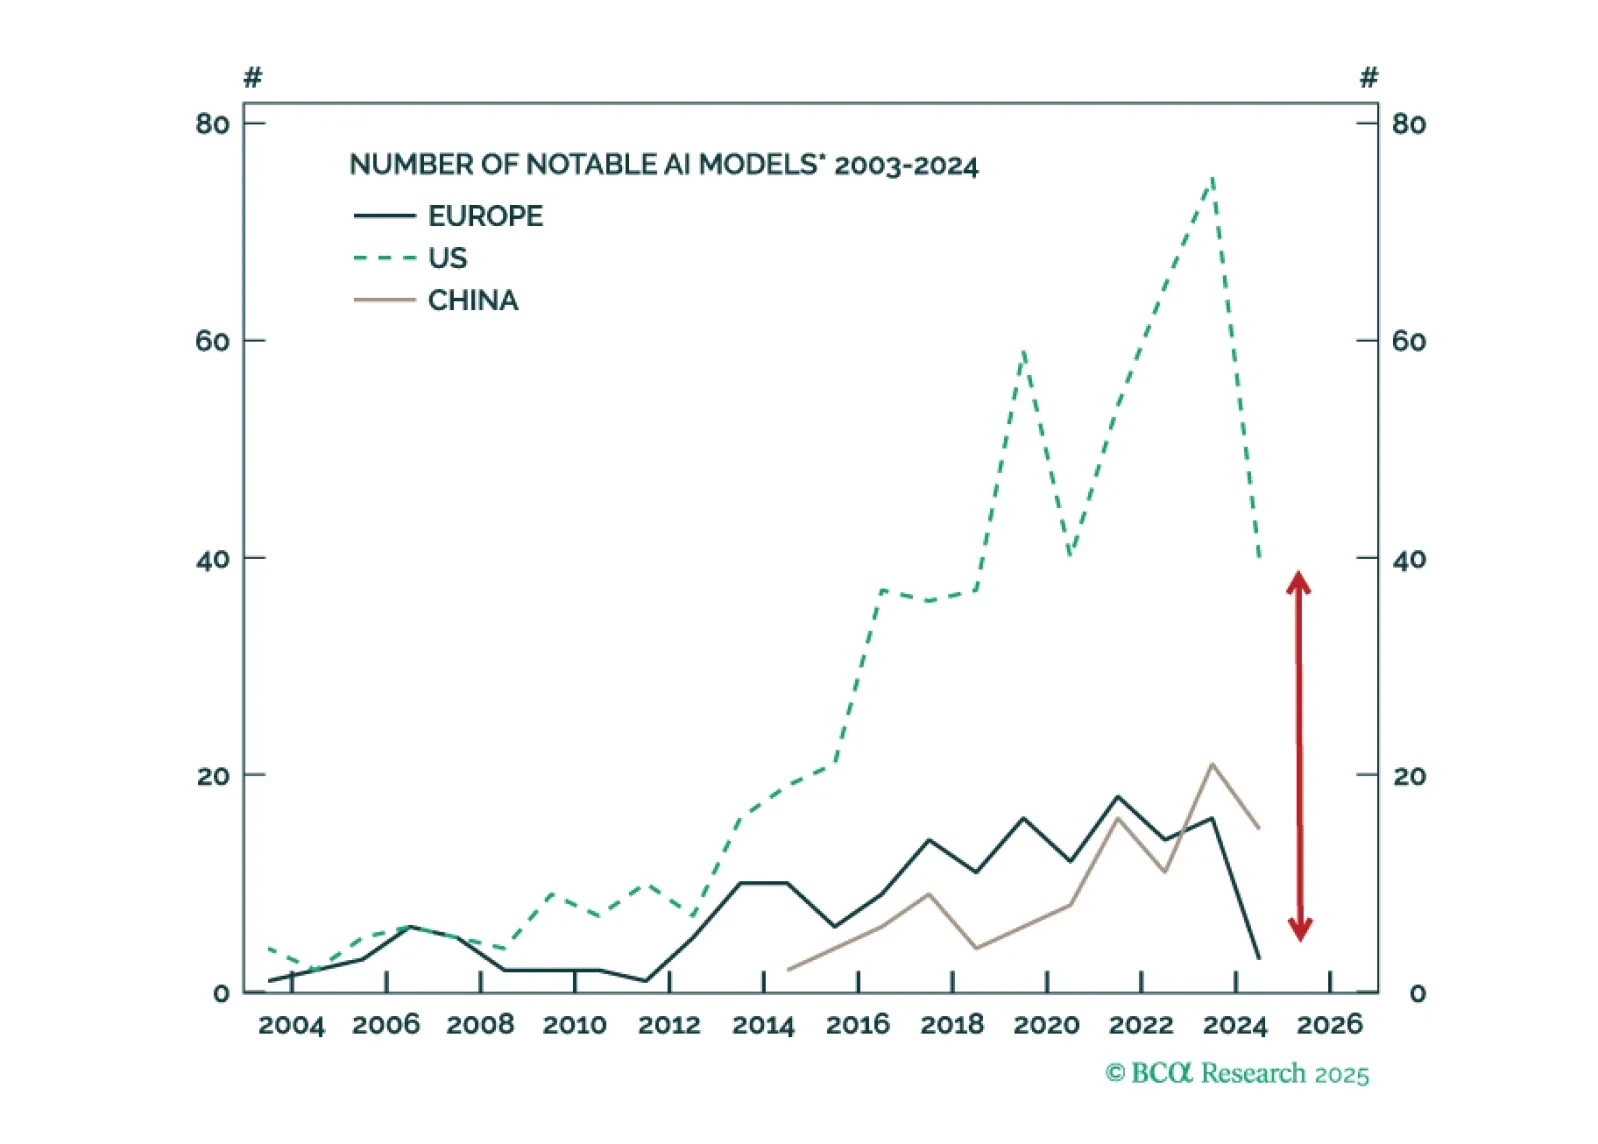
Europe is not left out of the AI race. Despite lagging US and China in LLMs and AI capex, Europe is quietly making progress where it matters, including industrial adoption. European capitals and the EU seem committed to not let that technology slip away, and are investing to support a “second-wave” role in AI. Scaling remains uneven, especially for SMEs, but will not prevent productivity gains in the region.
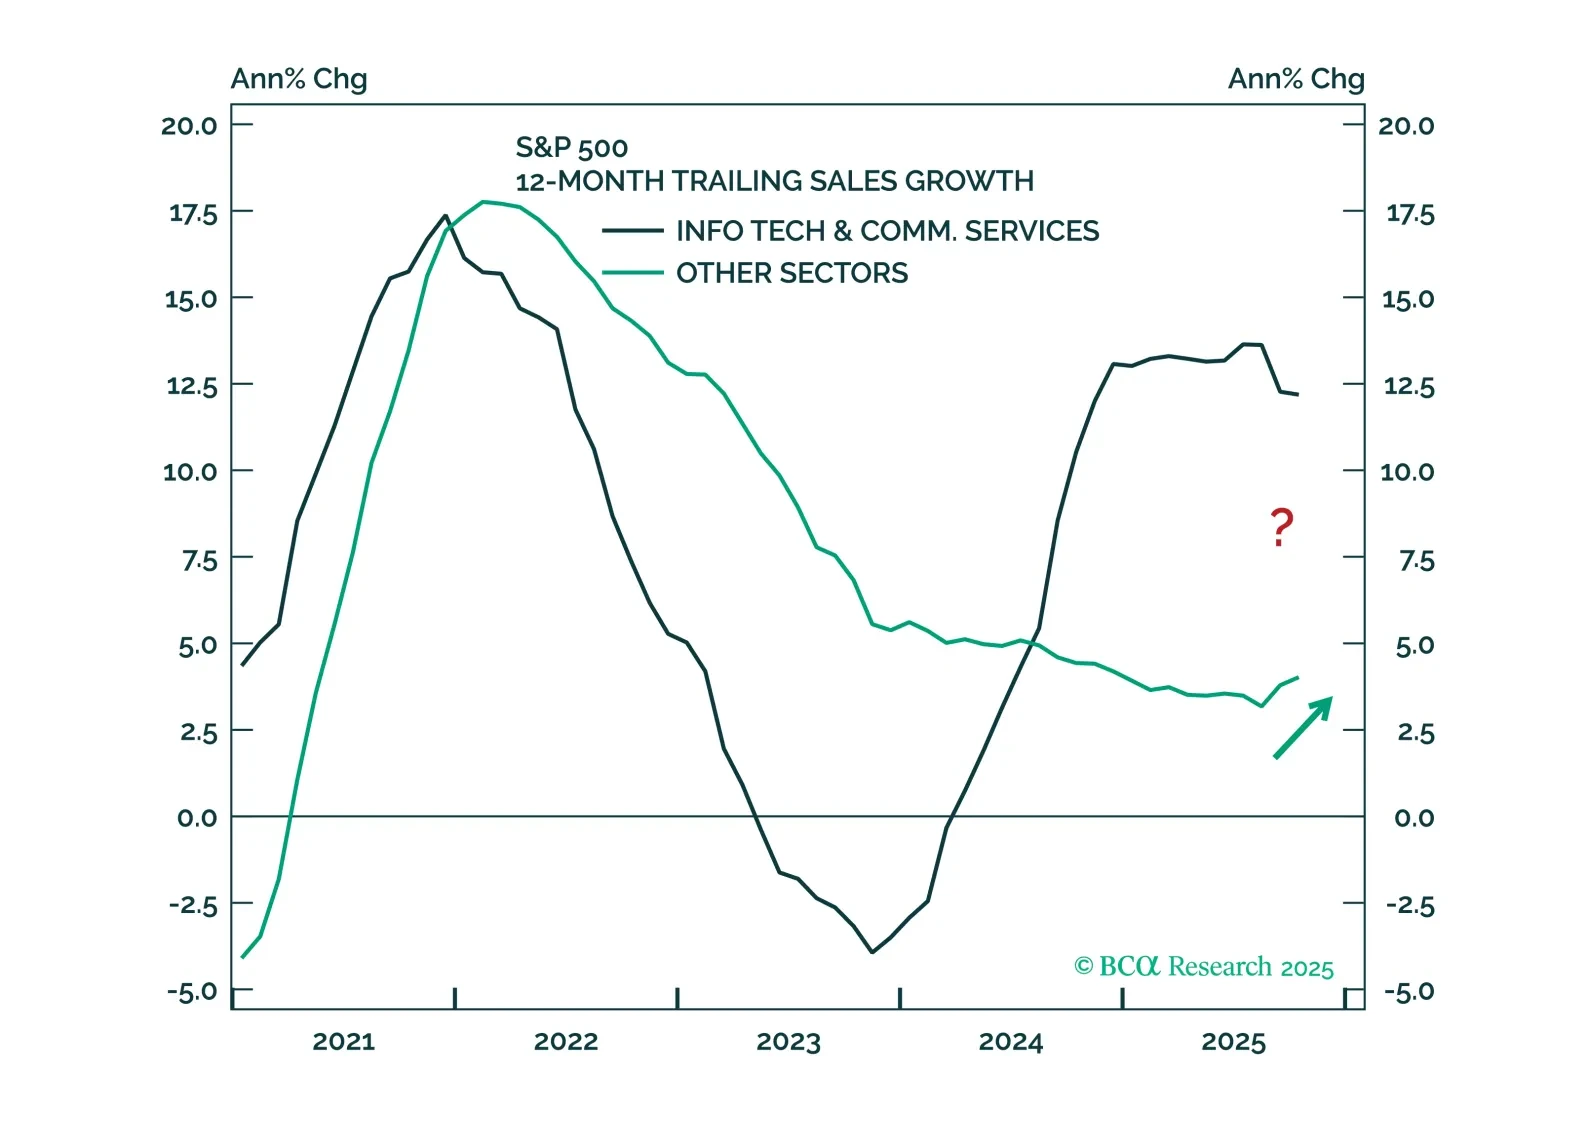
The K-shaped economy will likely reverse in 2026, with the cyclical parts of the economy doing better. Upgrade Financials and Materials from neutral to overweight. Downgrade Communication Services and Utilities from overweight to neutral. Favor value stocks. Upgrade Bitcoin from neutral to overweight.