Latest from BCA Research

In a widely anticipated move, the RBA resumed cutting rates. However, with housing, consumption, and PMIs improving, we see little scope for the RBA to ease beyond market expectations.
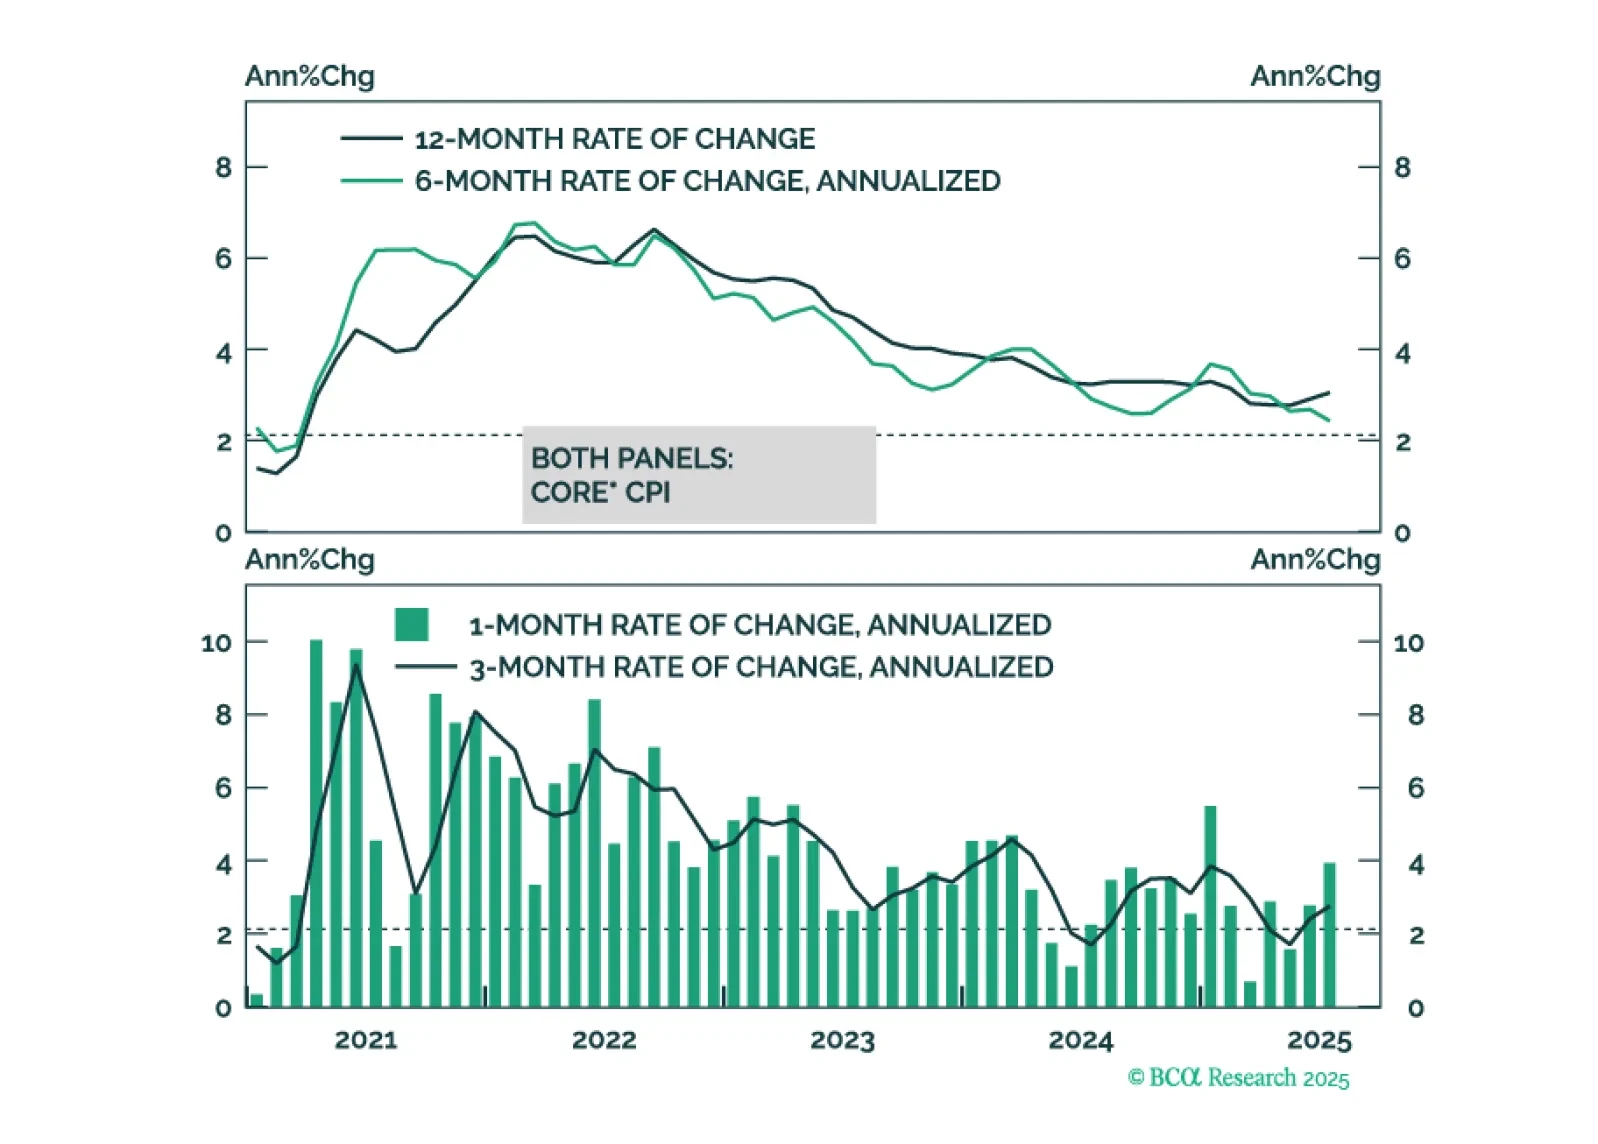
This morning’s CPI report marginally tips the scales in favor of a September rate cut.

This is the first time that our chartpack does not include any charts on the trade war. Did we just curse our equity overweight? Right as the inflation print comes out and causes agita to the market? Sure, maybe. The tactical ins and outs are not that interesting to us. Far more interesting is the fact that the Fed is going to have to cut regardless of what "widget inflation" does. With no more fiscal backstop fueling the economy via wanton transfer payments to households, the inflation-fiscal gravy train is over. As such, the Fed will cut more than the market thinks, particularly given the political pressure from the Trump White House.
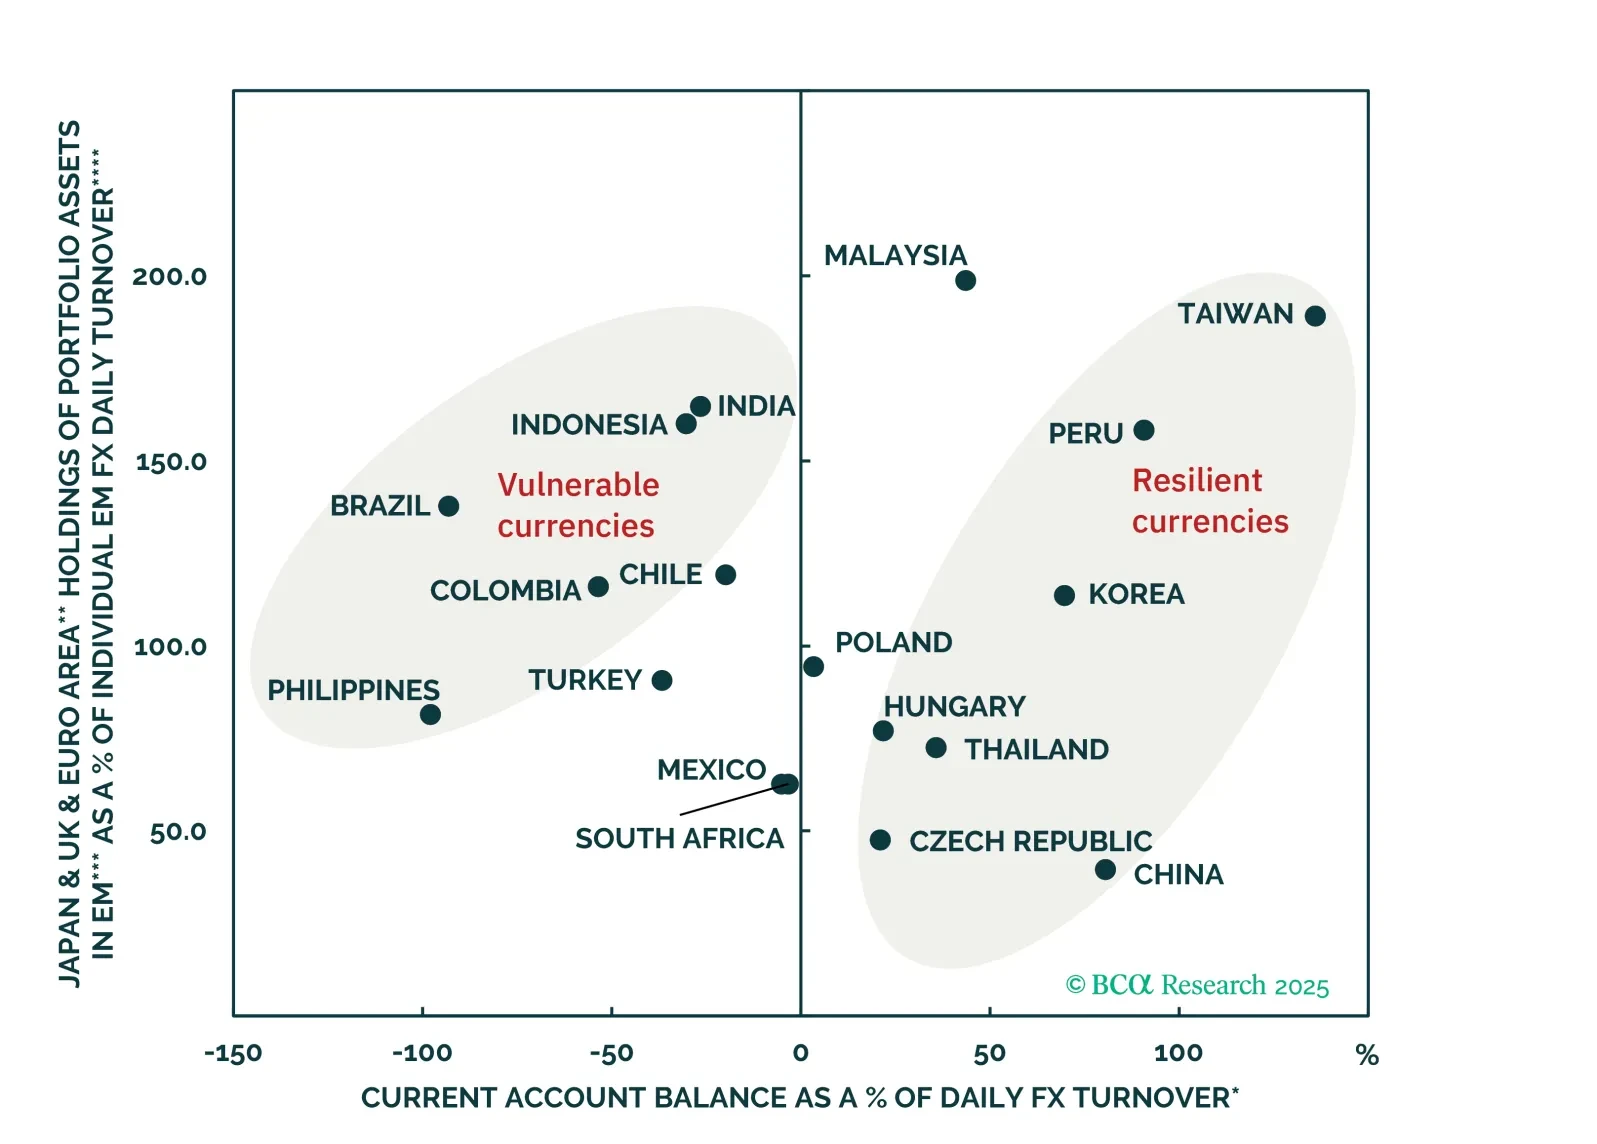
Despite widespread investor optimism Brazil’s currency outlook is challenged by a toxic mix of poor external, fiscal, and macro fundamentals. Expect BRL to underperform most EM peers.
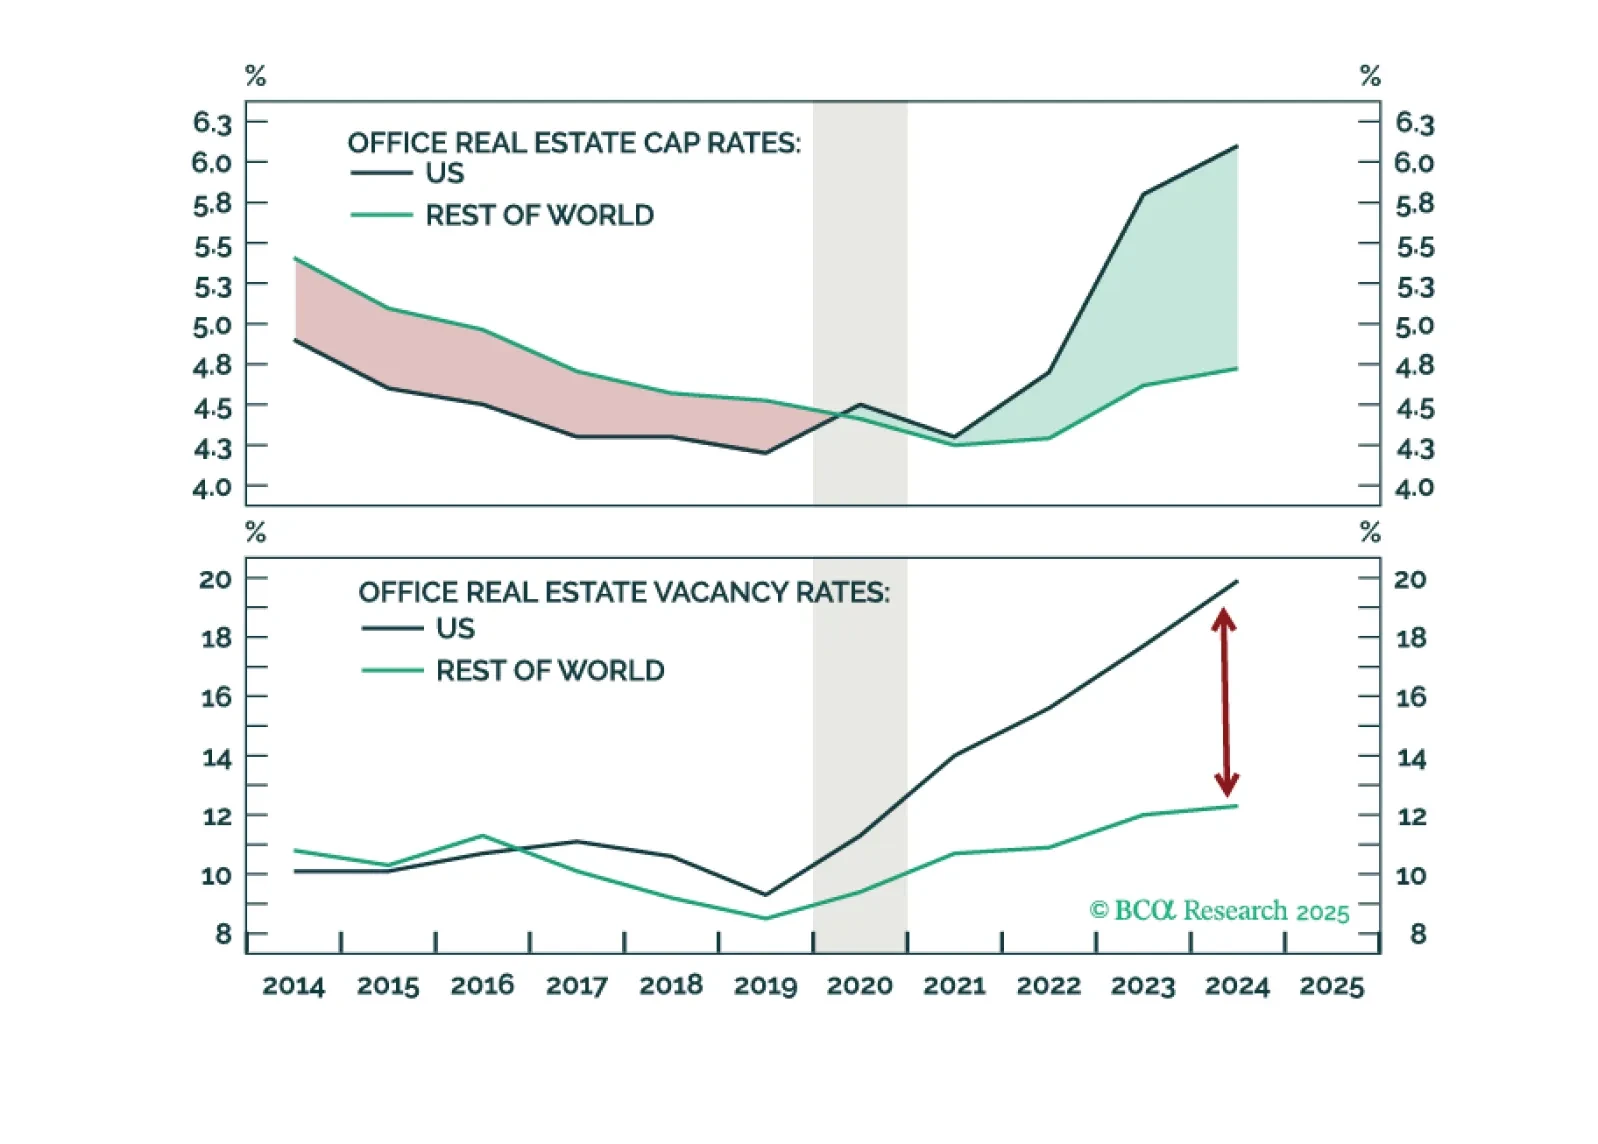

US tariffs will not derail the low-inflation economic recovery underway in the Euro Area. Investors should overweight European equities, focusing on parts of the market more insulated from tariffs.
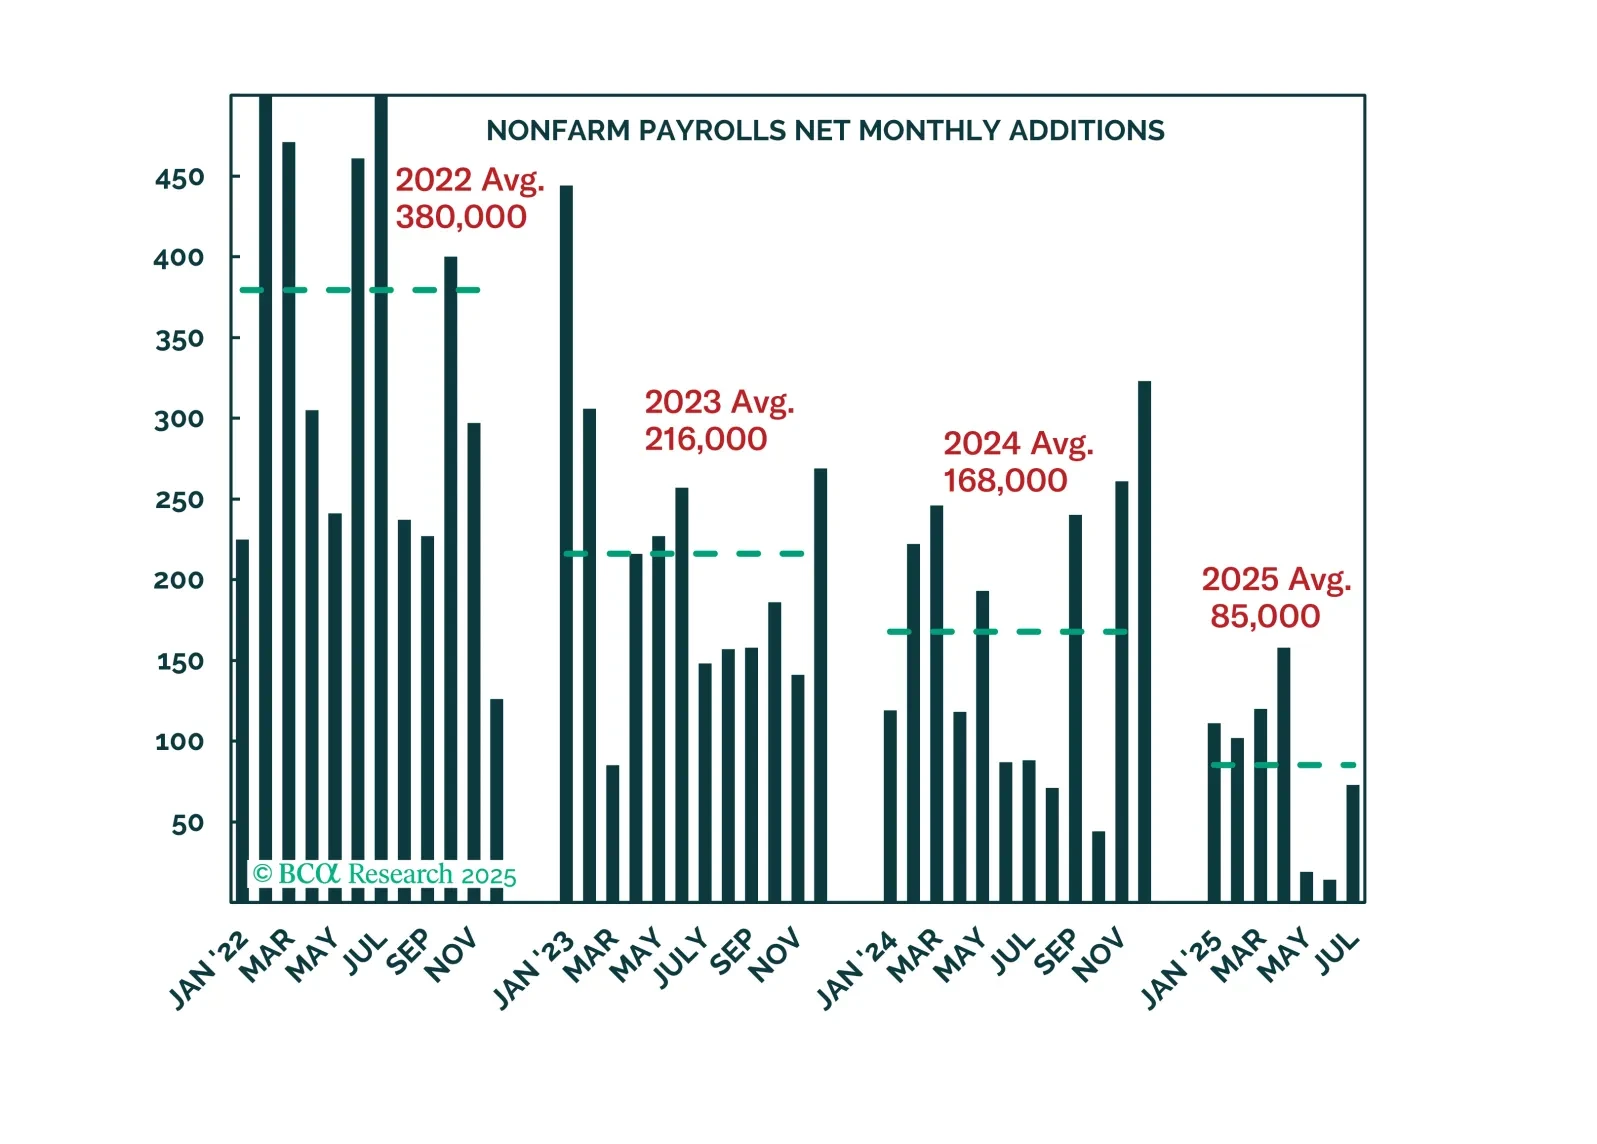
Data received since we began reassessing our bearish stance supported our notion that the economy is not as strong as the investor consensus perceives. But the softness will likely have to intensify in July and August to preserve our defensive recommendations.

The Q2 earnings season delivered solid earnings and sales growth and resilient margins, reassuring investors that corporate America remains in good health and is capable of navigating economic uncertainty while mitigating the impact of new trade levies. The outlook is generally positive, but with one important caveat: The full effect of tariffs has yet to materialize.
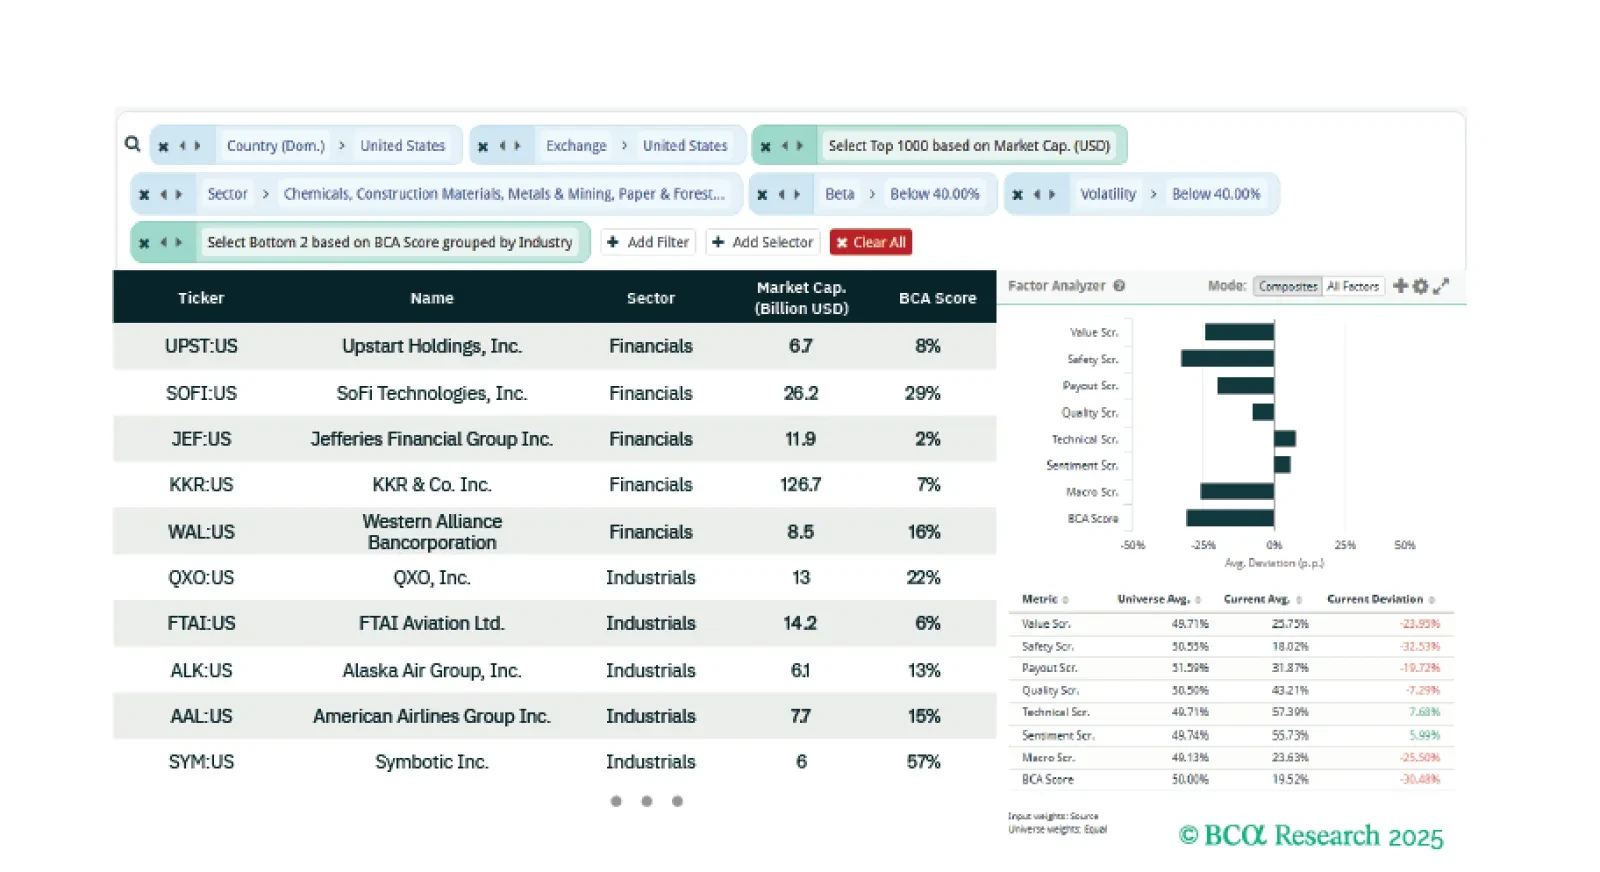
This week we develop two ideas with three screeners. The first identifies deep cyclical sectors that continue to outperform post Liberation Day in the US. We provide two screens to identify equity opportunities for this. Our final screener identifies momentum stocks that are cheap and trending and will benefit from a soft landing.
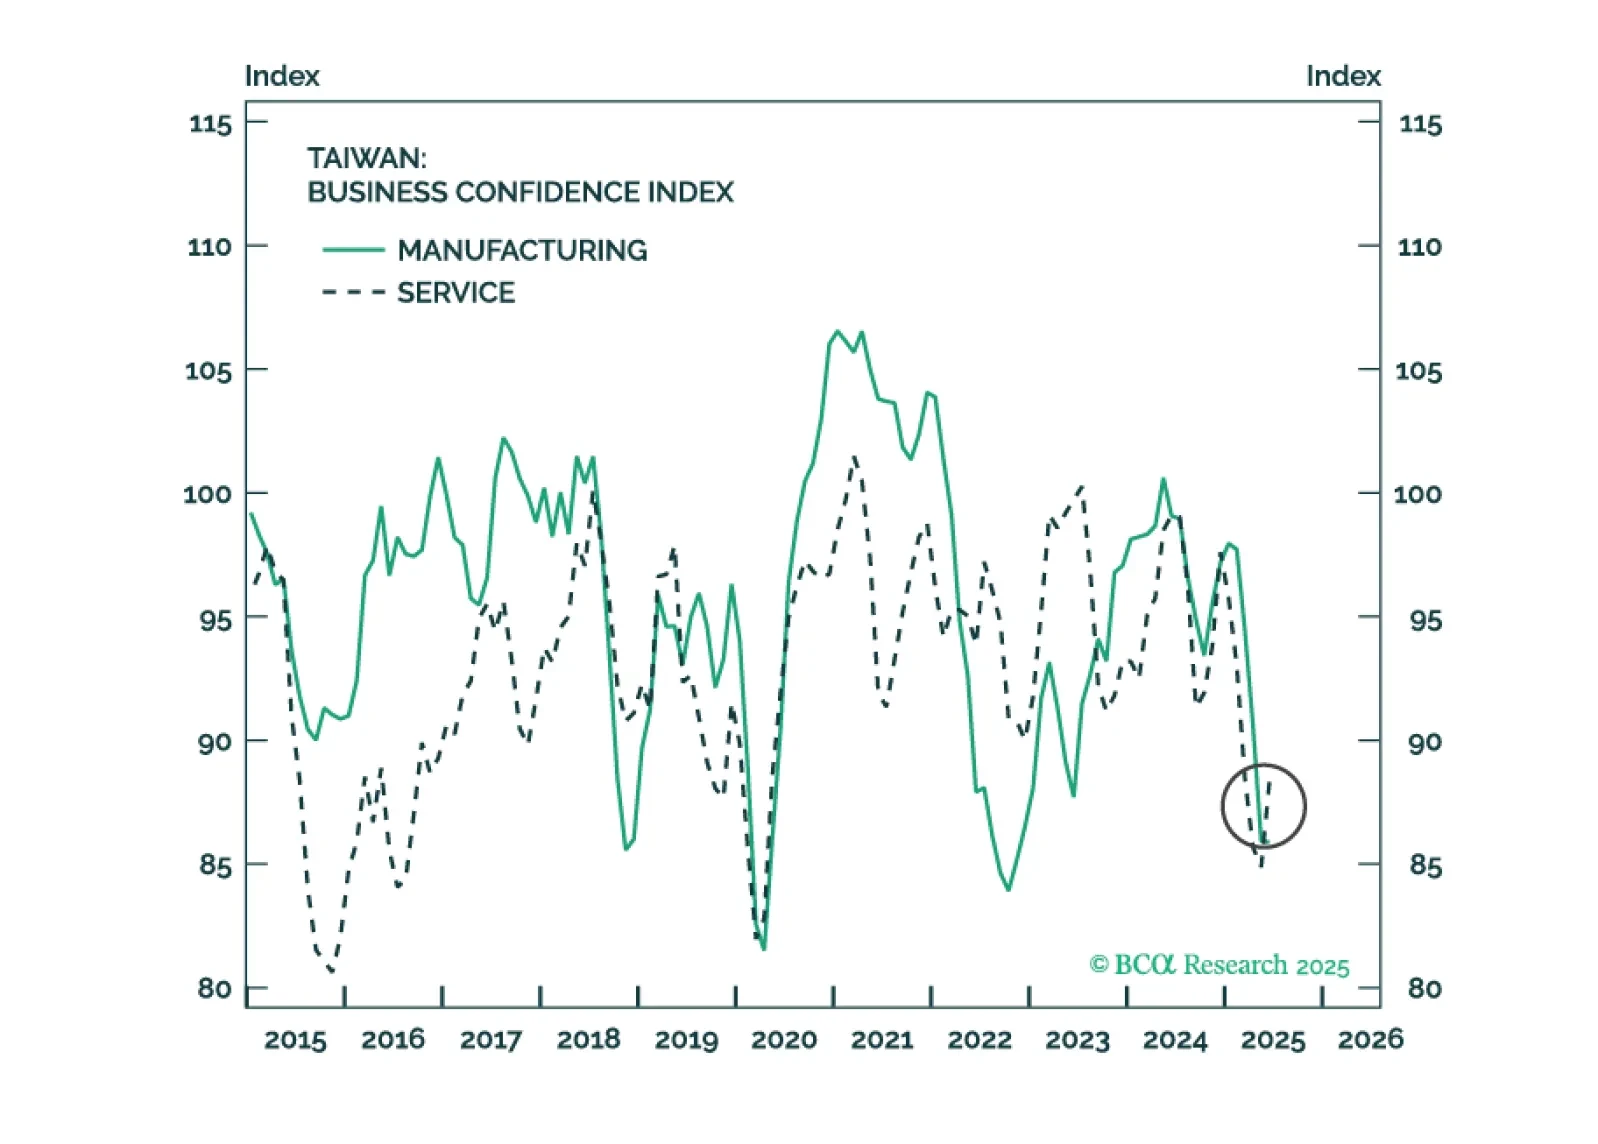
Taiwan’s failed recall election reduces 12-month geopolitical risk for Taiwanese and Chinese equities on the margin. We are reviewing our long European industrials / short Chinese industrials trade.