FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
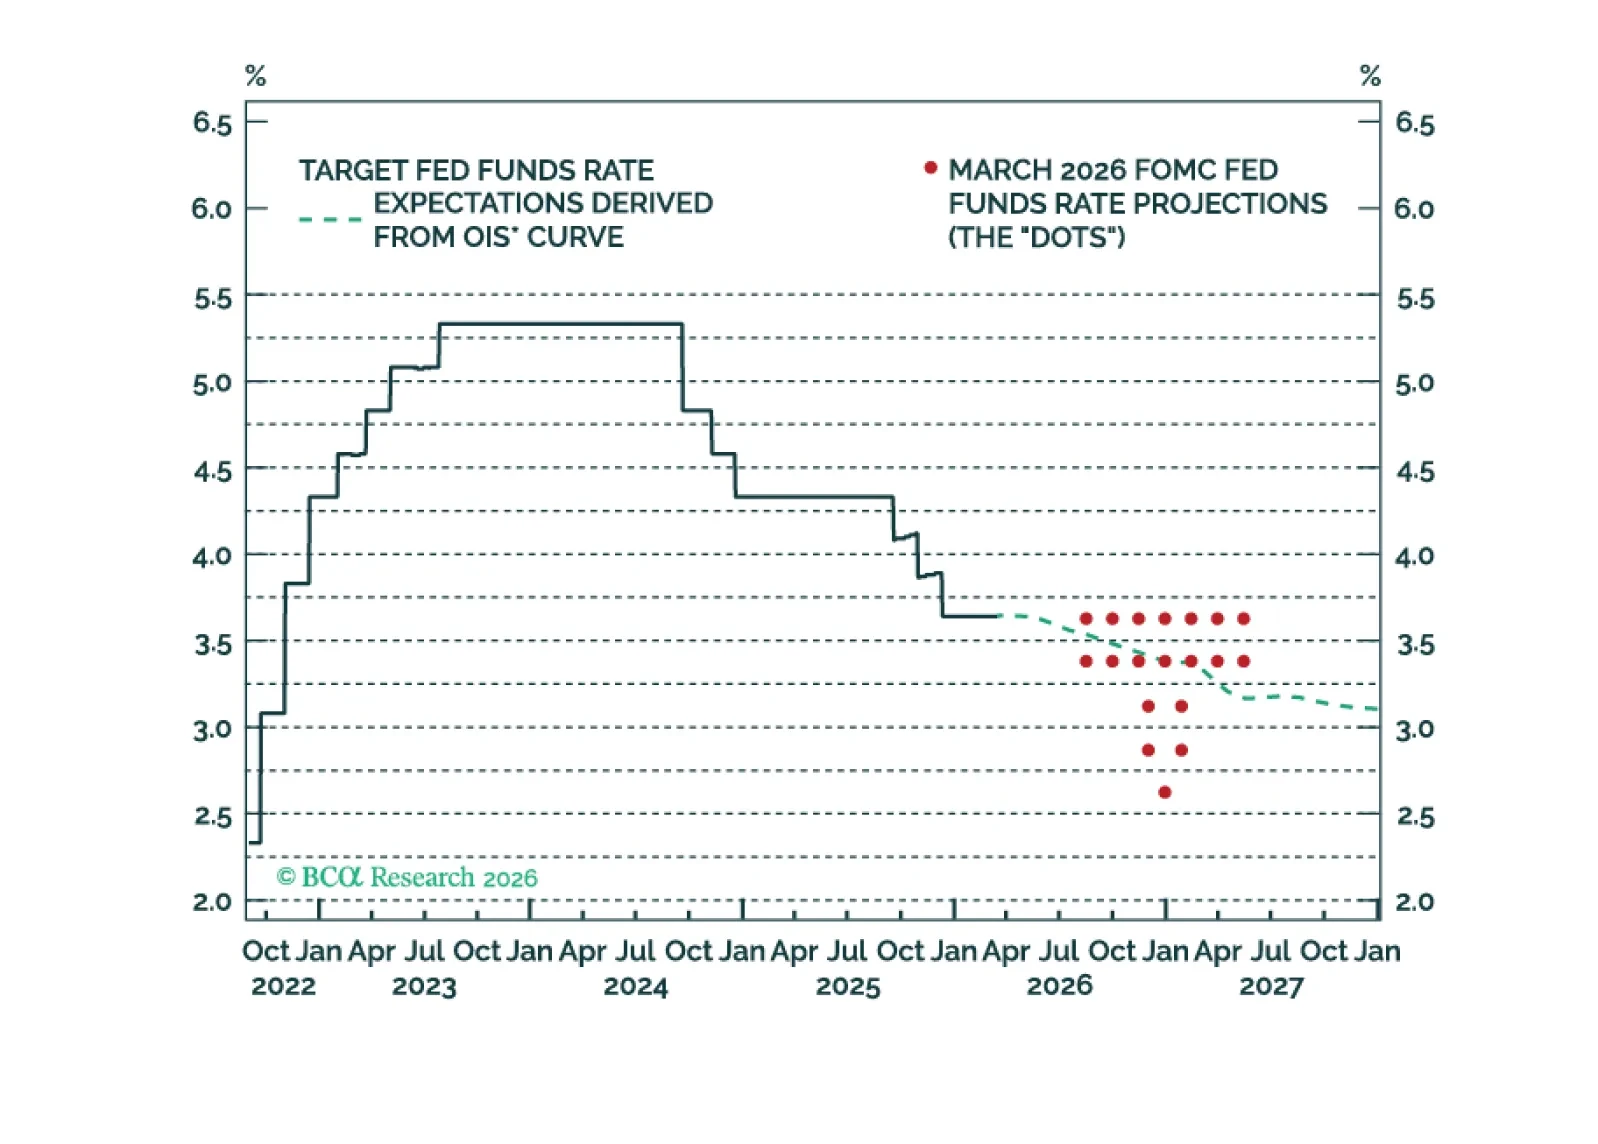
The Fed will not cut rates again until core inflation trends lower. This remains likely as the tariff impact on goods inflation wanes, but the recent energy price shock could delay any meaningful downtrend.
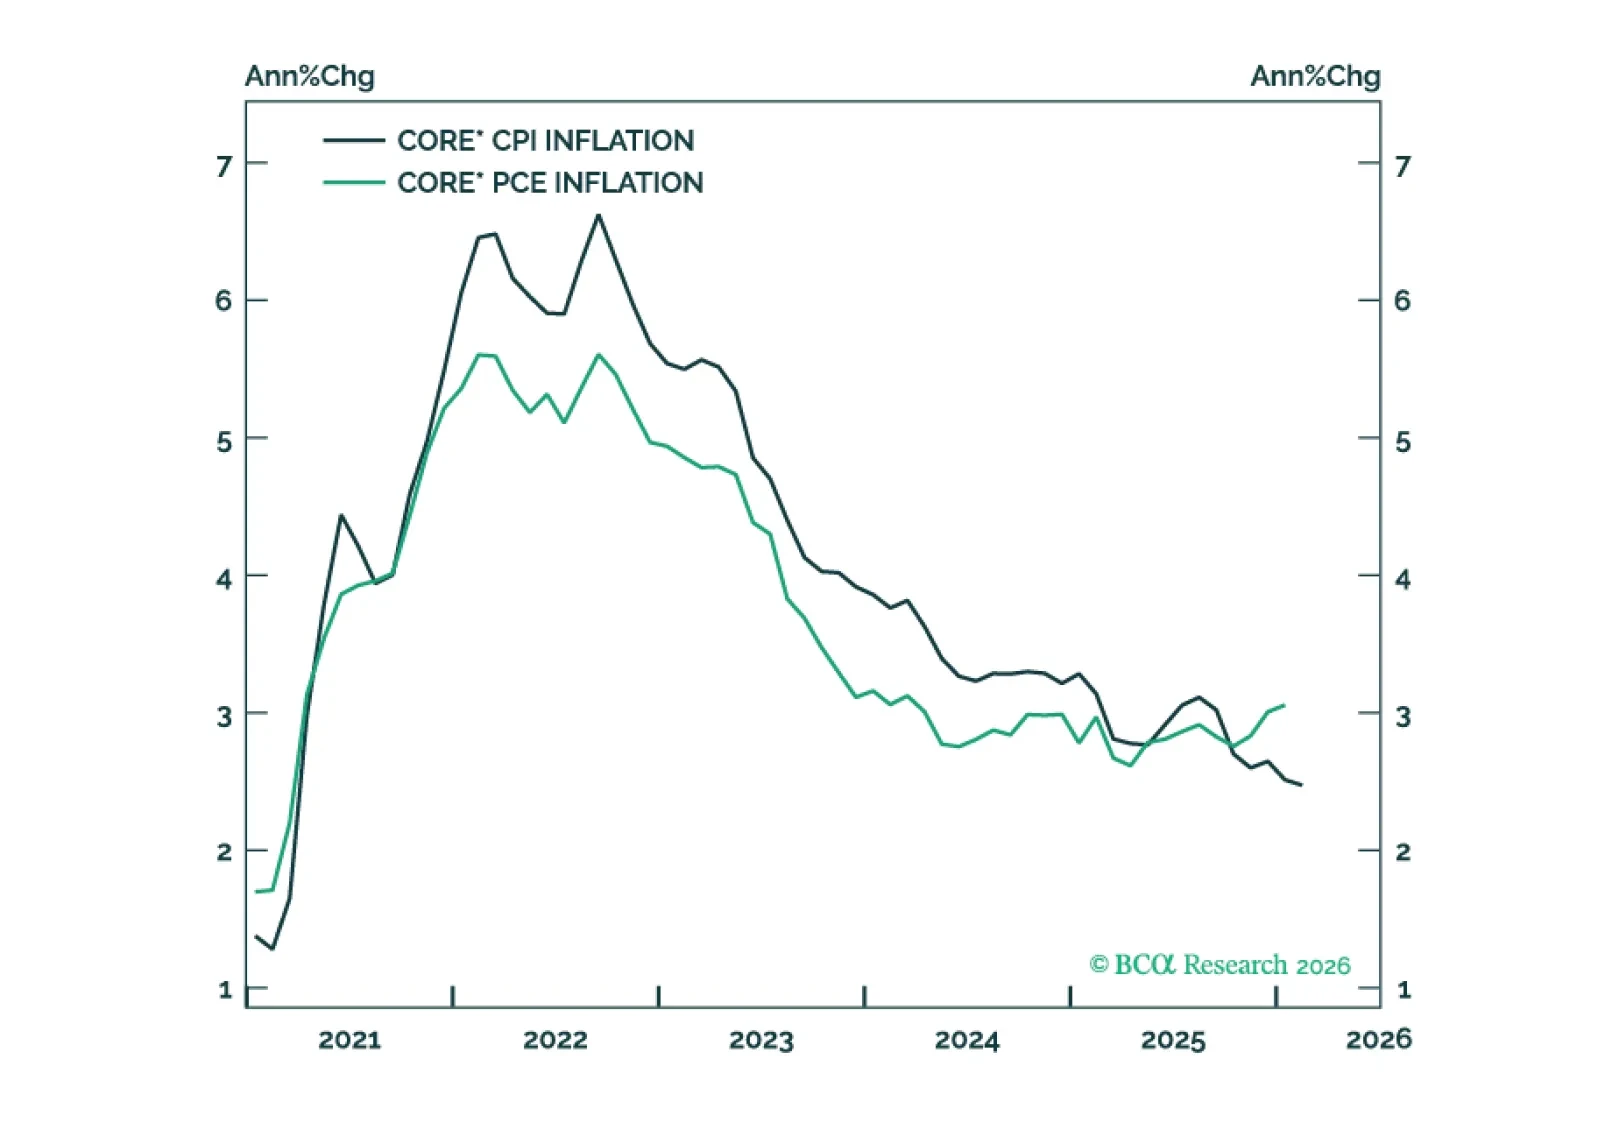
The gap between PCE and CPI inflation will narrow within the next few months, mostly driven by core PCE inflation converging toward its trimmed mean.
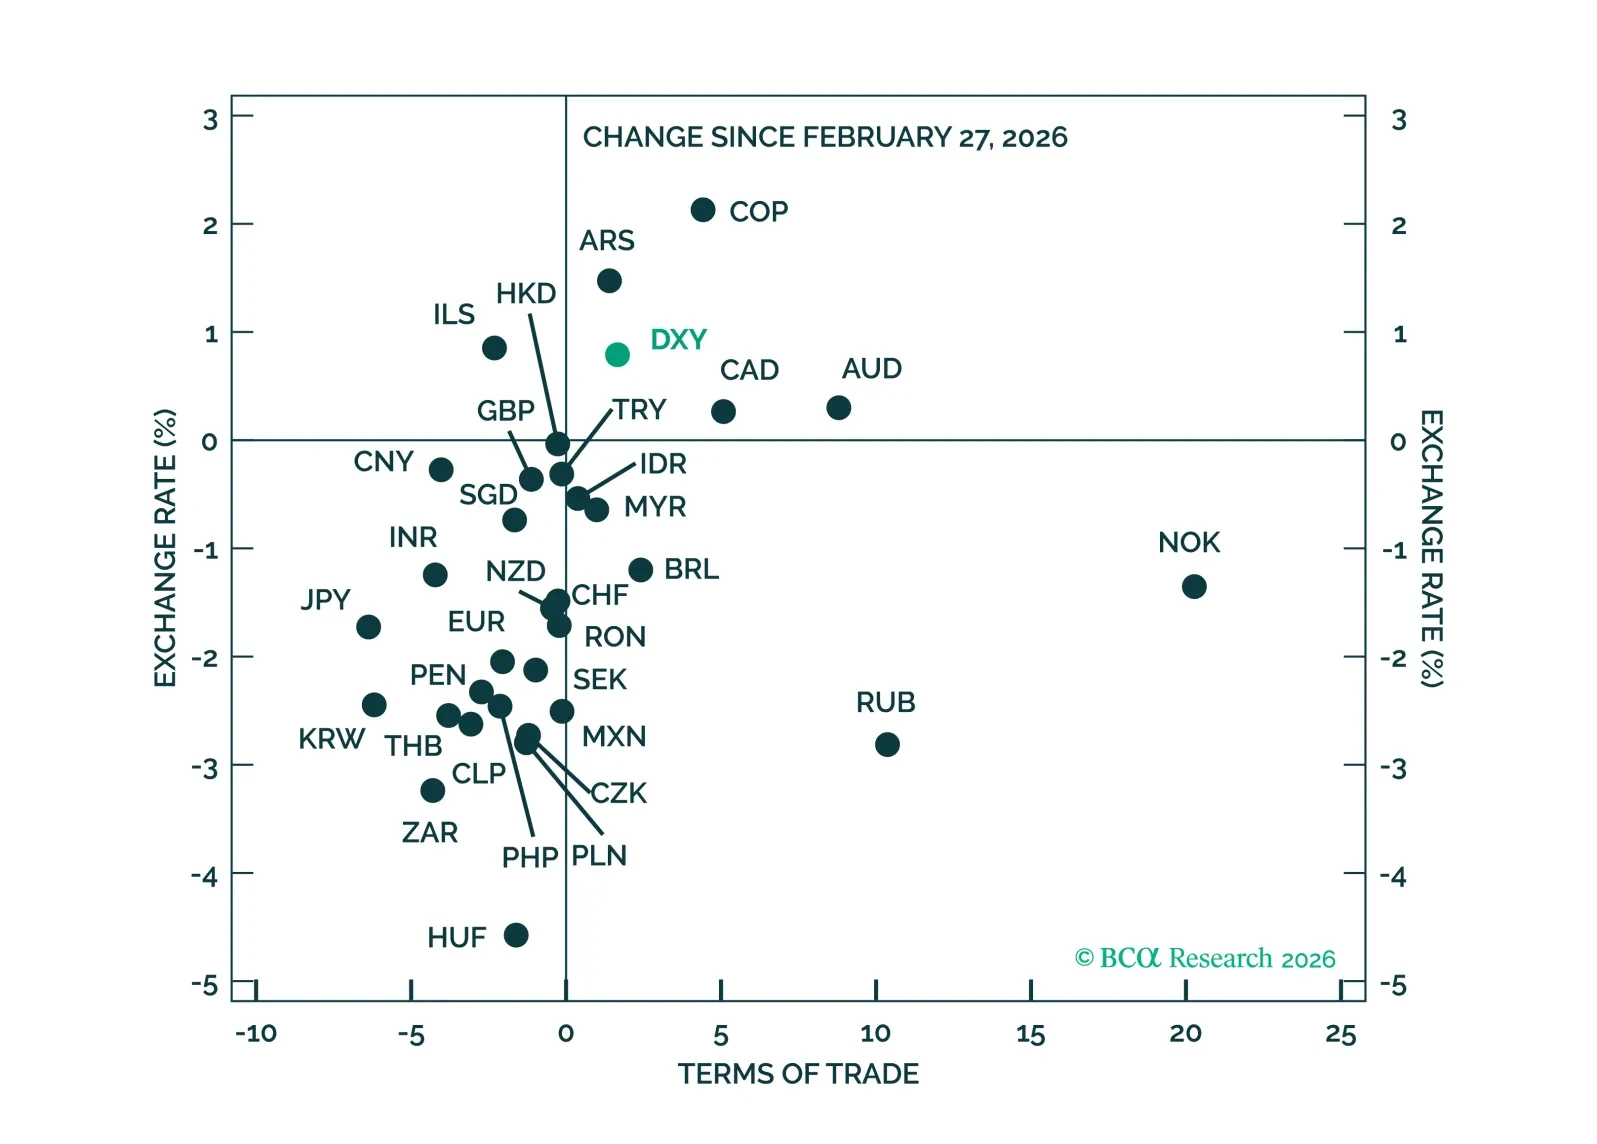
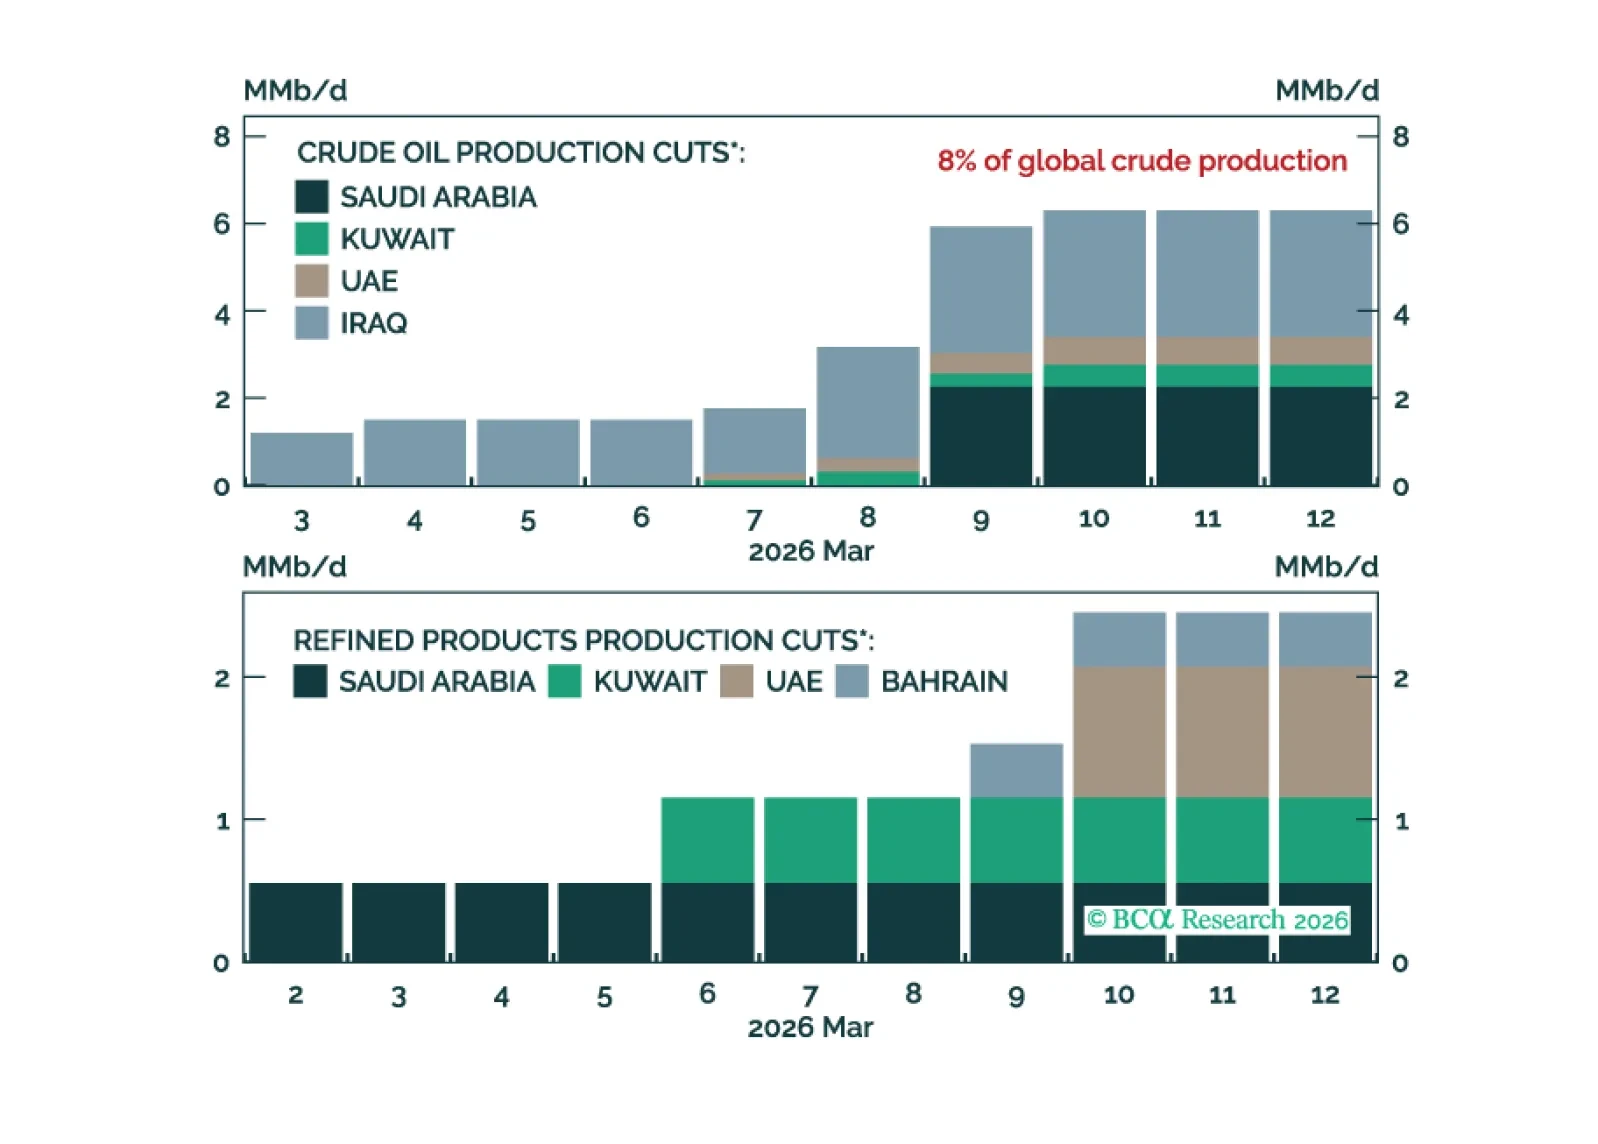
The Iran war remains a terms-of-trade shock rather than a classic flight to safety – for now. As oil risks skew higher, policy repricing and growth differentials should continue to favor a tactical rebound in the USD.
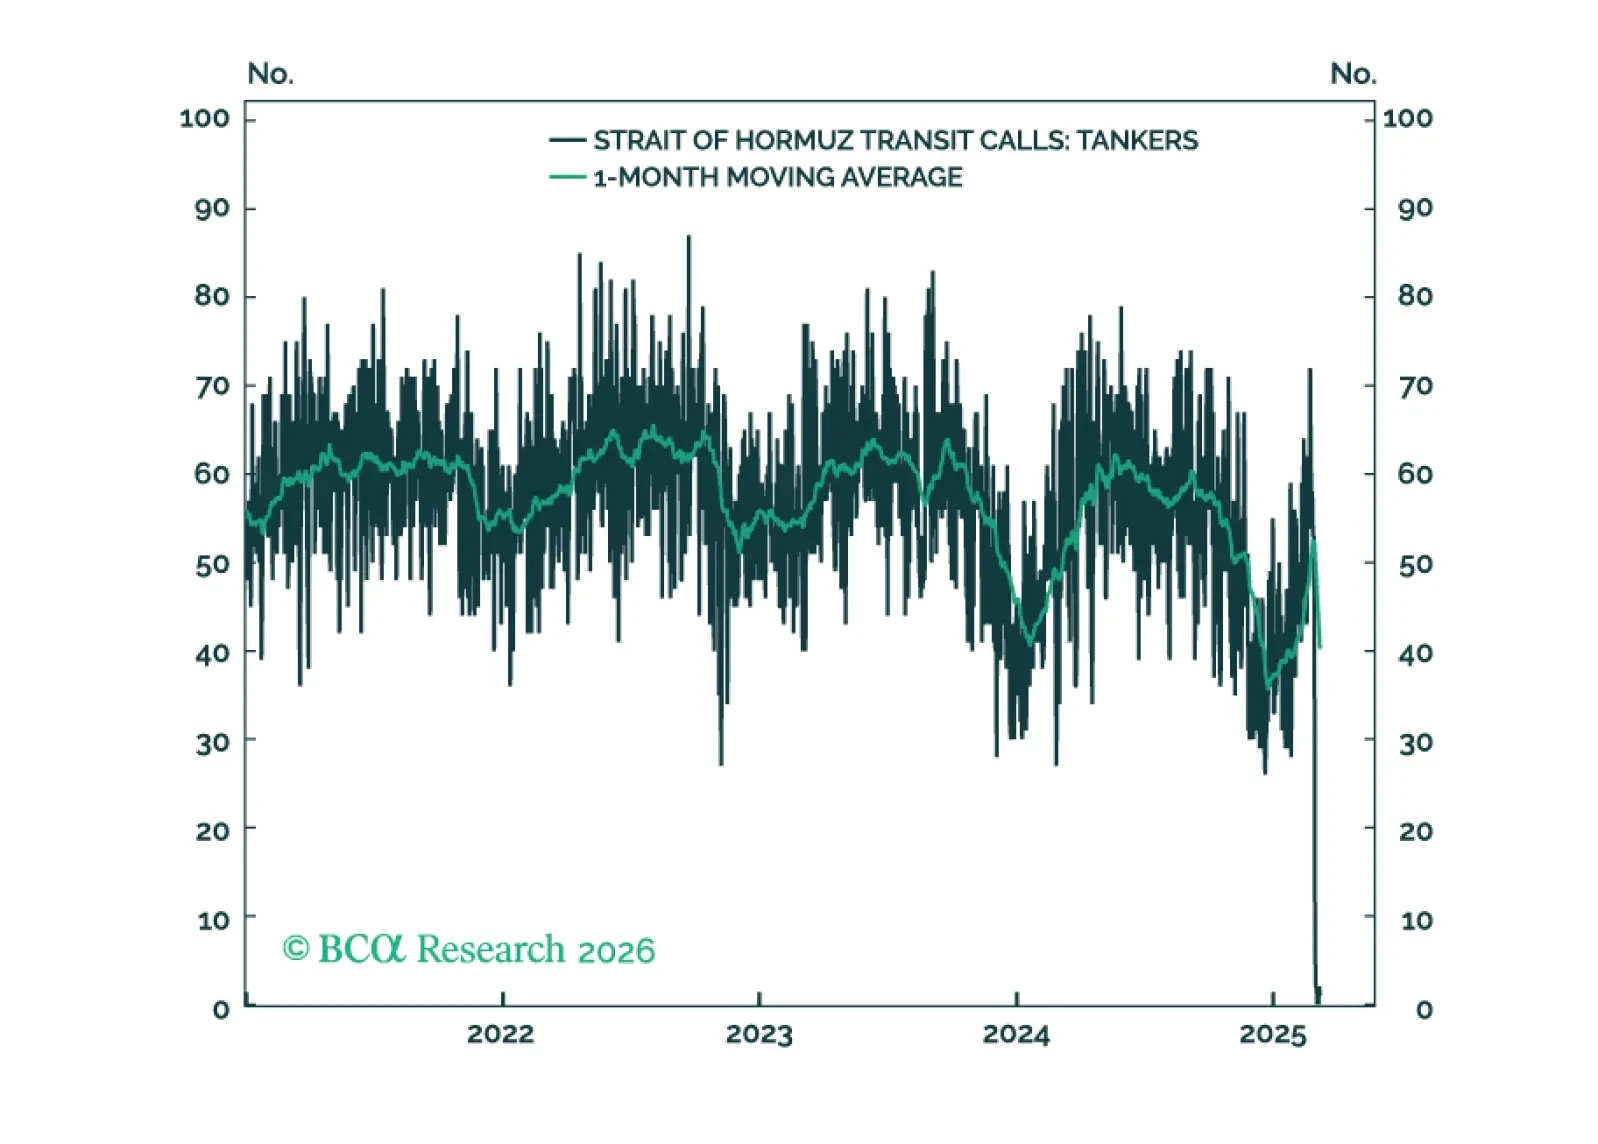
Drone and ballistic missile attacks were slowing, as of March 11. Air traffic in the region was also slowly recovering, as the pace of attacks declined. Warning, however: Reports from US CENTCOM and the IDF claim that Iran still has around 40% to 50% of its stockpile of missiles and launchers. Attacks are continuing, even though at a reduced tempo.

With all eyes on the Strait of Hormuz, BCA Research has created a dashboard of data for your convenience.

The recent oil price shock reinforces our view that inflation will surprise to the upside during the next few months but fall rapidly in H2 2026.
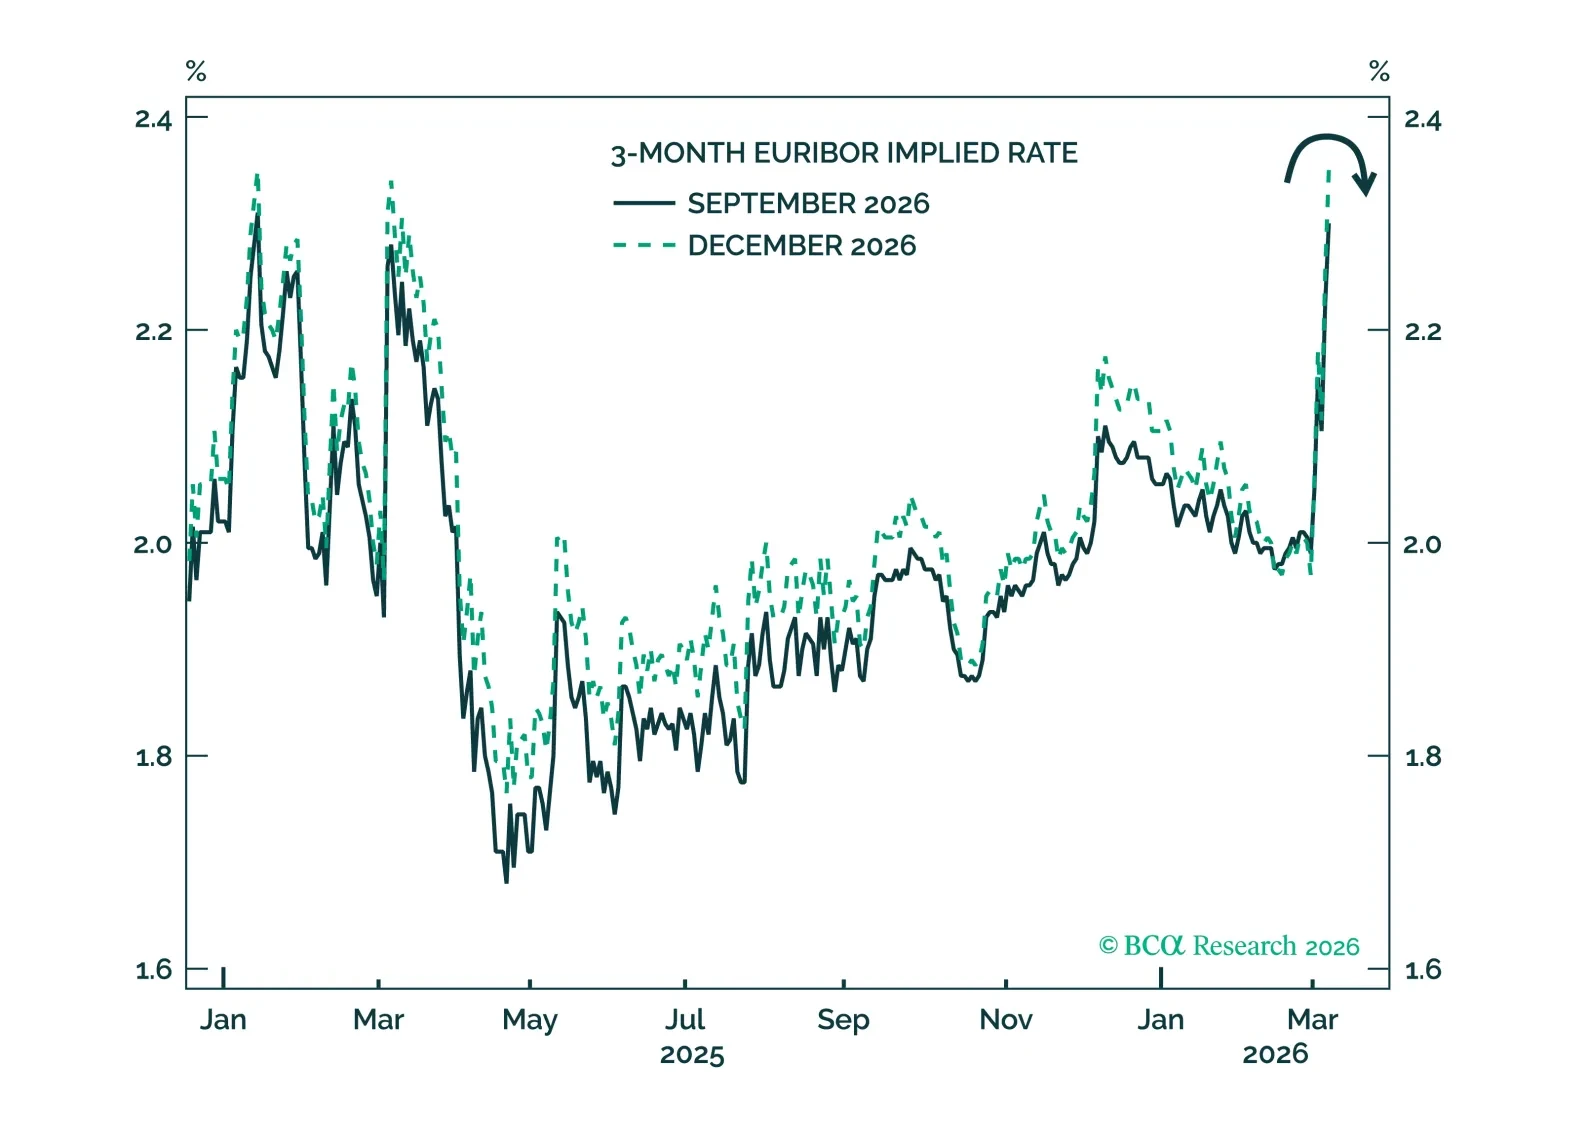
If the 2022 roadmap is any guide, equity markets and cyclical currencies will trough only after confirming that the peak in energy prices is in the rearview mirror. In the very near term, investors should focus on P&L preservation. Reduce exposure to equities, and seek refuge in gold, and inflation-linked bonds (ILBs). Amid a very different demand side than in 2022, today’s supply shock is unlikely to generate lasting inflation, and investors should fade rate-hike odds.