Skip to main content

FICC

One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
Explore FICC
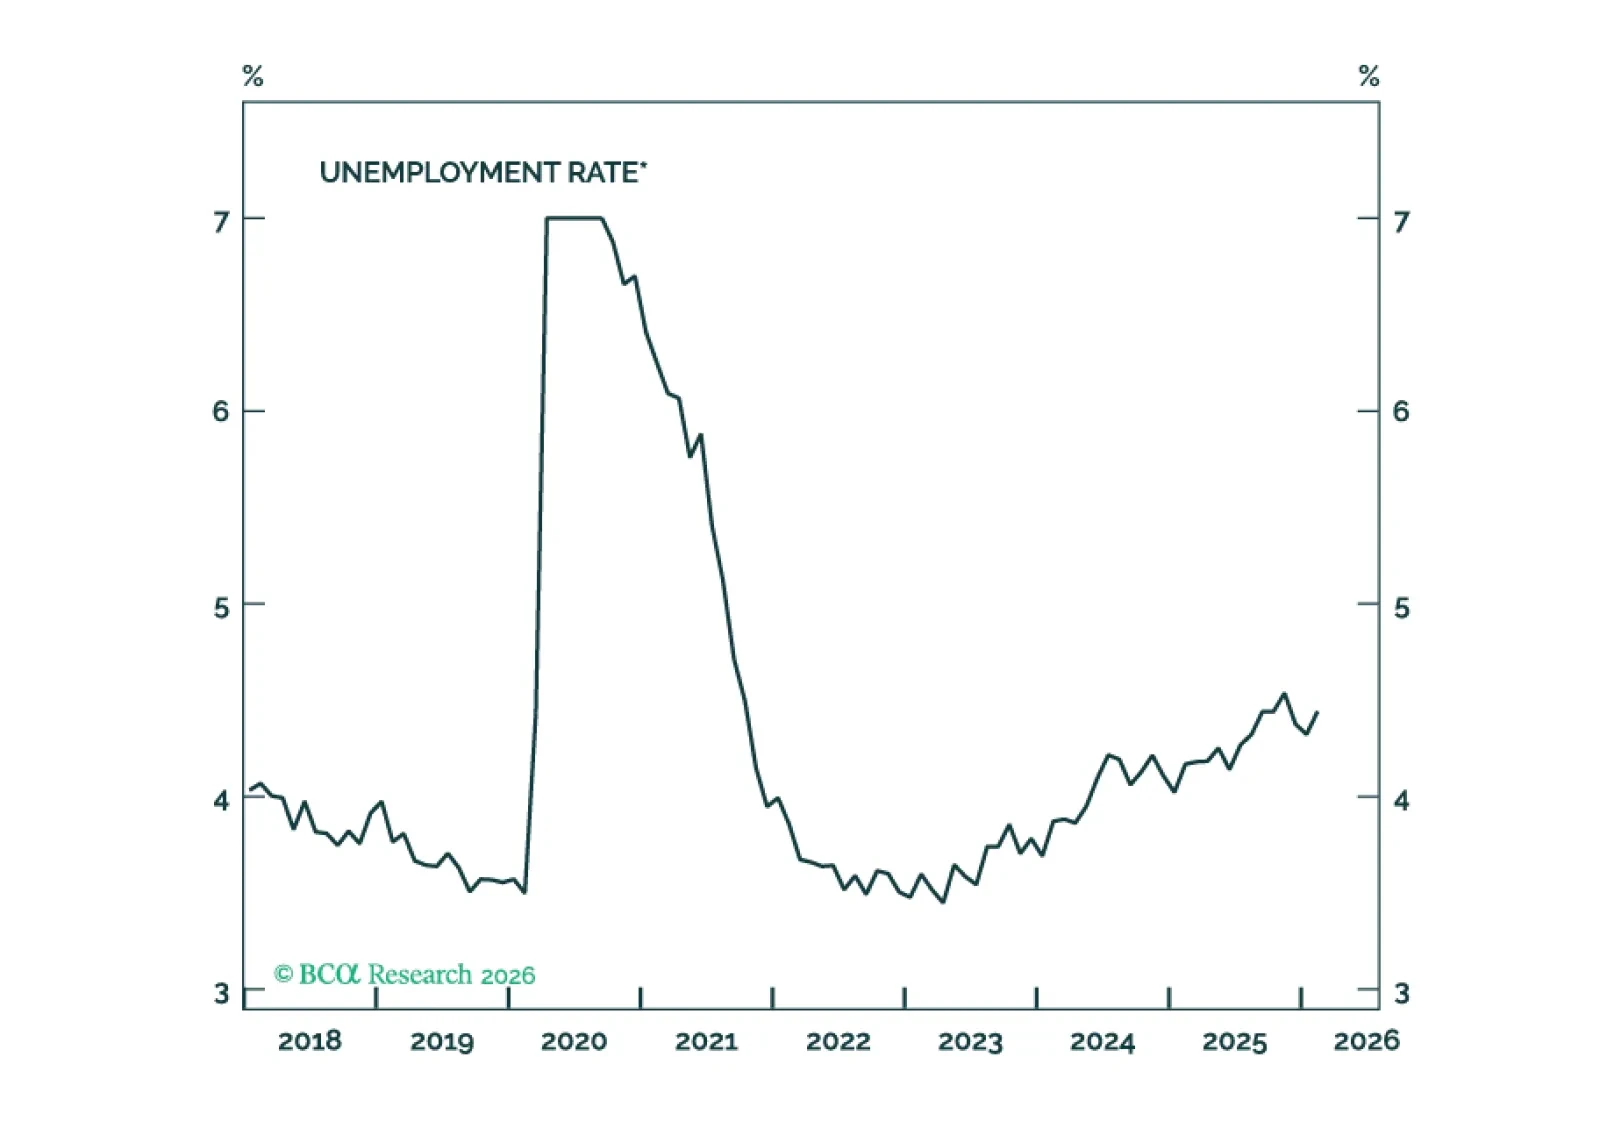
Looking through month-to-month volatility, job growth’s underlying trend is stable and consistent with a flat-to-slightly higher unemployment rate.
Special Report Europe’s fiscal debate has resurfaced as interest rates normalize and new spending pressures emerge. Yet alarmism is misplaced. Aggregate debt levels are high but broadly stable, servicing costs remain historically low, and r–g dynamics are broadly benign. Fiscal space matters less as the ECB and EU backstop growth and spreads. Structural reforms—not wanton fiscal spending—is Europe’s real opportunity.
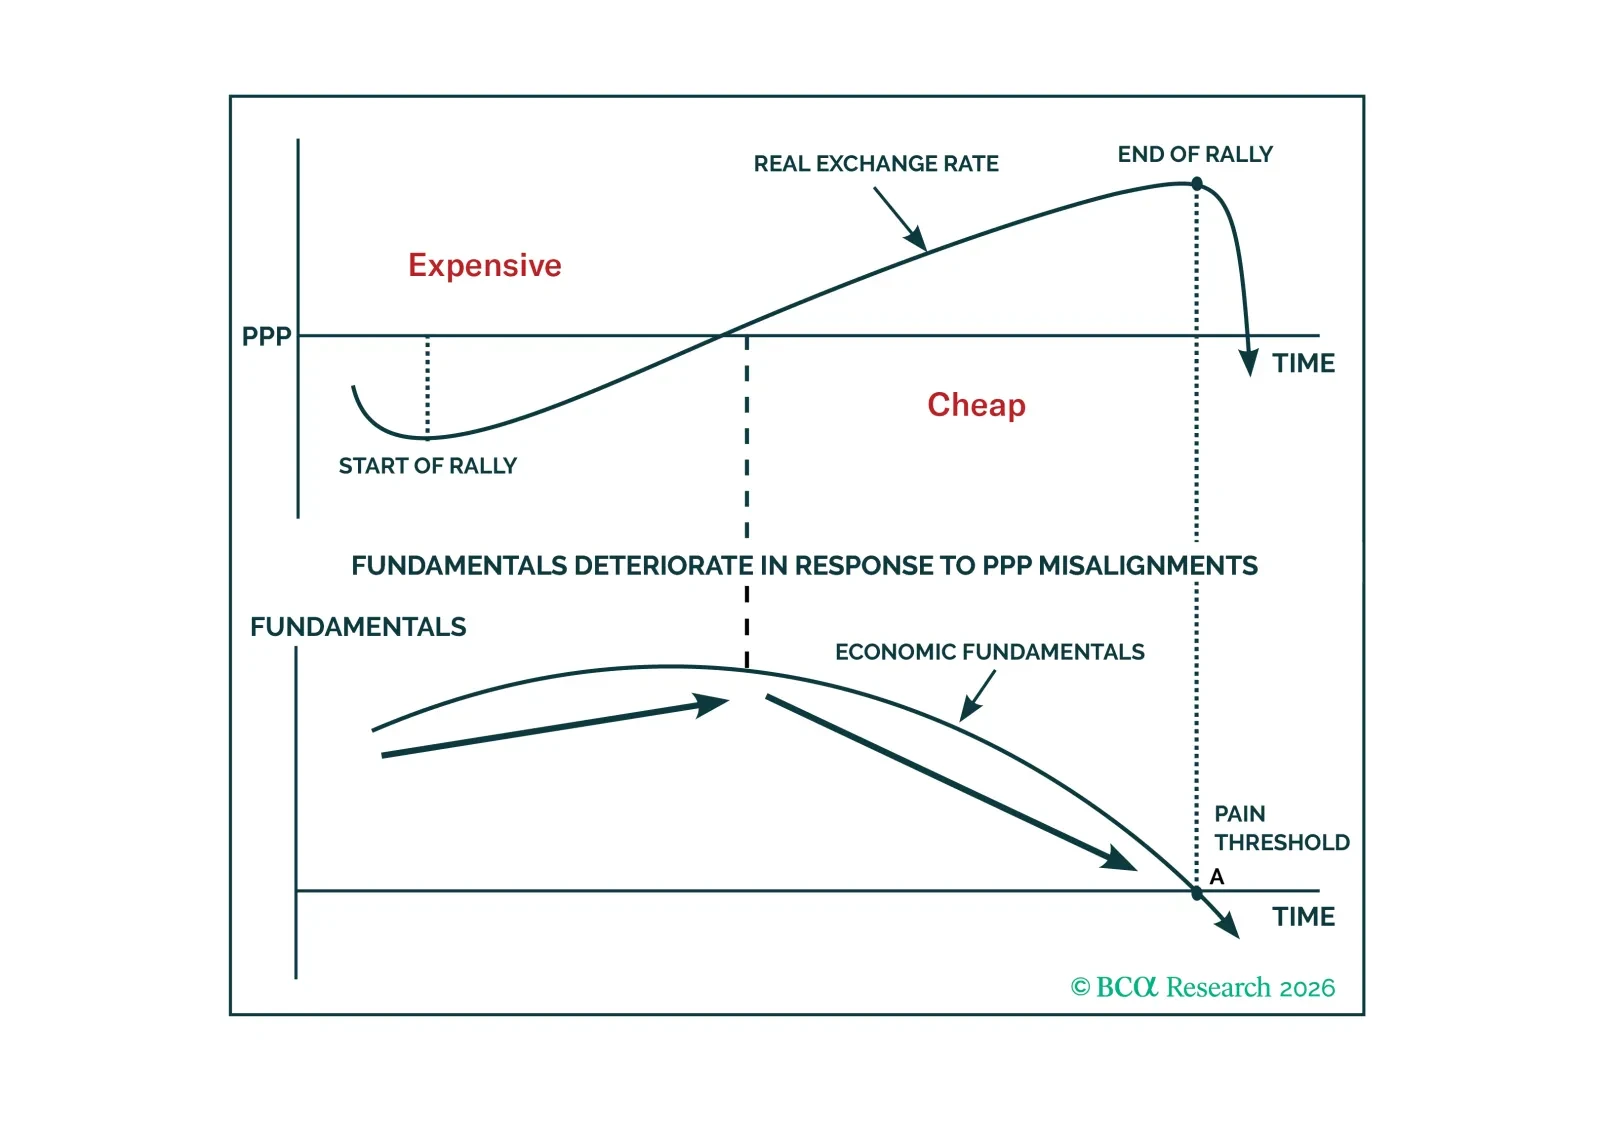
Special Report FX often looks random because no single model dominates across regimes. We lay out our long-term framework anchored in valuation, productivity, external balances, and the fiscal-monetary mix to identify when currencies are likely to mean-revert and where the long-run risk-reward is asymmetric.
Our Portfolio Allocation Summary for March 2026.
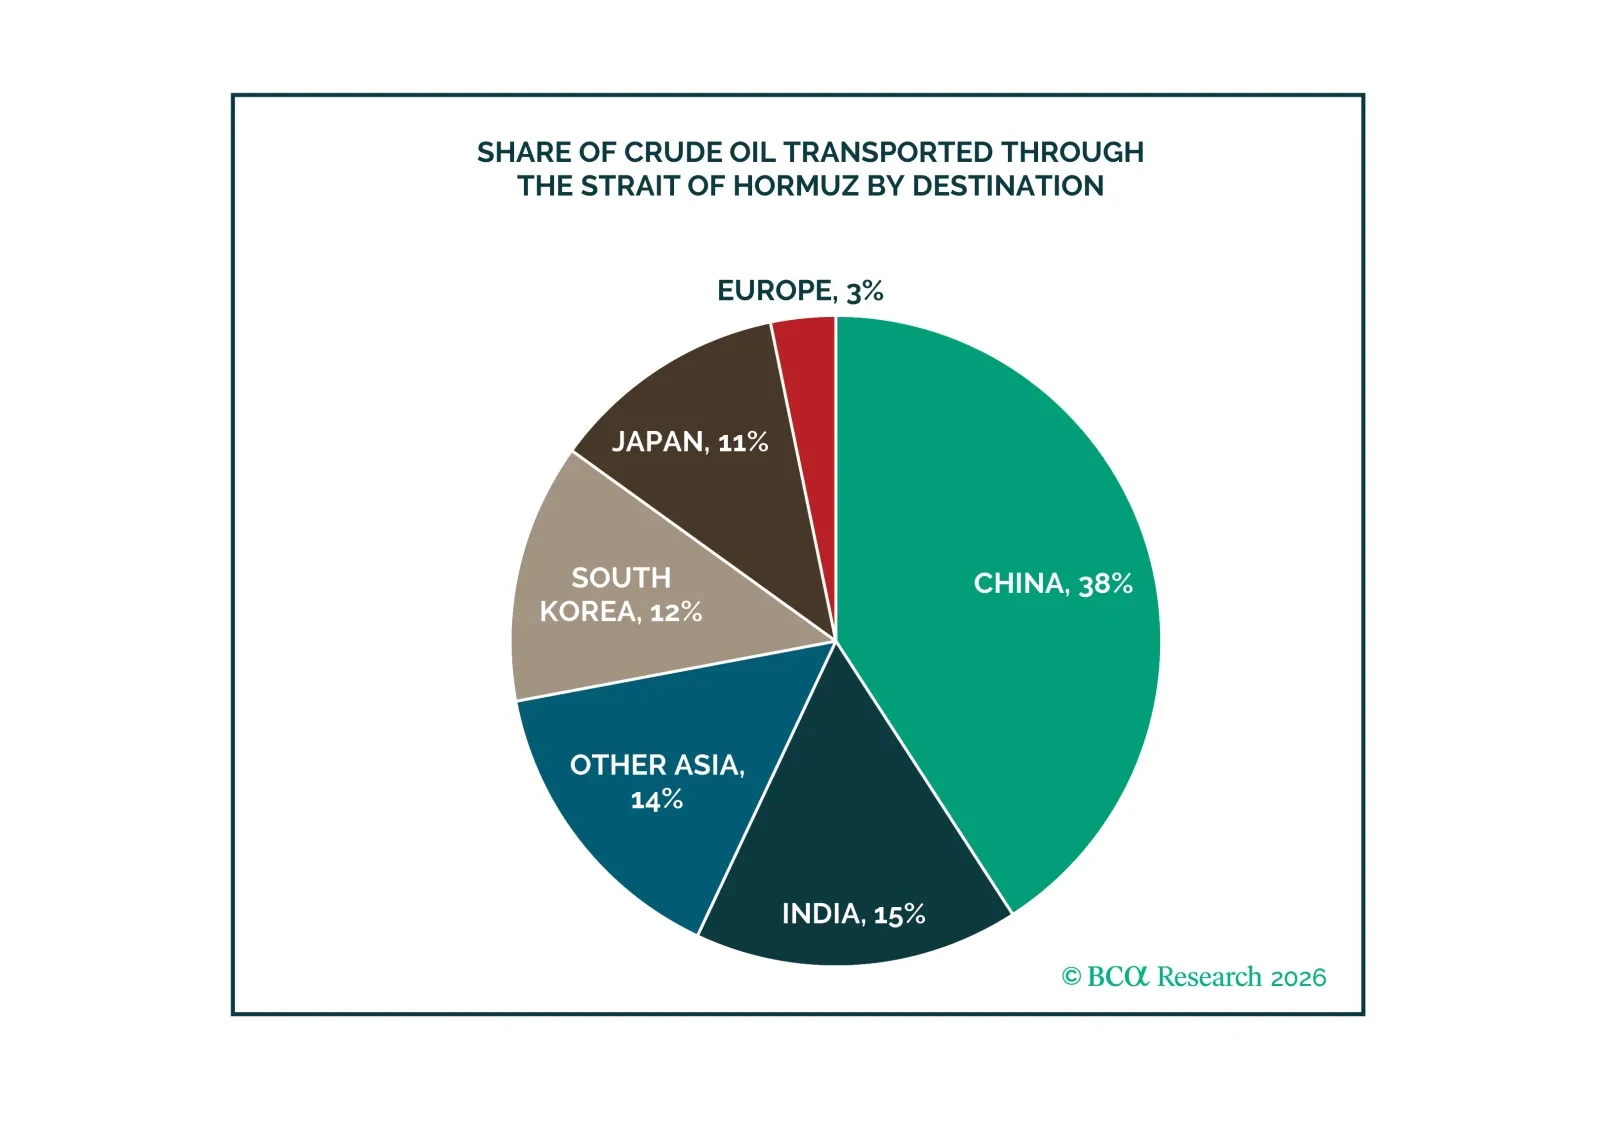
The war in Iran is disrupting global oil and LNG flows and remains a threat to regional energy infrastructure. Energy price risks remain skewed to the upside over the near term.
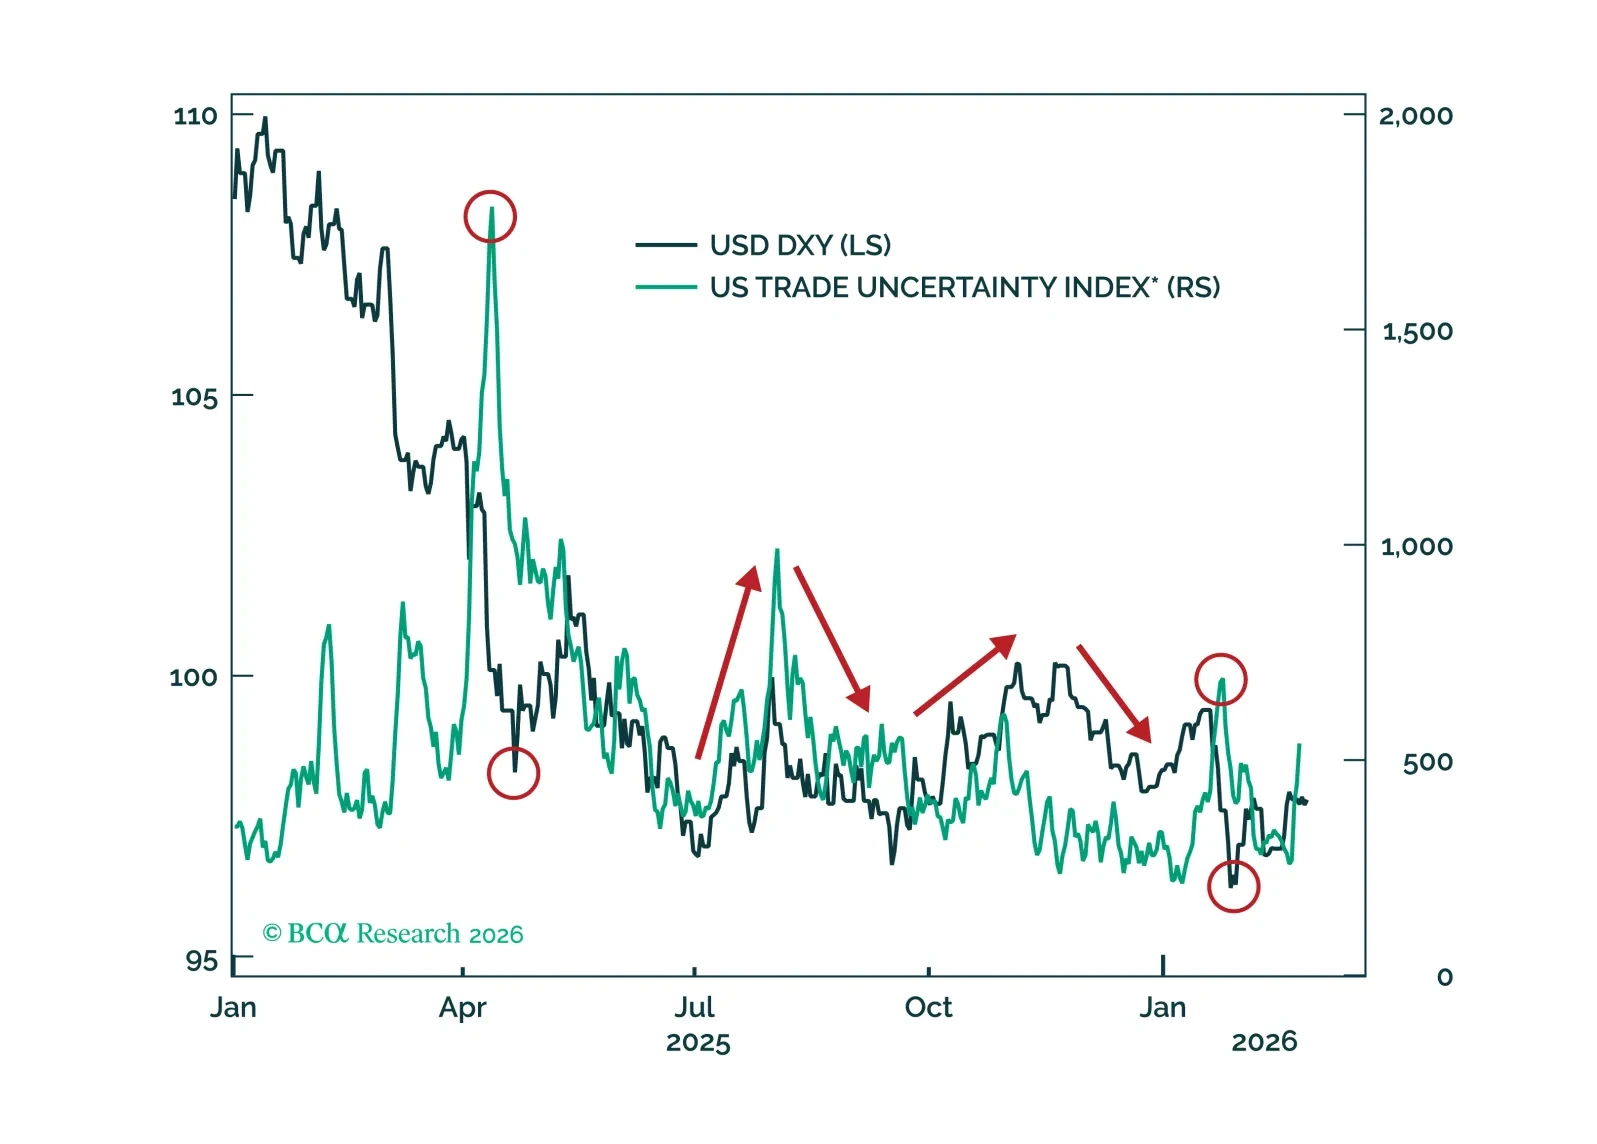
Policy risks are set to fade just as markets underestimate hawkish Fed repricing and crowd into short-USD positions, setting the stage for a tactical dollar rebound into the election cycle. Go long USD/CHF to capture the rate differential and receding policy uncertainty.
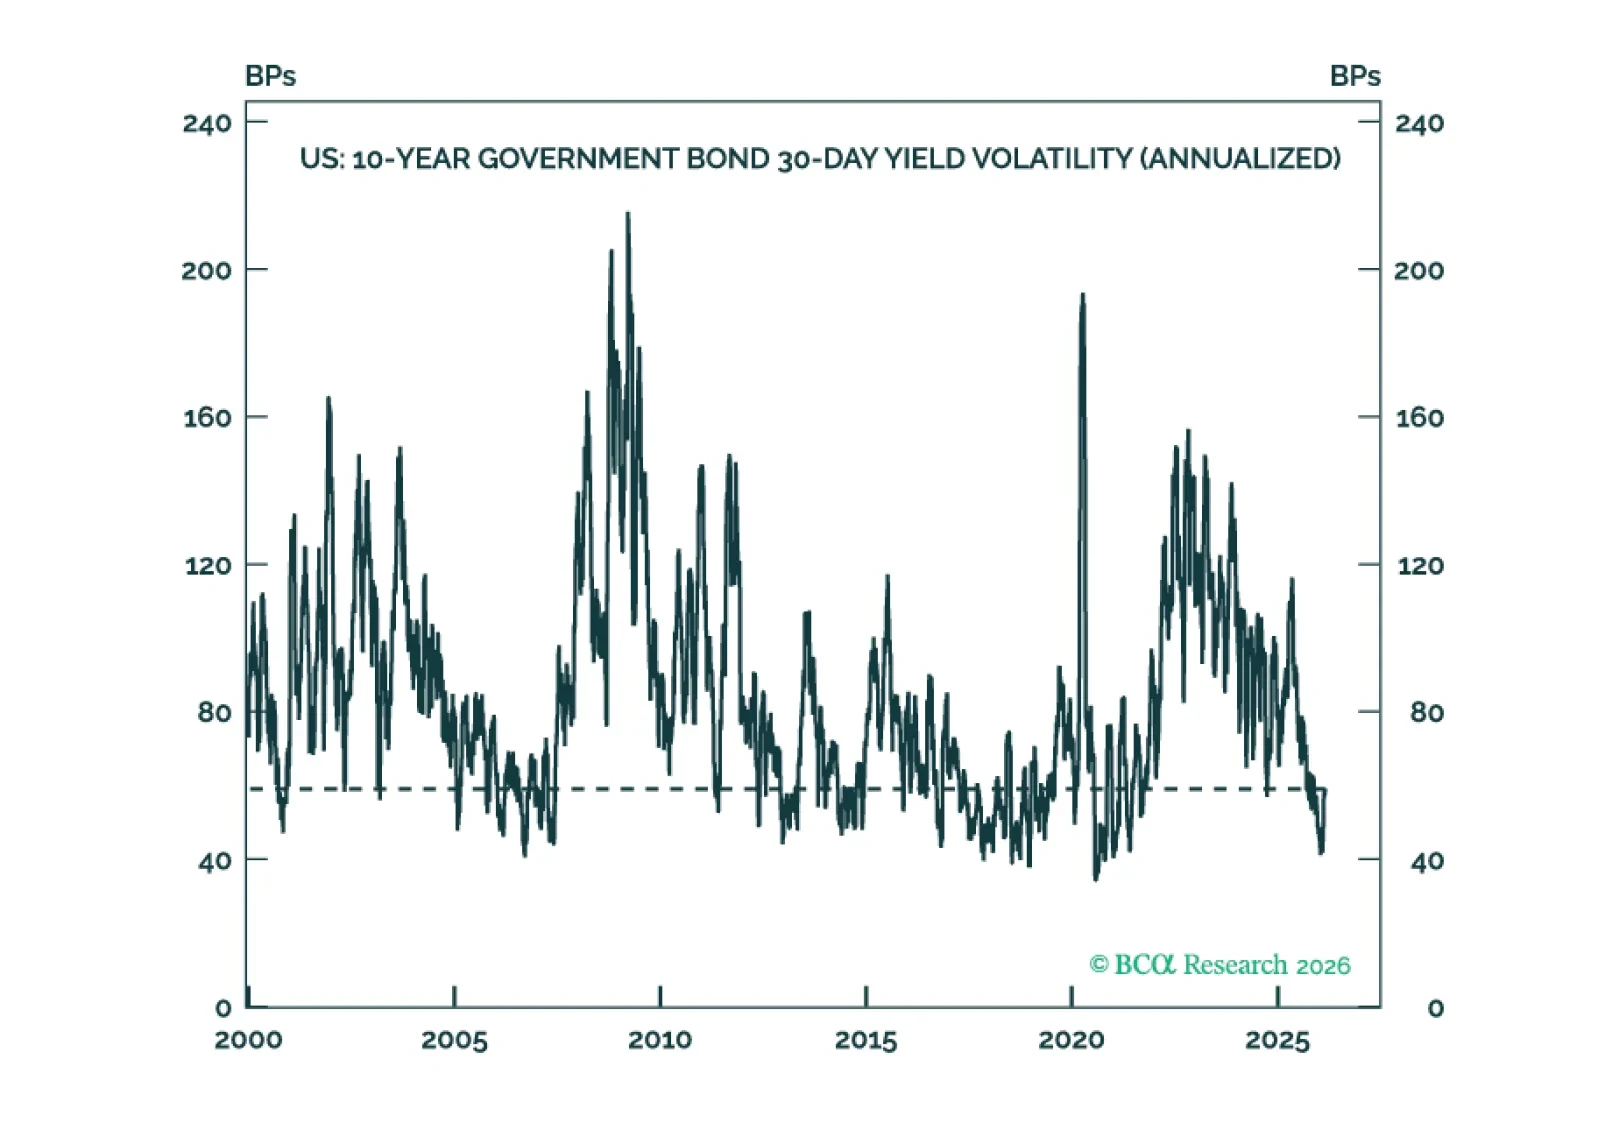
Special Report Interest rate volatility is very low across developed market fixed income. Investors should maximize the carry in their portfolios to outperform in a low rate vol environment.
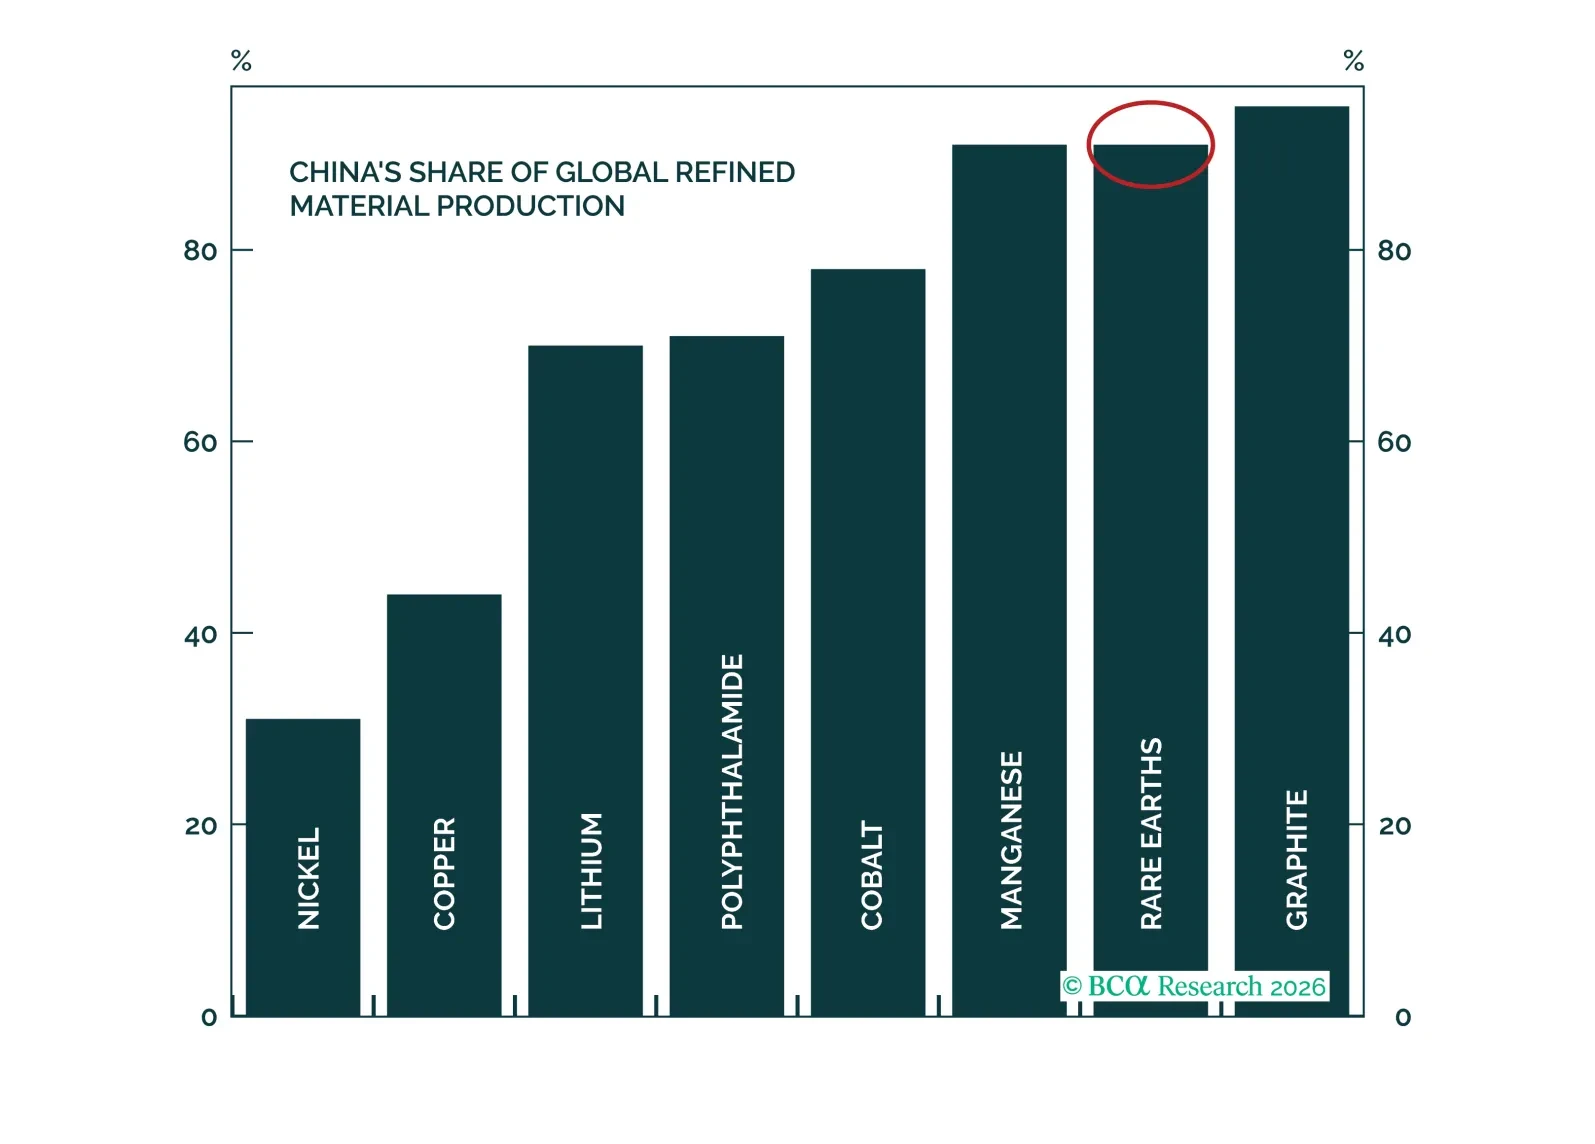
Special Report The global drive to build a resilient ex-China rare earth supply chain is accelerating. It has emerged as a strategic priority and is backed by both public and private sector investment in many countries. In this Special Report, we argue that rare earth adjacent plays present a more attractive opportunity for investors looking to gain exposure to the rare earth capex cycle than a pure-play strategy.
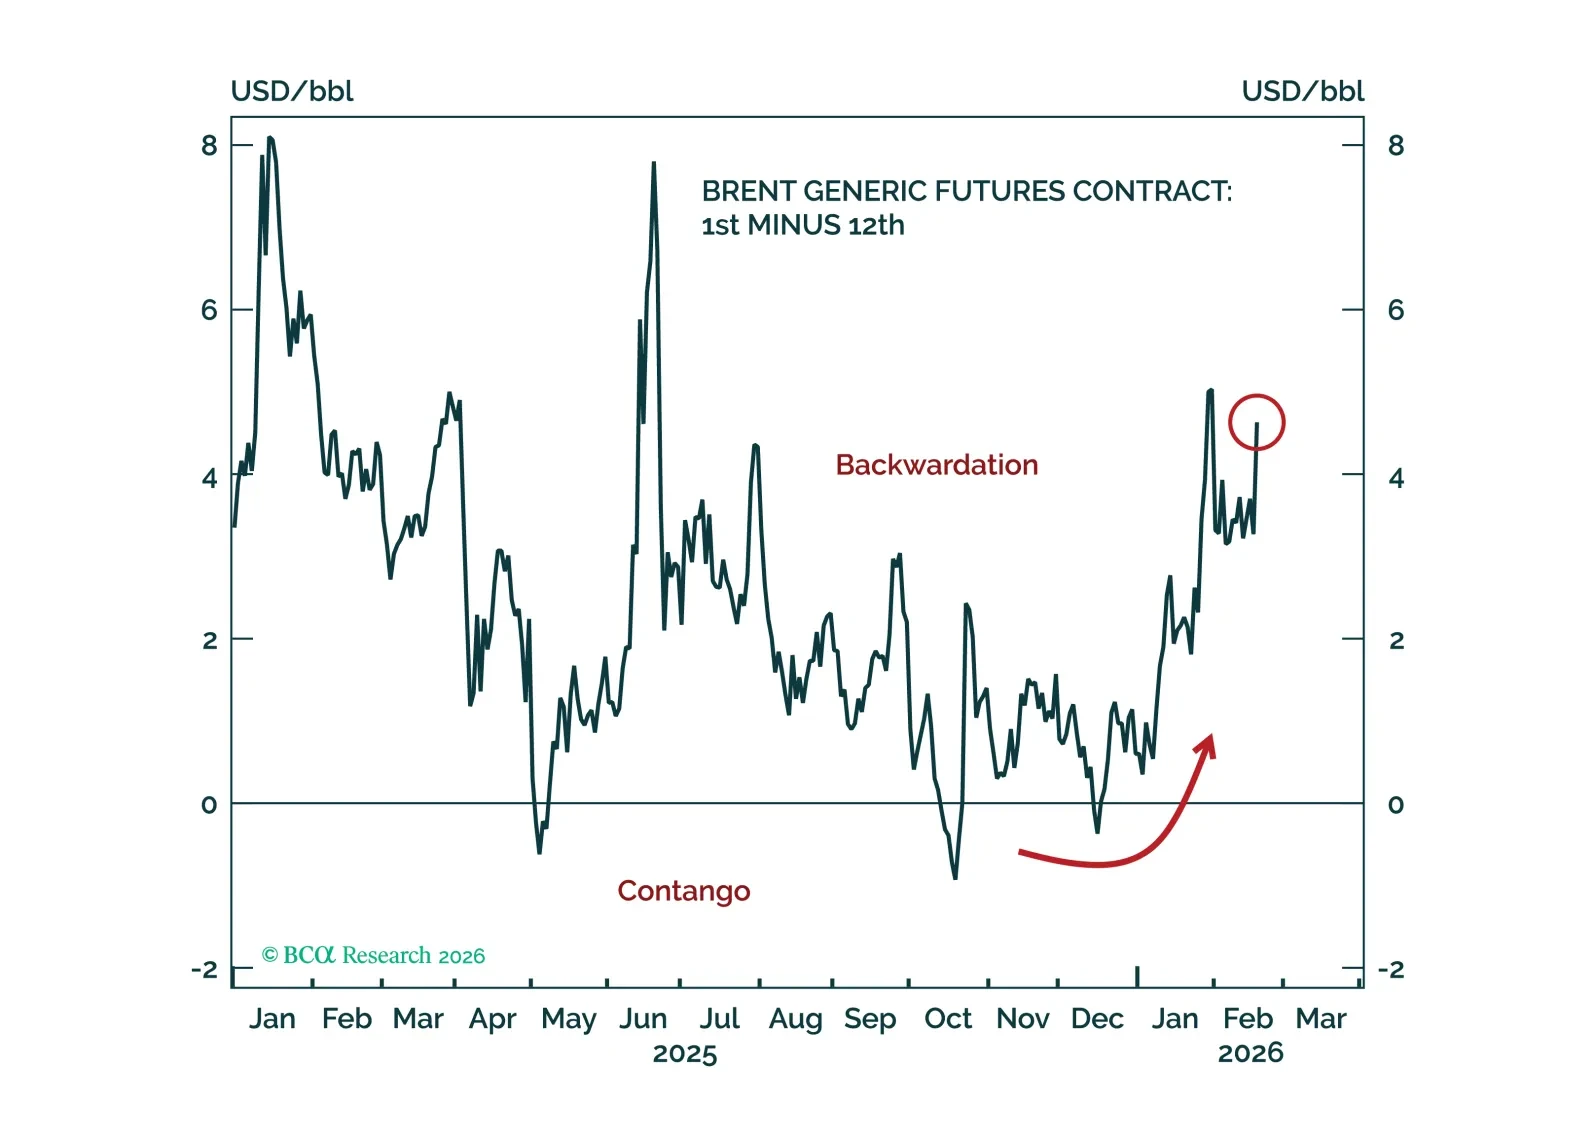
Oil price risks remain skewed to the upside over the near term as geopolitical risks continue to dominate. Nevertheless, we ultimately expect bearish fundamentals to reassert themselves over a six-to-12-month timeframe and drive oil prices lower.
We spent last week meeting investors in Switzerland. This Strategy Insight revisits the most prominent topics we discussed, including repatriation fears, SNB intervention, and Dutch pension reform.