Latest from BCA Research

Earnings reports and commentary from major retailers confirm that the consumer continues to lose momentum, while signs that the labor market continues to cool suggest that household income growth is poised to slow. We reiterate our downbeat fundamental take and our defensive asset allocation recommendations.
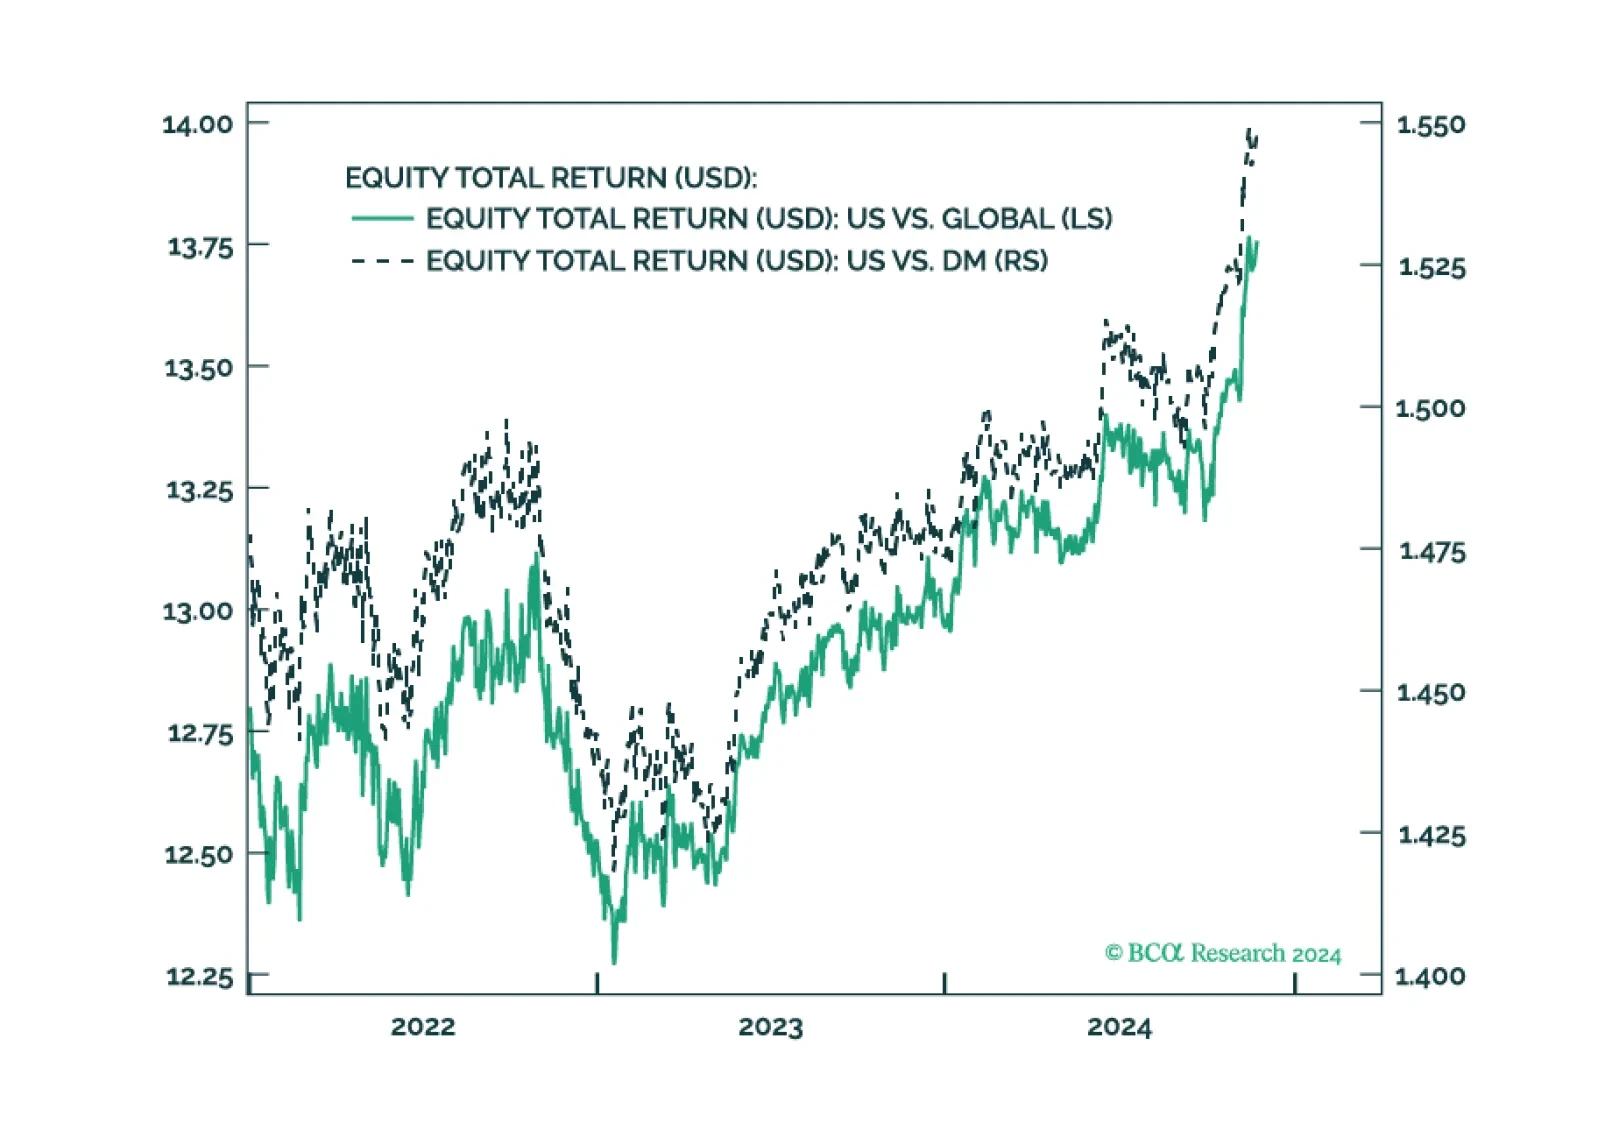
We were far too bearish on the US economy in 2024 – but the global economy remained sluggish and we got the critical geopolitical calls right. We predicted the Republican sweep in the US and the outbreak of direct military hostilities between Israel and Iran. We anticipated the escalation in Ukraine and Russia-NATO tensions that is taking place as we go to press. We stayed overweight US assets relative to global. We did not get blindsided by any of the elections in this “year of elections” – we traded several of them successfully. However, we disfavored cyclical sectors. We fought momentum stocks and lost. Many other trades turned sour. Equity volatility picked up substantially in 2024 as expected, but our attempts to take advantage of this shift fell flat.