Latest from BCA Research
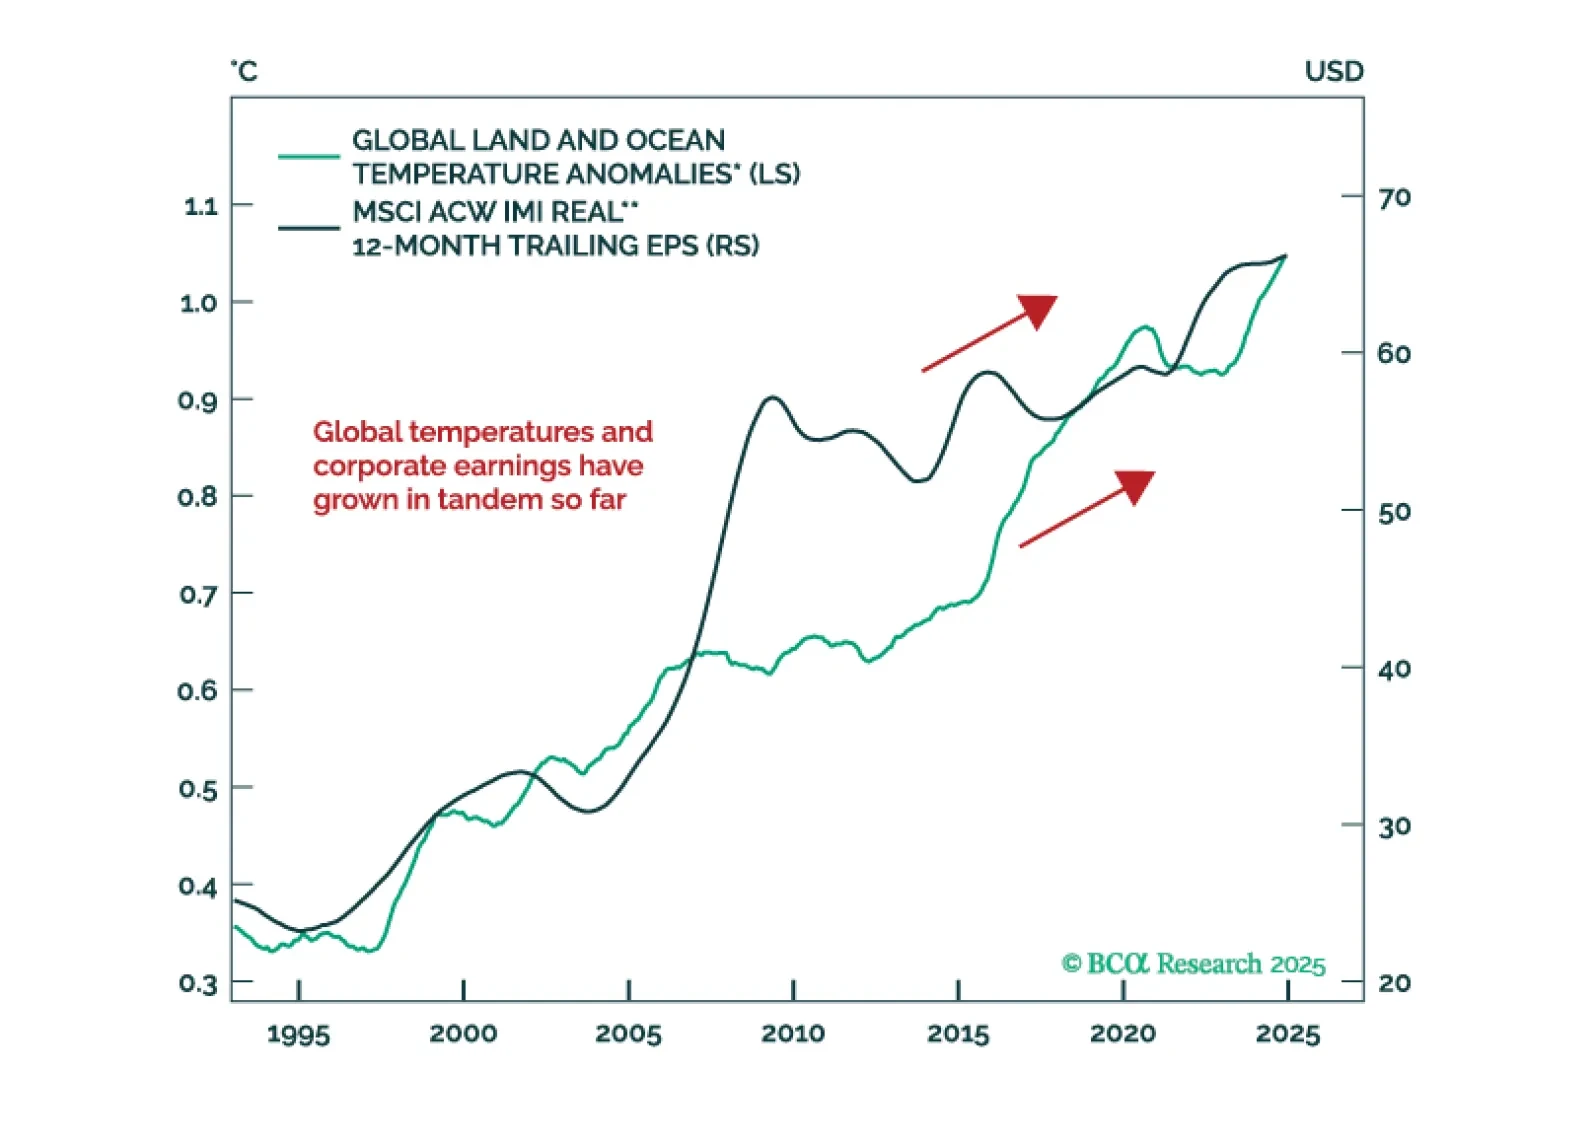
In our Beta report, we take a break from US politics and focus on the investment implications of climate change. Our colleague Ritika Mankar, of BCA’s Global Investment Strategy, makes a case for long-term investors to actually completely ignore climate change in their strategic asset allocation. Global warming will simply not make any difference, macroeconomically speaking, over the next five to ten years. Over a longer time horizon, climate change may even spur more economic growth, although with higher inflation as well.

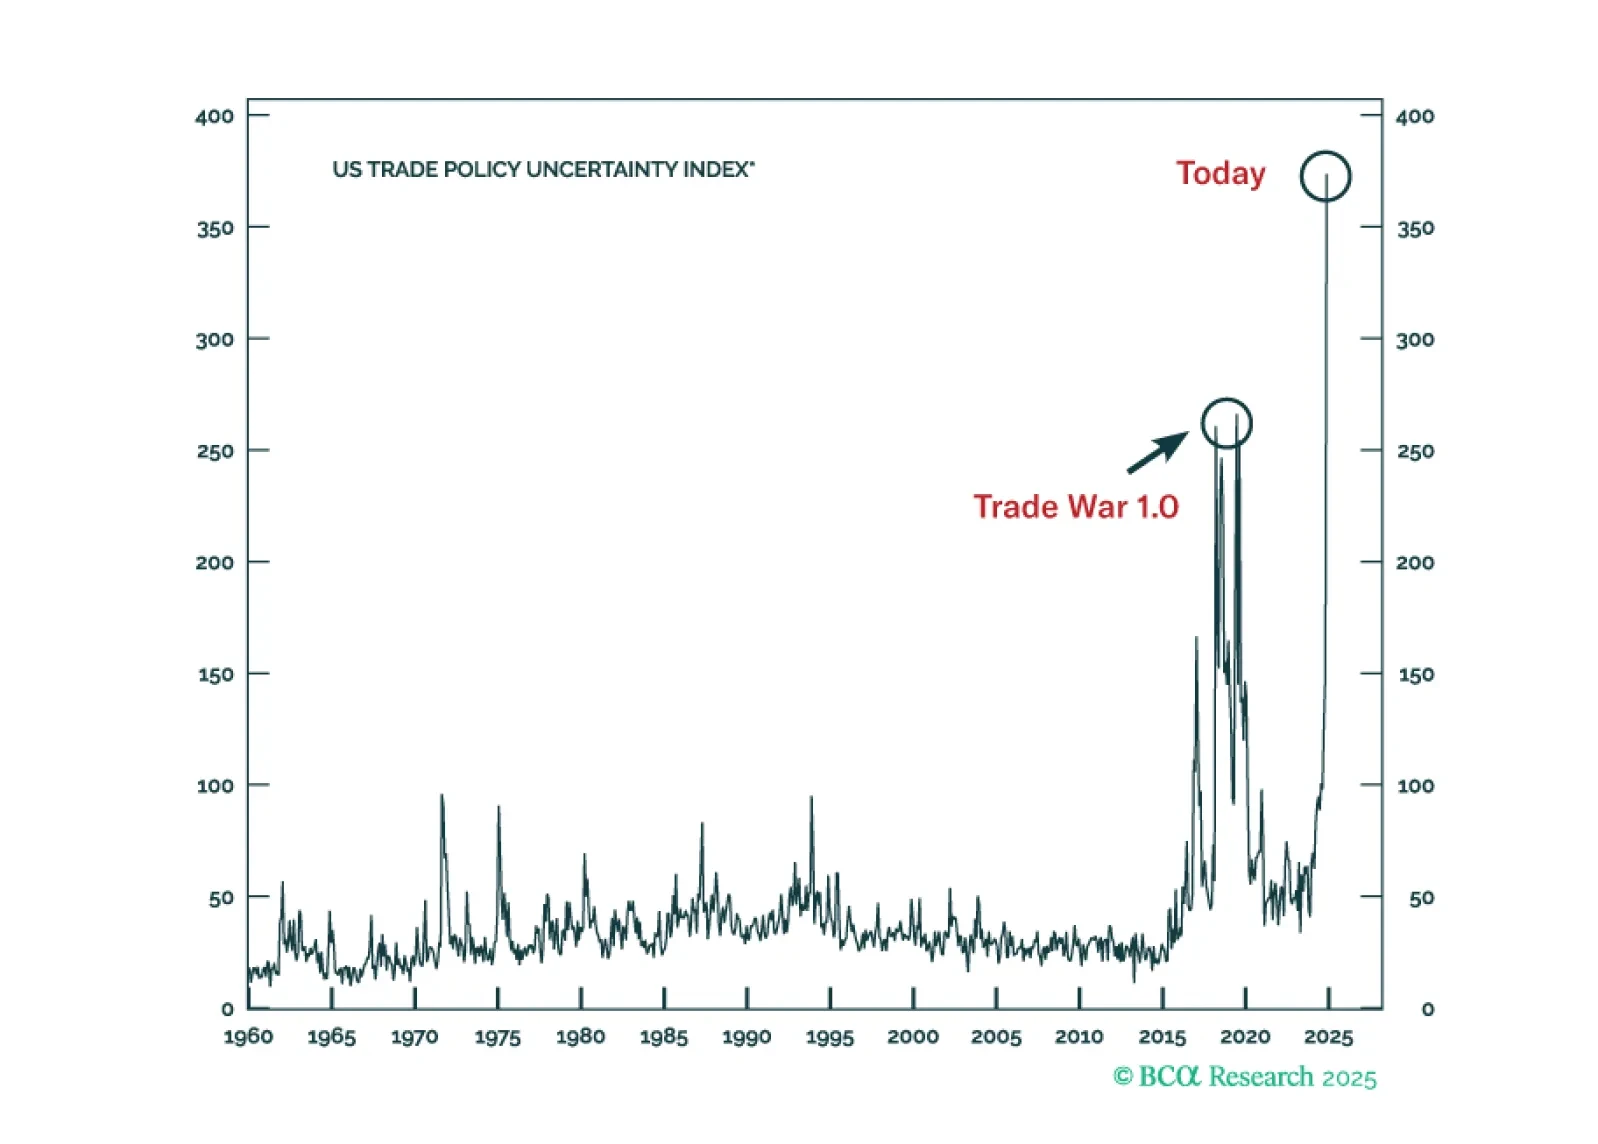
In our Alpha report, we reiterate that we expect President Trump to curb his most enthusiastic plans for tax cuts due to the pressure from the bond market. That will be good for equities in the long run – as it will assuage the pressure on yields. However, it should be negative for the USD as investors grapple with far less fiscal support for the US economy over the next four years than expected. We also give our readers a blueprint for following the news flow when it comes to trade policy. Stick to a framework and ignore tweets.

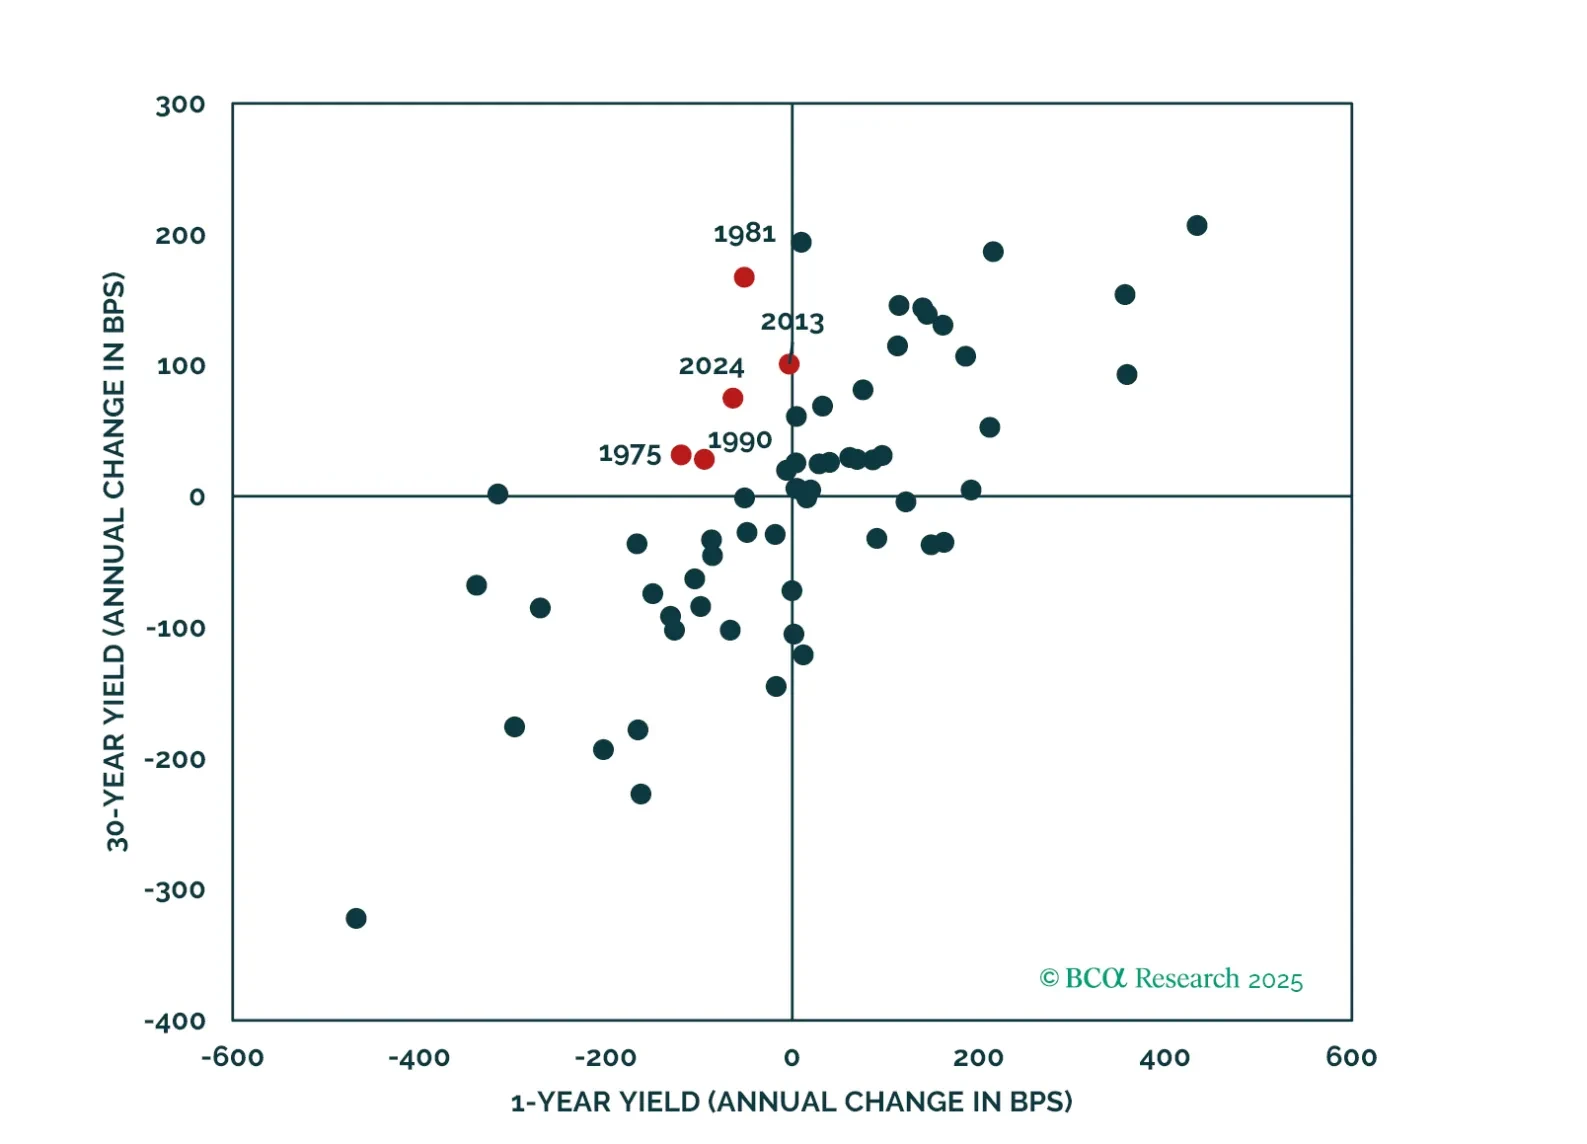
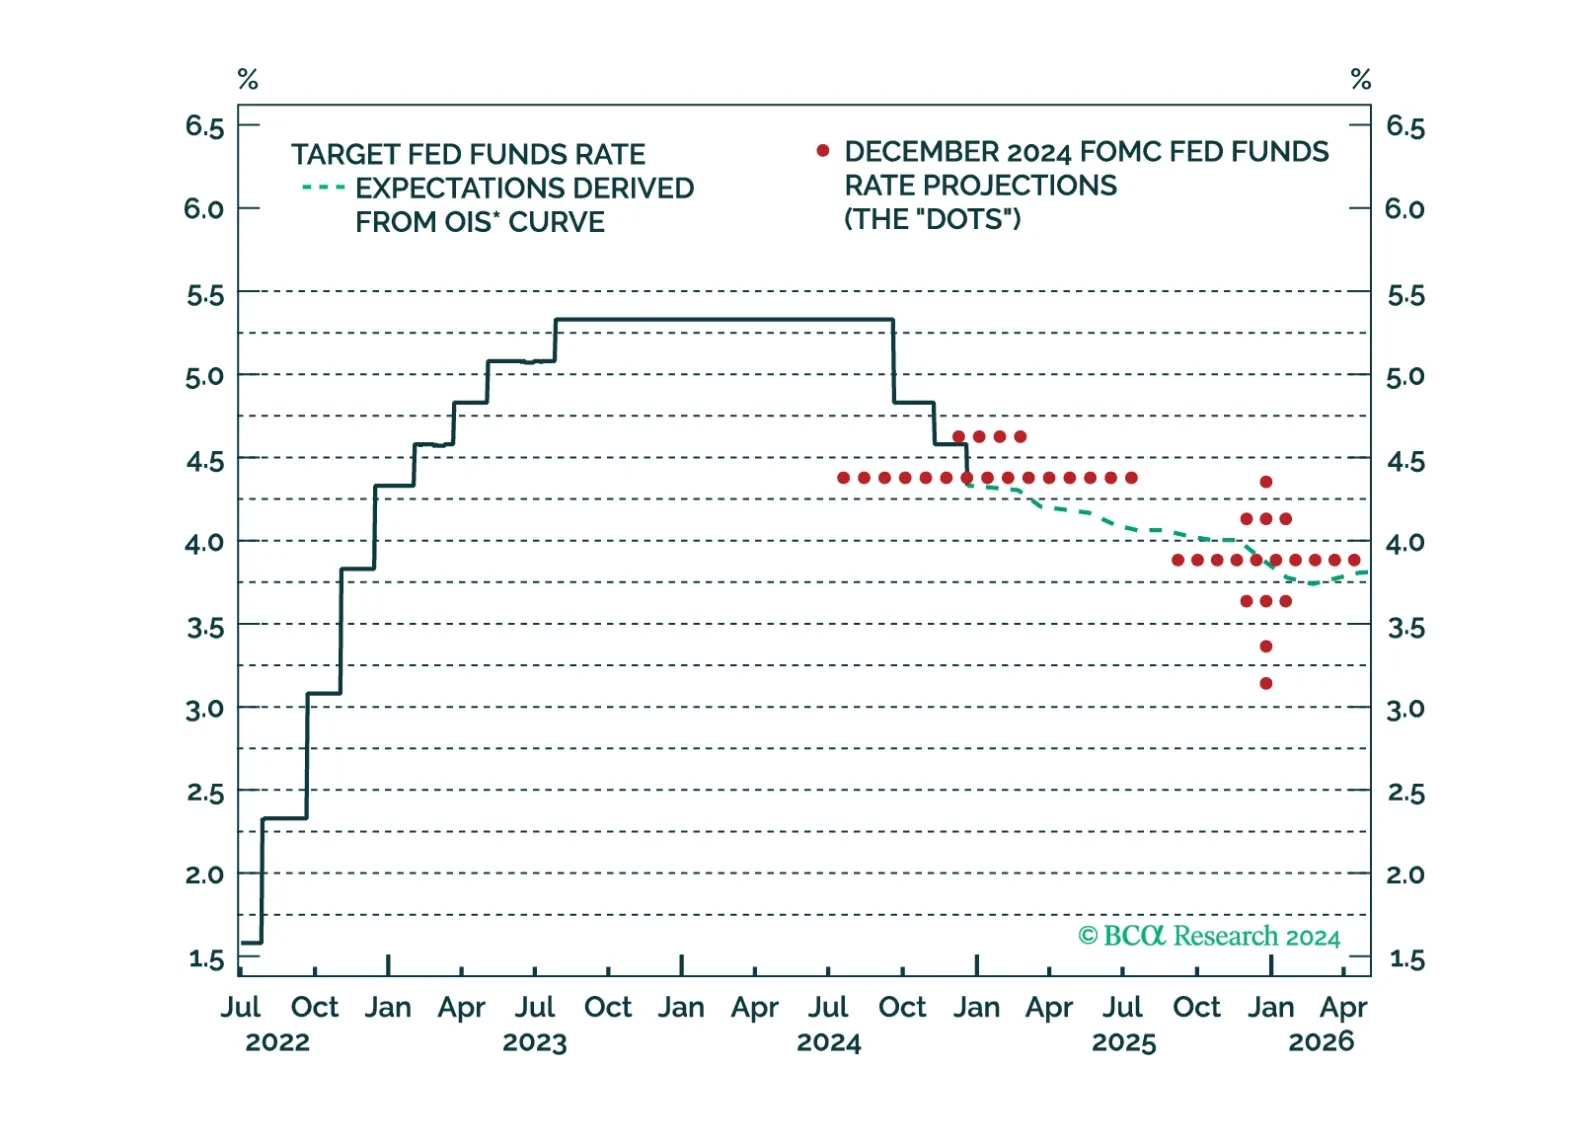
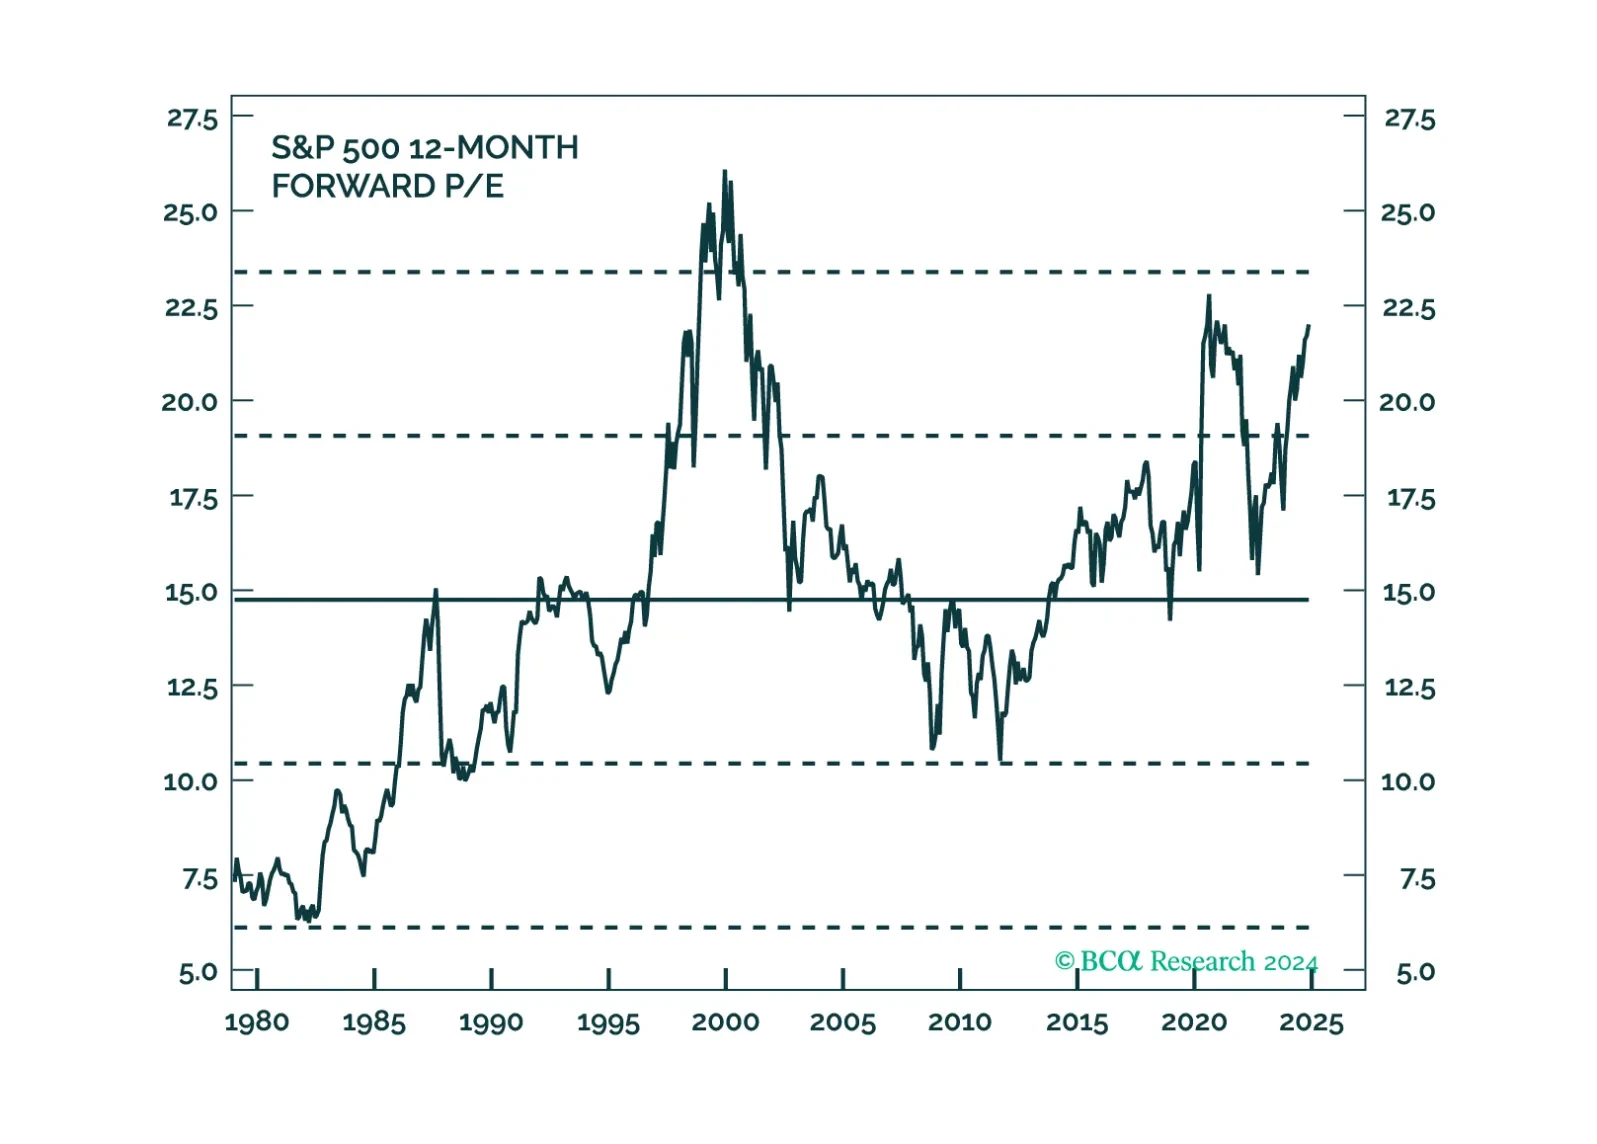
Paradoxically, raging optimism on the US economy is making a reacceleration in growth less likely in 2025. The reaction of the bond market has made the Fed rethink its cutting campaign. Markets are also constraining Trump’s agenda. US manufacturing will not recover with a surging dollar. Fears of inflation and debt sustainability have made moderate House Republicans push back against the President Elect’s wishes. Given the sky-high optimism embedded in asset prices, we believe a defensive portfolio stance is warranted on a 12-month horizon. Overweight gold to hedge the risk of a fiscal crisis.

The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
The latest version of the MacroQuant model sees the near-term risks to stocks as slightly tilted to the downside. It is neutral on bond duration and expects the US dollar to continue strengthening in the near term.
Our last publication of the year lets the charts do the talking about why we think the consumer post-pandemic momentum is fading along with the labor market.