 CoreMacro
| Global
Global macro research on the forces driving the world economy, with calls across stocks, bonds, and currencies.
All three of Trump's signature policy proposals - increased deficit-financed infrastructure spending, a more restrictive immigration policy, and trade protectionism - are dollar bullish. These policies could cause the U.S. economy to overheat, forcing the Fed to raise real rates more than it otherwise would. Equities could rally in the near term following a Trump victory, but are likely to face stiff longer-term headwinds. Treasurys would still suffer modest losses, while, ironically, the one asset that could suffer the most from a Trump victory is gold.
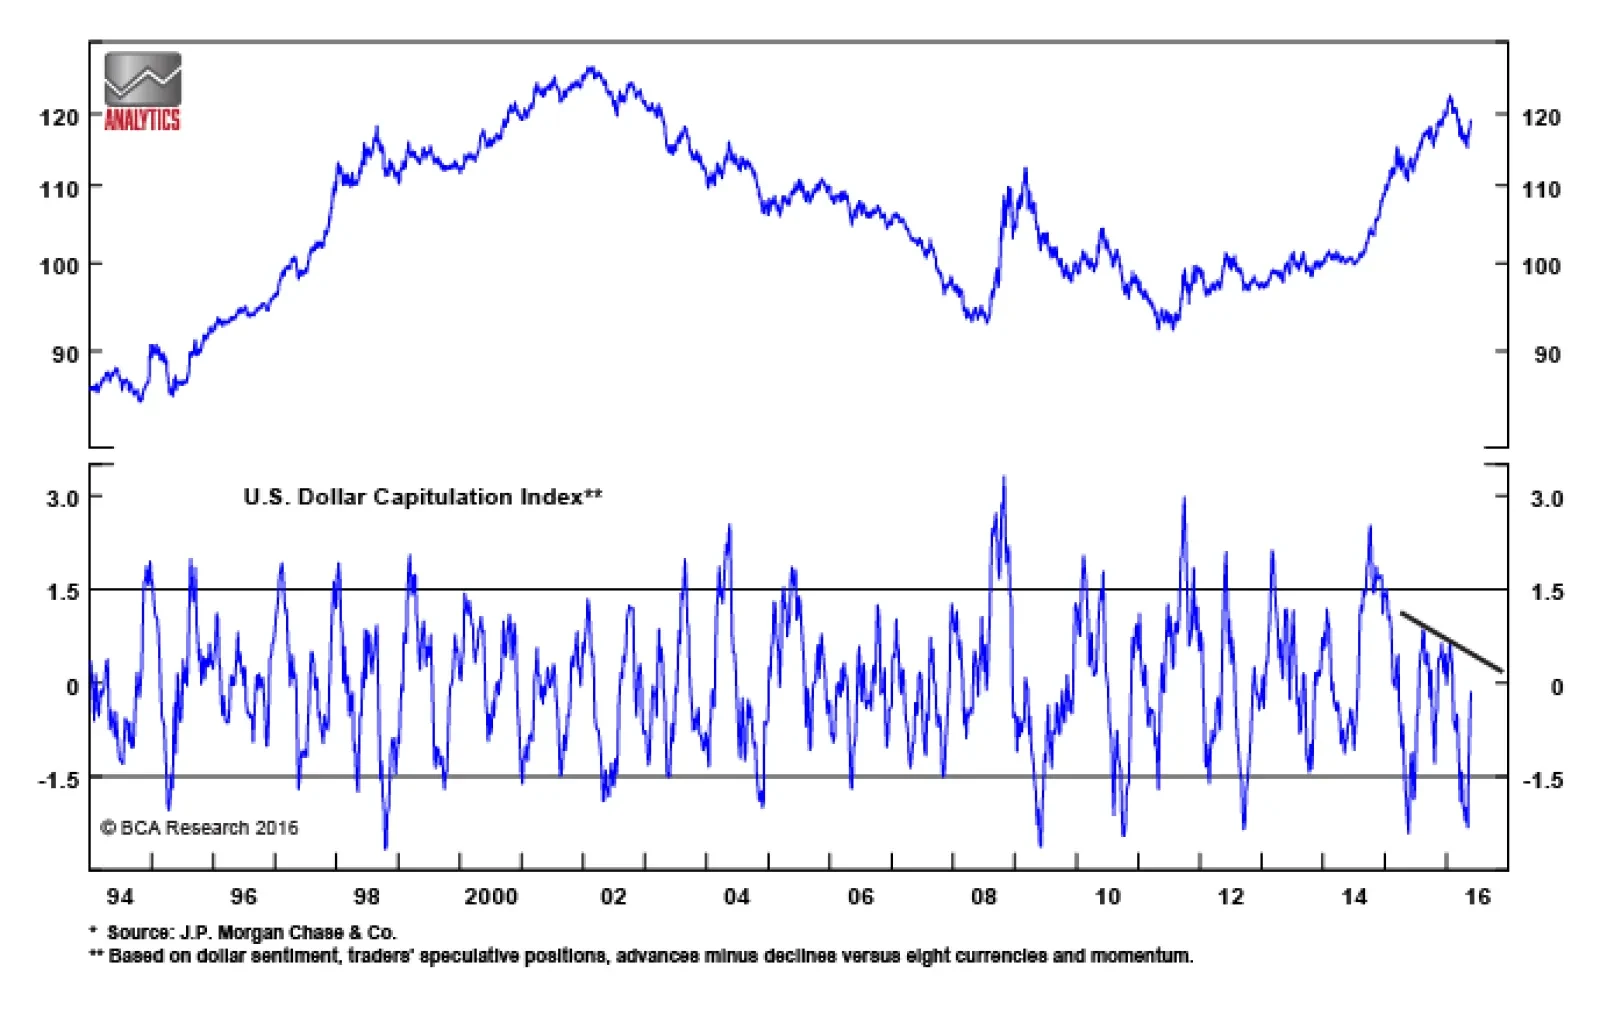
For the month of May, the model underperformed both global equities and the S&P 500. For the month of June, the model is further paring back its risk exposure.
China has fallen into the same "fiscal trap" that ensnarled Japan in the 1990s. Unprofitable investment projects undertaken by SOEs are a necessary evil. The underlying problem is not overinvestment, but an economy that is demand-deprived. Meanwhile, structural factors will ensure that savings remain high. Any efforts by the authorities to curb credit growth will result in a sharp economic downturn. China will continue to generate excess capacity and export deflation to the rest of the world, which is good for bonds. We recommend going long Chinese banks, the most hated equity sector.

Helicopter money is coming, and once deployed, will prove to be much more successful than most people imagine. Stay long Japanese and German inflation swaps. USD/JPY and EUR/USD are ultimately likely to reach 140 and 0.9, respectively, over the next two years. The U.S. economy will remain resilient enough to make helicopter money unnecessary but a strengthening dollar will greatly curtail the ability of the Fed to raise rates. Investors should overweight Treasurys relative to bunds and JGBs. Helicopter money will benefit gold as well as the beleaguered European and Japanese stock markets.
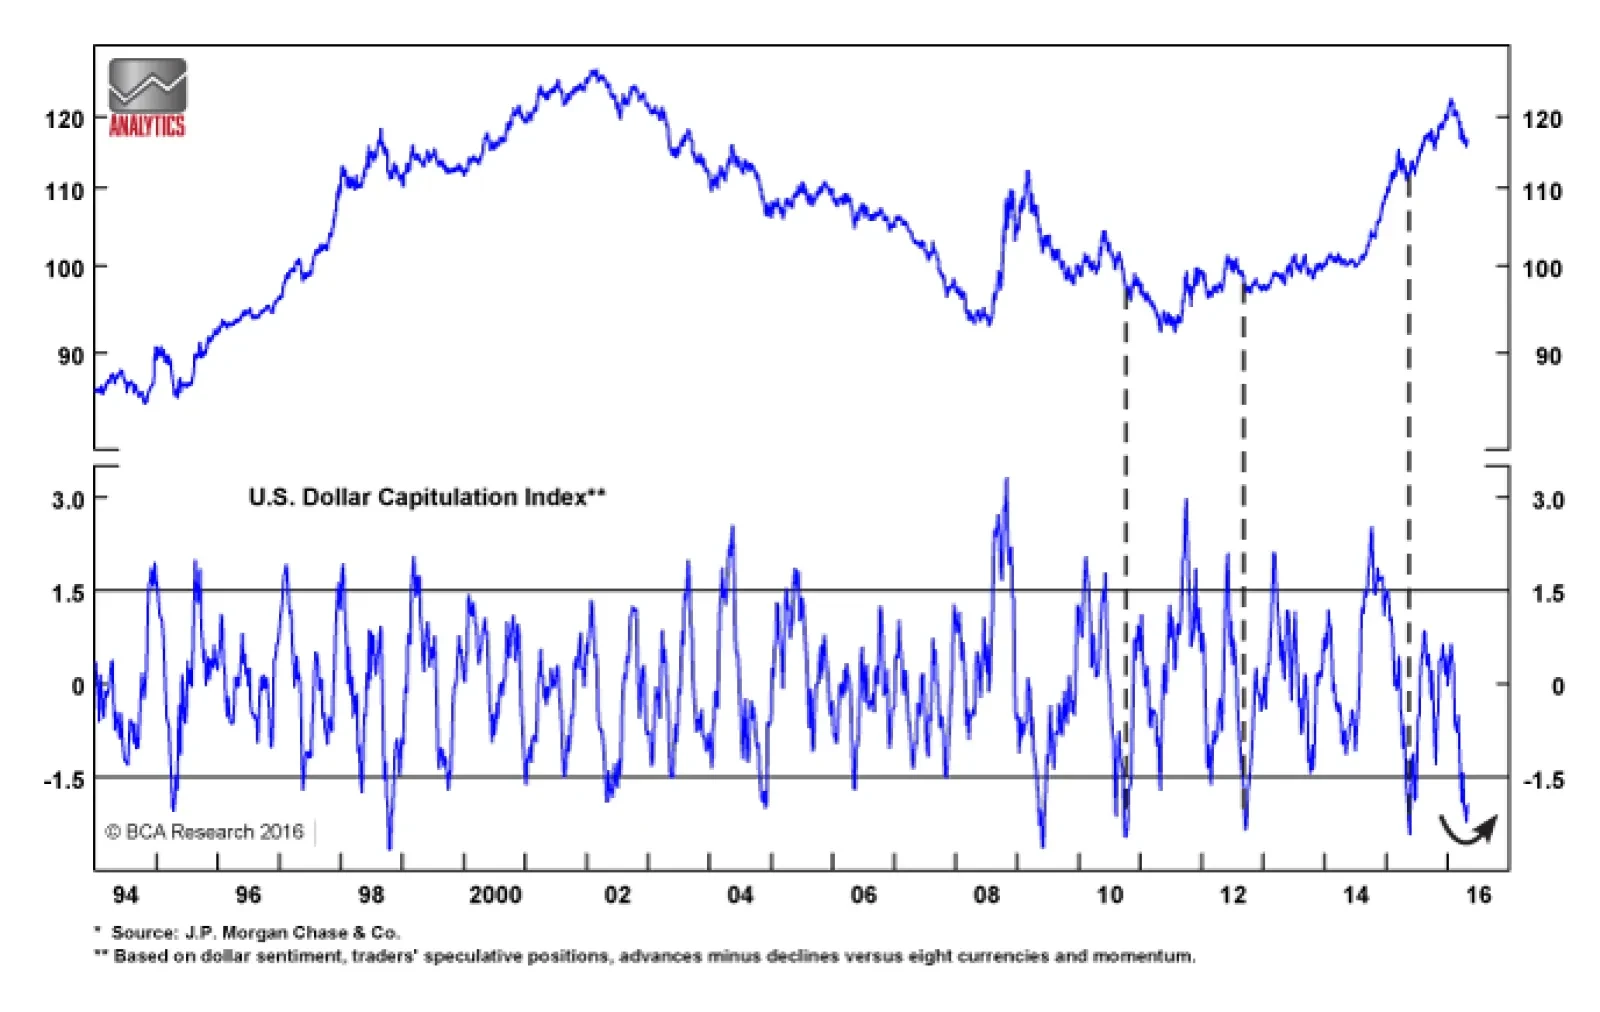
For the month of April, the model's performance was in line with the S&P 500, but lagged global equities. For May, the model is aggressively paring back its equity risk exposure. Both Europe and Emerging Markets were downgraded, but still possess the lion's share of the equity allocation, while defensive markets such as the U.S. and Switzerland received a boost. In the fixed-income space, U.S., Italian and Spanish paper were the model's favorites.
The Fed's statement underscored its 'go slow' approach, with a June hike increasingly unlikely, but September and December still in play. The BoJ stood pat, reluctant to admit that NIRP was a flop soon after it was launched. Nevertheless, we expect fresh easing this summer. Chinese stimulus should last a few more months, but commodities will resume their structural downtrend thereafter. Remain tactically bullish risk assets; be prepared to turn more cautious in Q2.

The reflation trade will continue for a few more months on Chinese fiscal/monetary stimulus and a more dovish Fed. Despite a slightly better-than-expected start to the earnings season, Q1 S&P 500 profits are set to fall for a fourth consecutive yoy decline. Ex-energy, things aren't so bleak. Domestically-focused companies will experience flat earnings and modestly-positive revenue growth in Q1. Although margins have almost certainly peaked, their decline will be drawn-out. Remain overweight Europe/Japan/China versus the S&P 500 (currency-hedged).
A stronger yen is hampering efforts to revive the Japanese economy and the BoJ's failed NIRP experiment leaves open the option of direct currency intervention. Probability is also high that the April 2017 sales tax hike will be postponed, perhaps indefinitely. A major stimulus package, "helicopter drops" of money, and a 4% inflation target may be the only way to permanently overcome deflation. Near-term, further yen strength is likely, but the long-term path is down.