FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.
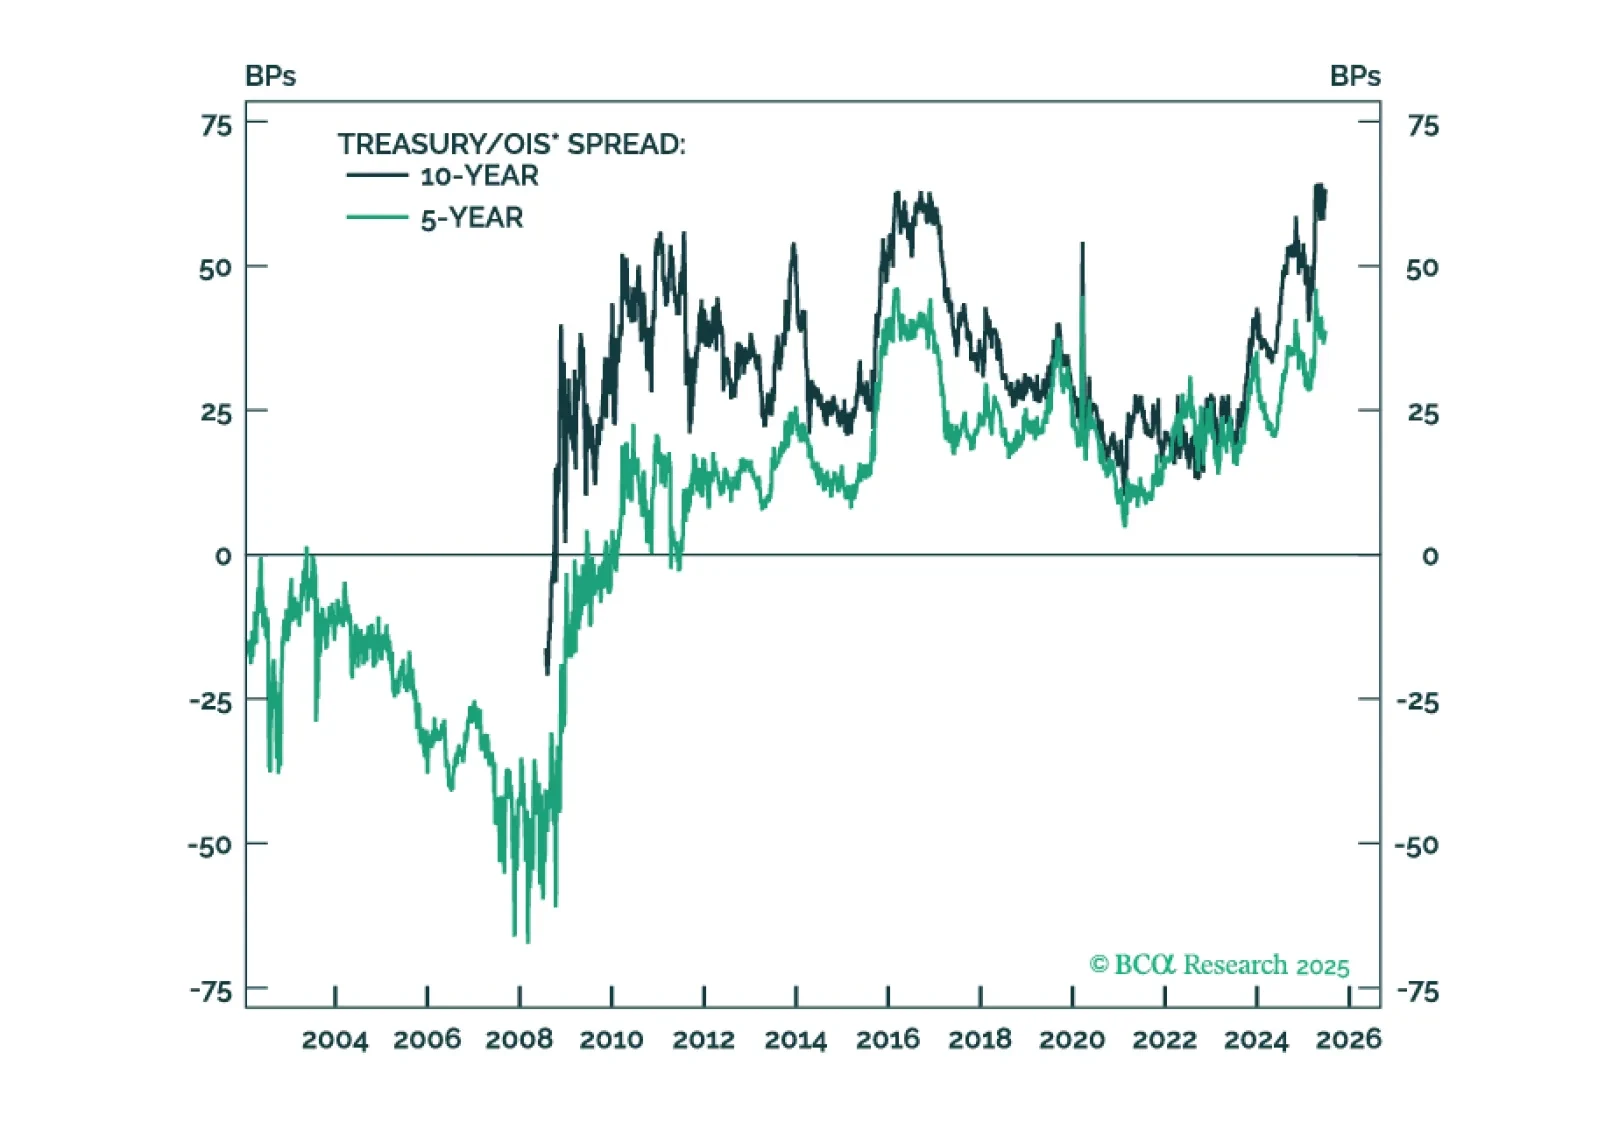

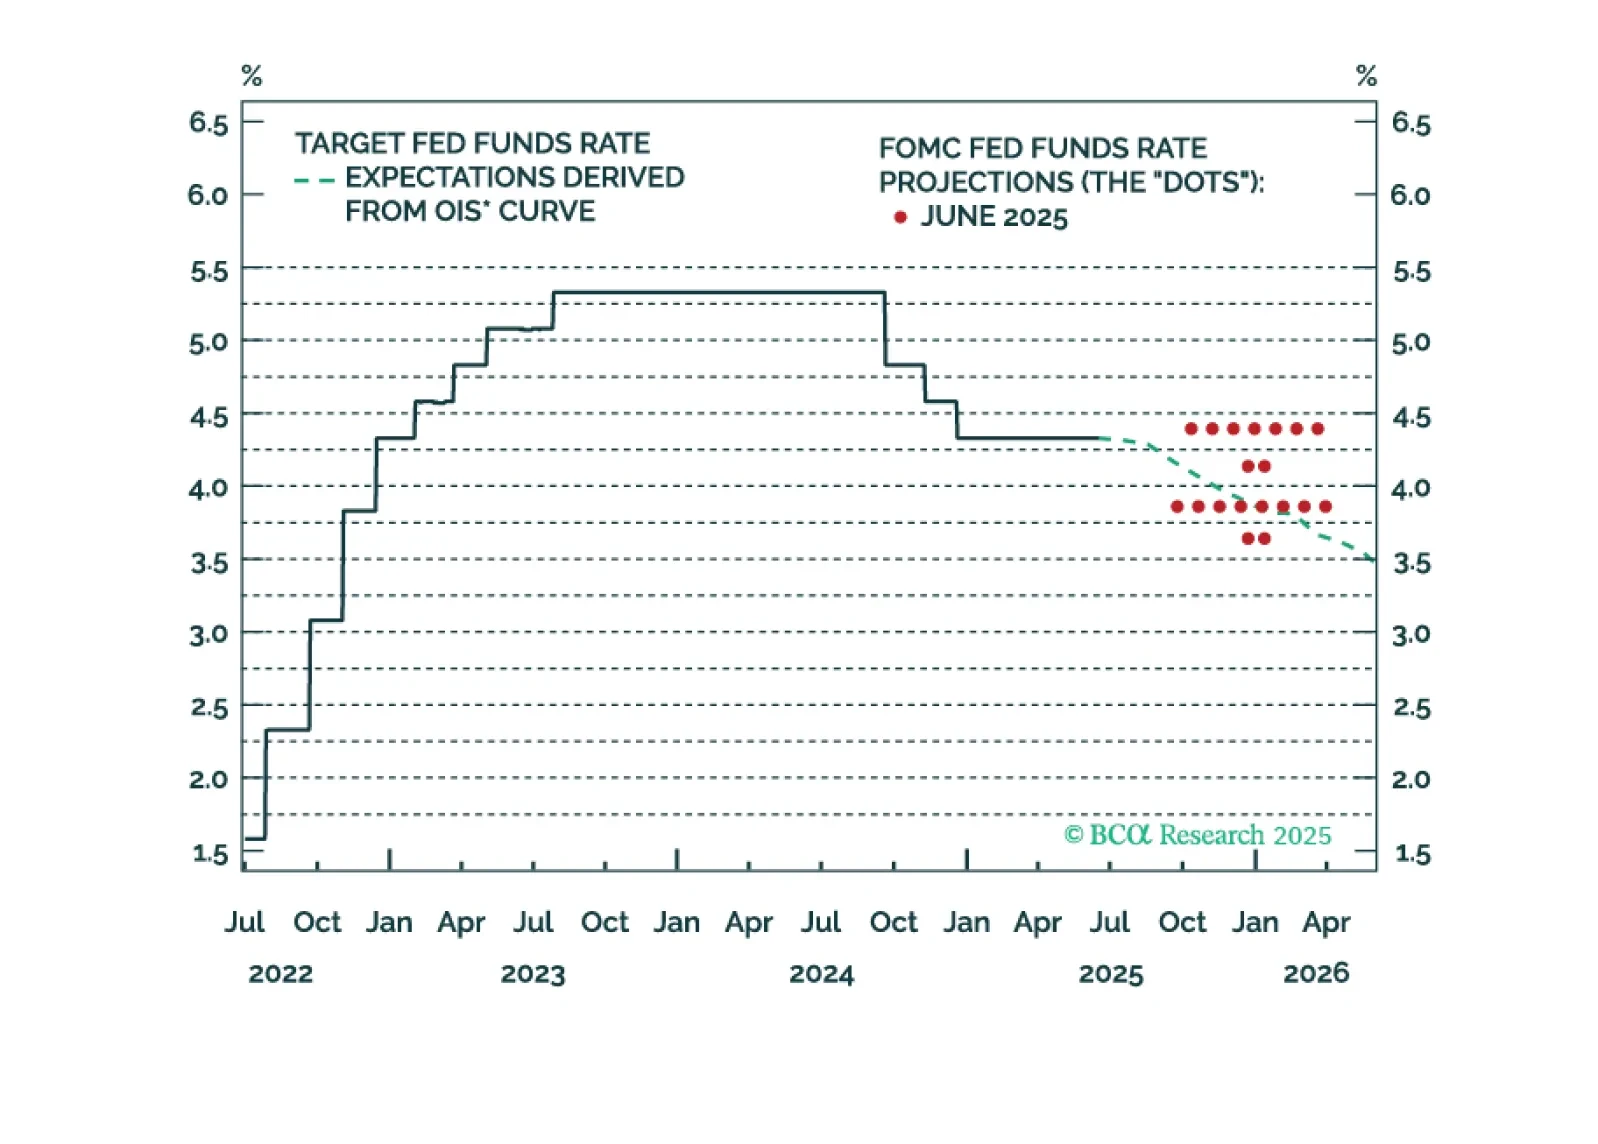
The Fed’s 2025 interest rate projections reveal two camps within the committee. One group looking for no rate cuts this year and another looking for 50-bps of easing. We think the second group’s forecast will turn out to be more accurate.
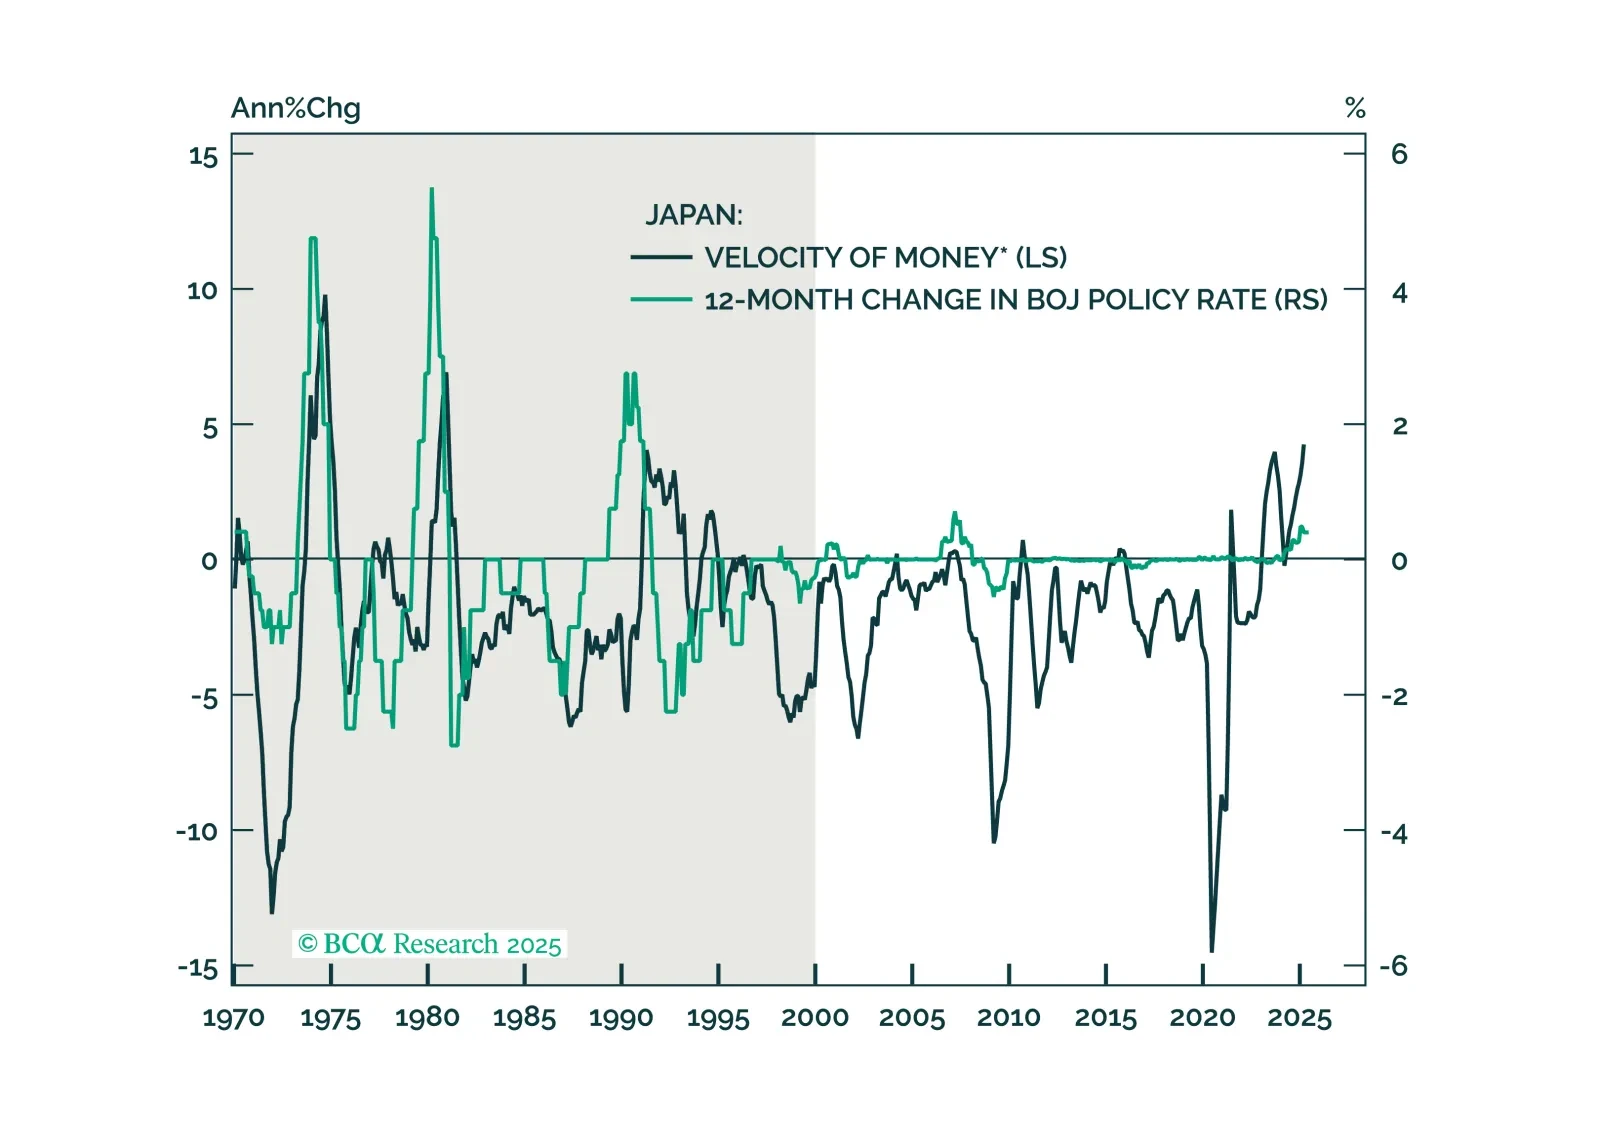
In this note, we reaffirm our underweight position in JGBs and long yen positions given the BoJ’s meeting overnight.
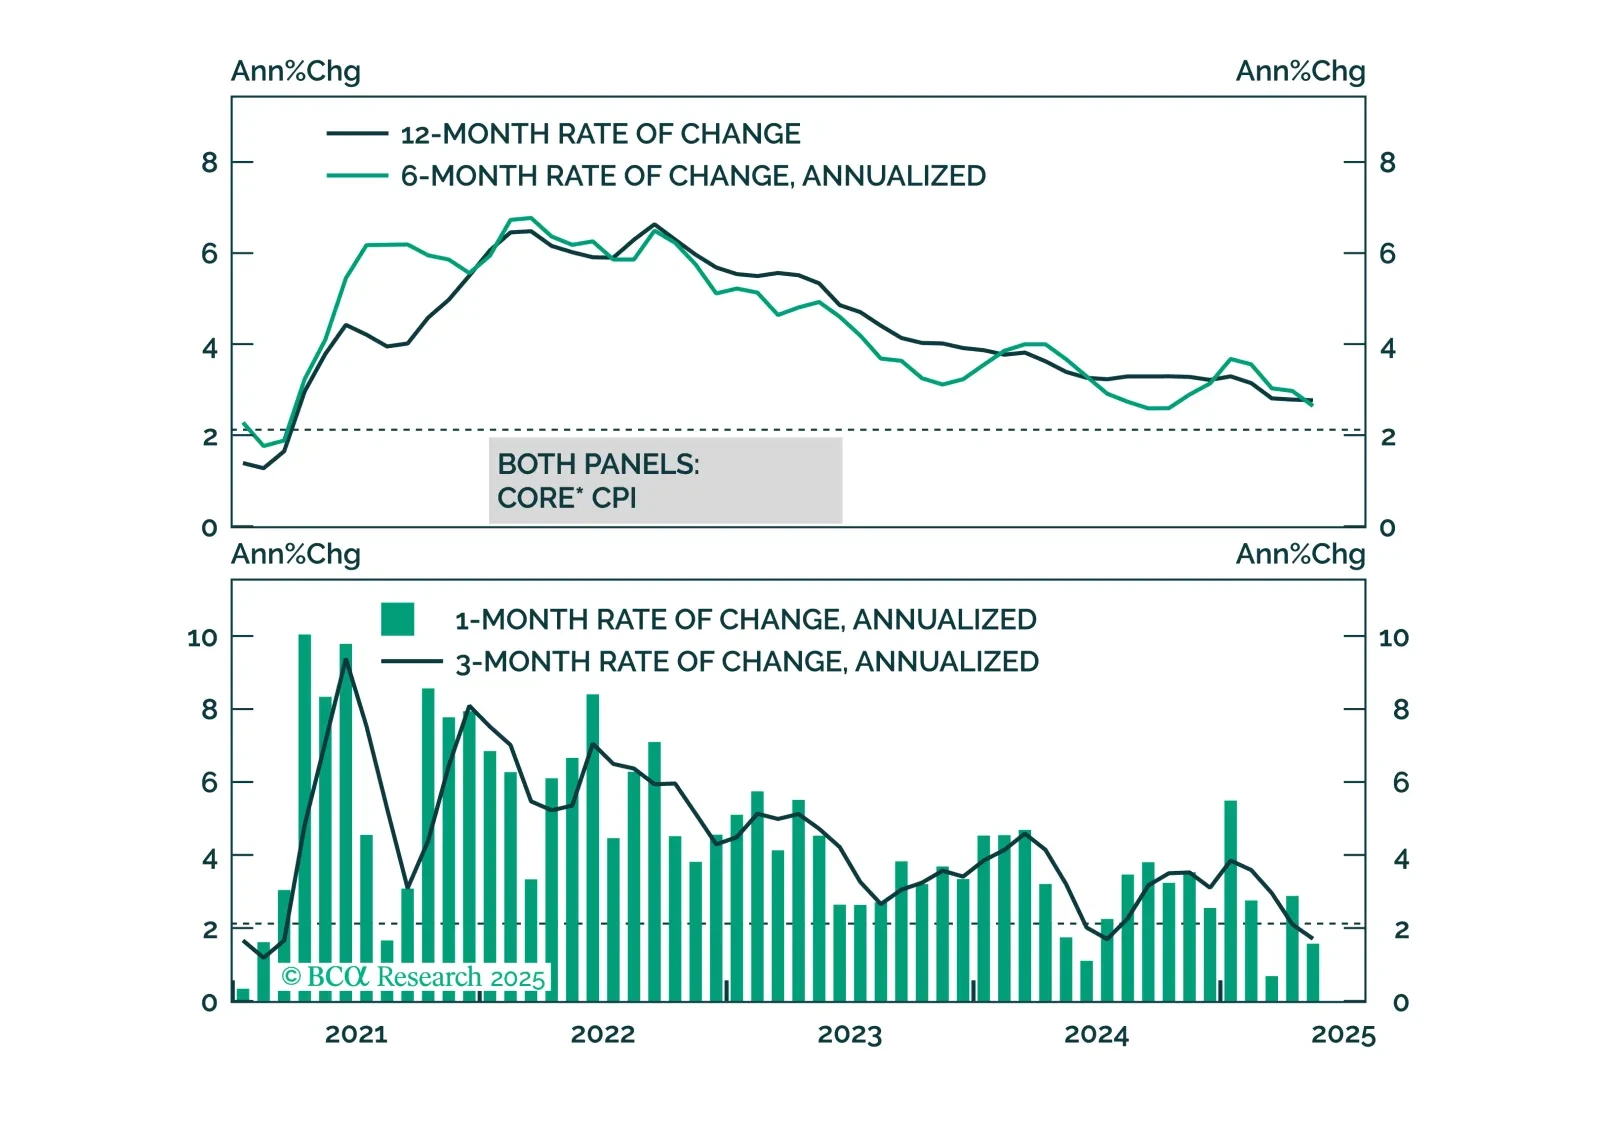
While we anticipate higher inflation in June, it looks increasingly likely that the price impact from tariffs will be less aggressive and long-lasting than many feared.

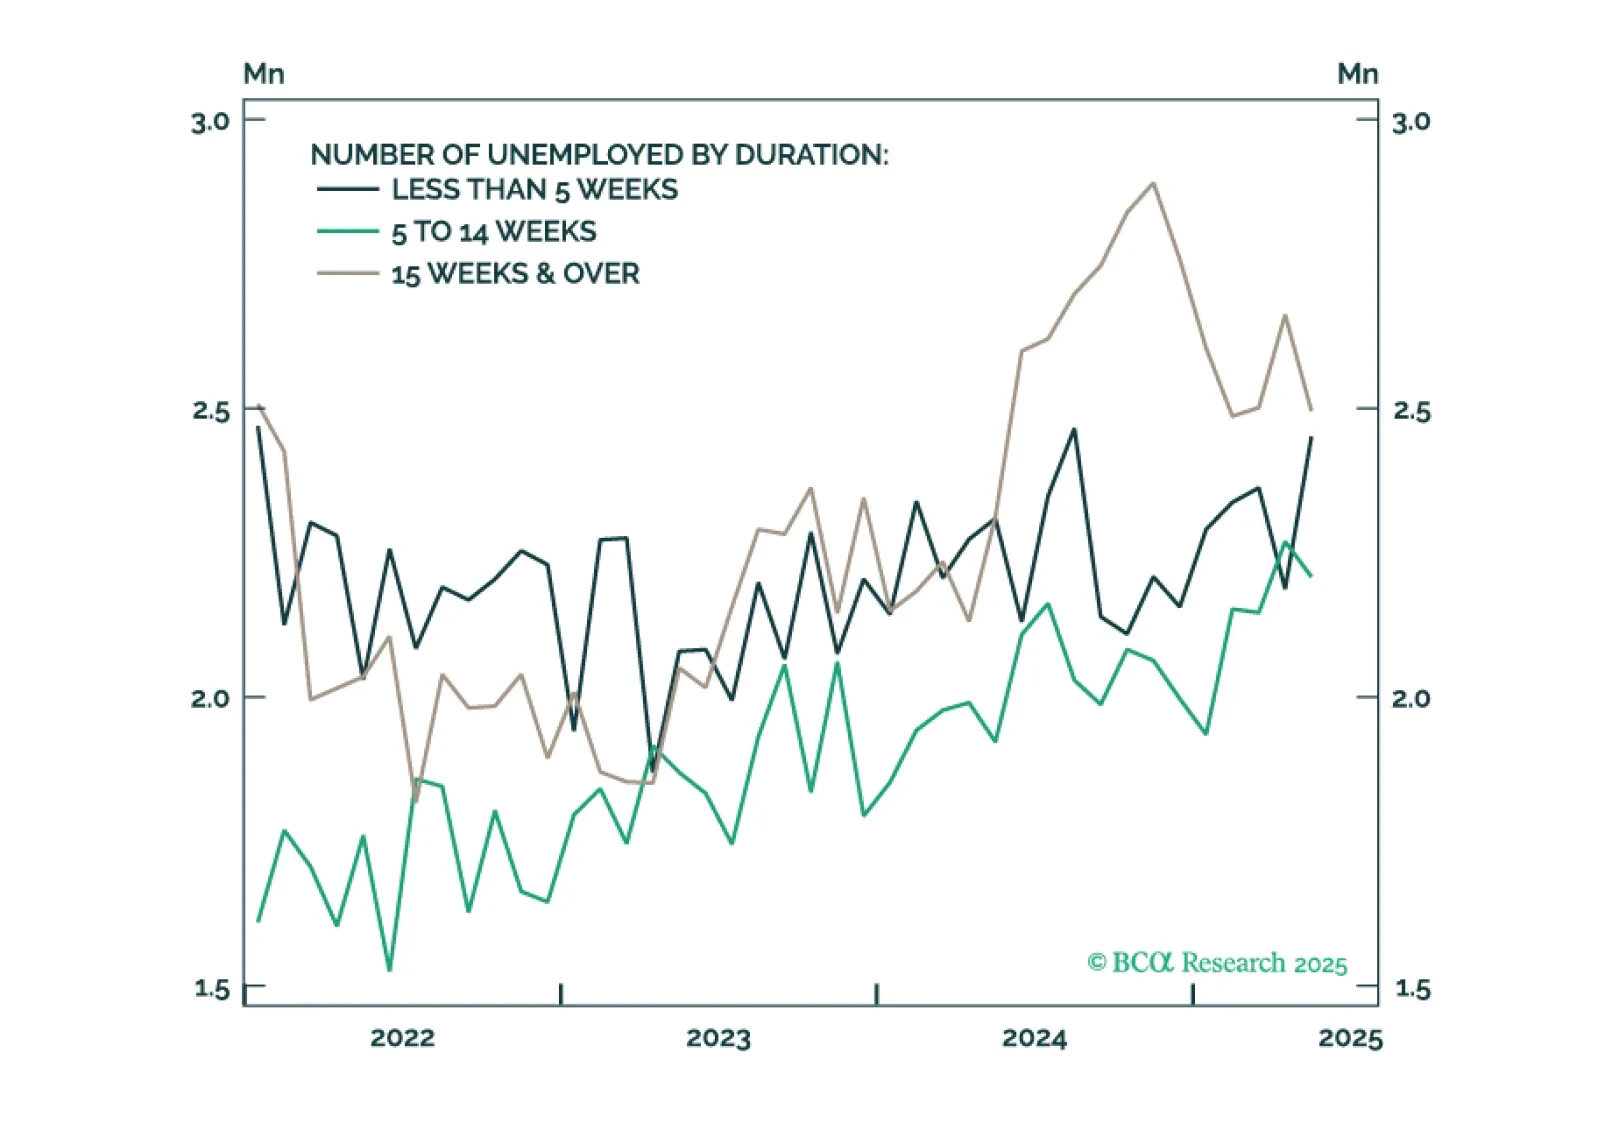
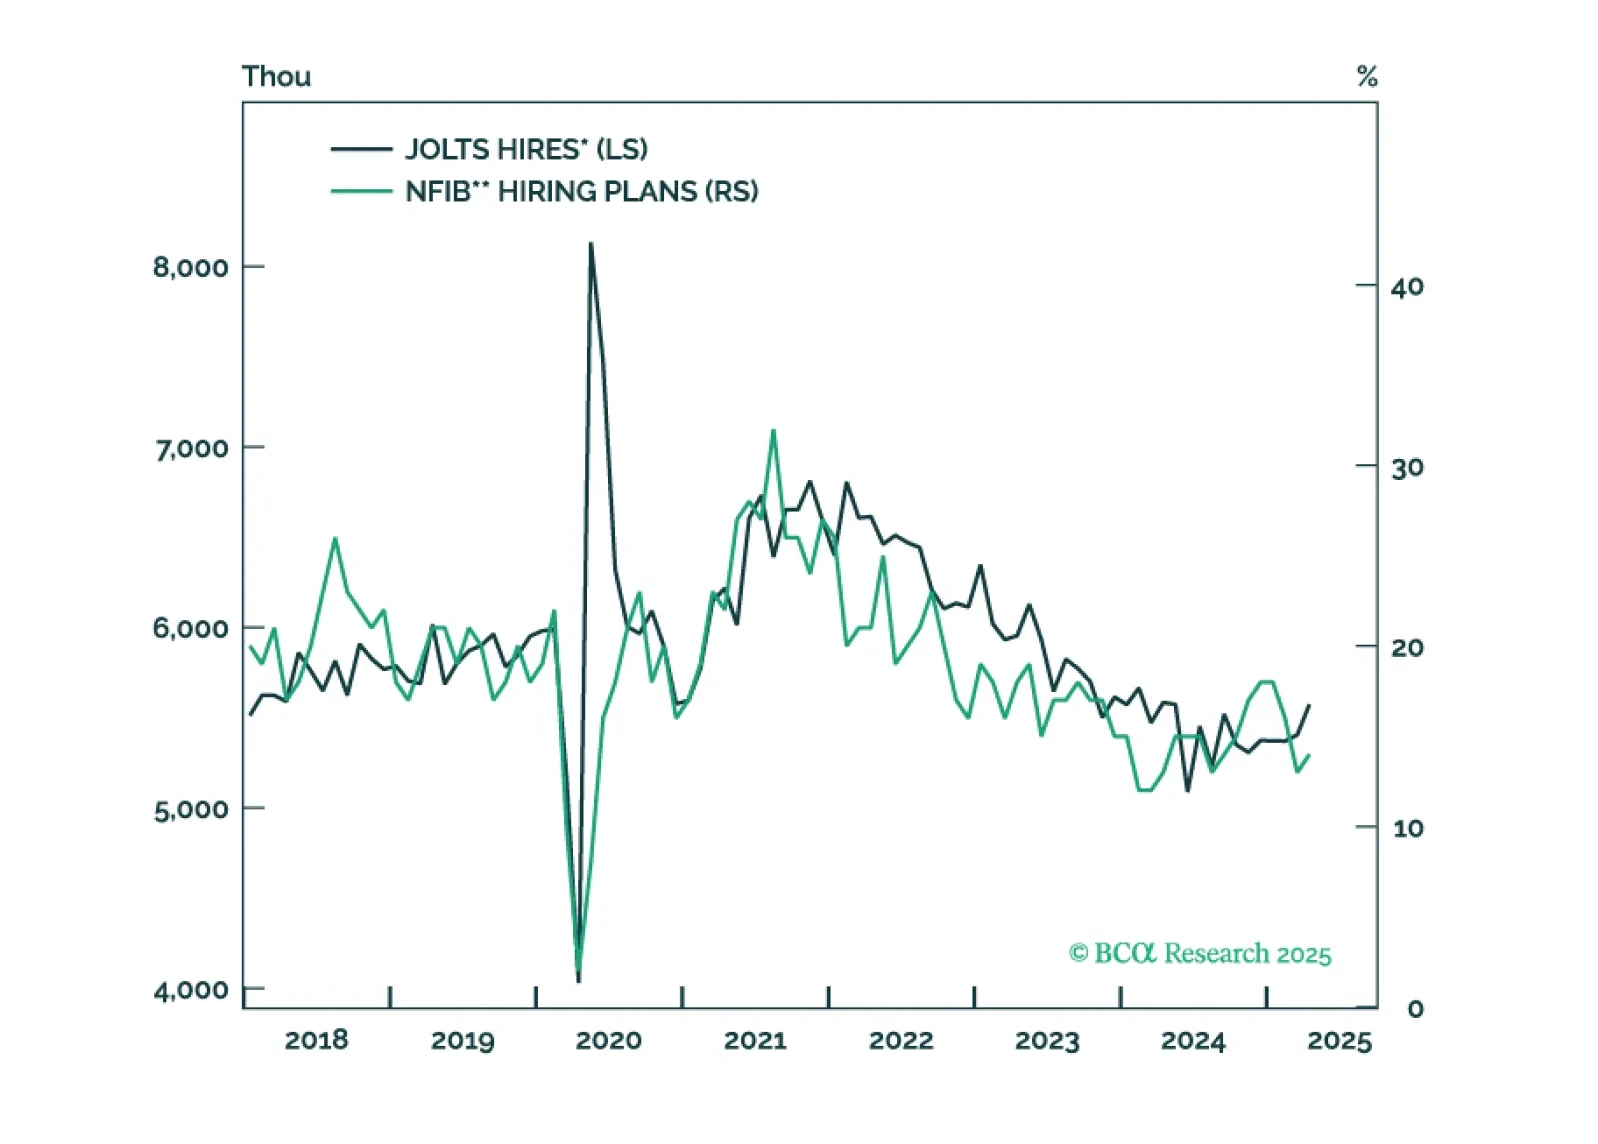
For now, measures of labor market utilization (like the unemployment rate) are only gradually weakening. But we know from history that these trends have a habit of quickly accelerating in advance of recession.
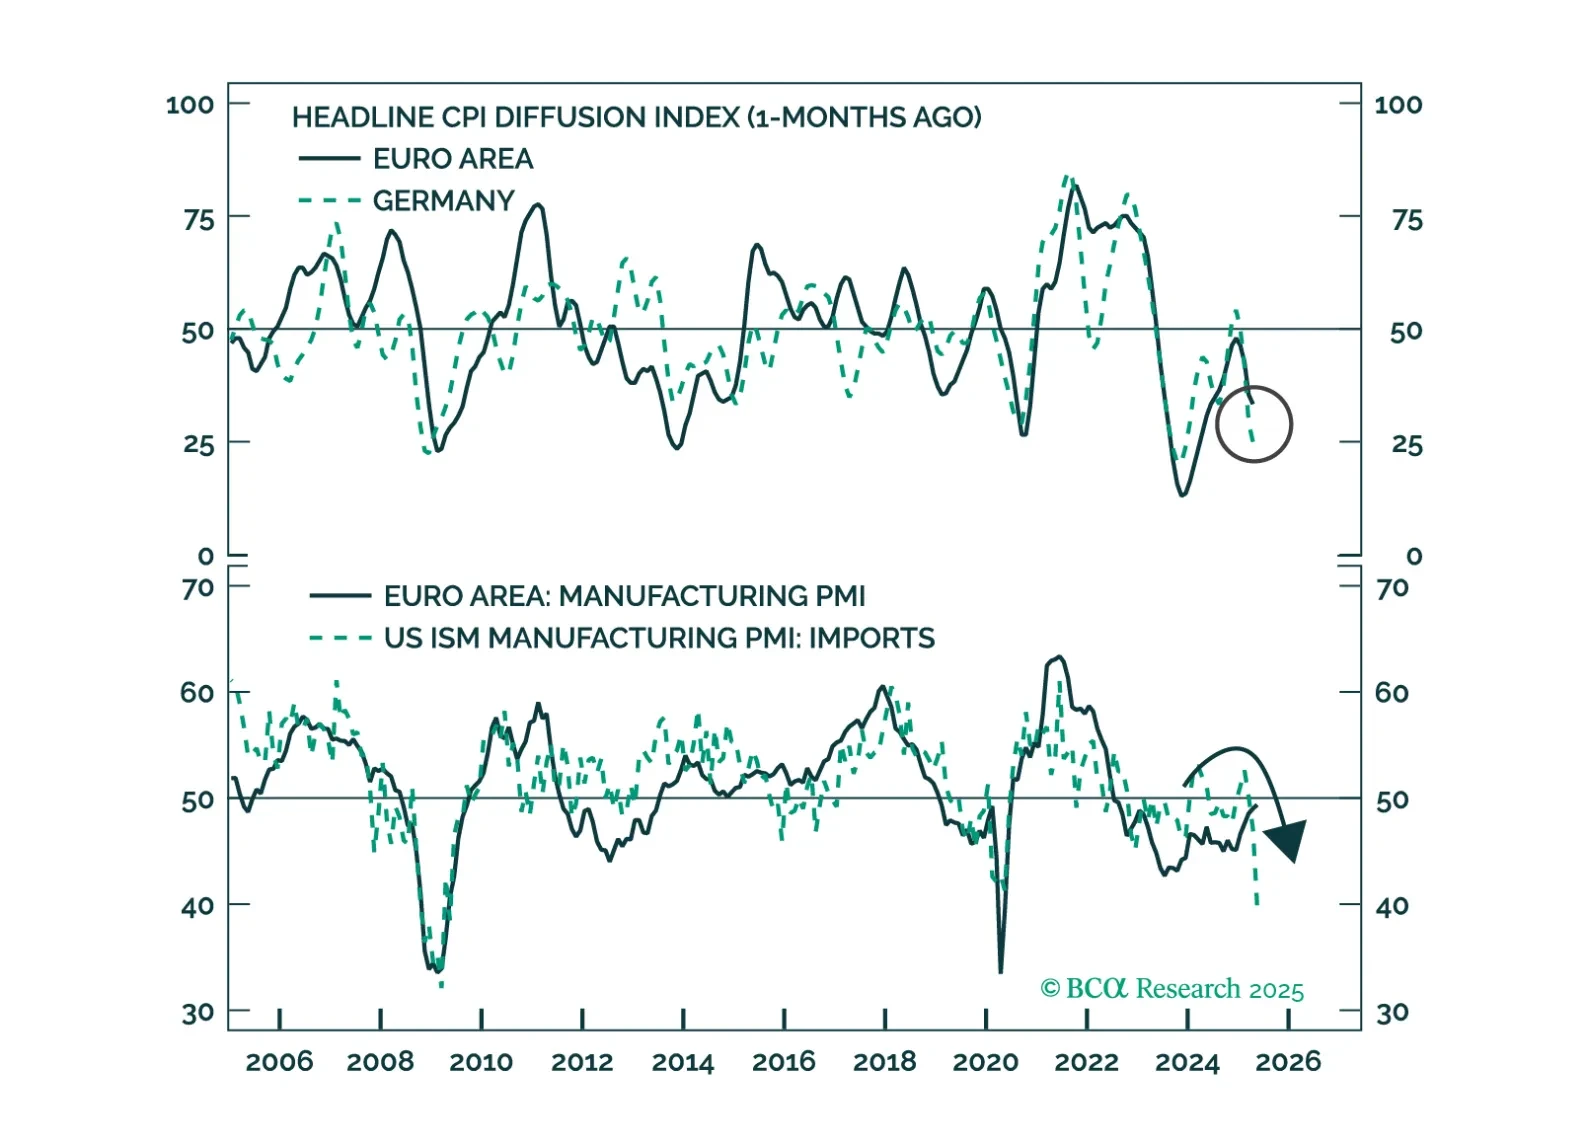
The ECB is changing its tone, but don’t call it a pivot. Slower cuts, sticky disinflation, and a soft growth patch shift the opportunity set. We break down the tactical bond trades and why EUR/USD dips are still for buying.
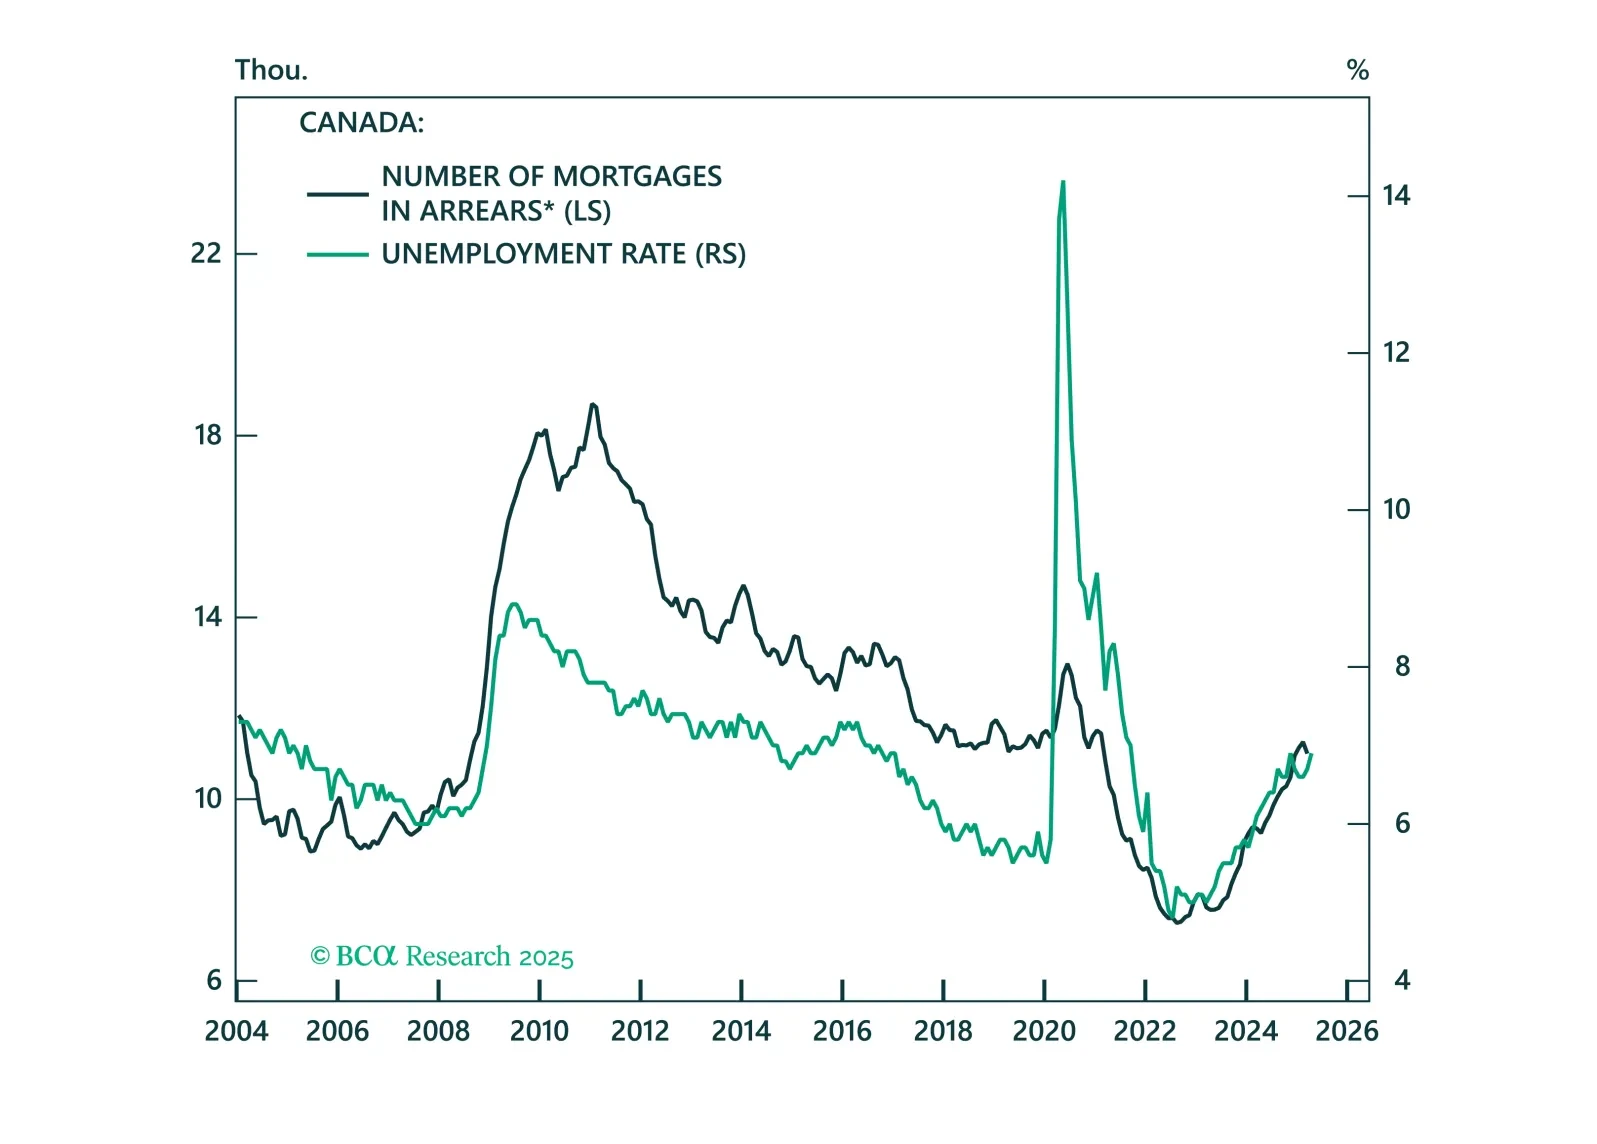
The Bank of Canada may be on hold for now, but deflationary risks are rising fast. Find out why rate cuts may come sooner than markets expect.