 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.

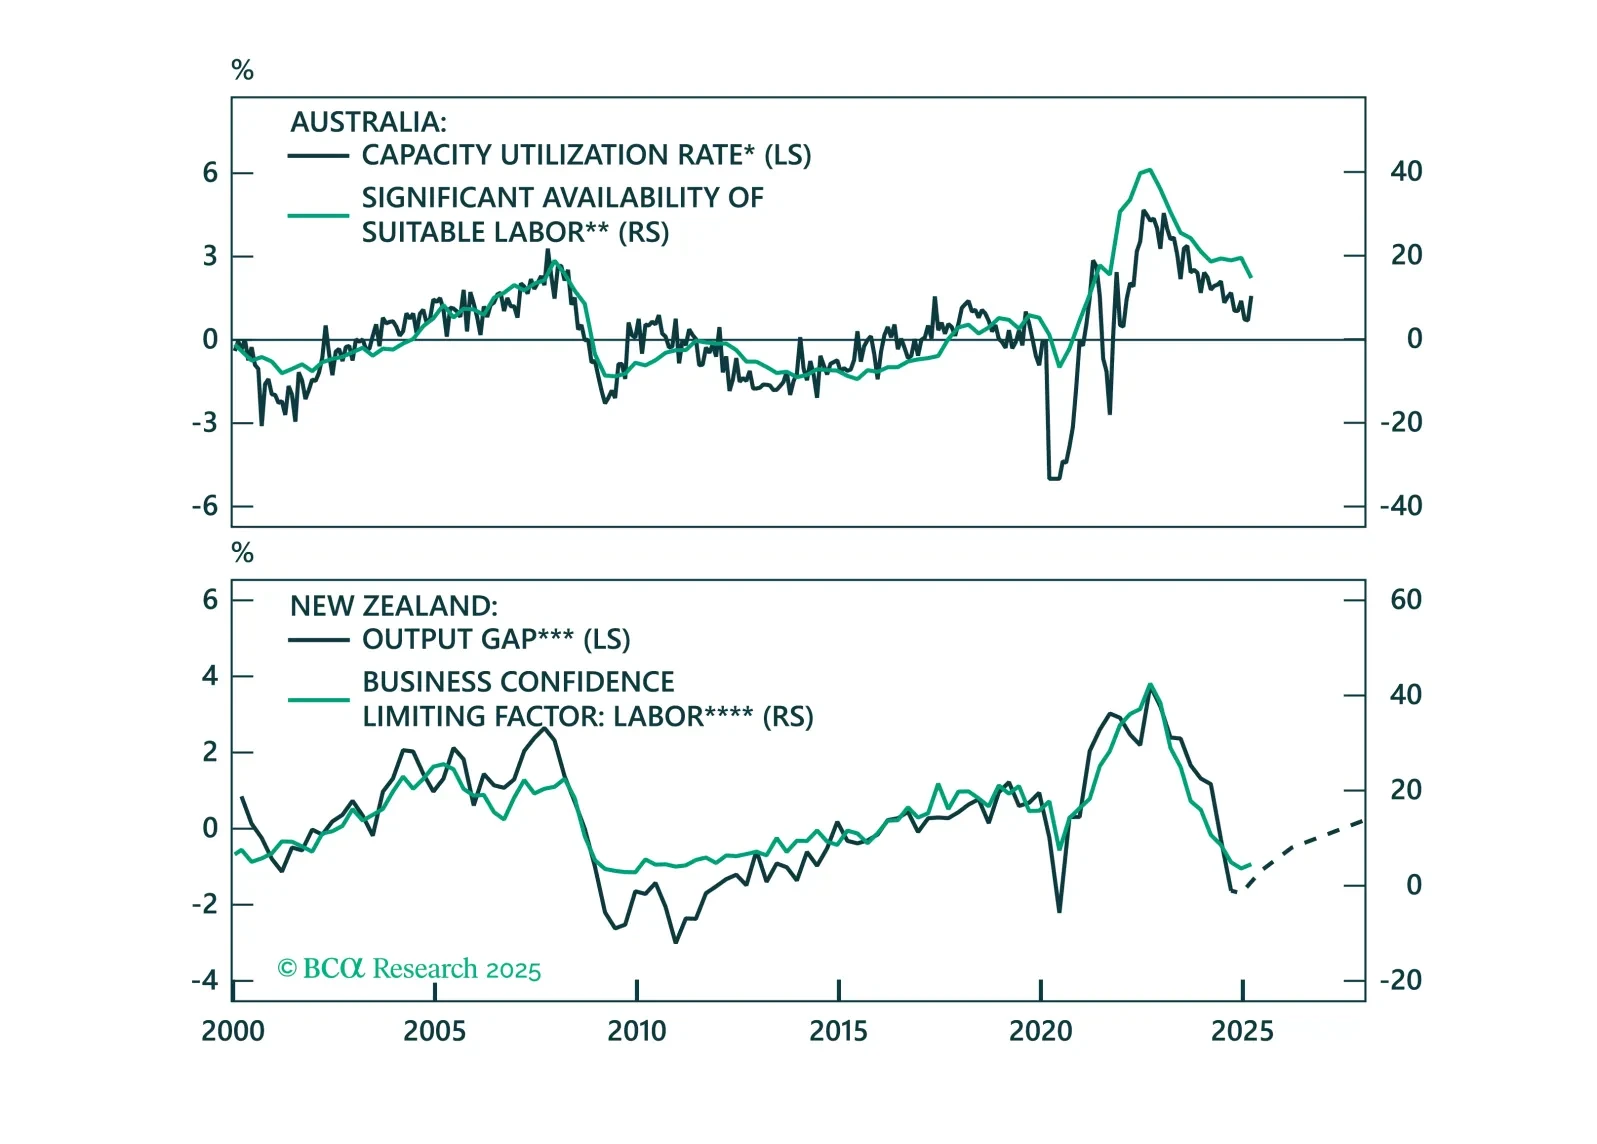
Rate cuts, recession risks, and relative value. This report unpacks how the BoE, Riksbank, and Norges Bank are reacting to global trade turmoil and where the opportunities lie.

Taiwan, Singapore, and Korea's currencies might appreciate versus the USD, driven by capital repatriation from domestic private investors away from the US. This thesis is less pertinent to India, Indonesia, and the Philippines because they have large net foreign portfolio liabilities. Malaysia and Thailand fall in the middle, while China is an exception. Investors should play intensifying deflationary pressures in Asia by betting on lower interest rates in the region.
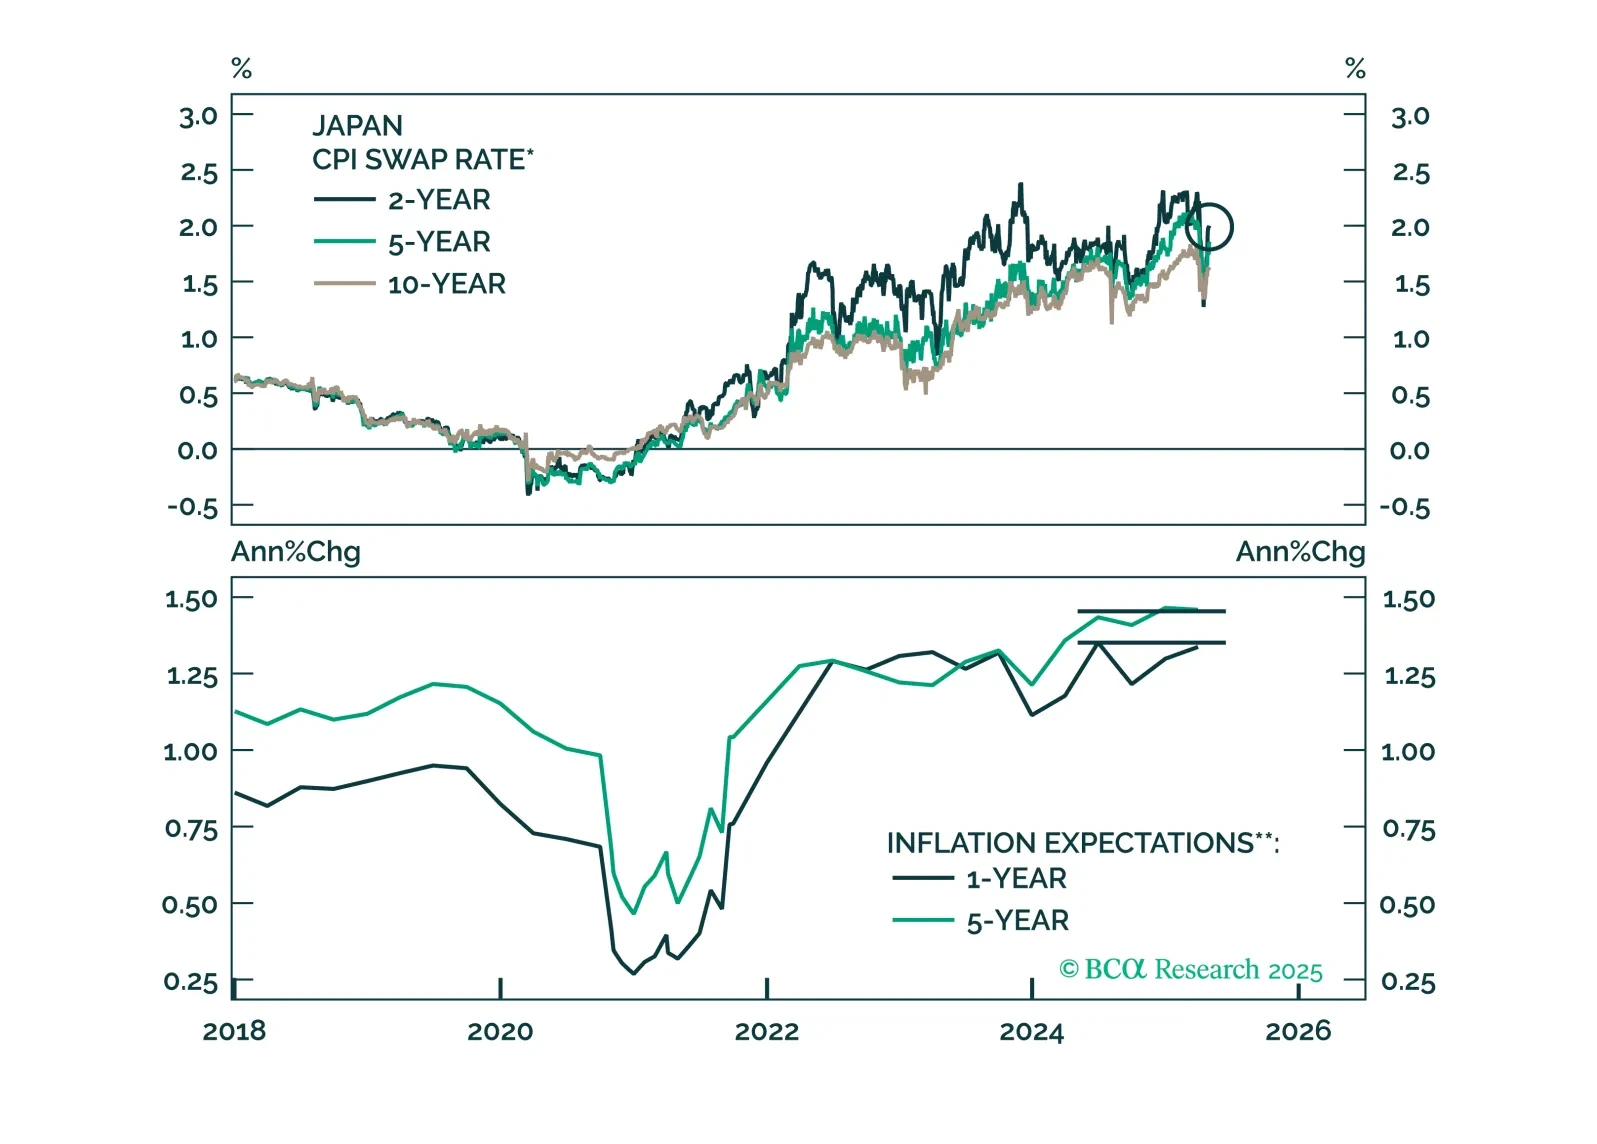
This week’s report looks at Japan, with the recent BoJ meeting. While a trade war has injected uncertainty into the Japanese economy, our conviction remains high that JGBs will underperform other government bond markets, and the yen will ultimately rally. That said, JPY is due for a tactical pullback.
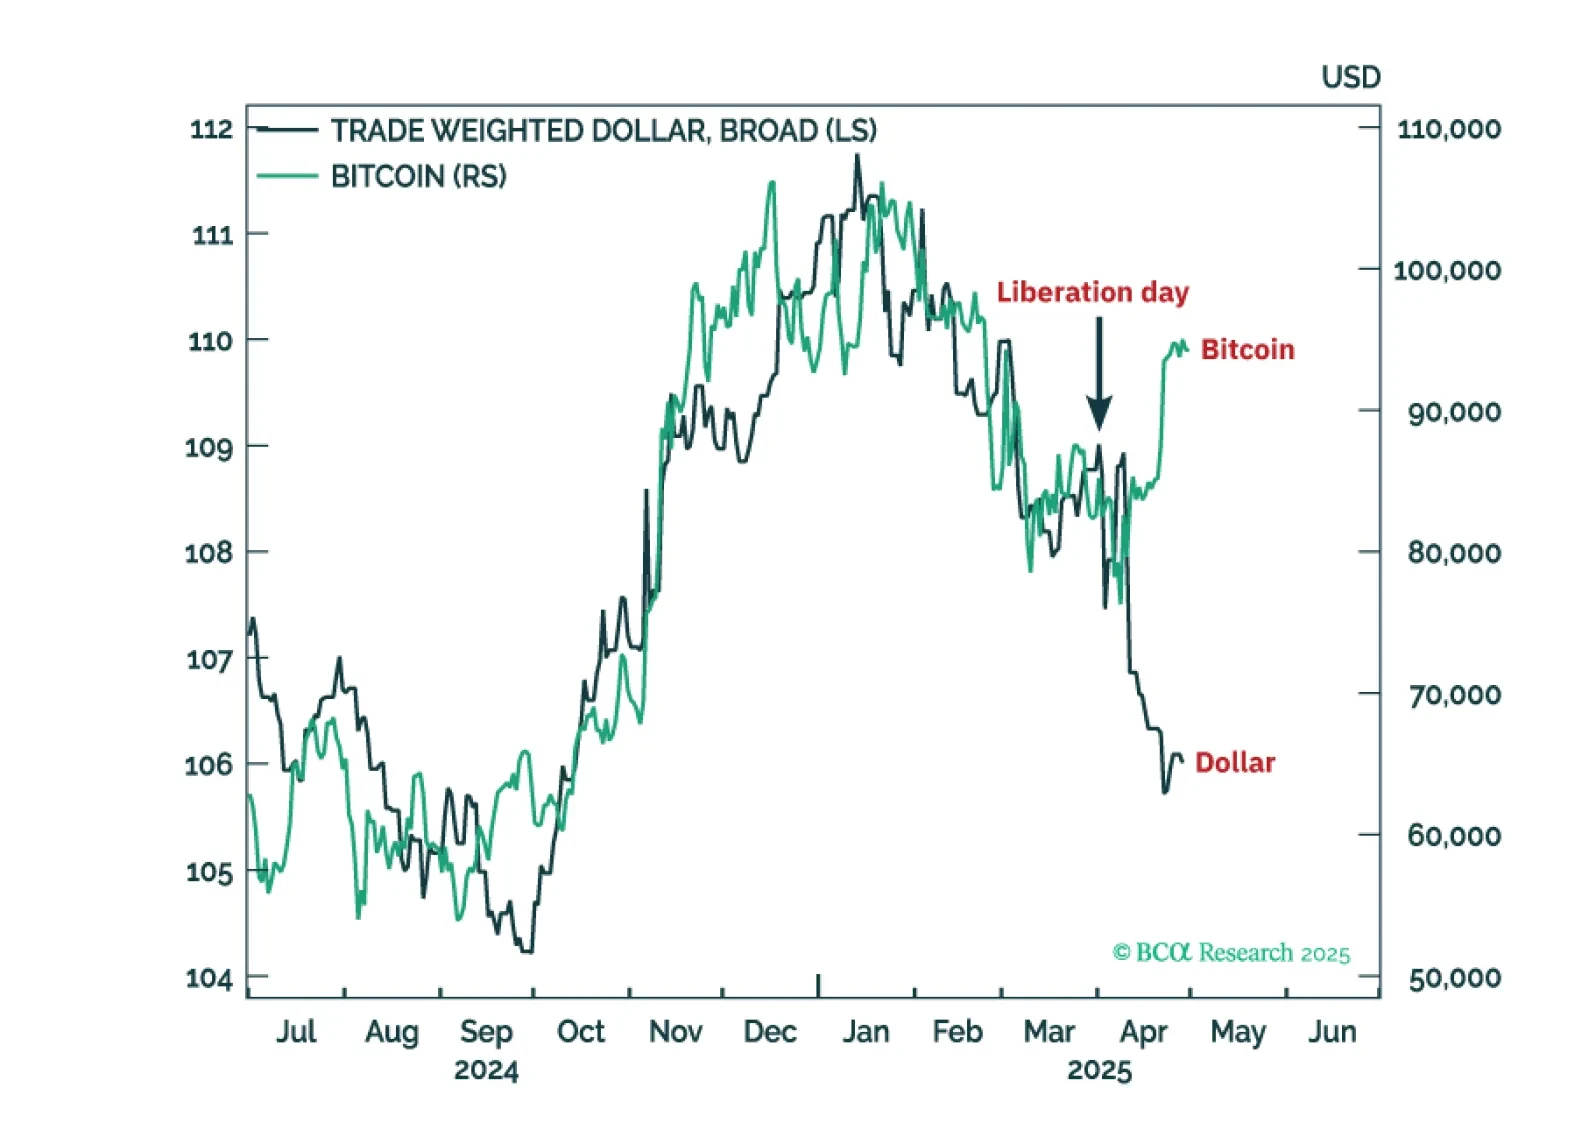
If Trump’s tariffs are ‘America's Brexit’, then UK gilts will recoup ten years of underperformance versus US T-bonds. Meanwhile, as the AI bubble fully deflates, Europe’s stock market valuation versus the US will rerate by about 25 percent. The big ‘currency’ winner of the structural exodus from the US dollar will be bitcoin. Plus: a trade for the next four weeks is to go tactically long USD/CHF.
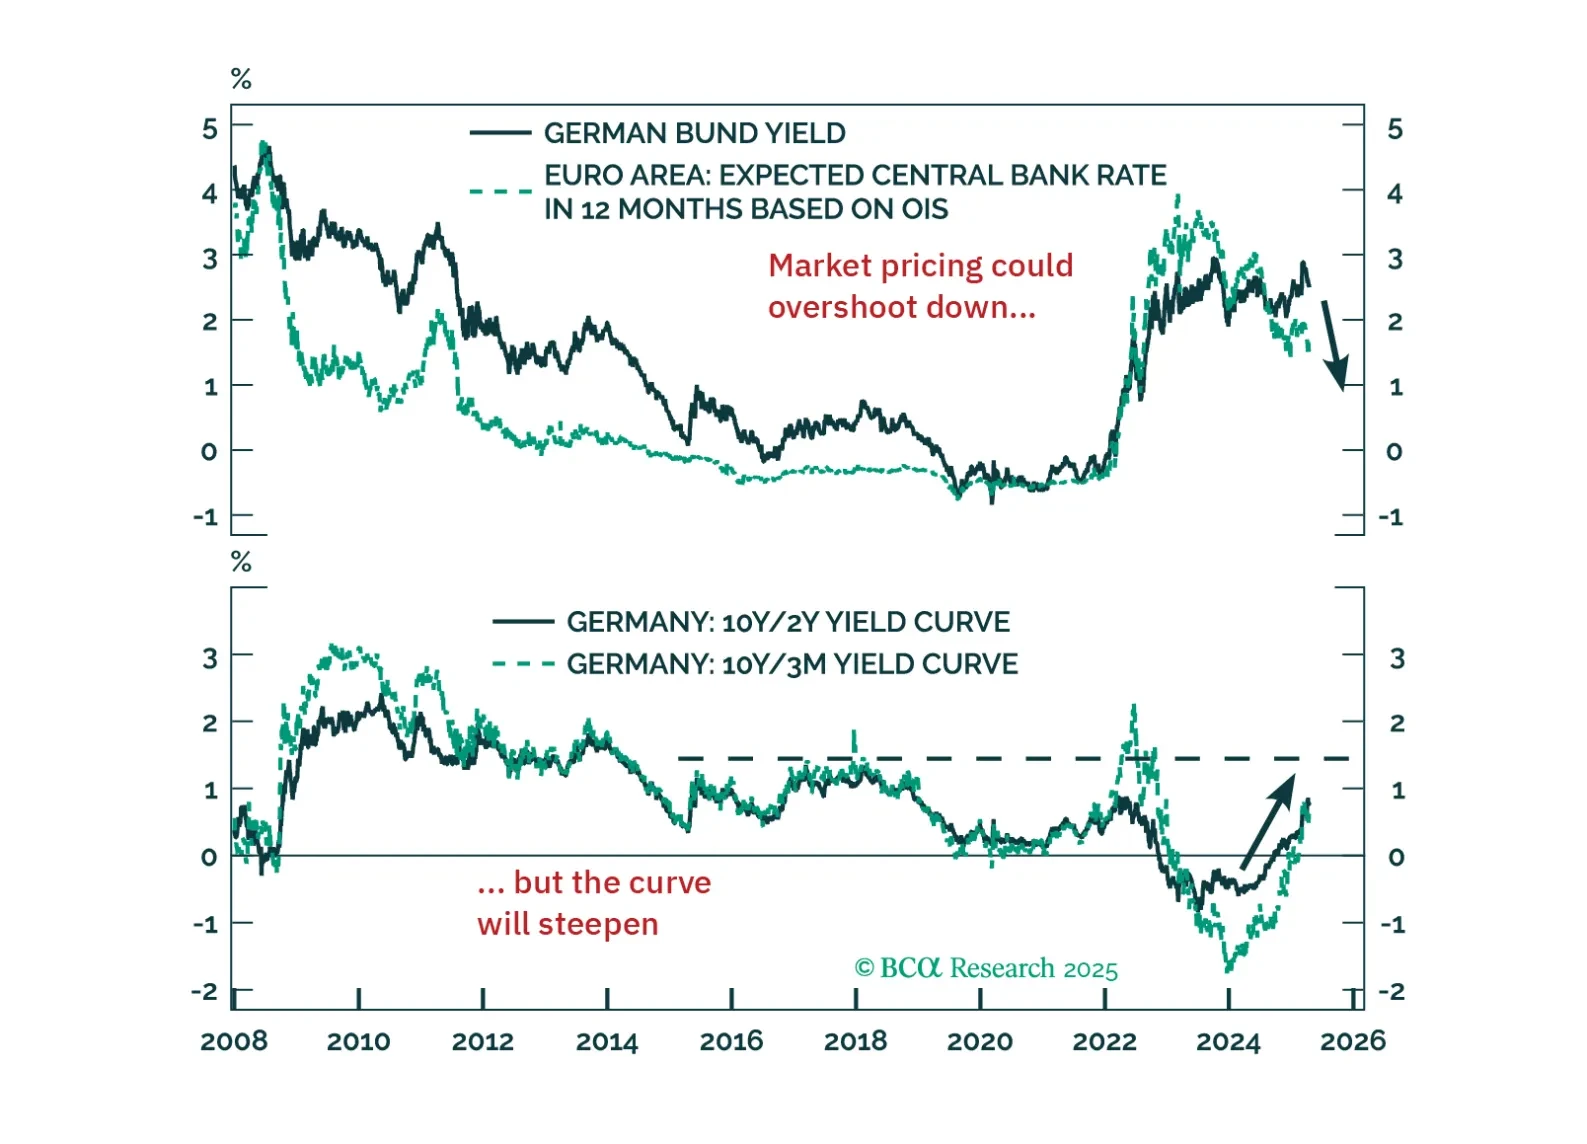
Europe’s deflation problem is getting harder to ignore. This week’s ECB cut is just the beginning — tariffs, the euro’s rally, and softening demand all point to more easing ahead. We explain what it means for yields, equities, and EUR/USD.
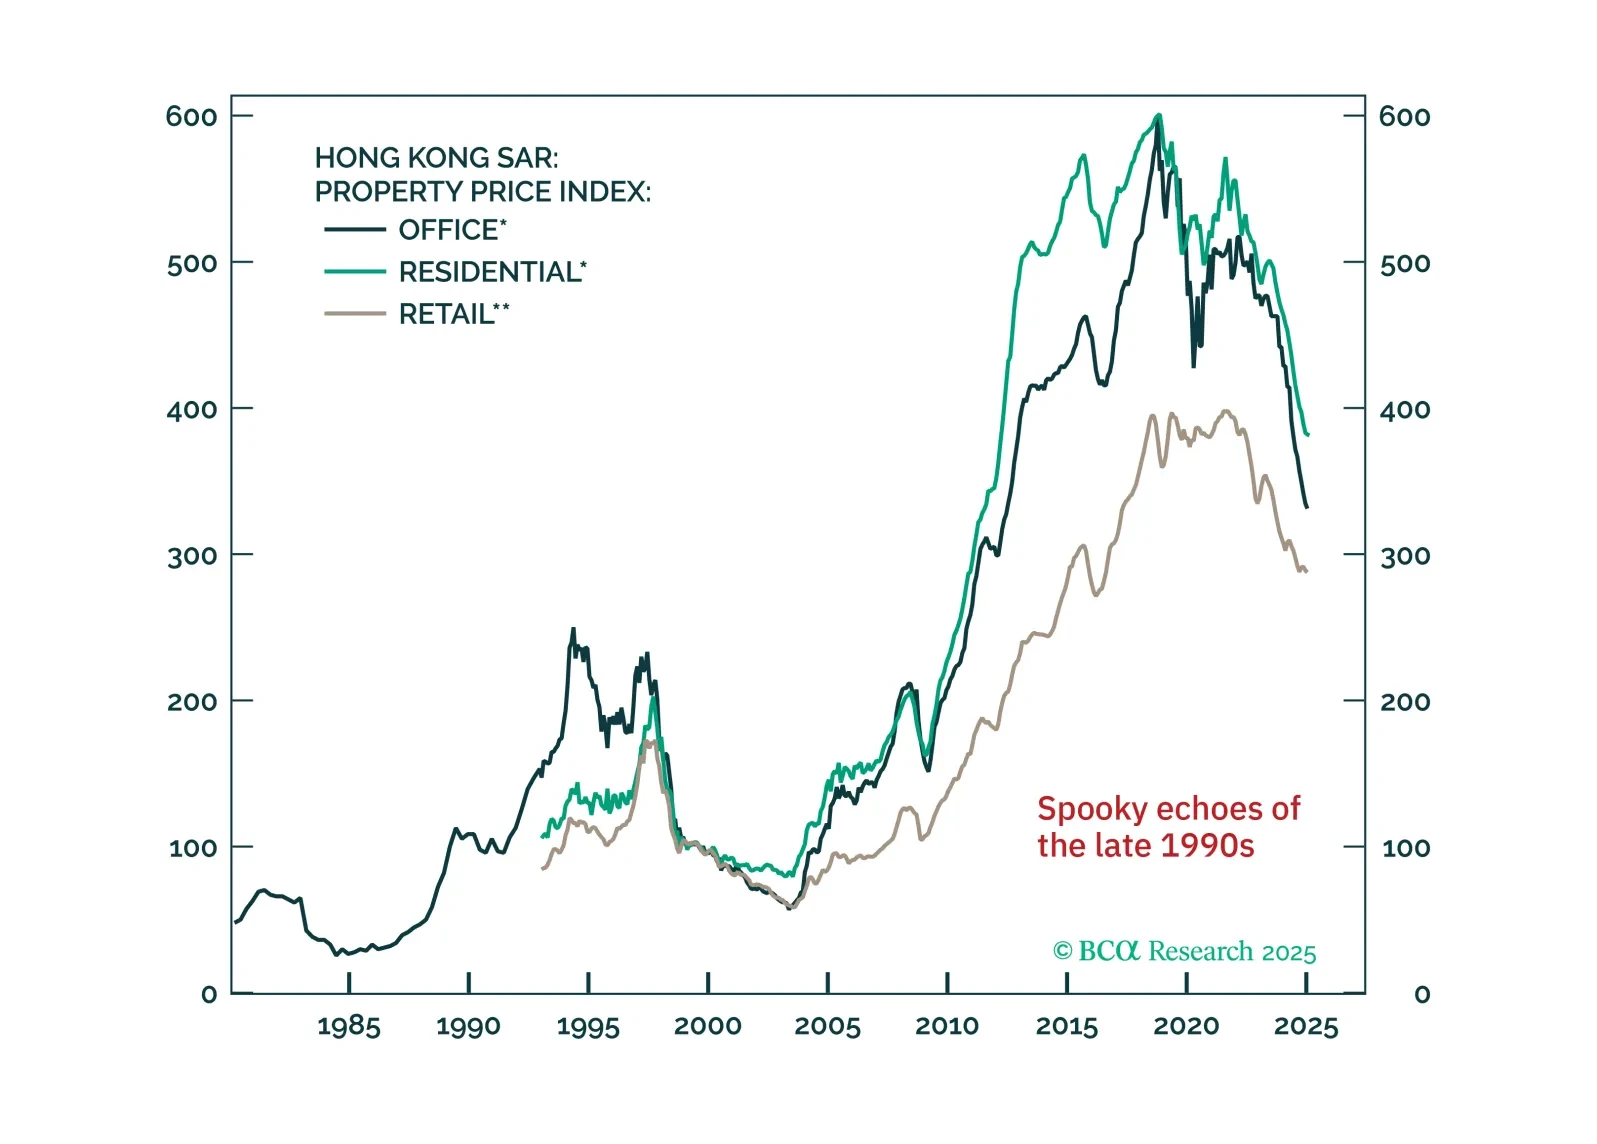

This report looks at the FX implications of the Trump tariffs, and the review of our Q1 trades.
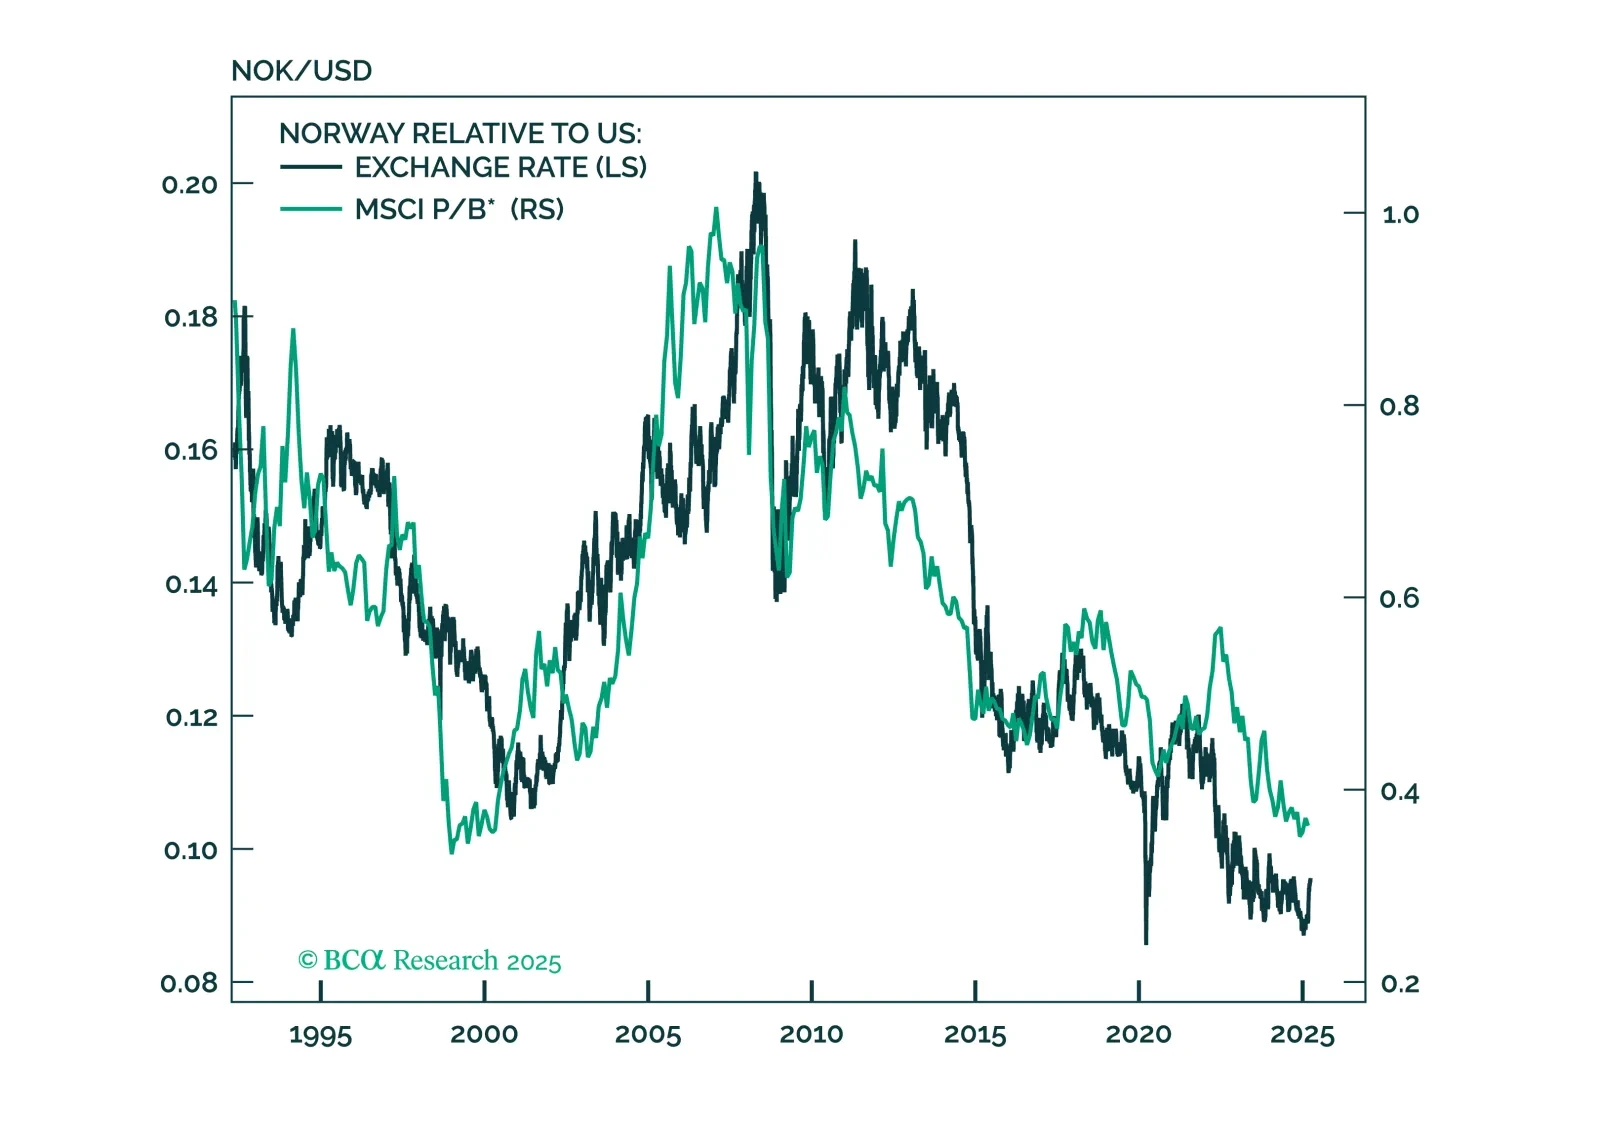
This report looks at investment implications, for Norwegian assets, given the recent meeting, from the Norges Bank.

This report is a quick take on our views on UK bonds and FX, given the recent budget.