Latest from BCA Research
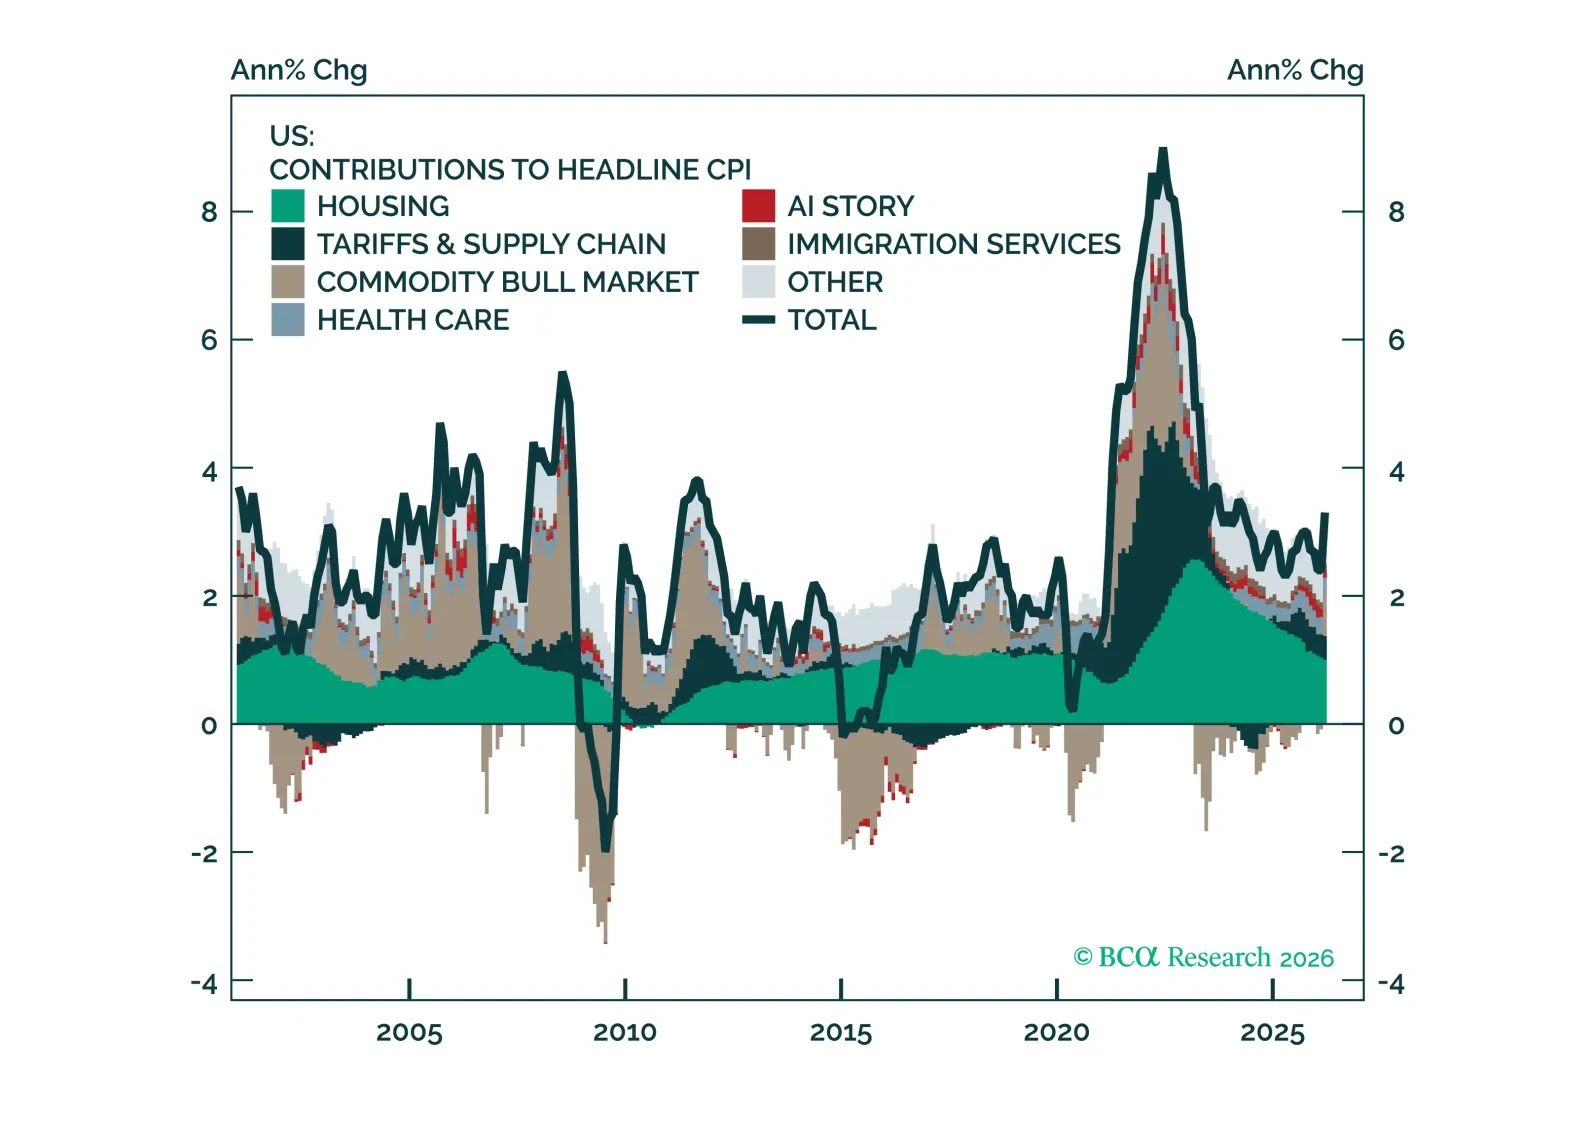
The tenuous ceasefire holds, with the "new geopolitical equilibrium scenario" remaining in place. Enough crude trickles through Hormuz to avert a global recession, but not to alleviate building inflationary pressures, a product of a complicated geomacro context that is not transitory. The Fed will look to ignore these in the short term, fueling the equity rally in the US. Chinese equities may pop thanks to the upcoming détente. When does it all end? Beware of major IPOs!

Central banks remain on hold amid heightened uncertainty. We rely on BCA’s Central Bank Monitors to assess the current policy stance of major central banks, and highlight the tactical opportunities across bond markets and currencies.
The surprisingly solid ceasefire between Iran, the US, Israel, and GCC countries broke on May 4 with a ballistic missile and drone attack against the UAE. According to reports, UAE defense forces intercepted 12 ballistic missiles, three cruise missiles, and four drones, launched by Iran.

The UAE’s exit from OPEC is unlikely to impact oil markets in 2026. Over the longer term, however, the emergence of an “anti-OPEC club” of producers favoring unconstrained oil output growth would create a headwind to crude prices and weaken the price floor that OPEC seeks to defend.
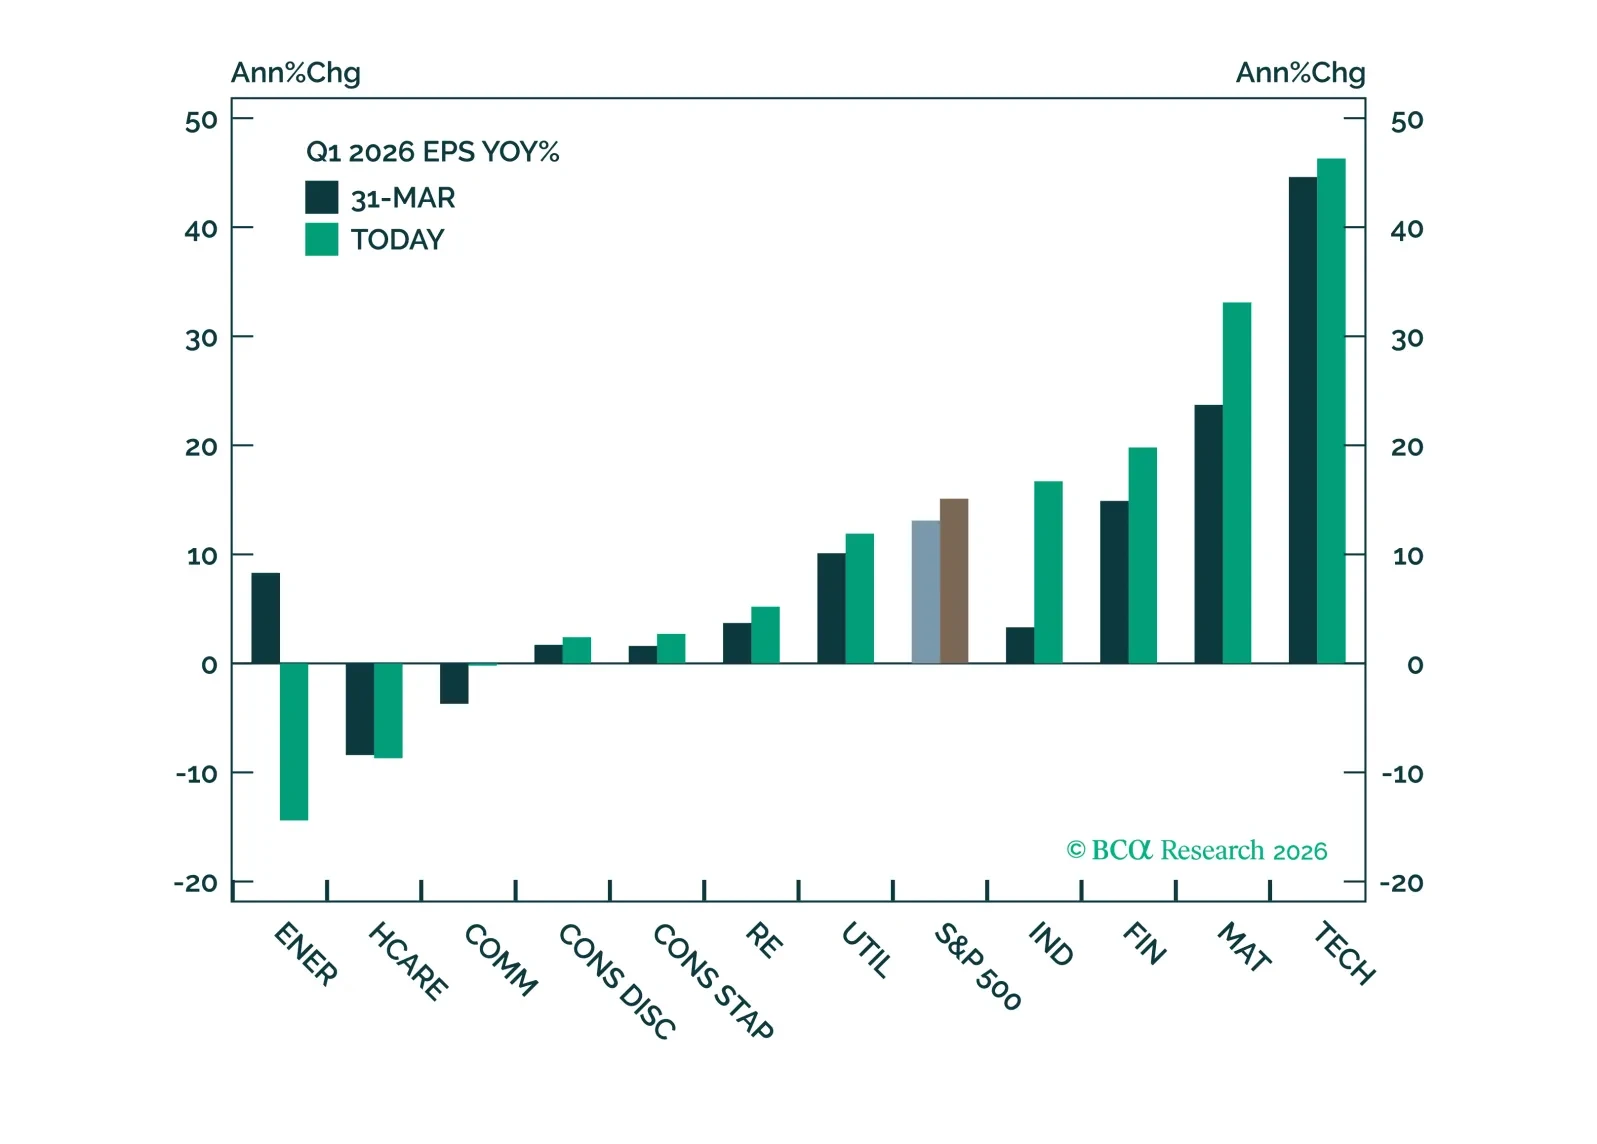
Leadership has rotated toward investment-driven sectors, reflected in both EPS growth and price performance. Expanding margins suggest the cycle may have longer to run, as productivity gains start to work their way through fundamentals. We continue to see upside for the S&P 500, with no change to our sector outlook.

So far, there is no evidence of second-round effects from the oil price shock showing up in the US economy. Fed rate hikes are off the table unless those effects emerge.
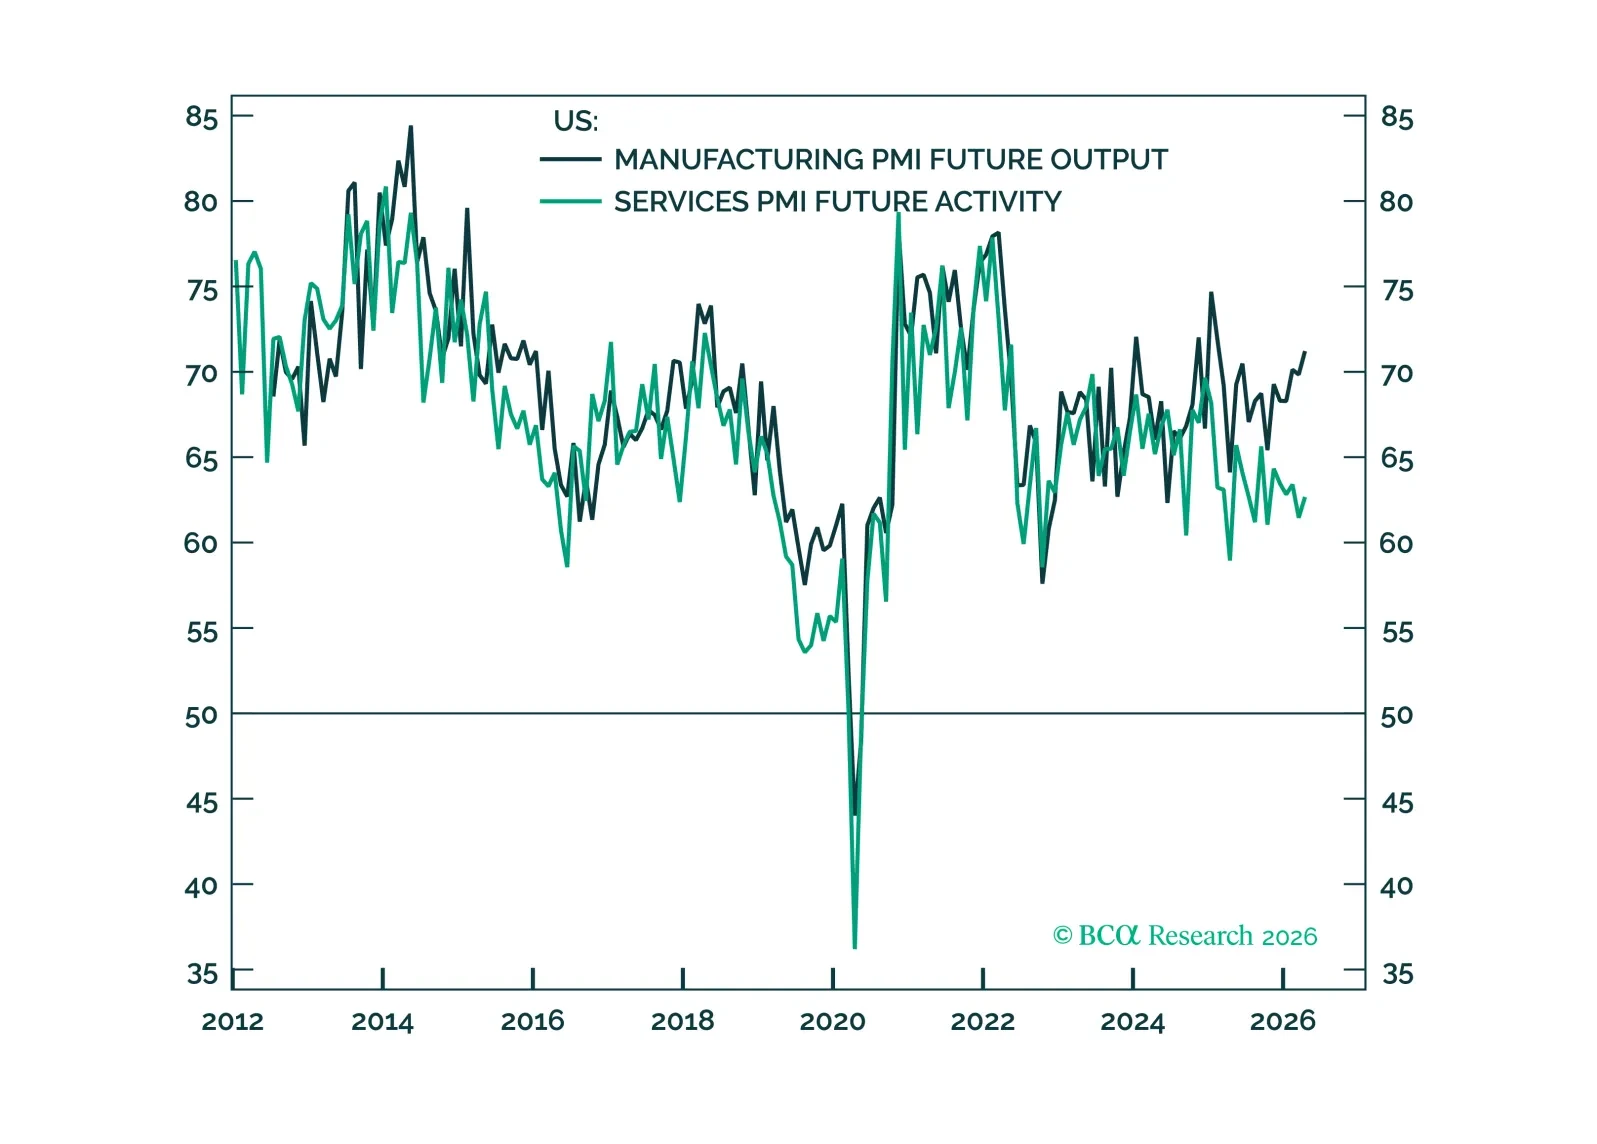
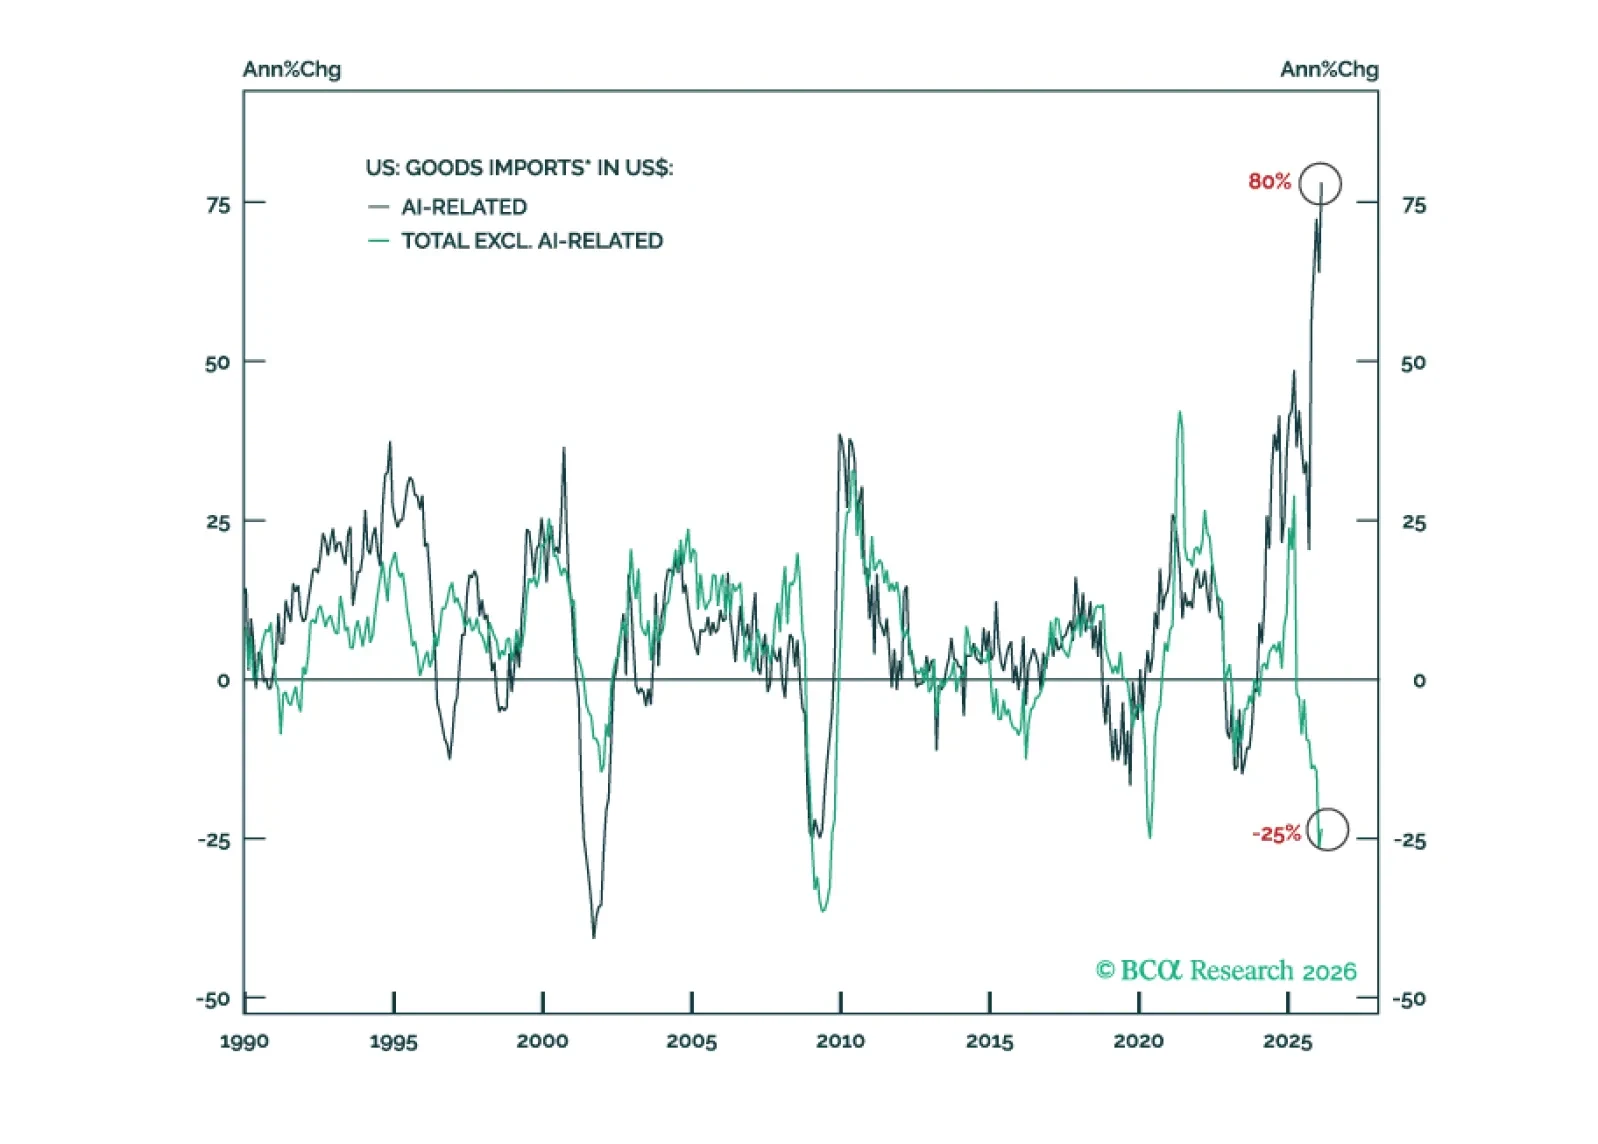
The Strait of Hormuz remains closed. Even if the Strait were to open tomorrow, global consumers will be squeezed for the rest of the year. However, AI capex is accelerating, and signs of ROI are emerging. This capex boom will keep the world from an economic downturn. Upgrade equities to overweight and downgrade cash to underweight. Upgrade the US and downgrade Europe and Australia. Upgrade Communication Services.

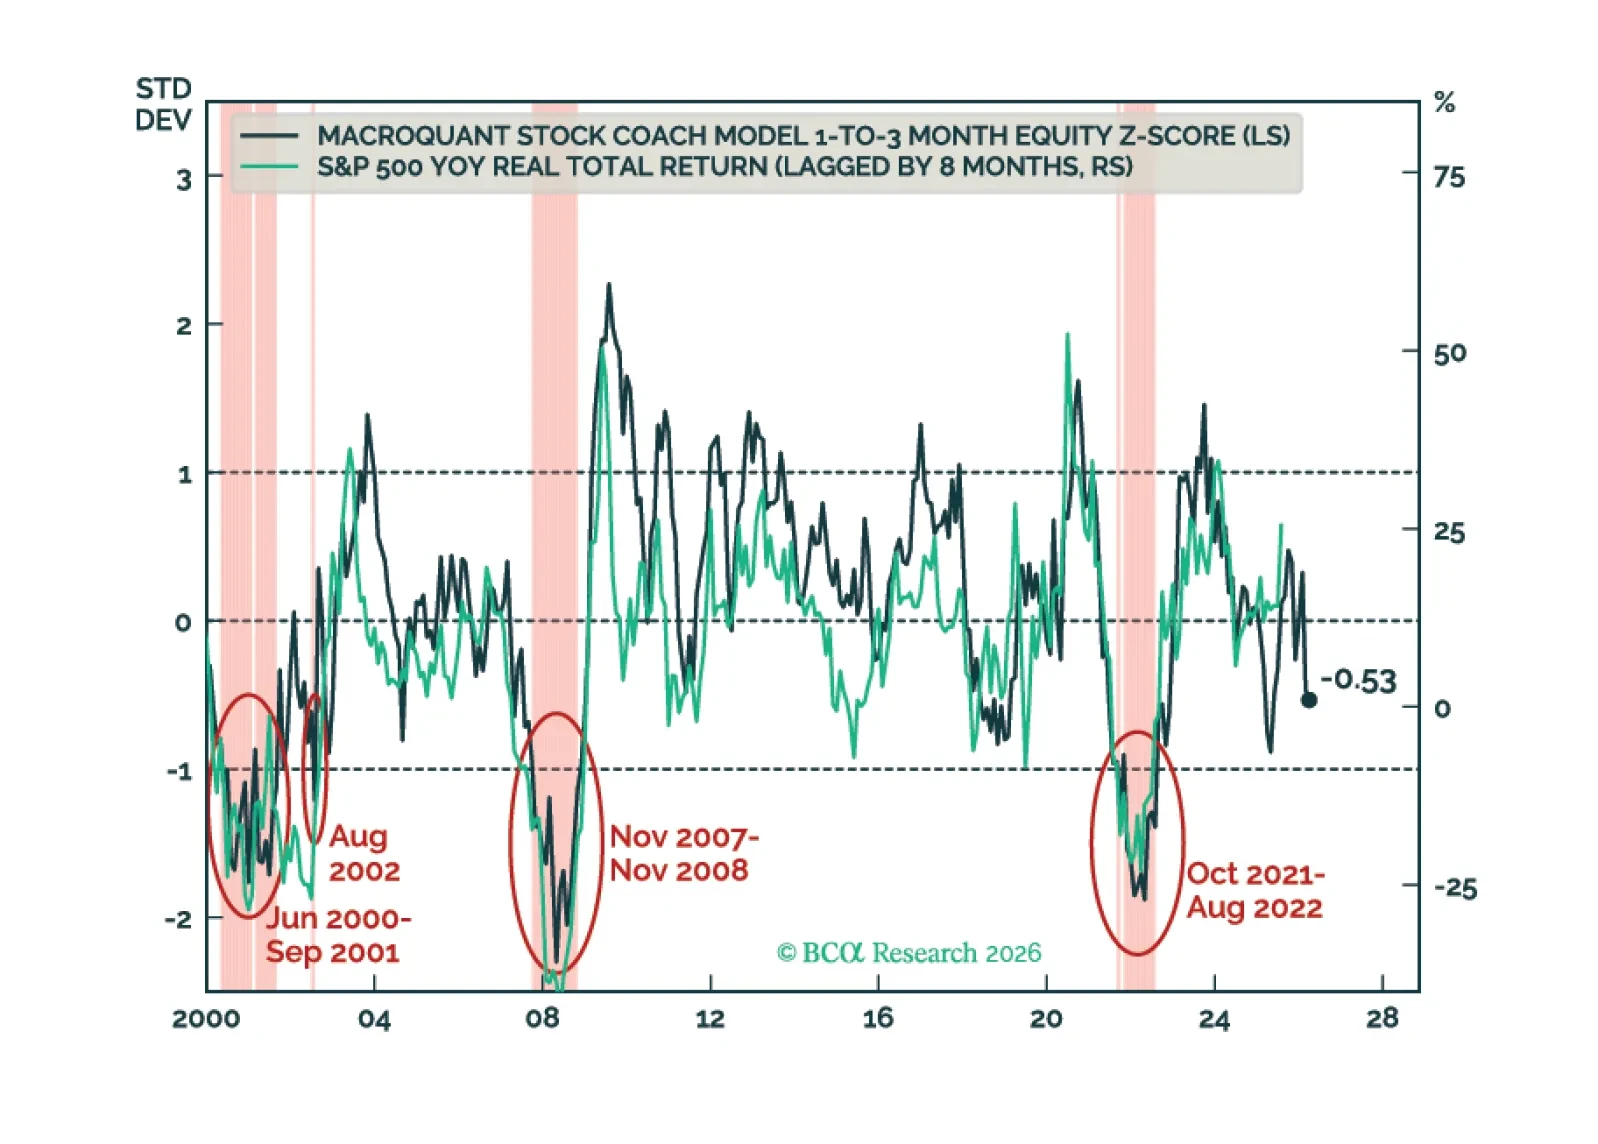
MacroQuant recommends an underweight position in equities, favors a below-benchmark duration stance in fixed-income portfolios, is neutral-to-slightly positive on the US dollar, remains neutral on gold, upgrades copper to neutral, and is very bullish on oil.